
 Asperger Syndrome Market | 2026-2036
Asperger Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Asperger Syndrome Market Analysis
The FDA's pediatric neurodevelopmental drug trial guidance is repositioning the cost-of-entry calculus for pharmaceutical developers targeting Asperger syndrome indications. Eli Lilly and Company leverages its psychiatric research infrastructure to sustain a presence in neurodevelopmental therapeutic development. Jazz Pharmaceuticals anchors its portfolio strategy through specialized central nervous system franchises. Otsuka Pharmaceutical differentiates via its long-standing investment in behavioral health drug discovery.
Asperger syndrome represents a neurodevelopmental condition characterized by intact cognitive function alongside restricted interests and social communication differences, typically assessed through standardized diagnostic instruments such as the Autism Diagnostic Observation Schedule. The condition primarily serves clinical and educational purposes, directing individuals toward targeted behavioral interventions, pharmacological symptom management, and structured support systems. Medication and therapy services command the largest revenue pools, reflecting chronic management needs across the lifespan, while online therapy delivery is expanding fastest as telehealth infrastructure matures and payer reimbursement frameworks adapt. Assessment tools retain stable demand tied to diagnostic protocol requirements in school and clinical settings.
The FDA, EPA, and HIPAA collectively shape product standards, trial conduct, and data handling across the Asperger syndrome treatment ecosystem, with FDA pediatric trial mandates directly influencing development timelines and investment thresholds. State-level Medicaid waivers and educational entitlement regulations under the Individuals with Disabilities Education Act further structure market access and reimbursement flows. Stakeholders must monitor evolving digital therapeutics classification decisions and school-based funding allocations to anticipate demand shifts.
Market Dynamics
School districts across the United States are accelerating their procurement of diagnostic instruments and behavioral intervention services, redirecting public education budgets toward specialized autism support infrastructure. This institutional demand pull is compressing vendor sales cycles and reshaping service delivery models.
Growth Catalysts
- Medicaid Waivers:State-level program expansions in Texas and California are extending reimbursement coverage for applied behavior analysis therapy, widening access for eligible families.
- Telehealth Infrastructure:Payer adaptation to remote service delivery is eliminating geographic barriers to specialist consultation, particularly in rural counties.
- IDEA Entitlements:Federal educational mandate enforcement is compelling school systems to maintain diagnostic capability and therapeutic staffing ratios.
Market Restraints
- Specialist Workforce Scarcity:Board-certified behavior analyst credentialing bottlenecks in the Northeast corridor are extending appointment wait times beyond sixteen weeks.
- Reimbursement Rate Compression:Commercial insurer fee schedule reductions in Florida and Illinois are squeezing outpatient clinic margins.
- Diagnostic Instrument Costs:ADOS-2 kit pricing and required clinician training hours create capital barriers for smaller pediatric practices.
Strategic Opportunities
- Employer-Sponsored Benefits:Large self-insured corporations in the technology sector are adding autism care navigation to employee assistance programs.
- Digital Therapeutics Pathway:FDA breakthrough device designation criteria for pediatric neurodevelopmental indications are creating expedited market access for software-based interventions.
- Adult Transition Services:Vocational rehabilitation agencies in Michigan and Ohio are commissioning social skills programming for post-secondary populations.
Industry Challenges
- Interoperability Standards:Electronic health record fragmentation between school-based IEP systems and clinical billing platforms complicates care coordination.
- Outcome Measurement Consistency:Absence of standardized metrics across behavioral intervention providers impedes value-based contracting negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asperger Syndrome Market |
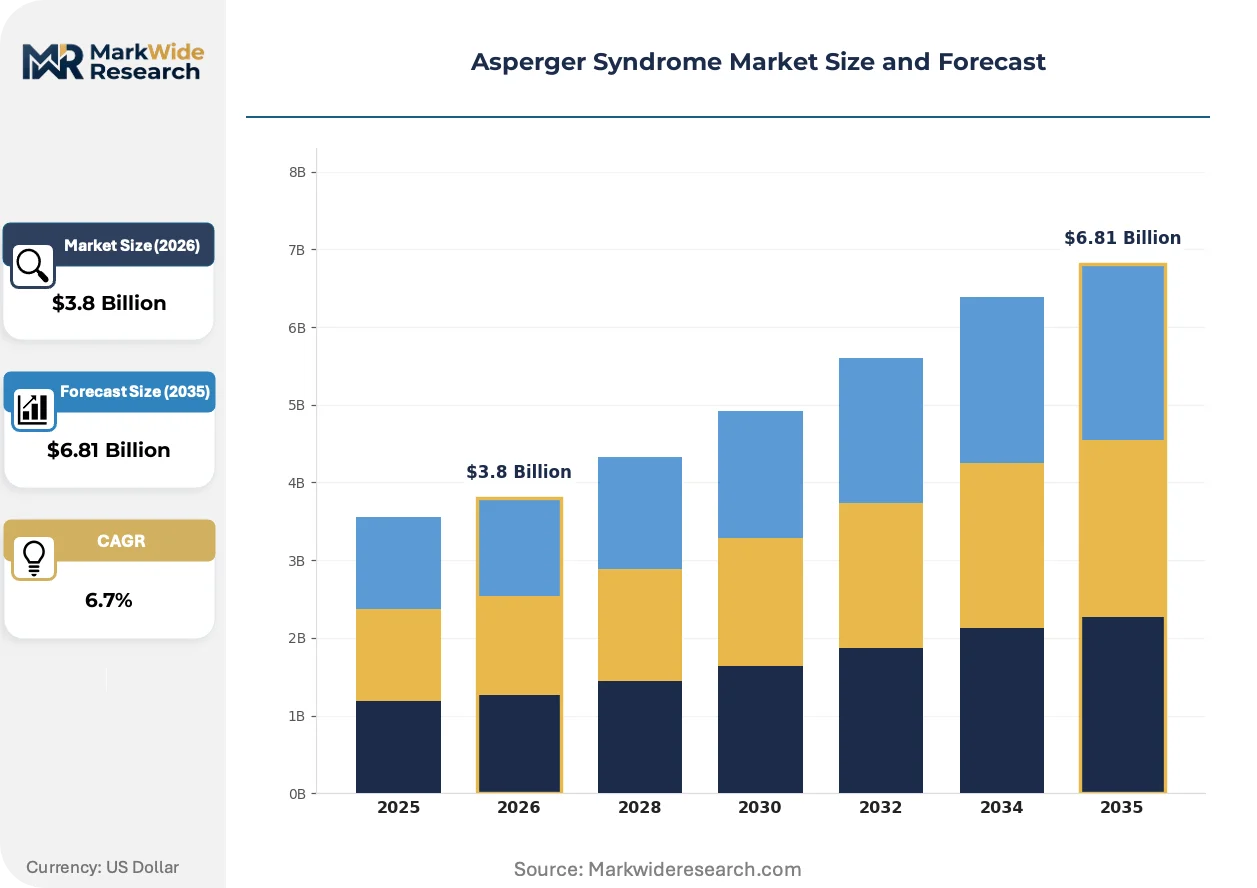
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication, Therapy Services, Assessment Tools, Educational Resources Delivery Model: In-Person, Online Therapy, Group Sessions, Home-Based End User: Individuals, Parents, Schools, Healthcare Professionals Age Group: Children, Adolescents, Adults, Seniors |
| Companies Covered | F. Hoffmann-La Roche, Jazz Pharmaceuticals, Eli Lilly and Company, Shire, Pfizer, Otsuka Pharmaceutical, AbbVie Inc., PaxMedica, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asperger Syndrome Market Emerging Trajectories
Telehealth delivery models are compressing the traditional geography-bound specialist consultation paradigm, while regulatory pressure on pediatric trial design is elevating investment thresholds for pharmaceutical development. These forces are simultaneously expanding access and concentrating capability.
Artificial intelligence-assisted diagnostic screening is consolidating the initial assessment workflow. Pediatric primary care networks in Minnesota and Wisconsin are deploying machine learning tools to flag atypical developmental patterns during routine well-child visits. This capability compression is reducing specialist referral volumes for clear-cut cases while concentrating complex diagnostic work in academic medical centers.
The FDA's evolving guidance on pediatric neurodevelopmental drug trials is extending protocol complexity and patient recruitment timelines. Developers must now incorporate multiple functional endpoints and longer observation periods. Early-phase biotechnology firms are responding by partnering with academic research hospitals possessing established autism research infrastructure.
Self-insured employers and regional health plans are unbundling autism care management from general behavioral health contracts. Third-party administrators in Colorado and Washington are carving out dedicated vendor panels with outcome guarantees. This purchasing pattern shift is most visible in the Mountain West, where narrow network designs are displacing open-access specialist referral models.
Asperger Syndrome Market Segmentation
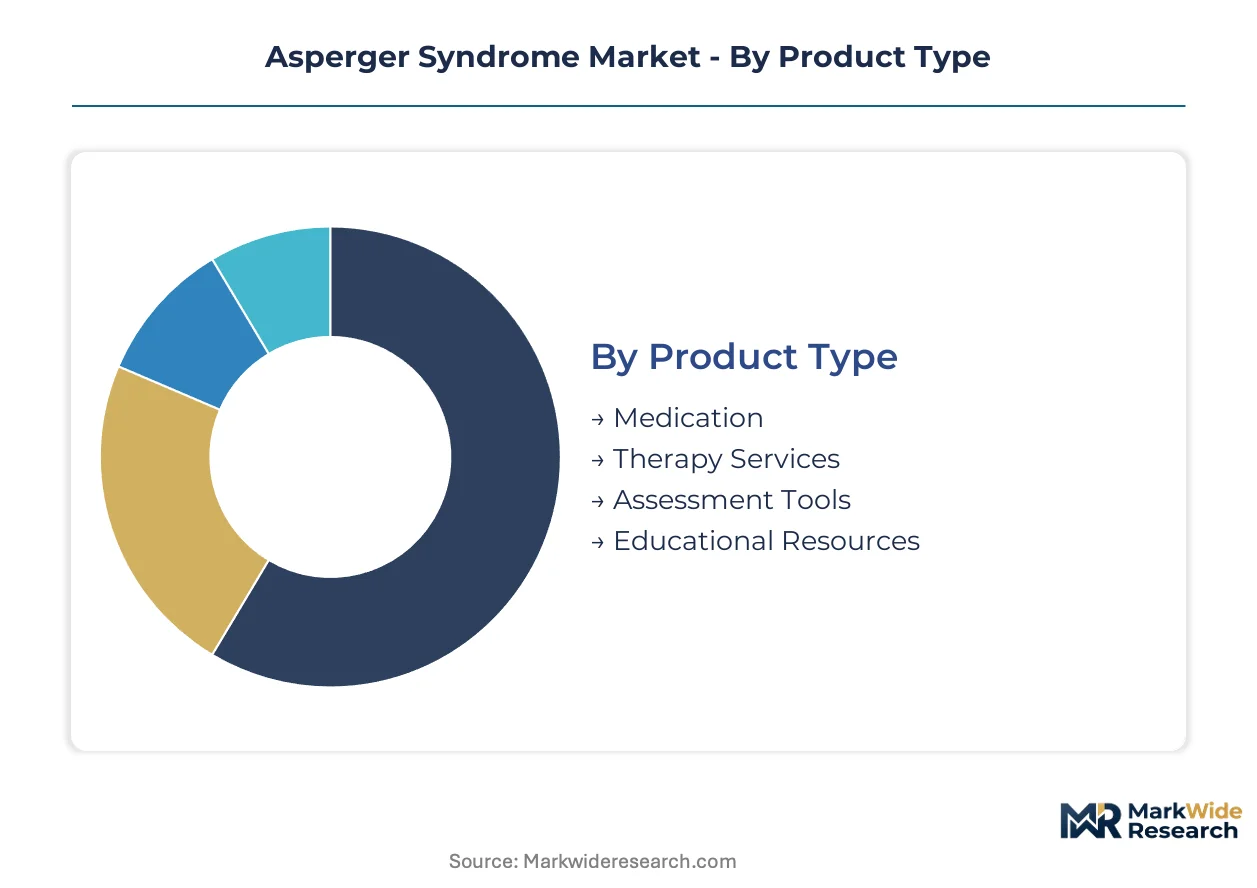
Segmentation in the Asperger syndrome market reveals how service delivery, procurement authority, and developmental life stage reshape vendor priorities. Understanding these divides clarifies where investment concentrates and where reimbursement pathways diverge.
Product Type:
Customization versus standardization tensions run deepest here, with pharmaceutical formulations demanding regulatory uniformity while behavioral interventions adapt to individual neurodevelopmental profiles.
- Medication:Psychotropic compounds target comorbid anxiety, attention deficits, and irritability through FDA-approved pediatric indications. Demand clusters in integrated care networks across Texas and California where Medicaid waivers expand pharmacy benefit coverage for antipsychotic and stimulant classes.
- Therapy Services:Applied behavior analysis, speech-language pathology, and occupational therapy constitute the revenue core, delivered through credentialed practitioner networks. School districts in the Northeast corridor are compressing vendor selection timelines as IDEA enforcement tightens therapeutic staffing mandates.
- Assessment Tools:Standardized instruments including ADOS-2 and ADI-R require certified administrator training and periodic recalibration.
- Educational Resources:Curriculum modifications, social skills training modules, and transition planning materials support IEP compliance.
Most installed capacity flows through Therapy Services. Expansion is steepest in Medication as pediatric neurodevelopmental trial pathways mature.
Delivery Model:
Cost tier stratification dominates this category, with premium in-person consultation yielding to scaled online delivery as payer reimbursement frameworks adapt.
- In-Person:Clinic-based delivery maintains diagnostic authority for complex differential assessments and intensive early intervention protocols. Academic medical centers in Michigan and Ohio anchor regional referral networks for severe presentations requiring multidisciplinary coordination.
- Online Therapy:Synchronous telehealth platforms eliminate geographic barriers to board-certified behavior analyst consultation, particularly in rural counties where specialist scarcity extends wait times beyond sixteen weeks.
- Group Sessions:Social skills programming and peer-mediated interventions reduce per-session cost while targeting core diagnostic features.
- Home-Based:Direct practitioner deployment to residential settings supports generalization of learned behaviors across natural environments.
Volume concentrates in In-Person delivery. The steepest expansion trajectory belongs to Online Therapy as state-level telehealth parity laws proliferate.
End User:
Customer type fragmentation creates divergent procurement rhythms, with institutional purchasers operating on fiscal year cycles while individual decision-making responds to diagnostic timing.
- Individuals:Self-directed adults and transition-age youth navigate vocational rehabilitation and independent living service menus, particularly in post-secondary populations across Colorado and Washington where employer-sponsored autism navigation benefits are emerging.
- Parents:Caregiver purchasers drive early childhood intervention demand, often bridging private pay and public entitlement coverage gaps.
- Schools:District-level procurement of assessment instruments and therapeutic staffing responds to federal educational mandate enforcement and state funding formulas.
- Healthcare Professionals:Pediatric primary care networks deploy screening tools while specialist referrals concentrate diagnostic complexity in academic centers.
Procurement volume flows through Schools. Expansion is most rapid among Individuals as adult diagnostic recognition climbs and vocational service commissioning diversifies.
Age Group:
Maturity gradients shape this category, with well-established pediatric service infrastructure yielding to nascent adult programming as diagnostic persistence across the lifespan gains clinical recognition.
- Children:Early intervention entitlements through IDEA and state early childhood systems concentrate assessment and therapeutic resource deployment in the 3-12 demographic, where neural plasticity arguments justify intensive service allocation.
- Adolescents:Transition planning requirements and secondary social complexity drive demand for combined educational and clinical coordination.
- Adults:Employment support, independent living services, and relationship counseling expand as diagnostic rates in this population climb.
- Seniors:Late-life diagnostic evaluation and aging-in-place support represent emerging service frontiers with limited dedicated infrastructure.
Most service capacity addresses Children. Steepest expansion is occurring in Adults as vocational rehabilitation agencies in Michigan and Ohio commission dedicated social skills programming.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Board-certified behavior analysts and developmental pediatricians cluster in jurisdictions with favorable reimbursement frameworks, concentrating service delivery capacity in specific metropolitan corridors.
United States
Integrated care networks in Texas and California are building dedicated autism service lines as Medicaid waivers expand applied behavior analysis coverage. The FDA's pediatric neurodevelopmental drug trial guidance is extending protocol complexity for pharmaceutical developers targeting Asperger syndrome indications. Academic medical centers in Michigan and Ohio anchor regional referral networks for complex diagnostic assessments.
Germany
Specialized central nervous system research infrastructure supports pharmaceutical development targeting neurodevelopmental conditions. The country's national pharmaceutical regulator maintains stringent pediatric trial standards that shape investment thresholds for drug developers. Clinical research clusters in Munich and Heidelberg concentrate autism spectrum disorder diagnostic expertise and therapeutic innovation.
United Kingdom
National Health Service commissioning frameworks are restructuring autism assessment pathway contracts toward integrated community-based delivery. The Care Quality Commission oversees diagnostic service standards and therapeutic provider registration requirements. London and Manchester metropolitan areas host concentrated behavioral intervention practitioner networks serving pediatric and adult populations.
Japan
Pediatric psychiatric service infrastructure is expanding diagnostic recognition and behavioral intervention access for neurodevelopmental conditions. The Pharmaceuticals and Medical Devices Agency maintains evolving guidance on central nervous system drug development for pediatric indications. Tokyo and Osaka medical districts concentrate specialist assessment capacity and research hospital networks.
Canada
Provincial health authority funding models are diversifying autism service delivery beyond traditional clinic-based models toward community and telehealth platforms. Health Canada regulatory frameworks shape medical device and therapeutic product approval pathways for neurodevelopmental indications. Toronto and Vancouver metropolitan regions anchor multidisciplinary diagnostic and intervention service capacity.
Asperger Syndrome Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across medication, therapeutic service, and diagnostic instrument segments. Market structure tilts toward consolidation in pharmaceutical development where regulatory barriers elevate capital requirements, while behavioral intervention delivery remains fragmented across regional practitioner networks. Three archetypes dominate: multinational pharmaceutical developers with psychiatric portfolios, specialized behavioral health service platforms, and diagnostic instrument manufacturers with certified training ecosystems. Competitive positioning depends on securing Medicaid and commercial payer contracts, plus building credentialed practitioner networks capable of meeting school district procurement timelines.
Within the pharmaceutical developer tier, Eli Lilly and Company, Jazz Pharmaceuticals, and Otsuka Pharmaceutical represent distinct strategic positions. Eli Lilly and Company exemplifies the diversified psychiatric research infrastructure approach, leveraging broad central nervous system development capabilities. Jazz Pharmaceuticals occupies a position as a specialized central nervous system franchise builder with focused therapeutic area concentration. Otsuka Pharmaceutical represents the behavioral health drug discovery archetype, anchoring its portfolio through long-standing investment in neurological and psychiatric indications. These three entities sit within a competitive set where FDA pediatric trial mandates and state-level reimbursement policy shifts determine relative market access.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Jazz Pharmaceuticals |
| Eli Lilly and Company |
| Shire |
| Pfizer |
| Otsuka Pharmaceutical |
| AbbVie Inc. |
| PaxMedica |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Telehealth platform maturation is compressing both service delivery costs and geographic distribution requirements, concentrating pricing power among vendors with established Medicaid payer contracts while fragmenting local clinic margins. This technology shift simultaneously enables scaled online therapy provision and intensifies reimbursement rate competition across traditional in-person service tiers.
Pricing Analysis
The bundled-versus-unbundled service split dominates pricing architecture, with comprehensive care navigation packages commanding premium positioning against à la carte assessment and therapy modules. Price differentiation hinges on certification tier—board-certified behavior analyst credentials versus registered technician levels—and geographic delivery cost differentials between urban corridor and rural county deployment. Pricing pressure stems from commercial insurer fee schedule compression in Florida and Illinois, squeezing outpatient clinic margins. School districts exhibit highest price sensitivity due to fixed entitlement budgets, while self-insured technology sector employers demonstrate lowest sensitivity when outcomes guarantees attach.
Supply Chain Analysis
Warehouse-distribution layer dynamics center on regional clinical staffing pools rather than physical inventory, with hub-and-spoke patterns clustering board-certified behavior analysts around academic medical centers in Michigan, Ohio, and the Northeast corridor. Supply concentration rests on United States credentialing infrastructure, Canadian provincial training programs, and United Kingdom National Health Service commissioning frameworks. Raw material dependencies include ADOS-2 instrument kits, specialized therapeutic curriculum licenses, and proprietary telehealth platform software. Single-source vulnerability concentrates in certified administrator training ecosystems. Distribution runs through school district procurement offices, integrated care network service lines, and direct-to-consumer telehealth portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asperger syndrome market functions as a stable compounder, with IDEA entitlement enforcement and Medicaid waiver expansions generating predictable institutional demand cycles across educational and healthcare procurement channels.
For Market Incumbents: Anchor defensive positioning through backward integration into credentialing training ecosystems, capturing board-certified behavior analyst pipeline control against emerging telehealth pure-plays. Consolidate regional clinic networks in Texas and California where Medicaid waivers widen reimbursement coverage. Vertical integration into assessment instrument distribution—particularly ADOS-2 kit provisioning—secures recurring revenue attachment to diagnostic protocol mandates. For New Entrants and Emerging Players: Launch via employer-sponsored benefits channels, targeting technology sector self-insured corporations adding autism care navigation to employee assistance programs. White-space concentration sits in adult transition services, where vocational rehabilitation agencies in Michigan and Ohio commission social skills programming for post-secondary populations with limited incumbent presence. Digital therapeutics pathway offers expedited FDA breakthrough device designation access for software-based interventions. For Investors and Strategic Acquirers: Valuations sit cheapest among regional behavioral health service platforms with underoptimized Medicaid payer contract portfolios. Long-term viability frames around 5-10 year diagnostic recognition expansion in adult populations and vocational service commissioning diversification. Acquisition target archetype: telehealth-enabled therapy platforms with established state-level telehealth parity law compliance. Signal to watch: FDA digital therapeutics classification decisions for pediatric neurodevelopmental indications as inflection indicator for platform valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Medicaid Payer Contract Expansion | Texas and California waiver expansions widen applied behavior analysis reimbursement access pools. |
| Digital Therapeutics FDA Pathway | Breakthrough device designation criteria expedite software-based intervention market entry timelines. |
| Credentialing Training Ecosystem Control | Board-certified behavior analyst pipeline ownership defends against telehealth pure-play disruption. |
| Employer-Sponsored Benefits Integration | Technology sector self-insured corporations add autism navigation to employee assistance programs. |
| Adult Transition Service Development | Vocational rehabilitation commissioning in Michigan and Ohio addresses underpenetrated post-secondary demand. |
Methodological Framework
Multiple input streams—structured interviews with developmental pediatricians and board-certified behavior analysts, regulatory filing analysis, and school district procurement documentation—were reconciled against secondary validation sources. Primary engagement captured formulary directors at regional health plans, special education administrators in Texas and California districts, and payer access specialists navigating Medicaid waiver implementation. Secondary sources encompassed FDA pediatric neurodevelopmental guidance documents, IDEA enforcement records, state-level telehealth parity legislation tracking, and CMS Medicare autism service utilization data. Bottom-up service volume estimates triangulated with top-down educational entitlement expenditure flows.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, delivery model, end user archetype, and age group maturity gradient. CAGRs derived from enrollment trend extrapolation in IDEA-mandated programs and Medicaid waiver expansion trajectories. Forecast inputs incorporated telehealth reimbursement parity law adoption curves and FDA digital therapeutics classification timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under state Medicaid funding freeze scenarios or diagnostic criteria revision by the American Psychiatric Association. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Enzyme Replacement Therapy Market
Specialty Medicine
Avascular Necrosis Market
Specialty Medicine
Tropical Spastic Paraparesis Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Global Postmenopausal Osteoporosis Market
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
Urinary Retention Market
Specialty Medicine
US Actinic Keratosis Treatment Market
Specialty Medicine
Transient Ischemic Attack Market
Specialty Medicine
Dry Eye Syndrome Market
Specialty Medicine
Hereditary Angioedema Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market
Specialty Medicine
Intraductal Papilloma Market
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market
Specialty Medicine
Serotonin Syndrome Market
Specialty Medicine
Growth Hormone Deficiency Market