
 Global Non-Small Cell Lung Cancer Diagnostics Market | 2026-2036
Global Non-Small Cell Lung Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Small Cell Lung Cancer Diagnostics Market Foresight
Hospital-based oncology workflows is shifting toward outpatient diagnostic laboratories and specialized clinics as healthcare systems prioritize cost containment and faster turnaround times. F. Hoffmann-La Roche Ltd leverages its integrated diagnostics-pharmaceutical platform to dominate companion diagnostic development. Thermo Fisher Scientific sustains broad reagent and instrument market presence across multiple molecular testing modalities. Illumina Inc anchors the next-generation sequencing infrastructure that underpins most comprehensive genomic profiling programs.
Non-small cell lung cancer diagnostics encompasses biomarker testing, imaging techniques, molecular diagnostics, histopathology, and immunohistochemistry methods used to identify cellular mutations, stage disease progression, and guide targeted therapeutic selection in adenocarcinoma, squamous cell carcinoma, and large cell carcinoma subtypes. These technologies detect EGFR, ALK, ROS1, BRAF, KRAS, MET, RET, and NTRK alterations with defined analytical sensitivity thresholds, enabling clinicians to match patients with FDA-approved or investigational tyrosine kinase inhibitors and immunotherapy regimens. Molecular diagnostics and next-generation sequencing command the highest margin pools as reimbursement aligns with therapy-linked companion diagnostic claims, while liquid biopsy technology represents the fastest-expanding segment as blood-based sampling reduces invasive tissue procurement requirements. Imaging techniques and histopathology remain mature, high-volume categories with stable but slower expansion trajectories.
FDA PMA and 510(k) pathways shape device commercialization timelines and clinical evidence requirements for all United States market entrants, while EMA companion diagnostic guidelines and IVDR transition timelines govern European market access conditions. China's NMPA innovation review pathways and national reimbursement list updates determine which molecular tests achieve hospital procurement eligibility. Stakeholders must monitor evolving payer coverage policies for multi-gene panel tests versus single-analyte assays to anticipate revenue model sustainability.
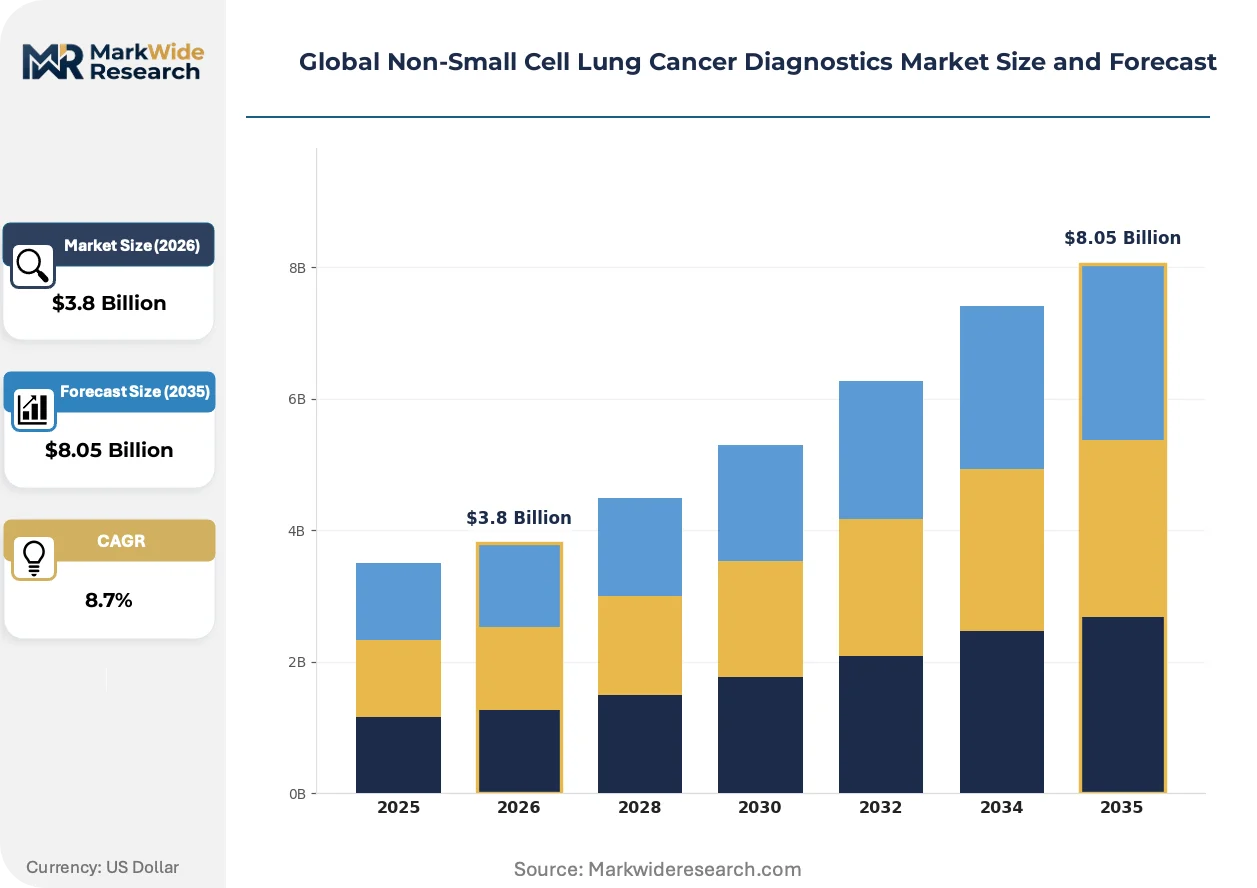
Market Dynamics
Companion diagnostic reimbursement alignment with targeted therapy approvals is compressing commercialization timelines and forcing test developers to secure FDA PMA clearance before launch rather than pursuing 510(k) pathways.
Growth Catalysts
- Liquid Biopsy Technology Maturation:Blood-based circulating tumor DNA detection reduces tissue biopsy failure rates in advanced-stage patients. Diagnostic laboratories in the United States and Germany are prioritizing platform investments here.
- EMA Companion Diagnostic Guidelines:European regulatory clarity on co-development requirements accelerates parallel drug-test submission strategies. This reduces time-to-market for multinational pharmaceutical sponsors.
- China NMPA Innovation Review Pathways:Priority review for breakthrough molecular diagnostics enables faster hospital procurement list inclusion. Domestic manufacturers leverage this to compete with imported platforms.
Market Restraints
- Reimbursement Fragmentation:United States Medicare coverage determinations for multi-gene panels lag behind single-analyte test policies. This creates revenue uncertainty for comprehensive genomic profiling providers.
- Supply Concentration in Sequencing Reagents:Three vendors control critical NGS library preparation chemistries. Any disruption affects downstream assay availability across diagnostic networks.
- IVDR Transition Timelines:European In Vitro Diagnostic Regulation conformity assessment bottlenecks delay CE marking renewals. Smaller assay developers face certification backlogs extending 18-24 months.
Strategic Opportunities
- Minimal Residual Disease Monitoring:Post-surgical recurrence detection represents an underserved application with limited approved assays. Early movers can establish clinical utility evidence before competitive entry.
- India CDSCO Streamlined Registration:Recent regulatory harmonization initiatives reduce import license processing for reference-standard molecular platforms. Multinational diagnostics firms can expand beyond metro hospital chains.
- Artificial Intelligence-Enabled Pathology:Digital image analysis for PD-L1 scoring converges with molecular testing workflows. Integrated diagnostic reports command premium pricing from oncology practices.
Industry Challenges
- Bioinformatics Pipeline Validation:Variant interpretation software requires continuous curation against evolving clinical knowledgebases. Laboratories must maintain specialized computational biology staff.
- Cross-Platform Standardization:Discordant results between tissue and liquid biopsy specimens complicate clinical decision-making. Harmonization initiatives across proficiency testing programs remain incomplete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Small Cell Lung Cancer Diagnostics Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biomarker Testing, Imaging Techniques, Molecular Diagnostics, Histopathology, Immunohistochemistry Application: Early Detection, Mutation Analysis, Treatment Monitoring, Prognosis Evaluation, Recurrence Detection End User: Diagnostic Laboratories, Cancer Research Centers, Academic Institutions, Biopharmaceutical Companies, Specialized Clinics Technology: Next-Generation Sequencing, Polymerase Chain Reaction, Fluorescence In Situ Hybridization, Liquid Biopsy, Mass Spectrometry |
| Companies Covered | F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, Illumina Inc, Agilent Technologies, Qiagen, Abbott, Bio-Rad Laboratories, Neogenomics Laboratories, Myriad Genetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Small Cell Lung Cancer Diagnostics Market Shifts & Advancements
Next-generation sequencing workflows are fragmenting into modular, point-of-care compatible formats while regulatory frameworks tighten evidentiary requirements for algorithm-driven diagnostic outputs.
Comprehensive genomic profiling using hybrid-capture NGS is overtaking single-gene PCR testing as the standard-of-care for treatment-naive advanced NSCLC. Major cancer centers in the United States now reflex to 500+ gene panels. This is overtaking the historical model of sequential biomarker testing and compressing pathology department turnaround time expectations to under 10 days.
FDA PMA pathway requirements for companion diagnostics now mandate prospective clinical trial enrollment rather than retrospective validation studies. This elevates development costs but strengthens payer confidence in test-treatment linkages. Oncology pharmaceutical sponsors in the United States are responding by integrating diagnostic co-development earlier in Phase II programs.
Outpatient diagnostic laboratories are capturing hospital oncology referrals previously managed within academic medical center pathology departments. Community-based molecular testing networks in Germany and China offer faster specimen logistics and competitive pricing. This channel migration is most visible in United States Medicare Advantage populations where prior authorization requirements favor external laboratory contracts.
Global Non-Small Cell Lung Cancer Diagnostics Market Segmentation
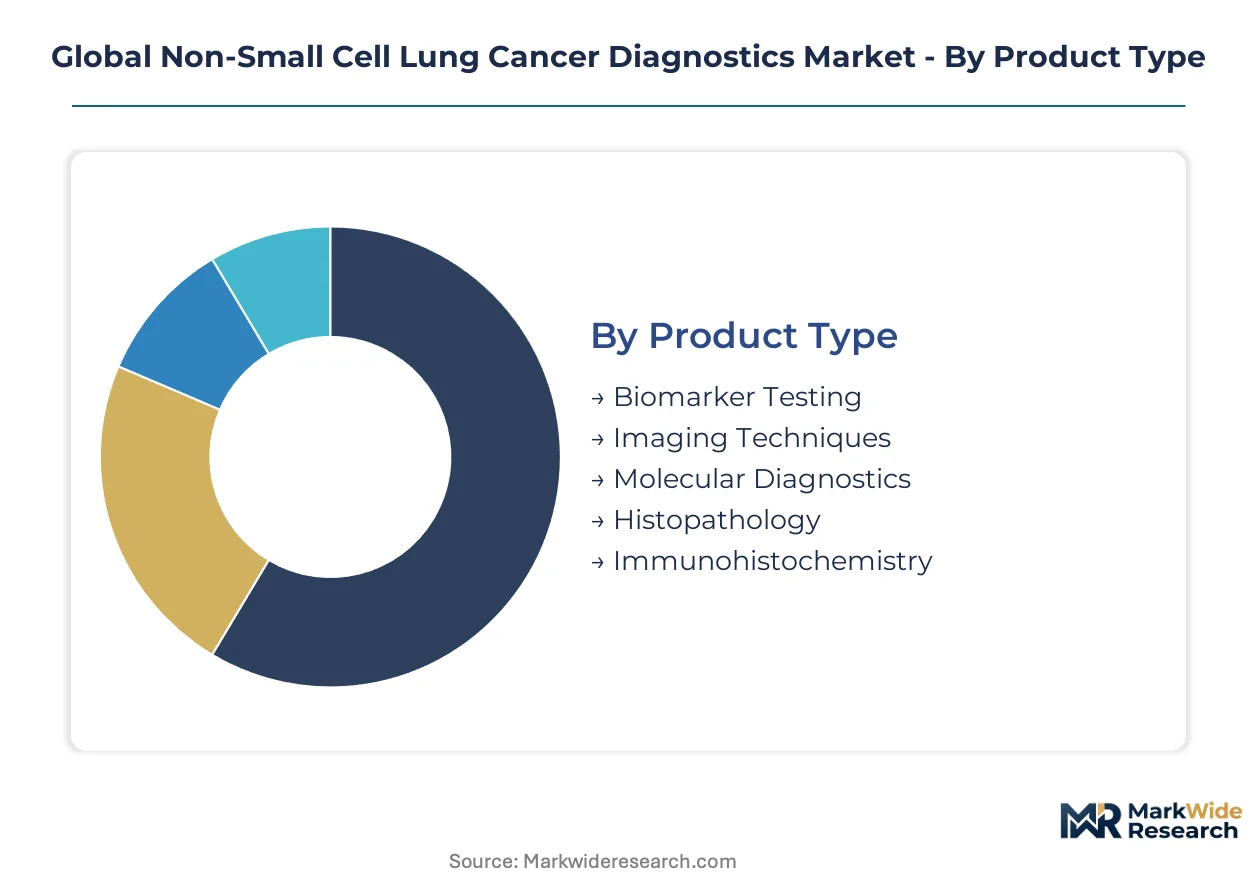
Segmentation in NSCLC diagnostics reveals how testing complexity stratifies across clinical settings. Product portfolios must balance high-throughput automation for centralized laboratories against modular flexibility for decentralized oncology workflows.
Product Type:
Standardization dominates high-volume categories while biomarker testing demands customization for therapy-matching protocols.
- Molecular Diagnostics:Hybrid-capture and amplicon-based assays detect actionable mutations with defined analytical sensitivity thresholds. United States cancer centers prioritize 500+ gene panels for treatment-naive patients, compressing turnaround expectations below 10 days.
- Biomarker Testing:Single-analyte and multi-plex protein assays identify PD-L1 expression, TMB scores, and MSI status to guide immunotherapy selection. German outpatient laboratories are expanding automated IHC platforms here to capture hospital referrals.
- Imaging Techniques:CT, PET-CT, and MRI modalities stage disease progression and monitor treatment response across adenocarcinoma subtypes.
- Histopathology:Tissue processing and morphological classification remain essential for initial diagnosis in squamous cell carcinoma.
- Immunohistochemistry:Antibody-based protein detection supports subtype classification and predictive biomarker quantification.
Leading the category by volume: Histopathology. Growing fastest: Molecular Diagnostics.
Application:
Clinical utility concentrates where reimbursement aligns with therapy-linked diagnostic claims.
- Mutation Analysis:Comprehensive genomic profiling identifies EGFR, ALK, ROS1, BRAF, KRAS, MET, RET, and NTRK alterations to match patients with approved tyrosine kinase inhibitors. China's NMPA innovation review pathways accelerate companion diagnostic approvals here.
- Treatment Monitoring:Serial ctDNA measurements track therapeutic response and resistance emergence in advanced-stage patients. United States Medicare Advantage prior authorization requirements favor external laboratory contracts for longitudinal testing.
- Early Detection:Screening protocols target high-risk populations with low-dose CT and emerging blood-based signatures.
- Prognosis Evaluation:Risk stratification models integrate molecular and clinical variables to predict survival outcomes.
- Recurrence Detection:Minimal residual disease monitoring identifies post-surgical molecular persistence with limited approved assays currently available.
Highest reimbursement capture: Mutation Analysis. Steepest expansion trajectory: Recurrence Detection.
End User:
Channel migration reflects cost containment pressures and specimen logistics optimization.
- Diagnostic Laboratories:Centralized molecular testing networks offer competitive pricing and faster turnaround than academic pathology departments. Community-based platforms in Germany and China capture hospital oncology referrals previously managed internally.
- Specialized Clinics:Outpatient oncology practices integrate point-of-care molecular testing for immediate treatment decisions. United States Medicare coverage determinations increasingly favor external contracts over hospital-based testing.
- Cancer Research Centers:Academic institutions drive clinical trial enrollment for companion diagnostic co-development programs.
- Biopharmaceutical Companies:Pharmaceutical sponsors integrate diagnostic development into Phase II oncology programs to satisfy FDA PMA requirements.
- Academic Institutions:Medical school pathology departments maintain reference-standard testing for complex variant interpretation.
Volume concentration: Diagnostic Laboratories. Fastest channel growth: Specialized Clinics.
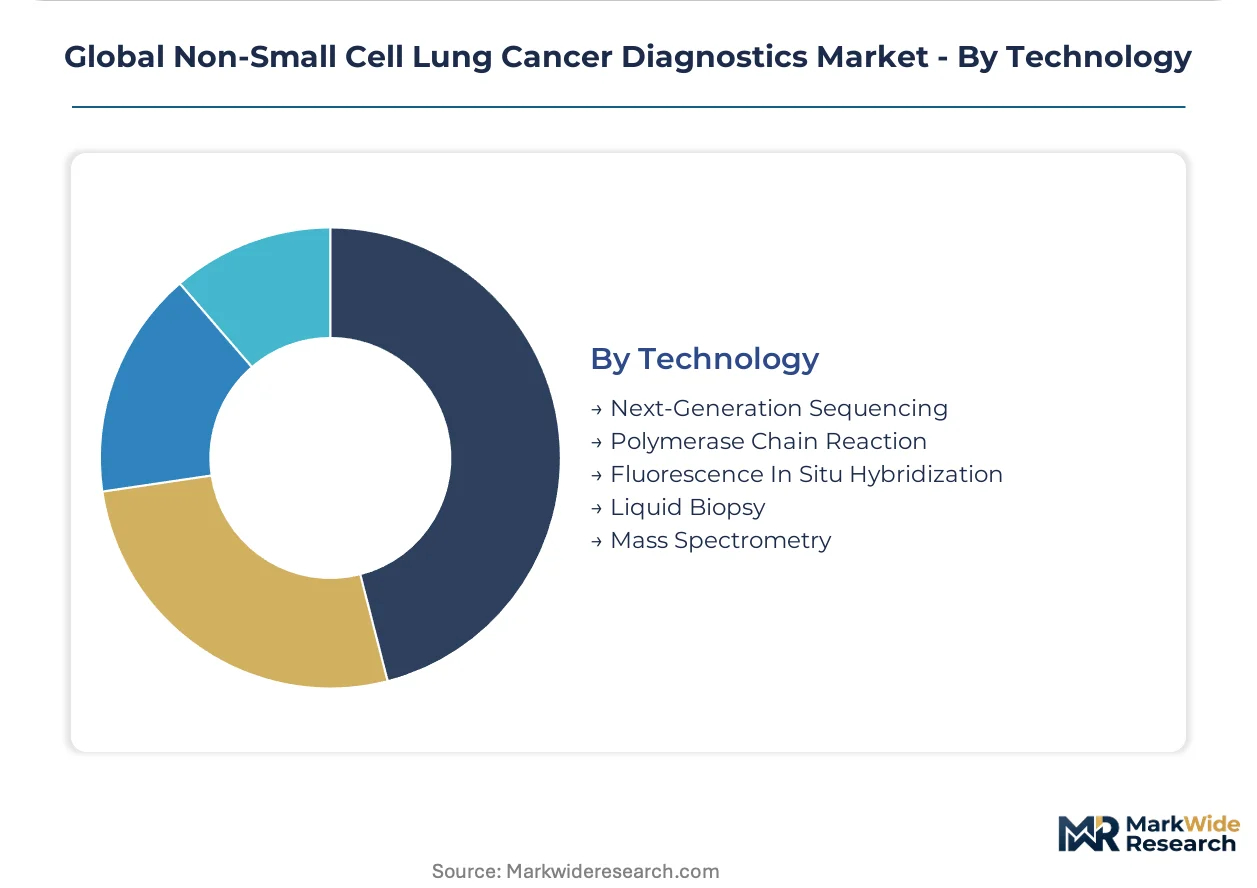
Technology:
Platform selection balances breadth of genomic coverage against cost per sample and regulatory validation burden.
- Next-Generation Sequencing:Hybrid-capture workflows deliver comprehensive genomic profiling with simultaneous detection of single nucleotide variants, indels, copy number alterations, and structural rearrangements. Three vendors control critical library preparation chemistries, creating supply concentration risk.
- Liquid Biopsy:Circulating tumor DNA detection from plasma reduces tissue biopsy failure rates in advanced-stage patients where tumor sampling is contraindicated. Diagnostic laboratories in the United States and Germany prioritize platform investments here.
- Polymerase Chain Reaction:Real-time and digital PCR methods provide rapid, cost-effective single-gene testing for known hotspot mutations.
- Fluorescence In Situ Hybridization:Cytogenetic analysis detects ALK, ROS1, and RET rearrangements with established clinical validation.
- Mass Spectrometry:Proteomic and metabolomic profiling supports emerging multi-omics diagnostic strategies.
Installed base leader: Polymerase Chain Reaction. Gaining share fastest: Liquid Biopsy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shanghai and Shenzhen accelerate molecular diagnostics manufacturing concentration, while precision oncology infrastructure investments in Munich and Boston create parallel demand hubs for companion diagnostic development.
United States
Medicare Advantage prior authorization requirements favor external laboratory contracts, channeling hospital oncology referrals toward outpatient diagnostic networks. FDA PMA pathway mandates for companion diagnostics elevate clinical evidence standards before commercialization. The Greater Boston biotech corridor anchors companion diagnostic co-development programs between pharmaceutical sponsors and testing platforms.
Germany
Outpatient diagnostic laboratories capture hospital referrals through faster specimen logistics and competitive pricing for molecular testing services. EMA companion diagnostic guidelines provide regulatory clarity for parallel drug-test submission strategies. The Munich metropolitan area concentrates automated IHC platform investments targeting immunotherapy biomarker quantification.
China
NMPA innovation review pathways accelerate breakthrough molecular diagnostic approvals and hospital procurement list inclusion. National reimbursement updates determine eligibility for multi-gene panel testing in cancer centers. The Yangtze River Delta biopharma cluster hosts domestic manufacturers competing with imported NGS platforms through prioritized regulatory channels.
Japan
PMDA consultation frameworks for in vitro diagnostics streamline companion diagnostic approval timelines alongside oncology drug submissions. National health insurance pricing revisions for genomic medicine tests expand patient access to comprehensive profiling. The Kanto region around Tokyo maintains reference-standard pathology networks for complex variant interpretation.
India
CDSCO streamlined registration processes reduce import license processing timelines for reference-standard molecular platforms. Metro hospital chains in Delhi and Mumbai expand precision oncology programs requiring diagnostic infrastructure partnerships. Domestic diagnostic chains leverage regulatory harmonization to deploy NGS services beyond tier-one urban centers.
Global Non-Small Cell Lung Cancer Diagnostics Market Competitive Landscape
Top-tier vendors anchor integrated diagnostics-pharmaceutical platforms, while mid-tier specialists concentrate on modular assay development and regional laboratory services. The market structure reflects consolidation around sequencing infrastructure providers and fragmentation across biomarker-specific test developers. Three strategic archetypes dominate: vertically integrated life science conglomerates, pure-play molecular diagnostics specialists, and laboratory service networks with captive assay portfolios. Competitive moves center on companion diagnostic co-development partnerships and point-of-care testing platform miniaturization.
Within the integrated platform tier, F. Hoffmann-La Roche Ltd and Thermo Fisher Scientific exemplify divergent approaches to market presence. Roche anchors its position through pharmaceutical-diagnostic convergence in oncology therapeutic areas. Thermo Fisher occupies a broad reagent and instrument supply role across multiple molecular testing modalities. Illumina Inc represents the sequencing infrastructure archetype, with its platform serving as the underlying technology for most comprehensive genomic profiling programs. These three entities collectively illustrate how market position derives from control over critical technology layers rather than end-user service delivery alone.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| Illumina Inc |
| Agilent Technologies |
| Qiagen |
| Abbott |
| Bio-Rad Laboratories |
| Neogenomics Laboratories |
| Myriad Genetics |
| Others |
Supply & Pricing Matrix
Companion diagnostic certification tiers bifurcate sharply between FDA PMA-cleared assays and laboratory-developed tests, with that divergence manifesting in both pricing premiums and supply chain qualification requirements. Premium-tier vendors command sustained margin pools through captive reagent supply chains and locked instrument placements, while commodity assay providers face cost compression from centralized laboratory procurement.
Pricing Analysis
Short lead-time premiums dominate contract structures for companion diagnostic co-development programs, with pharmaceutical sponsors paying substantial uplifts for expedited FDA PMA pathway completion. Pricing stratifies across premium, standard, and economy tiers based on analytical sensitivity thresholds and regulatory validation depth. Cost compression in laboratory-developed test segments is intensifying because Medicare coverage determinations increasingly favor externally validated platforms. Hospital-based pathology departments demonstrate highest price sensitivity, while biopharmaceutical sponsors show lowest sensitivity given therapy-linkage requirements.
Supply Chain Analysis
Single-source vulnerability sits with Illumina for sequencing flow cells and Thermo Fisher for library preparation chemistries, creating concentrated dependency at critical technology layers. Manufacturing anchors in the United States, China, and Germany for instrument assembly, with Singapore and Ireland hosting reagent production facilities. Supply chain risk centers on tariff exposure for Chinese-manufactured NGS consumables entering United States diagnostic networks. Distribution runs through specialized cold-chain logistics providers serving hospital systems and reference laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Library preparation chemistry capacity constraints prop pricing power for incumbent platform vendors, with supply-constrained segments commanding sustained premium capture. Reagent manufacturing bottlenecks limit competitive entry and reinforce existing margin structures.
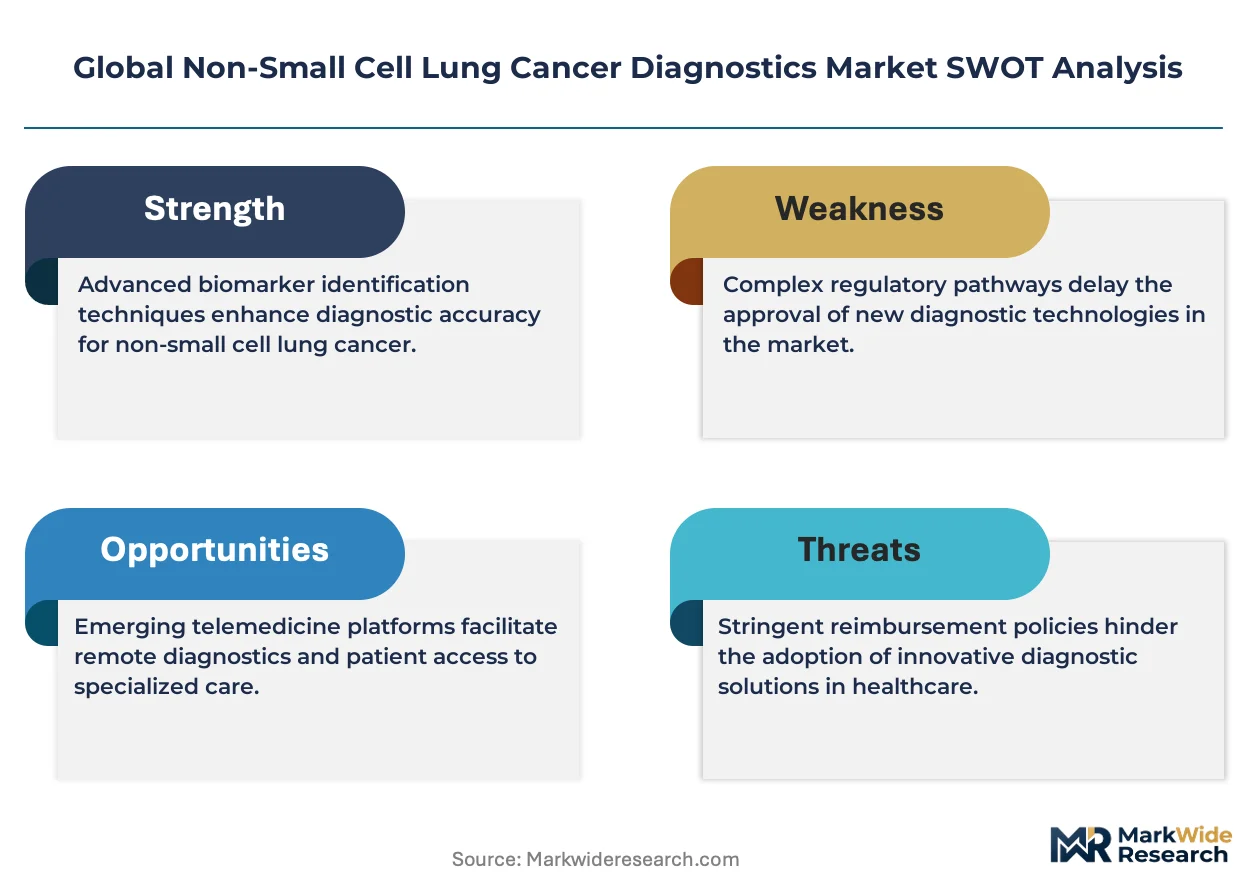
For Market Incumbents: Anticipate liquid biopsy platform commoditization by securing exclusive companion diagnostic co-development partnerships with late-stage oncology sponsors. Backward integration into proprietary assay chemistries defends margin position against open-source NGS workflow entrants. Prioritize automated IHC platform placements in German outpatient laboratories to capture channel migration from academic pathology departments. For New Entrants and Emerging Players: Enter via minimal residual disease monitoring assays, where clinical utility evidence gaps create white-space opportunity before competitive saturation. Target India CDSCO streamlined registration pathways to deploy reference-standard molecular platforms beyond metro hospital chains. Pursue artificial intelligence-enabled pathology integration as differentiated go-to-market positioning against established biomarker testing vendors. For Investors and Strategic Acquirers: Re-rating potential sits with modular point-of-care molecular diagnostics specialists given outpatient channel migration catalysts. Long-term viability over the next decade hinges on regulatory validation depth and reimbursement pathway security. Acquisition target archetype: liquid biopsy assay developers with prospective clinical trial enrollment completed. Signal to watch: FDA PMA pathway backlog clearance rates as inflection indicator for commercialization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-development | Early Phase II integration with pharmaceutical sponsors satisfies FDA PMA evidence requirements. |
| Liquid Biopsy Platform Expansion | Plasma-based ctDNA detection reduces tissue biopsy failure rates in advanced-stage patients. |
| Automated IHC Platform Deployment | PD-L1 scoring automation captures German outpatient laboratory channel migration. |
| AI-Enabled Pathology Integration | Digital image analysis converges with molecular testing for premium diagnostic reporting. |
| India CDSCO Registration Streamlining | Reduced import license processing expands molecular diagnostics beyond tier-one urban centers. |
Research Methodology
Independent corroboration across companion diagnostic development executives, regulatory affairs leads at molecular diagnostics firms, hospital pathology department directors, and Medicare coverage policy specialists underwrites the qualitative findings. Primary interviews with biopharmaceutical sponsor diagnostic strategists and GPO contracts managers combined with secondary validation from FDA PMA filings, EMA companion diagnostic submissions, ClinicalTrials.gov enrollment records, and CMS national coverage determination databases. Bottom-up assay volume modeling and top-down market sizing triangulate to convergent estimates.
Comparable-period anchoring to historical companion diagnostic approval timelines and reimbursement pathway establishment periods structured the projection horizon. Segmentation dimensions modeled include product type, application, end user, technology platform, and regional regulatory cluster. CAGRs derive from therapy-linked diagnostic claim expansion rates and precision oncology infrastructure investment trajectories. Forecast inputs incorporate liquid biopsy adoption curves and multi-gene panel reimbursement policy evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under IVDR transition bottleneck scenarios and Medicare coverage determination delays. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and pharmaceutical sponsor diagnostic co-development commitment levels. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Predictive Disease Analytics Market
Diagnostics
Spain in-Vitro Diagnostics Market
Diagnostics
Global Women's Health Diagnostics Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market
Diagnostics
Liver Function Tests Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Middle East and Africa HIV Diagnosis and Treatment Market
Diagnostics
Connected Diagnostics Market
Diagnostics
Critical Care Diagnostics Market
Diagnostics
Meningitis Diagnosis and Treatment Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
Infectious Disease Point-Of-Care (POC) Diagnostics Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
Global Lateral Flow Assay Market
Diagnostics
Mycoplasma Diagnostics Market
Diagnostics
Animal Auto-Immune Disease Diagnostics Market