
 Hemangioma Treatment Market | 2026-2036
Hemangioma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hemangioma Treatment Market Intelligence
Telemedicine consultation for diagnosis and follow-up care is expanding the service component of hemangioma treatment protocols. This shift allows for earlier intervention and monitoring, particularly for infantile cases. Pierre Fabre leverages its specialized dermatological portfolio to lead in topical solutions. Meanwhile, Eton Pharmaceuticals specializes in developing novel formulations for rare pediatric diseases, and Pfizer competes with its broad portfolio of corticosteroids and immunomodulators.
Hemangioma treatment encompasses medical and procedural interventions designed to manage benign vascular tumors, primarily composed of endothelial cells. These therapies aim to halt proliferation, induce regression, and prevent complications like ulceration or functional impairment. Oral beta blockers, specifically propranolol, represent the first-line therapy for problematic infantile hemangiomas. Pediatric clinics and specialized hospitals constitute the primary end-user channels, where early diagnosis and treatment initiation are critical.
Regulatory frameworks established by the FDA in the United States and the EMA in Europe govern the approval and labeling of systemic treatments like beta blockers. In China, the NMPA's guidelines for pediatric drug development influence market access and clinical trial requirements for new therapies. The key decision for drug developers is whether to pursue orphan drug designations for specific congenital hemangioma subtypes or focus on expanding indications for existing therapies.
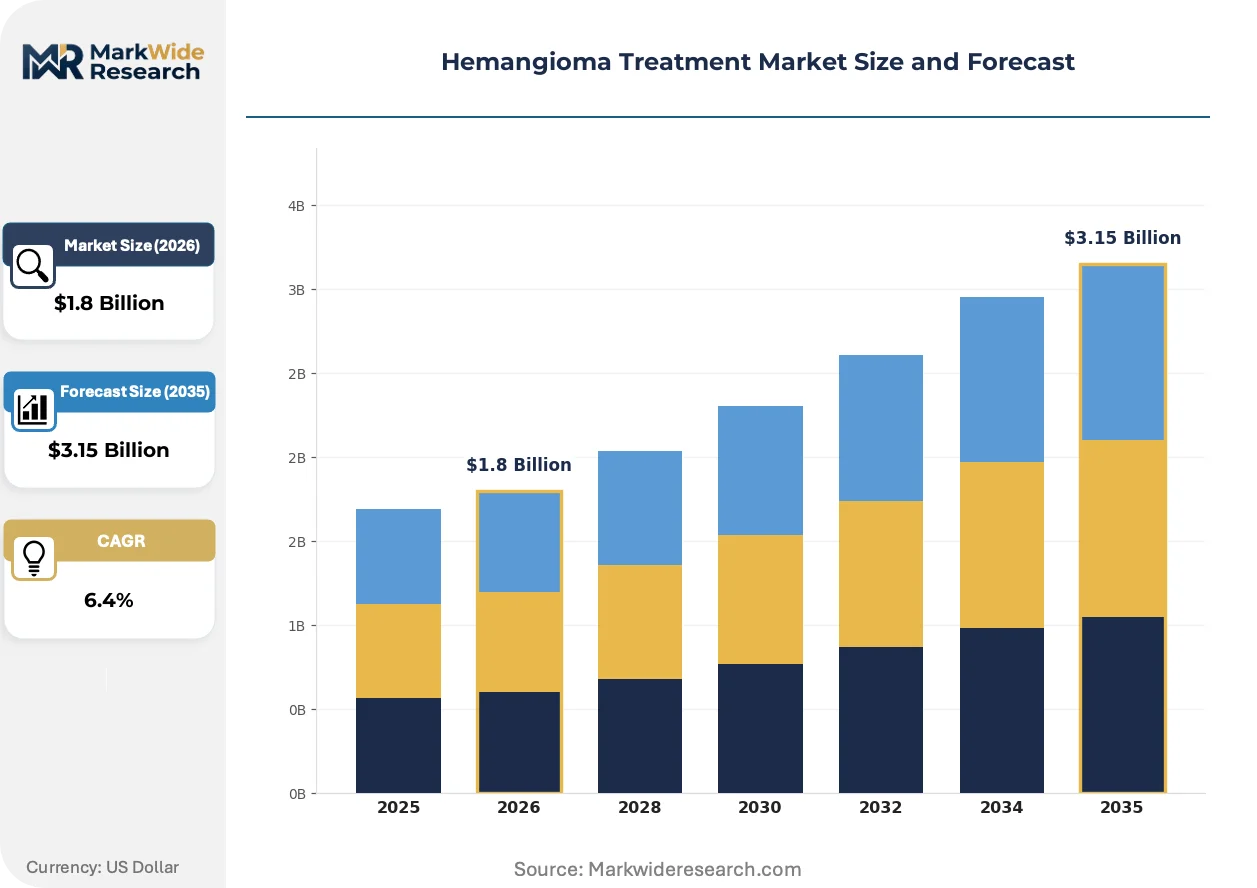
Market Dynamics
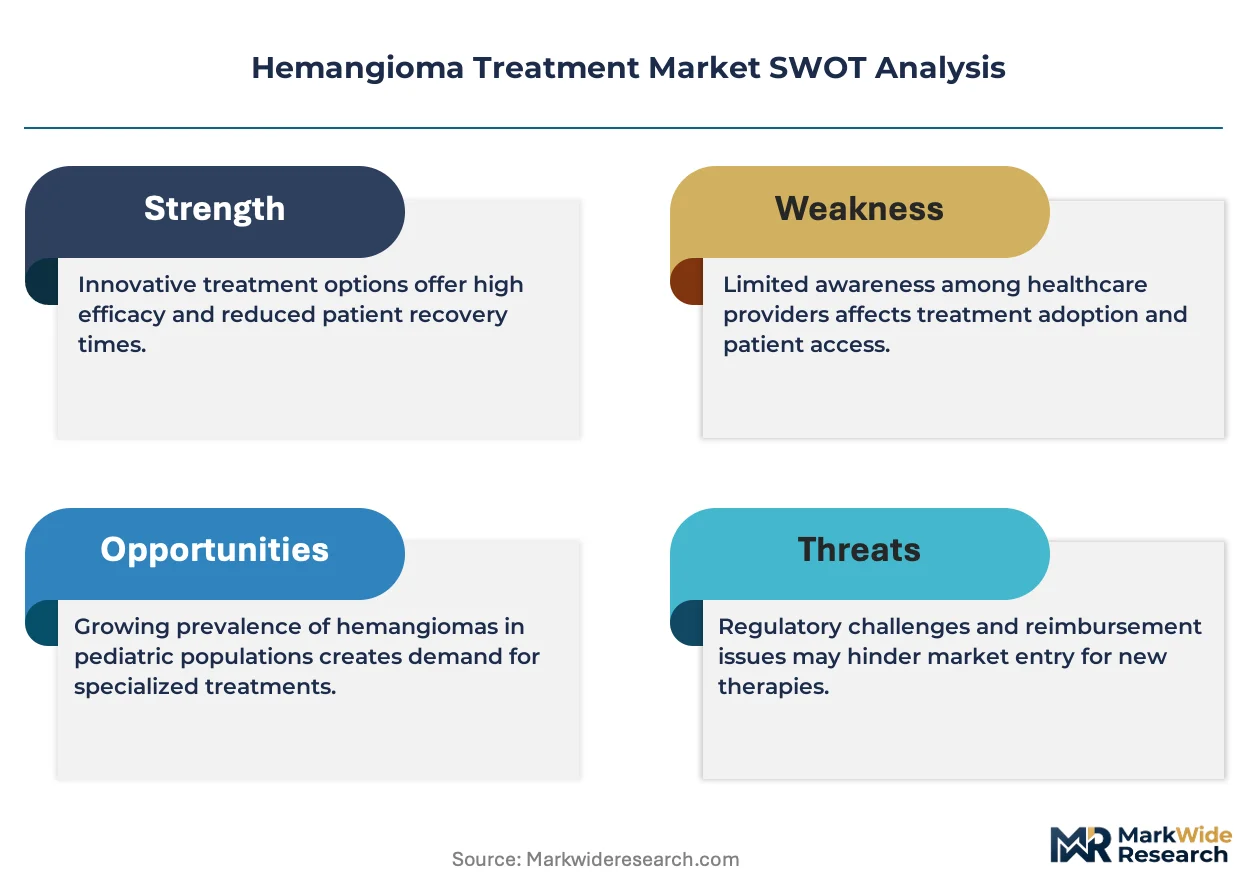
The primary structural force is the codification of non-invasive, systemic therapies as the first-line treatment for problematic infantile hemangiomas. This displaces older, more invasive methods and centers market value on approved oral formulations and specialized pediatric care delivery.
Growth Catalysts
- Regulatory Approvals:FDA and EMA clearance for pediatric-specific oral propranolol provides a standardized, less invasive therapy, accelerating adoption in pediatric clinics.
- Telemedicine Integration:The expansion of telehealth for diagnosis and follow-up enables earlier intervention and improves access for patients in remote geographical areas.
- Specialized Infrastructure:Growth in pediatric dermatology centers in nations like Germany and the United States concentrates expertise and demand for advanced protocols.
Market Restraints
- Reimbursement Variability:Inconsistent coverage policies for newer formulations across national healthcare systems and private insurers create patient access barriers.
- Diagnostic Challenges:Misdiagnosis or differentiation from other vascular anomalies without specialized expertise can delay appropriate treatment initiation.
- Off-Label Use:The continued off-label prescription of adult corticosteroids or compounded beta-blockers undermines the market for approved pediatric formulations.
Strategic Opportunities
- Orphan Drug Designation:Pursuing orphan drug status for therapies targeting rare congenital hemangioma subtypes offers significant regulatory and commercial incentives.
- Topical Formulation Development:A need exists for more effective, non-systemic topical treatments for superficial hemangiomas to avoid systemic side effects.
- Emerging Markets Penetration:Expanding access to diagnostics and first-line therapies in countries with developing pediatric care infrastructure presents a long-term growth opportunity.
Industry Challenges
- Specialist Scarcity:A shortage of pediatric dermatologists and vascular anomaly specialists, particularly outside major urban centers, limits access to expert diagnosis and management.
- Parental Adherence:Ensuring consistent administration of long-term oral medications and adherence to monitoring schedules for infantile hemangiomas is a significant operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemangioma Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beta Blockers, Corticosteroids, Laser Therapy, Surgery, Immunomodulators Therapy Area: Infantile, Congenital, Cavernous, Mixed, Superficial End User: Pediatric Clinics, Dermatology Centers, Specialized Hospitals, Outpatient Facilities Delivery Mode: Oral Administration, Topical Application, Intralesional Injection, Laser-based Procedures |
| Companies Covered | Pfizer, Bausch Health, Pierre Fabre, Bristol-Myers Squibb, Akrimax Pharmaceuticals, AstraZeneca, Eton Pharmaceuticals, Bayer, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemangioma Treatment Market Strategic Shifts & Innovations
The convergence of pharmaceutical advancements with digital health platforms is creating more personalized and accessible treatment pathways for hemangiomas. This evolution is moving care beyond specialized centers, enabling earlier and more consistent patient management across diverse geographies.
Novel liquid oral propranolol formulations provide a precise, dose-adjustable treatment specifically designed for infants. Pediatric clinics and hospitals are rapidly adopting these FDA and EMA-approved medications as the primary intervention for complicated cases. This shift away from compounded alternatives is rewriting the standard of care by improving safety, efficacy, and dosing accuracy.
Mandates from regulators like the FDA and EMA for pediatric-specific clinical trials are shaping the development pipeline. These rules require drug developers to generate safety and efficacy data directly in pediatric populations, rather than extrapolating from adult studies. Systemic therapy developers are most affected, now embedding pediatric investigation plans into their earliest strategic decisions.
A pronounced shift toward telemedicine for initial consultations and long-term monitoring is altering care delivery models. This digital-first approach disrupts the reliance on frequent, in-person visits to specialists, particularly for follow-up care after treatment stabilization. The trend is most advanced in the United States and parts of Europe, where reimbursement for virtual care is established.
Hemangioma Treatment Market Segmentation
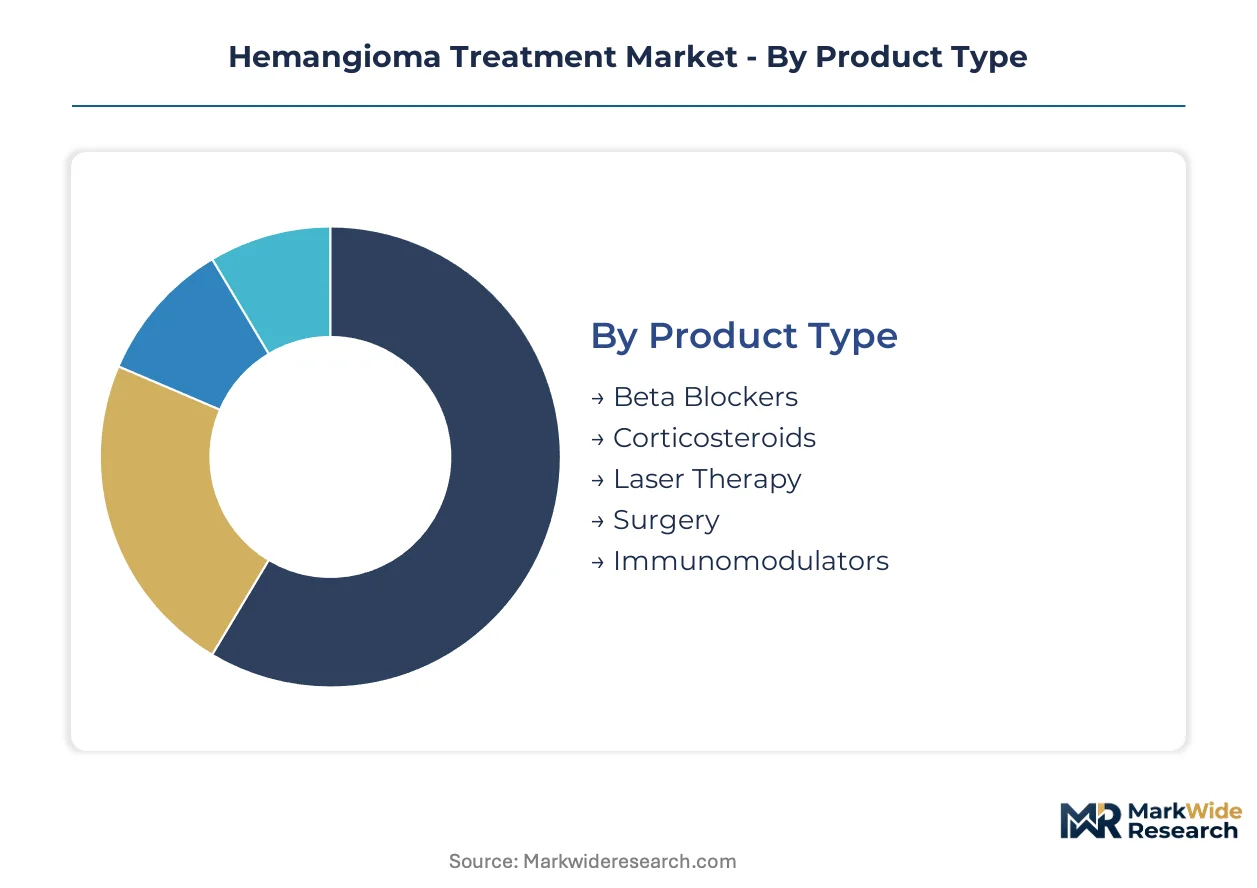
The Hemangioma Treatment Market segments across distinct product types, therapy areas, end-user profiles, and delivery modes. Understanding these categorizations reveals the varied pathways for managing benign vascular tumors, from pharmacological interventions to procedural therapies. This detailed segmentation helps stakeholders identify specific patient needs and market opportunities.
Product Type:
The regulatory approval burden significantly shapes the product type landscape, with systemic therapies like beta blockers requiring extensive FDA and EMA clearance for pediatric populations.
- Beta Blockers:These systemic medications, primarily propranolol, reduce hemangioma size by vasoconstriction and inhibition of angiogenesis. Demand concentrates in the United States and Germany, driven by established clinical guidelines and early intervention protocols for problematic infantile hemangiomas.
- Corticosteroids:These anti-inflammatory agents can reduce hemangioma growth, often used for larger or rapidly growing lesions when beta blockers are contraindicated. Pediatric clinics in Europe utilize these for specific cases, balancing efficacy against potential systemic side effects.
- Laser Therapy:Non-invasive light-based treatments target superficial hemangiomas to improve cosmetic appearance or manage ulceration. This method finds application in specialized dermatology centers across developed economies.
- Surgery:Surgical excision is reserved for complicated or residual lesions that do not respond to other treatments, particularly in cases of functional impairment.
- Immunomodulators:These agents modulate the immune response to inhibit hemangioma growth, often considered for refractory cases.
Beta Blockers sits at the top of the volume ranking, with Laser Therapy climbing the fastest.
Therapy Area:
Patient-specific presentation and age at diagnosis dictate the primary therapy area, influencing treatment selection and intervention timing.
- Infantile:These hemangiomas appear shortly after birth and typically proliferate rapidly before undergoing involution. Early diagnosis in pediatric clinics in the United States drives the need for effective medical management.
- Congenital:Present at birth, these hemangiomas are fully formed at delivery and do not undergo a proliferative phase. Specialized hospitals in France manage these rarer subtypes, often requiring a multidisciplinary approach.
- Cavernous:Characterized by larger, deeper vascular channels, cavernous hemangiomas often require systemic therapy or procedural intervention.
- Mixed:Combining superficial and deep components, mixed hemangiomas present complex management challenges for clinicians.
- Superficial:These lesions are located on the skin surface, often treated with topical agents or laser therapy for cosmetic improvement.
Infantile hemangiomas represent the largest segment by patient volume, while congenital hemangiomas are expanding most quickly in therapeutic research.
End User:
The specialized infrastructure required for diagnosis and treatment delivery defines end-user engagement, with expertise concentrating in dedicated medical facilities.
- Pediatric Clinics:These facilities serve as the first point of contact for many infantile hemangioma cases, emphasizing early diagnosis and medical management. The United States and Canada exhibit high patient throughput in these settings.
- Dermatology Centers:Specialized in skin conditions, these centers manage superficial hemangiomas and provide advanced laser therapies. German dermatology centers demonstrate significant expertise in this area.
- Specialized Hospitals:Tertiary care hospitals with multidisciplinary teams handle complex or high-risk hemangioma cases requiring advanced medical and surgical interventions.
- Outpatient Facilities:These settings provide follow-up care and administer less invasive treatments, improving patient convenience.
Pediatric Clinics generate the highest patient traffic for hemangioma treatment, with Dermatology Centers showing the steepest expansion trajectory for procedural interventions.
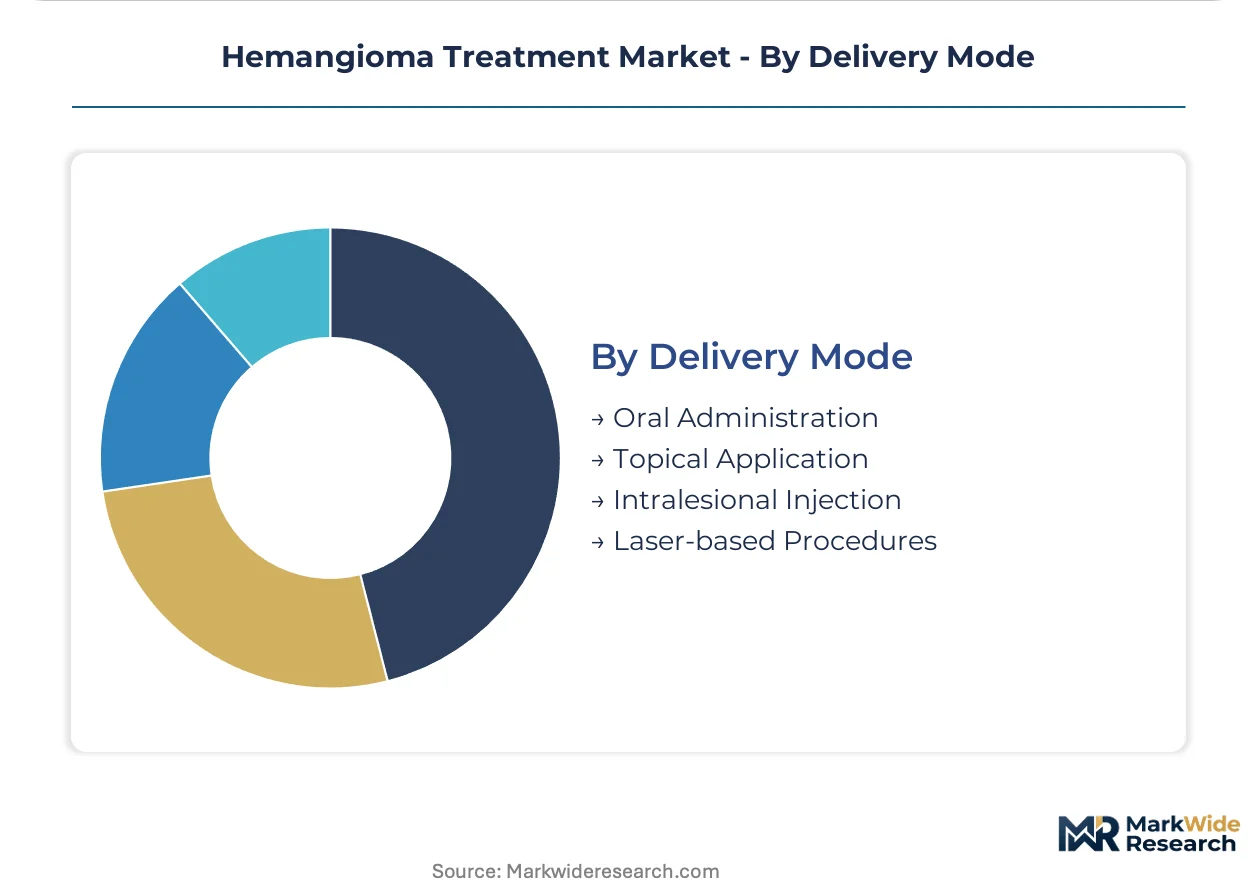
Delivery Mode:
Patient comfort and systemic exposure concerns drive innovation in delivery modes, with a clear preference for less invasive options where clinically appropriate.
- Oral Administration:Systemic medications like beta blockers are delivered orally, providing a non-invasive treatment for widespread or problematic hemangiomas. This mode dominates in Europe, supported by EMA-approved formulations.
- Topical Application:Creams or gels applied directly to superficial lesions minimize systemic side effects, particularly for smaller hemangiomas. Pierre Fabre leads in this segment with specialized dermatological formulations.
- Intralesional Injection:Direct injection of medications into the hemangioma provides localized treatment for specific lesion types.
- Laser-based Procedures:Non-invasive external laser application targets vascular lesions, offering precise treatment for superficial hemangiomas.
Oral Administration commands the largest share of treatment volume, while Topical Application is gaining share fastest due to reduced systemic side effects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States exhibits a rapid uptake of novel oral beta-blocker formulations, driven by established pediatric care infrastructure, while China focuses on expanding access and adhering to NMPA guidelines for new pediatric therapies. This regional divergence highlights varying stages of market maturity and regulatory environments. Advanced economies prioritize specialized infrastructure and early intervention protocols.
United States
The United States market demonstrates strong demand for FDA-approved oral propranolol, driven by early diagnosis in pediatric clinics and comprehensive insurance coverage. FDA clearance for pediatric-specific formulations has standardized treatment protocols. Major medical centers in Boston and Philadelphia actively conduct clinical trials for novel hemangioma therapies, driving innovation.
Germany
German pediatric dermatology centers show significant expertise in managing superficial hemangiomas and procedural interventions. The EMA's stringent approval processes ensure high-quality systemic treatments are available. Specialized clinics in Munich and Berlin contribute to advanced protocol development and patient management, integrating new laser therapies.
China
China presents a substantial growth opportunity, with the NMPA's pediatric drug development guidelines influencing market access for new therapies. Increasing awareness and improving pediatric care infrastructure drive the adoption of first-line treatments. Major urban centers like Shanghai and Beijing are establishing dedicated pediatric hospitals, enhancing diagnostic capabilities.
France
French specialized hospitals manage rarer congenital hemangioma subtypes, often requiring a multidisciplinary approach for complex cases. The ANSM regulates the approval and use of systemic treatments and specialized medical devices. Paris and Lyon host leading pediatric research institutions, contributing to refined treatment protocols and clinical research.
Hemangioma Treatment Market Key Industry Players
Top-tier vendors anchor the hemangioma treatment market with established pharmaceutical portfolios, while specialized biotechnology firms focus on niche pediatric formulations. The market structure exhibits a blend of large pharmaceutical companies and focused innovators. Strategic archetypes include broad-spectrum pharmaceutical giants, specialized dermatological solution providers, and rare disease drug developers. Companies primarily engage in portfolio diversification and strategic partnerships to expand their market reach and product offerings.
Specialists in dermatological solutions, such as Pierre Fabre, exemplify a focused approach to topical treatments for superficial hemangiomas, leveraging their expertise in skin care. Eton Pharmaceuticals occupies a position as an innovator in novel formulations for rare pediatric diseases, addressing specific unmet needs within the market with precision. Meanwhile, Pfizer anchors the broad-spectrum segment, leveraging its extensive portfolio of corticosteroids and immunomodulators to offer diverse therapeutic options across various hemangioma presentations. These companies represent distinct strategic orientations within the competitive landscape.
| Leading Market Players |
|---|
| Pfizer |
| Bausch Health |
| Pierre Fabre |
| Bristol-Myers Squibb |
| Akrimax Pharmaceuticals |
| AstraZeneca |
| Eton Pharmaceuticals |
| Bayer |
| Novartis AG |
| Others |
Cost & Logistics Intelligence
New oral beta-blocker formulations are reshaping cost economics and concentrating supply within regulated pharmaceutical channels. This shift prioritizes safety and efficacy for pediatric patients, moving away from less standardized treatment options.
Pricing Analysis
Capacity additions in the United States and Europe are reshaping price floors for approved pediatric formulations. The dominant pricing structure is value-based, reflecting clinical efficacy and reduced invasiveness compared to older methods. Price differentiation stems from FDA/EMA certification and the specialized nature of pediatric drug development. Pricing pressure stems from the continued off-label use of compounded beta-blockers. Pediatric clinics exhibit higher price sensitivity due to reimbursement variability, while specialized hospitals prioritize approved formulations for complex cases.
Supply Chain Analysis
Domestic-content mandates for pharmaceutical manufacturing are reshaping sourcing strategies in major economies. Supply concentration for active pharmaceutical ingredients (APIs) primarily resides in China, India, and the United States. Key raw material dependencies include specialized excipients for pediatric liquid formulations and sterile packaging components. A structural supply chain risk is regulatory restrictions on new pediatric drug manufacturing facilities. Distribution runs through specialized pharmaceutical distributors serving pediatric clinics and hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hemangioma treatment market presents a margin-expansion story, driven by a premium-tier shift towards FDA and EMA-approved pediatric formulations.
For Market Incumbents:Anchor existing market share by investing in pipeline diversification, particularly into novel topical solutions that minimize systemic side effects. Mitigate the threat of off-label use by demonstrating superior safety and efficacy profiles of approved products. Leverage telemedicine infrastructure to expand reach and enhance patient adherence to long-term treatment protocols. Continue R&D efforts for specific congenital hemangioma subtypes, securing orphan drug designations.
For New Entrants and Emerging Players:Enter via strategic focus on underserved niches, such as rare congenital hemangioma subtypes or more effective topical treatments. The most penetrable segment for new entrants is developing novel formulations for specific hemangioma presentations where current options are limited. A strong go-to-market angle involves emphasizing less invasive treatment options with improved patient comfort and reduced monitoring requirements. Build strong relationships with specialized pediatric dermatology centers.
For Investors and Strategic Acquirers:Valuations sit cheapest among specialized biotechnology firms developing early-stage pediatric formulations. The long-term viability of this market is strong, supported by consistent demand for early intervention and robust regulatory frameworks for pediatric drugs. Identify acquisition targets with strong intellectual property in novel delivery systems or those leveraging digital health platforms for patient management. The signal to watch is increased reimbursement for virtual care consultations, indicating broader market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel pediatric formulations addressing unmet needs. |
| Regulatory Approval Pathway | Secures market exclusivity and premium pricing for orphan drug designated therapies. |
| Manufacturing Scale-Up | Ensures consistent supply of FDA/EMA-approved beta-blockers for growing patient populations. |
| Strategic Partnership | Expands market reach and enhances patient support through integrated telemedicine solutions. |
| Pipeline Diversification | Reduces reliance on single product lines and addresses a broader spectrum of hemangioma types. |
Research Approach
Multiple input streams — primary interviews with industry stakeholders, secondary data analysis, and expert panel discussions — were reconciled to build this market analysis. Stakeholders engaged included pediatric dermatologists, pharmaceutical R&D executives, hospital procurement managers, and regulatory affairs specialists. Secondary data sources encompassed FDA filings, EMA submissions, ClinicalTrials.gov, and medical journal databases, ensuring a comprehensive view. This approach involved both bottom-up market sizing and top-down validation.
The cross-reference approach, comparing historical market data with expert panel input, formed the basis of the forecast framework. Segmentation dimensions modeled included product type, therapy area, end-user, delivery mode, and regional regulatory cluster. Compound annual growth rates (CAGRs) were derived from a blend of historical growth trends and projected market drivers over the analysis window. Pediatric population demographics and new drug approvals served as key industry-specific forecast inputs.
Inputs from pharmaceutical regulatory bodies and medical associations were available through the study window; gaps in comprehensive patient registry data introduce uncertainty bands. Forecasts reflect documented assumptions regarding regulatory stability and treatment adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Myelofibrosis Market
Specialty Medicine
Global Graves Disease Market
Specialty Medicine
Global Vasculitis Treatment Market
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Global Axial Spondyloarthritis (Axspa) Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Treatment Market
Specialty Medicine
Pulmonary Arterial Hypertension (PAH) Market
Specialty Medicine
Paediatric Sports Medicine Market
Specialty Medicine
Global Allergy Vaccine Market
Specialty Medicine
North America Precision Medicine Market
Specialty Medicine
Growth Hormone Deficiency Market
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Interstitial Lung Disease Treatment Market
Specialty Medicine
Hepatitis C Treatment Market
Specialty Medicine
Behcet's Syndrome Market