
 Neuropsychiatric Disorders and Treatment Market | 2026-2036
Neuropsychiatric Disorders and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Neuropsychiatric Disorders and Treatment Market Outlook
Small-molecule active pharmaceutical ingredients are decoupling from traditional synthetic routes as continuous manufacturing and biocatalysis reshape cost structures in neuropsychiatric drug production. Eli Lilly and Company leverages its Indianapolis-based manufacturing footprint to anchor North American supply of CNS therapies. Pfizer competes through global fermentation capacity that sustains cost leadership in generic psychotropic APIs. Otsuka Pharmaceutical differentiates via its Tokyo-centered R&D intensity in atypical antipsychotics, where it leads novel mechanism discovery.
Neuropsychiatric disorders and treatment encompasses the clinical management of conditions spanning mood, psychotic, anxiety, and cognitive-behavioral pathologies through pharmacological, psychotherapeutic, and neuromodulation interventions, with therapeutic efficacy typically measured against DSM-5 or ICD-11 diagnostic criteria and Montgomery-Åsberg Depression Rating Scale or Positive and Negative Syndrome Scale endpoints. The primary commercial purpose is to restore functional capacity and reduce disease burden across outpatient and institutional settings. Antidepressants occupy the largest product-type position due to broad major depressive disorder and generalized anxiety indications, while telehealth services represent the fastest-expanding treatment setting as asynchronous prescribing platforms gain reimbursement legitimacy. Mood stabilizers command concentrated margin pools in bipolar I maintenance therapy, where lithium carbonate and second-generation anticonvulsants face limited generic substitution.
The FDA's Risk Evaluation and Mitigation Strategy requirements for clozapine and other high-risk psychotropics shape distribution architecture and patient registry compliance costs for manufacturers. The Drug Enforcement Administration's scheduling controls on stimulant therapies constrain production quotas and directly limit supply expansion for attention-deficit indications. The Centers for Medicare & Medicaid Services' inpatient psychiatric facility quality reporting program ties reimbursement to seclusion and restraint metrics, altering capital allocation across residential treatment operators. Stakeholders must monitor how the FDA's forthcoming guidance on digital therapeutics for psychiatric conditions redefines competitive boundaries between pharmaceutical and software-based interventions.
Market Dynamics
The FDA's accelerated approval pathway for novel neuropsychiatric therapies is compressing development timelines and reshaping how sponsors allocate clinical trial capital across mood and psychotic disorder indications.
Growth Catalysts
- Telehealth reimbursement expansion:CMS reimbursement codes for asynchronous psychiatric prescribing are pulling treatment delivery into digital platforms, extending prescriber reach into underserved counties.
- Federal parity mandates:The Mental Health Parity and Addiction Equity Act enforcement actions by the Department of Labor are compelling commercial payers to expand behavioral health coverage.
- Biocatalysis adoption:Continuous manufacturing processes for small-molecule APIs are reducing batch-to-batch variability and cutting production costs for generic psychotropics.
Market Restraints
- DEA production quotas:Scheduling controls on stimulant APIs directly constrain supply expansion for attention-deficit indications, creating allocation bottlenecks during demand surges.
- Specialty workforce concentration:Child and adolescent psychiatrists cluster in urban academic medical centers, leaving rural and exurban markets chronically underserved.
- REMS compliance costs:FDA Risk Evaluation and Mitigation Strategy requirements for clozapine and other high-risk psychotropics impose patient registry and distribution architecture burdens.
Strategic Opportunities
- Digital therapeutics guidance:FDA's forthcoming psychiatric digital therapeutics framework will clarify regulatory boundaries for software-based interventions competing with pharmaceuticals.
- Neuromodulation access expansion:Transcranial magnetic stimulation reimbursement is penetrating Medicare Advantage plans, opening outpatient clinic deployment.
- India CDSCO harmonization:India's streamlined neuropsychiatric drug approval pathways are attracting contract research and manufacturing investment from Western sponsors.
Industry Challenges
- Psychiatric nursing scarcity:Inpatient psychiatric facilities face acute registered nurse shortages, forcing wage inflation and bed capacity constraints.
- Legacy EHR integration:Behavioral health-specific electronic health record systems struggle to interoperate with acute care platforms, fragmenting patient data across settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuropsychiatric Disorders and Treatment Market |
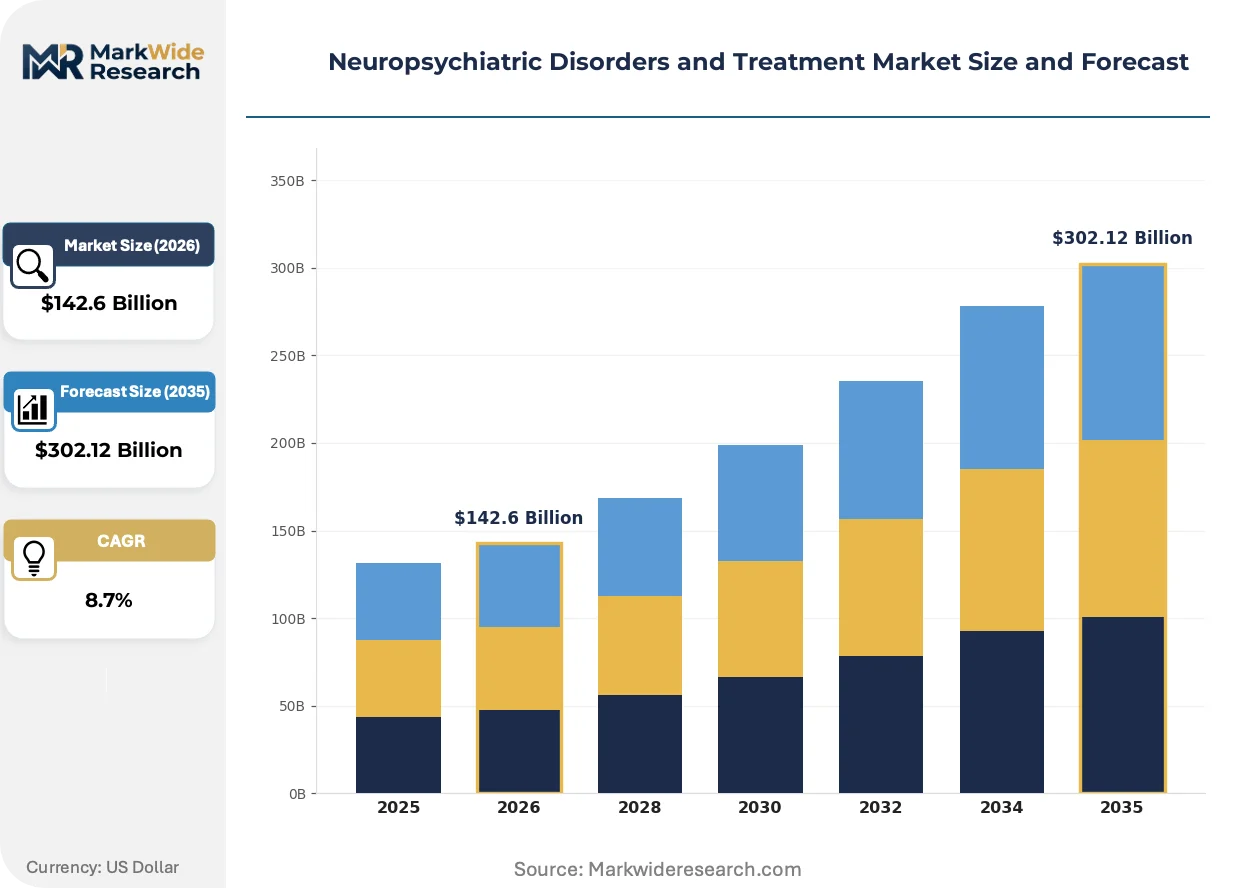
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $302.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antidepressants, Antipsychotics, Mood Stabilizers, Stimulants Treatment Setting: Outpatient Clinics, Inpatient Facilities, Telehealth Services, Residential Treatment Patient Age Group: Pediatrics, Adolescents, Adults, Geriatrics Therapeutic Area: Major Depression, Bipolar Disorder, Schizophrenia, Anxiety Disorders |
| Companies Covered | Johnson & Johnson, Pfizer, Eli Lilly and Company, AstraZeneca, GlaxoSmithKline, Bristol-Myers Squibb, Otsuka Pharmaceutical, AbbVie, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuropsychiatric Disorders and Treatment Market Strategic Shifts
Neuropsychiatric treatment delivery is bifurcating between precision pharmacology targeting receptor subtypes and technology-mediated care models that decouple prescriber location from patient access.
Digital phenotyping through smartphone sensor data and ecological momentary assessment is overtaking traditional clinic-based symptom monitoring. Academic medical centers and large integrated delivery networks are piloting passive data collection for bipolar mood state detection. This capability is compressing the feedback loop between symptom fluctuation and therapeutic adjustment, enabling just-in-time intervention protocols.
The FDA's draft guidance on model-informed drug development for CNS therapies is altering how sponsors design Phase 2 trials. Physiologically-based pharmacokinetic modeling now supports dosing rationale submissions, reducing reliance on extensive patient exposure data. Early-stage biotechnology companies with limited clinical infrastructure are leveraging this pathway most aggressively to conserve capital.
Employer-sponsored behavioral health benefits are consolidating procurement around integrated vendor platforms that combine employee assistance programs, teletherapy networks, and prescription management. Large self-insured employers in the technology and financial services sectors are driving this consolidation, demanding unified reporting on utilization and clinical outcomes. The shift is most pronounced in coastal metropolitan areas with concentrated white-collar employment.
Neuropsychiatric Disorders and Treatment Market Segmentation
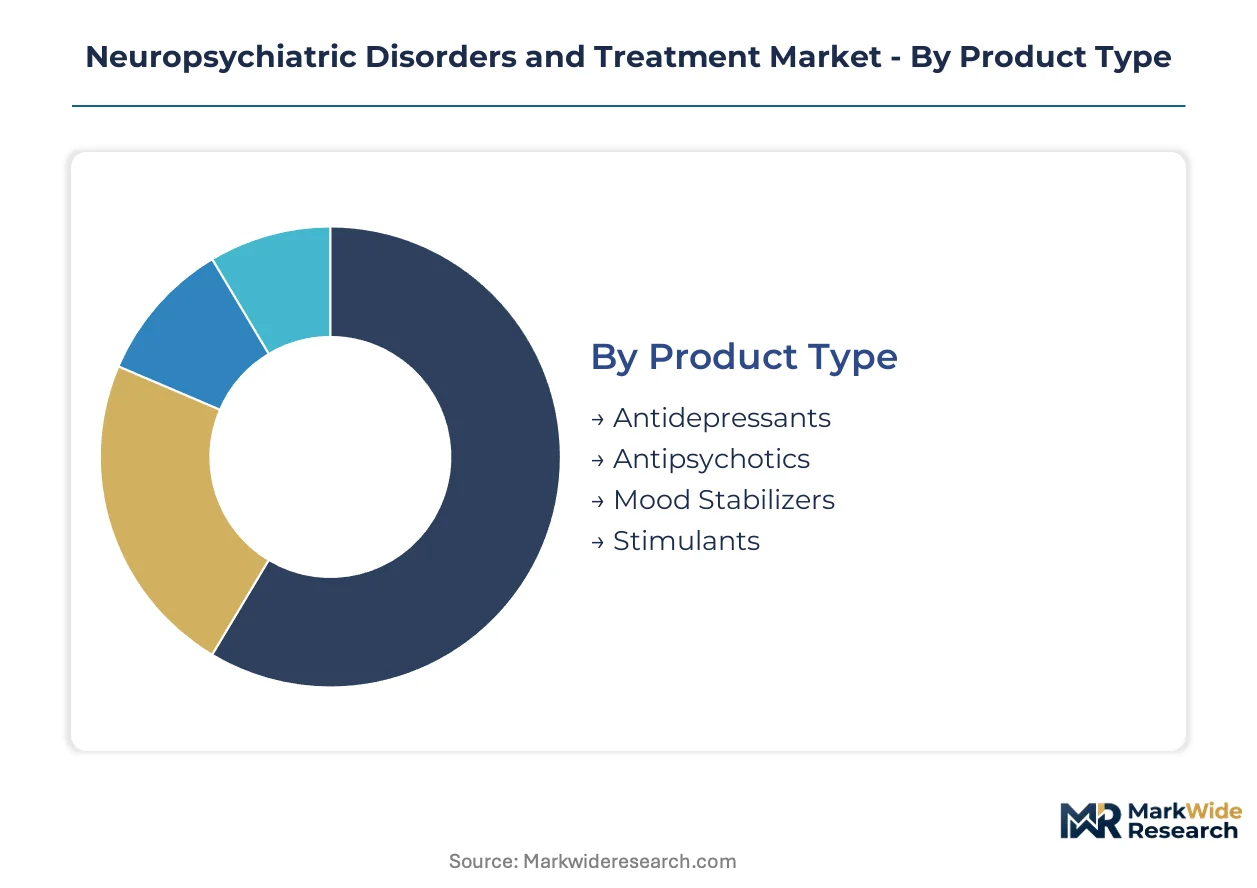
Neuropsychiatric treatment markets fragment across pharmacological mechanisms, care delivery modalities, and patient life stages. Each segmentation axis reveals distinct margin structures, regulatory burdens, and prescriber access patterns that shape commercial strategy.
Product Type:
Prescription upgrade cycles accelerate as patent expirations force manufacturers toward novel mechanisms and extended-release formulations.
- Antidepressants:Selective serotonin reuptake inhibitors and serotonin-norepinephrine reuptake inhibitors dominate first-line prescribing for major depressive disorder. Demand concentrates in the United States where commercial payer coverage has expanded under federal parity mandates, though generic penetration compresses pricing power in mature oral formulations.
- Antipsychotics:Second-generation atypical agents command premium positioning in schizophrenia and bipolar maintenance therapy through improved metabolic profiles versus first-generation haloperidol analogs. Long-acting injectable formulations sustain revenue concentration in Medicaid and Medicare populations where adherence failures drive hospitalization costs.
- Mood Stabilizers:Lithium carbonate and anticonvulsant derivatives anchor bipolar I disorder maintenance protocols with limited generic substitution resistance.
- Stimulants:DEA Schedule II controls on methylphenidate and amphetamine salts constrain production quotas and create allocation bottlenecks during pediatric demand surges.
Volume placements concentrate in Antidepressants; the faster expansion belongs to Antipsychotics.
Treatment Setting:
Cost tier differentiation separates high-acuity institutional care from lower-intensity community-based and virtual delivery models.
- Outpatient Clinics:Community mental health centers and private psychiatric practices handle the majority of medication management visits with lower overhead than institutional alternatives. Medicare reimbursement rates for evaluation and management codes sustain this channel's viability across suburban and urban markets.
- Telehealth Services:Asynchronous prescribing platforms and synchronous video psychiatry sessions are gaining reimbursement legitimacy under CMS codes established during the public health emergency. Rural counties with psychiatric workforce shortages show the steepest adoption curves as state Medicaid programs relax originating site requirements.
- Inpatient Facilities:Acute psychiatric hospitals and general hospital psychiatric units manage crisis stabilization and involuntary holds under CMS Inpatient Psychiatric Facility Quality Reporting Program constraints.
- Residential Treatment:Sub-acute facilities provide extended stabilization for substance use comorbidities with length-of-stay limits imposed by commercial utilization management.
Outpatient Clinics retain the highest visit volumes; Telehealth Services are climbing the fastest.
Patient Age Group:
Application-specific diagnostic criteria and regulatory safeguards fragment development and marketing approaches across life stages.
- Adults:The largest treated population spans ages 18-64 with major depressive disorder and generalized anxiety disorder representing the highest-incidence indications. Employer-sponsored behavioral health benefits concentrate procurement volume in this cohort through integrated EAP and teletherapy platforms.
- Geriatrics:Dementia-related behavioral disturbances and late-life depression drive prescribing with CMS Medicare Part D coverage determining formulary access. Black-box warnings on antipsychotic mortality in elderly dementia patients shape prescribing caution and liability exposure.
- Adolescents:FDA pediatric exclusivity incentives and required pediatric study commitments under the Pediatric Research Equity Act govern development timelines for this cohort.
- Pediatrics:Attention-deficit/hyperactivity disorder dominates prescribing with DEA production quotas directly limiting supply expansion for stimulant therapies.
Adults account for the dominant prescription volume; Geriatrics shows the steepest expansion trajectory.
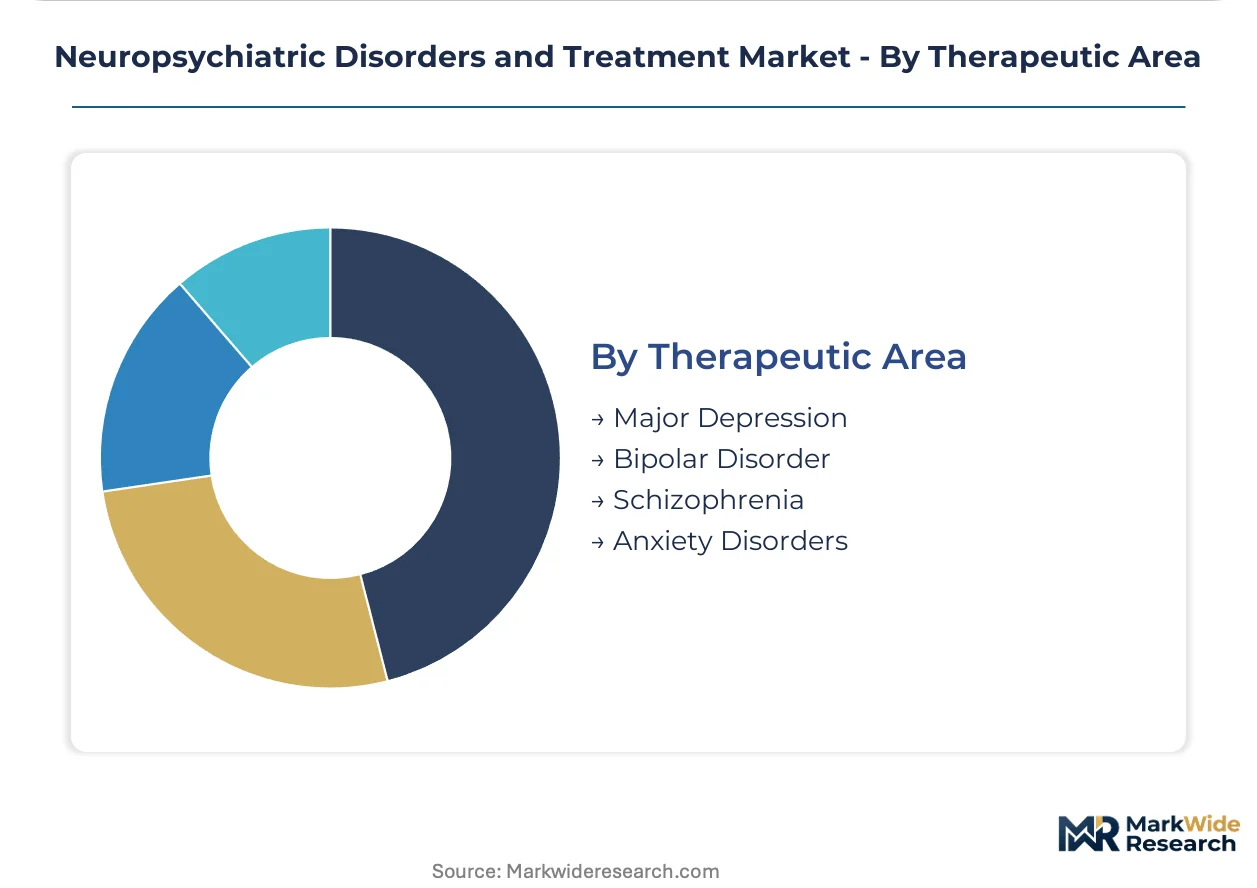
Therapeutic Area:
Margin concentration aligns with chronic disease burden, diagnostic specificity, and the availability of biomarker-guided patient selection.
- Major Depression:The highest-prevalence indication drives antidepressant volume with treatment-resistant depression subsegments commanding premium pricing for novel rapid-acting therapies. FDA breakthrough therapy designations in this space accelerate development timelines.
- Schizophrenia:Chronic disease burden and high relapse rates sustain long-acting injectable antipsychotic revenue with clozapine's REMS requirements creating distribution complexity and patient registry compliance costs.
- Bipolar Disorder:Maintenance therapy indications for mood stabilizers and atypical antipsychotics face limited generic substitution due to narrow therapeutic index concerns.
- Anxiety Disorders:Generalized anxiety and panic disorder overlap substantially with depression prescribing, though specific phobia and social anxiety segments show lower pharmacological treatment rates.
Major Depression captures the largest patient volume; Schizophrenia demonstrates the fastest-growing specialized investment intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones and pharmaceutical clusters concentrate neuropsychiatric treatment development across distinct national regulatory environments. Tax-advantaged manufacturing parks in India and China attract contract research investment. FDA breakthrough designations in the United States accelerate novel therapy timelines.
United States
Commercial payer expansion under Mental Health Parity and Addiction Equity Act enforcement drives antidepressant and antipsychotic prescribing volume. FDA accelerated approval pathways compress development timelines for novel neuropsychiatric therapies. The Indianapolis pharmaceutical corridor anchors North American CNS active pharmaceutical ingredient production.
Germany
EMA centralized marketing authorizations facilitate pan-European psychiatric drug distribution from German distribution hubs. Federal Institute for Drugs and Medical Devices enforces stringent pharmacovigilance requirements for psychotropic medications. The Rhine-Main biotech cluster concentrates Phase II-III CNS trial operations.
India
CDSCO streamlined neuropsychiatric approval pathways attract Western sponsor investment in contract manufacturing. Production-Linked Incentive schemes for pharmaceuticals reduce API import dependence. Hyderabad and Ahmedabad pharmaceutical parks expand generic psychotropic fermentation capacity.
Japan
PMDA Sakigake designation system accelerates priority review for novel psychiatric mechanisms. Aging demographic expands geriatric neuropsychiatric service demand beyond metropolitan Tokyo. Osaka-Kobe pharmaceutical corridor sustains atypical antipsychotic research intensity.
Switzerland
Swissmedic's streamlined authorization procedures support early-access programs for treatment-resistant depression therapies. Basel pharmaceutical cluster concentrates precision psychiatry biomarker development. Cantonal tax incentives sustain neuroscience venture capital deployment.
Neuropsychiatric Disorders and Treatment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with research-intensive developers commanding premium positioning in novel mechanisms while generic API fabricators compete on fermentation scale and biocatalysis efficiency. Market structure tilts toward consolidation among large-cap pharmaceutical developers with integrated CNS portfolios. Three archetypes dominate: vertically integrated innovators with captive manufacturing, specialty contract research organizations with regulatory navigation expertise, and regional generic houses with cost-optimized API supply. Competitive dynamics center on M&A activity targeting late-stage CNS pipelines and strategic partnerships bridging digital therapeutic platforms with traditional pharmaceutical distribution.
Among North American developers, Johnson & Johnson and Eli Lilly and Company exemplify the integrated innovator archetype with substantial Indianapolis-based manufacturing footprints. Pfizer occupies a position reflecting global fermentation capacity advantages in generic psychotropic production. Otsuka Pharmaceutical represents the Asia-Pacific R&D intensity model, with Tokyo-centered operations in atypical antipsychotic mechanism discovery. These three entities anchor distinct competitive vectors without exhausting the strategic diversity present in the broader participant base.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer |
| Eli Lilly and Company |
| AstraZeneca |
| GlaxoSmithKline |
| Bristol-Myers Squibb |
| Otsuka Pharmaceutical |
| AbbVie |
| Novartis |
| Others |
Value Chain & Pricing Dynamics
Brand-generic divergence in neuropsychiatric therapeutics manifests in starkly different margin structures and sourcing architectures, with originator small molecules commanding formulation premiums through REMS-gated distribution while commodity APIs flow through fermentation hubs in India and China.
Pricing Analysis
Volume placements concentrate in generic antidepressants where Medicaid and Medicare Part D formularies drive substitution toward lowest-cost alternatives; margin pools accrue to long-acting injectable antipsychotics with adherence-linked hospitalization risk contracts. Price differentiation rests on FDA breakthrough therapy designation status and REMS program complexity, with clozapine's mandatory patient registry sustaining distribution premiums. Cost compression in oral generic psychotropics intensifies as Indian CDSCO-approved manufacturers expand fermentation scale. Commercial payers under Mental Health Parity and Addiction Equity Act enforcement show lowest price sensitivity for novel rapid-acting depression therapies, while state Medicaid programs remain most cost-conscious.
Supply Chain Analysis
Current Good Manufacturing Practice certification and DEA Schedule II quota compliance gate entry for stimulant API production, concentrating qualified supply among Indianapolis, Hyderabad, and Shanghai pharmaceutical corridors. Active pharmaceutical ingredient production draws from fermentation-derived precursors and specialized biocatalysis intermediates, with lithium carbonate extraction tethered to Chilean and Australian mineral processing. Single-source vulnerability runs through DEA-controlled methylphenidate and amphetamine salt quotas, where annual production limits create allocation rigidity during pediatric demand surges. Distribution runs through specialty pharmacy networks for REMS-gated therapies and wholesale distributors for standard oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neuropsychiatric treatment markets favor consolidation plays as FDA digital therapeutics guidance redraws competitive boundaries between pharmaceutical and software-based interventions, forcing sub-scale developers toward strategic exits.
For Market Incumbents: Acquire late-stage CNS pipeline assets to replenish patent cliffs in atypical antipsychotics, while securing DEA quota allocations through backward integration into controlled-substance API production. Digital therapeutic platforms represent the primary substitute threat; counter by embedding prescription management tools within existing distribution infrastructure.
For New Entrants and Emerging Players: Enter via asynchronous telehealth prescribing platforms in rural counties with psychiatric workforce shortages, where state Medicaid originating-site waivers lower reimbursement barriers. Pediatric attention-deficit indications offer the most penetrable segment given chronic supply constraints under DEA production quotas; partner with established specialty pharmacies to navigate REMS compliance.
For Investors and Strategic Acquirers: Re-rating potential sits with biotechnology developers holding FDA breakthrough therapy designations in treatment-resistant depression given accelerated approval pathway access. Long-term viability hinges on biomarker-guided patient selection capabilities. Watch FDA draft guidance finalization on psychiatric digital therapeutics as the inflection signal for platform valuation resets.
| Strategic Initiative | Industry Significance |
|---|---|
| REMS Infrastructure Investment | Patient registry and distribution architecture compliance secures access for clozapine and high-risk psychotropics under FDA mandates. |
| Biocatalysis Manufacturing Scale-Up | Continuous processing adoption in Indianapolis and Hyderabad fermentation facilities reduces batch variability for generic API production. |
| Telehealth Platform Integration | Asynchronous prescribing capabilities capture CMS reimbursement codes in rural counties with psychiatric workforce gaps. |
| Digital Therapeutics Partnership | Software-based intervention alliances position sponsors for FDA forthcoming guidance on psychiatric digital therapeutics. |
| Long-Acting Injectable Formulation Development | Adherence-linked hospitalization risk contracts with Medicaid and Medicare sustain premium positioning in schizophrenia maintenance. |
Study Parameters
Document review covered FDA advisory committee transcripts, ClinicalTrials.gov CNS trial registries, and CMS Medicare Part D formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from EMA centralized marketing authorization records, DEA controlled substance production quota publications, and SEC 10-K pharmaceutical segment disclosures. Bottom-up prescription volume modeling and top-down therapeutic class expenditure analysis were triangulated against manufacturer-reported revenue allocations.
Historical prescription audit data from IQVIA and Symphony Health were cross-referenced against panel input from formulary directors and specialty pharmacy operators. Segmentation modeling spanned product type, treatment setting, patient age group, and therapeutic area across the analysis window, with regional regulatory clusters treated as distinct demand determinants. CAGRs were derived from patent expiration timelines, generic entry assumptions, and telehealth reimbursement expansion curves. Forecast inputs incorporated FDA approval probability assessments and DEA quota trajectory projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FDA digital therapeutics guidance or DEA stimulant quota policy shifts. Model outputs reflect assumptions regarding Mental Health Parity and Addiction Equity Act enforcement intensity and Medicaid telehealth originating-site flexibility. A model refresh is warranted upon material change in FDA psychiatric digital therapeutics final guidance or DEA Schedule II production quota methodology.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Japan Neurology Devices Market
Neurology
Argentina Neurology Devices Market
Neurology
Transverse Myelitis Treatment Market
Neurology
North America Neurology Devices Market
Neurology
Intracranial Aneurysm Market
Neurology
Acute Repetitive Seizures Market
Neurology
Neurocognitive Assessment and Rehabilitation Market
Neurology
Neurology Services Market
Neurology
Ischemic Cerebral Stroke Market
Neurology
Global MRI Guided Neurosurgical Ablation Market
Neurology
United Kingdom Neurology Devices Market
Neurology
Saudi Arabia Neurology Devices Market
Neurology
Optic Neuritis Treatment Market
Neurology
Cervical Dystonia Treatment Market
Neurology
Global Sciatica Treatment Market
Neurology
Mild Cognitive Impairment Market