
 Marfan Syndrome Management Market | 2026-2036
Marfan Syndrome Management Market Size, Share, and Industry Trends Forecast 2026-2036
Marfan Syndrome Management Market Foresight
The cardiothoracic surgeon talent pool is collapsing across community hospital systems, forcing complex aortic procedures into quaternary referral centers where Novartis Pharmaceuticals Corporation leverages its cardiovascular franchise to secure formulary placement. Pfizer competes through primary care channel density, while Medtronic anchors the interventional segment with thoracic stent graft portfolios. Teva Pharmaceuticals differentiates through generic beta-blocker accessibility that sustains volume in cost-constrained markets.
Marfan syndrome management encompasses pharmacologic intervention, surgical prophylaxis, genetic surveillance, and multidisciplinary coordination for this autosomal dominant connective tissue disorder caused by FBN1 mutations, with aortic root diameter thresholds of 50 mm typically triggering surgical consultation. The primary commercial purpose centers on preventing aortic dissection and mitigating lens ectopia, dural ectasia, and skeletal complications through lifetime monitoring protocols. Medications dominate current revenue as beta-blocker and ARB therapy remains first-line, while genetic testing kits represent the fastest-expanding segment as cascade screening of first-degree relatives accelerates detection. Telehealth services now capture growing margin pools by reducing travel burdens for dispersed patient populations requiring quarterly echocardiographic surveillance.
FDA orphan drug incentives and EMA's PRIME designation for rare diseases shape how developers allocate R&D resources toward Marfan-specific indications rather than broader cardiovascular labels. HIPAA compliance requirements and GDPR protections for genetic data constrain how telehealth platforms and testing laboratories architect cross-border data flows. Stakeholders must monitor how payer coverage policies for prophylactic aortic surgery evolve relative to emerging endovascular alternatives, as this reimbursement calculus will determine whether hospital-based or ambulatory care settings capture future procedure volumes.
Market Dynamics
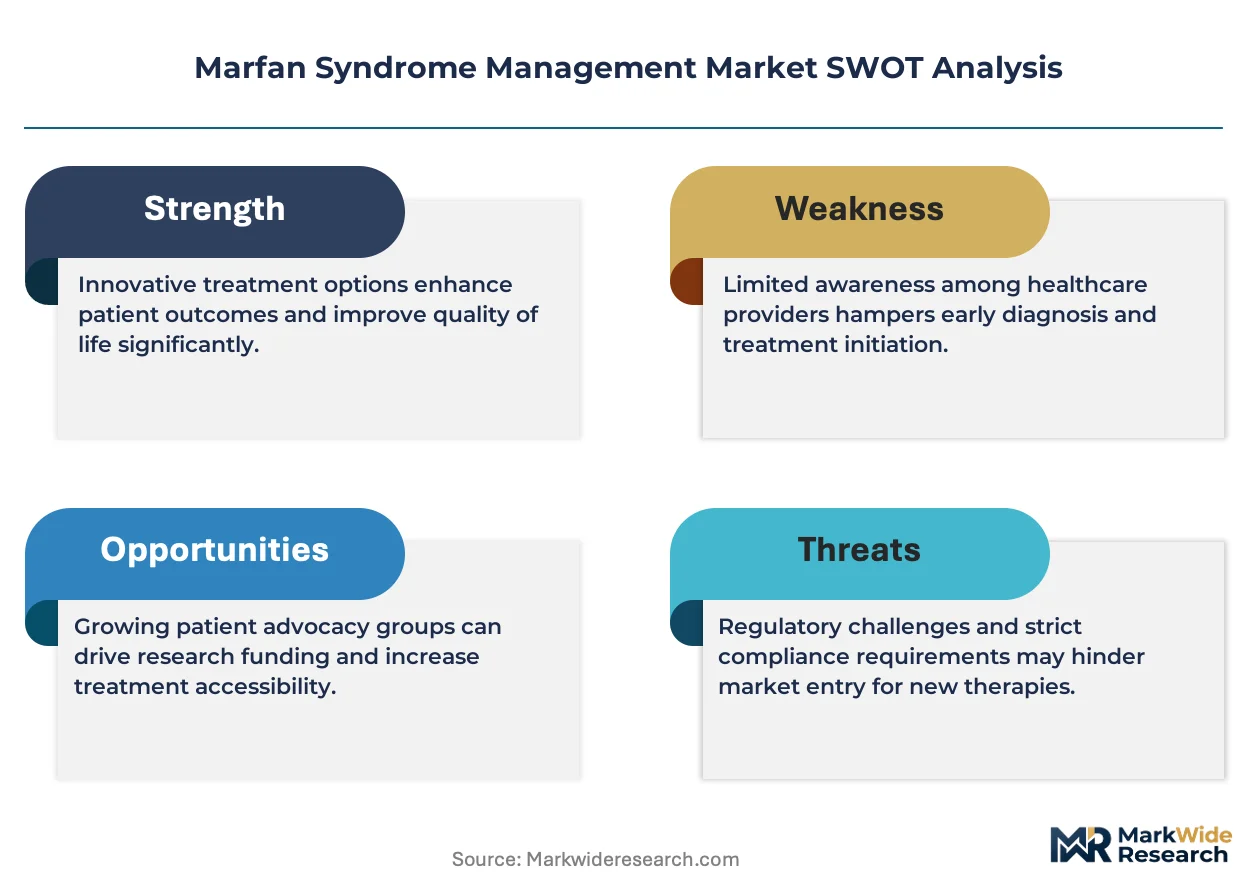
FDA orphan drug designation incentives are redirecting pharmaceutical R&D investment toward Marfan-specific cardiovascular therapies, compressing development timelines while fragmenting commercialization strategies across rare disease specialists and large cardiovascular franchises.
Growth Catalysts
- Cascade Screening Protocols:First-degree relative genetic testing mandates in US specialized clinics are expanding addressable patient pools beyond index cases. EMA's PRIME designation for rare diseases accelerates European market access for novel therapeutics.
- Telehealth Infrastructure:Remote echocardiographic monitoring platforms reduce travel burdens for dispersed Marfan populations requiring quarterly surveillance. HIPAA-compliant video consultation systems enable continuous care coordination between quaternary centers and community cardiologists.
- Aortic Surgery Volume Concentration:Community hospital cardiothoracic surgeon retirements are consolidating complex procedures into academic medical centers with dedicated Marfan clinics, creating captive referral networks for integrated device and pharmaceutical suppliers.
Market Restraints
- Genetic Testing Cost Barriers:FBN1 mutation analysis and multi-gene connective tissue panels carry substantial out-of-pocket expenses in high-deductible US health plans, limiting penetration among uninsured and underinsured populations.
- Specialized Surgical Talent Scarcity:The pipeline of fellowship-trained aortic surgeons has contracted across North American training programs, creating procedural bottlenecks at centers without established Marfan programs.
- Reimbursement Uncertainty for Endovascular Alternatives:Payer coverage policies for thoracic endovascular aortic repair in prophylactic Marfan indications remain inconsistent, constraining adoption of less invasive interventions relative to open surgical standards.
Strategic Opportunities
- Pediatric Early Intervention:ARB therapy initiation in childhood represents an underpenetrated segment with lifetime medication adherence potential, requiring pediatric cardiology partnership structures distinct from adult aortic clinics.
- Digital Biomarker Integration:Wearable heart rate variability monitors combined with AI-assisted echocardiographic interpretation could enable between-visit risk stratification, creating subscription revenue streams beyond episodic imaging.
- Cross-Border Genetic Data Networks:GDPR-compliant European rare disease registries offer frameworks for multinational natural history studies that accelerate FDA breakthrough therapy designation eligibility for novel mechanisms.
Industry Challenges
- Multidisciplinary Care Coordination Complexity:Effective Marfan management requires synchronized scheduling across ophthalmology, orthopedics, genetics, and cardiothoracic surgery departments, creating administrative friction in fee-for-service reimbursement environments.
- Legacy EHR Interoperability:Aortic dimension tracking across disparate hospital systems complicates lifetime longitudinal monitoring, as patients transition between pediatric and adult care settings and across geographically dispersed academic centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marfan Syndrome Management Market |
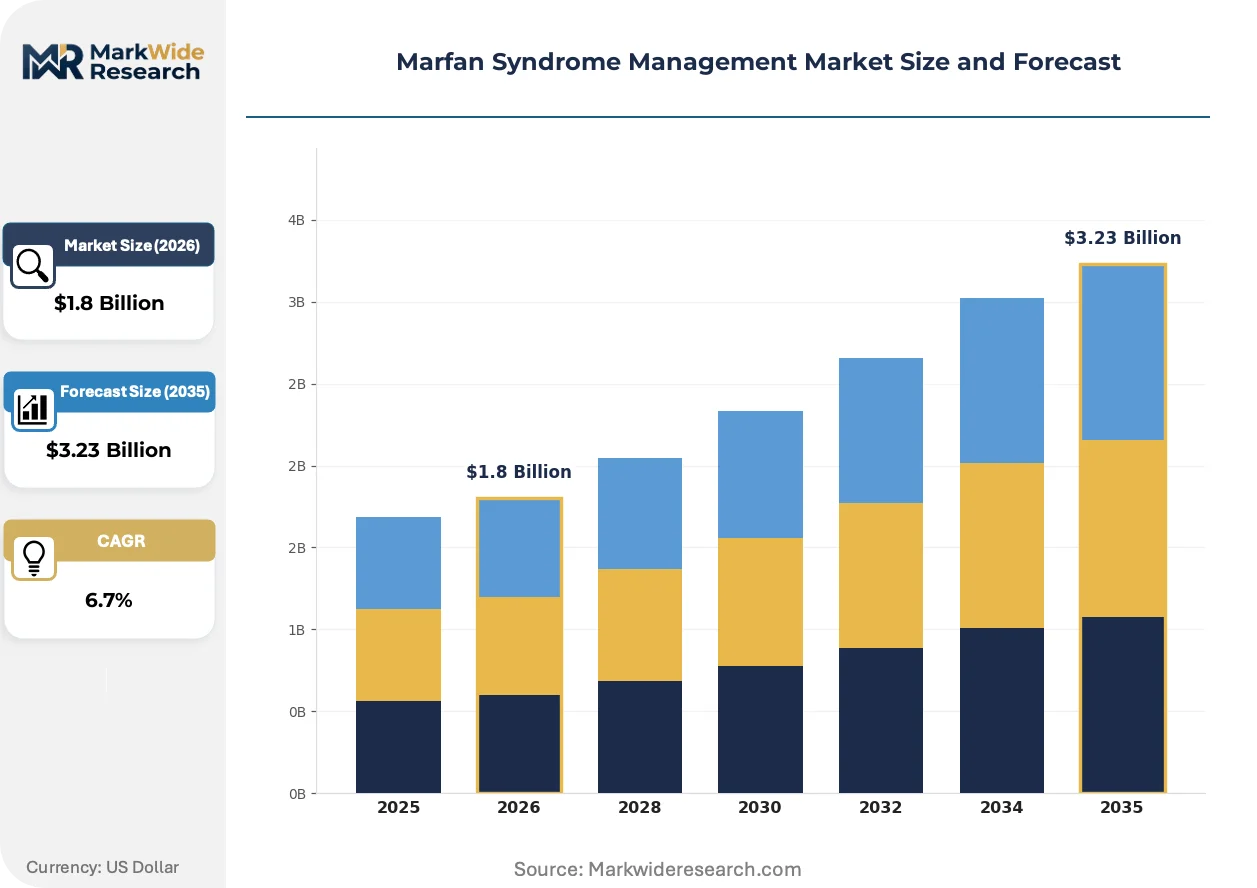
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Supportive Devices, Genetic Testing Kits, Educational Materials Delivery Mode: In-Person Consultation, Telehealth Services, Mobile Applications, Community Programs End User: Patients, Healthcare Providers, Family Members, Researchers Care Setting: Outpatient Clinics, Hospitals, Home Care, Rehabilitation Centers |
| Companies Covered | Novartis Pharmaceuticals Corporation, Teva Pharmaceuticals, AstraZeneca, Pfizer, Boehringer Ingelheim, Eli Lilly, Bayer, Medtronic, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marfan Syndrome Management Market Shifts & Advancements
Computational phenotyping and machine learning applications are transforming how clinicians predict aortic dissection risk, shifting management paradigms from diameter-based thresholds toward personalized biomechanical modeling.
Next-generation sequencing panels is displacing single-gene FBN1 testing in academic referral centers, enabling simultaneous evaluation of Loeys-Dietz and vascular Ehlers-Danlos overlap syndromes. Tertiary care genetic counselors are adopting these expanded assays within 48-hour turnaround protocols. This convergence is compressing time-to-diagnosis while complicating variant interpretation workflows and insurance pre-authorization processes.
EMA's Medical Device Regulation (MDR) recertification requirements are elevating clinical evidence standards for thoracic stent graft systems, particularly for inherited aortopathy indications without randomized trial data. Manufacturers must now submit post-market surveillance registries demonstrating real-world durability. The interventional cardiology segment is responding by prioritizing physician-sponsored investigational device exemption pathways over commercial launches in European markets.
Patient advocacy organizations are consolidating purchasing influence through centralized travel grant programs and preferred provider network designations. The Marfan Foundation's clinic certification program now directs members toward institutions meeting specific surgical volume and multidisciplinary staffing thresholds. This concentration is visible most acutely in the US Northeast corridor, where certified centers capture disproportionate shares of out-of-state migration for prophylactic root replacement procedures.
Marfan Syndrome Management Market Segmentation
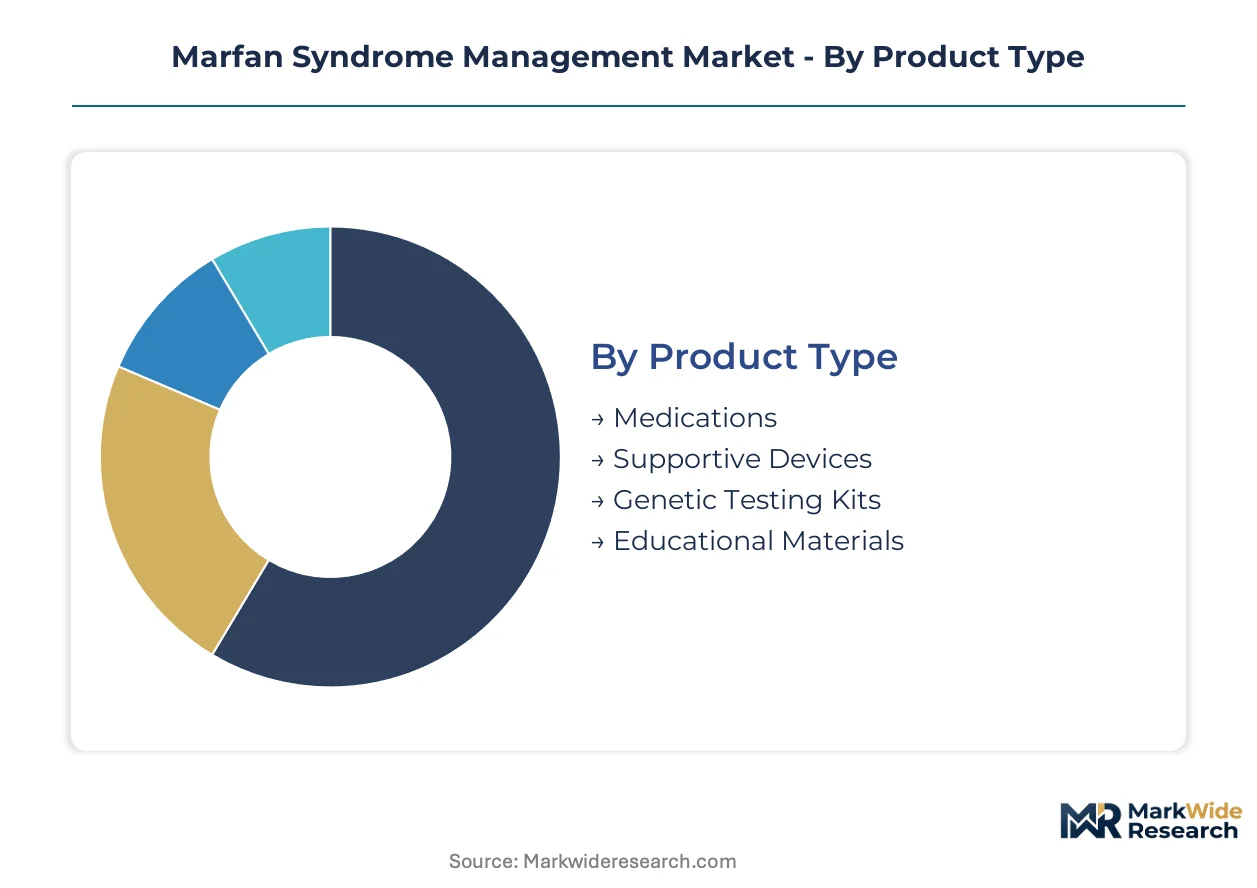
Marfan syndrome management requires precise segmentation to capture how care pathways split between acute intervention and longitudinal monitoring. Each category reflects distinct reimbursement logic and stakeholder control points that determine commercial access strategies.
Product Type:
Substitution pressure concentrates heaviest in pharmacologic segments where beta-blocker generics commoditize standard of care while ARB innovation commands premium positioning.
- Medications:Beta-blockers and angiotensin receptor blockers constitute first-line prophylaxis against aortic root dilation, with ARB therapy showing particular efficacy in pediatric populations. Demand clusters at quaternary cardiovascular centers in the United States where Johns Hopkins and Stanford anchor specialized Marfan clinics with dedicated pharmacy formularies.
- Genetic Testing Kits:Next-generation sequencing panels displace single-gene FBN1 assays in academic referral centers, enabling simultaneous evaluation of Loeys-Dietz and vascular Ehlers-Danlos overlap syndromes. Cascade screening mandates for first-degree relatives at US specialized clinics are accelerating kit consumption beyond index case identification.
- Supportive Devices:Thoracic stent grafts and custom orthopedic bracing address emergent aortic complications and skeletal deformities.
- Educational Materials:Digital patient resources and clinical decision support tools facilitate multidisciplinary care coordination.
Medications retain volume leadership; genetic testing kits hold the steepest expansion curve.
Delivery Mode:
Cost tier stratification separates capital-intensive in-person surgical consultation from margin-rich remote monitoring platforms that reduce travel burdens for dispersed populations.
- Telehealth Services:HIPAA-compliant video consultation systems enable continuous care coordination between quaternary centers and community cardiologists, with particular penetration in rural US regions distant from certified Marfan clinics. Quarterly echocardiographic surveillance requirements create recurring subscription revenue opportunities.
- In-Person Consultation:Face-to-face evaluation remains mandatory for surgical candidacy assessment and pre-operative planning at academic medical centers. Concentration of fellowship-trained aortic surgeons at Johns Hopkins, Stanford, and Mayo Clinic creates geographic access bottlenecks that telehealth cannot fully resolve.
- Mobile Applications:Patient-facing tools for symptom tracking and medication adherence support self-management between clinical encounters.
- Community Programs:The Marfan Foundation's outreach initiatives provide peer support and travel grant coordination for out-of-state surgical migration.
In-person consultation retains volume leadership; telehealth services are gaining share fastest.
End User:
Customer type determines purchasing authority, with healthcare providers controlling formulary decisions while family members drive genetic testing demand through cascade screening activation.
- Healthcare Providers:Cardiothoracic surgeons, genetic counselors, and multidisciplinary clinic coordinators control device procurement and therapeutic protocol selection. FDA orphan drug designation incentives are redirecting pharmaceutical R&D investment toward Marfan-specific cardiovascular therapies that target this prescriber base.
- Patients:Individual Marfan syndrome patients and their families bear substantial out-of-pocket costs for genetic testing in high-deductible US health plans. The Marfan Foundation's clinic certification program directs member flow toward institutions meeting specific surgical volume thresholds.
- Family Members:First-degree relatives represent the expanding addressable pool for cascade genetic screening protocols.
- Researchers:Academic investigators access natural history registries and biobank specimens for mechanistic studies.
Healthcare providers retain volume leadership; family members hold the steepest expansion curve.
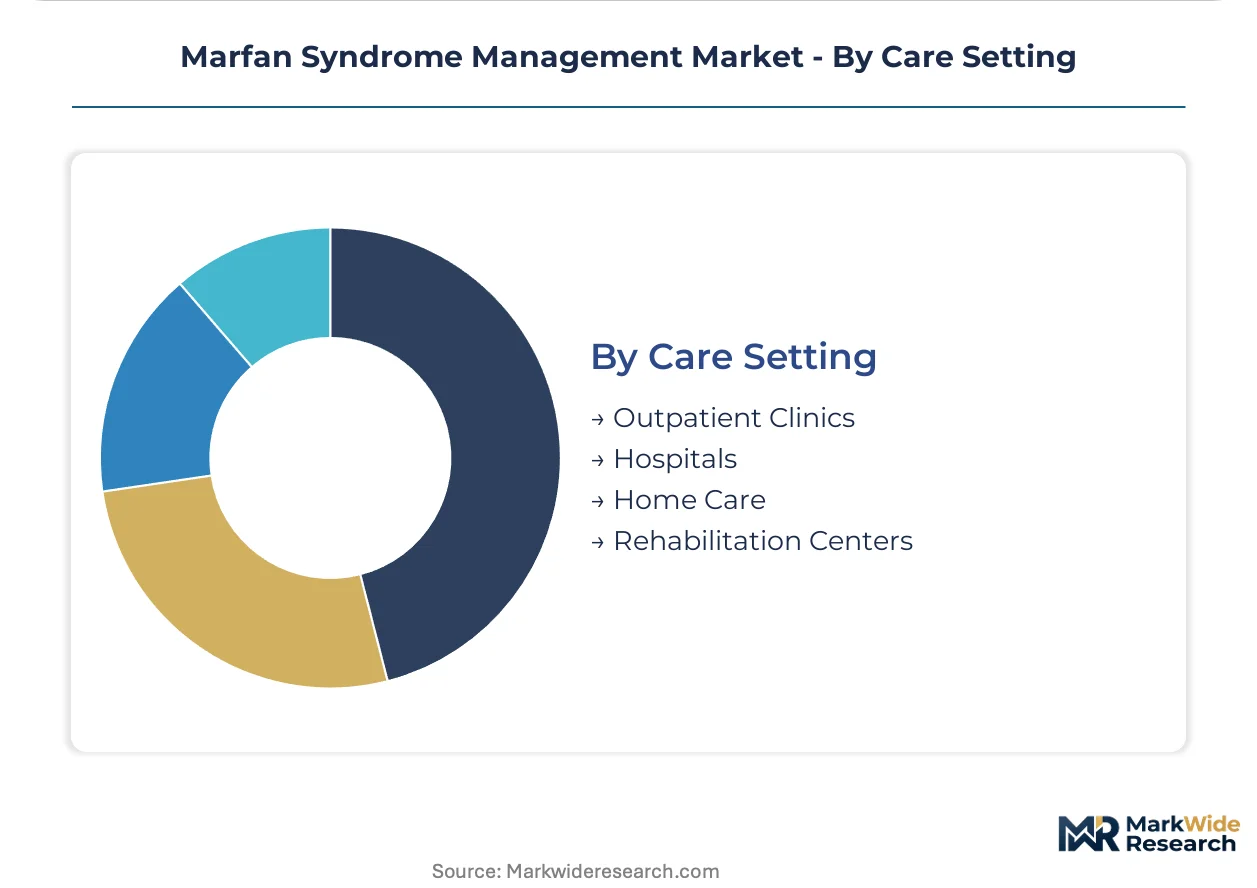
Care Setting:
Supply concentration in fellowship-trained surgical talent is forcing procedure volume toward hospital-based quaternary centers, marginalizing community and home-based alternatives for complex aortic intervention.
- Hospitals:Academic medical centers with dedicated Marfan programs capture disproportionate shares of prophylactic aortic root replacement procedures, particularly in the US Northeast corridor where certified centers attract out-of-state migration. EMA's MDR recertification requirements are elevating clinical evidence standards for thoracic stent graft systems used in these settings.
- Outpatient Clinics:Specialized Marfan clinics coordinate longitudinal surveillance across ophthalmology, orthopedics, genetics, and cardiology departments. Administrative friction in fee-for-service reimbursement environments complicates multidisciplinary scheduling at these facilities.
- Home Care:Remote monitoring and medication administration support patient stability between institutional encounters.
- Rehabilitation Centers:Post-surgical recovery and orthopedic complication management occur in specialized physical therapy settings.
Hospitals retain volume leadership; outpatient clinics are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price realization for Marfan syndrome therapeutics diverges sharply between the United States and European markets, where FDA orphan drug incentives sustain premium positioning against EMA cost-effectiveness pressures. Germany and France negotiate aggressive rebates through health technology assessment frameworks. Japan maintains distinct reimbursement logic through Chuikyo deliberations.
United States
Johns Hopkins and Stanford anchor specialized Marfan clinics that capture out-of-state surgical migration through The Marfan Foundation's certification program. FDA accelerated approval pathways compress development timelines for cardiovascular therapeutics targeting FBN1-related aortopathies. The Northeast corridor concentrates fellowship-trained aortic surgeon talent, forcing procedural volume concentration at quaternary academic medical centers.
Germany
EMA PRIME designation accelerates European market access for novel rare disease therapeutics, though IQWiG health technology assessments impose pricing constraints. The German Center for Cardiovascular Research coordinates natural history registries across Berlin, Munich, and Heidelberg clusters. Bavarian university hospitals lead post-market surveillance requirements under MDR recertification protocols for thoracic stent graft systems.
Japan
PMDA Sakigake designation offers priority review for pediatric ARB formulations addressing early intervention protocols. Chuikyo reimbursement negotiations determine formulary placement for genetic testing panels, with NGS coverage expanding gradually from academic centers. The Kanto region around Tokyo concentrates cardiothoracic surgical volume at National Cerebral and Cardiovascular Center and affiliated university hospitals.
United Kingdom
NICE technology appraisals evaluate cost-effectiveness of cascade screening protocols against quality-adjusted life year thresholds. Genomic England's rare disease program integrates FBN1 testing into mainstream NHS pathways, expanding detection beyond traditional academic referrals. London's Guy's and St Thomas' NHS Foundation Trust anchors a specialist aortopathy service drawing referrals from across England and Wales.
Canada
Health Canada orphan drug regulations parallel FDA incentives though with smaller addressable patient pools across dispersed geographies. CADTH reimbursement reviews create provincial variation in genetic testing coverage, with Ontario and Quebec leading adoption. Toronto's Peter Munk Cardiac Centre and Montreal Heart Institute anchor bilingual care networks serving francophone and anglophone Marfan populations.
Marfan Syndrome Management Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Marfan syndrome management value chain. The market structures around three distinct tiers: multinational cardiovascular franchises with orphan drug capabilities, generic manufacturers sustaining beta-blocker accessibility, and interventional device specialists with thoracic stent graft portfolios. Consolidation pressures concentrate surgical talent at academic centers, creating captive procurement relationships. Dominant competitive moves include strategic partnerships between pharmaceutical developers and specialized clinic networks, plus portfolio diversification into pediatric formulations.
Among established cardiovascular franchises, Novartis Pharmaceuticals Corporation and Pfizer occupy positions reflecting divergent channel strategies—specialized quaternary center penetration versus primary care density. Teva Pharmaceuticals exemplifies the cost-leadership archetype through generic beta-blocker accessibility. Medtronic anchors the interventional segment with device portfolios addressing emergent aortic complications. These three names represent the competitive spectrum: premium orphan drug development, volume-driven generic supply, and procedural technology integration.
| Leading Market Players |
|---|
| Novartis Pharmaceuticals Corporation |
| Teva Pharmaceuticals |
| AstraZeneca |
| Pfizer |
| Boehringer Ingelheim |
| Eli Lilly |
| Bayer |
| Medtronic |
| AbbVie |
| Others |
Supply & Pricing Matrix
Next-generation sequencing panel adoption replacing single-gene FBN1 assays is redrawing procurement geography toward US and German academic medical centers while compressing per-test margins through vendor consolidation and automated variant interpretation workflows.
Pricing Analysis
US-Europe price spreads exceed two-to-one for identical ARB formulations, with FDA orphan drug incentives sustaining premium positioning against IQWiG cost-effectiveness pressures in Germany. Three-tier pricing structure across premium orphan-designated therapies, standard branded ARBs, and generic beta-blockers reflects formulary tier placement and prescriber specialization level. Cost compression in the generic beta-blocker segment is intensifying as Teva Pharmaceuticals and Indian API suppliers expand volume contracts with US GPOs. Uninsured and underinsured patient populations exhibit highest price sensitivity, while quaternary academic centers with captive pharmacy formularies demonstrate lowest elasticity.
Supply Chain Analysis
Fellowship-trained aortic surgeon availability at Johns Hopkins, Stanford, and Mayo Clinic functions as the critical chokepoint constraining prophylactic root replacement procedure throughput across North American markets. Active pharmaceutical ingredient production for beta-blockers draws from India and China, while ARB finished dosage manufacturing concentrates in Ireland and Puerto Rico under FDA oversight. Single-source vulnerability characterizes the thoracic stent graft segment, where Medtronic's proprietary delivery systems face limited substitutability. Distribution runs through specialty pharmaceutical distributors to hospital-based outpatient pharmacies, with direct-to-clinic genetic testing kit logistics managed by centralized laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marfan syndrome management sits at early-cycle expansion, with cascade screening protocols activating first-degree relative testing demand that multiplies addressable patient pools beyond index case identification.
For Market Incumbents: Secure exclusive formulary placement at The Marfan Foundation-certified clinics through bundled ARB and genetic testing service contracts. Deepen backward integration into FBN1 variant interpretation software to defend margin position against emerging laboratory competitors. Expand pediatric cardiology partnership structures to capture lifetime medication adherence value.
For New Entrants and Emerging Players: Remote patient monitoring platform deployment represents the most penetrable service layer where incumbents under-serve rural populations distant from quaternary centers. Target HIPAA-compliant wearable heart rate variability integration with existing telehealth infrastructure. Pursue white-label AI-assisted echocardiographic interpretation partnerships with community cardiology practices lacking specialized Marfan expertise.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rare disease genetic testing platforms possessing CLIA-certified laboratories and established payer contracts. Five-to-ten year viability hinges on successful navigation from single-gene to multi-gene panel reimbursement expansion. Watch FDA breakthrough therapy designation announcements for novel TGF-beta pathway inhibitors as the primary inflection signal for pipeline asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric ARB Formulation Development | PMDA Sakigake designation in Japan accelerates priority review for early intervention protocols. |
| Hospital System Partnership | Johns Hopkins and Stanford certification requirements create captive procurement relationships for integrated suppliers. |
| Reimbursement Strategy | CADTH provincial reviews in Canada determine genetic testing coverage variation between Ontario and Quebec networks. |
| Software Companion Development | AI-assisted echocardiographic interpretation enables between-visit risk stratification subscription revenue streams. |
| CE Marking Pathway | EMA MDR recertification elevates clinical evidence standards for thoracic stent graft durability claims. |
Research Methodology
Desk research of FDA orphan drug designation filings, ClinicalTrials.gov cardiovascular entries, and EMA PRIME designation records preceded structured interviews with cardiothoracic surgeons, genetic counselors, hospital formulary directors, and rare disease payer access specialists. Bottom-up patient volume estimates from certified Marfan clinic networks were cross-validated against top-down pharmaceutical shipment data from IQVIA and hospital procurement databases. Primary interview insights on surgical referral patterns and telehealth adoption were triangulated against secondary validation from The Marfan Foundation annual reports and academic medical center press releases.
Variance decomposition across product type, delivery mode, end user, and care setting segmentation dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from slope-intercept modeling of historical pharmaceutical expenditure trajectories and procedure volume concentration trends at quaternary centers. Forecast inputs incorporated EMA MDR implementation timelines, FDA accelerated approval pathway utilization rates, and cascade screening protocol penetration assumptions across US specialized clinic networks.
Forecasts assume regulatory continuity in FDA orphan drug incentive structures and EMA PRIME designation criteria; material policy shifts would require re-modeling of pharmaceutical R&D allocation decisions. Specific risk factors include reimbursement retraction for prophylactic aortic surgery, thoracic stent graft safety signals triggering regulatory review, and genetic testing cost barriers limiting cascade screening penetration among underinsured populations. Practitioners should keep alternative scenarios live as payer coverage policies for endovascular alternatives and pediatric ARB formulations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Spinal Muscular Atrophy Treatment Market
Specialty Medicine
Brain Metastasis Therapeutics Market
Specialty Medicine
Quadriplegia Treatment Market
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Medical Foods for Orphan Diseases Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Nerve Entrapment Syndrome Therapeutics Market
Specialty Medicine
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market
Specialty Medicine
Global Tourette Syndrome Treatment Market
Specialty Medicine
Severe Hypertriglyceridemia (SHTG) Treatment Market
Specialty Medicine
Global Appendicitis Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market
Specialty Medicine
Global Gastrointestinal Therapeutics Market
Specialty Medicine
Dyschromia Therapeutics Market
Specialty Medicine
Europe Precision Medicine Market