
 Cutaneous T-Cell Lymphoma (CTLC) Market | 2026-2036
Cutaneous T-Cell Lymphoma (CTLC) Market Size, Share, and Industry Trends Forecast 2026-2036
Cutaneous T-Cell Lymphoma (CTLC) Market Outlook
Biopharmaceutical manufacturing capacity in North America is repositioning toward precision oncology infrastructure. Bristol-Myers Squibb anchors its immunotherapy portfolio through sustained investment in checkpoint inhibitor platforms. Kyowa Kirin leverages its dermatology heritage to compete in systemic retinoid supply chains. Merck & Co. differentiates through integrated clinical trial networks spanning oncology centers and specialized hospitals.
Cutaneous T-cell lymphoma comprises a heterogeneous group of non-Hodgkin lymphomas characterized by malignant proliferation of skin-homing T-cells, with mycosis fungoides and Sézary syndrome representing the predominant subtypes requiring histopathological confirmation via immunophenotyping for CD3, CD4, and CD7 markers. The condition demands staged therapeutic intervention ranging from skin-directed therapies for early lesions to systemic regimens for erythrodermic or nodal involvement. Immunotherapy represents the fastest-expanding product category as checkpoint inhibitors and monoclonal antibodies redirect T-cell antitumor responses, while phototherapy maintains stable utilization in dermatology clinics for plaque-stage mycosis fungoides. Early-stage CTLC protocols concentrate margin pools in topical corticosteroid and phototherapy combinations, whereas advanced-stage disease shifts value toward intravenous biologics administered at specialized hospitals.
FDA orphan drug incentives and EMA's priority medicines scheme shape development economics by compressing regulatory timelines and extending market exclusivity for novel CTLC therapies. The EU's Clinical Trials Regulation standardizes multi-country protocol requirements across member states, while Japan's PMDA sakigake designation accelerates access for innovative dermatologic oncology products. Stakeholders must monitor evolving biomarker-driven patient stratification methods that will determine reimbursement positioning for emerging pipeline assets.
Market Dynamics
Checkpoint inhibitor development pipelines are compressing clinical trial timelines while fragmenting patient recruitment pools across competing oncology centers. This competitive pressure for trial participants is restructuring how biopharmaceutical firms secure site contracts and investigator networks.
Growth Catalysts
- FDA Orphan Drug Designation:The pathway grants seven-year market exclusivity and tax credits for qualified CTLC therapies, accelerating sponsor investment in rare disease indications.
- Immunophenotyping Automation:Flow cytometry platforms with CD4/CD7 marker detection are standardizing diagnostic confirmation at dermatology clinics, expanding addressable patient identification.
- Japan's PMDA Sakigake:The priority review scheme compresses approval timelines for innovative dermatologic oncology products, attracting multinational trial placement.
Market Restraints
- Monoclonal Antibody Manufacturing Concentration:Contract manufacturing capacity for biologics concentrates in Massachusetts and North Carolina facilities, creating single-source vulnerability for intravenous CTLC therapies.
- Histopathologist Training Bottlenecks:Diagnostic confirmation requires specialized dermatopathology expertise that remains concentrated in academic medical centers, limiting community hospital service expansion.
- Phototherapy Equipment Depreciation:Narrowband UV-B cabin systems require substantial capital replacement cycles that strain outpatient clinic budgets.
Strategic Opportunities
- Germany's Early Benefit Assessment Pathway:The AMNOG framework enables rapid reimbursement negotiation for therapies demonstrating added benefit, creating a favorable pricing environment for novel biologics.
- Telemedicine-Enabled Triage:Remote dermatology consultations are identifying suspected mycosis fungoides cases earlier, expanding the pool of patients eligible for skin-directed interventions.
- Companion Diagnostic Convergence:Biomarker-driven patient stratification tools paired with targeted therapies are opening precision oncology positioning for pipeline assets.
Industry Challenges
- Cell Therapy Manufacturing Skill Scarcity:Autologous T-cell processing requires specialized cleanroom technicians that outpace current training program output.
- Multi-Site Trial Coordination Complexity:EMA's Clinical Trials Regulation mandates standardized protocol documentation across member states, increasing administrative burden for European expansion.
- Legacy EHR Integration Friction:Dermatology-specific staging data fields often conflict with hospital-wide oncology reporting systems, complicating real-world evidence collection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutaneous T-Cell Lymphoma (CTLC) Market |
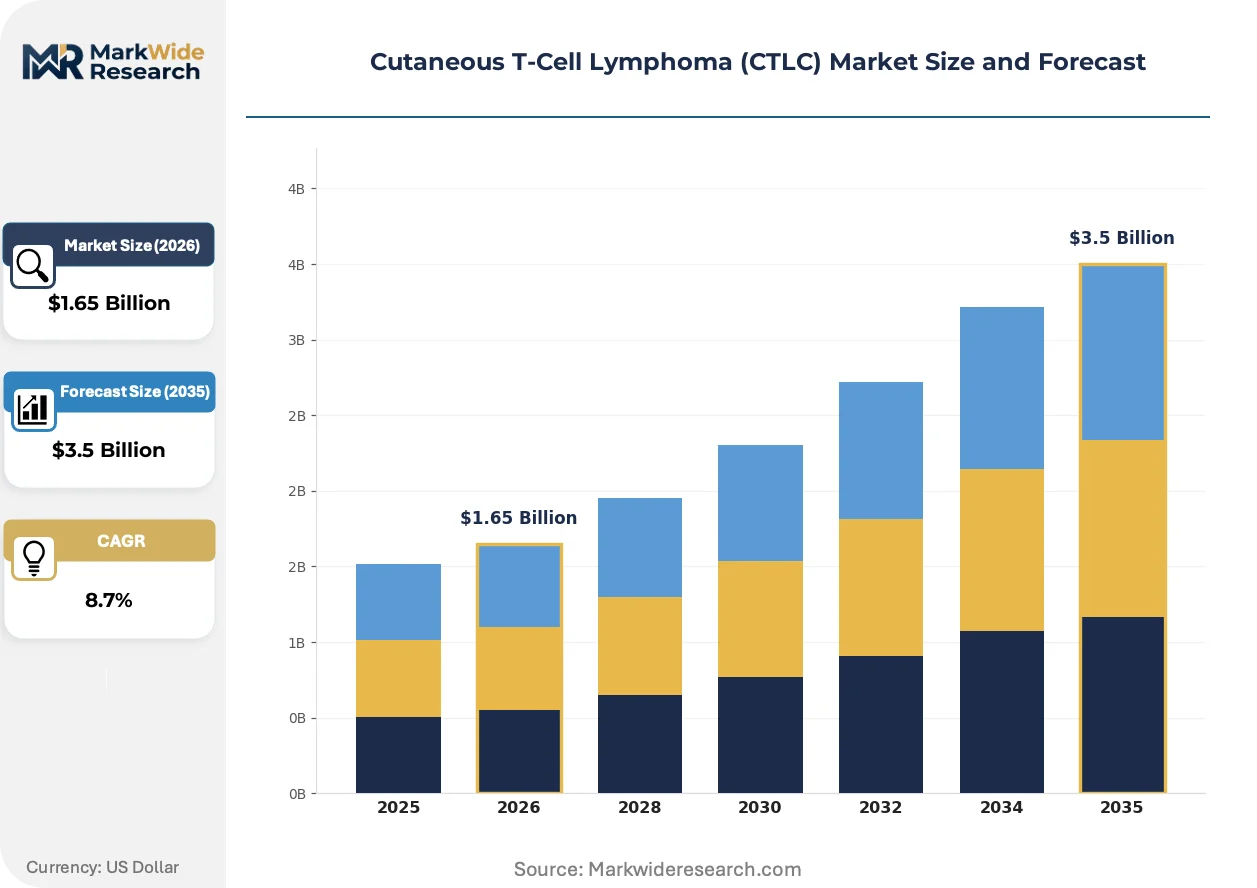
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.5 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Corticosteroids, Phototherapy, Systemic Retinoids, Immunotherapy Therapy Area: Early-Stage CTLC, Advanced-Stage CTLC, Sézary Syndrome, Mycosis Fungoides End User: Oncology Centers, Dermatology Clinics, Research Institutes, Specialized Hospitals Delivery Mode: Oral, Intravenous, Topical, Injectable |
| Companies Covered | Soligenix, Merck & Co., Kyowa Kirin, Bausch Health Companies, Helsinn Healthcare, Pfizer, Bristol-Myers Squibb, Novartis, Innate Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutaneous T-Cell Lymphoma (CTLC) Market Strategic Shifts
Biomarker-guided therapy selection is fragmenting the historical stage-based treatment paradigm into molecular subtype protocols. This shift demands new diagnostic infrastructure and reconfigures how pharmaceutical firms segment their addressable populations.
Artificial intelligence-enabled histopathology screening is decentralizing diagnostic confirmation from centralized academic laboratories to community hospital pathology departments. Regional dermatology networks in the United States are deploying convolutional neural networks trained on CD3/CD4 immunostain patterns. This capability compression is enabling faster biopsy triage and reducing specialist referral backlogs.
EMA's priority medicines scheme is accelerating access pathways for therapies addressing unmet needs in rare oncologic indications. The framework grants enhanced scientific advice and accelerated assessment timelines for qualifying submissions. CTLC sponsors targeting erythrodermic mycosis fungoides are prioritizing PRIME eligibility to compress European market entry sequences.
Patient advocacy organizations are consolidating purchasing influence through centralized trial matching platforms that bypass traditional investigator site relationships. The Leukemia & Lymphoma Society's registry tools in the United States are directing patient flow toward specific academic medical centers. This channel concentration is forcing biopharmaceutical firms to restructure their site engagement strategies around advocacy partnerships rather than independent physician outreach.
Cutaneous T-Cell Lymphoma (CTLC) Market Segmentation
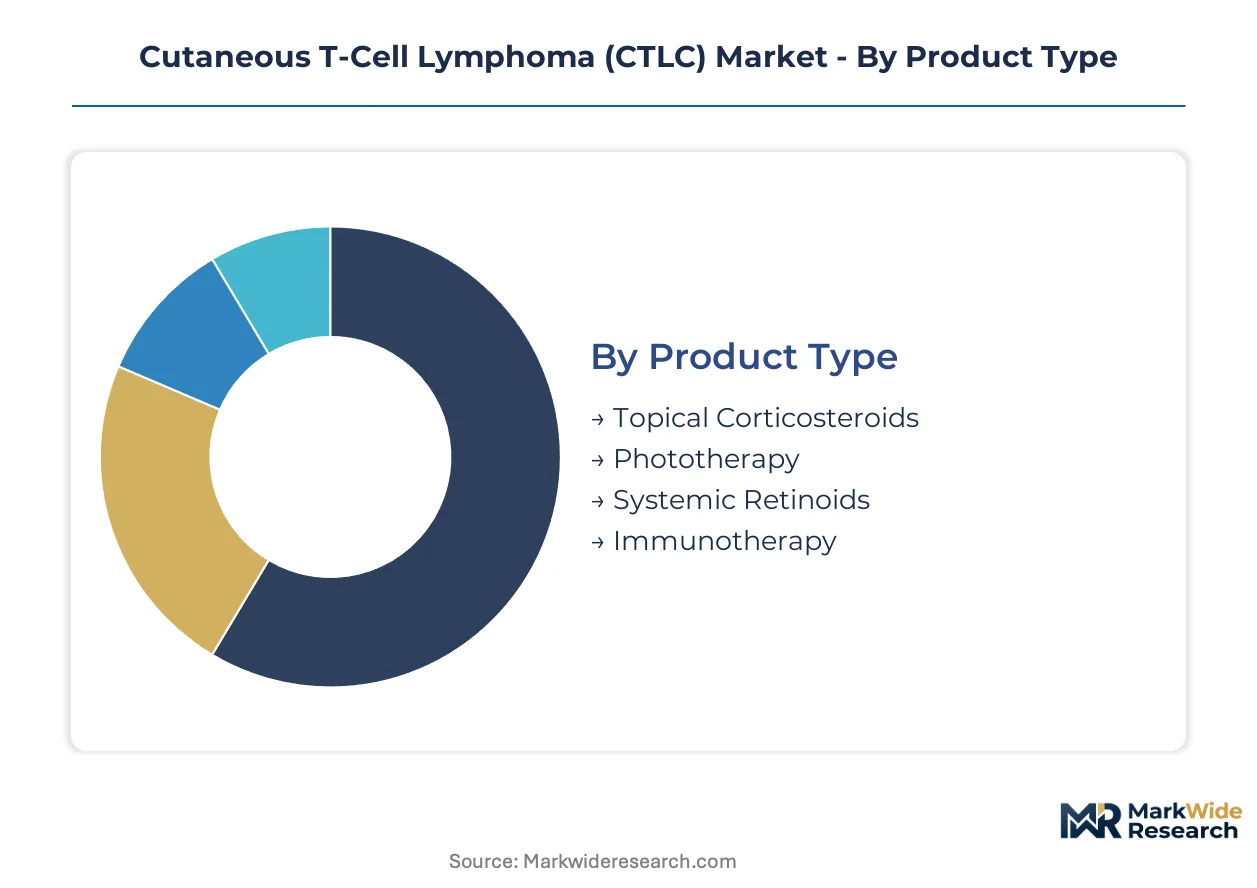
CTLC treatment selection hinges on disease stage, histopathology, and patient comorbidity profiles. Segmentation reveals how value migrates from skin-directed modalities toward systemic biologics as disease progresses.
Product Type:
Prescribing economics and reimbursement tiers determine product selection across dermatology and oncology settings.
- Immunotherapy:Checkpoint inhibitors and monoclonal antibodies redirect T-cell antitumor responses through PD-1/PD-L1 blockade. Demand concentrates at specialized hospitals in the United States and Germany as academic medical centers expand infusion capacity for advanced-stage protocols.
- Phototherapy:Narrowband UV-B and PUVA modalities deliver targeted ultraviolet irradiation for plaque-stage mycosis fungoides. Utilization clusters in dermatology clinics across Japan and Germany where outpatient reimbursement supports equipment capital cycles.
- Systemic Retinoids:Bexarotene and acitretin modulate T-cell differentiation for refractory disease.
- Topical Corticosteroids:High-potency formulations manage patch-stage lesions with minimal systemic exposure.
Volume sits with topical corticosteroids; growth tilts toward immunotherapy.
Therapy Area:
Disease progression and histopathological subtype dictate treatment intensity and site-of-care requirements.
- Advanced-Stage CTLC:Erythrodermic disease and nodal involvement require systemic biologics administered through oncology centers with infusion pharmacy capabilities. Patient recruitment concentrates in the United States and Germany where clinical trial density supports access to novel agents.
- Mycosis Fungoides:The predominant CTLC subtype spans patch, plaque, and tumor stages with staged therapeutic escalation. Diagnostic confirmation via CD4/CD7 immunophenotyping drives referral patterns to academic dermatopathology laboratories in Japan and the United States.
- Early-Stage CTLC:Limited skin involvement permits skin-directed therapy with favorable quality-of-life profiles.
- Sézary Syndrome:Leukemic variant demands aggressive systemic intervention with poor prognostic indicators.
Patient volume clusters in mycosis fungoides; Sézary syndrome commands the steepest expansion trajectory for novel targeted agents.
End User:
Site capabilities and reimbursement structures shape therapy distribution across care settings.
- Oncology Centers:Comprehensive cancer centers manage advanced-stage protocols with integrated clinical trial infrastructure. Capacity expansion in Massachusetts and North Carolina biopharma clusters supports infusion therapy growth.
- Specialized Hospitals:Academic medical centers combine dermatology and hematology expertise for complex case management. Concentration in German university hospitals and Japanese national cancer centers anchors regional referral networks.
- Dermatology Clinics:Outpatient settings dominate early-stage diagnosis and skin-directed therapy initiation.
- Research Institutes:Translational centers drive biomarker discovery and companion diagnostic development.
Transaction volume flows through dermatology clinics; value capture shifts toward oncology centers.
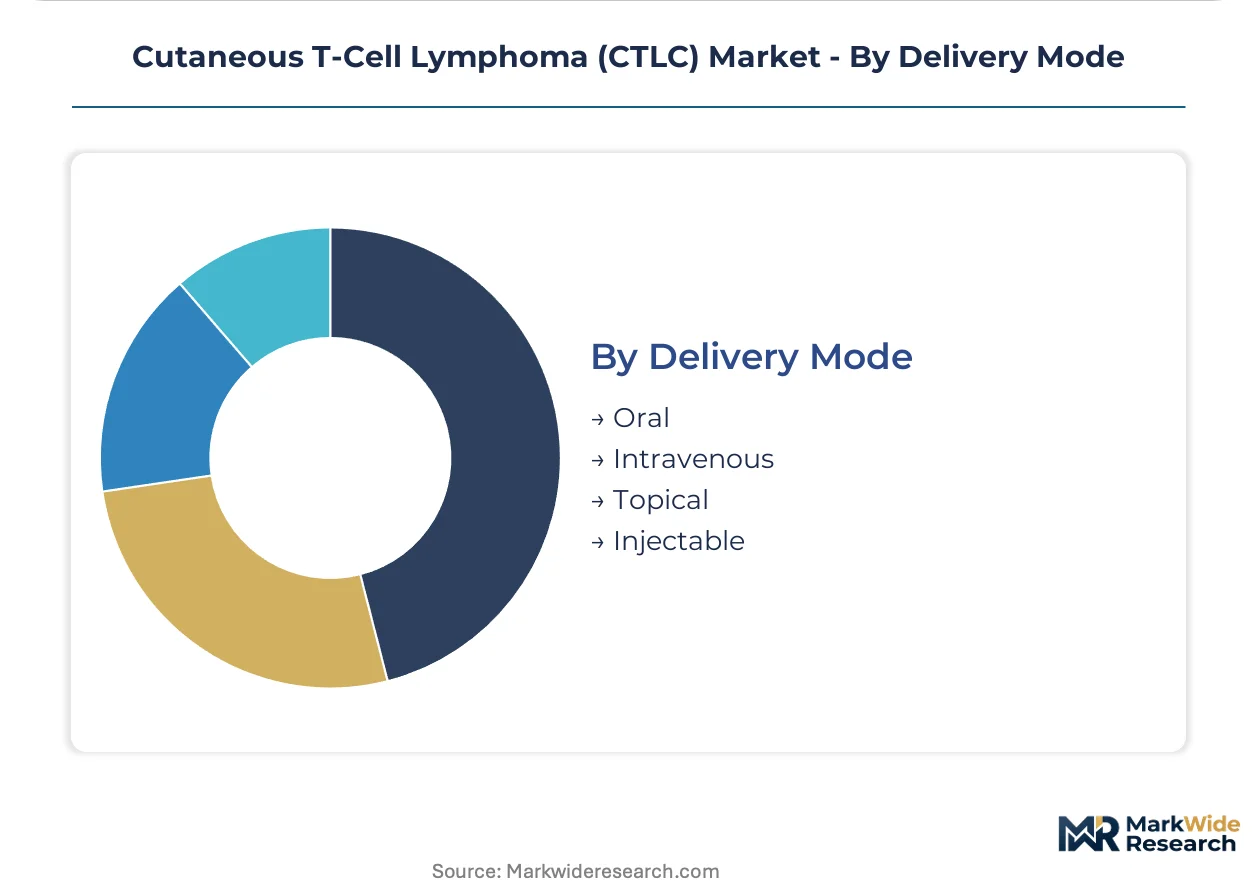
Delivery Mode:
Route selection balances bioavailability requirements with patient adherence and site-of-care constraints.
- Intravenous:Infusion delivery enables high-dose biologic administration with therapeutic drug monitoring. Utilization concentrates at oncology centers in the United States and Germany where nursing infrastructure supports extended infusion protocols.
- Oral:Systemic retinoids and small molecule inhibitors offer outpatient convenience with pharmacy-dispensed adherence support. Prescription volume clusters in Japan where PMDA sakigake designation accelerates oral targeted therapy access.
- Topical:Localized application minimizes systemic exposure for limited skin disease.
- Injectable:Subcutaneous formulations bridge outpatient convenience with biologic potency.
Prescription volume favors oral delivery; intravenous routes gain share fastest in advanced-stage segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts and North Carolina anchor biopharmaceutical manufacturing capacity for CTLC therapies, with specialized oncology infrastructure concentrating patient access and clinical trial recruitment in specific metropolitan clusters.
United States
FDA orphan drug designation accelerates CTLC therapy development through tax credits and market exclusivity incentives. The Leukemia & Lymphoma Society's patient registry tools direct case flow toward academic medical centers in Boston and Durham. Massachusetts General Hospital and Duke University Medical Center anchor regional referral networks for advanced-stage protocols.
Germany
AMNOG's early benefit assessment pathway enables rapid reimbursement negotiation for novel biologics demonstrating added clinical value. EMA's priority medicines scheme compresses European approval timelines for qualifying CTLC submissions. University hospitals in Munich and Heidelberg combine dermatopathology expertise with integrated hematology-oncology departments.
Japan
PMDA's sakigake designation accelerates access for innovative dermatologic oncology products through priority review and enhanced consultation. National Cancer Center Hospital in Tokyo anchors specialized CTLC case management with companion diagnostic integration. Osaka University Hospital expands phototherapy capacity for plaque-stage mycosis fungoides.
United Kingdom
NHS England's specialized commissioning framework routes complex CTLC cases toward designated supra-regional centers with histopathology automation. MHRA's early access to medicines scheme enables pre-approval use for therapies addressing unmet erythrodermic disease needs. Royal Marsden Hospital and St. John's Institute of Dermatology anchor London's referral density.
Switzerland
Swissmedic's expedited access pathway for orphan indications aligns with Basel's concentration of immunology R&D infrastructure. University Hospital Zurich maintains specialized cutaneous lymphoma units with flow cytometry diagnostic platforms. Roche's proximity shapes regional biomarker development partnerships for patient stratification tools.
Cutaneous T-Cell Lymphoma (CTLC) Market Competitive Environment
Global majors compete with regional champions across immunotherapy platform development and dermatology heritage positioning. The market structure consolidates around large-cap biopharmaceutical firms with checkpoint inhibitor infrastructure, mid-tier specialists with retinoid manufacturing legacy, and emerging immuno-oncology players. Three archetypes dominate: diversified immunotherapy platforms, dermatology-focused systemic therapy suppliers, and precision oncology biotechs. Competitive moves center on biomarker-driven trial design and site network exclusivity arrangements.
Among diversified immunotherapy platforms, Bristol-Myers Squibb anchors checkpoint inhibitor development with sustained investment in PD-1/PD-L1 infrastructure. Merck & Co. occupies a position in integrated clinical trial networks spanning oncology centers and specialized hospitals. Kyowa Kirin sits within the dermatology heritage tier, leveraging systemic retinoid supply chain capabilities.
| Leading Market Players |
|---|
| Soligenix |
| Merck & Co. |
| Kyowa Kirin |
| Bausch Health Companies |
| Helsinn Healthcare |
| Pfizer |
| Bristol-Myers Squibb |
| Novartis |
| Innate Pharma |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up dermatology clinic networks in the United States anchor outpatient phototherapy capacity, concentrating purchasing leverage over equipment suppliers while compressing service bundling margins for narrowband UV-B cabin vendors. This ownership consolidation feeds pricing discipline back into manufacturing, where depreciation cycles and extended warranty demands reshape supplier contract structures.
Pricing Analysis
Service bundling separates premium infusion protocols from unbundled diagnostic testing in oncology centers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA orphan-designated biologics commanding premium positioning against compounded topical alternatives. Cost compression in the phototherapy equipment tier intensifies because clinic networks consolidate purchasing volume. Community dermatology clinics exhibit highest price sensitivity, whereas academic medical centers with trial infrastructure demonstrate lowest sensitivity due to reimbursement pass-through mechanisms.
Supply Chain Analysis
Regional distribution centers in Massachusetts and North Carolina anchor biopharmaceutical warehousing for intravenous CTLC therapies, with hub-and-spoke patterns radiating toward oncology centers in Boston, Durham, and Philadelphia. Manufacturing concentration in these states draws from specialized cleanroom infrastructure and skilled technician labor pools. Single-source vulnerability concentrates in contract manufacturing organizations for monoclonal antibody production. Distribution runs through specialty pharmacy channels with cold-chain requirements for biologic stability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA orphan drug designation functions as a cost-of-compliance moat, extending market exclusivity and tax credit incentives that deter undercapitalized entrants from CTLC therapy development.
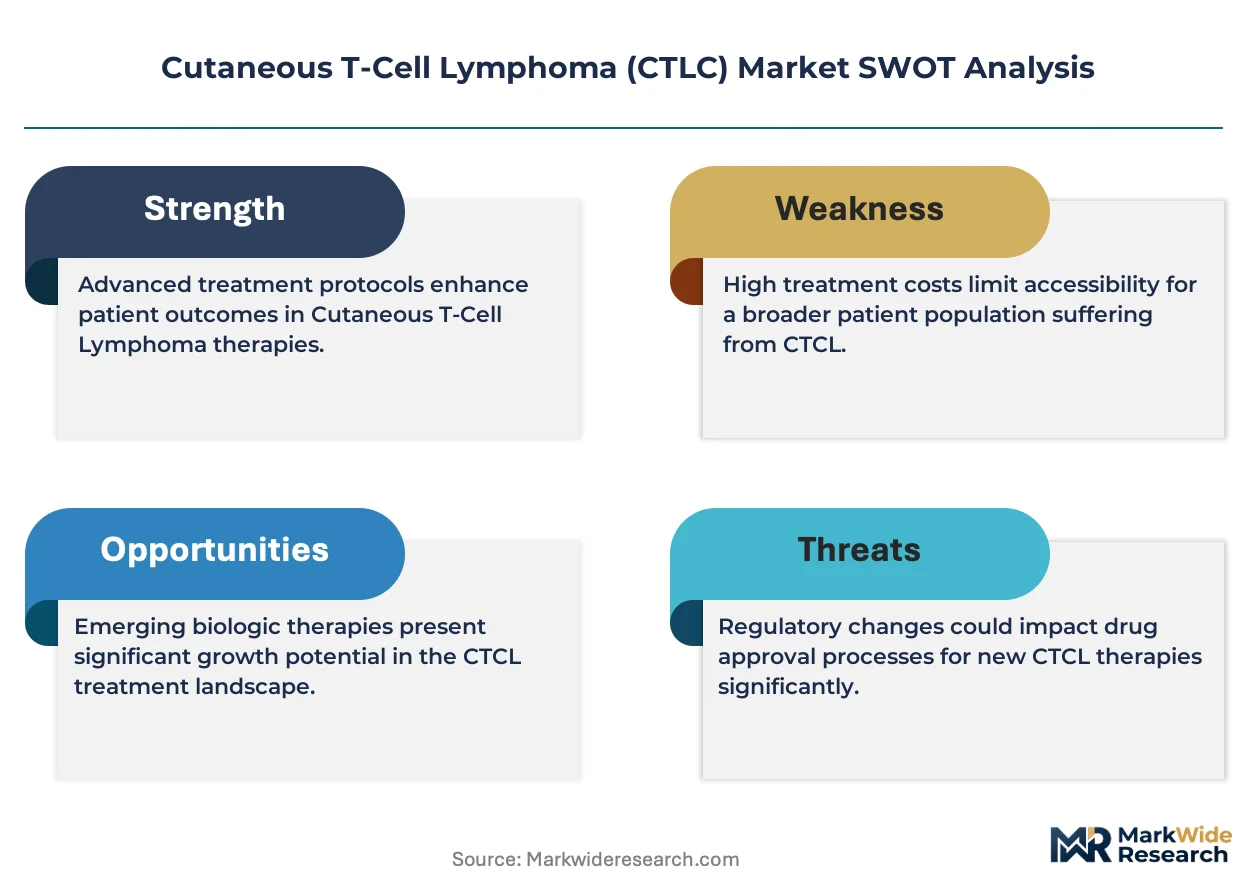
For Market Incumbents: To counter checkpoint inhibitor pipeline fragmentation across competing oncology centers, Bristol-Myers Squibb and Merck & Co. should secure exclusive site network arrangements with academic medical centers in Boston and Durham. Backward integration into companion diagnostic development reinforces biomarker-driven patient stratification capabilities against emerging precision oncology biotechs. For New Entrants and Emerging Players: PMDA's sakigake designation in Japan opens a window for oral targeted therapy positioning where dermatology clinic density supports localized market entry. White-space concentration sits with telemedicine-enabled triage platforms connecting rural dermatology networks to specialized histopathology laboratories. A go-to-market angle pairing AI-enabled diagnostic screening with remote patient monitoring addresses the community hospital service expansion bottleneck. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier systemic retinoid manufacturers with established dermatology heritage in Germany and Japan. Long-term viability over a five-to-ten year horizon rests on pipeline assets demonstrating PRIME eligibility under EMA's priority medicines scheme. Monitor biomarker-driven patient stratification tool approvals as the inflection signal for precision oncology valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Checkpoint inhibitor pipelines compress timelines through PD-1/PD-L1 platform standardization at oncology centers. |
| Regulatory Approval Pathway | FDA orphan drug designation accelerates CTLC therapy access through seven-year exclusivity incentives. |
| Manufacturing Scale-Up | Cleanroom capacity expansion in Massachusetts addresses monoclonal antibody production bottlenecks. |
| Pipeline Diversification | Biomarker-driven patient stratification tools open precision oncology positioning for emerging entrants. |
| Licensing Agreement | Companion diagnostic convergence partnerships with flow cytometry platform vendors secure diagnostic infrastructure control. |
Study Parameters
Independent corroboration across regulatory submission databases, clinical trial registries, and hospital procurement records underwrites the qualitative findings in this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchored segmentation estimates.
Rate-of-change decomposition across the analysis window disaggregated volume trajectories by treatment line, administration route, patient population, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to diagnosed incident cases and therapy penetration assumptions. Forecast inputs incorporated immunophenotyping automation adoption curves and orphan drug designation approval velocity.
Caveats apply where biomarker validation failures or reimbursement negotiation delays could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory pathway success rates and site network expansion timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Carcinoid Syndrome Management Market
Specialty Medicine
Fascioliasis Treatment Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Biliary Atresia Treatment Market
Specialty Medicine
Transthyretin Amyloidosis Treatment Market
Specialty Medicine
Carcinoid Tumor Syndrome Management Market
Specialty Medicine
Adenomyosis Market
Specialty Medicine
TMJ Disorders Market
Specialty Medicine
Thyroid Cancer Therapeutics Market
Specialty Medicine
Dyschromia Therapeutics Market
Specialty Medicine
Primary Hyperoxaluria Treatment Market
Specialty Medicine
Subdural Haematoma Market
Specialty Medicine
Pigmentosa Treatment Market
Specialty Medicine
Borderline Personality Disorder Market
Specialty Medicine
Histamine Toxicity Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market