
 Alport Syndrome Treatment Market | 2026-2036
Alport Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Alport Syndrome Treatment Market Analytics
RNA-targeting platform development is reshaping therapeutic architecture for Alport syndrome, shifting investment from small-molecule symptom management toward disease-modifying modalities. Chinook Therapeutics leverages precision nephrology capabilities to anchor its position in genetic kidney disease. Eloxx Pharmaceuticals competes through readthrough technology specialization for nonsense mutation subsets. Travere Therapeutics sustains clinical momentum across its rare renal portfolio.
Alport syndrome treatment encompasses therapeutic interventions for the X-linked, autosomal recessive, and autosomal dominant forms of collagen IV alpha-chain defects that manifest as progressive glomerulonephritis, sensorineural hearing loss, and ocular abnormalities. Standard care combines renin-angiotensin-aldosterone system blockade with emerging genetic and cellular interventions to delay end-stage renal disease. Antihypertensives and supportive care dominate current prescribing patterns due to established reimbursement pathways and nephrologist familiarity. Immunosuppressants represent the fastest-growing category as investigators explore mechanistic overlaps with other glomerular diseases and biomarker-driven patient stratification improves.
The FDA's orphan drug program and EMA's PRIME designation framework jointly shape development timelines and market access conditions for Alport syndrome innovators. The EU AI Act and GDPR impose specific constraints on genomic data utilization in multinational rare disease trials. The National Kidney Foundation and EURORDIS influence patient registry standards that determine trial feasibility. Stakeholders must monitor how payer evidence requirements for gene therapies diverge between single-payer and multipayer health systems.
Market Dynamics
Gene therapy platform maturation is compressing development timelines for Alport syndrome interventions while forcing nephrology departments to rebuild clinical trial infrastructure around nucleic acid delivery protocols.
Growth Catalysts
- Orphan Drug Incentives:The FDA's tax credits and market exclusivity provisions accelerate sponsor investment in rare renal indications. Pediatric nephrology centers leverage these incentives to expand screening cohorts.
- Precision Nephrology:Genomic stratification of collagen IV mutations enables targeted enrollment in mechanism-specific trials. Academic medical centers deploy next-generation sequencing to identify eligible patients earlier in disease progression.
- Gene Therapy Manufacturing:Contract development organizations in the United States and Switzerland are scaling AAV production capacity dedicated to renal indications. This infrastructure expansion reduces sponsor capital requirements for Phase I/II initiation.
Market Restraints
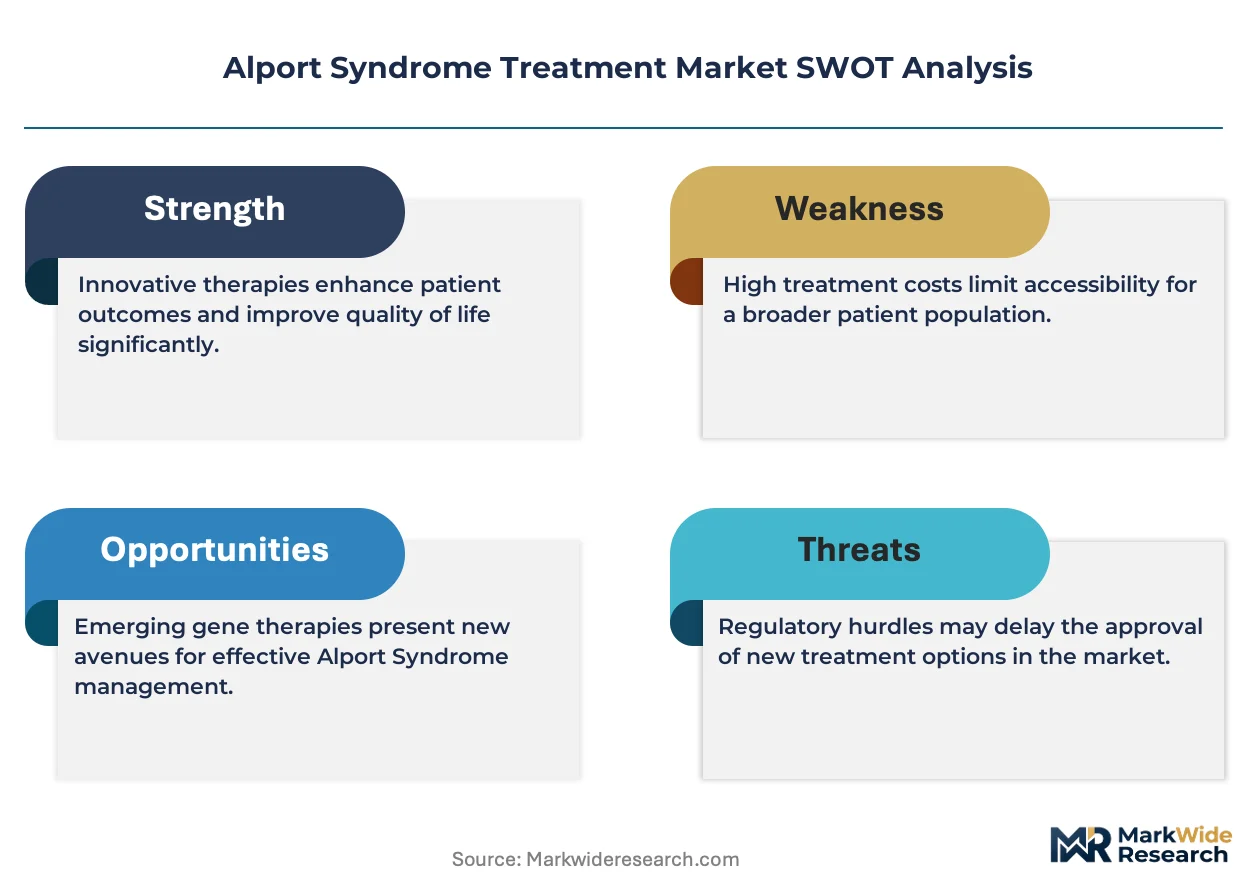
- AAV Immunogenicity:Pre-existing neutralizing antibodies in the general population exclude substantial patient subsets from gene therapy trials. Screening protocols must incorporate serology testing that adds cost and complexity.
- European Data Constraints:The EU AI Act and GDPR impose specific limitations on cross-border genomic data sharing for multinational rare disease studies. Trial sponsors face fragmented consent frameworks across member states.
- Specialist Distribution:Qualified principal investigators concentrate at tertiary academic centers in the United States, Germany, and Japan. Site activation timelines stretch 18-24 months in underserved regions.
Strategic Opportunities
- Autosomal Dominant Subset:The heterozygous COL4A3/COL4A4 population remains underserved by current X-linked-focused development programs. Mechanism-specific trials for this genotype represent unaddressed white space.
- Patient Registry Integration:The National Kidney Foundation and EURORDIS are harmonizing data standards across national registries. Sponsors who align trial endpoints with these frameworks gain accelerated recruitment access.
- Combination Therapy Architecture:Pairing RNA-targeting platforms with established renin-angiotensin-aldosterone system blockade could demonstrate additive efficacy. Nephrology departments in the United States are piloting such protocols.
Industry Challenges
- Gene Therapy Talent Scarcity:Clinical operations personnel with nucleic acid trial experience command premium compensation. Sponsors compete for limited candidates familiar with renal endpoint adjudication.
- Biomarker Validation:Proteinuria and estimated glomerular filtration rate remain imperfect surrogates for long-term renal survival. Regulatory agencies demand extended follow-up that extends trial duration and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alport Syndrome Treatment Market |
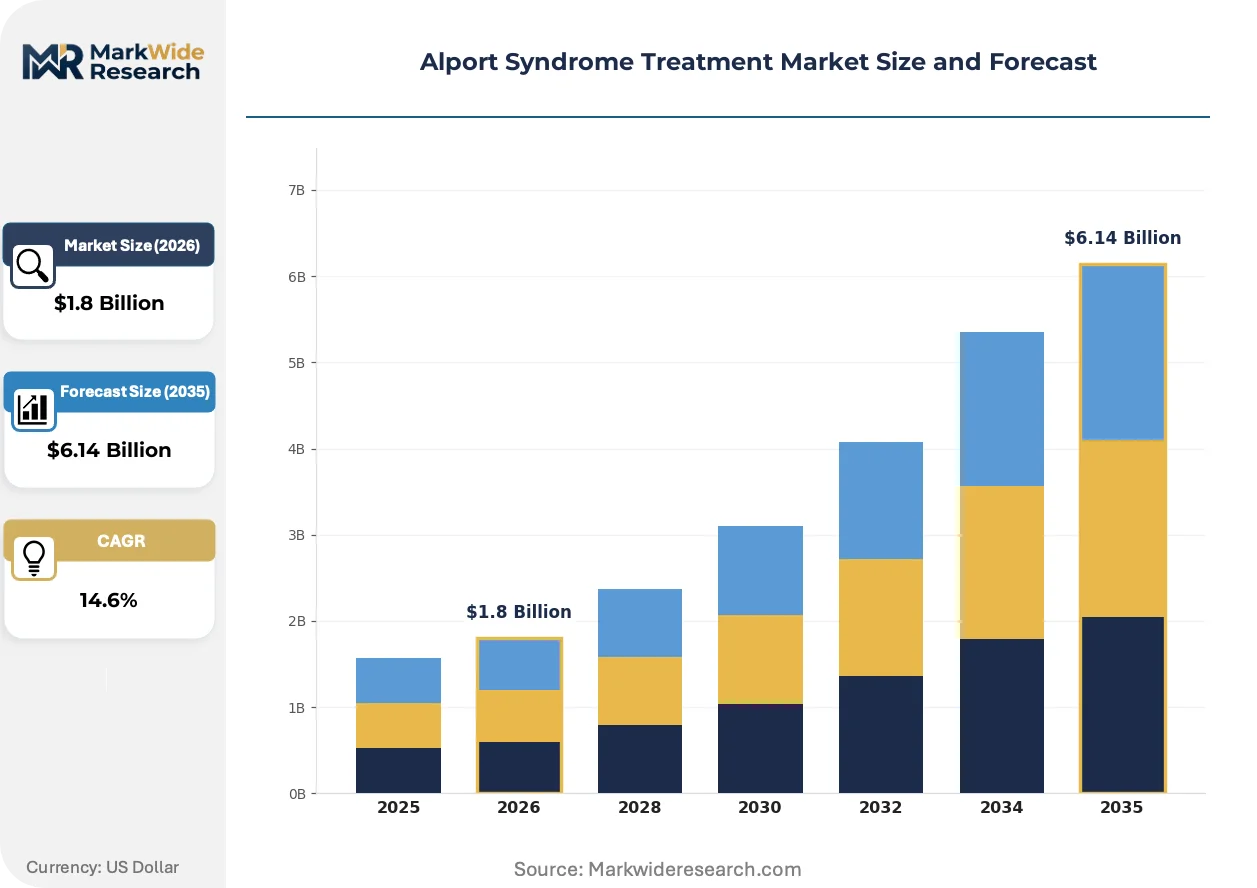
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihypertensives, Corticosteroids, Immunosuppressants, Supportive Care Therapy Area: Kidney Disorders, Genetic Disorders, Rare Diseases, Chronic Conditions Delivery Mode: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Clinics, Homecare, Research Institutions |
| Companies Covered | Eloxx Pharmaceuticals, Chinook Therapeutics, Travere Therapeutics, Reata Pharmaceuticals, Calliditas Therapeutics, Bayer, Regulus Therapeutics, Goldfinch Bio, River 3 Renal Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alport Syndrome Treatment Market Evolving Landscape
RNA-targeting modalities are displacing small-molecule symptom management as the dominant therapeutic architecture, forcing nephrology departments to rebuild clinical competency around nucleic acid therapeutics.
Antisense oligonucleotides targeting collagen IV alpha-chain expression is hybridizing with established nephrology practice. Pediatric nephrology departments at academic medical centers in the United States are adopting these platforms for nonsense mutation subsets. The technology is compressing the traditional small-molecule development cycle while raising reimbursement complexity around mechanism-based pricing.
The EMA's PRIME designation framework is accelerating scientific advice and accelerated assessment pathways for Alport syndrome innovators. Sponsors gain earlier regulatory engagement on surrogate endpoint acceptability. European nephrology centers are restructuring trial units to meet compressed submission timelines demanded by this mechanism.
Procurement patterns among United States payers are hardening around outcomes-based contracts for gene therapies. State Medicaid programs and commercial insurers in Massachusetts and California are piloting annuity payment structures tied to renal function preservation. This shift forces sponsors to build real-world evidence infrastructure that extends beyond traditional clinical trial boundaries.
Alport Syndrome Treatment Market Segmentation
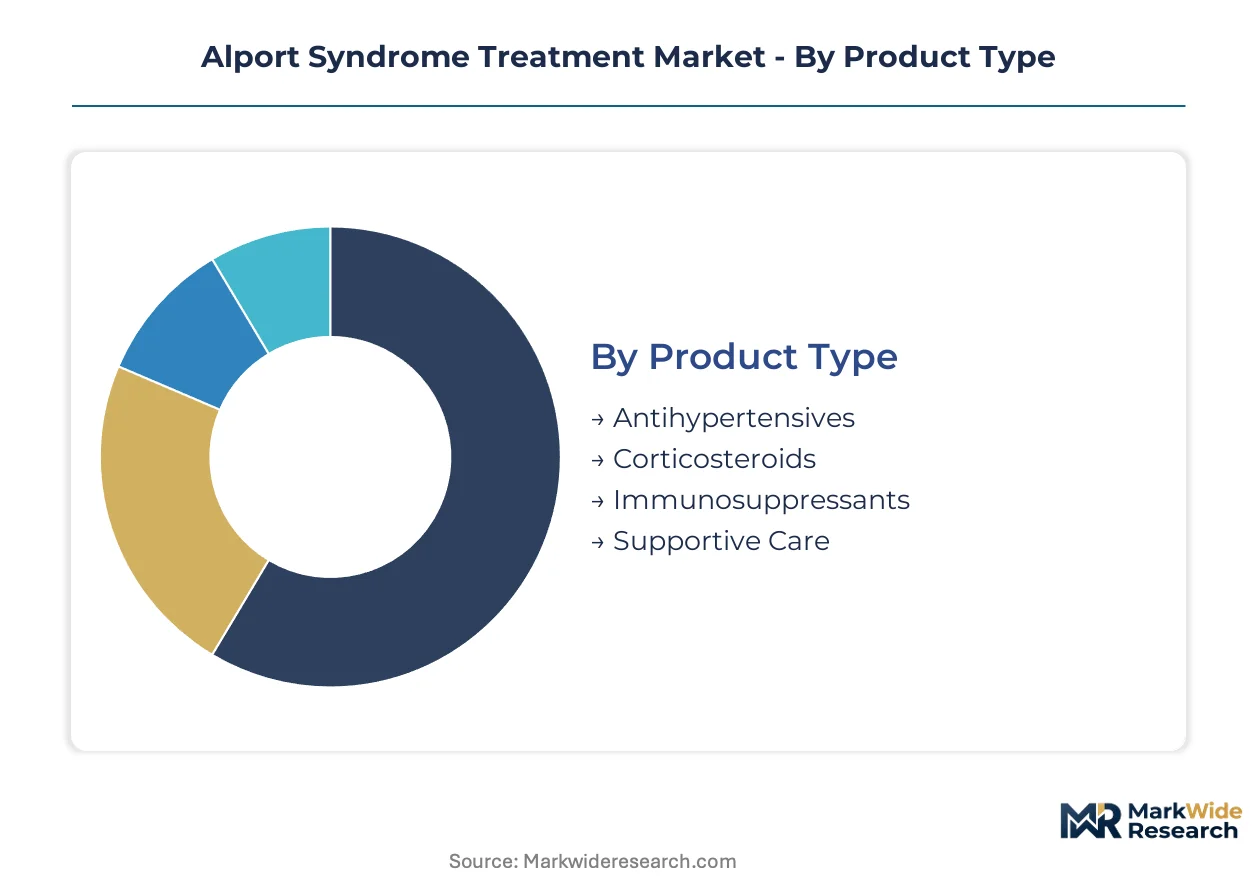
Treatment modality selection in Alport syndrome hinges on mutation type, disease stage, and renal function trajectory. Segmentation reveals how established symptomatic management coexists with emerging genetic interventions across diverse care settings.
Product Type:
Mature pharmacologic categories dominate prescribing volume while novel mechanisms reshape investment priorities.
- Antihypertensives:ACE inhibitors and ARBs constitute the foundational renin-angiotensin-aldosterone system blockade. Nephrology departments at Massachusetts General Hospital and Stanford Medicine standardize these protocols to delay end-stage renal disease progression.
- Immunosuppressants:Calcineurin inhibitors and mycophenolate mofetil are gaining trial enrollment for mechanistic overlaps with other glomerular pathologies. Academic centers in Germany and Japan pilot biomarker-driven stratification to identify responders.
- Corticosteroids:Limited evidence base restricts use to specific histologic presentations with inflammatory features.
- Supportive Care:Phosphate binders, erythropoiesis-stimulating agents, and dietary management address complications of declining renal function.
Antihypertensives retain volume leadership; immunosuppressants hold the steepest expansion curve.
Therapy Area:
Clinical trial design prioritizes genetic precision over broad chronic disease categorization.
- Genetic Disorders:COL4A5, COL4A3, and COL4A4 mutation-specific trials now stratify enrollment by variant class. The FDA's orphan drug incentives accelerate sponsor investment in mechanism-targeted development programs.
- Kidney Disorders:Proteinuria reduction and estimated glomerular filtration rate preservation remain the primary regulatory endpoints. Dialysis providers in the United States track these metrics for outcomes-based contracting.
- Rare Diseases:EMA PRIME designation eligibility compresses European assessment timelines for qualifying assets.
- Chronic Conditions:Long-term management protocols integrate hearing and ophthalmologic surveillance alongside renal monitoring.
Kidney disorders retain volume leadership; genetic disorders hold the steepest expansion curve.
Delivery Mode:
Route selection reflects the tension between patient convenience and therapeutic index requirements.
- Oral:Small-molecule antihypertensives and emerging RNA-targeting platforms favor this route for chronic administration. Patient adherence programs at pediatric nephrology centers in California address pill burden in adolescent populations.
- Intravenous:Gene therapy vectors and monoclonal antibodies require hospital-based infusion infrastructure. Tertiary centers in Switzerland and the United States are scaling dedicated renal gene therapy suites.
- Subcutaneous:Self-administration potential drives development of antisense oligonucleotide formulations for homecare settings.
- Topical:Limited applicability restricted to ocular surface manifestations and dermatologic complications.
Oral delivery retains volume leadership; intravenous holds the steepest expansion curve.
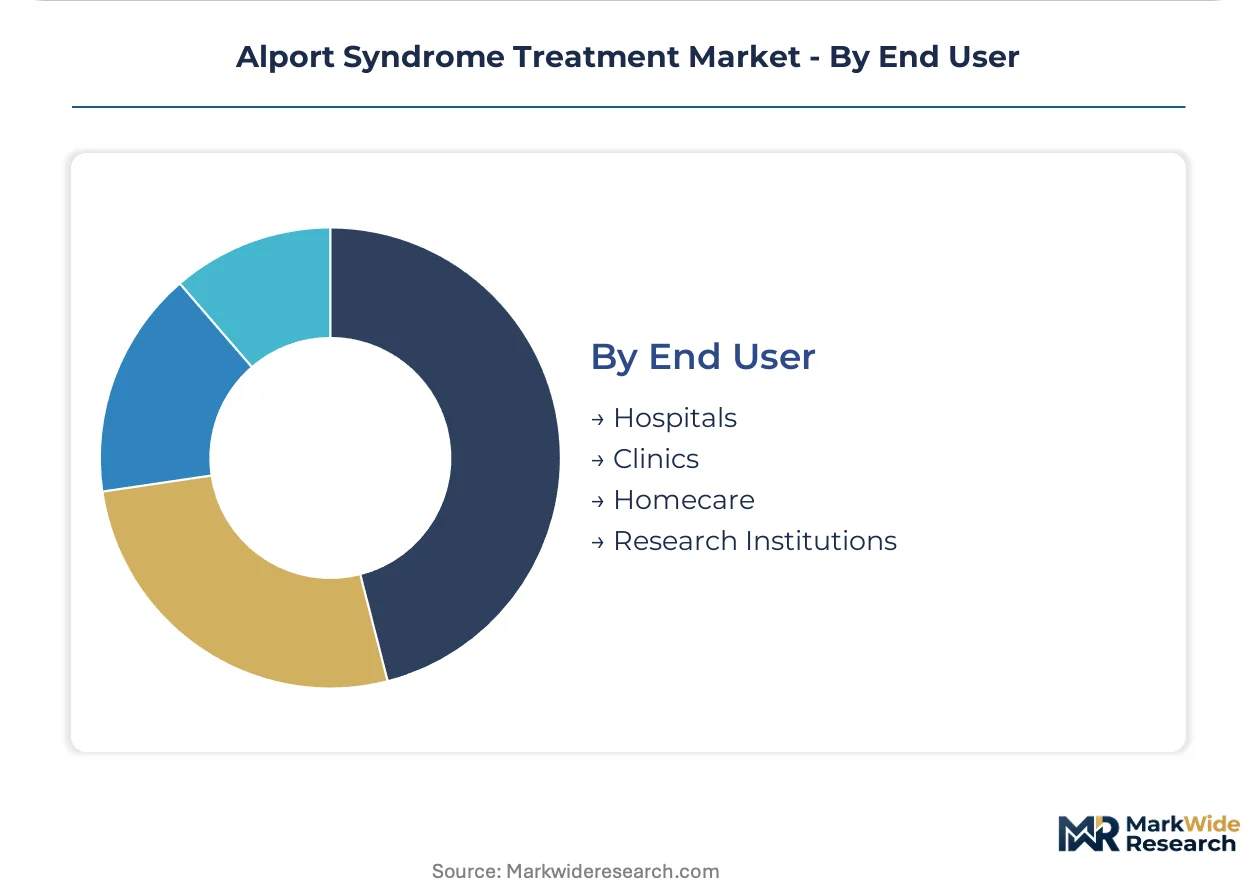
End User:
Care site selection follows disease severity and therapy complexity gradients.
- Hospitals:Tertiary academic medical centers concentrate gene therapy trials and transplant evaluation pathways. Pediatric nephrology departments at centers like Boston Children's Hospital anchor screening protocol expansion.
- Research Institutions:Natural history studies and biomarker validation work occur at specialized units with longitudinal follow-up infrastructure. The National Kidney Foundation collaborates with these sites on registry harmonization.
- Clinics:Community nephrology practices manage stable patients on established antihypertensive regimens.
- Homecare:Subcutaneous delivery advances and remote monitoring technology expand treatment location flexibility.
Hospitals retain volume leadership; research institutions hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric nephrologists at academic medical centers concentrate demand for Alport syndrome therapeutics, with specialist density and regulatory incentives determining geographic priority. The United States, Germany, Japan, United Kingdom, and Switzerland anchor clinical trial infrastructure and patient identification pathways.
United States
Massachusetts General Hospital and Stanford Medicine anchor precision nephrology screening expansion. The FDA's orphan drug tax credits and market exclusivity provisions accelerate sponsor investment in rare renal indications. Boston Children's Hospital pediatric departments deploy next-generation sequencing to identify COL4A5 mutations earlier in disease progression.
Germany
Academic nephrology centers in Heidelberg and Berlin pilot biomarker-driven immunosuppressant stratification protocols. EMA PRIME designation eligibility compresses scientific advice timelines for qualifying assets. The country's dense specialist network supports multinational trial site activation across the Rhine-Ruhr and Bavarian medical clusters.
Japan
PMDA's Sakigake designation system accelerates priority review for innovative renal therapies. Tokyo and Osaka tertiary centers concentrate gene therapy vector administration infrastructure. METI funding for rare disease manufacturing scales AAV production capacity dedicated to collagen IV alpha-chain interventions.
United Kingdom
Genomic England's rare disease sequencing program identifies COL4A3 and COL4A4 variants in pediatric cohorts. The MHRA's Innovative Licensing and Access Pathway compresses market access timelines for mechanism-targeted therapies. London and Cambridge research institutions anchor natural history study infrastructure with longitudinal follow-up capabilities.
Switzerland
Swissmedic's expedited assessment procedures align with EMA scientific advice for renal gene therapies. Basel and Zurich contract development organizations scale AAV manufacturing dedicated to rare disease indications. The country's central European location supports cross-border patient recruitment from France, Germany, and Italy.
Alport Syndrome Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across the Alport syndrome treatment landscape. The vendor base stratifies into three tiers: large-cap pharmaceutical companies with rare disease divisions, mid-cap precision nephrology specialists, and emerging gene therapy platforms. Dominant competitive moves include strategic partnerships for AAV manufacturing access and portfolio diversification into autosomal dominant genotype subsets.
Among precision nephrology specialists, Chinook Therapeutics and Eloxx Pharmaceuticals exemplify mechanism-targeted development strategies. Travere Therapeutics occupies a position within the rare renal portfolio tier. These companies represent the shift from small-molecule symptom management toward RNA-targeting and gene therapy architectures that reshape clinical trial design and regulatory engagement patterns.
| Leading Market Players |
|---|
| Eloxx Pharmaceuticals |
| Chinook Therapeutics |
| Travere Therapeutics |
| Reata Pharmaceuticals |
| Calliditas Therapeutics |
| Bayer |
| Regulus Therapeutics |
| Goldfinch Bio |
| River 3 Renal Corp |
| Others |
Value Network & Pricing Analysis
AAV vector manufacturing concentration in Switzerland and the United States determines where therapeutic margin pools accumulate, with sponsors paying premiums for dedicated renal gene therapy production slots that academic medical centers ultimately absorb through outcomes-based contracts.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate gene therapy procurement between sponsors and contract manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates validated GMP-grade vectors from research-grade materials and early-process development lots. Pricing pressure stems from AAV immunogenicity screening requirements that add serology testing costs to patient access programs. Pediatric nephrology departments at academic medical centers exhibit highest price sensitivity due to fixed reimbursement ceilings, while commercial payers in Massachusetts and California piloting annuity structures show lowest sensitivity.
Supply Chain Analysis
Contract manufacturing concentration rests with Swiss CDMOs in Basel and Zurich plus United States facilities in Massachusetts and California that scale AAV production capacity. Plasmid DNA, cell culture media, and purification resins constitute critical input dependencies. Single-source vulnerability pervades specialized AAV serotype production where qualified alternative suppliers remain scarce. Distribution runs through hospital-based infusion centers at tertiary academic medical centers that maintain cold-chain integrity for nucleic acid therapeutics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States commercial payers and state Medicaid programs that negotiate outcomes-based contracts, fragmenting pricing autonomy previously held by academic medical centers.
For Market Incumbents: Insulate gene therapy portfolios through backward integration into AAV manufacturing capacity in Switzerland or captive plasmid supply agreements. Lock in long-term site activation contracts with pediatric nephrology departments at Boston Children's Hospital and Stanford Medicine before competitor enrollment expansion. The threat of RNA-targeting platform displacement from Chinook Therapeutics and Eloxx Pharmaceuticals demands mechanism-specific trial acceleration. For New Entrants and Emerging Players: Build out autosomal dominant COL4A3/COL4A4 genotype programs as the most penetrable white space underserved by current X-linked-focused development. Target subcutaneous antisense oligonucleotide delivery for homecare settings where oral administration convenience drives patient adherence. Establish partnerships with the National Kidney Foundation for patient registry integration that accelerates recruitment access. For Investors and Strategic Acquirers: Capital is best deployed toward precision nephrology specialists with validated RNA-targeting platforms and existing EMA PRIME designation momentum. Long-term viability over the analysis window favors sponsors with diversified collagen IV mutation coverage spanning nonsense mutation readthrough and splice modulation mechanisms. Watch FDA orphan drug tax credit policy continuity as the signal indicating sustained sponsor investment appetite.| Strategic Initiative | Industry Significance |
|---|---|
| AAV Manufacturing Scale-Up | Swiss and United States CDMO capacity expansion reduces sponsor capital requirements for Phase I/II initiation. |
| Patient Registry Integration | Alignment with National Kidney Foundation and EURORDIS data standards accelerates trial recruitment timelines. |
| Combination Therapy Architecture | Pairing RNA-targeting platforms with ACE inhibitor standard-of-care demonstrates additive efficacy in nephrology pilots. |
| EMA PRIME Designation Pathway | Accelerated scientific advice compresses European assessment timelines for mechanism-targeted renal therapies. |
| Outcomes-Based Contracting | Annuity payment structures tied to renal function preservation reshape United States payer procurement patterns. |
Research Methodology
The analysis maps antihypertensive, immunosuppressant, gene therapy, and RNA-targeting sub-sectors, each validated through regulatory affairs leads at the FDA and EMA, nephrology department heads at academic medical centers, and payer access specialists at United States commercial insurers. Primary interview insights triangulate against secondary sources including ClinicalTrials.gov entries, EMA PRIME designation records, FDA orphan drug approval databases, and hospital procurement contracts. Bottom-up patient population estimates and top-down therapeutic category spend reconciliation anchor market sizing.
Assumptions held fixed include current FDA orphan drug tax credit rates and EMA PRIME eligibility criteria, while variables tested encompass AAV manufacturing capacity expansion rates and immunogenicity screening protocol adoption. Segmentation modeling spans treatment modality, mutation type, delivery route, and end-user site across the projection horizon. CAGR derivation incorporates epidemiological prevalence adjustments, diagnosis rate improvements from next-generation sequencing expansion, and therapy penetration curves by disease stage.
Stress conditions across AAV neutralizing antibody prevalence, European data sharing consent fragmentation, and gene therapy talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions and acknowledge that regulatory pathway disruptions or manufacturing yield breakthroughs could materially revise projections. Quarterly review of FDA orphan drug incentive policy, EMA scientific advice queue depth, and AAV serotype-specific immunogenicity data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Premature Ejaculation Treatment Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Neurodegenerative Disease Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Liver Metastases Treatment Market
Specialty Medicine
Post-Traumatic Stress Disorder Treatment Market
Specialty Medicine
Dry Eye Syndrome Market
Specialty Medicine
Bacteriophages Therapy Market
Specialty Medicine
Global Retinal Biologics Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Histamine Toxicity Market
Specialty Medicine
Psoriatic Arthritis (Psa) Treatment Market
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
Global Vasculitis Treatment Market
Specialty Medicine
Global Calciphylaxis Treatment Market