
 External Urine Management Products Market | 2026-2036
External Urine Management Products Market Size, Share, and Industry Trends Forecast 2026-2036
External Urine Management Products Market Intelligence
Market Context
Specialized wound-ostomy-continence nursing capacity is bifurcating the competitive landscape between premium catheter suppliers and commoditized bag manufacturers. Hollister Inc. leverages its silicone formulation expertise to dominate acute care contracts across North American hospital networks. Cardinal Health sustains broad distribution reach through its integrated medical supply chain, competing on logistics scale rather than device innovation. Coloplast Corp. differentiates through hydrophobic coating technology that reduces skin breakdown incidents in long-term care settings.
Technical Definition and Segment Structure
External urine management products encompass non-invasive collection systems including sheaths, adhesive seals, drainage bags, and connecting tubing designed to channel urine away from the body without urethral catheterization, typically employing medical-grade silicone or latex with hydrophobic surface treatments to prevent maceration and maintain skin integrity. These devices serve patients with urinary incontinence, post-surgical recovery needs, or catheterization contraindications across hospital, home care, and long-term care environments. Catheter and sheath systems capture the largest revenue share due to recurring replacement cycles and higher per-unit pricing, while collection devices and urine bags face margin compression from private-label competition. Hospitals remain the dominant end-user channel with centralized procurement power, though home care is expanding fastest as reimbursement shifts favor outpatient management and aging-in-place policies mature.
Regulatory Environment
FDA Class II medical device clearances govern market entry for external collection systems in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for hydrophobic-coated variants seeking CE marking. Health Canada and Japan's PMDA maintain aligned standards for biocompatibility testing that create parallel compliance burdens for multinational manufacturers. Stakeholders must monitor evolving post-market surveillance mandates and reimbursement code granularity as payers increasingly tie coverage to demonstrated reduction in catheter-associated urinary tract infections.
Market Dynamics
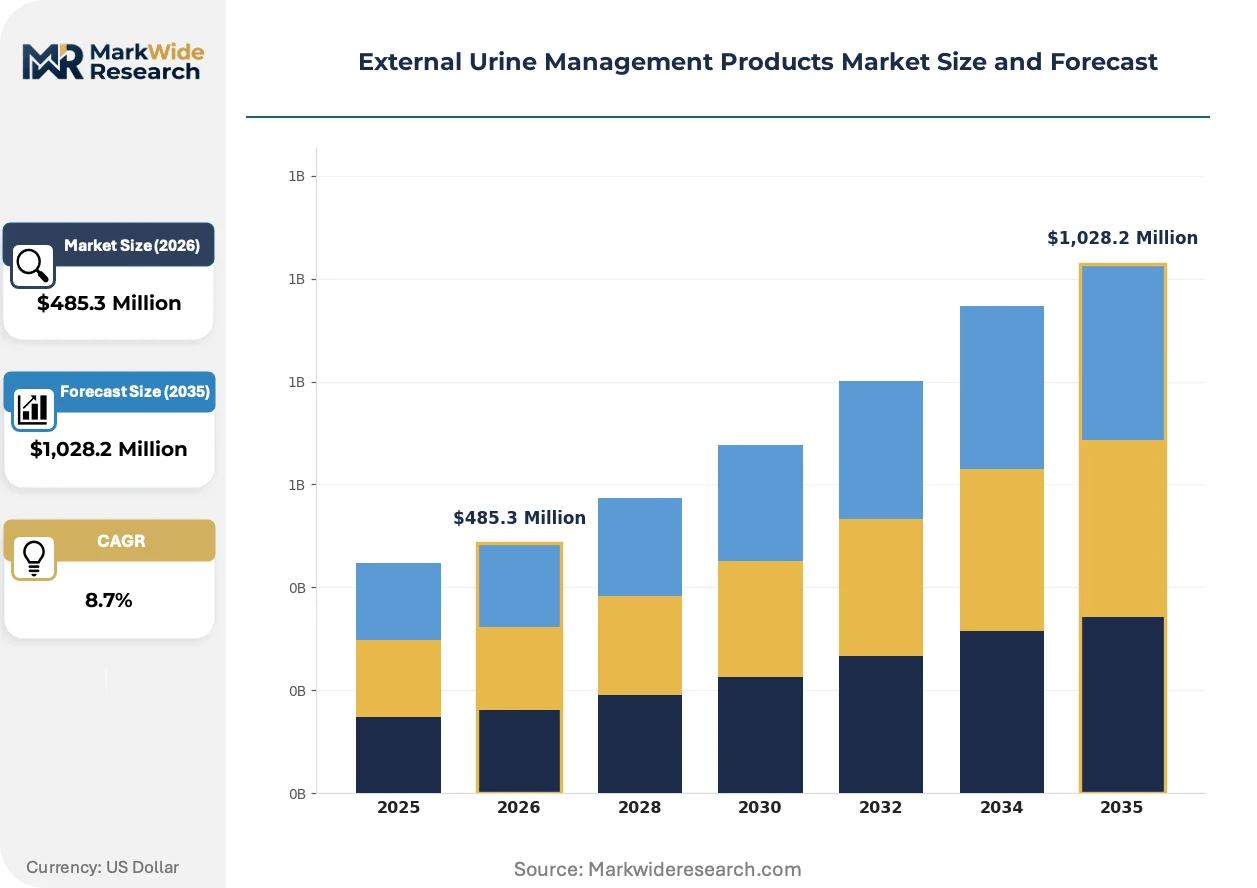
Hospital procurement consolidation is compressing margins for external urine management suppliers while simultaneously accelerating adoption of hydrophobic-coated systems that reduce catheter-associated infection liability. This structural pressure rewards manufacturers with vertically integrated silicone supply chains and penalizes distributors lacking clinical evidence packages.
Growth Catalysts
- Japan's PMDA fast-track pathway:Accelerated approval timelines for infection-prevention devices are shortening market entry cycles for hydrophobic-coated sheaths in acute care facilities.
- Home care reimbursement expansion:Germany's outpatient nursing insurance reforms are shifting urine collection device procurement from institutional to retail channels, creating recurring revenue streams.
- Silicone formulation advances:Medical-grade elastomer processing improvements are extending wear-time durations and reducing replacement frequency in long-term care settings.
Market Restraints
- Medical-grade silicone supply concentration:Raw material sourcing depends on a narrow supplier base concentrated in German and Japanese chemical clusters, exposing manufacturers to input volatility.
- EU MDR clinical evidence requirements:Stricter biocompatibility documentation for hydrophobic-coated variants is extending CE marking timelines and elevating compliance costs.
- Reusable intermittent catheter substitution:Single-use external collection systems face displacement from sterilizable alternatives in cost-sensitive home care segments.
Strategic Opportunities
- India's geriatric infrastructure buildout:National health mission allocations for district hospital continence care are creating first-mover advantages for suppliers establishing local manufacturing.
- Telehealth-integrated remote monitoring:Sensor-enabled drainage bags with wireless volume alerting are converging digital health platforms with traditional urological devices.
- US Medicare Advantage supplemental benefits:Plan-specific incontinence supply allowances are opening direct-to-patient channels bypassing traditional durable medical equipment distributors.
Industry Challenges
- Wound-ostomy-continence nursing shortages:Specialized clinician scarcity is limiting proper fitting and training for external sheath systems, elevating product return rates and patient injury claims.
- FDA 510(k) predicate device drift:Evolving substantial equivalence standards for hydrophobic-coated variants are forcing manufacturers into costly new clinical studies rather than streamlined clearances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | External Urine Management Products Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,028.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Urine Bags, Collection Devices, Sheath Systems End User: Hospitals, Home Care, Long-term Care Facilities, Ambulatory Surgical Centers Material: Silicone, Latex, PVC, Hydrophobic Coatings Feature: Anti-reflux, Odor Control, Disposable, Sterile |
| Companies Covered | Hollister Inc., Cardinal Health, Coloplast Corp., B. Braun Melsungen AG, Teleflex Inc., Sage Products (Stryker), Boehringer Laboratories LLC, Men’s Liberty (BioDerm), Tilla Care Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
External Urine Management Products Market Strategic Shifts & Innovations
Silicone surface engineering and digital connectivity are converging to transform external urine management from commodity drainage hardware into data-generating clinical tools. These shifts are compressing traditional equipment replacement cycles while elevating software and coating chemistry capabilities.
Plasma-activated hydrophobic coatings are displacing conventional silicone sheaths in North American acute care procurement. Hospital infection control committees are mandating these surfaces for ICU and post-surgical units where catheter-associated urinary tract infection liability concentrates. The technology is displacing standard latex alternatives by enabling 72-hour continuous wear protocols that reduce nursing labor and supply costs.
EU MDR post-market surveillance mandates are forcing manufacturers to maintain active clinical registries for hydrophobic-coated devices seeking CE renewal. This regulatory burden is consolidating competitive positioning toward firms with dedicated European regulatory affairs infrastructure. Long-term care distributors in France and Germany are prioritizing suppliers with documented skin integrity outcome data to satisfy purchasing committee due diligence requirements.
Consolidated hospital procurement is unbundling after-sales clinical training from device pricing in the United States. Integrated delivery networks are demanding separate service contracts for nursing education and fitting support, treating these as distinct line items from product acquisition. This behavioral shift is most pronounced in California and Texas health systems where centralized supply chain offices have absorbed individual facility purchasing autonomy.
External Urine Management Products Market Segmentation
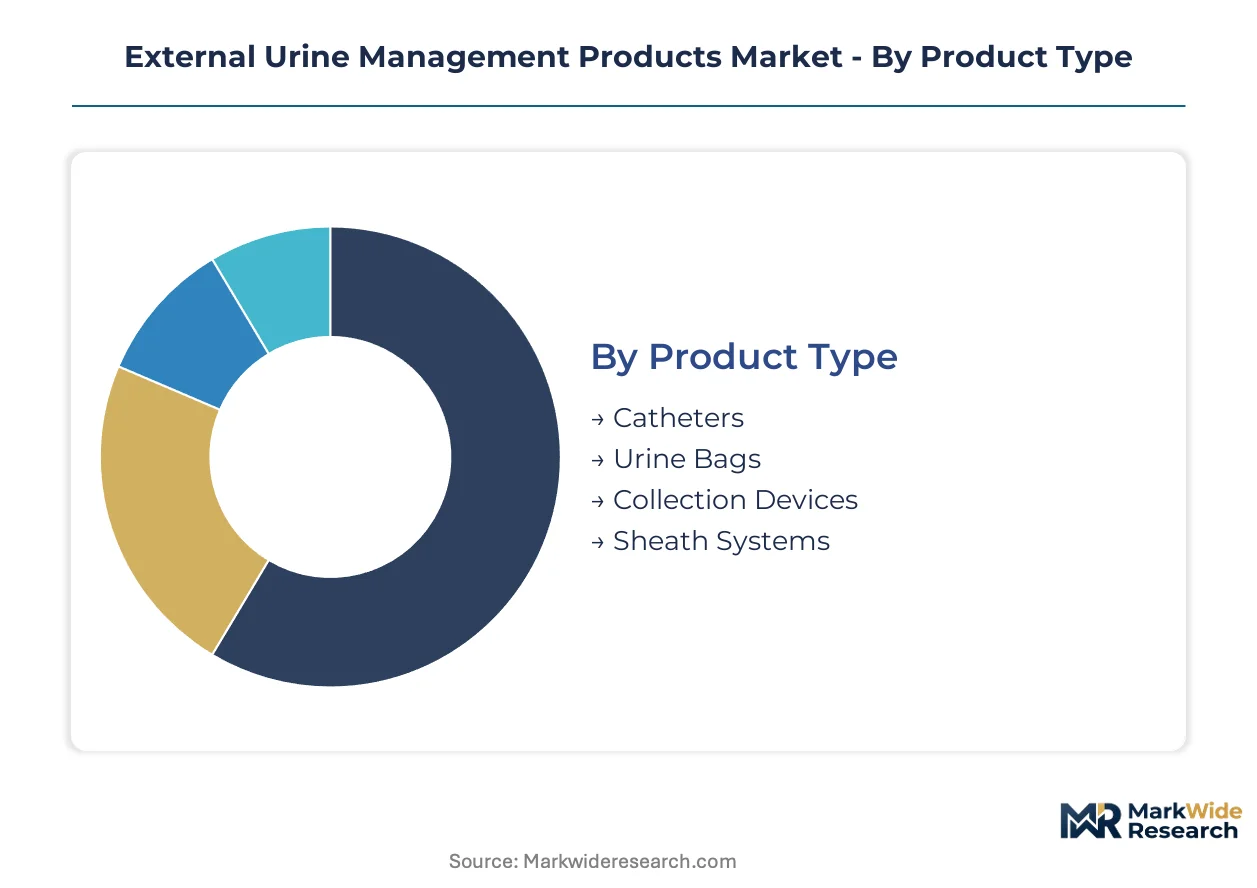
External urine management products fragment across four critical dimensions that determine procurement patterns and margin structures. Product type and material composition drive clinical differentiation, while end-user channel and feature sets shape pricing power and replacement frequency.
Product Type:
Catheter and sheath systems face the strongest substitution pressure from reusable intermittent alternatives in cost-sensitive home care segments, while drainage hardware confronts commoditization from private-label competition.
- Catheters:Urethral and external catheter variants employ medical-grade silicone or latex with hydrophobic surface treatments to prevent biofilm formation. Demand concentrates in United States hospital ICUs where infection control committees mandate coated variants to reduce catheter-associated urinary tract infection liability.
- Sheath Systems:Non-invasive external collection sheaths utilize adhesive seals and silicone elastomer formulations designed for extended wear protocols. German outpatient nursing insurance reforms are accelerating procurement shifts from institutional to retail channels for these systems.
- Urine Bags:Drainage reservoirs with anti-reflux valves and graduated volume markings serve as replacement-dependent consumables. Japanese acute care facilities specify high-capacity variants for post-surgical recovery units.
- Collection Devices:Integrated bedpans, urinals, and portable receptacles complete the non-invasive collection ecosystem. Long-term care facilities in France prioritize stackable, autoclavable designs for storage efficiency.
Catheters anchor the volume base while sheath systems gain share at the steepest rate.
End User:
Channel cost tiers stratify sharply between centralized hospital procurement with bundled service contracts and fragmented retail home care with direct-to-patient reimbursement pathways.
- Hospitals:Integrated delivery networks in California and Texas leverage centralized supply chain offices to unbundle clinical training from device pricing, treating nursing education as distinct line items. These systems command volume discounts while demanding hydrophobic-coated variants for infection liability reduction.
- Home Care:Aging-in-place policies and Medicare Advantage supplemental benefits are opening direct-to-patient channels that bypass traditional durable medical equipment distributors. United States reimbursement shifts favor outpatient management with recurring revenue models.
- Long-term Care Facilities:Skin integrity outcome data requirements from French and German purchasing committees elevate supplier qualification barriers. Plasma-activated hydrophobic coatings reduce maceration incidents in extended-stay populations.
- Ambulatory Surgical Centers:Same-day discharge protocols drive demand for compact, single-use collection systems with minimal fitting complexity. These facilities prioritize rapid turnover inventory over extended-wear technologies.
Hospitals dominate absolute procurement value while home care channels expand most quickly.
Material:
Supply concentration in German and Japanese chemical clusters creates input volatility that reshapes competitive positioning among formulation specialists.
- Silicone:Medical-grade elastomer processing improvements extend wear-time durations and reduce replacement frequency. Hollister Inc. leverages formulation expertise to dominate North American acute care contracts through vertically integrated supply chains.
- Hydrophobic Coatings:Plasma-activated surface treatments enable 72-hour continuous wear protocols that reduce nursing labor and supply costs. FDA Class II clearance pathways and EU MDR clinical evidence requirements extend development timelines for coated variants.
- Latex:Natural rubber formulations persist in cost-sensitive segments despite allergy concerns and inferior moisture management. These materials face displacement from silicone alternatives in premium procurement tiers.
- PVC:Polyvinyl chloride drainage tubing and connectors serve as commodity inputs with thin margins and high volume throughput. Private-label competition concentrates in this material tier.
Silicone anchors the volume base while hydrophobic coatings gain share at the steepest rate.
Feature:
Maturity gradients separate established anti-reflux engineering from emerging digital connectivity capabilities that transform hardware into data-generating clinical tools.
- Anti-reflux:Mechanical valve systems prevent urine backflow and contamination in drainage bags. These features represent baseline specifications for hospital procurement with limited pricing premium.
- Odor Control:Activated carbon filters and antimicrobial additives address quality-of-life concerns in home care and long-term care settings. German and Japanese consumers demonstrate willingness to pay premium pricing for these enhancements.
- Disposable:Single-use protocols dominate acute care to eliminate sterilization logistics and cross-contamination risk. Environmental regulations in EU member states are beginning to challenge this design paradigm.
- Sterile:Gamma-irradiated or ethylene oxide-sterilized packaging satisfies surgical and immunocompromised patient requirements. Ambulatory surgical centers mandate sterile presentation for all collection components.
Disposable features anchor the volume base while odor control gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Class II medical device clearances anchor the United States as the dominant geography, while aging demographics and reimbursement reforms reshape procurement patterns across Germany, Japan, and emerging markets.
United States
Integrated delivery networks in California and Texas leverage centralized supply chain offices to unbundle clinical training from device pricing. Medicare Advantage supplemental benefits for incontinence supplies are opening direct-to-patient channels that bypass traditional durable medical equipment distributors. Hospital infection control committees in the Northeast are mandating hydrophobic-coated variants for ICU procurement.
Germany
Outpatient nursing insurance reforms are shifting urine collection device procurement from institutional to retail channels, creating recurring revenue streams for sheath system suppliers. The EU Medical Device Regulation imposes stricter clinical evidence requirements for hydrophobic-coated variants seeking CE marking. Medical-grade silicone supply clusters in the Rhine-Ruhr region anchor formulation expertise for premium catheter manufacturers.
Japan
PMDA fast-track pathways for infection-prevention devices are shortening market entry cycles for hydrophobic-coated sheaths in Tokyo and Osaka acute care facilities. Aging-in-place policies are expanding home care reimbursement for external collection systems. The Kanto region concentrates demand from post-surgical recovery units specifying high-capacity drainage variants.
India
National health mission allocations for district hospital continence care are creating first-mover advantages for suppliers establishing local manufacturing in Maharashtra and Karnataka. The Central Drugs Standard Control Organization governs medical device registration with evolving biocompatibility testing standards. Chennai and Hyderabad clusters are emerging as assembly hubs for cost-sensitive drainage bag production.
United Kingdom
NHS procurement frameworks are consolidating external urine management purchasing through regional clinical commissioning groups, compressing margins while favoring suppliers with documented infection reduction outcomes. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR standards for post-market surveillance. London and Southeast England health systems are piloting telehealth-integrated remote monitoring for home care patients.
External Urine Management Products Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in external urine management products. Three strategic archetypes dominate: vertically integrated silicone formulators with captive supply chains, diversified medical distributors competing on logistics scale, and coating technology specialists differentiating through clinical outcome data. Competitive moves concentrate on M&A for regulatory infrastructure and strategic partnerships for digital health integration.
Among North American incumbents, Hollister Inc. and Cardinal Health exemplify contrasting scale strategies—one anchored in formulation expertise, the other in distribution reach. Coloplast Corp. occupies a position within the European specialist tier, representing the hydrophobic coating differentiation archetype. These three names anchor the competitive structure without exhausting its breadth.
| Leading Market Players |
|---|
| Hollister Inc. |
| Cardinal Health |
| Coloplast Corp. |
| B. Braun Melsungen AG |
| Teleflex Inc. |
| Sage Products (Stryker) |
| Boehringer Laboratories LLC |
| Men's Liberty (BioDerm) |
| Tilla Care Inc. |
| Others |
Cost & Logistics Intelligence
Capacity utilization at medical-grade silicone polymerization facilities in the Rhine-Ruhr and Kanto regions anchors cost structures across hydrophobic-coated sheath production, compressing margins for non-integrated converters while elevating price floors for premium variants. This scale concentration simultaneously reinforces procurement leverage for hospital GPOs and creates entry barriers for emerging coating specialists lacking captive elastomer supply.
Pricing Analysis
Geographic price spreads of 40-60% separate German hospital tenders from Indian district hospital procurement, reflecting divergent reimbursement density and regulatory compliance burdens. Three-tier pricing structure across premium, standard, and economy levels stratifies by hydrophobic coating certification tier and silicone formulation purity, with FDA-cleared variants commanding substantial premiums over CE-marked alternatives. Pricing pressure stems from consolidated IDN procurement offices unbundling clinical training from device acquisition. Home care patients exhibit highest price sensitivity, while ICU infection control committees prioritize infection liability reduction over unit cost.
Supply Chain Analysis
Inventory lead times for plasma-activated hydrophobic coatings extend 16-24 weeks due to batch qualification protocols at German and Japanese chemical clusters. Raw material sourcing draws from medical-grade silicone polymerization in Germany, fluoropolymer surface treatment chemicals in Japan, and gamma-sterilization packaging films in the United States. Single-source vulnerability concentrates in specialized coating applicators serving CE-marking requirements. Distribution runs through integrated medical supply distributors for hospital channels, direct-to-patient e-commerce for Medicare Advantage segments, and long-term care purchasing cooperatives in France and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent manufacturers face sustained substitution pressure from reusable intermittent catheter systems in cost-sensitive home care segments, requiring defensive repositioning around clinical outcome differentiation and service bundling.
For Market Incumbents: Compound formulation expertise into outcome-based contracting with IDN infection control committees, leveraging hydrophobic coating clinical registries to defend against sterilizable catheter displacement. Deepen backward integration into medical-grade silicone polymerization to secure input cost stability against Rhine-Ruhr supply volatility. Prioritize CE-marking infrastructure investment to navigate EU MDR post-market surveillance mandates without clearance delays.
For New Entrants and Emerging Players: Japan's PMDA fast-track pathway for infection-prevention devices offers accelerated market entry for hydrophobic-coated sheath innovators targeting Tokyo and Osaka acute care procurement. India's district hospital continence care allocations under National Health Mission represent the most penetrable geography, with local assembly partnerships circumventing import duty exposure. Direct-to-patient channels through Medicare Advantage supplemental benefits bypass entrenched durable medical equipment distributor relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors coating chemistry specialists with active European regulatory affairs infrastructure over commoditized drainage bag assemblers. Long-term viability hinges on software-hardware convergence capabilities for telehealth-integrated remote monitoring. Acquisition targets should demonstrate documented skin integrity outcome data and established hospital GPO contracts. Watch for inflection when sensor-enabled drainage bag volumes cross threshold penetration in US home care reimbursement codes.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR compliance infrastructure accelerates hydrophobic-coated variant market entry across German and French purchasing committees. |
| Hospital System Partnership | Integrated delivery network contracting unbundles clinical training from device pricing in California and Texas health systems. |
| Software Companion Development | Sensor-enabled drainage bags with wireless volume alerting converge digital health platforms with traditional urological hardware. |
| Backward Integration into Silicone | Captive medical-grade elastomer supply chains insulate margin structures from German and Japanese chemical cluster volatility. |
| Reimbursement Strategy | Medicare Advantage supplemental benefits for incontinence supplies open direct-to-patient channels bypassing traditional distributors. |
Research Approach
Initial hypotheses were tested against primary input from wound-ostomy-continence nursing directors, hospital procurement committee members, biomedical engineers, GPO contracts managers, and long-term care facility administrators, then refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation, CMS Medicare reimbursement databases, hospital procurement contract registries, and Japanese PMDA approval records. Bottom-up demand modeling across catheter, sheath, urine bag, and collection device segments triangulated with top-down macroeconomic indicators.
Variance decomposition across product type, material composition, end-user channel, and feature set dimensions structured the analytical framework over the projection horizon. CAGRs derived from replacement cycle frequency analysis, pricing trajectory modeling, and channel shift elasticity parameters incorporated silicone formulation advancement rates, reimbursement policy evolution, and infection control protocol adoption curves as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable reimbursement policy and regulatory clearance timeline assumptions; material deviation would warrant model refresh. Revision becomes warranted when hydrophobic-coated device penetration in ICU procurement crosses threshold adoption or when EU MDR post-market surveillance mandates extend CE renewal timelines beyond baseline expectations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
Global Incontinence and Ostomy Care Product Market
Patient Care Supplies
Self Inflating Bag Market
Patient Care Supplies
Ice Packs for Pain Market
Patient Care Supplies
Disposable Incontinence Products (Dips) Market
Patient Care Supplies
Stoma Care Market
Patient Care Supplies
Air-Assisted Patient Transfer Systems Market
Patient Care Supplies
US Pressure Ulcer Prevention Market
Patient Care Supplies
Global Stoma Care/Ostomy Care and Accessories Market
Patient Care Supplies
Abdominal Pads Market
Patient Care Supplies
Reusable Nursing Pads Market
Patient Care Supplies
Asia-Pacific Hospital Supplies Market
Patient Care Supplies
Incontinence Care Products Market
Patient Care Supplies
Stretcher Accessories Market
Patient Care Supplies
Global Patient Lateral Transfer Market
Patient Care Supplies
Shoe Cover Market
Patient Care Supplies
Reusable Incontinence Products Market