
 Mental Retardation Treatment Market | 2026-2036
Mental Retardation Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Mental Retardation Treatment Market Foresight
Multi-source pharmaceutical procurement is consolidating as health systems seek standardized formularies for neurodevelopmental therapies. Pfizer Inc leverages its established CNS portfolio to sustain institutional contracts across academic medical centers. Eli Lilly and Company anchors its position through dedicated psychiatry commercial infrastructure. AstraZeneca competes via differentiated long-acting injectable platforms for co-occurring behavioral conditions.
Mental retardation treatment encompasses pharmacological interventions, behavioral therapies, and structured educational interventions designed to improve cognitive functioning, adaptive behavior, and social integration in individuals with intellectual disability, typically involving psychostimulants, antipsychotics, and applied behavior analysis protocols with individualized education plan coordination. Medications command the largest revenue pool due to chronic prescribing patterns and patent-protected formulations, while telehealth delivery is expanding fastest as state Medicaid programs reimburse remote behavioral health consultations. Therapies retain stable demand in rehabilitation centers where bundled payment models incentivize intensive outpatient programs.
FDA oversight of psychopharmacological agents for pediatric populations shapes clinical trial design and label expansion pathways for intellectual disability indications, while CMS reimbursement policies determine site-of-care economics across hospital outpatient departments and community mental health centers. State-level Medicaid agencies administer home and community-based services waivers that directly fund supported employment and residential support services. Stakeholders must track evolving FDA guidance on biomarker qualification for neurodevelopmental drug development and anticipate CMS innovation center demonstrations that could restructure payment for coordinated specialty care.
Market Dynamics
Medicaid reimbursement restructuring is compressing site-of-care economics for behavioral health services, forcing providers to consolidate outpatient capacity and renegotiate pharmaceutical formulary contracts with health systems.
Growth Catalysts
- Home and Community-Based Services Waivers:State Medicaid agencies in the United States are expanding HCBS waiver enrollment caps, directly funding supported employment programs and residential behavioral support services for adults with intellectual disability.
- FDA Accelerated Approval Pathways:The agency's orphan drug incentives for rare neurodevelopmental conditions compress Phase II-to-launch timelines, attracting venture investment into targeted molecular therapies.
- Telehealth Infrastructure:State Medicaid programs now reimburse remote behavioral health consultations at parity with in-person visits, extending specialist access to rural counties and frontier health service areas.
Market Restraints
- Specialist Workforce Concentration:Board-certified developmental-behavioral pediatricians cluster in academic medical centers within 12 metropolitan statistical areas, creating access deserts across the Mountain West and Deep South.
- Formulary Standardization Pressure:Health system pharmacy benefit managers are narrowing psychotropic medication lists to three preferred agents per therapeutic class, constraining physician prescribing autonomy.
- Prior Authorization Burden:State Medicaid managed care organizations impose multi-step approval processes for atypical antipsychotics and long-acting injectable formulations, delaying therapy initiation by 14-21 days.
Strategic Opportunities
- Integrated Care Demonstrations:CMS Innovation Center models testing capitated payments for coordinated specialty care create margin pools for providers who bundle medical, behavioral, and social services.
- Biomarker-Qualified Endpoints:FDA guidance on cognitive endpoint validation for neurodevelopmental drug development opens regulatory pathways for disease-modifying therapies previously rejected for surrogate endpoint inadequacy.
- Peer Support Workforce Expansion:Certified peer specialist credentialing programs in 34 states enable Medicaid billing for family navigation and self-advocacy training services delivered by individuals with lived experience.
Industry Challenges
- Applied Behavior Analysis Technician Pipeline:Registered Behavior Technician certification requires 40 hours of supervised fieldwork, but training program capacity constraints create 6-9 month hiring delays for clinic operators.
- Electronic Health Record Interoperability:School district Individualized Education Plan systems lack HL7 FHIR connectivity with clinical practice management platforms, fragmenting care coordination across educational and medical settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mental Retardation Treatment Market |
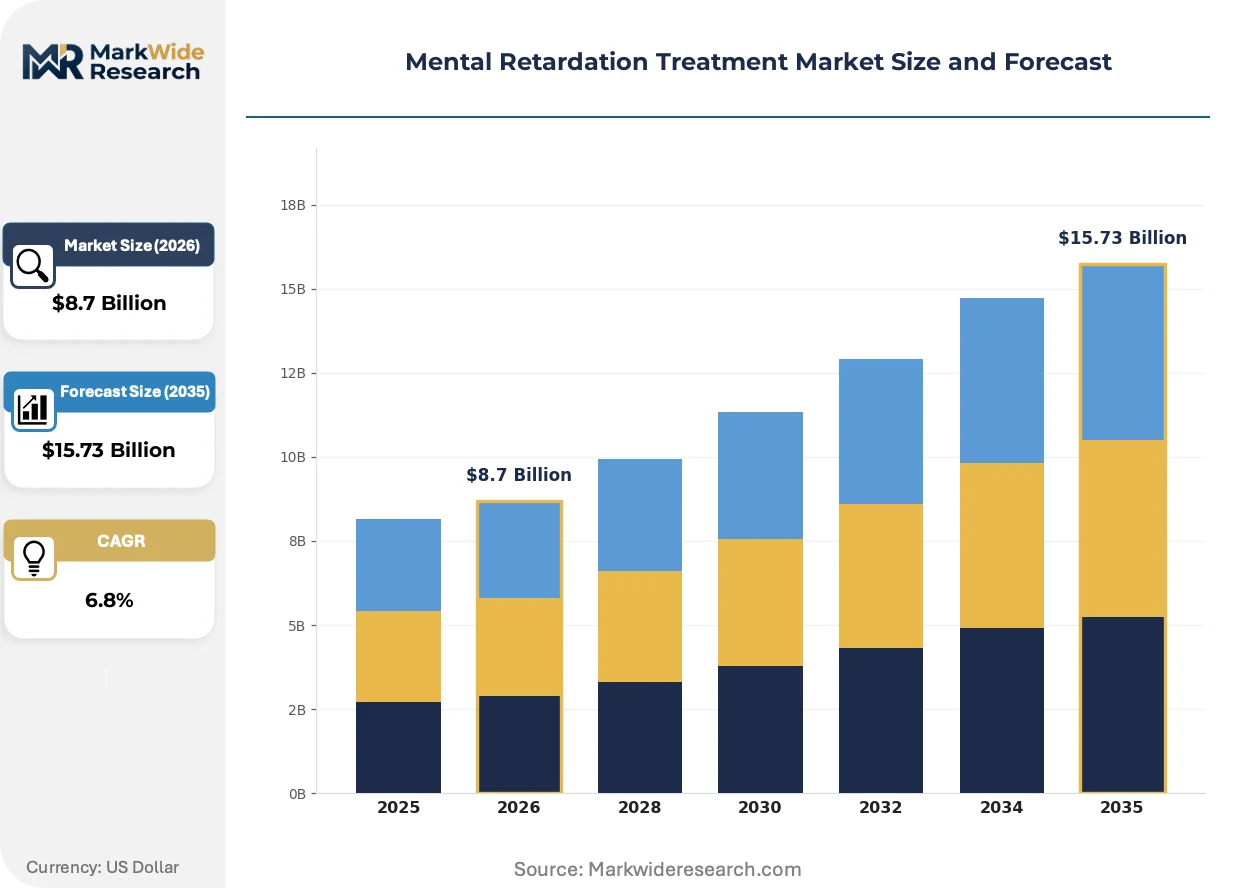
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Therapies, Support Services, Educational Programs End User: Hospitals, Outpatient Facilities, Home Care, Rehabilitation Centers Delivery Mode: In-person, Telehealth, Group Sessions, Individual Counseling Age Group: Children, Adolescents, Adults, Seniors |
| Companies Covered | Pfizer Inc, Eli Lilly and Company, AstraZeneca, Bristol Myers Squibb, Teva Pharmaceutical Industries Ltd, Biogen Inc, Johnson & Johnson, Novartis AG, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mental Retardation Treatment Market Shifts & Advancements
Digital phenotype capture and remote therapeutic monitoring are reconfiguring how clinicians track behavioral intervention efficacy, shifting measurement from episodic office visits to continuous ambulatory data streams.
Applied behavior analysis platforms incorporating artificial intelligence-driven data collection is converging with cloud-based parent coaching interfaces, enabling community mental health centers in Texas and Florida to extend therapist reach across multiple counties without proportional staff expansion.
FDA draft guidance on patient-focused drug development for neurodevelopmental disorders now mandates direct input from individuals with intellectual disability and their caregivers in clinical trial endpoint selection, compelling sponsors to redesign study protocols and consent processes before Phase II initiation.
Family caregivers are increasingly directing service selection through self-directed Medicaid waivers, bypassing traditional case management intermediaries in Ohio and Wisconsin to contract directly with independent support professionals and micro-provider networks.
Mental Retardation Treatment Market Segmentation
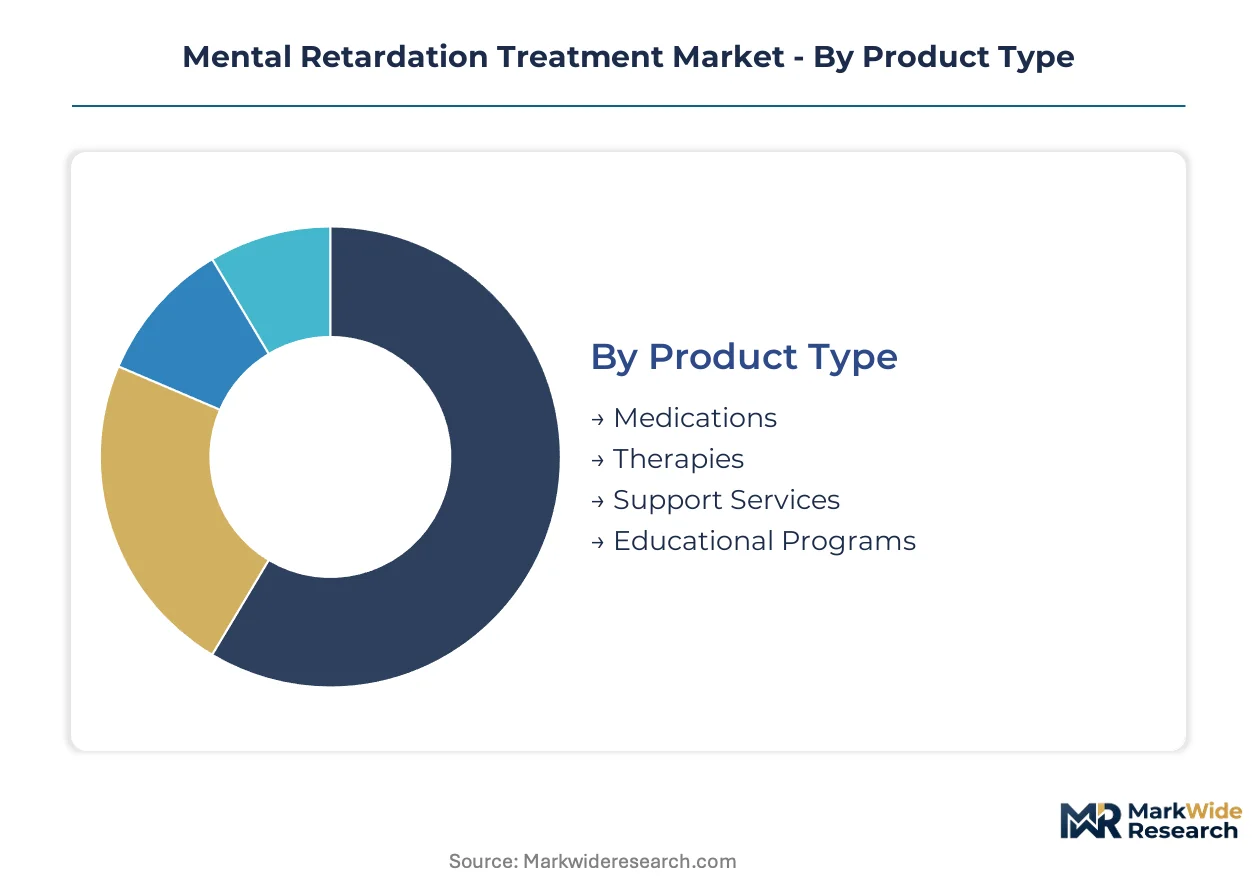
Treatment modality selection in intellectual disability care follows reimbursement pathways and site-of-care economics. Segment boundaries blur as integrated care models bundle pharmacological, behavioral, and social interventions under single episode payments.
Product Type:
Replacement cycles for neurodevelopmental therapies compress as FDA accelerated approvals bring novel molecular agents to market faster than behavioral protocol revisions.
- Medications:Psychostimulants, atypical antipsychotics, and mood stabilizers form the chronic prescribing backbone for co-occurring behavioral symptoms. Medicaid formularies in Texas and Florida drive volume concentration for long-acting injectable formulations that reduce adherence gaps in community settings.
- Therapies:Applied behavior analysis protocols require intensive technician supervision and discrete trial training methodologies. Demand clusters in metropolitan statistical areas where commercial insurance and Medicaid waivers overlap to fund 20-40 hour weekly treatment schedules.
- Support Services:Residential behavioral support and supported employment programs funded through HCBS waivers.
- Educational Programs:Individualized education plan coordination bridging school district and clinical systems.
Medications sit at the top of the volume ranking, with Therapies climbing the fastest as states expand autism mandate coverage.
End User:
Cost tier differentiation separates academic medical center command of complex polypharmacy from community-based efficiency in standardized behavioral protocols.
- Hospitals:Inpatient psychiatric units and specialized neurodevelopmental disorder clinics manage acute behavioral crises and medication optimization for refractory cases. Concentration in urban tertiary centers reflects Medicaid disproportionate share hospital payments that offset uncompensated care burdens.
- Outpatient Facilities:Community mental health centers deliver bundled psychiatric and psychological services under state plan authority. Volume expansion follows telehealth parity laws that extend rural reach without proportional facility investment.
- Home Care:Family-directed waiver services and in-home behavioral technician visits.
- Rehabilitation Centers:Post-acute residential programs and vocational training facilities.
Outpatient Facilities command the largest addressable population, while Home Care gains share fastest through self-directed waiver expansion.
Delivery Mode:
Customer type segmentation distinguishes institutional purchasers seeking scalable workforce training from family caregivers demanding flexible scheduling.
- In-person:Direct therapist-client interaction remains the gold standard for applied behavior analysis and developmental-behavioral pediatric assessment. Geographic concentration follows specialist workforce distribution with severe access deserts across the Mountain West.
- Telehealth:Synchronous video consultation and asynchronous parent coaching platforms extend specialist reach to frontier counties. State Medicaid programs in Ohio and Wisconsin now reimburse remote behavioral health at parity, accelerating infrastructure deployment.
- Group Sessions:Social skills training and parent support networks delivered in community settings.
- Individual Counseling:One-on-one psychotherapy and family navigation services.
In-person retains the highest session volume, though Telehealth shows the steepest expansion trajectory as licensure compacts expand.
Age Group:
Maturity curves diverge sharply with pediatric mandates driving coverage expansion while adult services face persistent Medicaid waiver waiting lists.
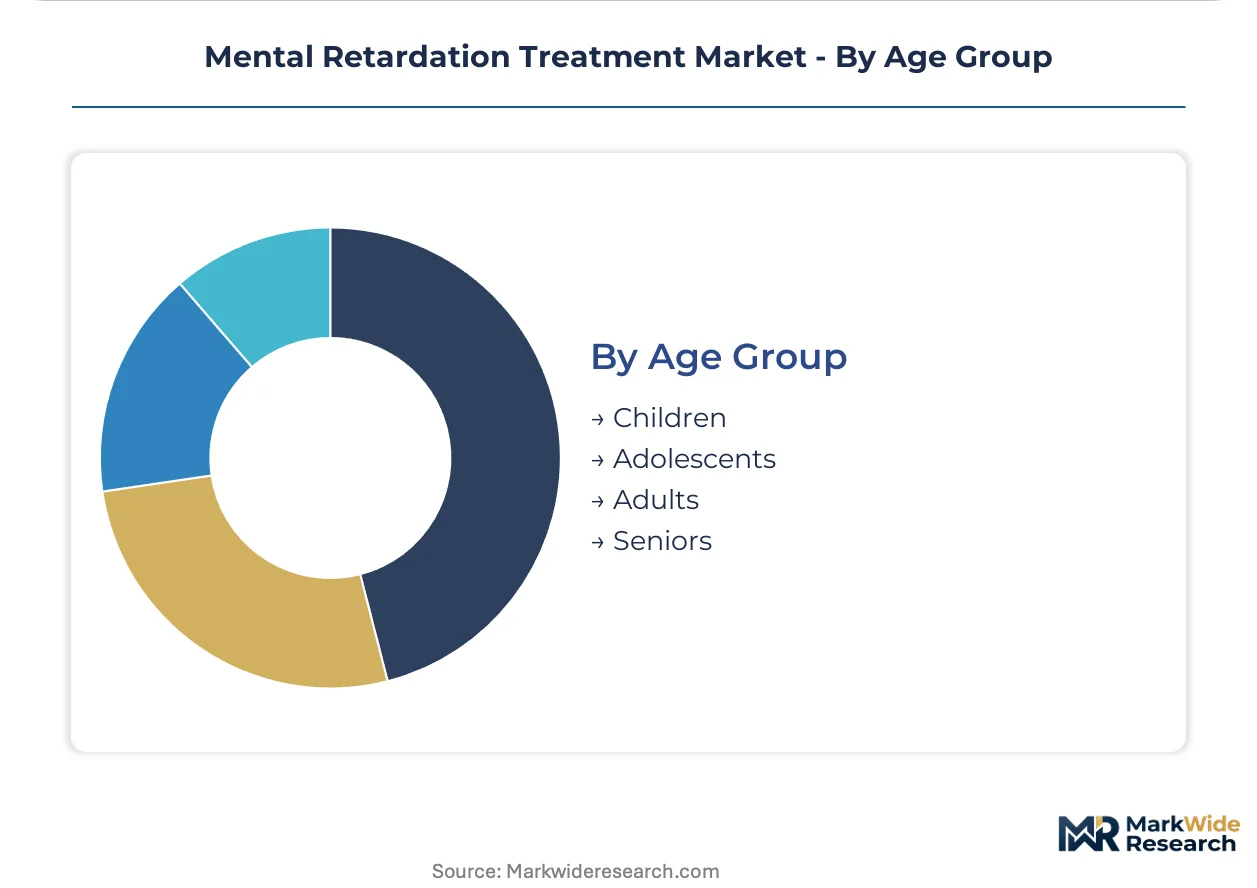
- Children:Early intervention services and school-age applied behavior analysis dominate commercial insurance and Medicaid spending. State autism mandate laws in 37 jurisdictions guarantee coverage for behavioral therapies up to age 18.
- Adolescents:Transition-age youth require coordinated handoffs from educational entitlements to adult service systems. Fragmentation between IDEA-mandated school services and fragmented adult Medicaid programs creates coverage gaps.
- Adults:Supported employment and community living services funded through 1915(c) waivers.
- Seniors:Aging caregivers and dual-diagnosis dementia-intellectual disability populations.
Children anchor current service volume, with Adults expanding most quickly as states rebalance institutional toward community-based spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Baltimore-Washington corridor anchors specialist service concentration for neurodevelopmental care, with academic medical centers driving protocol standardization and Medicaid policy diffusion across state lines.
United States
State Medicaid agencies administer HCBS waivers funding supported employment and residential behavioral support for adults with intellectual disability. FDA accelerated approval pathways for orphan neurodevelopmental drugs compress commercialization timelines from Phase II to launch. Pediatric neurology clusters in Boston, Philadelphia, and Baltimore concentrate board-certified developmental-behavioral specialists serving the Northeast corridor.
Germany
Statutory health insurance funds reimburse multimodal rehabilitation programs combining pharmacological and behavioral interventions for intellectual disability. The Federal Joint Committee (G-BA) evaluates new psychotropic therapies for inclusion in the national formulary through early benefit assessments. University hospitals in Munich and Heidelberg coordinate European reference networks for rare neurodevelopmental conditions.
United Kingdom
NHS England's Learning Disability Improvement Programme directs specialized commissioning for behavioral health services across integrated care systems. NICE guidelines on challenging behavior management in intellectual disability shape prescribing patterns for antipsychotics and mood stabilizers. The Maudsley Biomedical Research Centre in London anchors clinical trial infrastructure for novel molecular therapies.
Japan
PMDA orphan drug designation for neurodevelopmental disorders provides tax incentives and priority review for therapies addressing unmet needs in intellectual disability. Ministry of Health, Labour and Welfare reimbursement policies favor long-acting injectable formulations reducing hospitalization frequency. University hospitals in Tokyo and Osaka maintain the highest concentration of certified developmental disability specialists nationally.
India
CDSCO regulatory pathways for psychopharmacological agents in pediatric populations require distinct clinical trial designs addressing cognitive endpoint validation. National Trust programs under the Ministry of Social Justice and Empowerment fund community-based rehabilitation and vocational training for persons with intellectual disability. All India Institute of Medical Sciences in Delhi and NIMHANS in Bangalore anchor specialist training and research capacity.
Mental Retardation Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biomarker-qualified endpoints and gene therapy platforms for rare neurodevelopmental conditions. The market structure consolidates around diversified pharmaceutical conglomerates with CNS portfolios, mid-cap neurology specialists, and emerging biotechs targeting specific genetic etiologies of intellectual disability. Three archetypes dominate: legacy psychiatry franchises leveraging institutional contracts, neurology-focused developers pursuing disease-modification claims, and rare disease specialists exploiting FDA orphan incentives. Competitive moves center on portfolio diversification into long-acting injectable formulations and strategic partnerships with applied behavior analysis platform providers.
Among diversified pharmaceutical conglomerates, Pfizer Inc and Eli Lilly and Company exemplify the psychiatry franchise archetype, occupying positions sustained through institutional contracting relationships with academic medical centers and health system formularies. AstraZeneca represents the differentiated delivery platform approach, with its long-acting injectable expertise applicable to co-occurring behavioral conditions in intellectual disability populations. These three companies anchor the competitive landscape through distinct strategic vectors: formulary penetration, commercial infrastructure depth, and formulation innovation respectively.
| Leading Market Players |
|---|
| Pfizer Inc |
| Eli Lilly and Company |
| AstraZeneca |
| Bristol Myers Squibb |
| Teva Pharmaceutical Industries Ltd |
| Biogen Inc |
| Johnson & Johnson |
| Novartis AG |
| GlaxoSmithKline plc |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up applied behavior analysis clinic chains in Texas and Florida now control substantial Medicaid waiver service capacity, translating payer rate compression into disciplined formulary negotiations with pharmaceutical manufacturers while squeezing technician labor costs through centralized scheduling platforms.
Pricing Analysis
Input-cost pass-through from registered behavior technician wage inflation and long-acting injectable API sourcing is reshaping margin structures across outpatient behavioral health. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center polypharmacy management from community clinic standardized protocols and telehealth-only consultation services. Price differentiation rests on FDA label breadth and Medicaid preferred drug list status, with originator antipsychotics commanding premium positioning against authorized generics. Cost compression in the economy telehealth tier is intensifying because state Medicaid programs are narrowing reimbursement differentials between synchronous video and in-person visits. Family caregivers accessing self-directed waivers exhibit highest price sensitivity, while hospital outpatient departments remain least sensitive due to disproportionate share hospital payment offsets.
Supply Chain Analysis
Freight cost volatility for temperature-controlled distribution of long-acting injectable formulations is forcing inventory positioning closer to end-use sites in community mental health centers. Manufacturing concentration for atypical antipsychotic APIs centers on India, China, and the United States, with finished dose formulation clustering in Ireland, Puerto Rico, and North Carolina. Raw material dependencies span naphtha-derived intermediates, specialized polymer excipients for depot formulations, and cold-chain packaging materials. Single-source vulnerability for certain long-acting injectable devices creates exposure to supplier production disruptions. Distribution runs through specialty pharmacy networks and 340B-covered entities rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
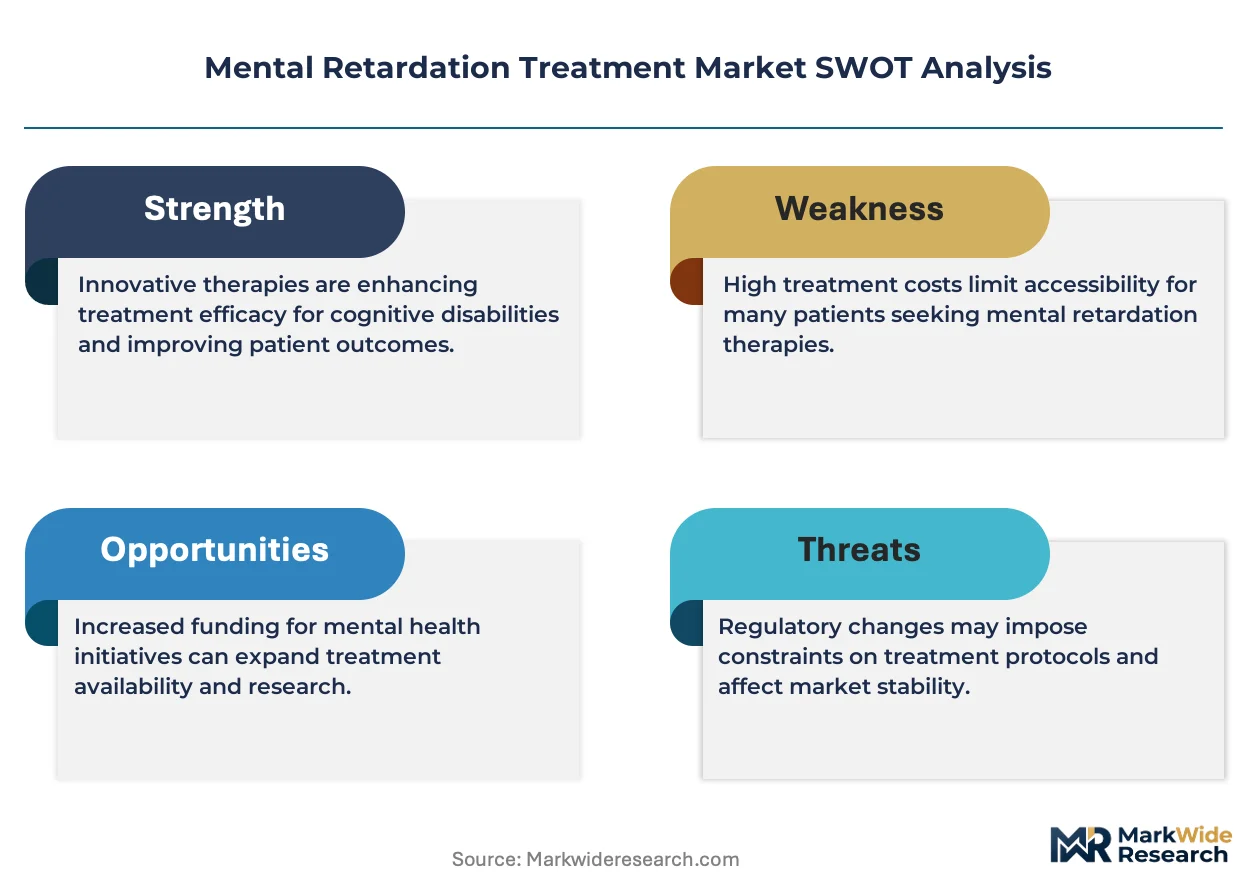
The Mental Retardation Treatment Market functions as a stable compounder anchored by Medicaid entitlement spending that resists cyclical downturns and sustains recurring revenue pools for established service providers.
For Market Incumbents: Anticipate formulary standardization pressure from health system pharmacy benefit managers by deepening long-acting injectable portfolios and securing institutional contracts with academic medical centers. Defensive consolidation moves should prioritize acquiring applied behavior analysis platform providers with established Medicaid waiver billing infrastructure. Vertical integration into registered behavior technician training programs addresses workforce pipeline constraints while creating captive labor supply for clinic expansion.
For New Entrants and Emerging Players: The mid-market price gap between premium academic medical center services and economy telehealth offerings creates white-space opportunity for hybrid models combining remote psychiatric consultation with in-home behavioral technician deployment. Target rural counties in Ohio and Wisconsin where self-directed Medicaid waiver expansion outpaces specialist workforce supply. Pursue peer support specialist credentialing programs as a go-to-market angle enabling Medicaid-reimbursable family navigation services without doctoral-level clinical overhead.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap applied behavior analysis platform providers with underoptimized Medicaid billing infrastructure and limited geographic footprint. Long-term viability framing centers on HCBS waiver enrollment growth trajectory and state-level rebalancing from institutional toward community-based spending. Acquisition target archetype: regional clinic chains with established payer contracts and untapped capacity for telehealth service line expansion. The signal to watch is CMS Innovation Center demonstration model expansion for capitated coordinated specialty care payments.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Qualified Endpoint Development | FDA guidance on cognitive validation opens disease-modification pathways previously blocked by surrogate endpoint inadequacy. |
| HCBS Waiver Contracting Expansion | State Medicaid agency direct relationships secure preferred provider status for supported employment and residential services. |
| Telehealth Infrastructure Deployment | Ohio and Wisconsin parity laws enable rural specialist reach without proportional facility capital investment. |
| Long-Acting Injectable Formulation Investment | Medicaid formulary preference for adherence-optimized delivery reduces hospitalization frequency and total cost of care. |
| Peer Support Workforce Credentialing | Thirty-four state certification programs unlock Medicaid billing for family navigation delivered by individuals with lived experience. |
Research Methodology
Multiple input streams — primary interviews with developmental-behavioral pediatricians, Medicaid formulary directors, and applied behavior analysis clinic operators; secondary validation through FDA orphan drug designations, state HCBS waiver enrollment data, and CMS Innovation Center demonstration announcements; and proprietary service utilization databases — were reconciled through bottom-up and top-down triangulation. Stakeholder interviews captured prescribing patterns, reimbursement pathway economics, and workforce capacity constraints. Secondary sources included ClinicalTrials.gov neurodevelopmental disorder listings, state Medicaid managed care organization formulary documents, and peer-reviewed health services research on intellectual disability care models.
Data-stream reconciliation across the projection horizon applied segment-specific growth assumptions to treatment modality, end-user site-of-care, delivery mode, and age group dimensions. CAGRs were derived from Medicaid spending trajectory analysis, FDA approval pipeline assessment, and telehealth reimbursement policy diffusion modeling. Forecast inputs incorporated state autism mandate law adoption patterns, registered behavior technician training program capacity expansion, and biomarker-qualified endpoint regulatory pathway probability.
The model assumes a particular technology adoption path; alternative pathways for AI-driven applied behavior analysis data collection platforms would alter the outlook if FDA software-as-medical-device oversight expands unexpectedly. Forecasts reflect assumptions regarding Medicaid waiver enrollment caps, specialist workforce geographic distribution, and telehealth parity law durability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Psychedelic Medicine Market
Specialty Medicine
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Grand Mal Seizure Market
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market
Specialty Medicine
Global Myeloproliferative Disorders (MPD) Treatment Market
Specialty Medicine
Global Targeted Cancer Therapy Market
Specialty Medicine
Global Chondrosarcoma Market
Specialty Medicine
Global Bile Duct Cancer Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Splenomegaly Therapeutics Market
Specialty Medicine
Infantile Spasms Therapeutics Market
Specialty Medicine
Chronic Obstructive Pulmonary Disease Therapeutics Market
Specialty Medicine
Hemangioma Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
Global Gastrointestinal Therapeutics Market
Specialty Medicine
Global Anal Fistula Treatment Market