
 Persistent Epithelial Defect Management Market | 2026-2036
Persistent Epithelial Defect Management Market Size, Share, and Industry Trends Forecast 2026-2036
Persistent Epithelial Defect Management Market Analytics
The EU Medical Device Regulation (MDR) is realigning market access requirements for advanced ocular biologics across European markets. Dompe Farmaceutici leverages its specialized manufacturing infrastructure to sustain leadership in recombinant growth factor therapies. Novartis AG anchors its position through extensive ophthalmology R&D networks, while RegeneRx Biopharmaceuticals differentiates via peptide-based regenerative platforms.
Persistent epithelial defect management encompasses therapeutic interventions that restore corneal epithelial integrity following trauma, surgery, or neurotrophic conditions, typically employing biologic matrices, autologous derivatives, or synthetic hydrogels with defined water content and oxygen permeability specifications. These interventions serve to prevent stromal melting, reduce infection risk, and preserve visual acuity in compromised ocular surfaces. Amniotic membrane products command premium positioning due to their anti-inflammatory cytokine profile and scaffold properties, while hydrogel dressings occupy the high-volume segment through accessible pricing and ease of application in outpatient settings. Therapeutic contact lenses are gaining traction as combination delivery vehicles that integrate mechanical protection with sustained drug release.
The U.S. FDA's Center for Biologics Evaluation and Research oversees advanced therapy medicinal product classifications that determine clinical trial requirements and approval pathways for novel epithelial repair agents. The European Medicines Agency's Committee for Advanced Therapies evaluates cell-based and tissue-engineered products under centralized procedures that influence commercialization timelines. Stakeholders must monitor evolving reimbursement coding for amniotic membrane applications and prepare for heightened pharmacovigilance obligations as real-world evidence requirements expand across major health authorities.
Market Dynamics
Regenerative biologics are displacing synthetic alternatives as hospital ophthalmology departments prioritize epithelial restoration speed and stromal preservation outcomes.
Growth Catalysts
- Advanced Therapy Medicinal Products framework:The EMA's centralized evaluation pathway accelerates commercialization timelines for cell-based corneal repair agents across EU member states.
- Neurotrophic keratopathy prevalence:Diabetes and herpetic eye disease expansion in aging populations generates sustained demand for biologic wound healing interventions.
- Amniotic membrane processing:Cryopreservation and lyophilization advances extend shelf stability and reduce cold-chain dependency for ambulatory surgical centers.
Market Restraints
- Donor tissue supply concentration:Placental tissue sourcing depends on a limited network of qualified tissue banks concentrated in the United States.
- Reimbursement coding fragmentation:CMS and private payers maintain inconsistent coverage determinations for amniotic membrane applications in outpatient settings.
- Autologous serum competition:Patient-derived therapies offer lower material costs for chronic defect cases, pressuring commercial biologic pricing.
Strategic Opportunities
- Synthetic hydrogel-peptide convergence:Engineered matrices combining recombinant growth factors with tunable mechanical properties address donor tissue scarcity.
- ASC procedure migration:Office-based surgical suites create direct-to-physician distribution channels bypassing hospital procurement committees.
- Japan's regenerative medicine framework:PMDA's conditional approval pathway for tissue-engineered products opens accelerated market entry for novel epithelial repair platforms.
Industry Challenges
- Corneal specialist training gaps:Advanced biologic application techniques require hands-on proficiency that residency programs inadequately address.
- Pharmacovigilance data infrastructure:Long-term safety tracking for novel regenerative agents demands investment in post-market surveillance systems.
- Legacy suture-based technique persistence:Established surgeons resist adopting amniotic membrane insertion devices despite reduced operative time.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Persistent Epithelial Defect Management Market |
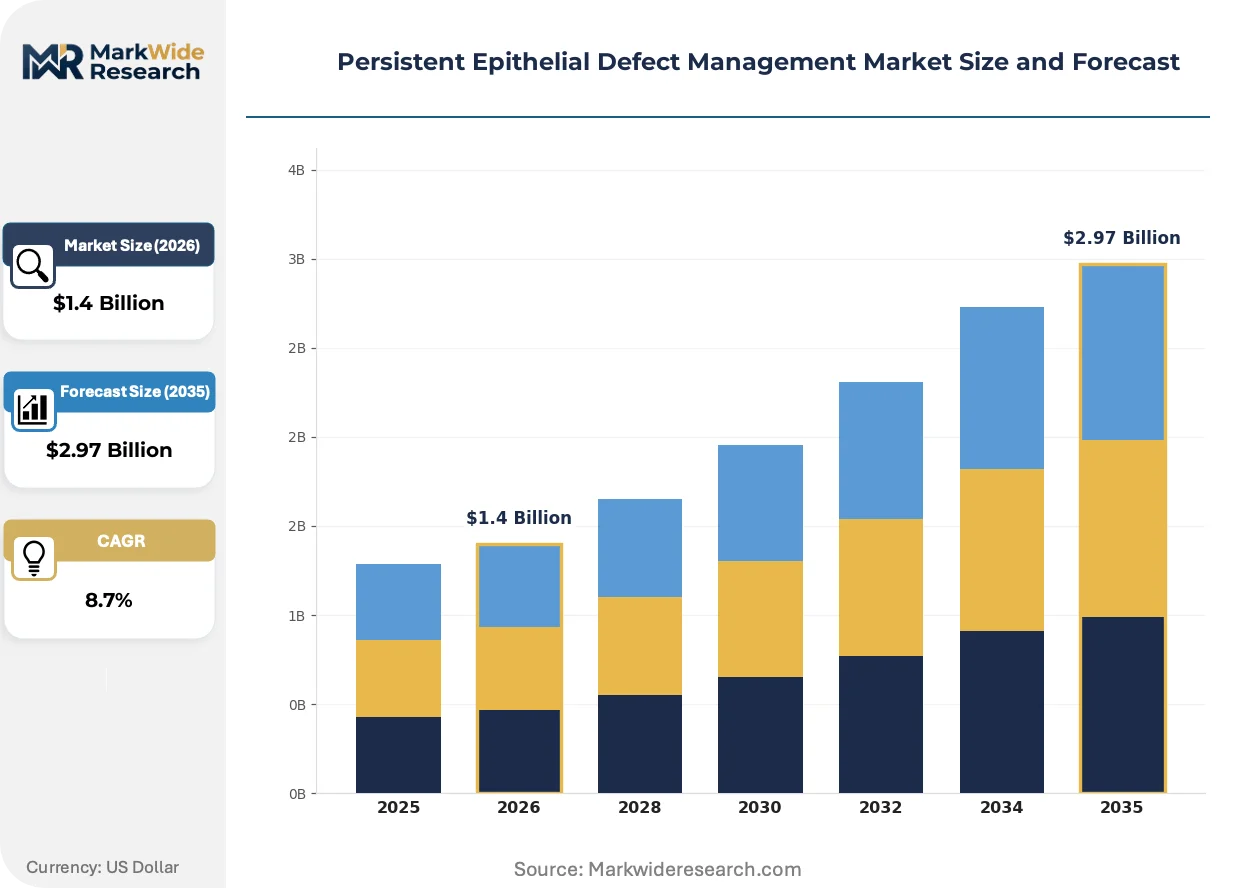
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogel Dressings, Autologous Serum, Amniotic Membrane, Therapeutic Contact Lenses Delivery Mode: Topical, Intraocular, Systemic, Localized End User: Ophthalmology Clinics, Hospitals, Optical Centers, Research Institutes Application: Corneal Repair, Wound Healing, Pain Management, Infection Control |
| Companies Covered | Dompe Farmaceutici, OcuNexus Therapeutics, Eyevance Pharmaceuticals, Johnson & Johnson Services Inc., Novartis AG, Bausch Health Companies Inc., RegeneRx Biopharmaceuticals, Noveome Biotherapeutics, Integra Lifesciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Persistent Epithelial Defect Management Market Evolving Landscape
Biomaterial engineering and point-of-care manufacturing are collapsing the gap between therapeutic production and clinical deployment in corneal care.
Recombinant human nerve growth factor formulations are absorbing market share from conventional lubricant therapies in neurotrophic defect management. Tertiary referral centers in Germany and the United States are adopting these agents for severe cases previously managed with tarsorrhaphy. The technology is absorbing high-complexity surgical volume while compressing dependency on invasive mechanical interventions.
MDR Article 117 requirements for clinical evidence on legacy amniotic membrane products are forcing retrospective data collection and post-authorization studies across European markets. Manufacturers must now demonstrate equivalence to predicate devices or pursue new conformity assessments. Smaller tissue processors in Italy and Spain face disproportionate compliance burdens relative to integrated multinationals.
Hospital procurement committees are consolidating vendor contracts for advanced wound care biologics under value-based frameworks that weight healing rates above unit cost. Integrated delivery networks in Texas and Florida are replacing fragmented specialty pharmacy arrangements with single-source agreements. This concentration is most visible in academic medical centers where ophthalmology departments negotiate system-wide access to regenerative platforms.
Persistent Epithelial Defect Management Market Segmentation
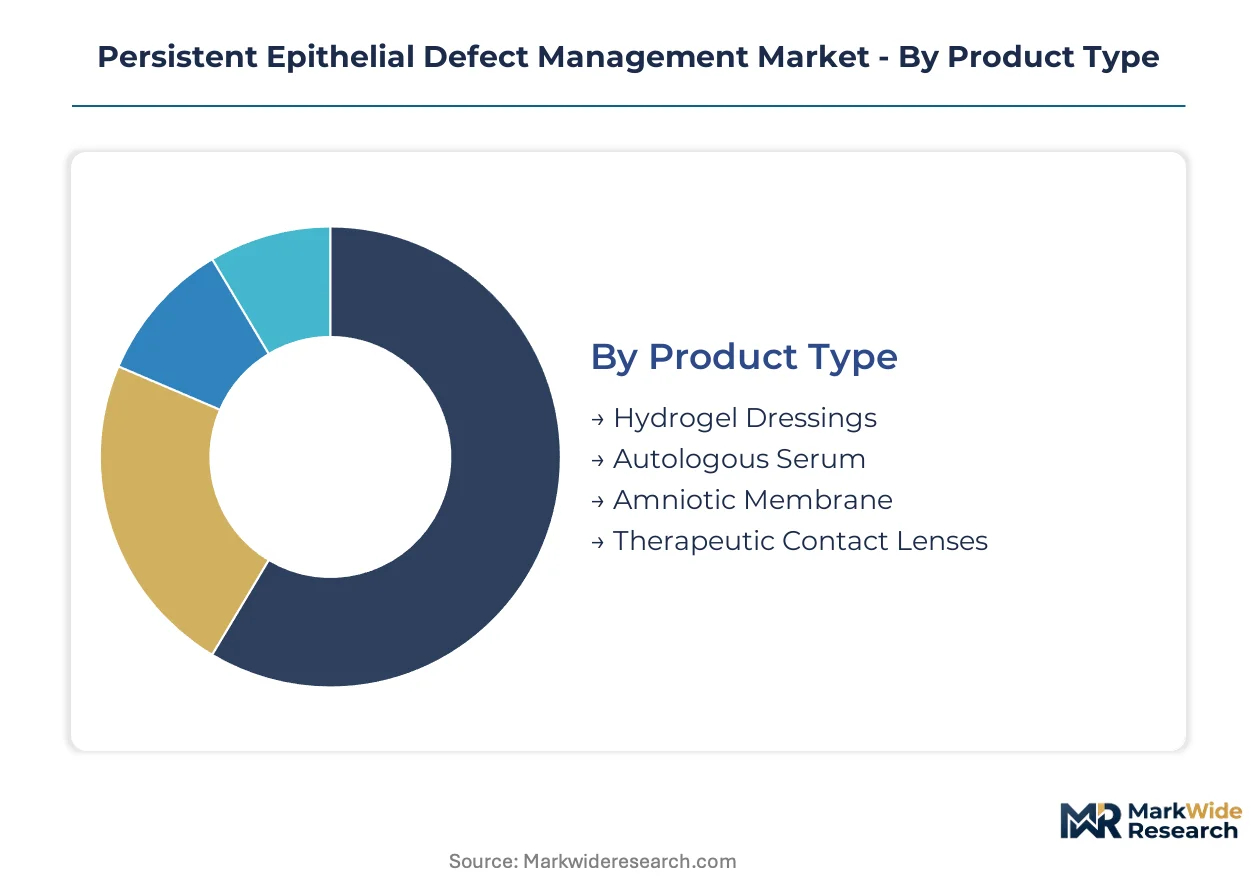
Treatment selection in persistent epithelial defect management hinges on defect severity, etiology, and reimbursement accessibility. Segmentation reveals how clinical decision pathways allocate spending across biologic, synthetic, and autologous alternatives.
Product Type:
Procurement committees weight healing velocity against material cost and storage requirements when selecting among available modalities.
- Amniotic Membrane:Cryopreserved or lyophilized placental tissue delivering anti-inflammatory cytokines and scaffold architecture for severe neurotrophic defects. Academic medical centers in the United States prioritize this modality for stromal preservation outcomes despite premium pricing and cold-chain logistics.
- Hydrogel Dressings:Synthetic matrices with tunable water content and oxygen permeability specifications for outpatient mechanical protection. Ambulatory surgical centers favor these for accessible unit economics and simplified inventory management in high-volume settings.
- Autologous Serum:Patient-derived tear film substitute prepared from centrifuged blood components. Compounding pharmacies and corneal specialists employ this for chronic defect cases where commercial biologic costs prove prohibitive.
- Therapeutic Contact Lenses:Combination delivery vehicles integrating mechanical protection with sustained drug release capabilities. Tertiary referral centers adopt these for moderate defects requiring extended wear protocols.
Volume sits with hydrogel dressings; growth tilts toward amniotic membrane applications.
Delivery Mode:
Route selection determines regulatory pathway complexity and reimbursement coding eligibility across institutional settings.
- Topical:Direct application of drops, gels, or membranes to the ocular surface. This route dominates outpatient practice due to non-invasive administration and favorable CMS coding for office-based procedures.
- Localized:Targeted depot or sustained-release formulations at the defect site. Hospital ophthalmology departments employ these for refractory cases requiring prolonged therapeutic concentration.
- Intraocular:Injection or implantation within the anterior chamber or vitreous. Specialized corneal surgery centers reserve this for complex postsurgical defects with concurrent intraocular pathology.
- Systemic:Oral or parenteral agents addressing underlying systemic etiologies. Endocrinology-ophthalmology collaboration drives use in diabetic neurotrophic keratopathy management.
Topical administration captures procedure volume; localized delivery is climbing the fastest as sustained-release platforms mature.
End User:
Site-of-care migration reshapes distribution economics and clinical training requirements for advanced biologic application.
- Hospitals:Integrated delivery networks with centralized procurement negotiating system-wide contracts for regenerative platforms. These institutions handle severe trauma and postsurgical complications requiring multidisciplinary coordination.
- Ophthalmology Clinics:Specialty practices with direct-to-physician distribution relationships and in-office surgical suites. Texas and Florida clusters lead adoption of point-of-care amniotic membrane processing.
- Optical Centers:Retail-affiliated settings focusing on therapeutic lens fitting and maintenance. These sites manage stable defects and post-healing visual rehabilitation.
- Research Institutes:Academic centers conducting investigator-initiated trials for novel epithelial repair agents. FDA and EMA real-world evidence programs concentrate patient recruitment at these facilities.
Hospitals anchor current spending; ophthalmology clinics are gaining share fastest through procedure migration to office-based settings.
Application:
Clinical indication determines product positioning against mechanical alternatives and surgical intervention thresholds.
- Corneal Repair:Restoration of epithelial integrity following trauma, surgery, or neurotrophic compromise. Biologic matrices with defined scaffold properties target this indication for stromal melting prevention.
- Wound Healing:Acceleration of re-epithelialization in persistent defects exceeding standard healing timelines. Recombinant growth factor therapies address this application in German and United States tertiary centers.
- Pain Management:Reduction of neuropathic discomfort associated with epithelial breakdown. Therapeutic lenses with integrated lubrication dominate this symptomatic indication.
- Infection Control:Barrier function restoration to prevent microbial colonization of compromised surfaces. Antimicrobial-impregnated hydrogels serve this prophylactic role in high-risk patients.
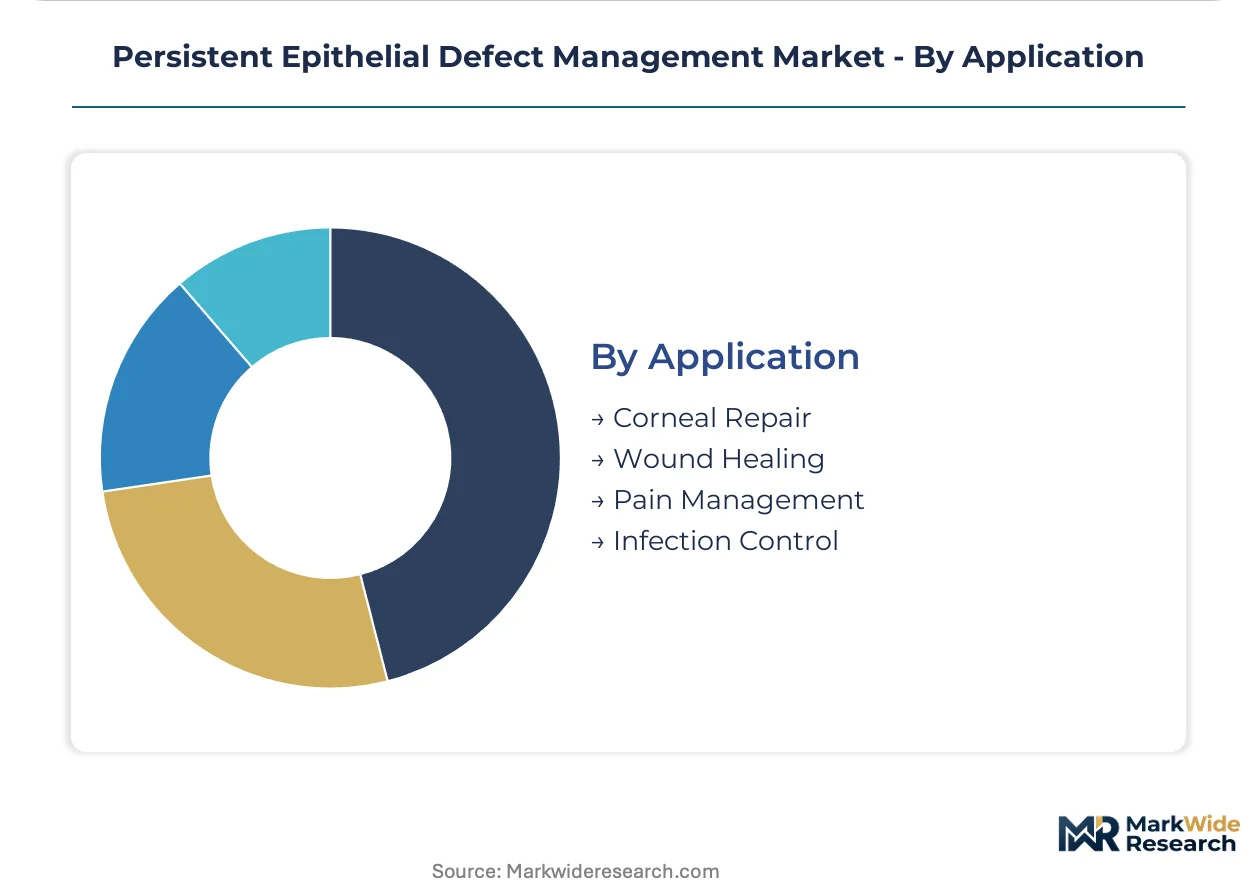
Corneal repair commands revenue concentration; wound healing shows steepest expansion trajectory as regenerative biologics displace conventional lubricants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's concentration of corneal surgery centers and academic medical institutions anchors United States demand for advanced epithelial repair modalities. Specialized referral networks in this cluster drive adoption of biologic matrices and regenerative platforms.
United States
Diabetes prevalence and herpetic eye disease expansion generate sustained procedural volume for neurotrophic keratopathy interventions. FDA's Center for Biologics Evaluation and Research oversees advanced therapy medicinal product classifications that shape clinical trial requirements. Texas and Florida ophthalmology clusters lead office-based procedure migration, creating direct-to-physician distribution channels for amniotic membrane applications.
Germany
Tertiary referral centers absorb high-complexity surgical volume previously managed with invasive mechanical interventions. EMA's Committee for Advanced Therapies evaluates cell-based products under centralized procedures influencing commercialization timelines. Bavaria's academic medical centers concentrate investigator-initiated trials for recombinant growth factor therapies.
Japan
Aging demographics and expanding diabetic populations drive demand for epithelial restoration biologics. PMDA's conditional approval pathway for tissue-engineered products enables accelerated market entry for novel repair platforms. Tokyo-Osaka metropolitan corridors host specialized corneal surgery centers adopting point-of-care manufacturing approaches.
United Kingdom
NHS procurement frameworks prioritize healing velocity outcomes in value-based contracting for advanced wound care biologics. MHRA alignment with EU MDR requirements maintains regulatory continuity for amniotic membrane product access. London-Southeast clusters concentrate private ophthalmology practices with direct distribution relationships to regenerative platform suppliers.
Switzerland
Concentration of specialized pharmaceutical manufacturing infrastructure supports recombinant growth factor production for export markets. Swissmedic oversight of advanced therapy medicinal products ensures alignment with EMA evaluation standards. Basel-Zurich corridor hosts integrated multinationals with ophthalmology R&D networks spanning European markets.
Persistent Epithelial Defect Management Market Competitive Landscape
The competitive structure tilts toward integrated pharmaceutical conglomerates with specialized ophthalmology divisions. Market concentration reflects high regulatory barriers and capital requirements for biologic manufacturing infrastructure. Three archetypes dominate: recombinant growth factor specialists, tissue-engineered product developers, and diversified eye care portfolios. Consolidation through strategic partnerships and technology licensing agreements reshapes access to ambulatory surgical center distribution channels.
Among European-based pharmaceutical developers, Dompe Farmaceutici and Novartis AG exemplify divergent strategic positioning within regenerative ophthalmology. Dompe Farmaceutici represents specialized manufacturing infrastructure focused on recombinant growth factor therapies. Novartis AG anchors diversified portfolio approaches leveraging extensive R&D networks across multiple therapeutic modalities. RegeneRx Biopharmaceuticals occupies a distinct position among peptide-based regenerative platform developers, illustrating how smaller entities differentiate through molecular engineering specialization rather than scale.
| Leading Market Players |
|---|
| Dompe Farmaceutici |
| OcuNexus Therapeutics |
| Eyevance Pharmaceuticals |
| Johnson & Johnson Services Inc. |
| Novartis AG |
| Bausch Health Companies Inc. |
| RegeneRx Biopharmaceuticals |
| Noveome Biotherapeutics |
| Integra Lifesciences |
| Others |
Value Network & Pricing Analysis
Cryopreservation and lyophilization advances in amniotic membrane processing simultaneously compress cold-chain logistics costs and consolidate manufacturing among United States-based tissue banks with qualified infrastructure. This technological transition concentrates supply-side power among integrated processors while enabling price premiums for shelf-stable formats in ambulatory surgical centers.
Pricing Analysis
Value-based contracting anchored to healing velocity outcomes dominates procurement negotiations for advanced wound care biologics. Three-tier pricing structure across premium, standard, and economy levels separates cryopreserved amniotic membranes from lyophilized alternatives and synthetic hydrogel dressings. Cost compression in the hydrogel segment is intensifying because autologous serum compounding offers lower material costs for chronic defect cases. Academic medical centers demonstrate least price sensitivity due to stromal preservation outcome priorities, while high-volume ambulatory surgical centers drive hardest unit economics negotiations.
Supply Chain Analysis
Domestic-content mandates for human tissue products under FDA tissue establishment registration rules reshape sourcing toward United States-qualified tissue banks with verified donor screening protocols. Placental tissue sourcing draws from a limited network concentrated in the United States, with cryopreservation media and specialized transport containers as critical input dependencies. Single-source vulnerability runs through the qualified donor tissue bank network, where regulatory compliance barriers limit rapid supplier substitution. Distribution runs through hospital procurement committees and direct-to-physician channels serving office-based surgical suites in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
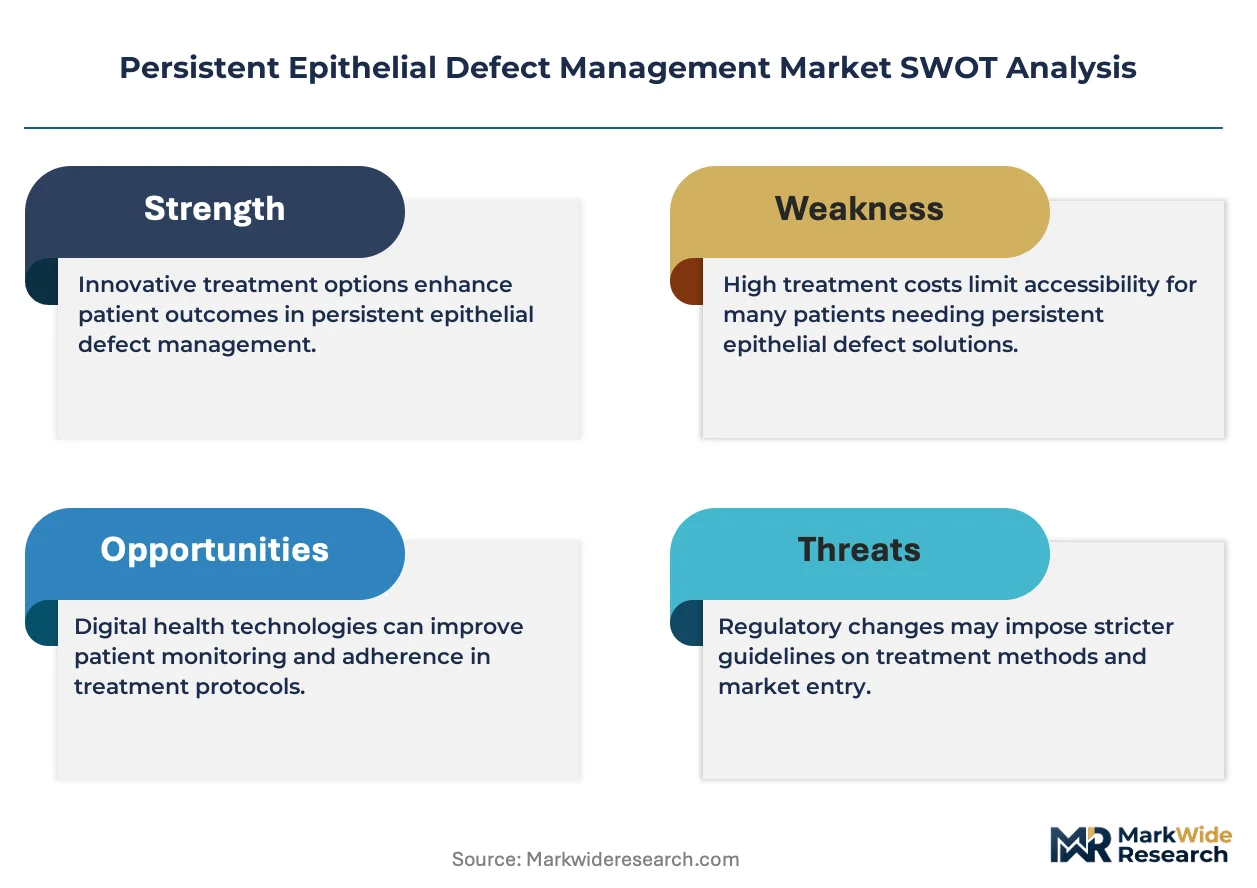
Donor tissue supply concentration props pricing power for qualified amniotic membrane processors, creating a supply-constrained market structure where capacity expansion lags demand growth from aging diabetic populations.
For Market Incumbents: To counter autologous serum competition in chronic defect management, Dompe Farmaceutici and integrated multinationals should deepen backward integration into placental tissue sourcing through exclusive tissue bank partnerships, while simultaneously investing in recombinant growth factor R&D to reduce dependency on donor-derived materials. For New Entrants and Emerging Players: Enter via synthetic hydrogel-peptide convergence platforms targeting donor tissue scarcity, with Japan's PMDA conditional approval pathway offering the most penetrable regulatory entry point for tissue-engineered products, leveraging point-of-care manufacturing approaches to bypass established cold-chain distribution networks. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified ophthalmology portfolios seeking regenerative platform capabilities, with long-term viability hinging on reimbursement coding consolidation for amniotic membrane applications. Watch for CMS national coverage determination signals as the critical inflection indicator for valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS coding alignment for amniotic membrane applications unlocks outpatient procedure volume expansion. |
| Manufacturing Scale-Up | Cryopreservation capacity additions at qualified tissue banks reduce cold-chain dependency for ambulatory surgical centers. |
| Regulatory Approval Pathway | PMDA conditional approval accelerates Japanese market entry for novel epithelial repair platforms. |
| Pipeline Diversification | Recombinant growth factor development reduces donor tissue supply risk for neurotrophic keratopathy indications. |
| Hospital System Partnership | Integrated delivery network contracts in Texas and Florida consolidate vendor relationships under value-based frameworks. |
Research Methodology
Multi-period observation of amniotic membrane application volumes, healing outcome metrics, and reimbursement coding changes anchored the trend analysis, supplemented by interviews with corneal surgeons, hospital procurement managers, tissue bank operations directors, and regulatory affairs specialists at EMA and FDA. Secondary validation drew from FDA 510(k) filings, EMA Committee for Advanced Therapies assessment reports, CMS national coverage determinations, and hospital GPO contract databases. Bottom-up procedure volume estimates triangulated against top-down pharmaceutical revenue disclosures.
Input-output matrices modeled segment-level demand across product type, delivery mode, end user, and application dimensions over the projection horizon. CAGRs derived from regression analysis against diabetes prevalence trajectories, herpetic eye disease incidence patterns, and office-based procedure migration rates. Forecast inputs incorporated EMA centralized procedure timelines, FDA regenerative medicine guidance evolution, and Japan's regenerative medicine framework adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under reimbursement coding fragmentation scenarios or donor tissue supply disruptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Bloch-Sulzberger Treatment Market
Medical Treatment
Cytokine Release Syndrome Management Market
Medical Treatment
Adenomyosis Treatment Market
Medical Treatment
Corneal Transplant Market
Medical Treatment
Global Leukapheresis Market
Medical Treatment
Meningococcal Meningitis Treatment Market
Medical Treatment
Birch Allergy Treatment Market
Medical Treatment
Cholera Treatment Market
Medical Treatment
Malaria Treatment Market
Medical Treatment
Dementia Treatment Market
Medical Treatment
Trauma and Extremities Market
Medical Treatment
North America Breast Reconstruction Market
Medical Treatment
Global Plasma Therapy Market
Medical Treatment
Congenital Hyperinsulinism Treatment Market
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
Achalasia Treatment Market