
 Eosinophilic Granulomatosis Market | 2026-2036
Eosinophilic Granulomatosis Market Size, Share, and Industry Trends Forecast 2026-2036
Eosinophilic Granulomatosis Market Analytics
Buyer concentration among hospital systems and specialty infusion centers is pivoting toward integrated care networks that control biologic purchasing decisions. Sanofi S.A. leverages its established immunology portfolio to anchor relationships with these consolidated buyers. GlaxoSmithKline plc competes through deep specialization in respiratory and eosinophilic conditions. Regeneron Pharmaceuticals, Inc. differentiates via its dupilumab franchise and co-development partnerships that extend reach into academic medical centers.
Eosinophilic granulomatosis denotes a systemic vasculitis characterized by asthma, eosinophilia, and extravascular granuloma formation, typically managed through corticosteroid induction followed by steroid-sparing maintenance with biologics targeting IL-5 or IL-4/IL-13 pathways. The condition demands precise eosinophil count monitoring and organ-specific staging to guide therapy intensity. Biologics and monoclonal antibodies now command the fastest expansion as steroid-sparing alternatives, while corticosteroids retain volume leadership in acute induction protocols. Injectable and intravenous delivery modes attract disproportionate investment as outpatient infusion centers scale capacity for biologic administration.
FDA orphan drug designations and EMA priority medicine schemes accelerate development timelines for eosinophilic granulomatosis therapies, compressing the gap between clinical proof and commercial access. Reimbursement authorities in Germany and Japan apply distinct health technology assessment criteria that favor quality-adjusted survival endpoints over surrogate markers. Stakeholders must monitor evolving payer evidence requirements for biologic switching protocols and real-world outcome registries.
Market Dynamics
Hospital-based allergy and immunology departments are consolidating biologic purchasing decisions within integrated care networks, concentrating procurement power among fewer buyers who demand outcome guarantees and bundled pricing for eosinophil-targeting therapies.
Growth Catalysts
- FDA Accelerated Approval:The FDA's orphan drug designation pathway compresses development timelines for rare disease biologics, enabling faster commercial access for IL-5 and IL-4/IL-13 inhibitors in eosinophilic granulomatosis.
- Biologic Infusion Center Expansion:Outpatient specialty infusion centers in the United States, Germany, and Japan are scaling capacity for injectable and intravenous biologic administration, creating dedicated infrastructure for chronic maintenance therapy.
- Steroid-Sparing Protocol Adoption:Corticosteroid induction followed by biologic maintenance is electrifying treatment algorithms, as pulmonologists and rheumatologists prioritize long-term organ protection over short-term symptom control.
Market Restraints
- Biologic Manufacturing Concentration:Monoclonal antibody production relies on concentrated mammalian cell culture capacity in Switzerland and Ireland, creating single-source vulnerability for fill-finish operations.
- Reimbursement Evidence Requirements:Germany's Federal Joint Committee (G-BA) and Japan's Central Social Insurance Medical Council apply distinct health technology assessment criteria that favor quality-adjusted survival endpoints over surrogate biomarker reductions.
- Corticosteroid Cost Anchor:Generic prednisone and methylprednisolone remain the economic comparator for induction therapy, compressing willingness-to-pay thresholds for novel biologics despite superior safety profiles.
Strategic Opportunities
- Real-World Evidence Registries:EMA's priority medicine scheme and FDA's Real-World Evidence program create regulatory tailwinds for post-approval data collection that supports label expansion and switching protocols.
- Subcutaneous Formulation Development:Self-administration devices for IL-5 inhibitors enable home-based maintenance, reducing infusion center dependency and capturing patients in rural or underserved regions.
- Eosinophil-Driven Comorbidity Expansion:Severe asthma and chronic rhinosinusitis with nasal polyps represent adjacent indications with overlapping pathology, allowing portfolio leverage across immunology franchises.
Industry Challenges
- Specialist Workforce Scarcity:Fellowship-trained vasculitis specialists remain concentrated at academic medical centers, limiting community-based diagnosis and appropriate referral for biologic initiation.
- Biomarker Standardization Gaps:Variability in eosinophil count measurement protocols across hospital laboratories creates staging inconsistency that complicates treatment intensity decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eosinophilic Granulomatosis Market |
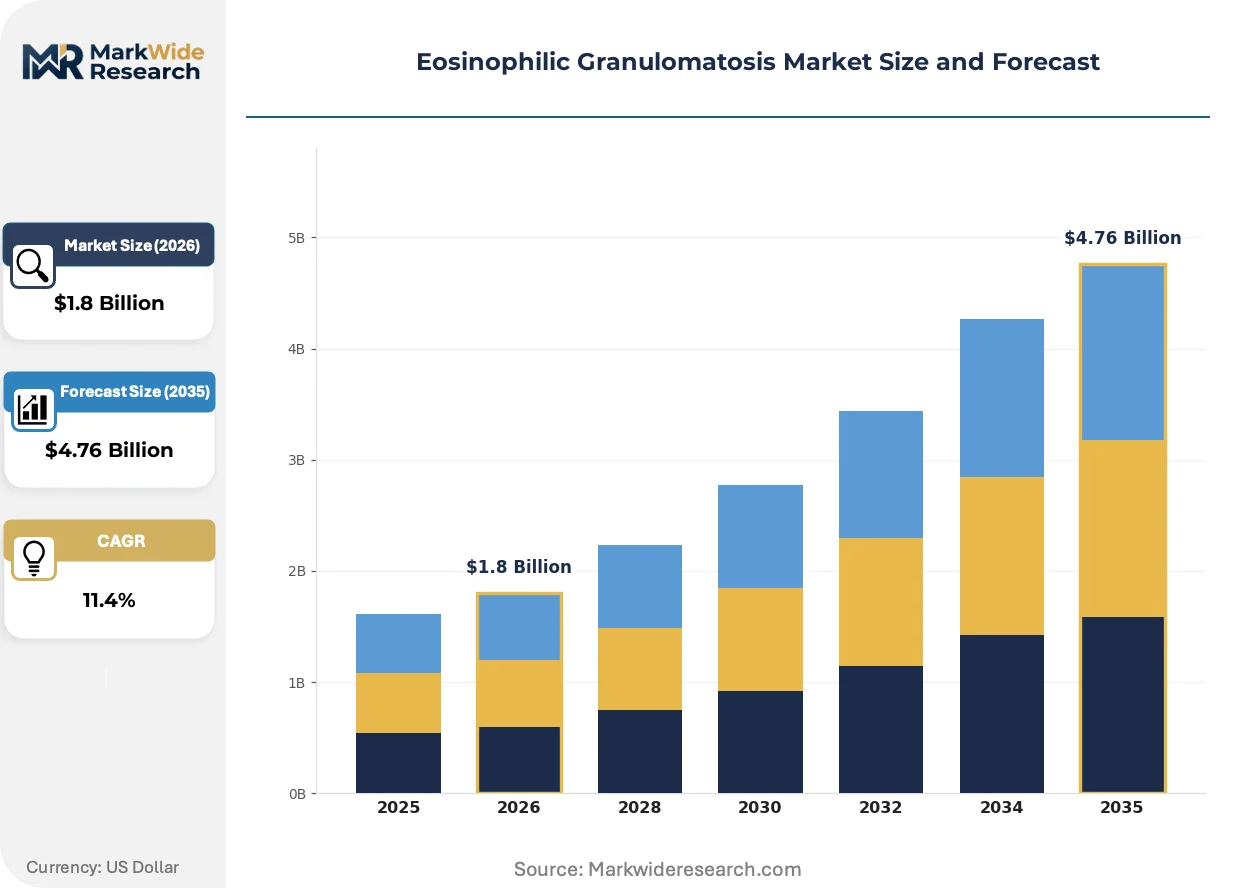
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunosuppressants, Biologics, Monoclonal Antibodies End User: Hospitals, Clinics, Home Care Settings, Specialty Centers Application: Chronic Disease Management, Allergy Treatment, Symptom Relief, Patient Support Delivery Mode: Oral, Injectable, Intravenous, Topical |
| Companies Covered | Sanofi S.A., F. Hoffmann-La Roche Ltd., GlaxoSmithKline plc, NS Pharma (Nippon Shinyaku), Novartis AG, AstraZeneca plc, Regeneron Pharmaceuticals, Inc., Boehringer Ingelheim International GmbH, Teva Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eosinophilic Granulomatosis Market Evolving Landscape
Precision immunology is electrifying therapeutic development in eosinophilic granulomatosis, with biomarker-driven patient stratification and targeted biologic delivery reshaping how specialists manage this complex vasculitis across outpatient and inpatient settings.
Next-generation IL-5 receptor antagonists and bispecific antibodies targeting IL-4/IL-13 pathways are electrifying the steroid-sparing maintenance landscape. Academic medical centers in the United States and Germany are adopting these agents earlier in disease course, displacing cyclophosphamide-based protocols. The technology is electrifying competitive positioning among manufacturers who can demonstrate superior eosinophil suppression with reduced infection risk.
EMA's priority medicine scheme and FDA's breakthrough therapy designation are compressing the evidentiary gap between clinical proof and reimbursement access. These accelerated pathways require sponsors to commit to post-approval outcome studies, shifting commercial strategy toward real-world evidence generation. Biologics targeting IL-5 pathways face the steepest evidentiary demands in Germany, where IQWiG assessments scrutinize comparative effectiveness against established standards.
Integrated care networks are consolidating biologic purchasing decisions under pharmacy benefit managers and specialty pharmacy arrangements. Hospital systems now negotiate outcomes-based contracts that tie reimbursement to sustained eosinophil suppression and reduced exacerbation rates. This concentration is most visible in the United States, where three national specialty pharmacy platforms control the majority of biologic distribution for rare immunology indications.
Eosinophilic Granulomatosis Market Segmentation
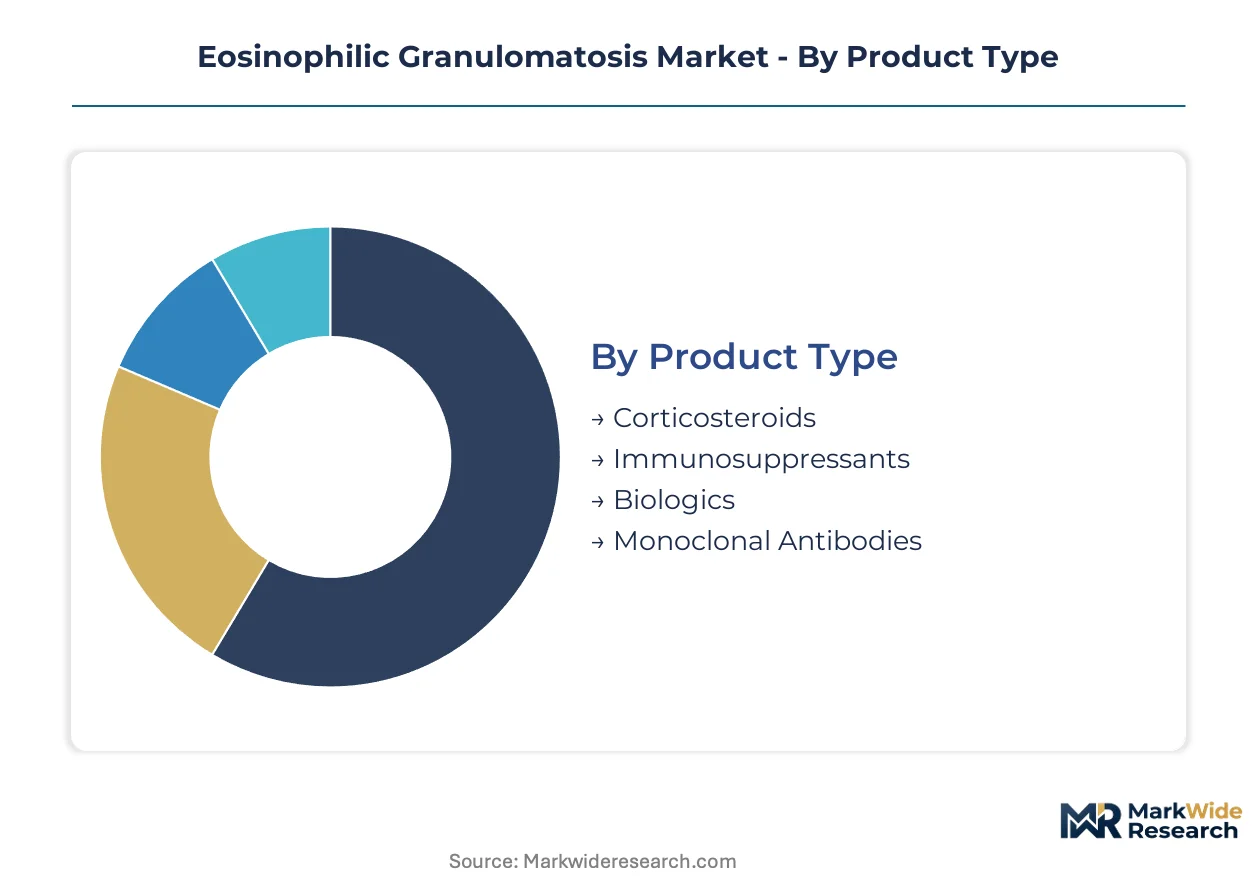
Segmentation in eosinophilic granulomatosis reveals how treatment protocols bifurcate between acute induction and long-term maintenance, with biologic delivery modes and care settings determining access patterns and commercial strategy.
Product Type:
Corticosteroids dominate volume through generic availability, while biologics capture premium positioning via targeted eosinophil suppression.
- Corticosteroids:Prednisone and methylprednisolone remain the standard for acute induction protocols due to rapid anti-inflammatory action and established reimbursement. Demand concentrates in United States emergency departments and German hospital admission wards where cost anchors compress willingness-to-pay for alternatives.
- Biologics:IL-5 inhibitors and IL-4/IL-13 pathway blockers deliver steroid-sparing maintenance with superior organ protection profiles. United States specialty infusion centers and Japanese academic medical centers drive adoption as pulmonologists prioritize long-term outcomes over short-term cost containment.
- Monoclonal Antibodies:Next-generation agents targeting eosinophil maturation and survival pathways command development investment from manufacturers seeking differentiation in crowded immunology portfolios.
- Immunosuppressants:Cyclophosphamide and azathioprine retain niche use in refractory cases where biologic access is limited by formulary restrictions or payer step-therapy requirements.
Today's leader: Corticosteroids. Tomorrow's challenger: Biologics.
End User:
Care setting determines therapy intensity, with hospital-based specialists controlling biologic initiation and home-based maintenance expanding addressable populations.
- Hospitals:Academic medical centers in the United States, Germany, and Japan concentrate vasculitis expertise, performing diagnostic staging and biologic induction under protocol-driven oversight.
- Specialty Centers:Dedicated allergy and immunology clinics manage chronic maintenance with embedded infusion infrastructure, capturing patients requiring frequent eosinophil monitoring.
- Clinics:Community-based rheumatology and pulmonology practices serve as referral filters, identifying candidates for specialist escalation based on organ involvement severity.
- Home Care Settings:Self-administered subcutaneous formulations enable rural patient access, reducing travel burden for chronic maintenance populations.
Specialty centers anchor biologic revenue. Home care settings represent the steepest expansion trajectory.
Application:
Clinical use cases stratify by disease phase, with chronic management commanding sustained revenue against episodic intervention.
- Chronic Disease Management:Long-term eosinophil suppression and organ protection protocols drive biologic maintenance prescriptions, with United States integrated care networks negotiating outcomes-based contracts tied to exacerbation reduction.
- Allergy Treatment:Asthma and chronic rhinosinusitis with nasal polyps comorbidities create indication expansion opportunities for eosinophil-targeting agents with overlapping mechanistic pathways.
- Symptom Relief:Acute exacerbation management relies on corticosteroid bursts, with emergency department presentation triggering specialist referral for definitive therapy.
- Patient Support:Adherence programs and nurse navigator services address injection fatigue and monitoring compliance in chronic maintenance populations.
Chronic management commands sustainable margins. Allergy treatment offers the fastest label expansion pathway.
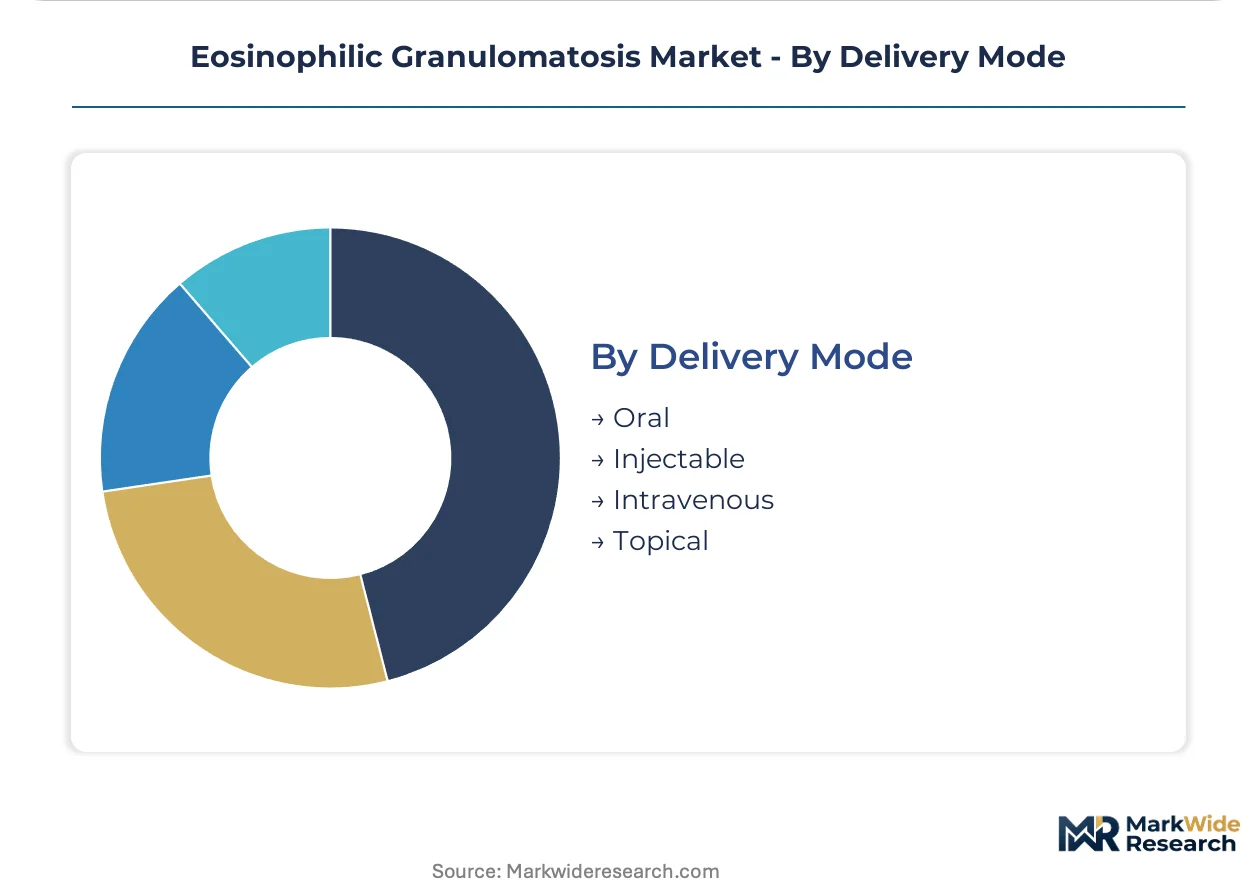
Delivery Mode:
Route of administration shapes patient autonomy, with parenteral forms requiring infrastructure investment and oral agents enabling broader access.
- Injectable:Subcutaneous IL-5 inhibitors permit home administration, reducing infusion center dependency while requiring cold-chain distribution integrity.
- Intravenous:Hospital-based infusion of monoclonal antibodies ensures therapeutic supervision during induction phases, with United States specialty pharmacy platforms controlling distribution logistics.
- Oral:Corticosteroid tablets and emerging small-molecule immunomodulators offer patient convenience, though bioavailability variability complicates precision dosing.
- Topical:Limited applicability in systemic vasculitis, with occasional use for cutaneous granuloma management in localized disease presentations.
Injectable formulations capture convenience premiums. Intravenous delivery anchors specialist-controlled initiation protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fellowship-trained vasculitis specialists concentrate at academic medical centers in the United States, Germany, and Japan, anchoring diagnostic expertise and biologic initiation capacity. These talent clusters determine where precision immunology protocols achieve fastest adoption. Regulatory frameworks and reimbursement structures in each geography shape how quickly steroid-sparing therapies displace corticosteroid dependence.
United States
Integrated care networks in Boston and New York Metro consolidate biologic purchasing decisions under specialty pharmacy platforms. FDA orphan drug designations compress development timelines for IL-5 and IL-4/IL-13 inhibitors. The Mayo Clinic and Cleveland Clinic anchor multicenter outcome registries that feed real-world evidence requirements for payer negotiations.
Germany
IQWiG assessments scrutinize comparative effectiveness of eosinophil-targeting agents against cyclophosphamide standards. The Federal Joint Committee applies quality-adjusted survival endpoints that favor long-term organ protection data. Heidelberg and Berlin academic hospitals coordinate the German Vasculitis Registry, generating post-approval evidence for EMA priority medicine scheme compliance.
Japan
PMDA Sakigake designation accelerates review timelines for biologics addressing unmet needs in refractory vasculitis. The Central Social Insurance Medical Council evaluates cost-effectiveness against corticosteroid comparators using lifetime health economic models. Tokyo and Osaka university hospitals concentrate specialist expertise for eosinophil-driven disorder staging protocols.
United Kingdom
NICE technology appraisals demand head-to-head evidence against standard-of-care immunosuppressants for biologic reimbursement. The NHS England specialized commissioning framework routes rare disease biologics through designated treatment centers. London and Manchester academic networks manage the UK and Ireland Vasculitis Society registry for outcome tracking.
Switzerland
Swissmedic expedited access pathways enable early reimbursement for biologics with breakthrough therapy status from FDA or EMA. Cantonal hospital networks in Zurich and Geneva coordinate cross-border patient referral for complex vasculitis cases. The country's concentrated mammalian cell culture capacity supplies fill-finish operations for monoclonal antibody production serving European markets.
Eosinophilic Granulomatosis Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the eosinophilic granulomatosis therapeutic space. The market structure tiers between established immunology franchises with broad respiratory portfolios and emerging biotech entities with single-pathway depth. Three archetypes dominate: large-cap pharmaceutical companies with integrated commercial infrastructure, mid-cap biotech firms with co-development partnerships, and specialty generics manufacturers with corticosteroid volume positions. Competitive moves center on real-world evidence generation for payer differentiation and subcutaneous formulation development to reduce infusion center dependency.
Among diversified pharmaceutical conglomerates, Sanofi S.A., GlaxoSmithKline plc, and Regeneron Pharmaceuticals, Inc. occupy positions shaped by their immunology portfolio breadth. Sanofi leverages established relationships with consolidated hospital buyers through its existing biologic infrastructure. GlaxoSmithKline exemplifies deep specialization in respiratory and eosinophilic conditions. Regeneron anchors academic medical center penetration through co-development arrangements that extend clinical trial access. These three entities represent how scale and partnership architecture determine competitive positioning in rare disease biologics.
| Leading Market Players |
|---|
| Sanofi S.A. |
| F. Hoffmann-La Roche Ltd. |
| GlaxoSmithKline plc |
| NS Pharma (Nippon Shinyaku) |
| Novartis AG |
| AstraZeneca plc |
| Regeneron Pharmaceuticals, Inc. |
| Boehringer Ingelheim International GmbH |
| Teva Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Fellowship-trained vasculitis specialists concentrated in Boston, New York Metro, and Heidelberg create labor-cost differentials that widen pricing-tier spreads between academic medical centers and community infusion networks.
Pricing Analysis
Bundled service contracts dominate biologic purchasing decisions, while unbundled per-dose pricing persists for corticosteroid induction protocols. Three-tier pricing structure across premium, standard, and economy levels separates originator biologics from biosimilar entrants and generic corticosteroids. Price differentiation hinges on outcome guarantee provisions and cold-chain reliability certification. Cost compression in the standard tier is intensifying because integrated care networks demand risk-sharing arrangements for maintenance therapy populations. Community rheumatology practices exhibit highest price sensitivity due to formulary step-therapy requirements, while academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Regional distribution centers in Switzerland and Ireland anchor hub-and-spoke patterns for monoclonal antibody fill-finish operations. Manufacturing concentration draws from mammalian cell culture capacity in Basel and Dublin, with active pharmaceutical ingredient sourcing from Singapore and Puerto Rico. Raw material dependencies include recombinant protein media, single-use bioreactor components, and temperature-controlled packaging systems. Single-source vulnerability for sterile fill-finish creates supply chain risk should regulatory inspections interrupt Swissmedic-certified facilities. Distribution runs through United States specialty pharmacy platforms and German hospital pharmacy consortia for last-mile delivery to infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The eosinophilic granulomatosis market functions as a stable compounder, with biologic maintenance protocols driving predictable revenue streams through chronic disease management requirements.
For Market Incumbents: To counter biosimilar entry pressure, anchor formulary position through real-world evidence generation partnerships with German and Japanese vasculitis registries. Deepen backward integration into cold-chain distribution infrastructure to capture margin currently ceded to third-party logistics providers. Secure exclusive supply agreements with academic medical center networks in Boston and Heidelberg to lock biologic initiation volume. For New Entrants and Emerging Players: Capture underserved home administration demand by developing subcutaneous formulations with patient self-injection devices for rural populations distant from infusion infrastructure. Target community rheumatology practices in the United States Midwest and Japanese prefectural hospitals as referral escalation points. Differentiate through bundled adherence monitoring services that address injection fatigue in chronic maintenance populations. For Investors and Strategic Acquirers: Large-cap immunology franchises with existing respiratory portfolios are the most active acquirer in this space, seeking pipeline expansion through Phase II-ready IL-5 pathway assets. Long-term viability rests on demonstrated switching capability from corticosteroid induction to biologic maintenance without exacerbation rebound. Monitor FDA breakthrough therapy designation frequency as inflection signal for competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Registry Partnership | German Vasculitis Registry data satisfies IQWiG quality-adjusted survival endpoints for reimbursement. |
| Subcutaneous Formulation Development | Self-administration devices reduce infusion center dependency and expand rural patient access. |
| Specialty Pharmacy Platform Integration | United States integrated care networks consolidate biologic purchasing through three national platforms. |
| EMA Priority Medicine Scheme Application | Accelerated review compresses timeline between clinical proof and German Federal Joint Committee assessment. |
| Outcome-Based Contract Negotiation | Bundled pricing tied to sustained eosinophil suppression aligns hospital system incentives with manufacturer revenue. |
Research Methodology
Multiple input streams — pulmonology and rheumatology specialists, hospital pharmacy directors, payer access managers, and regulatory affairs leads — were reconciled against FDA orphan drug filings, EMA priority medicine submissions, ClinicalTrials.gov protocols, and German G-BA assessment documents. Bottom-up patient flow modeling through United States, German, and Japanese treatment centers was cross-validated with top-down biologic revenue estimates from manufacturer disclosures and specialty pharmacy distribution data.
Historical prescription volume patterns were cross-referenced against expert panel input from the American College of Rheumatology and European Vasculitis Society to establish baseline assumptions across the analysis window. Segmentation dimensions modeled include treatment phase (induction versus maintenance), delivery mode (intravenous versus subcutaneous), and regional regulatory cluster (FDA, EMA, PMDA pathways). CAGRs were derived from epidemiology-adjusted prevalence estimates and biologic penetration rate assumptions, with sensitivity testing against corticosteroid cost-anchor thresholds and biosimilar entry timing scenarios.
Regulatory pathway delays, reimbursement evidence requirement changes, and specialist workforce expansion rates are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Polymyalgia Rheumatica Treatment Market
Specialty Medicine
Bronchiectasis Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market
Specialty Medicine
Ischemic Hepatitis Treatment Market
Specialty Medicine
Intraductal Papilloma Market
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
Global Non-Oncology Precision Medicine Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Global Postmenopausal Osteoporosis Market
Specialty Medicine
Acromegaly Market
Specialty Medicine
Healthcare Specialty Enzymes Market
Specialty Medicine
Global Plasma Therapeutics Market
Specialty Medicine
Whim Syndrome Management Market
Specialty Medicine
Premenstrual Dysphoric Disorder Market
Specialty Medicine
Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market