
 Self-Sampling Blood Collection and Storage Devices Market | 2026-2036
Self-Sampling Blood Collection and Storage Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Sampling Blood Collection and Storage Devices Market Outlook
The capital-intensity divergence between automated manufacturing platforms and manual assembly operations is redrawing competitive tiers in self-sampling blood collection. Becton Dickinson and Company leverages decades of vacuum-based device expertise to sustain premium positioning across hospital and laboratory channels. Tasso, Inc. competes with button-actuated capillary technology that eliminates venipuncture entirely, while Capitainer anchors its model on quantitative dried blood spot precision for therapeutic drug monitoring.
Self-sampling blood collection and storage devices comprise engineered consumables designed to capture defined blood volumes—typically 10–500 µL—through capillary action, vacuum assistance, or dried matrix absorption, with integrated stabilizers preserving analyte integrity during ambient transport. These systems serve decentralized diagnostics, remote clinical trials, and home-based chronic disease management by eliminating phlebotomist dependency and cold-chain logistics. Micro sampling devices command the fastest expansion trajectory as pharmaceutical sponsors adopt patient-centric trial designs, while dry blood spot technology dominates research institution procurement due to decades of validated biomarker compatibility. Automated systems represent the emerging margin pool where instrument placement creates recurring consumable pull-through.
FDA 510(k) clearance pathways and EMA ICH E6(R2) guidance on decentralized clinical trials are reshaping validation requirements and commercial access timelines for device developers. The EU In Vitro Diagnostic Regulation intensifies conformity demands for capillary collection products marketed across member states. Stakeholders must monitor evolving payer reimbursement for remote specimen collection as health systems recalibrate fee schedules between traditional phlebotomy and patient-administered alternatives.
Market Dynamics
Decentralized clinical trial infrastructure is compressing validation timelines while fragmenting procurement authority across sponsor organizations, CROs, and direct-to-patient platforms. This structural shift rewards device developers who can demonstrate analyte stability equivalence to venipuncture across multiple biomarker classes without cold-chain dependency.
Growth Catalysts
- FDA 510(k) clearance streamlining:The agency's microsampling guidance reduces predicate device burden for capillary collection systems, accelerating market entry for novel form factors targeting therapeutic drug monitoring.
- Home-based chronic disease management:Diabetes and cardiovascular patient populations in the United States, Germany, and Japan are driving demand for alternatives to clinic-based phlebotomy as remote monitoring programs expand.
- Button-actuated capillary technology:Painless blood extraction without venipuncture eliminates phlebotomist dependency and opens addressable populations previously excluded from serial biomarker studies.
Market Restraints
- Specialized polymer supply concentration:Medical-grade capillary tubes and hydrophilic coatings depend on concentrated German and Japanese specialty chemical suppliers, exposing device manufacturers to input cost volatility.
- EU In Vitro Diagnostic Regulation conformity costs:The MDR intensifies documentation requirements for capillary collection products, extending certification timelines and freezing smaller competitors from member state markets.
- Dried blood spot analytical equivalence limitations:Certain therapeutic classes and immunogenicity assays remain incompatible with microsample volumes, preserving venipuncture for specific biomarker panels.
Strategic Opportunities
- India's decentralized diagnostics expansion:The country's CDSCO regulatory pathway and PLI scheme for medical devices create entry points for affordable capillary collection systems targeting rural health networks.
- Quantitative dried blood spot precision convergence:Integration of volumetric absorptive microsampling with LC-MS/MS workflows opens therapeutic drug monitoring applications previously requiring plasma separation.
- Direct-to-patient clinical trial distribution:Patient-centric trial designs bypass traditional site-based recruitment, creating channel innovation for device developers with ambient stability claims.
Industry Challenges
- Biomarker assay validation expertise scarcity:Cross-functional teams combining microfluidics engineering, clinical chemistry, and regulatory science remain difficult to assemble, slowing product development cycles.
- Legacy laboratory information system integration:Hospital and reference lab IT infrastructure requires custom middleware development to accept patient-collected specimen data, complicating enterprise sales.
- Reimbursement code fragmentation:Payer fee schedules lack consistent categorization for remote specimen collection, forcing device manufacturers to navigate heterogeneous prior authorization requirements across health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Sampling Blood Collection and Storage Devices Market |
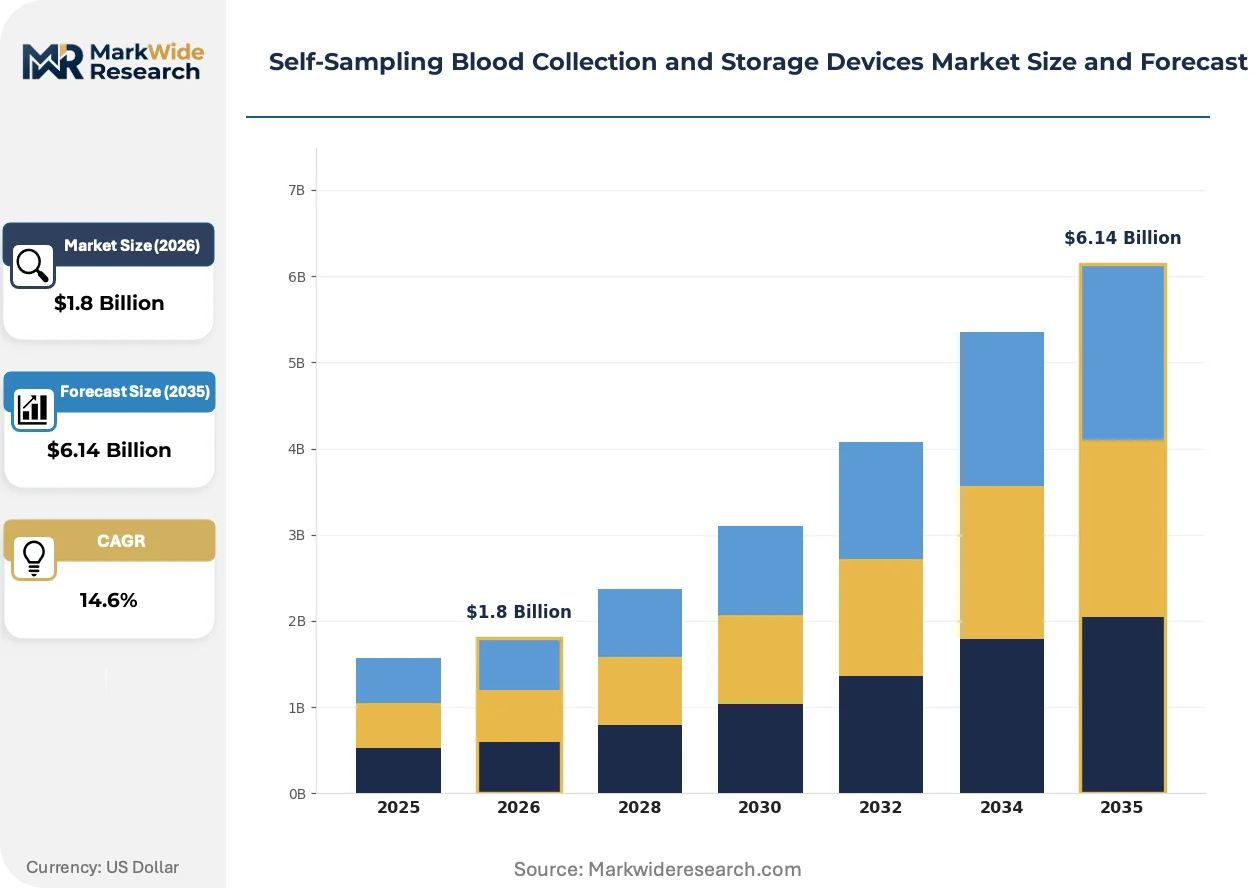
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capillary Tubes, Blood Collection Cards, Micro Sampling Devices, Storage Vials Technology: Vacuum-Based Collection, Dry Blood Spot, Capillary Collection, Automated Systems End User: Home Care, Research Institutions, Diagnostic Laboratories, Blood Banks Distribution Channel: Online Retail, Direct Sales, Distributors, Medical Supply Stores |
| Companies Covered | YourBio Health, Inc., Labcorp, Becton Dickinson and Company, Trajan Group Holdings Limited, Everlywell, Terumo Medical Corporation, Quest Diagnostics, Capitainer, Tasso, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Sampling Blood Collection and Storage Devices Market Strategic Shifts
Capillary collection technology is fragmenting into purpose-built modalities as end-users reject one-size-fits-all devices. Precision volumetric control, analyte-specific stabilizers, and automated processing compatibility are becoming minimum viable specifications rather than differentiators.
Microsampling devices incorporating volumetric absorptive matrices are bifurcating the research-use and clinical-use segments. Pharmaceutical sponsors adopt these systems for decentralized trials requiring precise analyte quantification, while academic researchers prioritize cost-minimized dried blood spot cards. This divergence is compressing margins for undifferentiated mid-tier products and rewarding developers with regulatory-grade performance claims.
EMA ICH E6(R2) guidance on decentralized clinical trials is mandating specimen provenance documentation that legacy capillary devices cannot satisfy. Device developers must integrate chain-of-custody features and temperature excursion logging to qualify for sponsor procurement. European CROs are responding by consolidating preferred supplier lists around vendors with EMA-recognized quality management systems.
Site-less trial recruitment is displacing traditional site-based patient enrollment for chronic disease studies. Direct-to-patient platforms ship collection devices to home addresses, bypassing investigator sites entirely. This behavioral shift concentrates in the United States and United Kingdom where regulatory frameworks accommodate remote informed consent and telemedicine oversight.
Self-Sampling Blood Collection and Storage Devices Market Segmentation
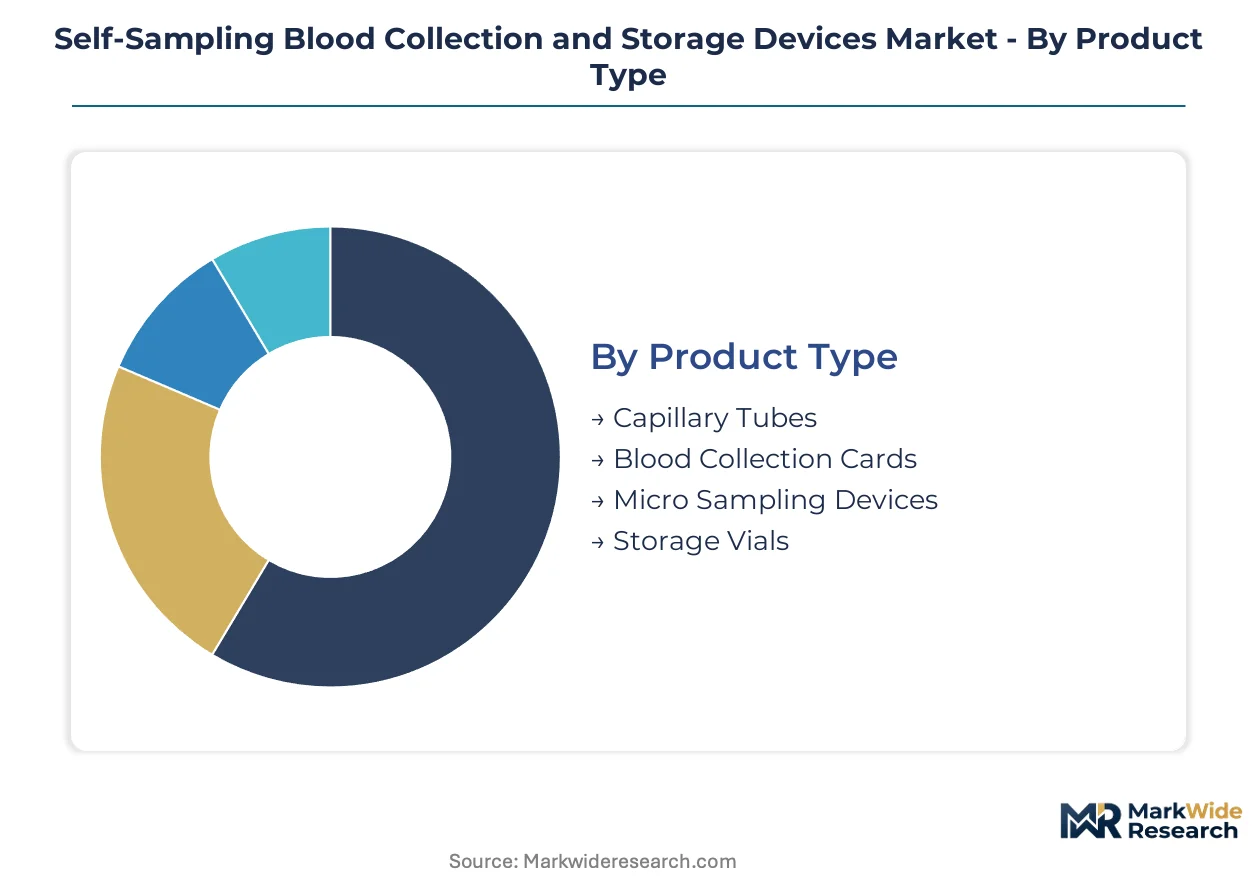
Segmentation in self-sampling blood collection reveals how technology differentiation and end-user requirements fragment procurement patterns. Understanding these divisions exposes where device developers must align specifications with regulatory pathways and reimbursement logic.
Product Type:
Margin pools concentrate in precision-engineered consumables where volumetric accuracy commands premium pricing over commodity collection tools.
- Micro Sampling Devices:Engineered consumables capturing 10–500 µL through capillary action or vacuum assistance, with integrated stabilizers preserving analyte integrity. Pharmaceutical sponsors in the United States and Germany are driving procurement for decentralized clinical trials requiring therapeutic drug monitoring equivalence to venipuncture.
- Storage Vials:Temperature-stable containers with barrier coatings preventing evaporation and oxidation during ambient transport. Blood banks and reference laboratories in Japan prioritize these systems for specimen integrity across extended logistics chains.
- Capillary Tubes:Medical-grade polymer or glass tubes calibrated for precise microvolume collection.
- Blood Collection Cards:Filter paper matrices for dried blood spot applications in research and screening programs.
The dominant share belongs to micro sampling devices, while storage vials are closing the gap fastest.
Technology:
Technology selection determines regulatory pathway complexity and the breadth of biomarker classes each system can support.
- Vacuum-Based Collection:Negative-pressure systems drawing defined blood volumes without venipuncture, leveraging decades of validated manufacturing protocols. Hospital and laboratory channels in Germany sustain demand for these devices given established workflow integration and predicate device familiarity for FDA submissions.
- Automated Systems:Instrumented platforms combining collection, processing, and digital chain-of-custody documentation. EMA ICH E6(R2) compliance requirements for decentralized trials are accelerating sponsor procurement of these systems across European CRO networks.
- Dry Blood Spot:Absorptive matrices enabling ambient transport without cold-chain infrastructure.
- Capillary Collection:Passive or assisted capillary action devices for fingerstick sampling.
Vacuum-based collection retains the largest installed base, though automated systems are expanding most quickly as trial decentralization mandates provenance documentation.
End User:
End-user segmentation maps directly to reimbursement availability and regulatory scrutiny intensity.
- Home Care:Patient-administered collection for chronic disease monitoring and remote trial participation. United States health systems and Japanese insurers are expanding coverage for diabetes and cardiovascular patient populations seeking alternatives to clinic-based phlebotomy.
- Research Institutions:Academic and government laboratories prioritizing cost-minimized dried blood spot cards for epidemiological and biomarker discovery studies. Procurement concentrates in Germany and the United Kingdom where public research funding supports large-scale biobanking initiatives.
- Diagnostic Laboratories:High-throughput processing facilities requiring standardized collection protocols.
- Blood Banks:Collection and processing centers for transfusion services and donor screening.
Home care commands the steepest expansion trajectory, while research institutions maintain the deepest volume concentration.
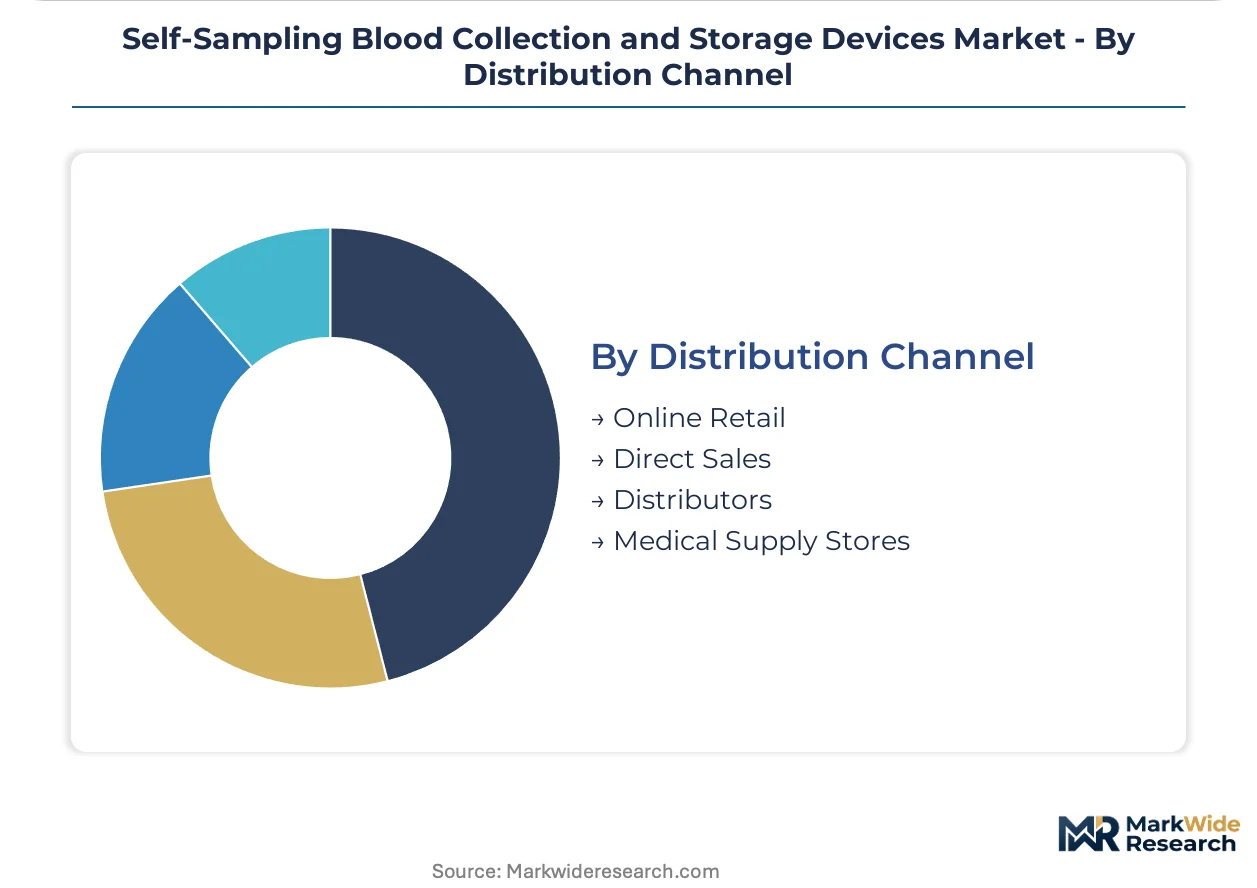
Distribution Channel:
Channel structure reflects customer scale and the technical support intensity each segment demands.
- Direct Sales:Manufacturer-led contracting with pharmaceutical sponsors, CROs, and health systems for customized device configurations. Large-scale decentralized trials in the United States and Germany are consolidating procurement through direct relationships to secure volume pricing and dedicated supply allocations.
- Distributors:Regional medical supply intermediaries serving diagnostic laboratories and blood banks with standardized product portfolios. Japanese and German distribution networks maintain particularly dense coverage of hospital procurement departments.
- Online Retail:Direct-to-patient and direct-to-consumer platforms for home care diagnostics.
- Medical Supply Stores:Brick-and-mortar channels for clinical and home care product access.
Direct sales captures the highest value per transaction, while distributors are gaining share fastest through laboratory consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese procurement channels where precision manufacturing standards command premium positioning, while Indian and Brazilian markets operate on volume-driven cost structures with compressed margins for standardized collection tools.
United States
Decentralized clinical trial infrastructure and home-based chronic disease management programs drive procurement intensity. FDA 510(k) clearance pathways for microsampling devices accelerate product validation timelines. The Boston-Cambridge biotech cluster anchors pharmaceutical sponsor demand for patient-centric collection systems.
Germany
Reference laboratory networks and public health screening programs sustain vacuum-based collection device demand. EMA ICH E6(R2) guidance on decentralized trials shapes validation requirements for device developers. The Rhine-Main region concentrates medical technology manufacturing and specialty polymer supply chains.
Japan
Aging demographics and remote patient monitoring expansion fuel home care diagnostics procurement. PMDA regulatory frameworks accommodate microsampling equivalence studies for therapeutic drug monitoring. The Kanto region around Tokyo hosts dense diagnostic laboratory networks and blood banking infrastructure.
India
Rural health network expansion and decentralized diagnostics programs create volume opportunities for affordable capillary collection systems. CDSCO regulatory pathways and PLI scheme incentives attract medical device manufacturing investment. The Maharashtra-Gujarat industrial corridor emerges as a production hub for export-oriented consumables.
United Kingdom
Site-less clinical trial adoption and NHS remote monitoring initiatives drive patient-administered collection demand. MHRA post-Brexit regulatory autonomy enables streamlined microsampling device approvals. The Cambridge-Oxford-London triangle concentrates biotech research and CRO procurement authority.
Self-Sampling Blood Collection and Storage Devices Market Competitive Environment
Concentration sits with diversified medical technology conglomerates leveraging decades of vacuum-based device expertise and established hospital procurement relationships. The competitive structure fragments across three tiers: premium precision-engineered consumables, mid-tier standardized collection tools, and emerging automated system platforms. Strategic archetypes include integrated diagnostics conglomerates, microsampling technology specialists, and patient-centric direct-to-consumer platforms. Dominant competitive moves encompass strategic partnerships with pharmaceutical sponsors for decentralized trial supply and portfolio diversification into ambient stability chemistries.
Within the integrated diagnostics tier, Becton Dickinson and Company and Terumo Medical Corporation exemplify scale-driven manufacturing archetypes with established predicate device familiarity. Among microsampling specialists, Tasso, Inc. and Capitainer occupy positions representing button-actuated capillary and quantitative dried blood spot modalities respectively. YourBio Health, Inc. anchors the patient-centric platform segment focused on eliminating phlebotomist dependency.
| Leading Market Players |
|---|
| YourBio Health, Inc. |
| Labcorp |
| Becton Dickinson and Company |
| Trajan Group Holdings Limited |
| Everlywell |
| Terumo Medical Corporation |
| Quest Diagnostics |
| Capitainer |
| Tasso, Inc. |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance pathways and EMA ICH E6(R2) guidance on decentralized clinical trials gate both supplier qualification and price differentiation simultaneously, forcing device developers to absorb certification costs that stratify procurement tiers. Manufacturers with predicate device familiarity command configured-to-order premiums from pharmaceutical sponsors, while undifferentiated producers compete on standardized collection tool margins.
Pricing Analysis
The customization-premium spread separates configured-to-order microsampling devices from standardized capillary tubes. Contract-based long-term offtake dominates sponsor procurement, with price differentiation driven by FDA clearance tier and volume scale. Cost compression in mid-tier standardized products is intensifying because EMA MDR conformity documentation extends certification timelines. Diagnostic laboratories exhibit highest price sensitivity, while decentralized trial sponsors prioritize ambient stability claims over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail among pharmaceutical sponsors running patient-centric trials, though reference laboratories maintain strategic stockpiles of vacuum-based devices. Medical-grade polymer feedstock draws from German and Japanese specialty chemical suppliers, with hydrophilic coating precursors sourced from concentrated Rhine-Main and Kanto region manufacturers. Single-source vulnerability in capillary tube substrates exposes device assemblers to input cost volatility. Distribution runs through direct manufacturer contracting with large sponsors and regional medical supply intermediaries serving hospital procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Self-sampling blood collection is approaching a platform-economics inflection where automated system placement creates recurring consumable pull-through, with interoperability between patient-administered devices and laboratory information systems determining competitive survival.
For Market Incumbents: Secure predicate device familiarity advantages by accelerating FDA 510(k) submissions for novel capillary form factors before guidance tightens. Deepen backward integration into medical-grade polymer supply to offset German and Japanese specialty chemical concentration. Channel control through direct sponsor relationships defends margin position against emerging automated system platforms. For New Entrants and Emerging Players: Anchor in India's CDSCO regulatory pathway and PLI scheme incentives to capture rural health network procurement with affordable capillary collection systems. The most penetrable white space sits in quantitative dried blood spot precision for therapeutic drug monitoring, where LC-MS/MS workflow integration remains incomplete. A direct-to-patient go-to-market angle bypasses entrenched hospital procurement gatekeepers entirely. For Investors and Strategic Acquirers: EMA ICH E6(R2) guidance on decentralized trials reshapes the acquisition landscape by mandating chain-of-custody capabilities that legacy devices cannot satisfy. Long-term viability over the coming decade hinges on ambient stability chemistry IP and automated processing compatibility. The acquisition target archetype combines microfluidics engineering with regulatory-grade quality management systems. The signal to watch is payer reimbursement code consolidation for remote specimen collection across United States health systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerated market entry for capillary collection systems targeting therapeutic drug monitoring applications. |
| CE Marking Pathway | EU MDR conformity enables member state access amid intensifying documentation requirements for smaller competitors. |
| Pharmaceutical Sponsor Partnership | Direct contracting secures volume pricing and dedicated supply allocations for large-scale decentralized trials. |
| Software Companion Development | Digital chain-of-custody integration satisfies EMA specimen provenance mandates for site-less trial recruitment. |
| Reimbursement Strategy | Prior authorization navigation across heterogeneous United States payer fee schedules unlocks home care diagnostics expansion. |
Study Parameters
Desk research of FDA 510(k) filings, EMA decentralized trial guidance documents, and hospital procurement databases preceded structured interviews with regulatory affairs leads at device developers, GPO contracts managers, and biomedical engineers at reference laboratories. Primary insights from pharmaceutical sponsor supply chain directors and CRO procurement officers combined with secondary validation from clinical chemistry literature and customs trade data. Bottom-up device shipment modeling and top-down addressable market sizing were triangulated for consistency.
Variance decomposition across product type, technology modality, end-user segment, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs incorporated decentralized trial adoption curves and chronic disease monitoring program expansion trajectories specific to United States, German, and Japanese health systems.
Underlying assumptions cover sustained FDA microsampling guidance stability and EMA ICH E6(R2) enforcement continuity, with deviation risk concentrated in payer reimbursement code fragmentation and specialty polymer supply disruptions. Forecasts reflect these documented conditions without claiming predictive certainty. Practitioners should keep alternative scenarios live as CDSCO regulatory pathway evolution and PLI scheme incentive adjustments reshape manufacturing geography.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ankle Mobile Bearing System Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
Middle East and Africa Non-Surgical Procedures Market
Medical Devices
Infant Incubator Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
India Medical Devices Market
Medical Devices
Endometrial Ablation Devices Market
Medical Devices
Bioimpedance Analyzers Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Global Gait Analysis System Market
Medical Devices
Global Brain Monitoring Devices Market
Medical Devices
LASIK Eye Surgery Devices Market
Medical Devices
Veterinary Respiratory Ventilators Market
Medical Devices
Heart Closure Devices Market
Medical Devices
Digital Intraoral Sensors and Consumables Market
Medical Devices
Bedwetting Alarm Market