
 Phenylketonuria Therapeutics Market | 2026-2036
Phenylketonuria Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Phenylketonuria Therapeutics Market Analytics
Good Manufacturing Practice certification for biologics manufacturing is rotating competitive advantage toward firms with validated cell-line and viral-vector production infrastructure. BioMarin Pharmaceutical leverages its established enzyme therapy platform to sustain dominance in phenylalanine-lowering biologics. Synlogic anchors its position through synthetic biology approaches to metabolic pathway engineering. Codexis competes by specializing in novel enzyme variants designed for improved phenylalanine degradation kinetics.
Phenylketonuria therapeutics encompass pharmacological and nutritional interventions that reduce blood phenylalanine levels, typically targeting concentrations below 360 μmol/L to prevent neurocognitive damage. These treatments function by either supplementing defective phenylalanine hydroxylase activity, providing alternative metabolic pathways, or restricting dietary phenylalanine intake through specialized medical foods. Pharmaceuticals and enzyme replacement therapy command the deepest margin pools due to patent protection and manufacturing complexity, while genetic therapies represent the fastest-growing category as clinical pipelines mature toward commercialization. Oral delivery modes retain the largest installed base among patient populations, though intravenous formulations are gaining traction in hospital settings for acute metabolic crisis management.
FDA orphan drug designation and EMA priority medicines pathways shape development timelines and market exclusivity structures for PKU innovators, while national newborn screening mandates from bodies such as the UK's NHS Screening Committee directly determine addressable patient populations. Payers in Germany through the G-BA and in France via the HAS apply distinct cost-effectiveness thresholds that filter which therapies achieve reimbursement. Stakeholders must monitor how regulatory divergence across FDA, EMA, and Japan's PMDA on gene therapy safety endpoints will fragment clinical trial strategies and commercial sequencing.
Market Dynamics
Gene therapy platforms are redirecting capital flows away from small-molecule phenylalanine-lowering drugs toward viral-vector and cell-based metabolic interventions, compressing development timelines for enzymatic and nucleic acid modalities while elevating manufacturing complexity barriers.
Growth Catalysts
- Newborn screening mandates:The UK's NHS Screening Committee and similar bodies across Germany, France, and Japan are tightening diagnostic protocols, expanding addressable patient populations at birth.
- Enzyme engineering advances:Novel phenylalanine ammonia lyase variants with improved kinetic profiles are enabling subcutaneous dosing frequencies that match patient compliance preferences.
- Biologics manufacturing infrastructure:Contract development organizations with validated cell-line platforms are reducing entry costs for mid-stage PKU therapeutics developers.
Market Restraints
- Reimbursement heterogeneity:Germany's G-BA and France's HAS apply divergent cost-effectiveness thresholds that fragment commercial sequencing across European markets.
- Viral-vector supply concentration:Plasmid DNA and AAV manufacturing capacity concentrates among a handful of North American and European contract manufacturers, creating bottlenecks for gene therapy candidates.
- Dietary protein substitute persistence:Medical food formulations remain the default first-line intervention in resource-constrained health systems, limiting pharmaceutical penetration.
Strategic Opportunities
- Gene therapy regulatory pathways:FDA's regenerative medicine advanced therapy designation and EMA's priority medicines framework offer accelerated review timelines for first-in-class metabolic interventions.
- Pediatric metabolic clinic networks:Specialized treatment centers in the United States are consolidating referral pathways, creating concentrated prescriber access points for novel therapeutics.
- Digital phenylalanine monitoring integration:Continuous biosensor platforms paired with therapeutic dosing algorithms are opening adherence-linked reimbursement models.
Industry Challenges
- Gene therapy talent scarcity:Viral-vector process development and regulatory strategy expertise concentrates among a limited pool of specialists with rare disease commercialization experience.
- Clinical endpoint standardization:Blood phenylalanine variability measures and neurocognitive assessment protocols lack harmonization across FDA, EMA, and PMDA guidance documents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenylketonuria Therapeutics Market |
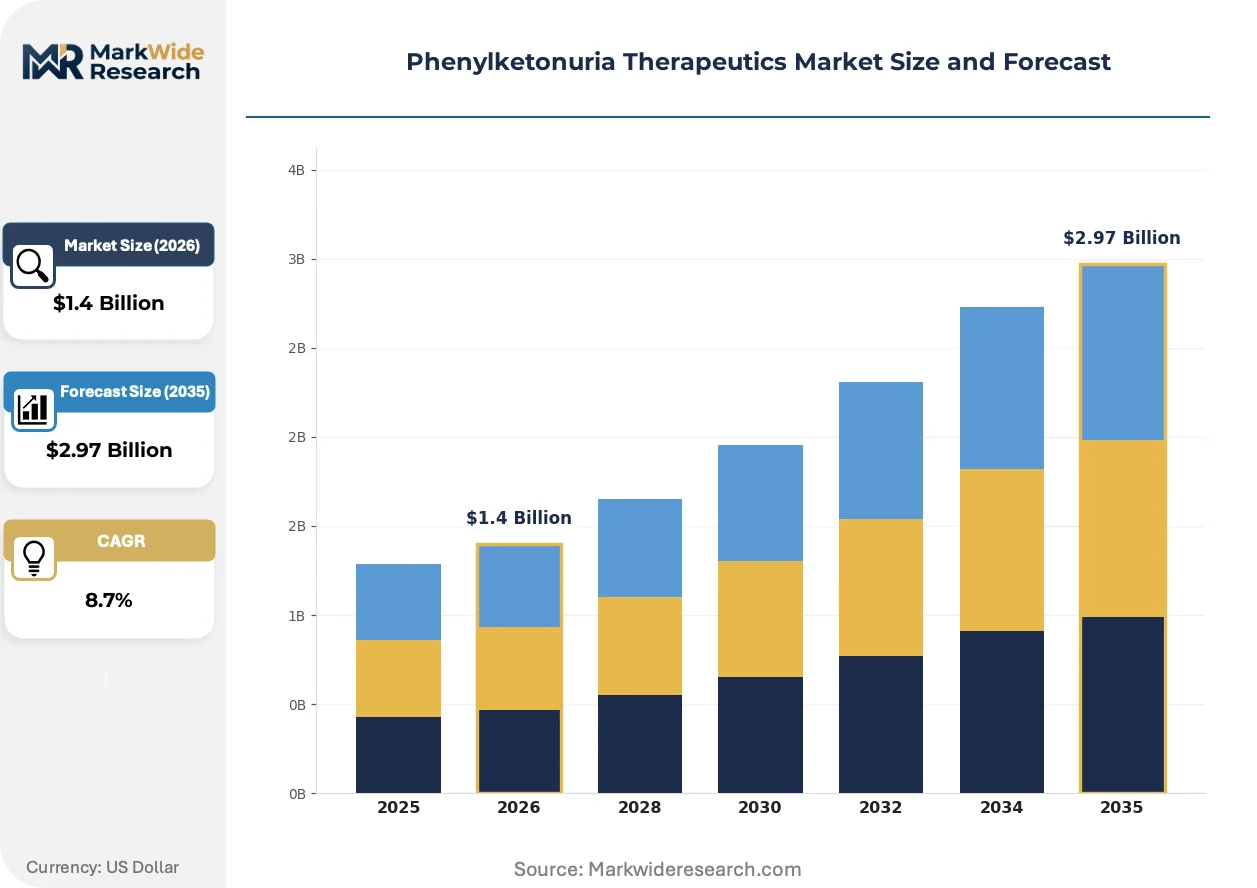
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dietary Supplements, Pharmaceuticals, Enzyme Replacement Therapy, Genetic Therapies Delivery Mode: Oral, Injectable, Intravenous, Nasal Indication: Classical PKU, Mild PKU, BH4 Deficiency, Other Enzyme Deficiencies End User: Hospitals, Clinics, Home Care, Long-term Care Facilities |
| Companies Covered | Synlogic, Codexis, BioMarin Pharmaceutical, American Gene Technologies, SOM Innovation Biotech, PTC Therapeutics, Travere Therapeutics, Jnana Therapeutics, Daiichi Sankyo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenylketonuria Therapeutics Market Evolving Landscape
Platform technologies are fragmenting competitive advantage across enzymatic, genetic, and nutritional intervention categories, with manufacturing sophistication and regulatory strategy replacing molecular novelty as the primary value determinant.
Gene therapy delivery systems is bifurcating clinical development pipelines between liver-directed AAV approaches and ex vivo hematopoietic stem cell modifications. Pediatric metabolic specialists in Boston, Philadelphia, and London are enrolling patients in parallel Phase I/II studies at unprecedented velocity. This divergence is compressing investor timelines for enzyme replacement platforms while extending capital commitments for genetic modalities.
EMA's advanced therapy medicinal products framework is harmonizing manufacturing quality standards across member states, reducing duplicate inspection burdens for biologics facilities. The regulation is accelerating centralized marketing authorization submissions for phenylalanine-lowering cell therapies. Developers are responding by consolidating European clinical trial operations in Belgium and the Netherlands to exploit streamlined ethics review pathways.
Patient advocacy organizations are consolidating purchasing influence through centralized medical food procurement consortia in the United States. Traditional pharmacy benefit manager channels are ceding ground to direct manufacturer-to-clinic distribution models for specialized metabolic formulas. This reconfiguration is most visible in California and Texas, where integrated care organizations now negotiate annual therapeutic food contracts separate from pharmaceutical formularies.
Phenylketonuria Therapeutics Market Segmentation
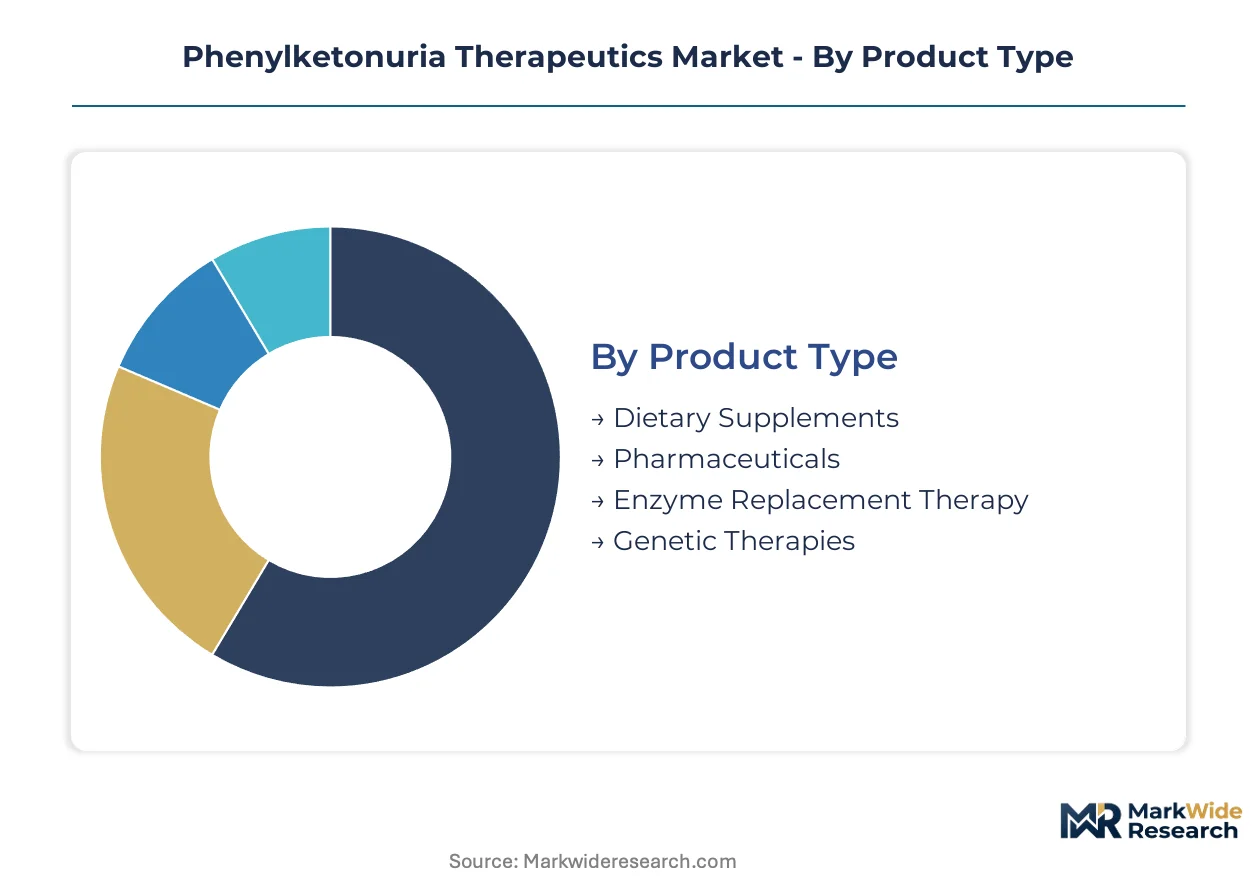
Treatment modality selection in PKU care hinges on disease severity, patient age, and metabolic control targets. Segmentation patterns reveal how innovation concentrates in high-margin biologics while medical foods retain volume dominance in routine management.
Product Type:
Dietary Supplements command domestic manufacturing footprints in the United States and Germany, while Genetic Therapies depend on export-oriented viral-vector production concentrated in Belgium and Massachusetts.
- Pharmaceuticals:Synthetic BH4 cofactors and phenylalanine-lowering small molecules target residual enzyme activity in mild phenylketonuria variants. Demand clusters in pediatric metabolic clinics across the United States where FDA orphan drug exclusivity supports premium pricing and prescriber education programs.
- Genetic Therapies:Liver-directed AAV vectors and ex vivo hematopoietic stem cell modifications aim to restore phenylalanine hydroxylase expression permanently. Clinical trial recruitment concentrates in Boston, Philadelphia, and London academic medical centers pursuing EMA priority medicines and FDA regenerative medicine advanced therapy designations.
- Dietary Supplements:Specialized amino acid mixtures and vitamin-mineral fortification products dominate first-line intervention protocols in resource-constrained health systems.
- Enzyme Replacement Therapy:Recombinant phenylalanine ammonia lyase variants enable subcutaneous phenylalanine reduction for classical PKU patients with null mutations.
Pharmaceuticals hold the largest share; momentum sits with Genetic Therapies.
Delivery Mode:
Cost tier stratification separates hospital-administered intravenous formulations from home-managed oral regimens, with injectable platforms occupying the mid-tier reimbursement band.
- Oral:Tablets, capsules, and liquid suspensions constitute the predominant administration route for BH4-responsive patients and maintenance-phase classical PKU. Home administration protocols in Germany and France reduce clinic visit burden while demanding rigorous patient adherence monitoring through digital phenylalanine tracking platforms.
- Injectable:Subcutaneous enzyme formulations enable self-administration by adolescent and adult patients seeking flexibility from dietary protein restriction. Adoption accelerates in the United States where specialty pharmacy networks manage prior authorization and training support.
- Intravenous:Hospital-based infusion protocols address acute metabolic decompensation and perioperative management in high-risk patients.
- Nasal:Investigational delivery systems target rapid phenylalanine reduction in patients with compromised gastrointestinal absorption or needle aversion.
Oral delivery dominates patient volumes; Injectable platforms are gaining share fastest.
Indication:
Application severity determines therapeutic intensity, with classical phenylketonuria requiring lifelong intervention while mild variants permit targeted pharmacological rescue.
- Classical PKU:Complete phenylalanine hydroxylase deficiency necessitates strict dietary phenylalanine restriction or enzyme replacement for neurocognitive protection. Newborn screening mandates in the United Kingdom, Germany, and Japan ensure earliest possible detection and treatment initiation.
- Mild PKU:Residual enzyme activity permits BH4 cofactor supplementation and relaxed dietary protocols in responsive patients. Genetic testing panels in the United States identify responsive variants to guide targeted pharmaceutical prescribing.
- BH4 Deficiency:Rare inborn errors of tetrahydrobiopterin synthesis require synthetic cofactor replacement and neurotransmitter precursors.
- Other Enzyme Deficiencies:Atypical hyperphenylalaninemias from dihydropteridine reductase or pterin-4a-carbinolamine dehydratase mutations demand specialized metabolic management.
Classical PKU commands the deepest therapeutic investment; Mild PKU shows the steepest expansion trajectory as genetic stratification improves.
End User:
Customer type fragmentation separates acute hospital-based metabolic crisis management from longitudinal home care maintenance, with clinic networks consolidating specialist expertise.
- Home Care:Patient-managed dietary protocols and self-administered enzyme injections constitute the predominant care setting for stable pediatric and adult PKU populations. Reimbursement frameworks in France through the HAS and in Germany via the G-BA increasingly cover remote monitoring technologies to support decentralized management.
- Clinics:Specialized metabolic centers in the United States, United Kingdom, and Netherlands coordinate multidisciplinary care teams and clinical trial access. These centers function as gatekeepers for novel therapeutic authorization and patient registry enrollment.
- Hospitals:Inpatient metabolic units manage acute hyperphenylalaninemic crises, pregnancy complications, and perioperative stabilization.
- Long-term Care Facilities:Residential settings accommodate adult PKU patients with significant neurocognitive impairment from historical treatment discontinuation.
Home Care captures the greatest patient volume; Clinics concentrate prescriber influence and innovation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric metabolic specialists and newborn screening programs concentrate demand in markets with mature rare disease infrastructure and established payer pathways for biologics. Regulatory divergence across FDA, EMA, and PMDA shapes commercial sequencing and clinical trial placement.
United States
Specialized treatment centers in Boston, Philadelphia, and San Francisco anchor prescriber networks for enzyme replacement and gene therapy candidates. FDA orphan drug designation and regenerative medicine advanced therapy pathways compress development timelines for metabolic interventions. Pediatric metabolic clinics in California and Texas are consolidating referral pathways and negotiating direct distribution contracts for medical foods.
Germany
The G-BA applies distinct cost-effectiveness thresholds that filter biologic reimbursement decisions, favoring therapies with demonstrated neurocognitive endpoints. Newborn screening mandates through statutory health insurance ensure earliest possible detection and treatment initiation. Manufacturing infrastructure for recombinant enzymes clusters in Bavaria and North Rhine-Westphalia, with contract development organizations reducing entry costs for mid-stage developers.
United Kingdom
The NHS Screening Committee's tightened diagnostic protocols expand addressable patient populations at birth, while NICE technology appraisals determine formulary placement for novel therapeutics. London academic medical centers coordinate Phase I/II gene therapy enrollment with EMA priority medicines frameworks. Scotland and Wales maintain separate health technology assessment processes that fragment commercial sequencing.
Japan
PMDA guidance on gene therapy safety endpoints influences clinical trial design for liver-directed AAV approaches, with METI funding supporting domestic viral-vector manufacturing capacity. Newborn screening expansion through the Ministry of Health, Labour and Welfare increases detection rates for classical PKU variants. Osaka and Tokyo metabolic centers participate in multinational studies for phenylalanine-lowering nucleic acid modalities.
France
The HAS evaluates cost-effectiveness through distinct methodological lenses that prioritize quality-adjusted life year gains in pediatric populations. ANSM oversees advanced therapy medicinal products manufacturing inspections, with centralized marketing authorization submissions accelerating European access. Paris and Lyon academic hospitals anchor the national metabolic clinic network and patient registry enrollment.
Phenylketonuria Therapeutics Market Competitive Landscape
Player mix skews toward integrated biologics manufacturers with validated cell-line platforms and emerging synthetic biology specialists. Market structure concentrates around three to five dominant enzyme therapy and gene therapy developers, with mid-stage innovators competing on manufacturing sophistication and regulatory strategy. Strategic archetypes include platform-technology licensors, rare disease commercialization specialists, and contract manufacturing-dependent developers. Competitive moves center on capacity reservation agreements for viral-vector supply and pediatric metabolic clinic network access.
Within the established enzyme therapy tier, BioMarin Pharmaceutical anchors biologics manufacturing infrastructure for phenylalanine-lowering interventions. Synlogic and Codexis occupy positions in the synthetic biology and novel enzyme variant design space, representing alternative metabolic pathway engineering approaches. These three exemplify how competitive advantage rotates toward firms with validated production infrastructure and regulatory rare disease experience.
| Leading Market Players |
|---|
| Synlogic |
| Codexis |
| BioMarin Pharmaceutical |
| American Gene Technologies |
| SOM Innovation Biotech |
| PTC Therapeutics |
| Travere Therapeutics |
| Jnana Therapeutics |
| Daiichi Sankyo |
| Others |
Value Network & Pricing Analysis
Ninety-day viral-vector production lead times concentrate pricing power among contract manufacturers with validated cell-line platforms in Belgium and Massachusetts, while enzyme therapy developers absorb cost pass-through through long-term offtake agreements indexed to plasmid DNA spot markets.
Pricing Analysis
Cost-plus contracts with plasmid DNA indexation dominate gene therapy procurement, separating premium-priced AAV vectors from standard-grade enzyme formulations and economy-tier dietary supplements. Price differentiation hinges on GMP certification tier and manufacturing scale, with multi-product facilities commanding 15-20% premiums over single-use suites. Pricing pressure stems from viral-vector supply scarcity as AAV demand outstrips GMP capacity expansion. Payers in Germany through the G-BA exhibit highest price sensitivity for chronic enzyme replacement, while US specialty pharmacy networks absorb premium pricing for acute metabolic crisis formulations.
Supply Chain Analysis
Inventory cycles of 120-180 days for recombinant phenylalanine ammonia lyase reflect single-source dependencies on Chinese-sourced fermentation media and German-engineered purification resins. Supply concentration centers on Belgium for viral-vector manufacturing, Massachusetts for plasmid DNA production, and Bavaria for enzyme fill-finish operations. Raw material dependencies include porcine-derived gelatin alternatives, chromatography-grade salts, and pharmaceutical-grade amino acid precursors. Single-source vulnerability in AAV capsid supply creates bottleneck risk for gene therapy candidates. Distribution runs through direct manufacturer-to-clinic channels for medical foods and specialty pharmacy networks for injectable biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PKU therapeutics market functions as a defensive-moat arena where regulatory entrenchment through FDA orphan drug exclusivity and EMA priority medicines pathways erects decade-long barriers against commoditization.
For Market Incumbents: Fortify manufacturing infrastructure through captive viral-vector capacity in Belgium or Massachusetts to insulate against plasmid DNA supply shocks. Deepen pediatric metabolic clinic network control through exclusive formulary partnerships with Boston, Philadelphia, and London academic centers, neutralizing emerging synthetic biology entrants before they achieve regulatory validation. For New Entrants and Emerging Players: Remote patient monitoring service gaps in home care settings offer white-space entry points where incumbents under-serve adherence tracking and dietary compliance optimization. Target France and Germany for first European market entry, exploiting HAS and G-BA reimbursement frameworks that favor demonstrated neurocognitive endpoints over legacy dietary protocols. Pursue digital phenylalanine biosensor companion development as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical parents with dormant rare disease metabolic assets lacking gene therapy platform integration. Five-to-ten year viability hinges on clinical pipeline progression toward permanent phenylalanine hydroxylase restoration rather than chronic enzyme supplementation. Monitor FDA regenerative medicine advanced therapy designation velocity as inflection signal for gene therapy capital allocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | Belgian and Massachusetts viral-vector facilities anchor AAV supply security for liver-directed candidates. |
| Regulatory Approval Pathway | FDA regenerative medicine advanced therapy and EMA priority medicines designations compress neurocognitive endpoint timelines. |
| Digital Phenylalanine Monitoring Integration | Continuous biosensor platforms paired with dosing algorithms enable adherence-linked reimbursement models in Germany. |
| Pediatric Metabolic Clinic Network Expansion | Boston, Philadelphia, and London centers consolidate prescriber influence and clinical trial patient access. |
| Pipeline Diversification | Ex vivo hematopoietic stem cell modifications hedge against liver-directed AAV immunogenicity risks in classical PKU. |
Research Methodology
Operator-level perspectives from pediatric metabolic specialists, regulatory affairs leads at gene therapy developers, formulary directors at German G-BA and French HAS, and hospital procurement managers anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation from FDA orphan drug designations, EMA advanced therapy medicinal products submissions, ClinicalTrials.gov enrollment data, and national newborn screening mandate databases. Bottom-up patient population modeling and top-down therapeutic category spend analysis triangulated market sizing.
Sensitivity analysis across enzyme engineering success rates, viral-vector manufacturing yield assumptions, and reimbursement approval probabilities framed forecast confidence intervals. Segmentation dimensions modeled encompassed treatment modality, delivery mode, disease severity indication, and regional regulatory cluster. CAGRs derived from patient cohort flow analysis, pricing trajectory assumptions indexed to biologics manufacturing cost curves, and adoption curve modeling for gene therapy transition. Forecast inputs incorporated newborn screening mandate expansion schedules and pediatric metabolic clinic network capacity constraints.
Underlying assumptions cover regulatory pathway timelines, manufacturing yield improvements, and payer reimbursement thresholds, with deviation risk concentrated in gene therapy immunogenicity events and viral-vector supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Glioma Therapeutics Market
Specialty Medicine
Adult Malignant Glioma Therapeutics Market
Specialty Medicine
Asia-Pacific Sports Medicine Market
Specialty Medicine
Marfan Syndrome Treatment Market
Specialty Medicine
Balantidiasis Treatment Market
Specialty Medicine
Mental Retardation Treatment Market
Specialty Medicine
Thoracic Outlet Syndrome Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
Angioimmunoblastic T-Cell Lymphoma (AILT) Market
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
TMJ Disorders Market
Specialty Medicine
Global Gastroesophageal Reflux Disease Market
Specialty Medicine
Liver Fibrosis Treatment Market