
 Hereditary Angioedema Market | 2026-2036
Hereditary Angioedema Market Size, Share, and Industry Trends Forecast 2026-2036
Hereditary Angioedema Market Intelligence
Subcutaneous delivery technology is reconfiguring how prophylactic therapies reach hereditary angioedema patients, shifting administration from hospital-based infusion suites to home self-injection protocols. Takeda Pharmaceutical Company Limited leverages its established plasma-derived C1 inhibitor portfolio to sustain market presence across both acute and preventive care settings. BioCryst Pharmaceuticals Inc. differentiates through oral kallikrein inhibitor technology, competing directly against injectable alternatives with a convenience profile that anchors patient preference in long-term prophylaxis.
Hereditary angioedema constitutes a rare genetic disorder characterized by recurrent, unpredictable swelling attacks driven by uncontrolled plasma kallikrein activity and excessive bradykinin generation, with C1 inhibitor deficiency or dysfunction as the underlying biochemical defect. The condition demands continuous therapeutic intervention to prevent life-threatening laryngeal attacks and reduce the burden of cutaneous or abdominal episodes that disrupt employment and daily function. Plasma-derived C1 inhibitor concentrates retain established reimbursement pathways and physician familiarity, though subcutaneous delivery modes are capturing faster growth as home administration reduces healthcare utilization costs. Oral therapies represent an emerging structural segment where margin pools concentrate, given their potential to displace both intravenous and subcutaneous prophylaxis through superior patient adherence.
The FDA orphan drug framework and EMA's parallel designation for rare disease therapies shape clinical trial design incentives and extended market exclusivity periods that protect novel entrants. Health technology assessment bodies in Germany, France, and England apply distinct cost-effectiveness thresholds that fragment pricing and access negotiations across major European markets. Stakeholders must monitor gene editing pipeline progress from Intellia Therapeutics Inc. and other developers, as curative approaches would fundamentally alter the preventive treatment paradigm and reshape commercial assumptions for chronic therapy manufacturers.
Market Dynamics
The migration from hospital-based infusion to home self-administration is restructuring patient access economics and reordering competitive advantage between subcutaneous and oral prophylactic modalities.
Growth Catalysts
- FDA Orphan Drug Exclusivity:Extended market protection periods incentivize novel therapeutic development for rare disease indications, accelerating pipeline investment in kallikrein inhibitors and gene editing approaches.
- Home Administration Technology:Prefilled subcutaneous autoinjector devices eliminate cold-chain complexity and reduce nursing dependency, expanding addressable patient populations beyond major metropolitan centers.
- Germany's AMNOG Process:Early benefit assessment pathways for orphan drugs create predictable reimbursement timelines that support commercial planning for European market entry.
Market Restraints
- Plasma Supply Concentration:Dependence on US and European plasma collection networks creates vulnerability to donor availability fluctuations and geographic supply disruptions.
- EMA Conditional Approval Burden:Post-authorization study requirements impose ongoing clinical trial obligations that strain development budgets for smaller manufacturers.
- Biologic Manufacturing Complexity:C1 inhibitor production requires specialized fractionation capabilities that limit contract manufacturing options and extend scale-up timelines.
Strategic Opportunities
- Japan's Sakigake Designation:Priority review and dedicated consultation pathways for innovative therapies reduce time-to-market for first-in-class oral prophylactics in Asia's second-largest pharmaceutical market.
- Specialty Pharmacy Networks:Direct-to-patient distribution through accredited specialty pharmacies bypasses traditional hospital pharmacy gatekeepers and captures margin from channel consolidation.
- Gene Editing Convergence:CRISPR-based in vivo editing platforms targeting the SERPING1 locus offer potential curative intervention that would displace chronic prophylactic therapy paradigms entirely.
Industry Challenges
- Rare Disease Trial Recruitment:Small patient populations across dispersed geographies extend enrollment timelines and complicate statistical powering for pivotal efficacy studies.
- Reimbursement Evidence Generation:Payers demand real-world effectiveness data that manufacturers struggle to produce before launch, creating access delays for novel mechanisms.
- Legacy System Integration:Hospital electronic health record systems require custom interoperability builds for patient monitoring apps that support home-based therapy management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hereditary Angioedema Market |
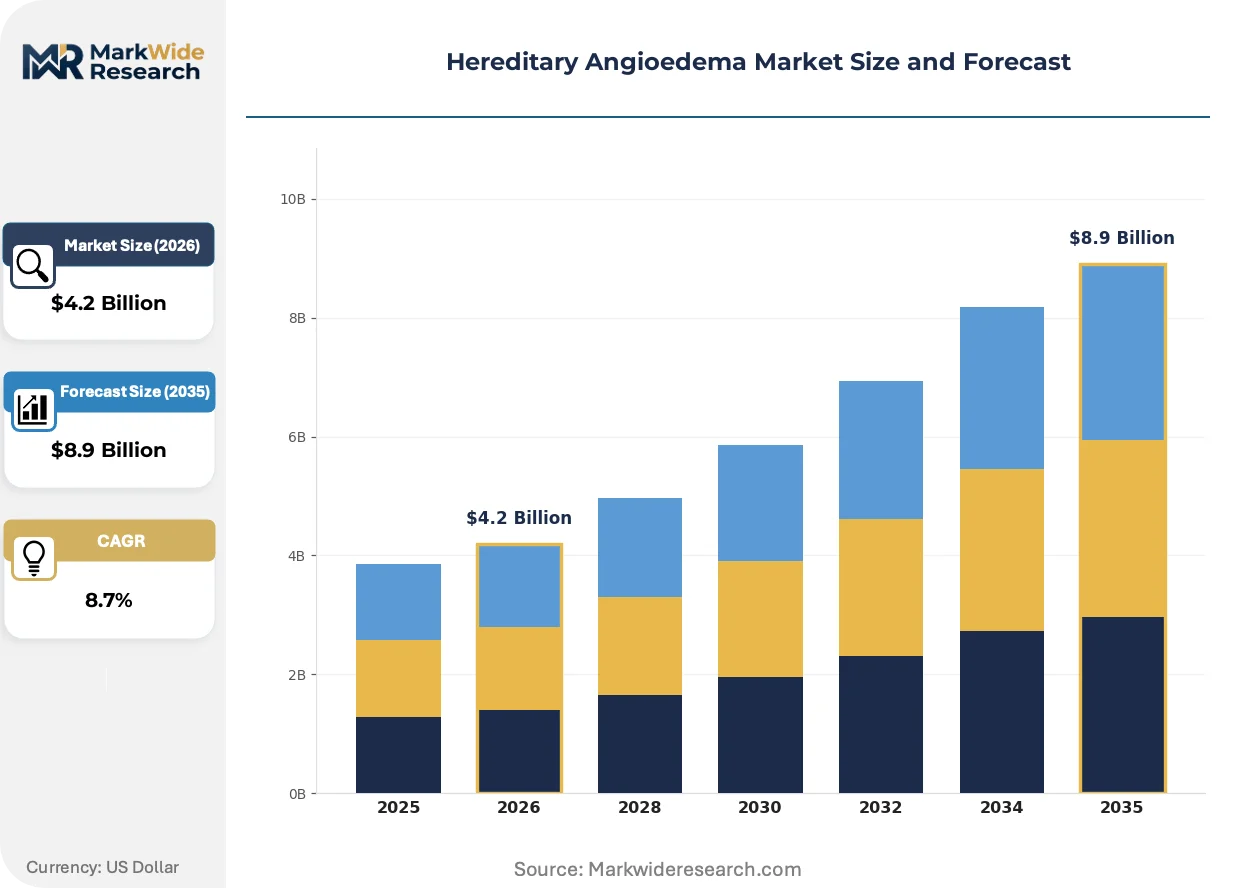
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $8.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exacta, C1 Inhibitor Concentrate, Plasma-Derived C1 Inhibitor, Other Therapies Delivery Mode: Subcutaneous, Intravenous, Oral, Other Methods End User: Hospitals, Clinics, Home Care Settings, Pharmaceuticals Application: Acute Treatment, Preventive Treatment, Diagnosis, Research |
| Companies Covered | Takeda Pharmaceutical Company Limited, CSL Behring, BioCryst Pharmaceuticals Inc., Pharming Group N.V., KalVista Pharmaceuticals Inc., Ionis Pharmaceuticals Inc., Sanofi S.A., Intellia Therapeutics Inc., Pharvaris N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hereditary Angioedema Market Strategic Shifts & Innovations
Oral small-molecule prophylactics are compressing the addressable market for injectable therapies by eliminating cold-chain logistics and reducing treatment burden for patients managing chronic disease.
Subcutaneous C1 inhibitor formulations with extended half-lives are rendering obsolete the twice-weekly intravenous infusion protocols that previously anchored hospital-based treatment models. Patients in the United States and Germany are transitioning to home autoinjector systems at accelerating rates. This shift is compressing specialty infusion center utilization and redirecting reimbursement flows toward pharmacy benefit managers.
EMA's orphan drug regulation revisions are tightening evidentiary standards for market exclusivity extensions, forcing manufacturers to demonstrate superior efficacy rather than incremental formulation improvements. Companies now face mandatory comparative effectiveness requirements that extend development timelines. Plasma-derived product manufacturers in Europe are responding by accelerating biosimilar defense strategies and indication expansion programs.
Patient advocacy organizations are consolidating purchasing influence through centralized assistance programs that negotiate directly with manufacturers on behalf of underinsured populations. These programs in the United States are displacing traditional patient services models with outcome-guaranteed arrangements. The restructuring concentrates volume through fewer access channels and intensifies price transparency pressures on list pricing strategies.
Hereditary Angioedema Market Segmentation
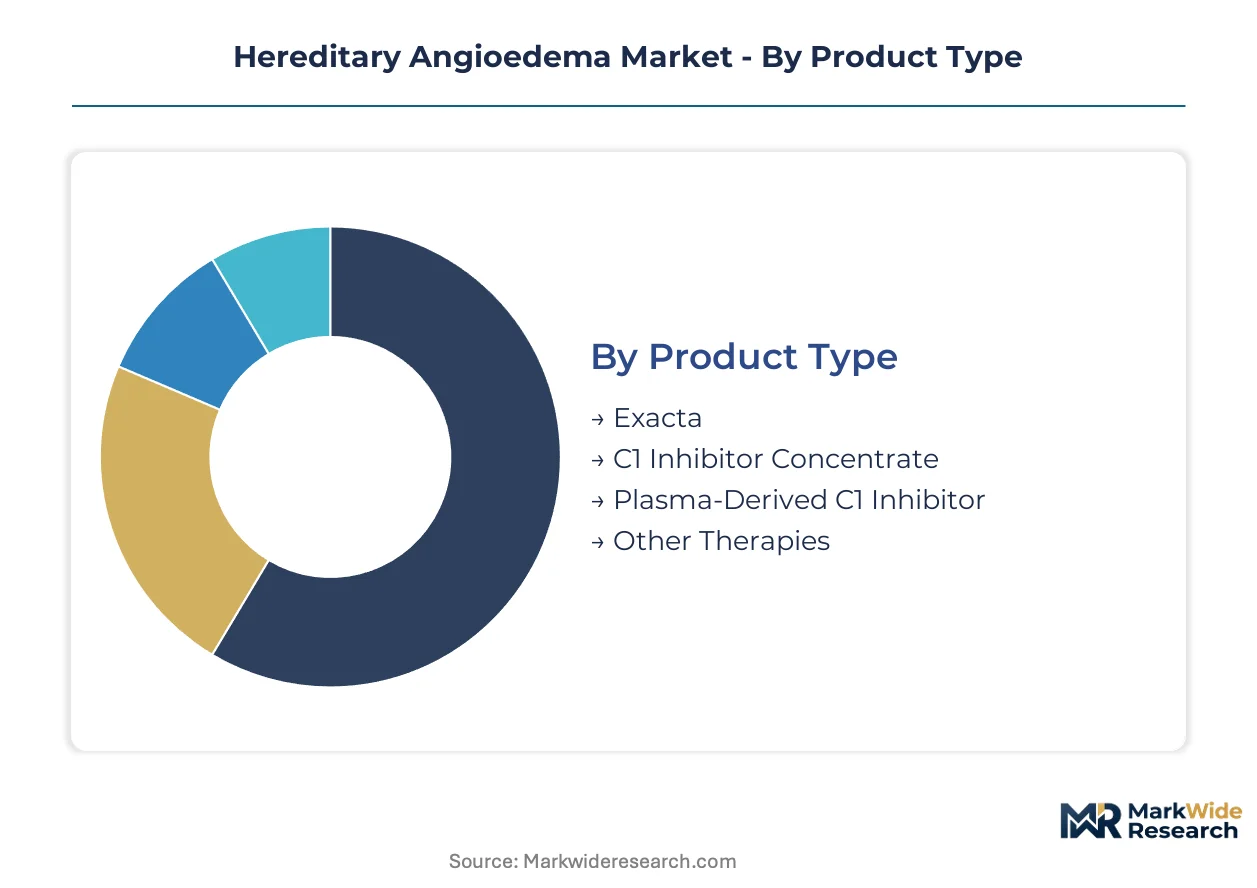
Segmentation in hereditary angioedema reveals how treatment modality choices directly shape patient adherence patterns and reimbursement economics. Product formulation and delivery technology decisions determine whether therapy remains hospital-dependent or migrates to autonomous home administration.
Product Type:
Cycle times vary sharply across this category, with plasma-derived products turning inventory slowly due to fractionation complexity while synthetic kallikrein inhibitors move through distribution channels rapidly.
- C1 Inhibitor Concentrate:Recombinant and plasma-derived formulations restore functional C1 inhibitor levels to interrupt bradykinin-mediated swelling cascades. Demand concentrates in Germany and the United States where specialty pharmacy networks have built cold-chain distribution infrastructure for biologic therapies.
- Plasma-Derived C1 Inhibitor:Human plasma fractionation yields concentrated C1 inhibitor with established immunogenicity profiles and decades of clinical documentation. Manufacturing depends on US and European plasma collection networks, creating supply vulnerability during donor availability fluctuations.
- Exacta:Novel formulation technology targeting extended half-life pharmacokinetics to reduce dosing frequency.
- Other Therapies:Androgen derivatives and antifibrinolytic agents retained for specific patient subpopulations with contraindications to first-line options.
Plasma-derived C1 inhibitor dominates installed base. C1 inhibitor concentrate is where expansion concentrates.
Delivery Mode:
Cost tier stratification separates hospital-dependent intravenous administration from premium-priced home injection systems and emerging oral alternatives.
- Subcutaneous:Prefilled autoinjector devices enable patient self-administration without nursing supervision or infusion suite scheduling. Home care adoption in the United States accelerates as pharmacy benefit managers prefer reduced medical benefit utilization.
- Oral:Small-molecule kallikrein inhibitors eliminate injection burden and cold-chain logistics entirely. Patient preference data from US treatment centers indicates strong willingness to switch from injectable prophylaxis for convenience-equivalent efficacy.
- Intravenous:Hospital-based infusion protocols retain role for acute attack termination where rapid bioavailability remains critical.
- Other Methods:Investigational depot formulations and gene therapy delivery mechanisms in preclinical development.
Intravenous administration dominates installed base. Oral delivery is where expansion concentrates.
End User:
Volume concentration tracks reimbursement pathway fragmentation, with site-of-care decisions increasingly driven by payer preference rather than clinical necessity.
- Home Care Settings:Self-administered subcutaneous and oral therapies shift treatment location from clinical facilities to patient residences. Germany's AMNOG process and US Medicare Part D coverage create predictable reimbursement for home-based biologic delivery.
- Hospitals:Acute attack management and intravenous prophylaxis administration retain concentration in tertiary centers with emergency airway capabilities. Laryngeal edema protocols require immediate intubation access that community settings cannot replicate.
- Clinics:Outpatient infusion centers serve patients without home injection confidence or insurance authorization for self-administration.
- Pharmaceuticals:Contract manufacturing organizations and specialty distributors handling cold-chain logistics.
Hospitals dominate installed base. Home care settings is where expansion concentrates.
Application:
Maturity differentiation separates well-established acute intervention protocols from emerging preventive treatment paradigms that reshape lifetime therapy economics.
- Preventive Treatment:Long-term prophylaxis reduces attack frequency and severity in patients with frequent or severe episodes. US treatment guidelines now recommend preventive therapy for most diagnosed patients regardless of attack history, expanding addressable population.
- Acute Treatment:On-demand therapy terminates active attacks through C1 inhibitor replacement or bradykinin pathway blockade. Emergency department utilization in the United States remains substantial despite preventive therapy expansion.
- Diagnosis:C4 complement level testing and C1 inhibitor functional assays confirm hereditary angioedema subtype classification.
- Research:Clinical trial infrastructure and natural history study enrollment supporting pipeline development.
Acute treatment dominates installed base. Preventive treatment is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty infusion centers and home care networks concentrate purchasing power for hereditary angioedema therapies in markets with mature rare disease reimbursement infrastructure. Tertiary care institutions in the United States, Germany, and Japan anchor demand volume through established C1 inhibitor prescribing patterns and prophylaxis protocol adoption.
United States
Pharmacy benefit managers and specialty distributors consolidate procurement for subcutaneous autoinjector therapies across major metropolitan markets. FDA orphan drug exclusivity provisions and priority review vouchers accelerate novel therapeutic entry, with Boston and San Francisco biotech clusters hosting gene editing pipeline developers targeting curative approaches.
Germany
AMNOG early benefit assessment pathways create predictable reimbursement timelines for plasma-derived and recombinant C1 inhibitor products entering statutory health insurance formularies. The country's plasma fractionation infrastructure in Bavaria and Hesse supports domestic manufacturing capacity for established therapies while Berlin-based university hospitals pioneer real-world effectiveness data collection for oral kallikrein inhibitors.
Japan
Sakigake designation for innovative rare disease therapies reduces regulatory review timelines for oral prophylactic candidates seeking market entry ahead of Western approvals. Tokyo and Osaka medical centers concentrate diagnosed patient populations for clinical trial enrollment, with PMDA consultation pathways shaping development strategies for subcutaneous formulation submissions.
United Kingdom
NICE technology appraisals apply distinct cost-effectiveness thresholds for orphan drugs that fragment pricing negotiations from continental European benchmarks. London and Manchester specialist centers coordinate national patient registries supporting natural history studies, while Scottish Medicines Consortium parallel reviews create additional access pathway complexity for manufacturers.
France
ANSM regulatory oversight and HAS transparency commission evaluations determine hospital formulary placement for acute attack therapies and prophylactic protocols. Paris and Lyon university hospital networks maintain laryngeal edema emergency response capabilities that sustain intravenous C1 inhibitor utilization despite home administration trends elsewhere in the market.
Hereditary Angioedema Market Key Industry Players
Channel-controlling players compete with product-specialist players across overlapping territory in hereditary angioedema therapeutics. Plasma fractionation conglomerates with integrated collection networks face pressure from biotechnology developers of oral small-molecule and gene editing platforms. Two strategic archetypes dominate: established biologics manufacturers defending incumbent positions through formulation lifecycle management, and emerging therapy developers pursuing displacement of injectable paradigms through convenience innovation. Competitive moves concentrate on M&A activity targeting rare disease pipeline assets and strategic partnerships securing plasma supply agreements.
Within the plasma-derived therapy tier, Takeda Pharmaceutical Company Limited and CSL Behring occupy positions anchored by decades of clinical documentation and established reimbursement pathways. Among oral therapeutic developers, BioCryst Pharmaceuticals Inc. exemplifies the convenience-driven archetype competing directly against injectable alternatives. Intellia Therapeutics Inc. represents the gene editing convergence strategy that would fundamentally alter preventive treatment economics if curative approaches reach commercialization.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| CSL Behring |
| BioCryst Pharmaceuticals Inc. |
| Pharming Group N.V. |
| KalVista Pharmaceuticals Inc. |
| Ionis Pharmaceuticals Inc. |
| Sanofi S.A. |
| Intellia Therapeutics Inc. |
| Pharvaris N.V. |
| Others |
Cost & Logistics Intelligence
Plasma collection network concentration in the United States and Germany determines both pricing tier spreads and supply chain shape, with donor availability fluctuations creating asymmetric cost pressure across plasma-derived and recombinant product categories.
Pricing Analysis
Cost-plus contracts with plasma cost indexation anchor pricing for C1 inhibitor concentrates, tying list prices to fractionation input costs and donor compensation trends. Three-tier pricing structure across premium, standard, and economy levels separates recombinant formulations from plasma-derived alternatives and legacy androgen derivatives. Pricing pressure stems from pharmacy benefit manager consolidation and outcome-guaranteed patient assistance programs. Uninsured and underinsured patient populations exhibit highest price sensitivity, while commercially insured patients with specialty pharmacy networks show lowest sensitivity due to copay assistance structures.
Supply Chain Analysis
Export control regimes on plasma fractionation technology limit equipment and know-how flows to emerging manufacturing regions, constraining supply expansion outside established networks. Manufacturing concentrates in the United States, Germany, and Austria where fractionation infrastructure and cold-chain logistics are mature. Production draws from US and European plasma collection networks, recombinant cell line bioreactors, and synthetic small-molecule chemical synthesis. Single-source vulnerability runs through concentrated plasma collection sites and specialized albumin-free formulation capabilities. Distribution runs through specialty pharmacy networks and hospital-based infusion centers with temperature-controlled logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized plasma fractionation expertise and gene editing platform capabilities constitute scarce assets that will determine competitive outcomes as curative approaches advance toward clinical validation.
For Market Incumbents: Insulate plasma-derived revenue streams by securing long-term donor collection agreements and accelerating biosimilar defense strategies in European markets. Invest in subcutaneous formulation lifecycle extensions to delay oral therapy displacement. EMA orphan drug regulation revisions threaten exclusivity extensions without comparative efficacy demonstrations. For New Entrants and Emerging Players: Build out oral small-molecule prophylactic portfolios targeting patients with needle aversion and cold-chain access limitations. Japan's Sakigake designation pathway offers fastest regulatory timeline for first-in-class submissions. Penetrate specialty pharmacy direct-to-patient channels to bypass hospital formulary gatekeepers. For Investors and Strategic Acquirers: FDA gene therapy breakthrough therapy designation reshapes the acquisition landscape by accelerating curative pipeline timelines and compressing chronic therapy valuation windows. Target platform-stage gene editing developers with in vivo liver-targeting delivery capabilities. Watch for SERPING1 knockout efficacy readouts as inflection signal for preventive therapy paradigm disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Gene editing candidates targeting SERPING1 locus require liver-directed delivery optimization to demonstrate durable editing. |
| Regulatory Approval Pathway | Priority review vouchers from FDA accelerate oral kallikrein inhibitor launches ahead of standard timelines. |
| Licensing Agreement | Plasma supply contracts with US collection networks secure fractionation feedstock against donor availability volatility. |
| Manufacturing Scale-Up | Subcutaneous autoinjector production capacity expansion supports home administration transition and pharmacy benefit manager preferences. |
| Pipeline Diversification | Oral prophylactic programs complement injectable portfolios against convenience-driven patient switching. |
Research Approach
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and payer access specialists provided ongoing calibration against secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient population estimates and top-down pharmaceutical revenue triangulation anchored market sizing across treatment modalities.
Scenario-bracketing around regulatory approval timelines, pricing negotiation outcomes, and gene therapy clinical success rates bounded forecast ranges across the analysis window. Segmentation modeling incorporated treatment line, dosage form, administration route, and regional regulatory cluster dimensions. CAGRs derived from patient diagnosis growth, treatment penetration elasticity, and therapy switching dynamics with inputs from natural history registry data and real-world evidence studies.
Stress conditions across plasma supply disruptions, gene therapy regulatory acceleration, and oral therapy pricing compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on patient population growth and reimbursement pathway evolution. Material shifts in curative therapy clinical success or EMA orphan drug evidentiary requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Acute Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Dyschromia Therapeutics Market
Specialty Medicine
Global Eye Allergy Therapeutics Market
Specialty Medicine
Rosacea Therapeutics Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Eosinophilic Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Global Pancreatic Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Hypoactive Sexual Desire Disorder Treatment Market
Specialty Medicine
US Opioid Use Disorder (OUD) Market
Specialty Medicine
Global Hormone Replacement Therapy Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Mantle Cell Lymphoma Market
Specialty Medicine
Global Bile Duct Cancer Market