
 Hemangioma Market | 2026-2036
Hemangioma Market Size, Share, and Industry Trends Forecast 2026-2036
Hemangioma Market Outlook
REACH compliance is restructuring the cost-of-entry calculus for topical hemangioma formulations in Europe, forcing reformulation investments that favor established pharmaceutical manufacturers. Pfizer leverages its global manufacturing scale to distribute beta-blocker therapies across multiple regulatory jurisdictions. Novartis anchors its position through sustained R&D investment in pediatric oncology crossover applications. Cutera specializes in laser-based vascular lesion systems, competing on wavelength precision and treatment safety profiles.
Hemangiomas are benign vascular tumors composed of proliferating endothelial cells that typically present in infancy, with lesions ranging from superficial cutaneous strawberry marks to deep subcutaneous masses requiring imaging-guided intervention. These lesions serve both diagnostic and therapeutic purposes across pediatric medicine, cosmetic dermatology, and reconstructive surgery. Oral medications, particularly systemic beta-blockers, dominate pharmacological intervention while laser therapy captures premium positioning for superficial lesions in cosmetic and pediatric dermatology settings. Surgical interventions retain significance for refractory or function-threatening cases, though minimally invasive modalities are displacing open resection in ambulatory settings where recovery protocols favor same-day discharge.
The FDA's pediatric exclusivity provisions and EMA's Paediatric Investigation Plans shape clinical trial design and market access timelines for hemangioma therapeutics, while the EU MDR raises conformity assessment burdens for laser and surgical device manufacturers. Health Canada and TGA alignment with FDA pediatric study requirements creates parallel submission pathways that compress regulatory lag for multinational sponsors. Stakeholders must monitor evolving reimbursement codes for observation versus active treatment modalities as payors scrutinize the cost-effectiveness of prophylactic intervention against spontaneous regression.
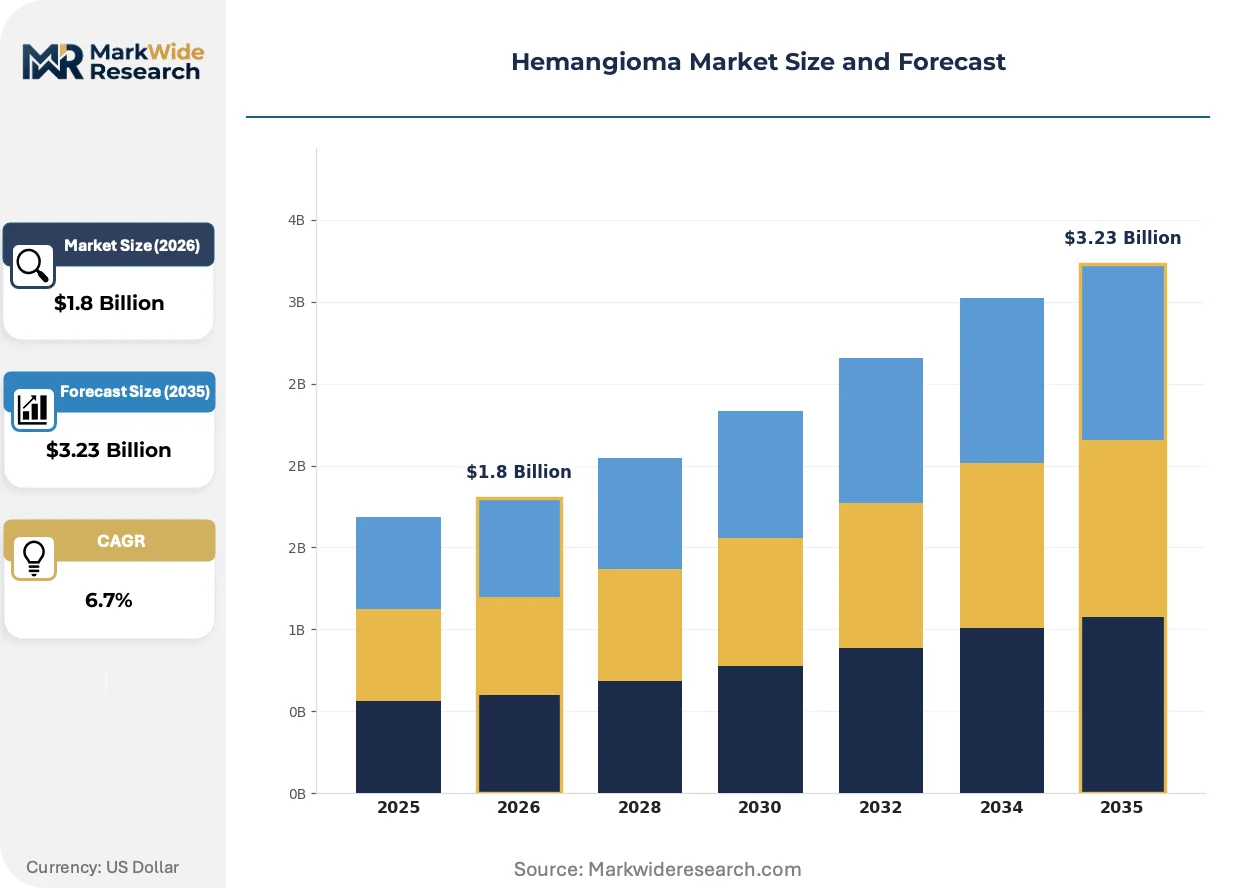
Market Dynamics
Non-invasive treatment protocols are compressing surgical volumes across pediatric dermatology, while regulatory pediatric exclusivity provisions reshape clinical trial economics for hemangioma therapeutics.
Growth Catalysts
- Orphan drug designation:The FDA's accelerated approval pathway reduces development timelines for novel beta-blocker formulations targeting infantile hemangiomas.
- Laser wavelength precision:Advanced pulsed-dye systems enable safer superficial lesion treatment in ambulatory pediatric settings.
- Vascular anomaly center clustering:Metropolitan hospital networks in the United States concentrate specialized expertise and referral volumes.
Market Restraints
- Propranolol supply concentration:Generic beta-blocker API manufacturing concentrates in Indian and Chinese chemical intermediates suppliers.
- EU MDR conformity burdens:Laser device manufacturers face extended notified body review timelines and clinical evidence requirements.
- Spontaneous regression substitution:Observation protocols compete with active intervention for uncomplicated superficial lesions.
Strategic Opportunities
- Pediatric Investigation Plans:EMA's structured development framework offers patent term extensions and market exclusivity incentives for pediatric indications.
- Topical formulation white space:Timolol gel applications address caregiver preference for non-systemic administration in outpatient settings.
- Telemedicine triage integration:Remote lesion assessment platforms expand specialist reach into underserved rural and suburban geographies.
Industry Challenges
- Pediatric dermatology workforce scarcity:Fellowship-trained specialists remain concentrated in academic medical centers, limiting community access.
- Reimbursement code fragmentation:Observation versus active treatment coding disputes create claims denial risk and administrative burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemangioma Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Oral Medications, Surgical Interventions, Laser Therapy Application: Pediatrics, Dermatology, Oncology, Plastic Surgery End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Home Care Treatment Modality: Pharmacological, Surgical, Minimally Invasive, Observation |
| Companies Covered | Pierre Fabre, AstraZeneca, Bristol-Myers Squibb, Novartis, Pfizer, Bayer, AbbVie, Merck & Co., Cutera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemangioma Market Strategic Shifts
Digital diagnostic tools and refined therapeutic modalities are compressing time-to-treatment while elevating safety profiles across pediatric vascular anomaly management.
Multimodal imaging systems combining dermoscopy with near-infrared spectroscopy are integrating depth assessment capabilities into initial clinical evaluation. Pediatric dermatology clinics in the United States adopt these platforms to reduce unnecessary ultrasound referrals. The technology is integrating diagnostic and treatment planning workflows, compressing specialist consultation cycles.
REACH compliance restructuring is forcing topical formulation reformulation investments across European manufacturers. ECHA substance restriction timelines accelerate substitution of certain excipients in hemangioma gels. German and French pharmaceutical suppliers absorb these costs through established regulatory affairs infrastructure.
Parental preference for same-day discharge protocols is reshaping treatment site selection across the United States. Ambulatory surgery centers capture lesion cases previously routed to inpatient facilities. This shift concentrates volume in metropolitan networks with dedicated pediatric anesthesia capabilities.
Hemangioma Market Segmentation
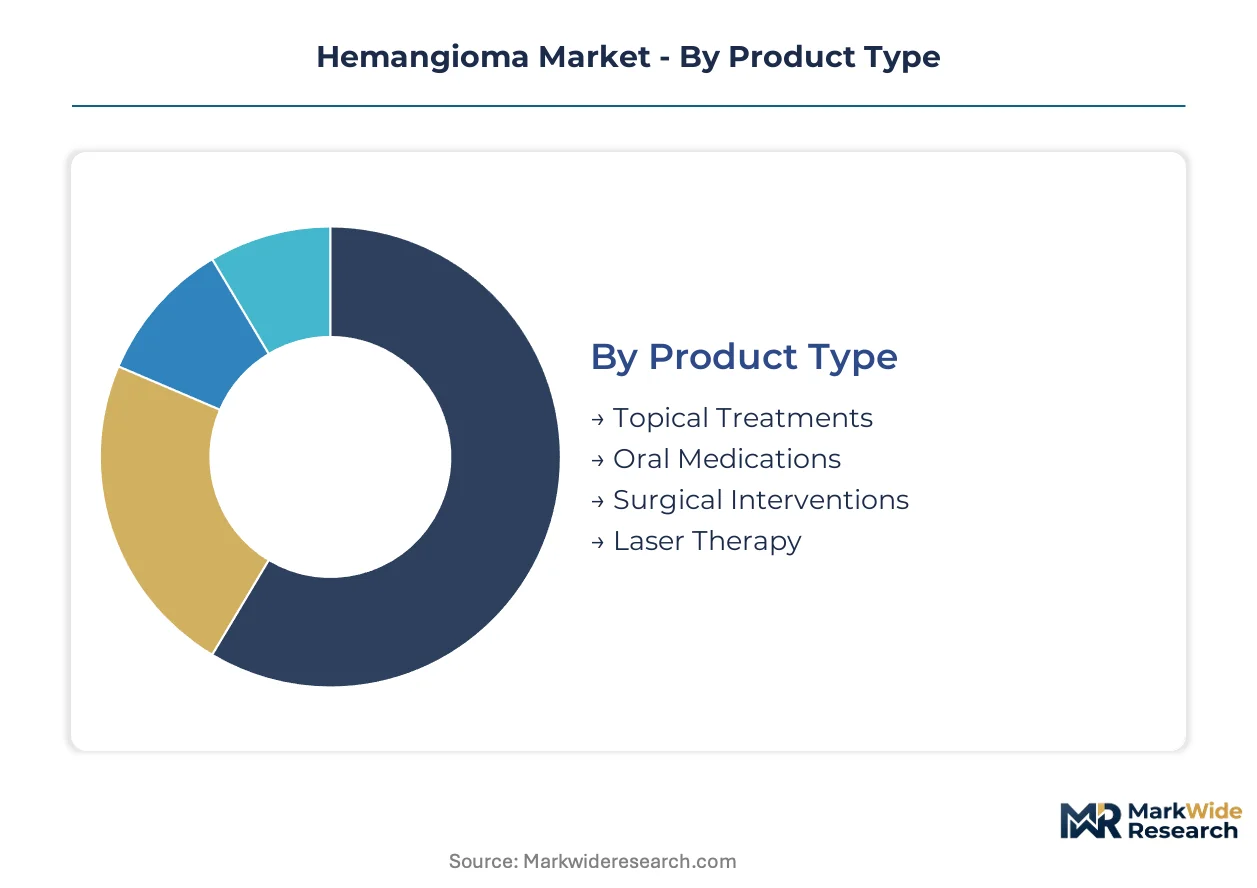
Hemangioma treatment selection depends on lesion depth, patient age, and functional impact. Segmentation reveals how capital requirements and reimbursement structures concentrate volume in specific modalities while newer approaches capture niche growth.
Product Type:
Capital intensity varies sharply across this category, with laser systems requiring substantial upfront equipment investment while pharmaceutical manufacturing spreads fixed costs across broader therapeutic portfolios.
- Oral Medications:Systemic beta-blockers, primarily propranolol formulations, constitute the pharmacological backbone for complicated infantile hemangiomas. Demand concentrates in pediatric wards at metropolitan hospital networks where FDA pediatric exclusivity provisions have compressed generic entry timelines. Manufacturing scale advantages favor established pharmaceutical suppliers with validated API sourcing.
- Laser Therapy:Pulsed-dye and Nd:YAG systems deliver wavelength-specific energy for superficial and deep vascular lesions respectively. Premium positioning in cosmetic dermatology clinics across the United States reflects capital recovery requirements and specialized technician training. Device manufacturers compete on pulse duration precision and integrated cooling systems.
- Topical Treatments:Timolol gel formulations address caregiver preference for non-systemic administration in outpatient settings.
- Surgical Interventions:Open resection retains indication for refractory or function-threatening lesions requiring tissue reconstruction.
Most installed capacity flows through Oral Medications. Expansion is steepest in Laser Therapy.
Application:
Patient age and lesion characteristics determine referral patterns, with pediatric specialists managing the majority of incident cases while adult presentations route through distinct clinical pathways.
- Pediatrics:Infantile hemangiomas present in the first weeks of life, with proliferative phase management dominating clinical volume. Specialized vascular anomaly centers at academic medical centers in the United States cluster diagnostic expertise and coordinate multidisciplinary care. EMA Paediatric Investigation Plans incentivize sponsors to develop age-appropriate formulations.
- Dermatology:Cosmetic and medical dermatology practices manage superficial lesions, residual markings, and adult-onset vascular anomalies. Ambulatory settings in Germany and France leverage integrated dermoscopy platforms to reduce unnecessary imaging referrals. Reimbursement coding distinguishes observation from active intervention.
- Oncology:Kaposiform hemangioendothelioma and other aggressive variants require chemotherapy coordination.
- Plastic Surgery:Reconstructive specialists address residual fibrofatty tissue and contour deformities following involution.
Pediatrics commands the highest case volume. Dermatology is gaining share fastest.
End User:
Site-of-care economics and anesthesia capabilities shape patient routing, with same-day discharge protocols favoring settings with dedicated pediatric infrastructure.
- Hospitals:Tertiary centers manage complicated lesions requiring imaging guidance, systemic therapy monitoring, and multidisciplinary coordination. Major metropolitan networks in the United States concentrate fellowship-trained specialists and handle high-risk cases excluded from community settings. Inpatient capacity supports lesions with airway, orbital, or hepatic involvement.
- Specialty Clinics:Pediatric dermatology and vascular anomaly clinics provide focused expertise with streamlined referral pathways. Academic medical center affiliations enable rapid escalation for treatment failures. Telemedicine triage platforms extend reach into underserved suburban and rural geographies.
- Ambulatory Surgical Centers:Same-day discharge protocols capture lesion cases previously routed to inpatient facilities.
- Home Care:Topical administration and oral beta-blocker regimens shift monitoring responsibilities to caregivers.
Hospitals retain the most complex case mix. Ambulatory Surgical Centers are expanding quickest.
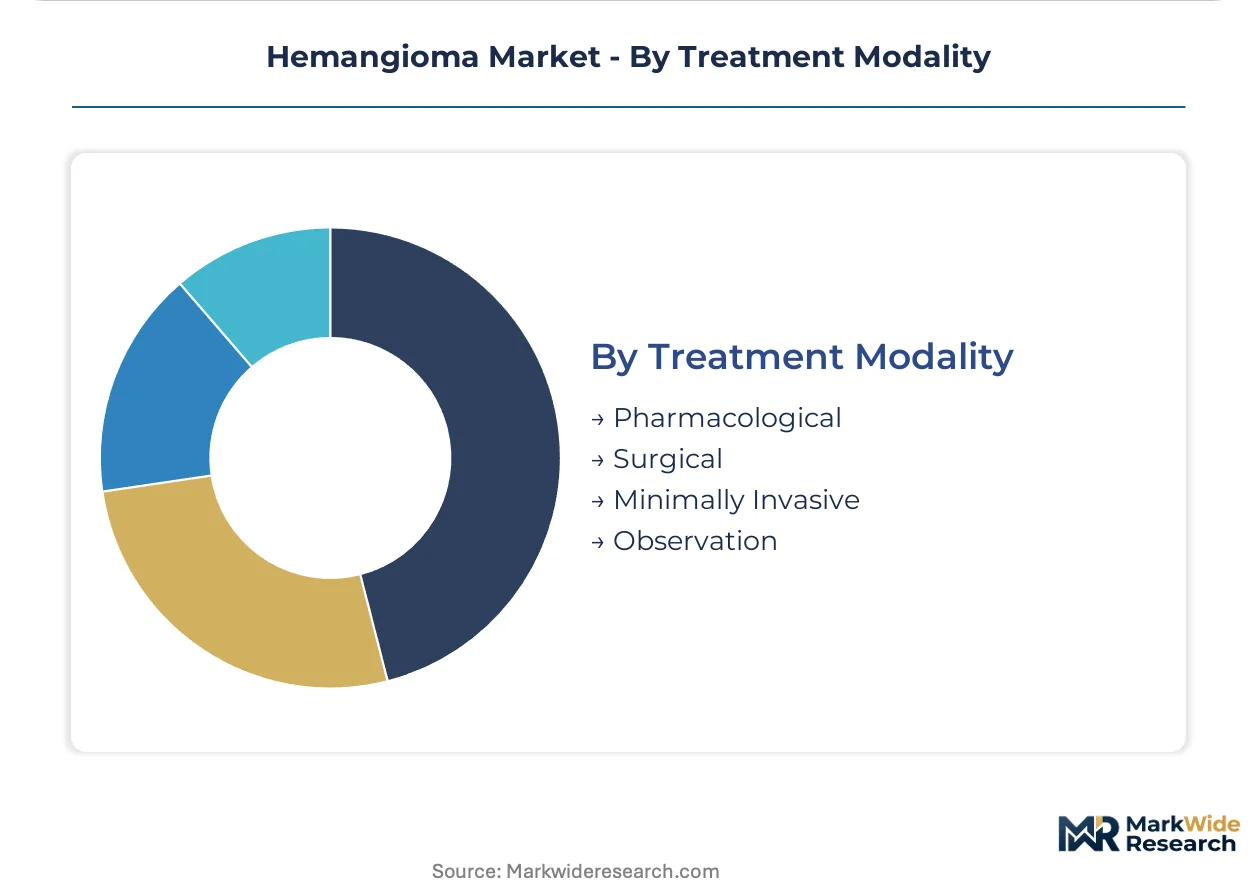
Treatment Modality:
Clinical decision frameworks balance involution probability against functional risk, with observation protocols competing for uncomplicated superficial presentations.
- Pharmacological:Systemic and topical agents target endothelial proliferation through beta-adrenergic blockade and other mechanisms. FDA orphan drug designation has accelerated development timelines for novel formulations. Supply concentration in Indian and Chinese API manufacturers creates procurement risk for generic propranolol.
- Minimally Invasive:Laser and intralesional approaches reduce recovery time compared to open procedures. Pulsed-dye systems dominate superficial lesions while Nd:YAG addresses deeper components. EU MDR conformity assessment burdens extend review timelines for device manufacturers.
- Surgical:Excision and reconstruction retain indication for refractory, ulcerated, or function-threatening lesions.
- Observation:Expectant management competes for uncomplicated superficial hemangiomas with high spontaneous regression probability.
Pharmacological approaches handle the most patients. Minimally Invasive modalities are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fellowship-trained pediatric dermatologists cluster in the United States, Germany, Japan, India, and France, anchoring regional treatment capacity and referral patterns for hemangioma management.
United States
Metropolitan hospital networks concentrate specialized vascular anomaly centers in Boston, New York, and Los Angeles. FDA pediatric exclusivity provisions compress generic entry timelines for propranolol formulations. Academic medical centers in these cities coordinate multidisciplinary care for complicated lesions requiring systemic therapy monitoring.
Germany
Integrated dermoscopy platforms reduce unnecessary imaging referrals in outpatient dermatology practices across Bavaria and North Rhine-Westphalia. REACH compliance forces reformulation investments for topical hemangioma gels containing restricted excipients. Pharmaceutical suppliers in Frankfurt and Munich absorb regulatory costs through established ECHA liaison infrastructure.
Japan
PMDA alignment with FDA pediatric study requirements creates parallel submission pathways for beta-blocker therapies. METI incentives support domestic manufacturing of laser device components. Tokyo and Osaka medical centers adopt pulsed-dye systems for ambulatory superficial lesion treatment.
India
Generic propranolol API manufacturing concentrates in Gujarat and Maharashtra chemical intermediates suppliers. CDSCO pediatric investigation frameworks accelerate local trial enrollment for multinational sponsors. Mumbai and Hyderabad house contract research organizations managing hemangioma therapeutic development.
France
ANSM oversight of pediatric orphan drug applications streamlines market access for novel beta-blocker formulations. Île-de-France academic hospitals cluster diagnostic expertise for kaposiform hemangioendothelioma cases. Paris-based dermatology practices integrate telemedicine triage for suburban and rural lesion assessment.
Hemangioma Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the hemangioma therapeutic landscape. The market structure splits between established pharmaceutical manufacturers with global distribution scale and device specialists competing on wavelength precision. Three archetypes dominate: diversified pharma conglomerates with pediatric crossover portfolios, laser system specialists with capital-intensive equipment platforms, and generic API suppliers concentrated in Asian chemical manufacturing hubs. Competitive moves center on regulatory pathway optimization for pediatric exclusivity and geographic expansion of vascular anomaly center networks.
Within the diversified pharmaceutical tier, Pfizer and Novartis exemplify scale-driven players leveraging global manufacturing infrastructure across multiple regulatory jurisdictions. Cutera occupies a position among device specialists competing on pulse duration precision and integrated cooling systems. Pierre Fabre represents the mid-cap European pharmaceutical archetype with established pediatric dermatology positioning.
| Leading Market Players |
|---|
| Pierre Fabre |
| AstraZeneca |
| Bristol-Myers Squibb |
| Novartis |
| Pfizer |
| Bayer |
| AbbVie |
| Merck & Co. |
| Cutera |
| Others |
Value Chain & Pricing Dynamics
Captive API sourcing by diversified pharmaceutical conglomerates anchors both supply security and pricing power across beta-blocker hemangioma therapies, while device manufacturers absorb capital recovery requirements through premium service bundling.
Pricing Analysis
Bundled service contracts dominate laser therapy pricing, separating equipment lease arrangements from per-procedure consumables and technician training fees. Price differentiation rests on wavelength precision specifications and integrated cooling system performance. Cost compression in generic propranolol intensifies as Indian and Chinese API suppliers expand manufacturing scale. Community dermatology practices exhibit highest price sensitivity, while academic medical centers prioritize clinical outcome metrics over unit economics.
Supply Chain Analysis
Direct-to-hospital channels handle systemic beta-blocker distribution, with specialty pharmaceutical distributors managing cold-chain logistics for temperature-sensitive formulations. Active pharmaceutical ingredient manufacturing concentrates in India, China, and select European chemical hubs. Laser device assembly draws from Japanese optical component suppliers and German precision engineering facilities. Single-source vulnerability in propranolol API creates procurement risk for generic formulation sponsors. Distribution runs through GPO-negotiated contracts for institutional purchasers and direct sales forces for ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with caregiver preference shifting toward premium safety profiles in pediatric laser systems and orphan-designated pharmaceutical formulations.
For Market Incumbents: Hedge against generic propranolol price erosion by deepening backward integration into API manufacturing or securing exclusive supply agreements with Indian chemical intermediates suppliers. Invest in FDA pediatric exclusivity pathway optimization to compress competitor entry timelines. Fortify vascular anomaly center network relationships through embedded clinical specialist programs.
For New Entrants and Emerging Players: Begin with topical timolol gel formulations in European outpatient settings, where REACH-driven reformulation investments have cleared competitive space for excipient-compliant alternatives. Target suburban dermatology practices in the United States with telemedicine-integrated lesion assessment platforms. Pursue EMA Paediatric Investigation Plan structuring to capture patent term extension incentives.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap laser device specialists because EU MDR conformity burdens are forcing smaller manufacturers toward exit. The five-to-ten year viability window favors platforms with established notified body relationships and installed base service revenue. Monitor FDA orphan drug designation grant velocity as an inflection indicator for therapeutic development pipeline health.
| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA accelerated approval compresses development timelines for novel beta-blocker formulations targeting infantile hemangiomas. |
| EU MDR Conformity Pathway | Extended notified body review timelines favor established laser device manufacturers with clinical evidence portfolios. |
| Pediatric Investigation Plan Structuring | EMA framework offers patent term extensions and market exclusivity incentives for age-appropriate therapeutic development. |
| Telemedicine Triage Integration | Remote lesion assessment platforms extend specialist reach into underserved rural geographies and compress consultation cycles. |
| API Supply Security Investment | Backward integration into Indian and Chinese chemical intermediates manufacturing mitigates procurement concentration risk. |
Study Parameters
Multiple input streams — clinical development databases, regulatory filing records, hospital procurement contracts, and GPO pricing disclosures — were reconciled through systematic cross-validation. Primary interviews with pediatric dermatologists, vascular anomaly center directors, formulary access specialists, and biomedical equipment procurement managers informed demand-side assumptions. Secondary sources included FDA orphan drug designation records, EMA Paediatric Investigation Plan documentation, ClinicalTrials.gov enrollment data, and CMS Medicare reimbursement code analyses. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Data-stream reconciliation across treatment modality, patient age segmentation, and regional regulatory clustering shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume forecasts weighted by reimbursement code evolution and technology adoption curve positioning. Modeled dimensions included lesion depth classification, administration route, site-of-care economics, and pediatric exclusivity incentive capture rates. Forecast inputs incorporated vascular anomaly center network expansion trajectories and REACH-driven formulation reformulation timelines.
Several conditions sit outside the modeled scope, including spontaneous regression rate variability, off-label utilization patterns, and emerging gene therapy pipeline advancement. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and API supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cryptococcosis Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market
Specialty Medicine
Global Liver Cancer Treatment Market
Specialty Medicine
Wet Age-Related Macular Degeneration (Wet AMD) Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Dyschromia Therapeutics Market
Specialty Medicine
Chronic Myelogenous Leukemia Treatment Market
Specialty Medicine
HPV Associated Disorders Market
Specialty Medicine
Rhabdomyosarcoma Treatment Market
Specialty Medicine
Global Photodynamic Therapy Market
Specialty Medicine
Subdural Haematoma Market
Specialty Medicine
Asia-Pacific Sports Medicine Market
Specialty Medicine
Global Autism Spectrum Disorders Market
Specialty Medicine
Balantidiasis Treatment Market
Specialty Medicine
Acute Hepatic Porphyria (AHP) Treatment Market