
 Glucagon Therapy Market | 2026-2036
Glucagon Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Glucagon Therapy Market Analytics
Aftermarket training and support revenue is rewriting profitability expectations for device manufacturers. Novo Nordisk A/S leverages its diabetes care infrastructure to sustain glucagon kit distribution across European and North American channels. Xeris Biopharma Holdings, Inc. anchors its position through ready-to-use liquid glucagon formulations that eliminate reconstitution steps. Eli Lilly and Company competes via integrated diabetes portfolios that bundle insulin and rescue therapy access.
Glucagon therapy encompasses parenteral and non-parenteral formulations of the 29-amino-acid peptide hormone designed to reverse acute hypoglycemia by stimulating hepatic glycogenolysis and raising blood glucose within minutes. Injectable glucagon retains dominant share in hospital and emergency settings where intramuscular administration protocols are standardized, while nasal glucagon captures expanding homecare demand through caregiver-friendly delivery that requires no needle handling. Combination therapy segments show concentrated R&D investment as developers pair glucagon with GLP-1 analogues for metabolic disease applications beyond rescue indications.
The FDA's biologics licensing requirements and the EMA's centralized marketing authorization process shape product development timelines and cross-border commercialization strategies for glucagon manufacturers. ISO 15197 standards for blood glucose monitoring interoperability indirectly influence glucagon device ecosystem design, while WHO essential medicines listings support national procurement programs in lower-income health systems. Stakeholders must monitor evolving GLP-1 drug class expansions that could redefine glucagon's role from standalone rescue therapy toward integrated metabolic management platforms.
Market Dynamics
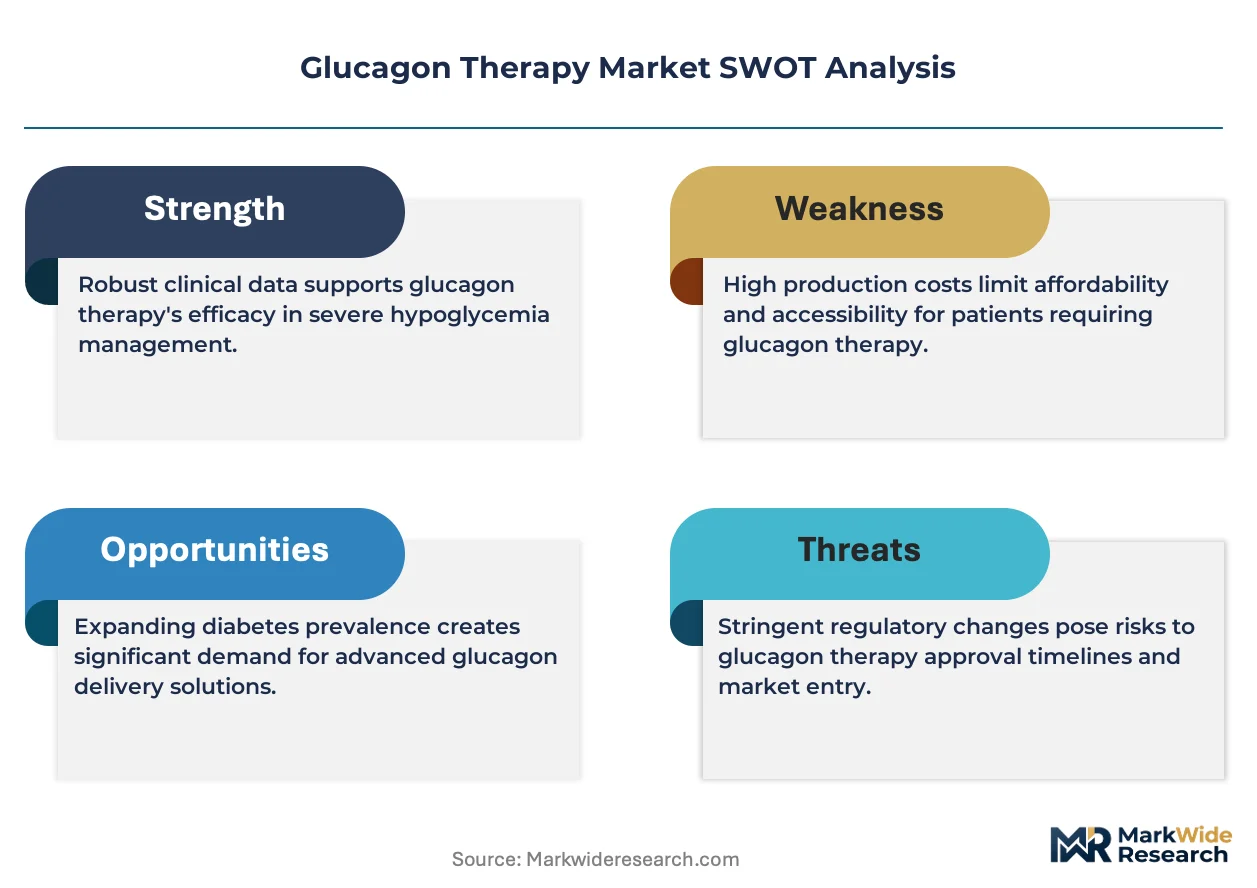
Glucagon therapy is restructuring around ready-to-use formulations that collapse the time-to-treatment window for severe hypoglycemia, with FDA's streamlined biologics pathway accelerating competitive entry and compressing traditional kit-based revenue models.
Growth Catalysts
- Ready-to-use liquid stability:Shelf-stable glucagon formulations eliminate cold-chain dependencies and reconstitution delays, expanding deployment in ambulances and school nurse stations across the United States.
- GLP-1 analogue co-development:Fixed-dose combinations pairing glucagon with semaglutide or tirzepatide analogues are entering Phase II trials for obesity and non-alcoholic steatohepatitis indications.
- Emergency medical services protocol updates:National EMS curricula in the United States now mandate ready-to-use glucagon carriage, institutionalizing demand outside traditional hospital settings.
Market Restraints
- Peptide synthesis cost volatility:Solid-phase manufacturing of synthetic glucagon depends on protected amino acid feedstocks concentrated in Chinese and Indian chemical intermediate suppliers.
- Cold-chain infrastructure gaps:Lyophilized kit formulations still dominate procurement in lower-income health systems where refrigerated distribution remains unreliable.
- Biologics licensing timeline friction:FDA's BLA requirements for novel glucagon formulations impose 18-24 month review cycles that delay market entry relative to small-molecule rescue therapies.
Strategic Opportunities
- Pediatric caregiver segments:Nasal glucagon devices open access to parents and school staff who lack injection training, particularly in United States suburban districts with high Type 1 diabetes incidence.
- Integrated diabetes management platforms:Continuous glucose monitor manufacturers are licensing glucagon rescue algorithms for automated closed-loop systems that predict and preempt severe hypoglycemic events.
- WHO essential medicines procurement:National tenders in sub-Saharan African and South Asian markets are expanding for basic glucagon kits as insulin access programs mature.
Industry Challenges
- Peptide formulation expertise scarcity:Competent process development scientists for glucagon stability engineering command premium compensation in Boston and San Diego biotech clusters.
- Device-API integration complexity:Auto-injector and nasal delivery platform development requires concurrent optimization of glucagon concentration, pH stability, and plume geometry.
- Legacy kit inventory amortization:Distributors face write-down pressure as hospitals accelerate conversion to ready-to-use alternatives before traditional glucagon kits expire.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucagon Therapy Market |
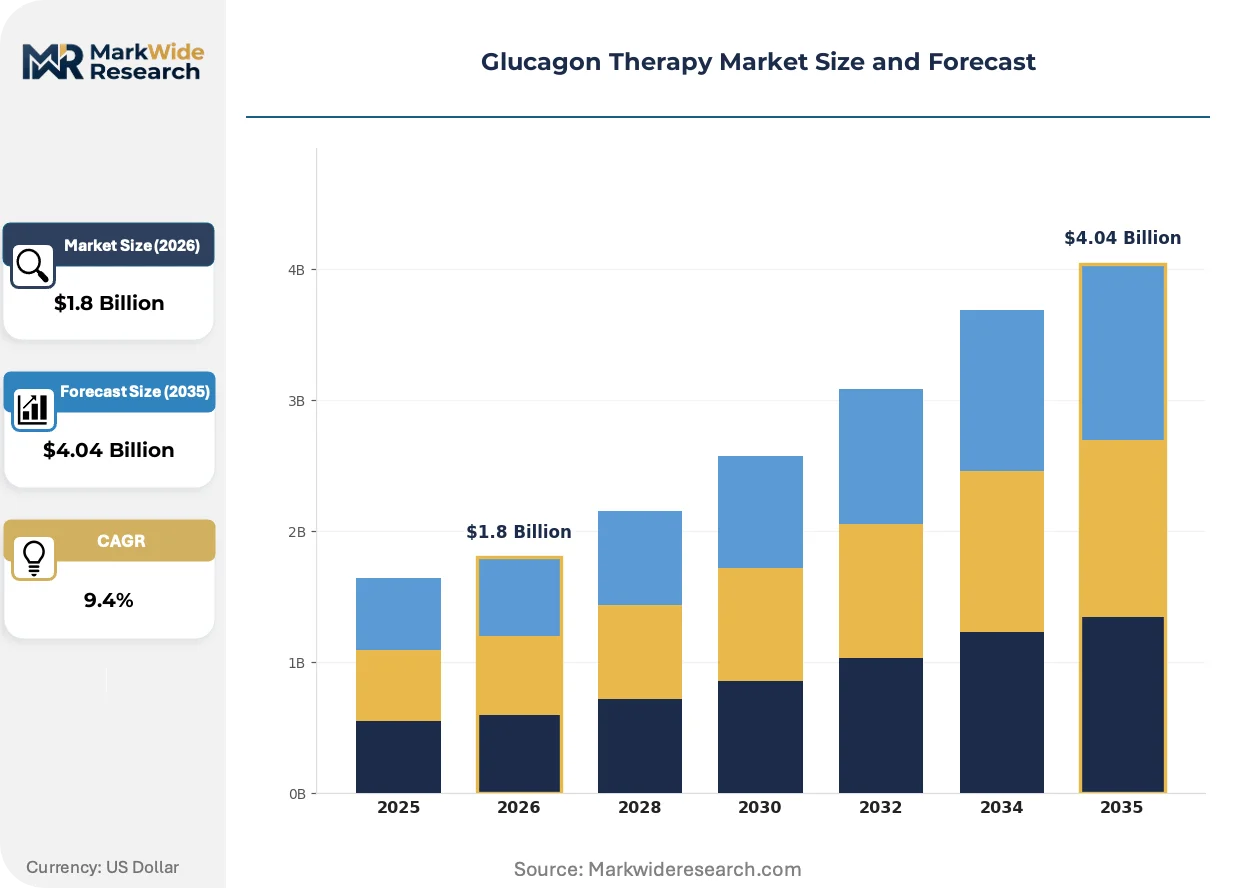
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Glucagon, Nasal Glucagon, Biosimilar Glucagon, Combination Therapy End User: Hospitals, Clinics, Homecare, Emergency Services Delivery Mode: Sublingual, Intramuscular, Intravenous, Subcutaneous Application: Hypoglycemia Treatment, Diabetes Management, Research Applications, Weight Management |
| Companies Covered | Novo Nordisk A/S, Xeris Biopharma Holdings, Inc., Eli Lilly and Company, Fresenius Kabi, Zealand Pharma A/S, Amphastar Pharmaceuticals, Inc., ILS Inc., Taj Pharmaceuticals Limited, United Biotech (P) Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucagon Therapy Market Evolving Landscape
Formulation science and delivery device engineering are converging to displace reconstitution-dependent glucagon kits, while regulatory pathways and procurement models adapt to prioritize speed of administration over unit cost.
Ready-to-use liquid glucagon is hybridizing rescue therapy with chronic disease management infrastructure. Xeris Biopharma's stabilized aqueous formulation enables room-temperature storage for two years, permitting distribution through retail pharmacy channels previously inaccessible to cold-chain biologics. Hospital systems are adopting these formulations for crash cart standardization, while endocrinology practices bundle them with insulin pump prescriptions. The technology is hybridizing acute rescue into longitudinal diabetes care platforms.
EMA's centralized marketing authorization process for emergency-use biologics is compressing cross-border commercialization timelines for glucagon manufacturers. The 2023 revision to MDR Annex I clarified stability testing requirements for peptide hormones, reducing regulatory uncertainty for novel formulations. European hospital procurement consortia are consolidating tender specifications around ready-to-use criteria, pressuring legacy kit suppliers to reformulate or exit.
Caregiver-administered rescue is displacing patient self-injection as the dominant use case for glucagon delivery. School districts and assisted living facilities now specify nasal or autoinjector devices in their emergency preparedness mandates, rejecting traditional syringe-based kits that require assembly under stress. This behavioral shift concentrates demand in devices with minimal training requirements, particularly visible in United States Medicare Advantage plans that cover rescue glucagon without prior authorization.
Glucagon Therapy Market Segmentation
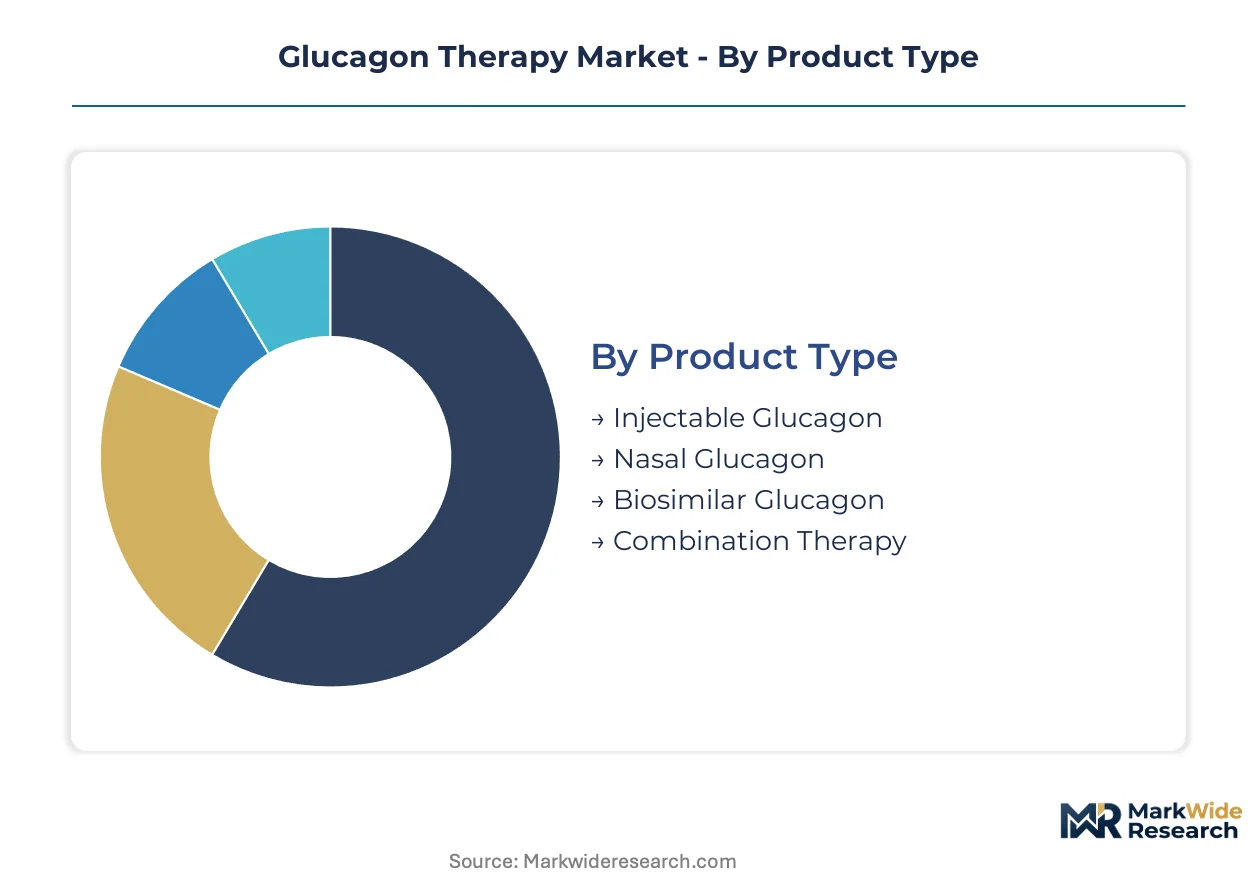
Glucagon therapy segmentation reveals divergent margin profiles across delivery platforms, with device-integrated formulations commanding premium pricing and aftermarket service revenue streams. Manufacturers calibrate portfolio investments based on reimbursement tiers and emergency-use certification requirements that vary by delivery complexity.
Product Type:
After-sales-service intensity peaks in device-dependent segments where training, calibration, and replacement programs generate recurring revenue exceeding initial hardware margins.
- Injectable Glucagon:Lyophilized powder requiring reconstitution with sterile water remains the cost baseline for institutional procurement. Hospital systems in the United States favor this format for crash cart standardization despite reconstitution delays, driven by established reimbursement codes and familiar nursing protocols.
- Nasal Glucagon:Ready-to-use powder formulation delivered through intranasal device eliminates needle handling and reduces caregiver training burden. Demand concentrates in United States school districts and assisted living facilities where untrained administrators must execute rescue under stress, with Medicare Advantage plans now covering these devices without prior authorization.
- Biosimilar Glucagon:Follow-on biologics referencing originator peptide sequences offer unit cost reductions for cash-constrained health systems.
- Combination Therapy:Fixed-dose formulations pairing glucagon with GLP-1 analogues target metabolic disease applications beyond acute rescue indications.
By volume, Injectable Glucagon leads. By growth pace, Nasal Glucagon is ahead.
End User:
Cost tier stratification separates institutional buyers with centralized procurement from dispersed homecare purchasers where out-of-pocket sensitivity shapes brand selection.
- Hospitals:Inpatient and emergency departments maintain standardized protocols for severe hypoglycemia reversal. United States health systems prioritize ready-to-use formulations for code cart deployment, with formulary committees weighing device training costs against time-to-treatment metrics.
- Homecare:Patients and caregivers administer rescue therapy outside clinical supervision. United States suburban districts with high Type 1 diabetes incidence drive demand for intuitive devices, with endocrinology practices bundling rescue prescriptions with insulin pump initiations.
- Clinics:Outpatient endocrinology and primary care settings stock rescue therapy for patient education and emergency preparedness.
- Emergency Services:Ambulance and first-responder protocols mandate carriage of hypoglycemia reversal agents.
Institutional purchasers dominate unit volume. Homecare channels are expanding most quickly as device simplification enables patient-directed acquisition.
Delivery Mode:
Application context determines route selection, with speed of onset and administrator skill level driving protocol decisions across care settings.
- Intramuscular:Injection into deltoid or thigh muscle delivers rapid glycemic elevation through established vascular absorption. United States EMS curricula mandate this route for prehospital severe hypoglycemia, with auto-injector devices standardizing administration depth and reducing needlestick risk.
- Subcutaneous:Injection into adipose tissue offers alternative for patients with adequate perfusion and trained caregivers. United States diabetes camps and recreational programs favor subcutaneous auto-injectors for counselor-administered rescue where medical oversight is limited.
- Sublingual:Mucosal absorption through oral cavity formulations eliminates injection entirely.
- Intravenous:Direct vascular delivery reserved for hospital settings with continuous monitoring capability.
Intramuscular administration leads by protocol penetration. Sublingual formats are gaining share fastest as formulation stability improves.
Application:
Customer type segmentation separates acute rescue indications with episodic demand from chronic management applications requiring sustained engagement.
- Hypoglycemia Treatment:Acute reversal of severe insulin-induced glucose depletion constitutes the foundational indication. United States emergency departments document this application in over 95% of glucagon administrations, with quality metrics tracking time from arrival to glycemic recovery.
- Diabetes Management:Integration into closed-loop systems and bundled care protocols positions glucagon as longitudinal therapy component. Continuous glucose monitor manufacturers in the United States are licensing rescue algorithms for predictive hypoglycemia prevention, expanding addressable use cases beyond reactive rescue.
- Research Applications:Academic and pharmaceutical studies employ glucagon for metabolic pathway investigation and device validation.
- Weight Management:Emerging applications in obesity pharmacotherapy leverage glucagon's anorectic and thermogenic effects.
Hypoglycemia Treatment dominates current utilization. Diabetes Management shows the steepest expansion trajectory as sensor-integrated systems mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in cash-constrained health systems exhibit acute price sensitivity toward lyophilized kit formulations, while United States institutional purchasers prioritize time-to-treatment metrics over unit cost. Emergency medical services protocol standardization accelerates ready-to-use adoption in affluent markets. Regulatory pathway efficiency varies sharply by jurisdiction.
United States
FDA's streamlined biologics licensing pathway compresses product entry timelines for emergency-use formulations. National EMS curricula now mandate ready-to-use glucagon carriage, institutionalizing demand outside hospital settings. Boston and San Diego biotech clusters concentrate peptide formulation expertise, with process development scientists commanding premium compensation.
Germany
EMA's centralized marketing authorization process reduces cross-border commercialization friction for novel glucagon formulations. Hospital procurement consortia consolidate tender specifications around ready-to-use criteria, pressuring legacy kit suppliers. The Rhine-Ruhr industrial corridor anchors pharmaceutical distribution infrastructure serving Central European markets.
United Kingdom
NICE technology appraisals increasingly weight caregiver-administered rescue capabilities in reimbursement decisions. MHRA post-Brexit regulatory autonomy enables accelerated approval timelines for stabilized aqueous formulations. London's healthcare innovation district attracts diabetes device ecosystem partnerships.
India
CDSCO's evolving biologics framework shapes import substitution strategies for domestic glucagon manufacturing. Insulin access program maturation drives national tender expansion for basic rescue kits in sub-Saharan African and South Asian markets. Hyderabad and Mumbai pharmaceutical clusters develop peptide synthesis capabilities for export markets.
Japan
PMDA's orphan drug designation pathway accelerates pediatric hypoglycemia rescue therapy approvals. Aging demographics expand assisted living facility demand for intuitive nasal delivery devices. The Kanto region's medical device manufacturing base supports auto-injector platform development.
Glucagon Therapy Market Competitive Landscape
Integrated diabetes care conglomerates and specialized rescue therapy developers split the market along portfolio breadth versus formulation depth lines. The vendor base concentrates around three strategic archetypes: pharmaceutical majors leveraging existing endocrinology infrastructure, biotech specialists engineering novel stability technologies, and generic manufacturers competing on unit cost for institutional tenders. Dominant competitive moves include strategic partnerships with continuous glucose monitor manufacturers and geographic licensing arrangements for cold-chain-limited markets.
Within the integrated care tier, Novo Nordisk A/S and Eli Lilly and Company exemplify pharmaceutical majors bundling rescue access with chronic disease portfolios. Xeris Biopharma Holdings, Inc. occupies a position representing the specialized stability-engineering archetype. These three entities collectively anchor competitive dynamics across North American and European channels.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Xeris Biopharma Holdings, Inc. |
| Eli Lilly and Company |
| Fresenius Kabi |
| Zealand Pharma A/S |
| Amphastar Pharmaceuticals, Inc. |
| ILS Inc. |
| Taj Pharmaceuticals Limited |
| United Biotech (P) Limited |
| Others |
Value Network & Pricing Analysis
Chinese and Indian chemical intermediate suppliers concentrate protected amino acid feedstock production for solid-phase glucagon synthesis, anchoring margin capture in the peptide manufacturing tier while finished formulation value pools with device-integrated developers in Boston and San Diego.
Pricing Analysis
Aftermarket service contracts and training programs generate lifetime value exceeding initial device margins. Pricing stratifies across premium ready-to-use formulations, standard lyophilized kits, and economy biosimilar tiers. Cost compression in the lyophilized segment is intensifying as hospital systems accelerate conversion to room-temperature stable alternatives. Institutional purchasers exhibit lowest price sensitivity, prioritizing time-to-treatment metrics, while cash-constrained health systems in lower-income markets remain acutely cost-focused.
Supply Chain Analysis
Protected amino acid feedstocks draw from specialized chemical intermediate manufacturers concentrated in China and India. Solid-phase peptide synthesis equipment and lyophilization infrastructure represent critical capital dependencies. Single-source vulnerability in Fmoc-protected amino acid supply creates exposure to geopolitical trade restrictions. Distribution runs through pharmaceutical wholesale networks serving hospital systems and retail pharmacy channels, with cold-chain logistics for traditional kits imposing geographic reach limitations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glucagon therapy market is recovering from cyclical compression in legacy kit valuations as ready-to-use formulations reset revenue models, with FDA's streamlined biologics pathway serving as the cyclical driver accelerating product entry and margin recovery.
For Market Incumbents: Pre-empt biosimilar encroachment by accelerating conversion of hospital formularies to ready-to-use liquid formulations before patent cliffs erode originator peptide pricing. Anchor backward integration into peptide synthesis capabilities to secure feedstock supply against Chinese and Indian intermediate supplier consolidation. Defensive patent thickets around stabilization chemistry represent critical moats.
For New Entrants and Emerging Players: Build out nasal delivery platform expertise targeting United States school district and assisted living facility procurement channels where caregiver-administered rescue mandates create device-specific demand. Pediatric caregiver segments offer the most penetrable white-space, with minimal incumbent presence in untrained administrator training ecosystems. Go-to-market positioning should emphasize Medicare Advantage prior authorization elimination.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty pharma platforms holding legacy glucagon kit portfolios facing inventory amortization pressure. Long-term viability hinges on successful formulation transition to room-temperature stability. Acquisition targets should demonstrate concurrent device-API optimization capabilities. The signal to watch is EMA centralized marketing authorization timeline compression for novel stability technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA's streamlined BLA process for emergency-use biologics accelerates competitive entry timelines. |
| Manufacturing Scale-Up | Peptide synthesis capacity expansion in Boston and San Diego biotech clusters commands premium talent. |
| Strategic Partnership | Continuous glucose monitor licensing agreements integrate glucagon rescue into closed-loop systems. |
| Pipeline Diversification | GLP-1 analogue co-development programs expand addressable indications beyond acute rescue. |
| Reimbursement Strategy | Medicare Advantage prior authorization elimination drives patient-directed acquisition in homecare channels. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up prescription volume modeling and top-down market sizing triangulated across these sources established segment boundaries.
Forecast inputs include treatment line, dosage form, administration route, and regional regulatory cluster segmentation across the projection horizon. CAGRs were derived from modeled adoption curves for ready-to-use formulations and EMS protocol standardization timelines. Peptide synthesis cost trajectories and device-API integration complexity served as industry-specific forecast inputs.
Sensitivities concentrate around FDA review cycle duration, Chinese intermediate supplier pricing volatility, and GLP-1 drug class expansion timelines. Forecasts reflect assumptions about institutional procurement conversion rates and reimbursement policy stability. Cross-checking against CMS Medicare Part B claims data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Vitiligo Treatment Market
Specialty Medicine
North America Cancer Therapy Market
Specialty Medicine
Global Cough Hypersensitivity Syndrome Treatment Market
Specialty Medicine
Stuttering Therapeutics Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Combined Immune Deficiency (CID) Market
Specialty Medicine
Cholangitis Market
Specialty Medicine
Facial Paralysis Market
Specialty Medicine
Global Brain Tumor Therapeutics Market
Specialty Medicine
Infantile Spasms Therapeutics Market
Specialty Medicine
HTLV-1 Associated Myelopathy (HAM) Market
Specialty Medicine
HPV Associated Disorders Market
Specialty Medicine
Global Polycystic Ovarian Syndrome Treatment Market
Specialty Medicine
Global Melanoma Diagnostics and Therapeutics Market
Specialty Medicine
Relapsing-Remitting Multiple Sclerosis (MS) Market
Specialty Medicine
Cirrhosis Management Market