
 Hook Lifts and Skip Loaders Market | 2026-2036
Hook Lifts and Skip Loaders Market Size, Share, and Industry Trends Forecast 2026-2036
Hook Lifts and Skip Loaders Market Analysis
Dealer networks for heavy truck-mounted equipment is narrowing across Western Europe as direct OEM-service contracts capture larger municipal accounts. PALFINGER Group leverages its crane heritage to cross-sell hook lift systems into existing chassis dealer relationships. Marrel Corporation (Ampliroll) anchors its position through specialized hydraulic engineering for high-cycle refuse applications. Meiller Group competes on manufacturing scale at its German production complex, sustaining cost advantages in the 11-15 ton load capacity tier.
Hook lifts and skip loaders are hydraulically actuated truck-mounted mechanisms designed to demount and transport standardized roll-off containers, typically rated for axle loads from 18 to 32 tonnes and operating at pressures exceeding 200 bar. These systems enable rapid container exchange without dedicated lifting infrastructure, serving construction debris removal, commercial waste collection, and material logistics. The hook lift segment dominates equipment value due to higher unit pricing and attachment versatility across chassis brands. Skip loader demand concentrates in municipal services where lower acquisition costs and simpler maintenance protocols align with constrained public budgets. Electric fuel type variants are gaining traction fastest among waste management end users facing urban emissions restrictions, though diesel retains margin depth in heavy-load construction deployments.
EU Green Deal implementation through national regulators is tightening CO2 performance standards for commercial vehicle fleets, directly conditioning hook lift chassis eligibility and retrofit pathways. Germany's KBA enforces type approval requirements for hydraulic lifting mechanisms that exceed EU baseline safety thresholds, creating compliance differentiation among suppliers. France's ANSM-aligned environmental directives on circular economy waste streams are mandating container traceability systems that integrate with loader telematics. Stakeholders must monitor how battery-electric chassis weight penalties reshape optimal load capacity specifications across product portfolios.
Market Dynamics
Electrification mandates from the EU Green Deal are forcing waste management fleets to re-specify hook lift chassis for battery-electric compatibility, compressing load capacity tolerances and hydraulic system weight budgets across equipment portfolios.
Growth Catalysts
- EU landfill diversion targets:Germany's KBA enforces stricter type approval thresholds for waste handling equipment, compelling municipal fleet upgrades to containerized collection systems.
- Containerized logistics infrastructure:France and the Benelux region maintain the densest roll-off container networks in Europe, sustaining replacement demand for high-cycle hook lift mechanisms.
- Urban emissions restrictions:Battery-electric chassis penetration in municipal fleets creates parallel demand for lightweight hydraulic systems that preserve payload ratings under stricter axle load limits.
Market Restraints
- Battery weight penalties:Electric chassis battery packs consume 800-1,200 kg of payload capacity, forcing downsizing in load capacity tiers or reduced container interchange efficiency.
- Hydraulic component supply concentration:High-pressure valve and cylinder manufacturing clusters in Southern Germany create single-source vulnerability for specialized refuse equipment OEMs.
- Steel input cost volatility:Chassis frame and container fabrication exposure to European hot-rolled coil pricing compresses margin stability for equipment assemblers.
Strategic Opportunities
- Telematics-integrated container tracking:France's ANSM-aligned circular economy directives mandate waste stream traceability, opening retrofit markets for sensor-equipped hook lift systems.
- Construction debris logistics:Urban densification in Dutch and Belgian metropolitan corridors expands demand for rapid container exchange at confined building sites.
- Remanufacturing services:Extended producer responsibility frameworks in Germany incentivize hydraulic system refurbishment versus replacement, creating recurring revenue attach rates.
Industry Challenges
- Hydraulic technician scarcity:Specialized 200+ bar system maintenance expertise concentrates among aging workforce cohorts in Bavaria and Baden-Württemberg.
- CE marking timeline compression:Revised EU machinery safety standards for automated lifting equipment extend certification cycles for new product introductions.
- Chassis-electric integration complexity:Battery thermal management and hydraulic power take-off coordination demands cross-functional engineering coordination absent in legacy diesel platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hook Lifts and Skip Loaders Market |
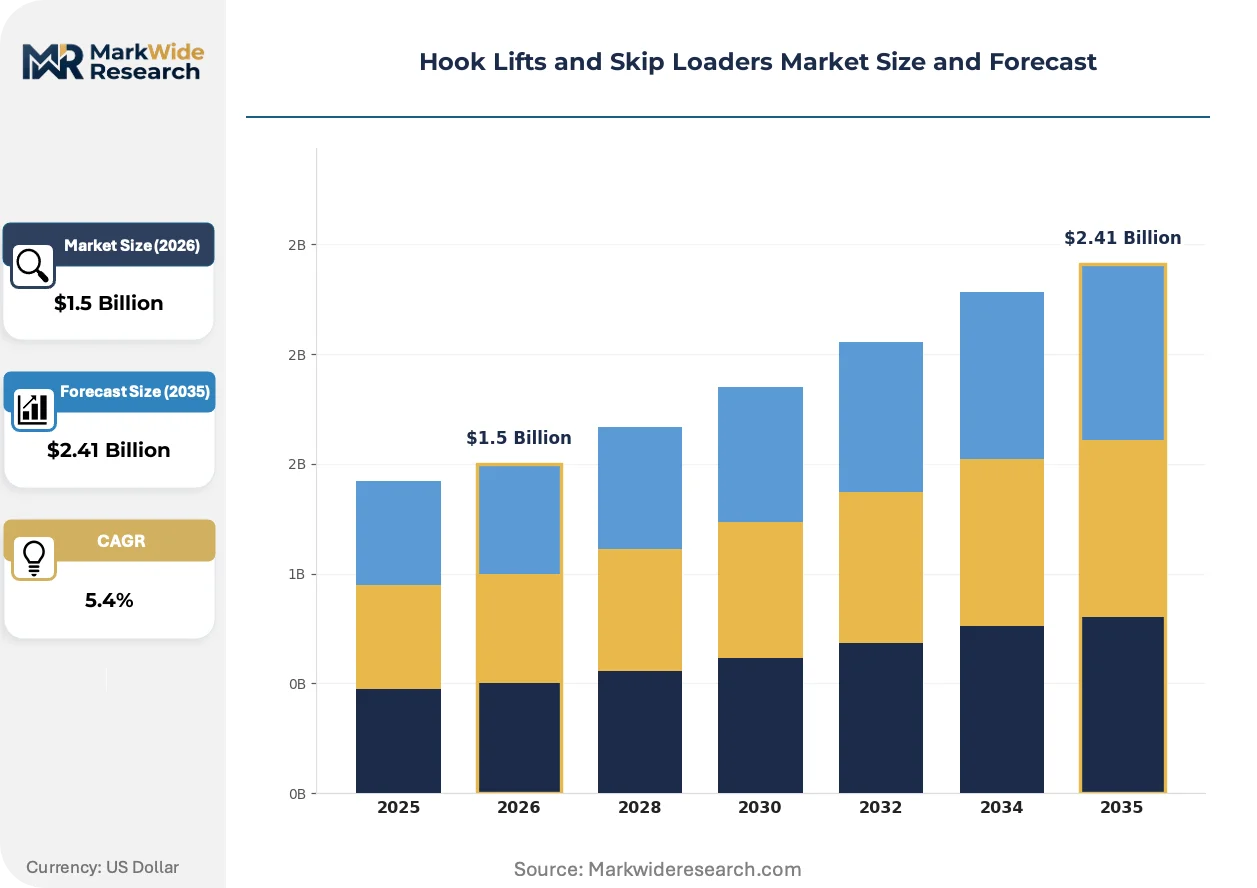
| Market Size in 2026 | $1.5 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hook Lift, Skip Loader, Roll-Off Container, Flatbed End User: Construction Companies, Waste Management, Municipal Services, Landscaping Firms Load Capacity: 2-5 Tons, 6-10 Tons, 11-15 Tons, 16+ Tons Fuel Type: Diesel, Electric, Hybrid, Gasoline |
| Companies Covered | PALFINGER Group, Galbreath, Marrel Corporation (Ampliroll), SwapLoader USA Ltd., Stellar Industries, Cargotec Corporation, VDL Containersystemen B.V., B.O.B. Sistemi Idraulici S.p.A., Meiller Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hook Lifts and Skip Loaders Market Emerging Trajectories
Sensor integration and predictive maintenance protocols are redefining equipment lifecycle economics across European waste handling fleets. Three developments are compressing traditional service intervals and procurement criteria.
Telematics-enabled load monitoring is digitizing fleet management practices for municipal waste operators. Pressure transducers and position sensors embedded in hook lift arms transmit real-time container weight and exchange frequency data to centralized depot systems. German municipal fleets in North Rhine-Westphalia and Bavaria are deploying these systems fastest, enabling dynamic route optimization that reduces chassis engine hours and hydraulic system wear.
EU Green Deal implementation through national regulators is tightening CO2 performance standards for commercial vehicle fleets. Germany's KBA enforces type approval requirements for hydraulic lifting mechanisms that exceed baseline EU safety thresholds. This regulatory layering creates compliance differentiation among suppliers, with French and Benelux procurement specifications increasingly referencing German KBA standards as procurement gatekeepers.
Direct OEM-service contracts are displacing traditional dealer network intermediation for large municipal accounts. Waste management authorities in Rotterdam, Lyon, and Hamburg now negotiate multi-year total cost of ownership agreements spanning chassis, hook lift mechanism, and container pools. This channel consolidation concentrates purchasing power among fewer buyers while compressing aftermarket parts margins for independent service providers.
Hook Lifts and Skip Loaders Market Segmentation
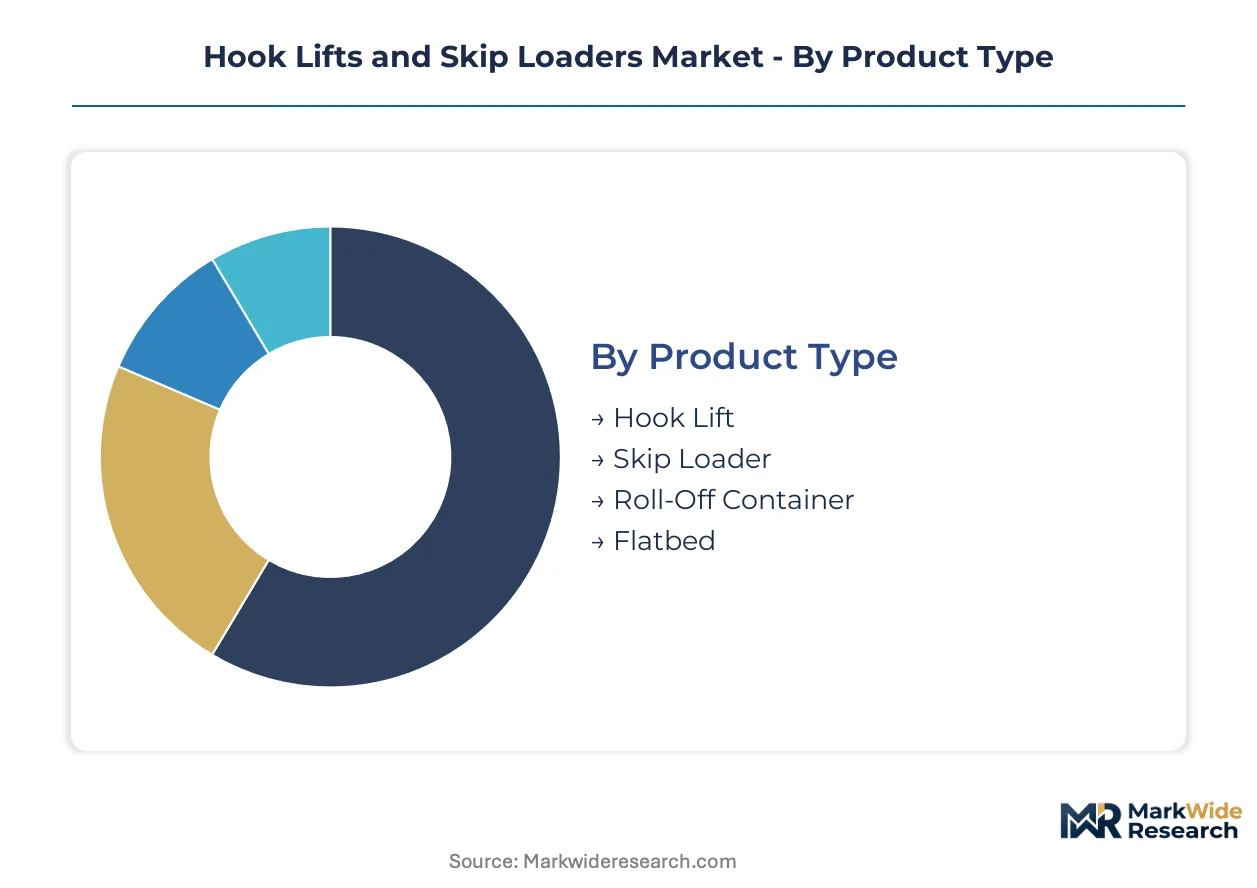
Equipment segmentation in this market tracks diverging lifecycle economics across municipal and commercial fleets. Service intensity varies dramatically by product architecture, with hydraulic complexity dictating maintenance contract structures and parts revenue potential.
Product Type:
After-sales intensity correlates directly with hydraulic sophistication and duty cycle frequency across equipment categories.
- Hook Lift:Hydraulically actuated arm mechanisms rated for 200+ bar operating pressure enable rapid container exchange without auxiliary lifting equipment. Demand concentrates in German and Benelux waste management fleets where high-cycle operations justify premium acquisition costs and comprehensive service agreements.
- Skip Loader:Simpler cable or chain-based lifting systems prioritize reliability over interchange speed, typically mounted on lighter chassis. Municipal services in France favor these units for budget-constrained procurement where in-house maintenance capabilities limit hydraulic specialist dependency.
- Roll-Off Container:Standardized steel bins designed for hook lift and skip loader compatibility, fabricated in 10-40 cubic meter capacities.
- Flatbed:Non-containerized platform configurations serving irregular load geometries in construction logistics.
Hook Lift holds the largest share; momentum sits with Electric-compatible lightweight variants.
End User:
Customer procurement authority shapes margin structures, with municipal tender processes compressing equipment pricing while extending service contract durations.
- Waste Management:Specialized fleet operators managing containerized collection routes under landfill diversion mandates. German KBA type approval requirements drive specification upgrades, while France's ANSM-aligned traceability directives accelerate telematics integration.
- Construction Companies:Project-based demand for debris removal at urban densification sites across Dutch and Belgian metropolitan corridors. Rotterdam and Antwerp building codes mandate rapid site clearance timelines that favor hook lift interchange efficiency.
- Municipal Services:Public sector procurement constrained by budget cycles and political approval timelines, prioritizing total cost of ownership over upfront capital expenditure.
- Landscaping Firms:Seasonal demand patterns with lower utilization rates, favoring skip loader simplicity and reduced hydraulic maintenance exposure.
Waste Management commands the dominant revenue position; Construction Companies are expanding most quickly.
Load Capacity:
Axle load regulations and chassis weight penalties from battery-electric powertrains are compressing optimal capacity specifications.
- 11-15 Tons:The dominant European specification balancing container volume against road weight restrictions. Meiller Group's German manufacturing complex sustains cost advantages in this tier through production scale and vertical integration into hydraulic component fabrication.
- 16+ Tons:Heavy-duty configurations for construction debris and industrial waste streams, retaining diesel powertrain dominance due to battery weight penalties that would compromise payload ratings.
- 6-10 Tons:Municipal service entry segment where electric chassis penetration advances fastest, though compressed load capacity limits container interchange efficiency.
- 2-5 Tons:Light commercial applications with limited container standardization, constraining aftermarket parts revenue potential.
11-15 Tons maintains volume leadership; 6-10 Tons faces steepest specification pressure from electrification mandates.
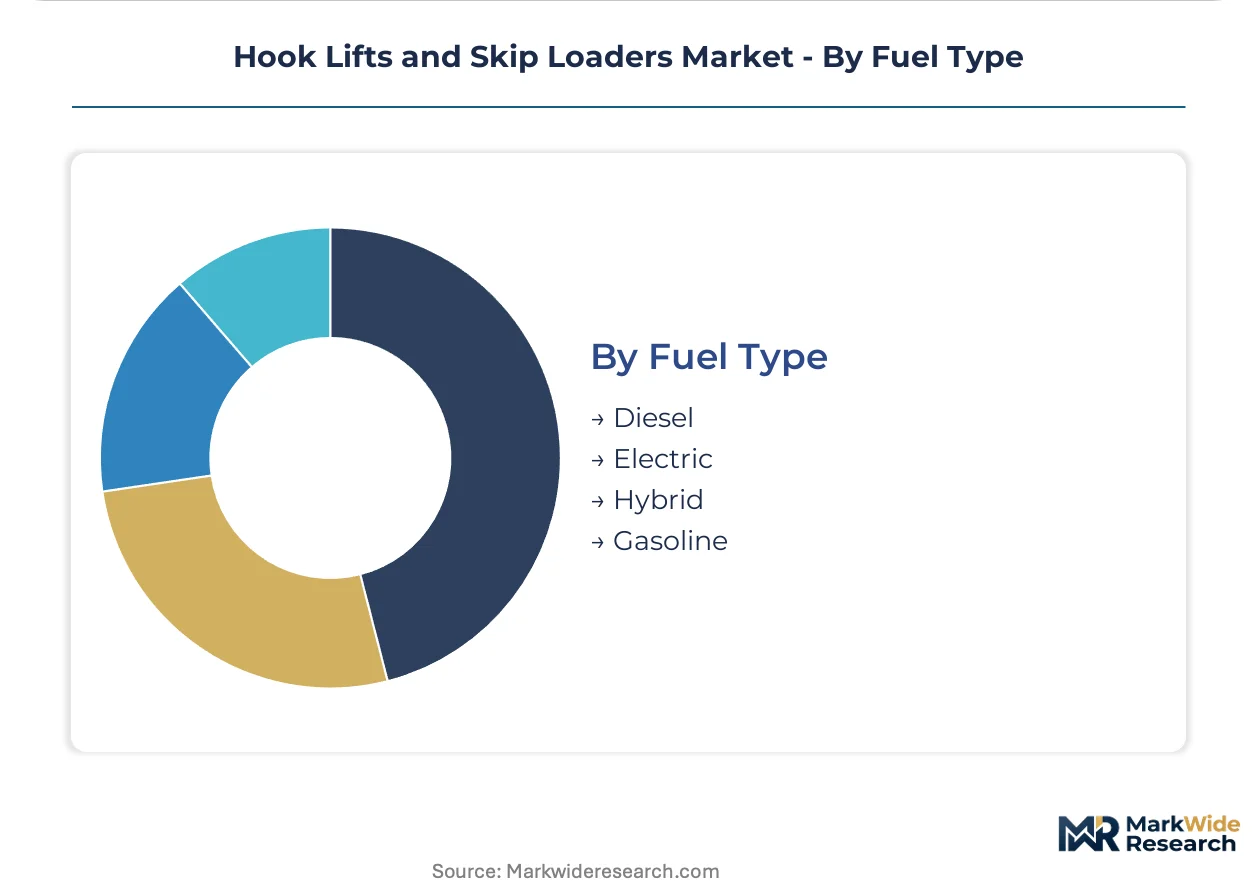
Fuel Type:
Powertrain selection determines chassis weight budgets, directly constraining hydraulic system design parameters and container payload economics.
- Diesel:Retains margin depth in heavy-load construction deployments where battery weight penalties would eliminate operational viability. German KBA emissions testing protocols maintain certification barriers for non-EU powertrain imports.
- Electric:Battery packs consuming 800-1,200 kg of payload capacity force trade-offs between range, container weight, and hydraulic system mass. Urban emissions restrictions in Hamburg, Lyon, and Rotterdam accelerate municipal fleet adoption despite these constraints.
- Hybrid:Transitional architectures attempting to preserve payload capacity while meeting urban low-emission zone requirements.
- Gasoline:Minimal penetration limited to light-duty landscaping and maintenance applications with low utilization intensity.
Diesel retains the installed base dominance; Electric is gaining share fastest in municipal waste segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in containerized waste logistics, connecting Bavarian manufacturing clusters to North Sea port networks.
Germany
Waste management fleets in North Rhine-Westphalia and Bavaria are expanding hook lift deployments to meet EU landfill diversion targets. Germany's KBA enforces type approval requirements for hydraulic lifting mechanisms that exceed baseline EU safety thresholds. Manufacturing gravity concentrates at Meiller Group's German production complex, sustaining cost advantages in the 11-15 ton load capacity tier.
France
Containerized collection infrastructure in Île-de-France and Auvergne-Rhône-Alpes sustains replacement demand for high-cycle hook lift mechanisms. France's ANSM-aligned environmental directives on circular economy waste streams mandate container traceability systems that integrate with loader telematics. Lyon municipal authorities negotiate multi-year total cost of ownership agreements spanning chassis, hook lift mechanism, and container pools.
Netherlands
Urban densification in Rotterdam and Amsterdam metropolitan corridors expands demand for rapid container exchange at confined building sites. Dutch building codes mandate rapid site clearance timelines that favor hook lift interchange efficiency. Rotterdam waste management authorities now procure through direct OEM-service contracts that displace traditional dealer network intermediation.
Belgium
Antwerp's port logistics ecosystem and Brussels municipal services drive demand for electric-compatible lightweight hydraulic systems. Belgian fleets face urban emissions restrictions that accelerate battery-electric chassis adoption despite 800-1,200 kg payload penalties. Containerized logistics infrastructure in Flanders maintains the densest roll-off container networks in Europe alongside Dutch counterparts.
United States
Construction debris logistics across the Northeast Corridor and Great Lakes manufacturing belt sustain demand for heavy-load hook lift configurations. EPA emissions standards and state-level fleet electrification mandates in California and New York condition procurement criteria for load handling equipment. Galbreath and SwapLoader USA Ltd. anchor North American supply through specialized hydraulic engineering for high-cycle refuse applications.
Hook Lifts and Skip Loaders Market Vendor Landscape
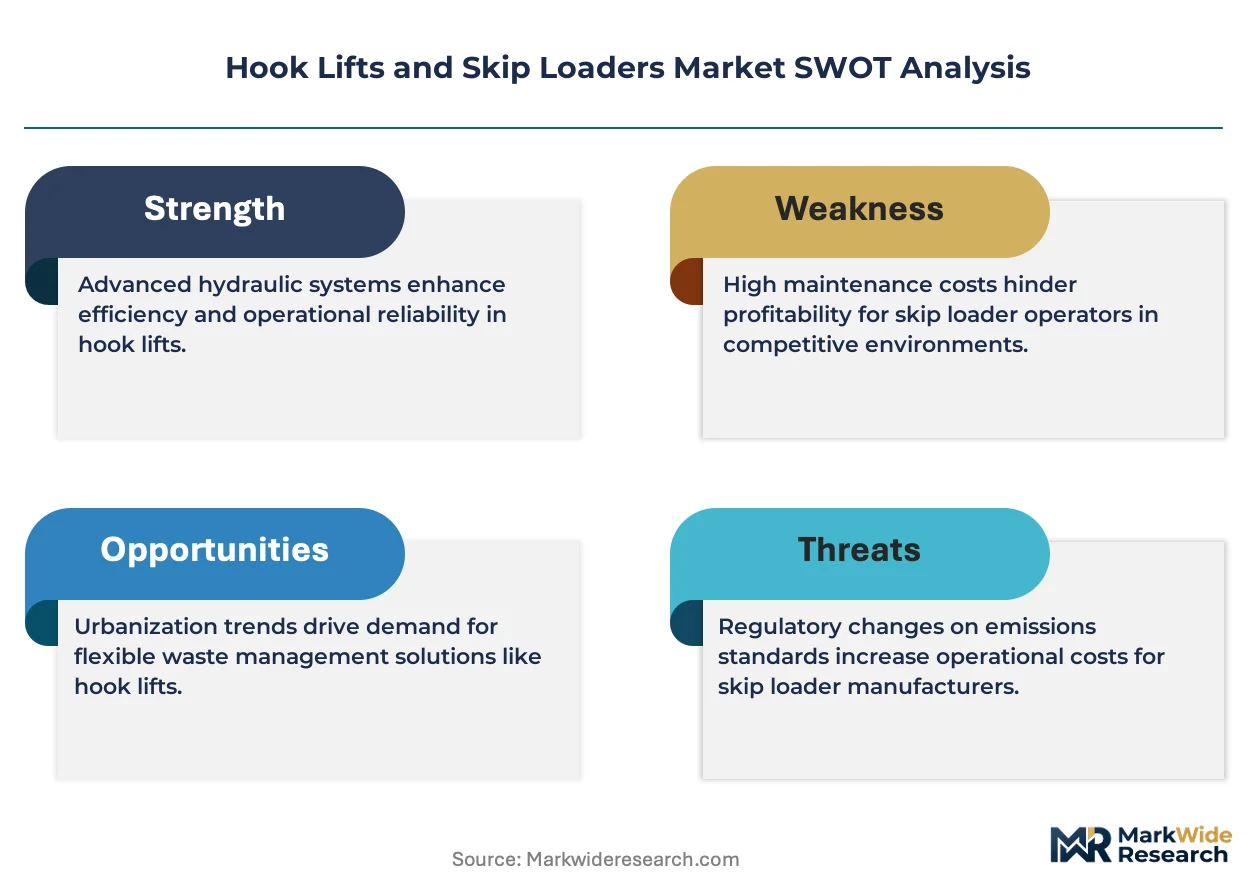
On the supply side, the industry is consolidating around three strategic archetypes: diversified industrial conglomerates with crane heritage cross-selling into chassis relationships, specialized hydraulic engineering firms serving high-cycle municipal applications, and scale-driven fabricators competing on manufacturing throughput in standardized load capacity tiers. Competitive positioning hardens through direct OEM-service contracts capturing municipal accounts and telematics-integrated container tracking systems that create switching costs.
Within the specialized hydraulic engineering tier, Marrel Corporation (Ampliroll) exemplifies technical differentiation for refuse applications, while PALFINGER Group represents diversified industrial equipment conglomerates leveraging crane heritage into adjacent load handling markets. Meiller Group anchors the scale-driven fabrication archetype through German-based manufacturing concentration.
| Leading Market Players |
|---|
| PALFINGER Group |
| Galbreath |
| Marrel Corporation (Ampliroll) |
| SwapLoader USA Ltd. |
| Stellar Industries |
| Cargotec Corporation |
| VDL Containersystemen B.V. |
| B.O.B. Sistemi Idraulici S.p.A. |
| Meiller Group |
| Others |
Supply Flow & Price Mechanics
Southern German hydraulic component clusters feed specialized valve and cylinder fabrication that anchors margin capture at the OEM tier. High-pressure system manufacturing concentrates among aging workforce cohorts in Bavaria and Baden-Württemberg, constraining supply elasticity while elevating pricing power for integrated producers.
Pricing Analysis
Volume-discount tiering structures separate municipal fleet contracts from commercial construction procurement. Three-tier pricing stratification across premium, standard, and economy levels reflects KBA certification grade, after-sales service bundling, and chassis integration complexity. Cost compression in the standard tier intensifies as electric chassis weight penalties force hydraulic system downsizing. Municipal services exhibit highest price sensitivity due to political approval timelines, while waste management fleets prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
European hot-rolled coil pricing volatility feeds directly into chassis frame and container fabrication costs. Steel input supply draws from German, Belgian, and Dutch mill complexes, while high-pressure hydraulic components rest on Southern German manufacturing clusters. Single-source vulnerability concentrates in specialized valve manufacturing. Distribution runs through direct OEM-service contracts for large municipal accounts and traditional dealer networks for commercial construction buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal electrification mandates are forcing battery-electric chassis re-specification that compresses hydraulic system weight budgets and reshapes competitive advantage toward lightweight engineering specialists.
For Market Incumbents: Pre-empt margin erosion in the 11-15 ton tier by securing captive supply of high-pressure hydraulic components before workforce retirement waves constrain Southern German manufacturing capacity. Defend position through telematics-integrated container tracking systems that create switching costs against emerging lightweight competitors.
For New Entrants and Emerging Players: Pursue white-space opportunity in electric-compatible 6-10 ton hook lift variants where battery weight penalties have left specification gaps unaddressed by incumbent portfolios. Target Dutch and Belgian metropolitan construction corridors where rapid site clearance mandates favor rapid container exchange efficiency over established brand relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized hydraulic engineering firms with demonstrated KBA certification pathways and aging founder-owner transition timelines. Watch for inflection when French ANSM-aligned traceability mandates trigger mandatory telematics retrofit cycles across existing fleet installed bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Lightweight Hydraulic System Development | Preserves payload ratings under battery-electric chassis weight penalties for municipal fleets. |
| Telematics Platform Integration | Enables compliance with France's ANSM container traceability mandates and creates recurring revenue. |
| Backward Integration into Valve Manufacturing | Secures supply continuity against Southern German workforce retirement concentration risks. |
| Remanufacturing Service Buildout | Captures extended producer responsibility incentives in Germany's circular economy framework. |
| Direct Municipal Contracting Expansion | Displaces dealer intermediation in Rotterdam, Lyon, and Hamburg procurement channels. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across municipal fleet managers, construction procurement leads, hydraulic system maintenance directors, and OEM chassis integration engineers. Secondary validation drew from KBA type approval filings, EU Green Deal implementation directives, German steel trade association data, and French ANSM circular economy guidance. Bottom-up equipment shipment analysis and top-down waste management fleet expenditure triangulation anchored volume estimates.
Calibration against historical replacement cycles and electrification mandate phase-in schedules structured projections across the analysis window. Segmentation modeling tracked product architecture, load capacity tier, fuel type compatibility, and end-use procurement authority. CAGRs derived from equipment lifecycle compression effects and regulatory compliance upgrade timing. Battery weight penalty assumptions and hydraulic system efficiency curves informed electric-compatible variant penetration.
Macroeconomic conditions sit as an overlay; deviation in steel input pricing, construction activity indices, or municipal budget cycles would shift the trajectory. Forecasts reflect documented assumptions about electrification compliance timelines and workforce availability in specialized maintenance trades. Cross-checking against European waste management fleet expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Air/Pneumatic Balancers Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Tipper Pads Market
Material Handling Equipment
GCC Conveyor Belt Market
Material Handling Equipment
Global Metal Shredder Machine Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Stair Lifts and Climbing Devices Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market
Material Handling Equipment
Global Telescopic Boom Forklift Truck Market
Material Handling Equipment
Linear Slide Units Market
Material Handling Equipment
Water Hose Market
Material Handling Equipment
Global Conveyors Market
Material Handling Equipment
Industrial Pulley Market
Material Handling Equipment
Industrial Jacks Market
Material Handling Equipment
Log Loaders Market
Material Handling Equipment
Reach Stacker Market