
 Low Clearance Loaders Market | 2026-2036
Low Clearance Loaders Market Size, Share, and Industry Trends Forecast 2026-2036
Low Clearance Loaders Market Foresight
Telematics-linked maintenance subscriptions is hardening into a standard revenue layer rather than an optional add-on for low clearance loader OEMs. Caterpillar leverages its dealer network to bundle predictive service contracts with machine sales. Epiroc differentiates through R&D intensity in autonomous tramming systems for confined headings. Bobcat Company anchors its position in compact utility segments where landscaping contractors prioritize maneuverability over raw lift capacity.
Low clearance loaders are purpose-built material handling machines with restricted overall height and width dimensions, typically operating in headings below 2.5 meters vertical clearance using articulated steering and compact wheelbases. These machines serve primarily underground mining and confined construction environments where standard equipment cannot physically access the workspace. Skid steer loaders occupy the most mature margin pool in landscaping and light construction, while electric technology represents the fastest-growing segment as mine operators face escalating ventilation costs from diesel exhaust. Compact track loaders compete aggressively in soft-ground mining applications where flotation and traction outweigh speed requirements.
The EPA and EU Stage V emission frameworks compel diesel-powered loader fleets toward particulate filtration or full electrification, directly raising equipment costs but opening retrofit markets for existing machines. OSHA confined space standards and ISO underground machinery safety protocols shape operator cabin design and emergency egress requirements across North American and European sales channels. Stakeholders must weigh captive electric infrastructure investment against hybrid transitional architectures as regulatory deadlines tighten without universal global alignment.
Market Dynamics
Electric drivetrain conversion is compressing the operational economics of underground mining fleets, forcing capital allocation decisions between captive charging infrastructure and hybrid transitional architectures before EPA and EU Stage V deadlines fully phase out unfiltered diesel equipment.
Growth Catalysts
- EPA Stage V emission mandates:Underground operators in Australia and Canada face compulsory particulate filtration retrofits or full electrification, accelerating replacement cycles for legacy diesel fleets in hard-rock extraction corridors.
- Narrow-vein mining expansion:Gold and base metal deposits in South Africa's Bushveld Complex and Western Australia's Kalgoorlie region require machines below 2.5 meter clearance, directly pulling compact loader demand.
- Battery energy density improvements:Solid-state and lithium-iron-phosphate chemistries now deliver shift-length runtime without mid-cycle charging, eliminating the productivity penalty that stalled earlier electric adoption.
Market Restraints
- Copper and rare earth price volatility:Electric motor windings and battery cathodes expose OEMs to input cost swings that compress margin predictability on fixed-price equipment contracts.
- Shaft infrastructure retrofit requirements:Existing mine hoists and ventilation systems in Canada's Abitibi belt and Australia's Broken Hill district cannot accommodate battery charging stations without seven-figure capital outlays.
- Skid steer substitution in surface applications:Compact utility loaders with universal quick-attach systems capture overlapping use cases in landscaping and light construction, capping pricing power for dedicated low-clearance designs.
Strategic Opportunities
- Indonesia's nickel-cobalt underground expansion:Sulawesi and Halmahera mining concessions are commissioning new narrow-vein operations where virgin infrastructure can be engineered around electric equipment from commissioning.
- Telematics-enabled predictive maintenance:Sensor-fleet subscriptions transform one-time equipment sales into recurring revenue streams, with OEMs capturing lifetime value through hydraulic wear monitoring and component replacement scheduling.
- Autonomous tramming convergence with LiDAR:Machine-vision navigation layered onto electric platforms eliminates operator exposure in unstable headings while reducing ventilation requirements for human-occupied cabins.
Industry Challenges
- Electrician and battery technician scarcity:Underground maintenance crews lack training on high-voltage isolation procedures and thermal runaway containment, forcing mines to import specialized labor or defer electrification timelines.
- ISO 19296 compliance certification delays:Third-party validation of fire-resistant hydraulic fluids and emergency egress systems extends product launch schedules by 8-14 months for new platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Clearance Loaders Market |
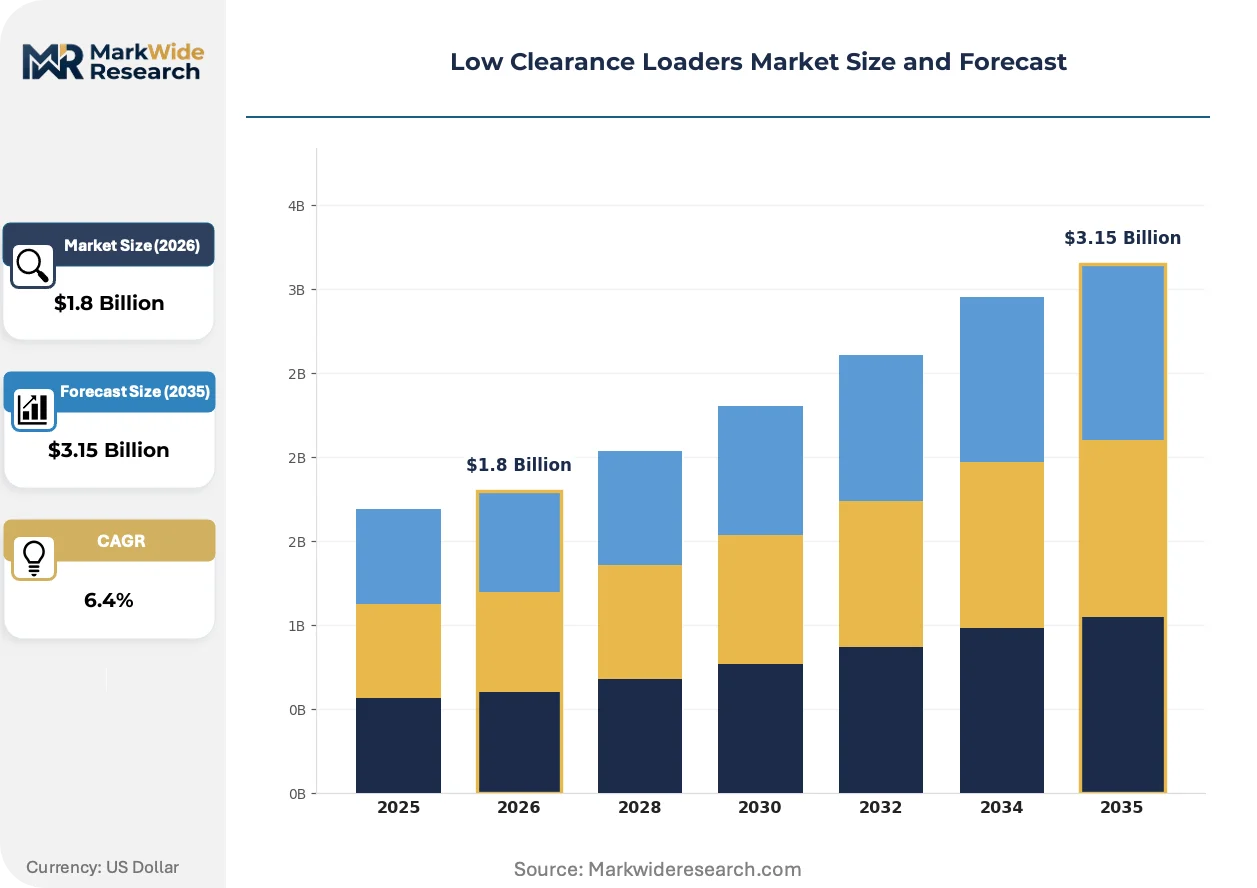
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Loaders, Skid Steer Loaders, Compact Track Loaders, Wheel Loaders End User: Construction, Landscaping, Agriculture, Mining Capacity: Under 1 Ton, 1-2 Tons, 2-3 Tons, Over 3 Tons Technology: Diesel, Electric, Hybrid, Hydraulic |
| Companies Covered | Bobcat Company, Sandvik, Epiroc, Eimco Elecon, Toro Australia, McDowell, KMW, Hard-Line, Caterpillar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Clearance Loaders Market Shifts & Advancements
Autonomous navigation systems are penetrating confined headings faster than surface mining applications, compressing the timeline for operatorless extraction in seams too narrow for conventional equipment. Three developments are restructuring competitive advantage.
LiDAR-based simultaneous localization and mapping is automating tramming cycles in headings below 2.2 meters where GPS denial and magnetic interference defeat conventional guidance. Australian hard-rock operators in the Yilgarn Craton are deploying retrofitted fleets with 40% faster cycle times than manned equivalents. The technology is automating shift scheduling and reducing ventilation costs by eliminating diesel particulate from occupied zones.
EU Stage V and EPA Tier 4 Final emission frameworks are mandating diesel particulate filters or exhaust aftertreatment on all new underground equipment, adding $45,000-$80,000 to machine first cost. North American metal mines are responding with accelerated lease-to-own transitions that shift compliance risk to OEM financing arms. European coal and salt operators face the strictest retrofit deadlines, driving scrap-and-replace decisions rather than engine rebuilds.
After-sales service unbundling is fragmenting traditional dealer relationships as mine procurement teams separate parts, labor, and remote diagnostics into discrete contract vehicles. Western Australian gold producers now source consumables through direct OEM portals while retaining third-party technicians for field repair. The practice is most visible in mature mining districts where captive maintenance capabilities reduce dependency on distributor technical support.
Low Clearance Loaders Market Segmentation
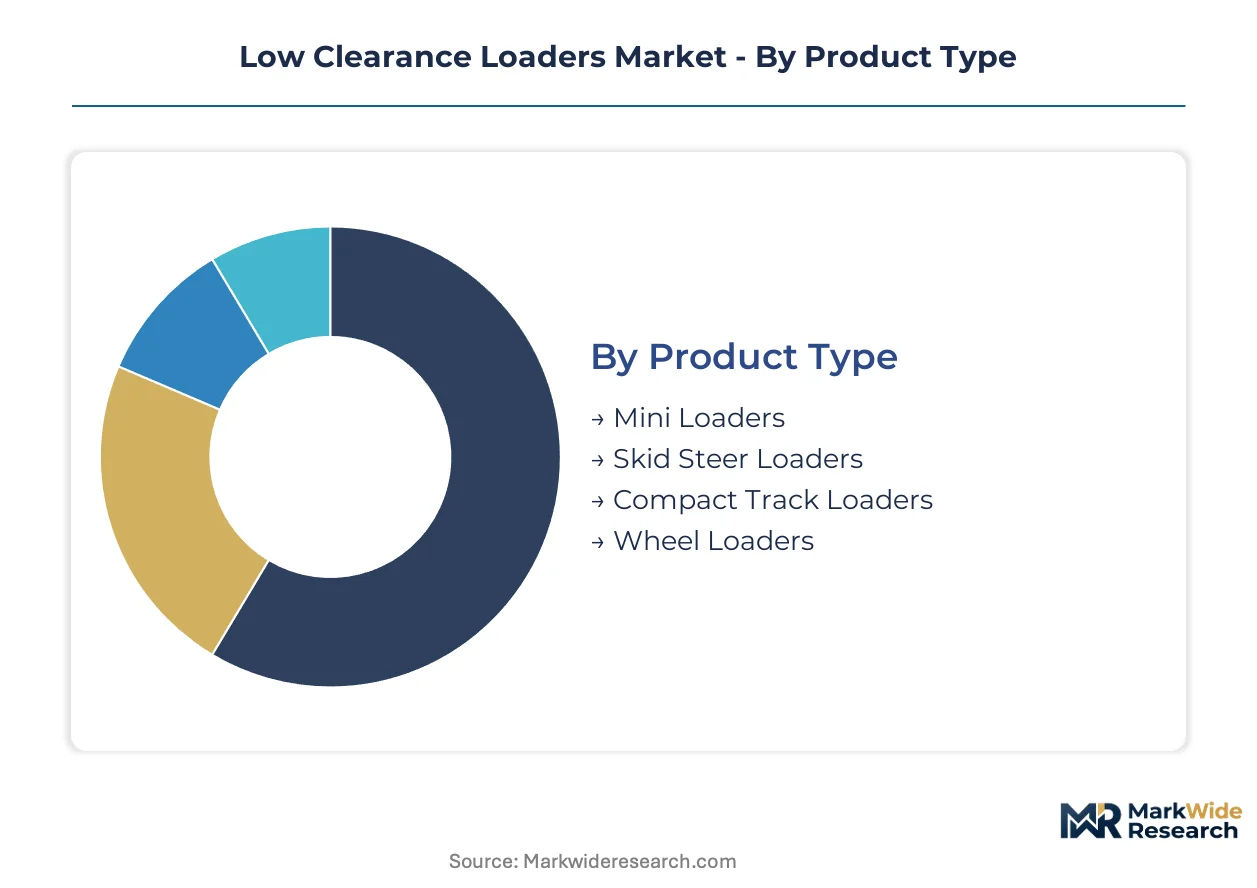
Equipment classification in low clearance loaders determines regulatory pathway, infrastructure requirements, and aftermarket service intensity. Segmentation by dimension, duty cycle, and powertrain creates distinct margin pools and competitive dynamics across underground mining and confined construction applications.
Product Type:
ISO 19296 fire-resistance certification and EPA Tier 4 Final compliance burdens vary sharply across product architectures, with articulated units facing stricter hydraulic fluid specifications than rigid-frame designs.
- Skid Steer Loaders:Vertical-lift and radial-lift variants dominate surface landscaping and light construction with universal quick-attach systems. Australian hard-rock mines specify compact skid steers below 2.2 meter height for narrow-vein development headings where maneuverability outweighs lift capacity.
- Compact Track Loaders:Rubber-track undercarriages distribute ground pressure below 35 kPa for soft-ground mining applications in Canada's oil sands and Indonesia's nickel laterite concessions. Flotation advantages command 15-25% price premiums over wheeled equivalents in boggy conditions.
- Mini Loaders:Sub-1.5 meter height machines serve tunnel rehabilitation and shaft maintenance in South Africa's Bushveld Complex.
- Wheel Loaders:Articulated steering with compact wheelbases handles ore mucking in Australia's Kalgoorlie gold camps.
Skid steer loaders sit at the top of the volume ranking, with compact track loaders climbing the fastest.
End User:
Customer concentration and procurement sophistication diverge sharply, with mining operators demanding telematics integration while construction contractors prioritize rental availability.
- Mining:Underground hard-rock and narrow-vein operations in Western Australia, Ontario's Abitibi belt, and South Africa's platinum reefs drive specifications below 2.5 meter clearance. Ventilation cost pressures and EPA Stage V deadlines accelerate electric fleet transitions.
- Construction:Urban infrastructure and tunneling projects in Germany and Japan specify compact loaders for confined workspace access. Equipment rental channels dominate procurement, compressing margins through fleet standardization.
- Landscaping:Residential and commercial grounds maintenance in US Sun Belt states favors skid steer maneuverability over lift capacity.
- Agriculture:Livestock operations and confined barn cleaning in Denmark and the Netherlands demand low-height machines for indoor manure handling.
Mining commands the highest average selling prices, with construction delivering the steepest volume expansion trajectory.
Capacity:
Payload rating determines engine displacement thresholds and corresponding emission compliance tiers under EU Stage V and EPA frameworks.
- 1-2 Tons:Mid-range payload segment balances breakout force with dimensional constraints for Australia's gold and base metal narrow-vein extraction. Battery-electric architectures achieve competitive runtime without mid-shift charging in this weight class.
- Under 1 Ton:Ultra-compact machines serve shaft maintenance and rehabilitation headings where vertical clearance drops below 2.0 meters.
- 2-3 Tons:Heavier payload rating requires diesel-hybrid or full electric powertrains to meet ventilation limits in deep Canadian and South African operations.
- Over 3 Tons:Specialized mucking loaders for bulk ore movement in wider headings face slower electrification due to battery weight penalties.
1-2 ton capacity sits at the top of the volume ranking, with under 1 ton machines gaining share fastest in shaft rehabilitation applications.
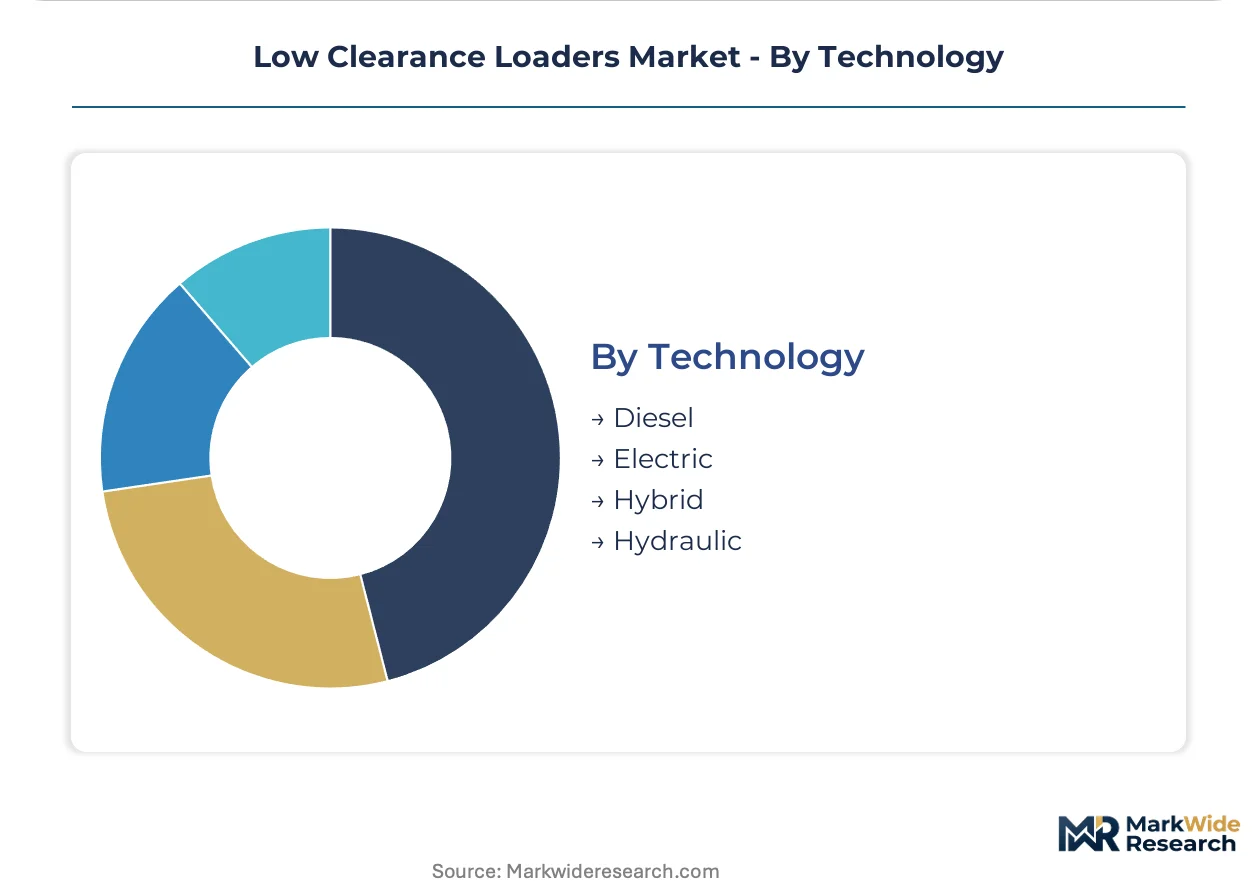
Technology:
Powertrain selection locks in infrastructure investment requirements and determines residual value risk across regulatory compliance timelines.
- Electric:Battery-electric drivetrains eliminate diesel particulate emissions and reduce ventilation infrastructure costs by 30-40% in deep underground operations. Solid-state and lithium-iron-phosphate chemistries now deliver full-shift runtime for Australian and Canadian hard-rock mines.
- Diesel:Legacy fleets face EPA Stage V and EU Stage V retrofit deadlines, with particulate filtration adding $45,000-$80,000 to machine first cost.
- Hybrid:Diesel-electric architectures serve transitional deployments in Indonesia's new nickel concessions where charging infrastructure remains unproven.
- Hydraulic:Conventional hydrostatic transmissions persist in surface construction and landscaping applications with less stringent emission constraints.
Diesel technology sits at the top of the volume ranking, with electric powertrains climbing the fastest as battery energy density improves and ventilation costs escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia commands premium pricing for sub-2.5 meter machines while Canadian operators grapple with legacy shaft retrofit costs that delay electric fleet conversions.
Australia
Western Australia's Kalgoorlie gold camps and Yilgarn Craton drive specifications for articulated wheel loaders below 2.2 meter clearance. The country's national mining regulator enforces strict diesel particulate exposure limits in underground operations. Perth-based procurement teams now source battery-electric units directly from OEM portals, bypassing traditional dealer networks for consumables.
Canada
Ontario's Abitibi belt and British Columbia's underground copper operations require compact loaders for narrow-vein extraction in confined headings. Health Canada and provincial mining authorities mandate compliance with ISO 19296 fire-resistance standards for hydraulic systems. Toronto-area equipment distributors report extended lead times as mines defer electrification pending shaft infrastructure upgrades.
United States
Nevada's Carlin-type gold deposits and Idaho's silver-lead mines specify low-clearance machines for vein widths under 3 meters. EPA Tier 4 Final emission frameworks compel particulate filtration retrofits or full equipment replacement. Phoenix and Elko serve as procurement hubs where rental channels dominate surface construction applications.
South Africa
The Bushveld Complex platinum reefs and gold operations in the Witwatersrand Basin demand mini loaders for shaft maintenance below 2.0 meter clearance. The country's Department of Mineral Resources enforces occupational exposure limits for diesel exhaust in deep-level operations. Johannesburg-based mining houses face electrician scarcity that stalls battery technician training programs.
Indonesia
Sulawesi and Halmahera nickel-cobalt concessions commission new narrow-vein operations with virgin infrastructure engineered around electric equipment. The country's energy ministry promotes downstream mineral processing investments that require captive mining equipment fleets. Makassar and Manado emerge as logistics coordination points for equipment commissioning in greenfield underground sites.
Low Clearance Loaders Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with mining-grade equipment consolidating around integrated OEMs while construction applications fragment across rental channels. The vendor base organizes into three archetypes: diversified mining equipment conglomerates, compact machinery pure-plays, and regional fabrication specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as electrification timelines compress.
Among diversified mining equipment conglomerates, Caterpillar anchors the premium-tier position through dealer network bundling of predictive service contracts. Epiroc occupies a position within the autonomous tramming specialization vector, while Sandvik exemplifies the integrated hard-rock mining systems archetype. Bobcat Company sits within the compact utility segment where landscaping contractors prioritize maneuverability specifications over raw lift capacity metrics.
| Leading Market Players |
|---|
| Bobcat Company |
| Sandvik |
| Epiroc |
| Eimco Elecon |
| Toro Australia |
| McDowell |
| KMW |
| Hard-Line |
| Caterpillar |
| Others |
Supply & Pricing Matrix
Specialized battery technician concentrations in Ontario's Abitibi belt and Western Australia's Kalgoorlie corridor create labor-cost differentials that widen pricing-tier spreads between premium OEM service bundles and third-party maintenance contracts.
Pricing Analysis
Capacity additions in Indonesia's Sulawesi nickel concessions are reshaping price floors for electric low clearance loaders as greenfield mines absorb volume without retrofit premiums. Three-tier pricing structure across premium, standard, and economy levels separates autonomous-ready platforms from basic diesel units and refurbished legacy fleets. Price differentiation hinges on ISO 19296 fire-resistance certification and telematics integration depth. Cost compression in the economy tier is intensifying because Indonesian mines source consumables through direct OEM portals, bypassing distributor markups. Construction rental channels exhibit highest price sensitivity; mining operators with captive maintenance capabilities show least.
Supply Chain Analysis
Dual-sourcing requirements from Australian hard-rock operators now mandate qualified suppliers in China for battery cells, South Korea for electric drivetrains, and Germany for precision hydraulics. Raw material dependencies center on lithium-iron-phosphate cathodes, rare earth motor windings, and fire-resistant hydraulic fluids. Single-source vulnerability concentrates in solid-state battery cell supply as OEMs qualify alternative chemistries. Distribution runs through Perth and Toronto mining equipment hubs serving regional procurement clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential through ventilation-cost avoidance as electric fleets displace diesel equipment in deep underground operations.
For Market Incumbents: Lock in predictive maintenance subscription attach rates above 80 percent to capture lifetime value through hydraulic wear monitoring and component replacement scheduling. Deepen backward integration into battery pack assembly to offset copper and rare earth price volatility exposure. Defend against skid steer substitution in surface construction by emphasizing narrow-vein specialization and ISO 19296 certification tiers that universal loaders cannot match. For New Entrants and Emerging Players: Direct-to-mine procurement portals offer the lowest channel friction for entering Western Australian gold camps where Perth-based buyers already source consumables outside dealer networks. Target Indonesia's greenfield nickel concessions for initial equipment commissioning where virgin infrastructure eliminates shaft retrofit barriers. White-space exists in battery technician training partnerships with South African mining houses facing electrician scarcity. For Investors and Strategic Acquirers: Diversified mining equipment conglomerates are the most active acquirers in this space, consolidating autonomous tramming capabilities and electric platform R&D. Long-term viability rests on electrification timeline execution across the next decade as EPA and EU Stage V deadlines phase out unfiltered diesel. Acquisition target archetype: compact loader pure-plays with certified electric architectures and established narrow-vein customer relationships in Australia's hard-rock corridors. The signal to watch is battery energy density improvement announcements that eliminate mid-shift charging requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Tramming Platform Launch | LiDAR-based navigation eliminates operator exposure in unstable headings below 2.2 meters. |
| Battery-Electric Product Line Expansion | Solid-state chemistry investments capture ventilation-cost savings in deep Canadian operations. |
| Predictive Maintenance Subscription Rollout | Telematics-linked service contracts transform one-time sales into recurring revenue streams. |
| Regional Fabrication Partnership | Local assembly in Indonesia's Sulawesi region reduces logistics costs for nickel-cobalt concessions. |
| ISO 19296 Certification Acceleration | Fire-resistant hydraulic validation shortens product launch schedules for new platform introductions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged maintenance directors at underground hard-rock operations, OEM procurement teams, aftermarket service heads, and battery technician training program coordinators. Secondary validation drew from EPA emission filings, EU Stage V compliance databases, mining equipment customs records, and ISO certification registries. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates across product type, capacity tier, and powertrain technology segments.
Segment-weighting applied differential growth rates to electric, hybrid, diesel, and hydraulic powertrain categories across mining, construction, landscaping, and agriculture end uses. Modeled dimensions included clearance height specifications, payload capacity bands, and regional regulatory clusters. CAGRs derived from equipment replacement cycle analysis and electrification penetration curves. Forecast inputs incorporated battery energy density improvement trajectories and ventilation infrastructure cost escalation assumptions.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook. Forecasts reflect assumptions about EPA and EU Stage V enforcement timelines, copper price stability, and mine shaft retrofit capital availability. Deviation in electrician training program scale or battery thermal runaway incident frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Bulk Material Handling System Market
Material Handling Equipment
Slag Handling Equipment Market
Material Handling Equipment
Sand Washing Machine Market
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Light Duty Telehandler Market
Material Handling Equipment
Decoiler Machine Market
Material Handling Equipment
Machined Springs Market
Material Handling Equipment
Global Precision Gearboxes Market
Material Handling Equipment
Global Tension Control Market
Material Handling Equipment
Electric Hoist Market
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
Vibrating Feed Conveyors Market
Material Handling Equipment
Rail Mounted Gantry Crane Market
Material Handling Equipment
Automated Material Handling Systems Market
Material Handling Equipment
Lifting Machinery Market
Material Handling Equipment
Port Equipment Market