
 Level Loader Market | 2026-2036
Level Loader Market Size, Share, and Industry Trends Forecast 2026-2036
Level Loader Market Insights
Skilled maintenance technician shortages across North American manufacturing hubs is redrawing competitive dynamics for level loader suppliers. Southworth Products Corporation leverages its domestic production footprint to sustain shorter lead times for hydraulic and electric units. Bishamon Industries Corp. anchors its position through specialized ergonomic designs that target warehouse retrofit installations.
A level loader is a height-adjustable material handling platform that uses hydraulic, electric, or pneumatic actuation to raise or lower loads to ergonomic working heights, typically accommodating capacities from 2,000 to 6,000 pounds with travel ranges of 24 to 48 inches. Its primary industrial purpose is eliminating bending and stretching during pallet loading, unloading, and assembly operations to reduce musculoskeletal injury risk and improve throughput consistency. Electric loaders command the widest installed base due to quieter operation and lower energy costs, while pneumatic variants retain niche dominance in explosion-sensitive chemical processing environments where spark elimination matters. Mobile deployment configurations are gaining fastest in third-party logistics as facilities prioritize flexible floor layouts over fixed infrastructure.
OSHA ergonomic guidelines and the EU Machinery Directive shape product design requirements for guarding, stability, and load capacity verification across export markets. Japan's METI industrial safety standards add certification complexity for suppliers targeting automotive assembly applications. Stakeholders must monitor how battery-electric loader development intersects with evolving industrial electrification codes and carbon accounting rules.
Market Dynamics
OSHA ergonomic enforcement and the EU Machinery Directive are compressing design cycles for level loader manufacturers, forcing faster validation of guarding systems and load stability algorithms before market entry.
Growth Catalysts
- OSHA ergonomic standards:Warehouse operators in the United States face escalating injury liability exposure, accelerating replacement of fixed-height platforms with adjustable units.
- Automotive assembly:Japanese OEMs are retrofitting mixed-model lines with electric level loaders to accommodate variable vehicle architectures without reconfiguring fixed infrastructure.
- Battery-electric industrial equipment:Carbon accounting rules in Germany are pushing logistics providers toward electrified material handling fleets, including level loaders with lithium-ion powertrains.
Market Restraints
- Hydraulic fluid cost volatility:Petroleum-based hydraulic oil price swings compress margin predictability for manufacturers serving price-sensitive warehousing segments.
- Steel supply concentration:Structural steel sourcing from concentrated foundry regions creates input vulnerability for platform fabrication.
- Pneumatic infrastructure dependency:Compressed air system requirements limit pneumatic loader deployment in facilities without existing airline networks, capping addressable market share.
Strategic Opportunities
- India warehousing expansion:Cold chain and e-commerce fulfillment investments in Mumbai and Delhi industrial corridors remain underpenetrated for ergonomic load positioning equipment.
- EU Green Deal industrial electrification:Battery-electric loader categories qualify for accelerated depreciation under national green transition frameworks.
- Telematics-embedded maintenance:Convergence of IoT sensors and predictive analytics enables remote condition monitoring, opening subscription revenue streams for OEM service divisions.
Industry Challenges
- Certification timeline compression:Japan's METI industrial safety standards add validation layers for automotive assembly applications, extending product launch cycles.
- Electromechanical integration complexity:Legacy hydraulic system architectures resist straightforward retrofit with electric actuation, complicating upgrade paths for installed base customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Level Loader Market |
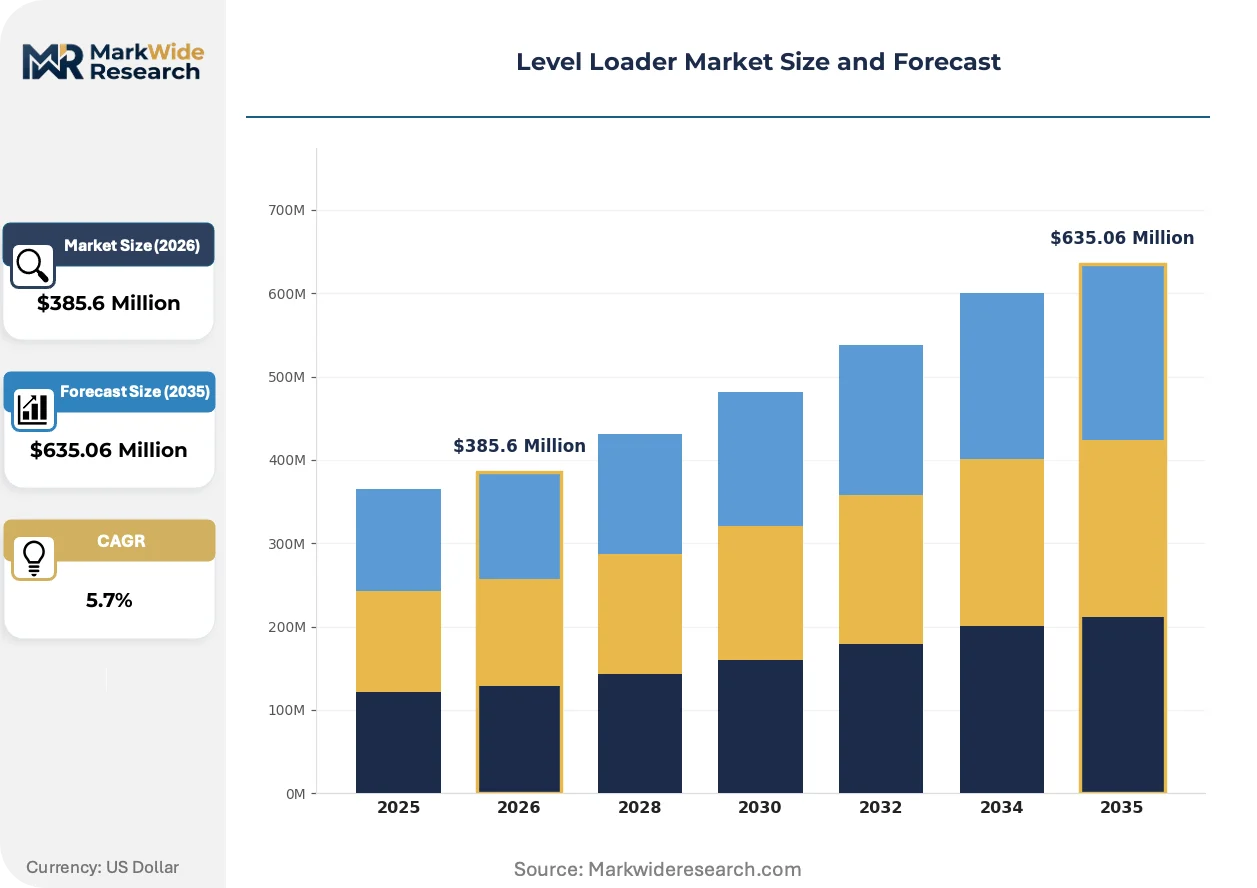
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $635.06 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Loaders, Electric Loaders, Pneumatic Loaders, Manual Loaders End User: Construction, Agriculture, Mining, Logistics Deployment: On-site, Off-site, Mobile, Stationary Application: Material Handling, Soil Loading, Waste Management, Bulk Transport |
| Companies Covered | Southworth Products Corporation, Bishamon Industries Corp., Presto Lifts, Inc., Vestil Manufacturing Corporation, Pentalift Equipment Corporation, Hymo Industries, Interthor Industries, Autoquip Corporation, Rhino Material Handling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Level Loader Market Trends and Innovations
Electrification architectures and predictive maintenance capabilities are redefining competitive differentiation in level loader supply, shifting value capture from hardware margins toward lifecycle service contracts.
Brushless DC motor systems with integrated position feedback are replacing hydraulic cylinders in mid-capacity applications. Third-party logistics providers in Germany and the United States are specifying these units for multi-shift operations. The technology is miniaturizing actuator footprints while maintaining load ratings, enabling platform designs that fit legacy facility layouts without structural modifications.
The EU Machinery Directive's 2023 update tightened requirements for stability testing under eccentric loading conditions. Manufacturers must now submit third-party validation of tip-over resistance before CE marking. Automotive assembly applications in Stuttgart and Wolfsburg industrial clusters are experiencing the longest certification backlogs as notified bodies prioritize high-risk machinery categories.
Equipment-as-a-service contracting is displacing capital purchase models among North American warehousing operators. Facility managers in Ohio and Pennsylvania industrial corridors are bundling level loader deployments with maintenance and uptime guarantees through regional distributor networks. The shift compresses supplier working capital cycles while transferring operational risk to OEM service organizations.
Level Loader Market Segmentation
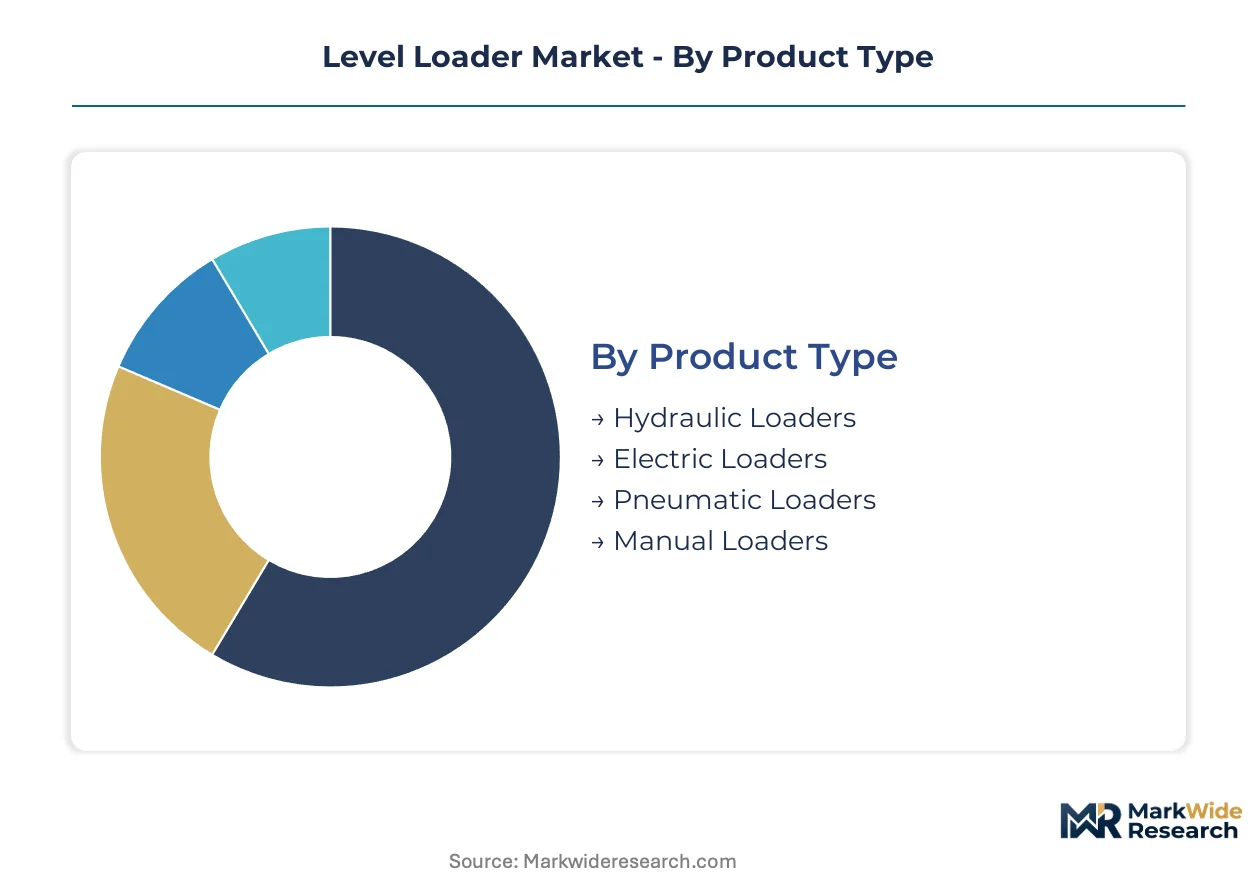
Segmentation in level loader supply reveals how regulatory frameworks, operational environments, and infrastructure constraints shape procurement decisions across industrial verticals. Understanding these divisions exposes where electrification mandates, ergonomic enforcement, and mobility requirements create divergent technology preferences.
Product Type:
OSHA ergonomic standards and the EU Machinery Directive impose divergent certification burdens on each actuation technology, compressing design cycles for electric variants while preserving niche exemptions for pneumatic systems in hazardous environments.
- Hydraulic Loaders:These units deploy petroleum-based fluid actuation systems delivering 2,000 to 6,000 pound capacities with 24 to 48 inch travel ranges. German logistics hubs specify hydraulic platforms for heavy palletizing operations where load stability algorithms must validate guarding compliance under the EU Machinery Directive's eccentric loading requirements. Petroleum-based hydraulic oil price volatility compresses margin predictability for manufacturers serving price-sensitive warehousing segments.
- Electric Loaders:Brushless DC motor systems with integrated position feedback enable quieter operation and lower energy costs across multi-shift operations. Third-party logistics providers in the United States and Germany are specifying these units for warehouse retrofit installations where carbon accounting rules favor electrified material handling fleets. Battery-electric industrial equipment categories qualify for accelerated depreciation under national green transition frameworks.
- Pneumatic Loaders:Compressed air actuation eliminates spark generation for explosion-sensitive chemical processing environments.
- Manual Loaders:Hand-crank or foot-pump mechanisms serve low-throughput operations without power infrastructure.
Electric loaders handle the majority of throughput; mobile deployment configurations are the fastest mover on share.
End User:
Cost tier differentiation separates capital-intensive project-based buyers from volume-driven fleet operators with recurring replacement cycles.
- Construction:Project-based procurement concentrates demand in fixed infrastructure installations.
- Agriculture:Seasonal throughput patterns favor mobile units for grain handling and equipment loading.
- Mining:Explosion-proof pneumatic loaders dominate where spark elimination matters in confined extraction environments.
- Logistics:Third-party fulfillment operators in Germany, the United States, and Japan are retrofitting mixed-model lines with electric level loaders to accommodate variable pallet dimensions without reconfiguring fixed infrastructure. OSHA ergonomic enforcement accelerates replacement of fixed-height platforms with adjustable units in United States warehouse operations.
Logistics commands the largest installed base; construction shows the steepest expansion trajectory in developing industrial corridors.
Deployment:
Application environment dictates whether load positioning equipment integrates with permanent facility infrastructure or operates as transferable assets.
- On-site:Fixed installation at dedicated material handling stations.
- Off-site:Temporary deployment for project-based construction or event logistics.
- Mobile:Castor-mounted or forklift-transportable units enable flexible floor layouts in third-party logistics facilities prioritizing reconfigurable workflows over fixed infrastructure. Cold chain and e-commerce fulfillment investments in Mumbai and Delhi industrial corridors remain underpenetrated for mobile ergonomic load positioning equipment.
- Stationary:Pit-mounted or bolted platforms serve high-throughput automotive assembly lines where Japanese OEMs retrofit mixed-model operations.
Mobile deployment is climbing the fastest; stationary configurations retain the deepest penetration in automotive assembly.
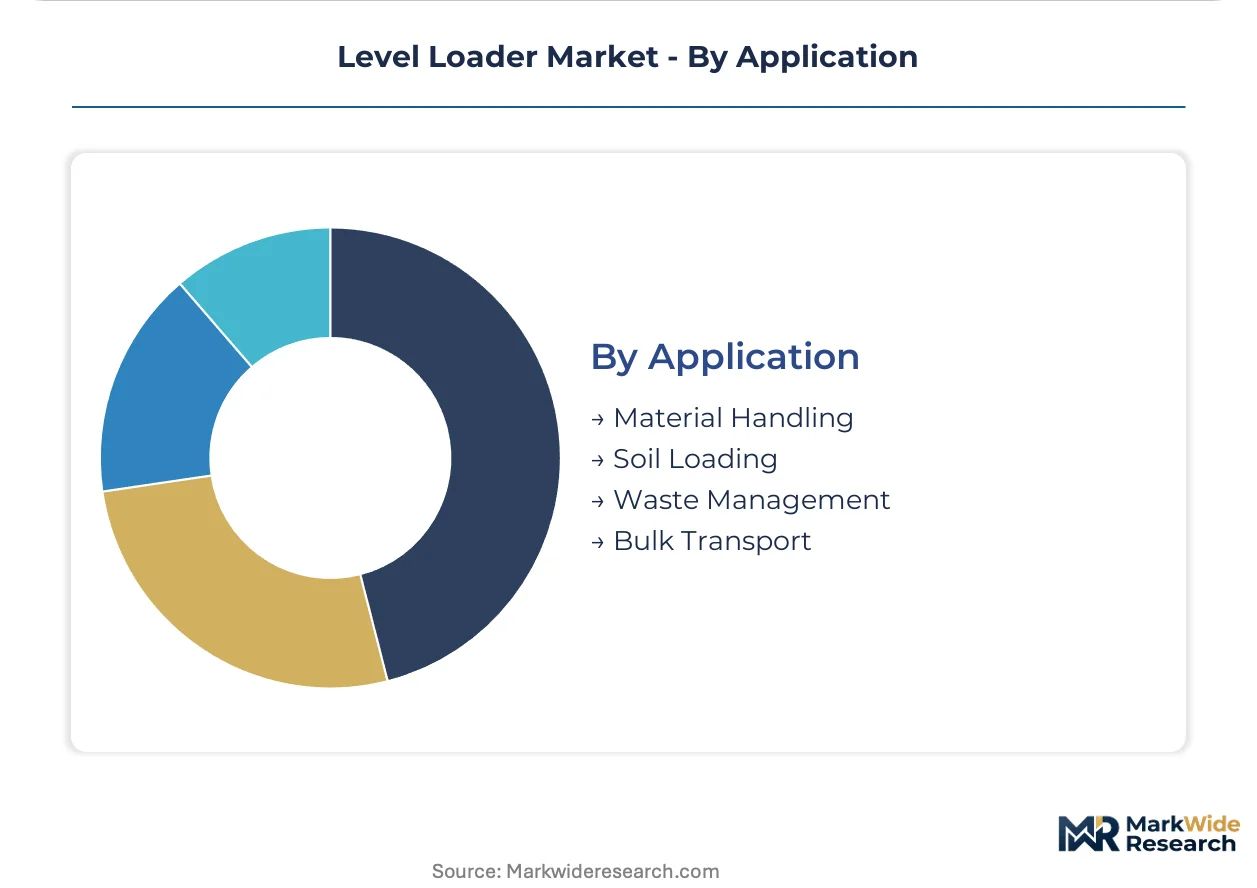
Application:
Volume concentration and margin structure vary sharply between repetitive palletizing operations and intermittent bulk material movement.
- Material Handling:Pallet loading, unloading, and assembly operations drive the core installed base where eliminating bending and stretching reduces musculoskeletal injury risk. Warehouse operators face escalating injury liability exposure under OSHA ergonomic guidelines, accelerating adjustable platform adoption.
- Soil Loading:Construction and landscaping applications require weather-resistant actuation systems.
- Waste Management:Contaminated environment specifications demand sealed hydraulic systems or pneumatic alternatives.
- Bulk Transport:Grain, aggregate, and chemical loading operations in agricultural and mining verticals.
Material handling generates the highest unit volume; waste management applications are gaining share fastest on regulatory compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA ergonomic enforcement anchors demand in the United States, while the EU Machinery Directive and Japan's METI standards reshape procurement patterns across export markets. Industrial clusters in Germany, Japan, and India concentrate investment in electrified material handling fleets.
United States
Warehouse operators face escalating injury liability exposure under OSHA ergonomic guidelines, accelerating replacement of fixed-height platforms with adjustable electric units. The Inflation Reduction Act's industrial electrification incentives favor battery-electric loader categories in multi-shift logistics operations. Third-party fulfillment providers in Ohio and Pennsylvania industrial corridors are bundling level loader deployments with maintenance guarantees through regional distributor networks.
Germany
Carbon accounting rules push logistics providers toward electrified material handling fleets, including level loaders with lithium-ion powertrains. The EU Machinery Directive's 2023 update tightened stability testing requirements under eccentric loading conditions, extending certification backlogs for automotive assembly applications. Stuttgart and Wolfsburg industrial clusters experience the longest validation delays as notified bodies prioritize high-risk machinery categories.
Japan
Automotive OEMs retrofit mixed-model assembly lines with electric level loaders to accommodate variable vehicle architectures without reconfiguring fixed infrastructure. METI industrial safety standards add certification complexity for load positioning equipment targeting automotive applications. Nagoya and Tokyo industrial corridors concentrate demand for stationary pit-mounted platforms in high-throughput manufacturing environments.
India
Cold chain and e-commerce fulfillment investments in Mumbai and Delhi industrial corridors remain underpenetrated for ergonomic load positioning equipment. The Production-Linked Incentive scheme for logistics infrastructure accelerates capital deployment in automated material handling. Domestic fabricators compete on cost for mobile deployment configurations serving flexible warehouse layouts.
United Kingdom
Post-Brexit regulatory divergence from EU Machinery Directive standards creates dual certification burdens for suppliers serving continental and domestic markets. Warehouse retrofit installations in the Midlands and Southeast England concentrate demand for specialized ergonomic designs. Third-party logistics operators prioritize quieter electric units to comply with local noise ordinances in urban distribution centers.
Level Loader Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the level loader supply base. The market structure consolidates around domestic production specialists and multinational material handling conglomerates with broad lifting equipment portfolios. Two strategic archetypes dominate: regional fabricators leveraging proximity for shorter lead times, and diversified industrial equipment suppliers capturing fleet procurement contracts. Competitive moves center on portfolio diversification into battery-electric variants and geographic expansion through distributor network consolidation.
Among North American specialists, Southworth Products Corporation and Bishamon Industries Corp. exemplify the regional fabricator archetype, while Presto Lifts, Inc. occupies a position within the diversified industrial equipment tier. These named companies represent contrasting strategic positions—domestic production footprint against specialized ergonomic design focus—without implying specific market share or technological superiority. The competitive dynamic rewards suppliers capable of integrating telematics-enabled predictive maintenance into service offerings, shifting value capture from hardware margins toward lifecycle contracts.
| Leading Market Players |
|---|
| Southworth Products Corporation |
| Bishamon Industries Corp. |
| Presto Lifts, Inc. |
| Vestil Manufacturing Corporation |
| Pentalift Equipment Corporation |
| Hymo Industries |
| Interthor Industries |
| Autoquip Corporation |
| Rhino Material Handling |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with German and Japanese automotive OEMs lock in steel platform supply and stabilize unit economics across multi-year procurement cycles. These arrangements transfer petroleum-based hydraulic oil volatility risk to fabricators while securing price visibility for fleet operators facing OSHA ergonomic compliance deadlines.
Pricing Analysis
North American electric level loader deployments command 15-20% premiums over hydraulic equivalents in Germany and Japan due to Inflation Reduction Act electrification incentives and regional carbon accounting rules. Three-tier pricing structure across premium brushless DC systems, standard electric units, and economy hydraulic platforms separates buyers by certification grade and after-sales service bundling. Cost compression in mid-capacity hydraulic tiers is intensifying because petroleum-based fluid price swings compress margin predictability for price-sensitive warehousing segments. Third-party logistics providers in the United States show highest price sensitivity, while Japanese automotive OEMs prioritize performance specifications over unit cost.
Supply Chain Analysis
Strait of Malacca transit routes underpin structural steel sourcing from concentrated East Asian foundry regions, creating input vulnerability for platform fabrication. Supply concentrates in China, South Korea, and Germany for precision-machined actuator components and high-grade structural steel. Raw material dependencies rest on petroleum-based hydraulic fluids, lithium-ion battery cells, and alloy steel plate. Single-source vulnerability in brushless DC motor controllers threatens electric loader production timelines. Distribution runs through regional distributor networks in Ohio, Pennsylvania, and Stuttgart industrial corridors, with aftermarket parts flowing through OEM service organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Level loader supply fragments across actuation technologies and regional compliance regimes, creating niche opportunities as electrification mandates diverge procurement priorities between German carbon accounting rules and Japanese METI safety standards.
For Market Incumbents: Shield installed base relationships through telematics-embedded predictive maintenance subscriptions that transfer operational risk to OEM service divisions. Deepen backward integration into lithium-ion powertrain assembly to capture margin from battery-electric loader categories qualifying for accelerated depreciation. Counter emerging equipment-as-a-service entrants by bundling uptime guarantees with shorter lead times from domestic production footprints. For New Entrants and Emerging Players: Anchor in India's cold chain and e-commerce fulfillment corridors where Mumbai and Delhi industrial corridors remain underpenetrated for mobile ergonomic load positioning equipment. Target third-party logistics retrofit installations requiring flexible floor layouts without structural modifications. Pursue distributor network consolidation in the Midlands and Southeast England where post-Brexit dual certification burdens disadvantage continental suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OEMs with telematics-enabled service organizations capable of lifecycle contract capture. Long-term viability over the projection horizon favors suppliers integrating predictive analytics platforms with hardware deployments. Acquisition targets should demonstrate regional production footprints serving automotive assembly clusters. Monitor battery-electric loader penetration rates in German logistics hubs as inflection indicator for electrification investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium-Ion Powertrains | Captures margin from battery-electric categories qualifying under German green transition frameworks. |
| Telematics-Enabled Predictive Maintenance Launch | Shifts value capture from hardware margins toward subscription revenue streams with Ohio logistics operators. |
| Regional Distributor Network Consolidation | Compresses working capital cycles for North American warehousing operators bundling deployments with guarantees. |
| EU Machinery Directive Certification Investment | Accelerates CE marking pathways for Stuttgart and Wolfsburg automotive assembly applications. |
| Mobile Deployment Configuration Expansion | Addresses underpenetrated cold chain investments in Mumbai and Delhi industrial corridors. |
Research Methodology
The analysis maps hydraulic, electric, pneumatic, and manual loader sub-sectors, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary interviews with third-party logistics operators in Germany, the United States, and Japan combined with secondary validation from OSHA enforcement databases, EU Machinery Directive filings, METI safety standard records, and customs trade data. Bottom-up unit shipment modeling and top-down industrial equipment spending triangulation anchored volume estimates across the projection horizon.
Consistency checks against external benchmarks validated volume and value outputs against industrial electrification investment disclosures and material handling fleet procurement patterns. The analytical framework segmented by actuation technology, deployment configuration, end-use vertical, and regional regulatory cluster across the analysis window. CAGRs derived from trend extrapolation of OSHA ergonomic enforcement intensity, carbon accounting rule adoption curves, and automotive assembly line retrofit cycles. Forecast inputs incorporated petroleum-based hydraulic oil price volatility indices and lithium-ion battery cost trajectories without year-specific references.
Underlying assumptions cover sustained OSHA enforcement intensity, EU Machinery Directive stability testing backlogs, and Japanese METI certification timelines, with deviation risk concentrated in petroleum price volatility and steel supply disruptions. Practitioners should keep alternative scenarios live as electrification code evolution and carbon accounting rule amendments reshape procurement priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
Swivel Coupler Market
Material Handling Equipment
Global Forklift Market
Material Handling Equipment
Belt Weigh Feeder Market
Material Handling Equipment
Industrial Girth Gear Market
Material Handling Equipment
Robotic Palletizers and De-Palletizers Market
Material Handling Equipment
Loaded Container Handler Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Drag Chain for Machine Market
Material Handling Equipment
Compactor Market
Material Handling Equipment
North America Screw Conveyor Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Heavy Duty Telehandler Market
Material Handling Equipment
Hydraulics Components Market
Material Handling Equipment
Middle East and Africa Conveyors Market