
 Tipper Pads Market | 2026-2036
Tipper Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Tipper Pads Market Intelligence
European production capacity for composite tipper pads is expanding to meet new vehicle weight regulations and performance demands. Continental AG leverages its extensive material science portfolio to develop durable rubber pads for the commercial vehicle sector. Freudenberg Group specializes in high-performance sealing and vibration control technologies applicable to tipper systems. Plastic Omnium Co. competes through its focus on lightweight plastic and composite components for automotive applications.
A tipper pad is a component, typically made of high-durometer rubber or composite materials, placed between a tipper body and the vehicle chassis. It functions to absorb impact, dampen vibration, and protect the vehicle structure from wear during operation. While rubber pads constitute a large market segment, composite pads see increased use in the demanding mining and construction sectors. Demand for enhanced surface protection and equipment stabilization applications is steering product development.
Vehicle safety standards from the U.S. National Highway Traffic Safety Administration (NHTSA) and commercial vehicle regulations within the European Union influence material and design specifications. Furthermore, ISO 9001 quality management standards are critical for suppliers to ensure product consistency and reliability. Future competitive differentiation depends on developing pads that meet stricter noise pollution limits and offer extended service life in harsh operational environments.
Market Dynamics
The central structural force shaping the tipper pads market is the dual pressure from vehicle lightweighting mandates and demand for increased operational durability. This is accelerating the material shift from traditional rubber to higher-performance polymer and composite solutions.
Growth Catalysts
- Infrastructure Investment:Government-led infrastructure projects, such as those funded by the Bipartisan Infrastructure Law in the United States, stimulate demand for new heavy-duty trucks and replacement components for existing fleets.
- Material Innovation:The development of advanced polyurethane and thermoplastic composites offers superior load-bearing capacity and resistance to abrasion and chemicals, attracting adoption in the demanding mining and construction sectors.
- Regulatory Standards:Stringent vehicle weight and safety regulations in the European Union are compelling fleet owners to adopt lightweight components, including composite pads, to maximize payload capacity without violating legal limits.
Market Restraints
- Cost Sensitivity:The higher upfront cost of advanced composite and polyurethane pads compared to conventional rubber alternatives remains a significant barrier to adoption for small fleet operators and in price-sensitive aftermarket channels.
- Raw Material Volatility:Price fluctuations in petroleum-derived raw materials, including synthetic rubber and specialized polymers, create margin pressure and supply chain uncertainty for manufacturers.
- Technical Limitations:Certain composite materials can exhibit brittleness under extreme cold or impact scenarios, posing performance limitations that restrict their application in specific harsh-environment mining operations in arctic regions.
Strategic Opportunities
- Smart Pad Development:Integrating sensors into pads to monitor load balance, vibration, and chassis stress offers a new value stream by providing actionable data for predictive maintenance and operational safety.
- Emerging Market Penetration:Targeting rapidly industrializing economies in Southeast Asia and Africa, where construction and mining activities are expanding, presents significant growth opportunities for tipper pad suppliers.
- Noise Reduction Solutions:Developing pads with enhanced acoustic dampening properties can address stricter urban noise pollution regulations, creating a specialized, high-margin product category for vehicles operating in populated areas.
Industry Challenges
- Fragmented Standardization:A lack of universal fitment and performance standards across diverse truck chassis and tipper body manufacturers complicates product design, increases inventory SKUs, and hinders economies of scale.
- Certification Complexity:Navigating the distinct and evolving compliance requirements of bodies like the U.S. NHTSA and Germany's KBA for commercial vehicle components adds significant time and cost to product development and market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tipper Pads Market |
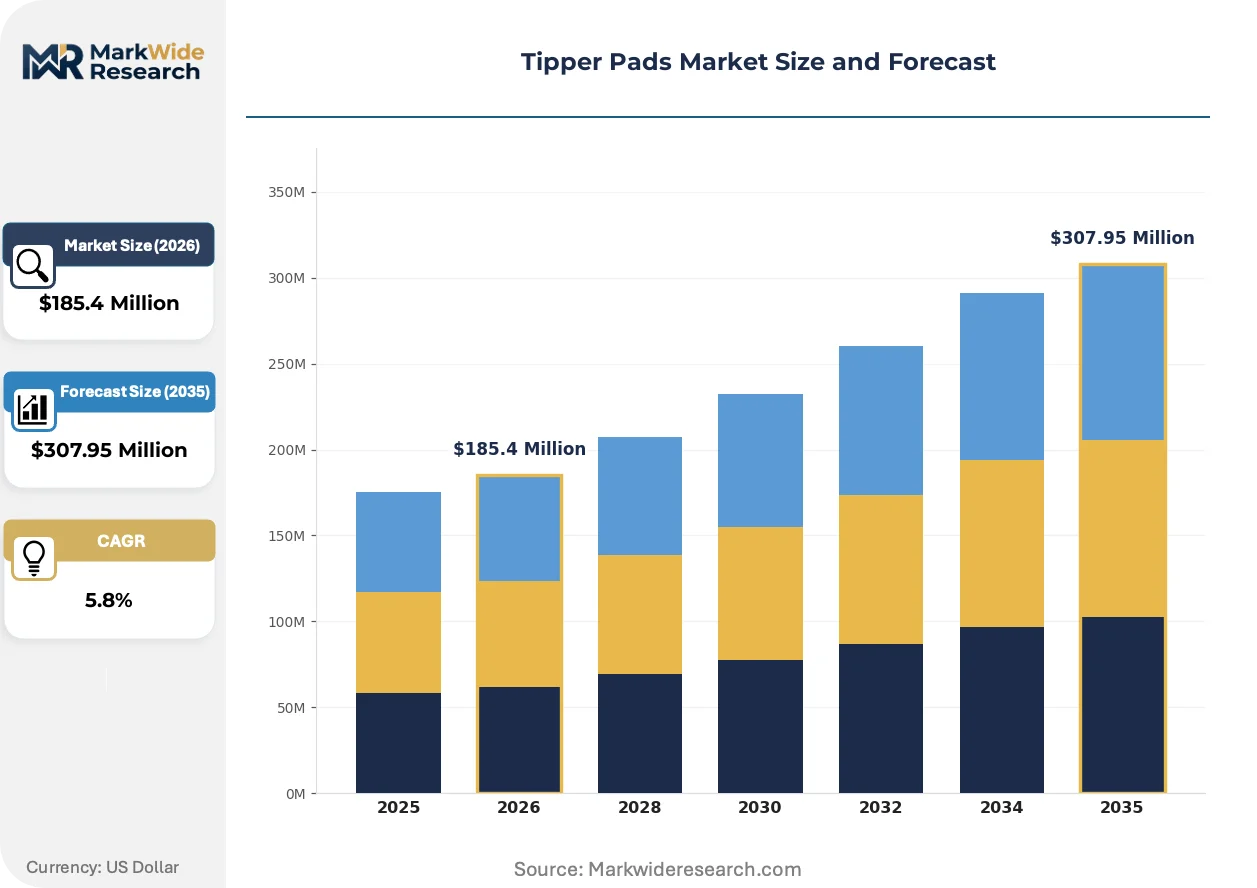
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $307.95 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Pads, Metal Pads, Composite Pads, Plastics Pads End User: Construction, Mining, Transportation, Agriculture Application: Load Handling, Vibration Dampening, Surface Protection, Equipment Stabilization Installation Method: Bolted, Adhesive Bonding, Welded, Integrated |
| Companies Covered | Magna International, Inc., Continental AG, ZF Friedrichshafen AG, Plastic Omnium Co., Polymax LTD., Autoneum, Freudenberg Group, Cooper-Standard Automotive, Albert Jagger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tipper Pads Market Strategic Shifts & Innovations
The tipper pad market is being redefined by the integration of advanced material science with digital feedback capabilities. This evolution is transforming pads from passive protective components into active contributors to vehicle efficiency, safety, and total cost of ownership.
Advanced composites and hybrid polymer formulations are the focus of product evolution. These materials provide a superior combination of impact absorption, wear resistance, and weight reduction compared to traditional rubber. Heavy-duty sectors like mining and aggregate transport are driving adoption, seeking to extend equipment service life and reduce maintenance downtime. This technology is unifying the previously separate goals of lightweighting for fuel efficiency and enhancing structural durability for harsh applications.
European Union regulations, particularly the framework supporting the EU Green Deal, are influencing material selection and product lifecycle management. These policies encourage the use of recyclable materials and sustainable manufacturing processes, impacting pad design. The composite pad segment is most affected, with manufacturers exploring thermoplastic polymers over thermosets to improve end-of-life recyclability and meet corporate sustainability reporting goals under directives like the CSRD.
A notable shift in purchasing behavior involves large fleet operators prioritizing total cost of ownership (TCO) over initial unit price. This model favors suppliers who can provide data-backed evidence of extended pad lifespan, reduced chassis wear, and lower maintenance frequency. This trend is most prominent within corporate logistics and large-scale construction fleets in North America and Germany, where operational efficiency is a primary competitive metric.
Tipper Pads Market Segmentation
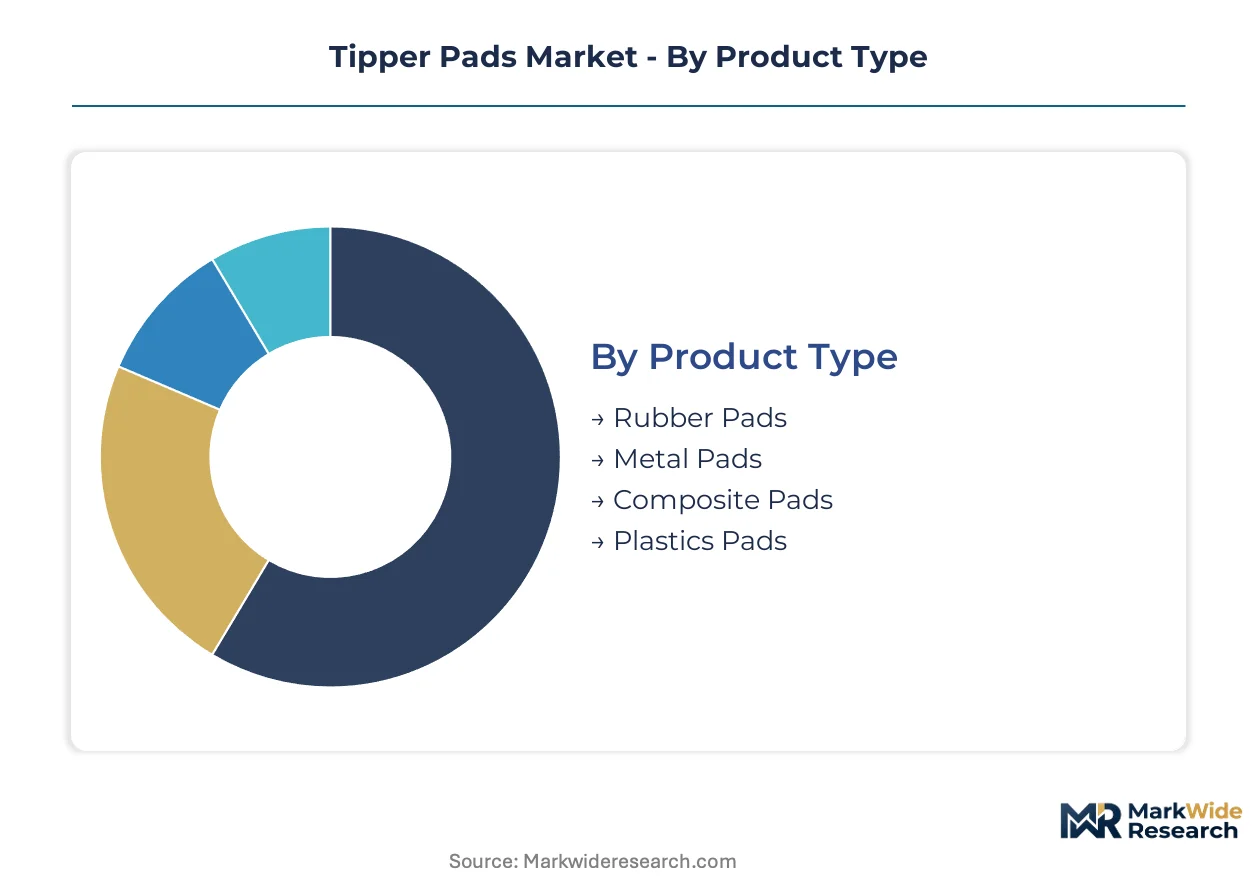
The segmentation of the tipper pads market provides a detailed understanding of product evolution and demand drivers across diverse operational environments. Analyzing these distinct categories helps stakeholders identify specific material preferences, end-user requirements, and functional priorities influencing purchasing decisions. This granular view is essential for strategic product development and market penetration.
Product Type:
The upgrade and replacement cycles heavily influence material choices within this segment, as operators weigh initial cost against long-term durability and performance. New vehicle procurements increasingly specify advanced solutions.
- Composite Pads:These advanced materials, combining polymers with reinforcing fibers, offer superior strength-to-weight and wear resistance. Demand concentrates in heavy-duty construction and mining in the US and Germany, driven by lightweighting and extended service life.
- Rubber Pads:Made from high-durometer natural or synthetic rubber, these pads provide excellent vibration dampening and impact absorption. They remain a large market segment in aftermarket channels and general transportation, due to cost-effectiveness.
- Plastics Pads:These lighter pads find application in less demanding environments, prioritizing weight reduction. They are often utilized in smaller tipper bodies.
- Metal Pads:Primarily steel or aluminum, these pads are used in niche, extremely harsh applications requiring maximum rigidity and abrasion resistance.
Volume placements concentrate in Rubber Pads; the faster expansion belongs to Composite Pads.
End User:
The specific operational applications and environmental conditions of each end-user segment dictate required performance characteristics and material specifications. Industries prioritize distinct attributes like abrasion resistance or load capacity.
- Construction:This sector requires pads withstanding heavy loads, frequent impacts, and abrasive materials like aggregates. Infrastructure projects in the United States and Europe drive demand for durable, high-performance pads.
- Mining:Mining operations present extremely harsh conditions, demanding pads with exceptional wear resistance, impact strength, and resistance to extreme temperatures. Specialized composite pads gain traction in Australia and Canada for longevity.
- Transportation:Commercial logistics and general freight fleets utilize tipper pads for bulk material movements. Cost-effectiveness and reliable vibration dampening are primary considerations.
- Agriculture:Agricultural tippers, used for grain or produce, require pads offering basic protection and vibration absorption. This segment prioritizes economical solutions.
The construction sector represents the largest demand pool, while mining operations are driving innovation in high-performance materials.
Application:
The evolution of tipper pad functionalities reflects a shift from passive components to active contributors to vehicle efficiency and safety. Manufacturers design pads for specialized roles beyond basic protection.
- Vibration Dampening:Pads significantly reduce structural fatigue and noise by absorbing shocks and vibrations between the tipper body and chassis. This application is critical for driver comfort and extends vehicle lifespan.
- Surface Protection:These pads prevent direct metal-on-metal contact, safeguarding the tipper body and vehicle chassis from wear, scratches, and corrosion. This function is vital in construction and waste management.
- Load Handling:Pads designed for load handling ensure even weight distribution and prevent cargo shifting during transport. They contribute to vehicle stability and safety.
- Equipment Stabilization:These pads provide enhanced stability during the tipping process itself, minimizing sway and improving safety during material discharge.
While surface protection remains a core function, vibration dampening solutions are experiencing significant technological advancements.
Installation Method:
Supply chain configurations and manufacturing capabilities heavily influence the prevalence of different installation methods, some requiring specialized tooling or expertise. This choice impacts initial assembly costs and maintenance accessibility.
- Bolted:This traditional method uses mechanical fasteners to secure pads, offering ease of replacement and robust attachment. It is widely adopted across various vehicle types, especially for heavier pads in construction equipment.
- Integrated:Pads designed for integration are often molded directly into or permanently bonded within vehicle components during manufacturing. This approach reduces assembly time and offers a seamless fit for original equipment manufacturers (OEMs).
- Adhesive Bonding:This method uses high-strength industrial adhesives, offering a cleaner aesthetic and potentially better vibration isolation. It suits lighter pads.
- Welded:Primarily for metal pads, welding provides an extremely strong, permanent attachment. This method is less common for non-metallic tipper pads.
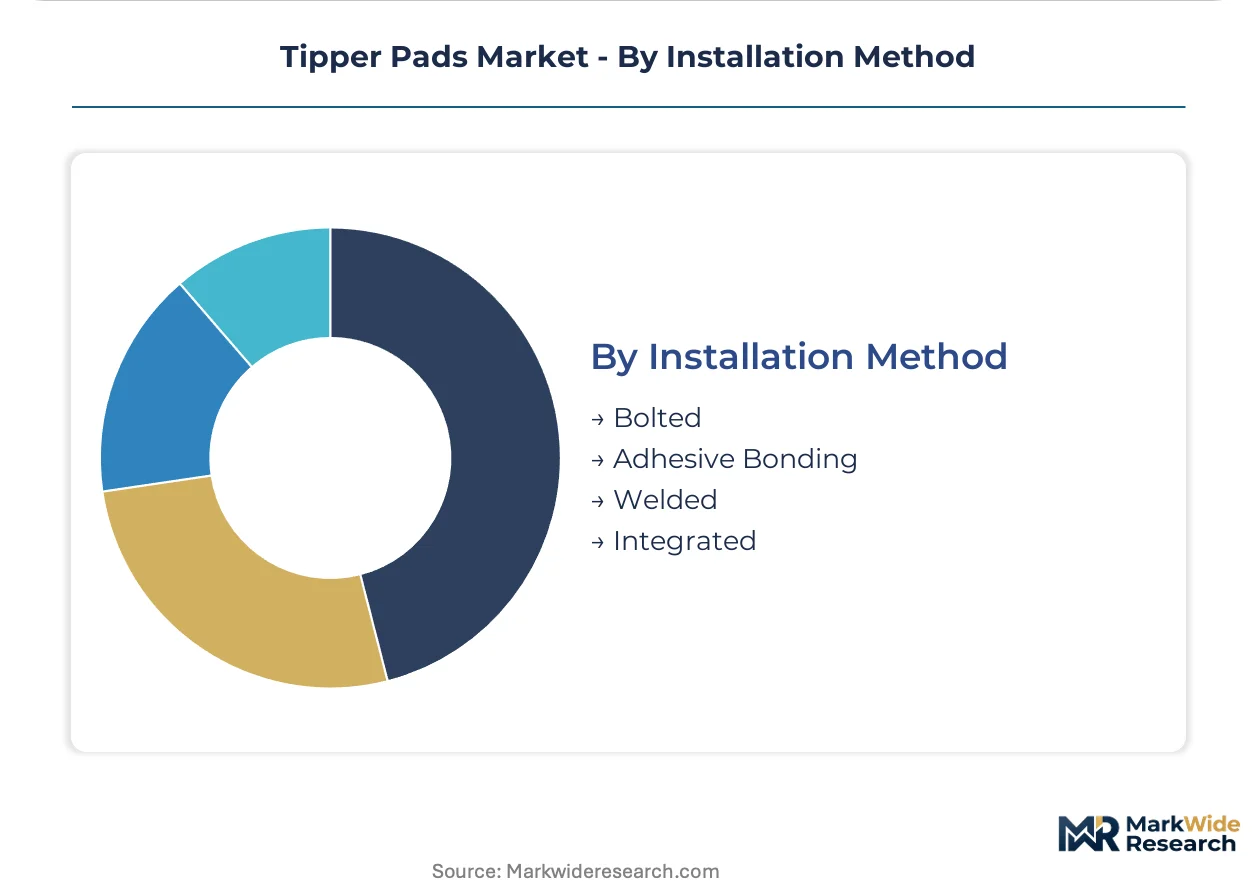
Bolted installations dominate the aftermarket, while integrated solutions are gaining traction with original equipment manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The market for tipper pads relies heavily on advanced polymers and composite materials. Germany's strong material science and advanced manufacturing base establishes it as a key center for developing high-performance tipper pad solutions. This expertise supports innovation across the global supply chain.
United States
The United States market sees significant demand from government-led infrastructure projects. The Bipartisan Infrastructure Law stimulates procurement for new heavy-duty trucks and replacement components. Large-scale construction fleets in states like Texas and California prioritize operational efficiency.
Germany
Germany experiences strong demand linked to logistics fleet modernization and vehicle lightweighting initiatives. Commercial vehicle regulations within the European Union compel fleet owners to adopt lightweight components. Manufacturing hubs in Bavaria and Baden-Württemberg integrate advanced polymer and composite pads.
Australia
Mining operations in Australia present extremely harsh conditions, requiring pads with exceptional wear resistance. Industry-specific safety standards influence material specifications for equipment in this sector. Mining regions in Western Australia and Queensland drive innovation for specialized composite pads.
Canada
Canadian mining activities, particularly in arctic regions, demand tipper pads capable of extreme cold performance. National safety standards shape material and design specifications for heavy equipment. Mining operations in Ontario and British Columbia seek solutions to overcome material brittleness limitations.
India
India's rapidly industrializing economy and expanding construction activities generate substantial demand for tipper pads. The Bureau of Indian Standards (BIS) influences product quality and material specifications for commercial vehicles. Infrastructure projects in Maharashtra and Gujarat stimulate procurement for both new and replacement components.
Tipper Pads Market Key Industry Players
Global majors compete with regional champions across material innovation and application-specific performance. The tipper pads market exhibits a tiered structure, with a few large, diversified suppliers alongside numerous smaller, specialized manufacturers. Two strategic archetypes dominate: integrated material science companies and niche component fabricators. Companies pursue strategic partnerships and portfolio diversification to enhance their market presence.
Among European-based material science specialists, Continental AG exemplifies a diversified approach, leveraging extensive material science portfolios for durable rubber pads in the commercial vehicle sector. Freudenberg Group occupies a position in high-performance sealing and vibration control technologies, applicable to tipper systems. Plastic Omnium Co. represents a focus on lightweight plastic and composite components, particularly for automotive applications where weight reduction is critical. These companies collectively anchor the premium segment by developing advanced solutions for durability, vibration dampening, and weight reduction. Their presence underscores the market's shift towards higher-performance materials and engineering expertise to meet evolving regulatory and operational demands.
| Leading Market Players |
|---|
| Magna International, Inc. |
| Continental AG |
| ZF Friedrichshafen AG |
| Plastic Omnium Co. |
| Polymax LTD. |
| Autoneum |
| Freudenberg Group |
| Cooper-Standard Automotive |
| Albert Jagger |
| Others |
Cost & Logistics Intelligence
European Union sustainability mandates, particularly those under the EU Green Deal, gate both qualified supply and premium-tier pricing access for tipper pad manufacturers. These policies encourage the use of recyclable materials and sustainable manufacturing processes, impacting pad design and material selection.
Pricing Analysis
Warranty and service bundling often differentiates offerings in the tipper pads market, especially for high-performance composite solutions. The dominant pricing structure is typically per-unit transactional, though large fleet operators negotiate contract-based long-term offtake agreements. Price differentiation stems from material quality grade, such as advanced composites versus conventional rubber, and certification levels like ISO 9001. Cost compression in conventional rubber pads is intensifying due to commoditization and raw material price volatility. Small fleet operators and aftermarket channels remain highly price-sensitive, while large construction and mining fleets prioritize total cost of ownership over initial unit price.
Supply Chain Analysis
Dual-sourcing requirements from major OEMs and large fleet operators drive diversification within the tipper pads supply chain. Geographic supply concentration includes Germany for advanced material science, the United States for heavy-duty vehicle manufacturing, and Asian countries for rubber and basic polymer production. The market draws from petroleum-derived polymers, synthetic rubber, and reinforcing fibers like carbon or glass. Raw material volatility, particularly in petroleum prices, creates a significant supply chain risk for manufacturers. Distribution runs through direct OEM supply, specialized industrial distributors, and a fragmented aftermarket network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tipper pads market reads as a consolidation play, where increasing regulatory complexity and cost sensitivity pressure smaller, less innovative players. This environment favors larger entities with diversified portfolios and strong R&D capabilities.
For Market Incumbents: Anticipate continued pressure from vehicle lightweighting mandates by accelerating advanced composite material R&D. Expand global manufacturing footprint, particularly in regions with robust infrastructure investment like the United States and Germany, to mitigate logistics costs. Reinforce OEM partnerships through co-development initiatives for integrated pad solutions. Invest in certification processes for new materials to meet evolving regulatory standards across diverse geographies.
For New Entrants and Emerging Players: Launch via specialized distribution channels, targeting underpenetrated segments with innovative solutions like smart pads. Focus on niche applications, such as extreme cold mining environments or urban logistics requiring enhanced noise reduction. Penetrate rapidly industrializing economies in Southeast Asia and Africa, offering cost-effective yet durable solutions. Emphasize value-based selling by highlighting total cost of ownership benefits, rather than competing solely on upfront price.
For Investors and Strategic Acquirers: Significant adoption of smart pad technology by large fleet operators is the leading indicator that value creation is shifting from material science to integrated data solutions. The long-term viability of this market over a 5-10 year window remains strong, driven by infrastructure development and fleet modernization. Target specialized composite material fabricators or sensor technology integrators for acquisition, focusing on companies with strong intellectual property and established OEM relationships. Deviation in raw material price stability would shift the outlook materially.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Advanced Composites | Increases production scale for high-demand, lightweight materials in key manufacturing hubs. |
| Integration of Sensor Technology | Transforms pads into smart components, offering new value streams for predictive maintenance and safety. |
| Strategic OEM Partnerships | Secures long-term supply agreements and facilitates co-development of integrated vehicle solutions. |
| Targeted Geographic Expansion | Captures growth in emerging economies with expanding construction and mining sectors. |
| Recyclable Material Development | Addresses EU Green Deal mandates and improves corporate sustainability reporting for manufacturers. |
Research Approach
Independent corroboration across heavy-duty vehicle OEMs, fleet procurement managers, and material scientists underwrites the qualitative findings within this analysis. Primary interviews with component engineers and aftermarket distributors provided direct market insights. Secondary validation involved reviewing NHTSA accident data, EU vehicle regulation documents, ISO standards databases, and corporate sustainability reports, ensuring a robust bottom-up and top-down triangulation.
The forecast framework utilizes a comparable-period approach, anchoring projections to historical performance across the analysis window. Segmentation dimensions modeled include product type (composite pads, rubber pads), end-user (construction, mining), installation method (bolted, integrated), and key geographic regions. Compound annual growth rates were derived from detailed market size assessments and future projections based on identified growth catalysts. Infrastructure spending forecasts and heavy-duty vehicle production volumes served as critical industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for advanced polymer composites would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and raw material availability. Deviation in raw material price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Cherry Picker Crane Market
Material Handling Equipment
Drive-In Pallet Racking Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Slag Handling Machine Market
Material Handling Equipment
Electric Wire Rope Hoist Market
Material Handling Equipment
Vibrating Screen Market
Material Handling Equipment
Hose Pipe Market
Material Handling Equipment
Fork Lift Attachments Market
Material Handling Equipment
Latin America Conveyors Market
Material Handling Equipment
Global Forklift Market
Material Handling Equipment
Belt Scales Market
Material Handling Equipment
Log Loaders Market
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
Asia-Pacific Forklift Truck Market
Material Handling Equipment
Forklift Rental Market