
 Log Loaders Market | 2026-2036
Log Loaders Market Size, Share, and Industry Trends Forecast 2026-2036
Log Loaders Market Analysis
The log loaders market is restructuring around a widening capability gap between premium knuckleboom grapple systems and commodity straight-boom configurations. Caterpillar leverages its powertrain integration depth to dominate high-cycle applications in steep terrain. Komatsu anchors its position through hydrostatic drive refinement and telematics bundling. John Deere differentiates via dealer density and forestry-specific attachment ecosystems.
Log loaders are self-propelled material handling machines engineered to lift, transport, and sort felled timber using hydraulic grapple or bucket attachments, typically rated by lift capacity at maximum reach and swing torque. Track loaders lead in soft-ground forestry applications where ground pressure below 35 kPa prevents soil compaction, while wheel loaders retain share in roadside mill yards where travel speed and fuel efficiency govern operating economics. Electric and hybrid technology segments are expanding fastest among municipal and European contractors facing emission zone restrictions, though diesel units still occupy the majority of remote harvesting sites lacking grid infrastructure.
EPA Tier 4 Final and EU Stage V standards are forcing engine after-treatment complexity that elevates first cost and maintenance intervals, reshaping fleet replacement cycles. OSHA logging safety directives and ISO 11850 machinery guarding specifications further constrain design freedom and compliance documentation burdens. Stakeholders must monitor battery energy density trajectories and charging infrastructure buildout in key timber basins to time capital commitments between incumbent diesel platforms and emerging electric architectures.
Market Dynamics
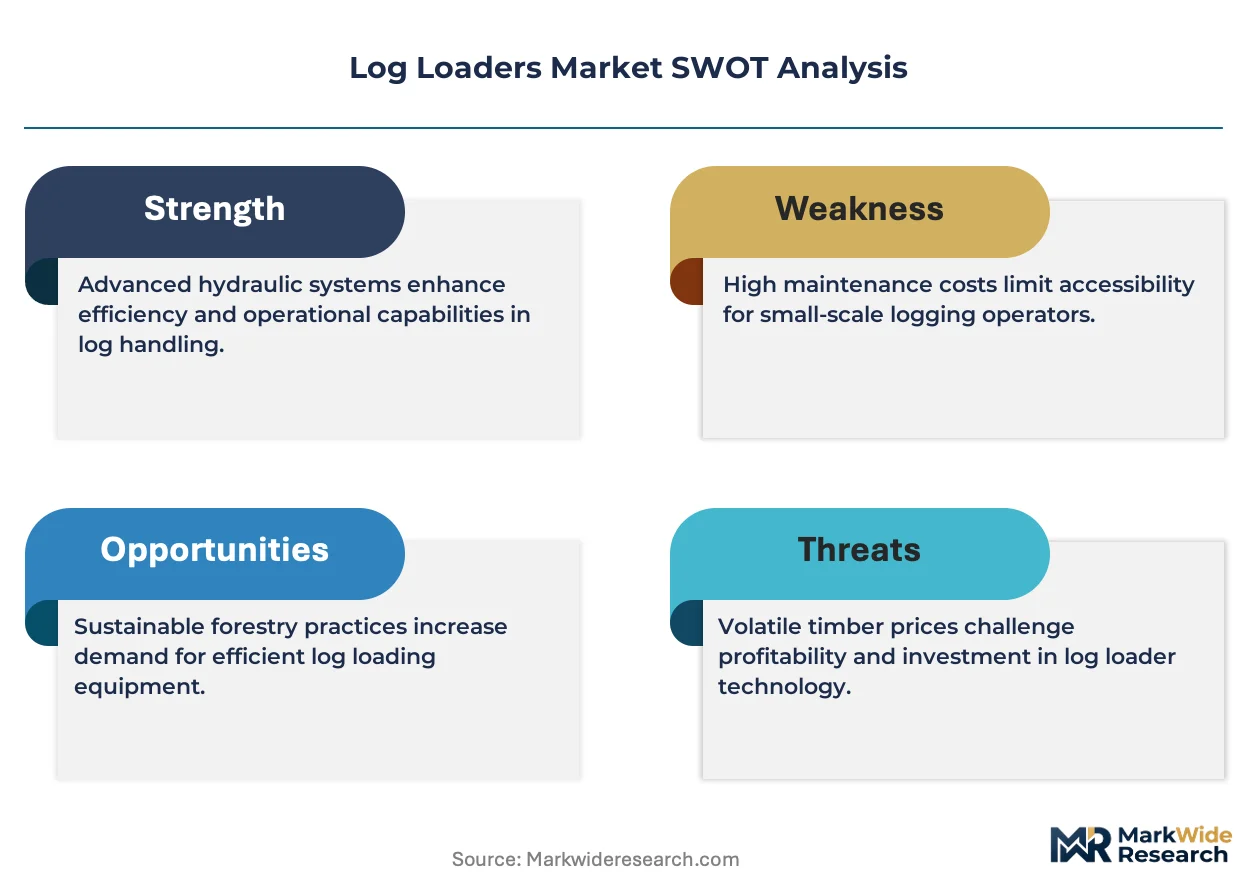
EPA Tier 4 Final and EU Stage V emission mandates are compressing diesel loader margins while accelerating electric-hybrid platform development. Contractors face capital allocation pressure between incumbent powertrains and unproven electrification architectures.
Growth Catalysts
- Mechanized harvesting mandates:Scandinavian forestry regulators now require grapple-equipped loaders for steep-slope operations, pulling demand for knuckleboom configurations with extended reach capabilities.
- EU Green Deal timber certification:Sustainable sourcing requirements in Germany and France favor low-ground-pressure track loaders that minimize soil disturbance during extraction cycles.
- Battery energy density improvements:Lithium-ion pack designs now deliver sufficient duty cycles for eight-hour municipal logging shifts, enabling electric unit deployment in European emission zones.
Market Restraints
- After-treatment cost inflation:Diesel particulate filters and selective catalytic reduction systems add procurement burden and maintenance complexity to Tier 4 Final-compliant engines.
- Charging infrastructure gaps:Remote harvesting basins in Canada, Russia, and Brazil lack grid connectivity sufficient for electric loader recharging, constraining zero-emission adoption.
- Steel and hydraulic component volatility:Boom cylinder and grapple actuator supply chains face input cost pressure from commodity price swings, squeezing OEM margins.
Strategic Opportunities
- US Pacific Northwest rental consolidation:Fleet operators are concentrating procurement volumes, creating preferred supplier arrangements for multi-unit contracts with standardized telematics.
- Telematics-ERP convergence:Loader operating data integration with contractor enterprise systems enables predictive maintenance and fuel optimization services.
- Japanese steep-terrain automation:METI-supported R&D programs are advancing semi-autonomous grapple control for hillside harvesting applications.
Industry Challenges
- Certified technician scarcity:EPA and EU Stage V after-treatment systems require specialized diagnostic skills that forestry labor pools lack, extending downtime intervals.
- Legacy fleet integration friction:Electric-hybrid loaders demand incompatible maintenance protocols and charging infrastructure, complicating mixed-fleet contractor operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Log Loaders Market |
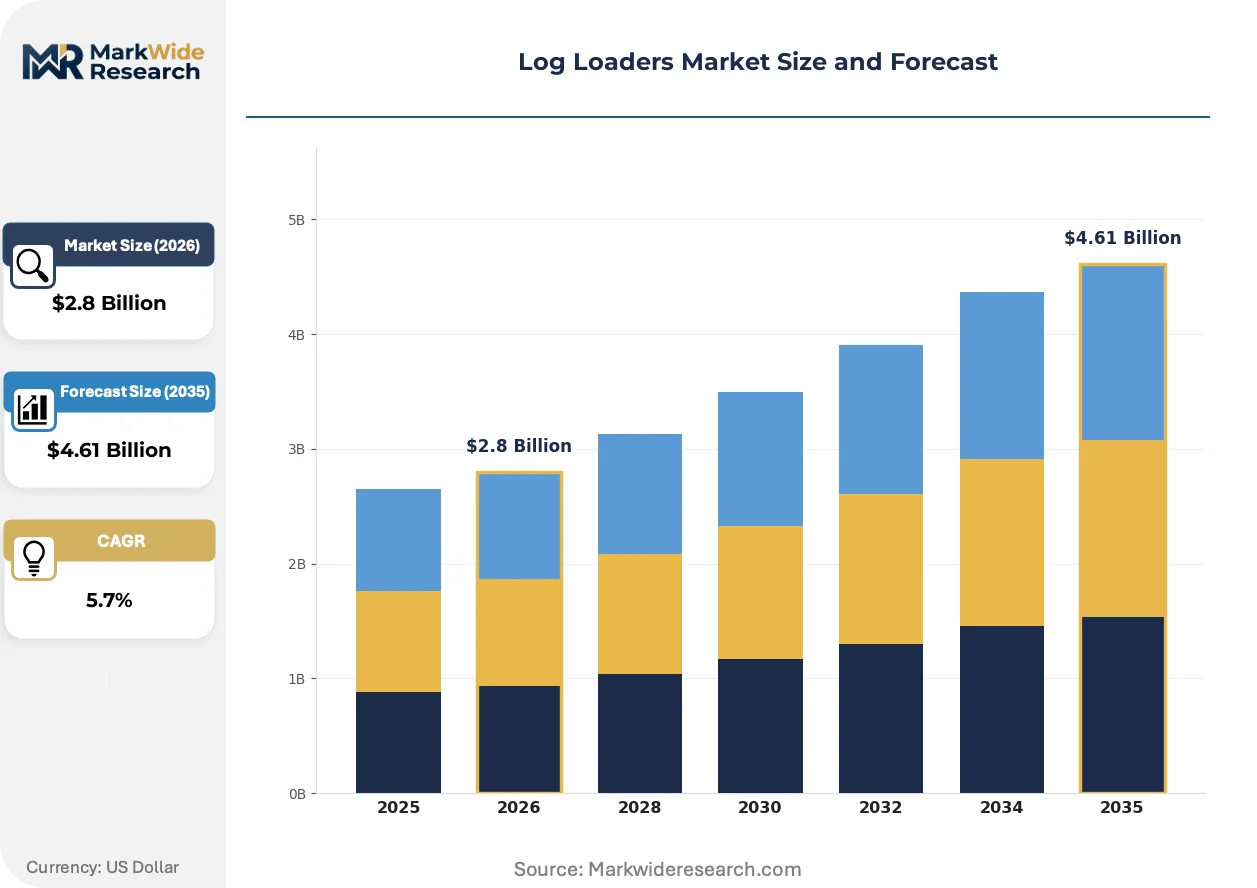
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheel Loaders, Track Loaders, Hydraulic Loaders, Grapple Loaders Application: Lumber Industry, Forestry Operations, Construction Sites, Recycling Facilities Technology: Electric, Diesel, Hybrid, Smart Loaders End User: Contractors, Timber Merchants, Municipalities, Equipment Rental Services |
| Companies Covered | Caterpillar, Komatsu, DEVELON, Uotani Iron Works, Igland, Prentice, John Deere, Doosan, Tigercat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Log Loaders Market Emerging Trajectories
Electrification architectures and autonomous control systems are restructuring competitive capability requirements. OEMs must now integrate power electronics expertise alongside traditional hydraulic engineering competencies.
Electro-hydraulic actuation is integrating digital valve control with conventional grapple circuits, enabling precision load handling previously requiring operator experience. Municipal contractors in German emission zones are specifying these systems for urban forestry applications. This convergence is integrating software-defined functionality into hardware-dominated loader architectures, compressing differentiation timelines.
EPA Tier 4 Final compliance deadlines have forced widespread adoption of exhaust after-treatment systems across diesel loader portfolios. Engine manufacturers now bundle extended warranty programs to offset reliability concerns from added component complexity. North American contractors are responding by extending replacement cycles and prioritizing remanufactured powertrains.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-scale European logging cooperatives. Rental fleet operators capture maintenance revenue streams while contractors convert fixed asset burdens to operating expenses. This shift is most pronounced in Sweden and Finland, where seasonal harvest variability favors flexible capacity arrangements over owned equipment.
Log Loaders Market Segmentation
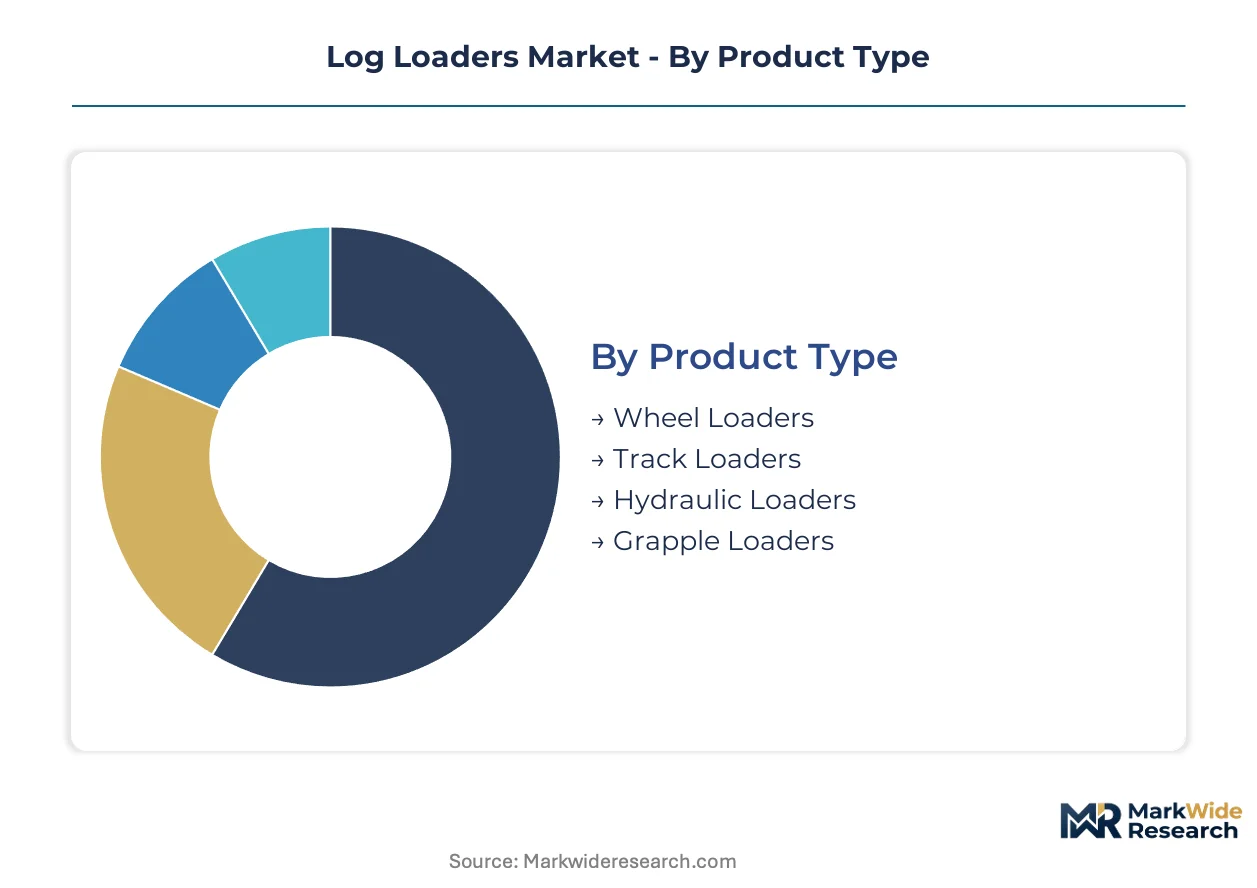
Log loader procurement decisions hinge on ground conditions, duty cycles, and emission zone access. Buyers match undercarriage configuration to terrain, powertrain to operating hours, and grapple geometry to timber species handled.
Product Type:
Ground pressure ratings and travel speed requirements drive the initial equipment specification.
- Wheel Loaders:Pneumatic-tired configurations deliver travel speeds exceeding 35 km/h for mill yard operations. Fleet operators in roadside processing facilities prioritize these units for fuel efficiency during frequent repositioning cycles.
- Track Loaders:Steel or rubber-tracked undercarriages distribute operating weight across broad ground contact areas. Scandinavian steep-slope contractors specify these for terrain where ground pressure must remain below 35 kPa to prevent root damage and soil compaction.
- Hydraulic Loaders:Straight-boom designs with fixed grapple circuits serve commodity extraction operations. These units dominate emerging market procurement where capital constraints limit technology investment.
- Grapple Loaders:Knuckleboom articulation with rotating grapple heads enables precision sorting and loading. Mechanized harvesting mandates in Norway and Sweden pull demand for extended-reach configurations.
Track loaders lead on scale; grapple loaders lead on momentum.
Application:
End-use environment dictates guarding specifications, boom reach requirements, and duty cycle intensity.
- Lumber Industry:Sawmill infeed operations and log yard management require high-cycle loading with consistent grapple positioning. US Pacific Northwest integrated processors specify telematics-equipped units for production tracking.
- Forestry Operations:Felling site extraction and forwarding demand robust undercarriages and protective guarding against falling debris. Finnish and Swedish contractors face regulatory pressure for low-impact extraction methods.
- Construction Sites:Temporary material handling for infrastructure projects uses versatile loader configurations. Municipal contractors in German emission zones specify electric-hybrid units for urban proximity work.
- Recycling Facilities:Mixed waste and biomass handling requires reinforced grapple designs with debris-resistant hydraulics. These applications favor used equipment conversions over new procurement.
Forestry operations anchor volume demand; recycling facilities show steepest expansion trajectory.
Technology:
Powertrain selection balances first cost against fuel expense, maintenance intervals, and regulatory compliance burdens.
- Electric:Battery-electric architectures eliminate tailpipe emissions and reduce noise signatures. German and French municipal contractors deploy these in urban emission zones where grid infrastructure supports overnight charging.
- Diesel:Compression-ignition engines with Tier 4 Final or Stage V after-treatment retain dominance in remote harvesting basins. Canadian and Russian operators lack charging infrastructure for alternative powertrains.
- Hybrid:Diesel-electric configurations capture regenerative energy from boom lowering cycles. Japanese R&D programs supported by METI advance these systems for steep-terrain fuel efficiency.
- Smart Loaders:Integrated telematics, semi-autonomous grapple control, and predictive maintenance algorithms. These systems gain traction among large rental fleet operators seeking utilization optimization.
Diesel retains installed base dominance; electric powertrains gain share fastest.
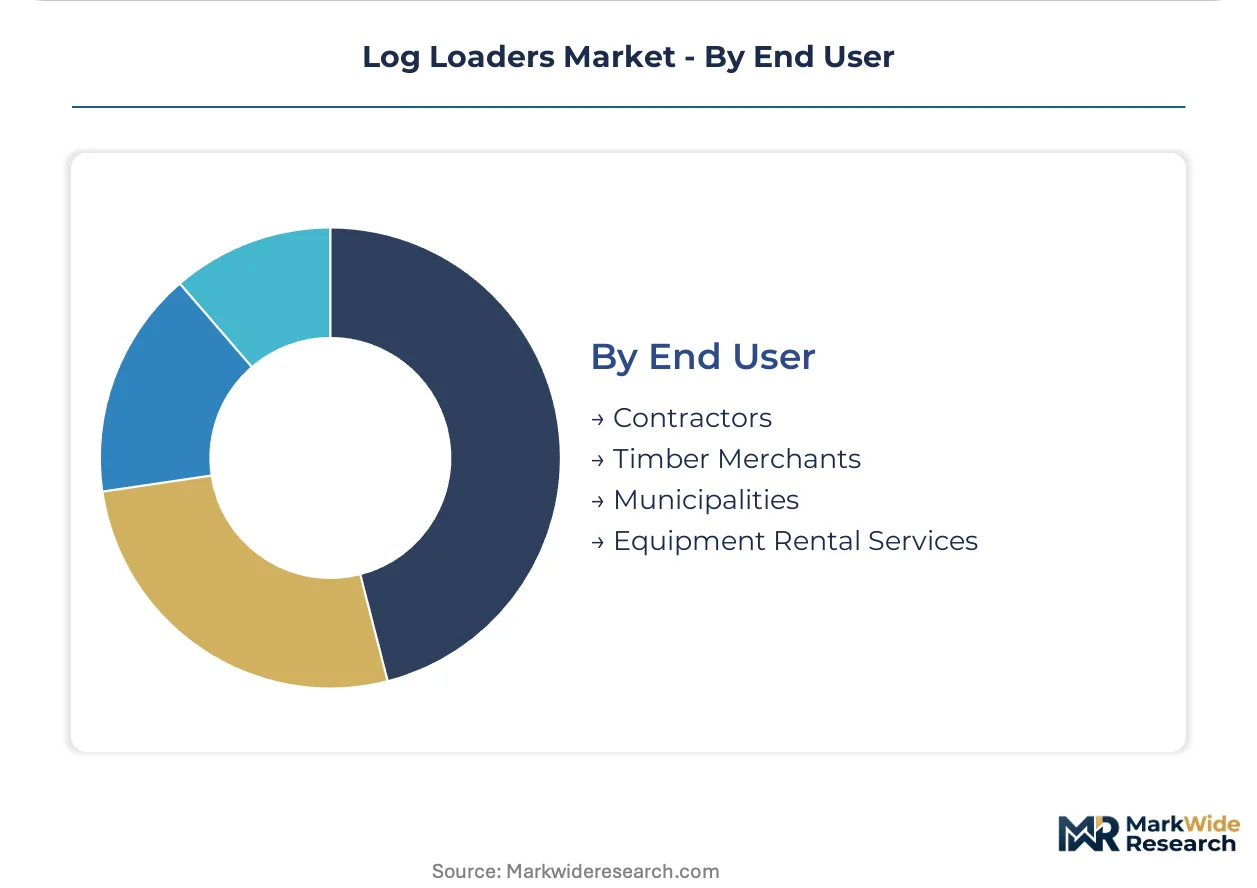
End User:
Capital availability and equipment utilization rates determine ownership versus rental models.
- Contractors:Independent logging operators with seasonal demand variability. Swedish and Finnish cooperatives increasingly favor equipment-as-a-service arrangements over asset ownership.
- Timber Merchants:Vertically integrated forest products companies with continuous harvesting requirements. These buyers standardize fleets around single OEM platforms to compress parts inventory and technician training costs.
- Municipalities:Public sector urban forestry and park maintenance departments. German cities specify electric units for noise and emission compliance in populated areas.
- Equipment Rental Services:Fleet operators aggregating demand across fragmented contractor bases. US Pacific Northwest rental consolidation creates preferred supplier arrangements for multi-unit contracts.
Contractors represent the largest addressable base; rental services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled equipment operators and certified forestry technicians concentrate in timber basins with mechanized harvesting mandates. Their expertise anchors regional procurement patterns. Regulatory compliance requirements reshape capital deployment across key markets.
United States
Pacific Northwest contractors drive knuckleboom grapple demand for steep-slope extraction. OSHA logging safety directives mandate protective guarding and operator certification programs. Seattle-Tacoma rental fleet operators concentrate multi-unit procurement volumes with standardized telematics requirements.
Sweden
Mechanized harvesting regulations now require grapple-equipped loaders for all steep-terrain operations. The EU Green Deal timber certification favors low-ground-pressure track configurations. Västerbotten and Norrbotten counties host contractor cooperatives shifting from ownership to equipment-as-a-service models.
Germany
Municipal urban forestry departments specify electric-hybrid units for emission zone compliance. The EU Stage V standard compresses diesel loader margins through after-treatment cost inflation. Bavarian cities deploy battery-electric architectures where grid infrastructure supports overnight charging cycles.
Canada
Remote harvesting basins in British Columbia retain diesel dominance due to charging infrastructure gaps. EPA Tier 4 Final compliance elevates first cost and maintenance complexity for new equipment. Vancouver Island contractors extend replacement cycles and prioritize remanufactured powertrains.
Japan
METI-supported R&D programs advance semi-autonomous grapple control for hillside harvesting. Domestic steep-terrain automation reduces operator fatigue in mountainous forestry operations. Nagoya industrial clusters integrate electro-hydraulic actuation with conventional loader circuits for precision load handling.
Log Loaders Market Vendor Landscape
Top-tier vendors anchor premium knuckleboom grapple systems, while commodity straight-boom fabricators compete on first cost. The vendor base stratifies across powertrain integration depth, dealer density, and telematics bundling capability. Three archetypes dominate: integrated powertrain specialists, hydrostatic drive refiners, and forestry-specific attachment ecosystem builders. Consolidation concentrates procurement volumes among rental fleet operators, while OEMs diversify through predictive maintenance service offerings.
Among North American equipment manufacturers, Caterpillar, John Deere, and Tigercat occupy positions across the capability spectrum. Caterpillar exemplifies powertrain integration depth for high-cycle steep terrain applications. John Deere represents dealer density and attachment ecosystem strategies. Tigercat anchors specialized forestry equipment fabrication with regional service infrastructure. Komatsu and Doosan exemplify hydrostatic drive refinement and telematics bundling approaches among Asia-Pacific headquartered manufacturers. DEVELON, Uotani Iron Works, Igland, and Prentice sit within specialized tier configurations serving regional procurement patterns.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu |
| DEVELON |
| Uotani Iron Works |
| Igland |
| Prentice |
| John Deere |
| Doosan |
| Tigercat |
| Others |
Supply Flow & Price Mechanics
Equipment rental fleet operators in the US Pacific Northwest concentrate procurement volumes, creating preferred supplier arrangements that compress transaction margins while elevating service bundling premiums for telematics-integrated contracts.
Pricing Analysis
Equipment-as-a-service contracting unbundles hardware from maintenance and telematics services, creating hybrid pricing structures where capital purchase models compete with operating expense conversions. Price differentiation hinges on EPA Tier 4 Final compliance certification and grapple reach specification tiers. Pricing pressure stems from after-treatment cost inflation on diesel powertrains, squeezing margins on straight-boom commodity configurations. Municipal contractors in German emission zones show lowest price sensitivity due to regulatory compliance mandates, while emerging market buyers of hydraulic loaders exhibit highest sensitivity to first cost.
Supply Chain Analysis
Dual-sourcing requirements from major OEMs now mandate qualified secondary suppliers for boom cylinders and grapple actuators, reducing single-source dependency but extending qualification timelines. Steel and hydraulic component supply chains draw from Germany, Japan, and South Korea for precision-manufactured subassemblies. Raw material dependencies include high-strength steel plate, hydraulic valve blocks, and lithium-ion battery packs for electric architectures. Tariff exposure on steel imports creates margin volatility for fabricators. Distribution runs through authorized dealer networks and direct rental fleet contracts, with aftermarket parts flowing through regional service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Scandinavian mechanized harvesting mandates and EU Green Deal timber certification pull demand toward premium knuckleboom grapple systems with extended reach capabilities.
For Market Incumbents: Deepen powertrain integration expertise to defend high-cycle steep terrain applications against emerging electric-hybrid specialists. Invest in EPA Tier 4 Final and EU Stage V after-treatment service capabilities to capture maintenance revenue from compliance-burdened diesel fleets. Compress parts inventory costs through standardized fleet programs with timber merchant accounts. For New Entrants and Emerging Players: Launch via equipment-as-a-service partnerships with Swedish and Finnish contractor cooperatives seeking flexible capacity arrangements over asset ownership. Target municipal urban forestry departments in German emission zones where electric unit specifications create white-space demand. Penetrate through telematics-ERP integration services that incumbent OEMs underinvest in. For Investors and Strategic Acquirers: Rental fleet operators are the most active acquirer in this space, consolidating fragmented contractor demand into multi-unit procurement volumes. Long-term viability centers on predictive maintenance service platforms and battery energy density trajectories that enable electric deployment in remote basins. Monitor charging infrastructure buildout in Canadian and Russian timber regions as inflection indicator for diesel displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Platform Development | Battery-electric architectures enable German municipal contractors to comply with EU Stage V emission zones. |
| Telematics-ERP Integration | Loader operating data convergence with contractor enterprise systems unlocks predictive maintenance revenue streams. |
| Aftermarket Service Expansion | EPA Tier 4 Final after-treatment expertise addresses certified technician scarcity extending downtime intervals. |
| Equipment-as-a-Service Contracting | Flexible capacity arrangements displace capital purchases among Swedish and Finnish seasonal operators. |
| Semi-Autonomous Grapple Control | METI-supported R&D programs advance precision load handling for Japanese hillside harvesting applications. |
Methodological Framework
Multiple input streams — OEM product planning directors, forestry contractor equipment managers, rental fleet procurement heads, and hydraulic component suppliers — were reconciled against trade association production data, customs import records, and EPA certification filings. Secondary validation drew from machinery registration databases, timber harvest volume statistics, and EU ETS compliance disclosures. Bottom-up unit demand estimates and top-down market value reconstructions were triangulated to anchor forecast boundaries.
Data-stream reconciliation across product type, application, technology, and end-user segmentation dimensions informed the analytical framework throughout the projection horizon. CAGRs were derived from fitted growth curves calibrated to mechanized harvesting mandate implementation timelines and battery energy density improvement trajectories. Forecast inputs incorporated Scandinavian regulatory compliance deadlines and charging infrastructure deployment schedules in key timber basins.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity steel price volatility and lithium-ion supply disruption scenarios. Projections reflect assumptions regarding EPA and EU Stage V enforcement continuity and electric grid extension rates in remote harvesting regions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Steel Coil Handling Equipment Market
Material Handling Equipment
Froth Flotation Equipment Market
Material Handling Equipment
Low-Level Order Picker Pallet Truck Market
Material Handling Equipment
Dust Extractors Market
Material Handling Equipment
Europe Automated Material Handling (AMH) Market
Material Handling Equipment
Roller Crusher Market
Material Handling Equipment
Heavy Duty Ramp Market
Material Handling Equipment
Middle East and Africa Automated Material Handling Market
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Pedestal Boom System Market
Material Handling Equipment
Motorized Decoiler Machine Market
Material Handling Equipment
High-Density Racks Market
Material Handling Equipment
Crushing Screening Equipment Market
Material Handling Equipment
Australia Forklift Market
Material Handling Equipment
Vibrating Screen Market