
 Global Loaders Market | 2026-2036
Global Loaders Market Size, Share, and Industry Trends Forecast 2026-2036
Global Loaders Market Foresight
A widening capability gap in powertrain electrification is bifurcating the competitive landscape. Caterpillar Inc. leverages its integrated dealer network and captive battery development to anchor North American mining contracts. Komatsu Ltd. sustains leadership in autonomous haulage integration, while Xuzhou Construction Machinery Group Co. Ltd. dominates domestic procurement through cost-optimized hydraulic architectures and state-backed financing channels.
Loaders are self-propelled earthmoving machines equipped with front-mounted buckets ranging from 0.5 to over 30 cubic meters, designed to scoop, lift, and transport loose materials across construction sites, mineral extraction zones, and agricultural operations. Wheel loaders command the largest installed base due to their mobility and payload versatility across surface applications. Electric technology is gaining fastest in urban construction zones where municipal noise ordinances and zero-emission worksite mandates restrict diesel operation. Diesel configurations retain margin concentration in remote mining deployments where charging infrastructure remains absent.
EPA Tier 4 Final and EU Stage V regulations are tightening particulate and NOx limits, forcing redesigns of engine after-treatment systems and accelerating hybrid development timelines. China's MIIT enforces national GB standards for non-road mobile machinery emissions, creating a fragmented compliance landscape for exporters. Stakeholders must monitor how rapidly battery energy density improvements and charging standard harmonization reshape total cost of ownership calculations against legacy diesel platforms.
Market Dynamics
Powertrain electrification is decomposing the traditional diesel-centric loader value chain, forcing manufacturers to rebuild engineering competencies around battery thermal management and electric drivetrain integration while mining customers in Australia and Chile delay fleet decisions pending charging infrastructure clarity.
Growth Catalysts
- EPA Tier 4 Final and EU Stage V compliance deadlines:Regulatory pressure on NOx and particulate emissions is accelerating replacement cycles in North American and European construction fleets. Equipment owners face retrofit costs that favor new machine acquisition.
- Autonomous haulage integration:Mining operators in Australia's Pilbara region are specifying loader-to-truck coordination protocols that require OEMs to embed machine-to-machine communication hardware. This capability specification is concentrating procurement among suppliers with proven autonomous system architectures.
- State-funded infrastructure corridors:China's western provinces are executing railway and highway projects that demand sustained earthmoving capacity. Provincial procurement authorities are bundling loader acquisitions into multi-year equipment service agreements.
Market Restraints
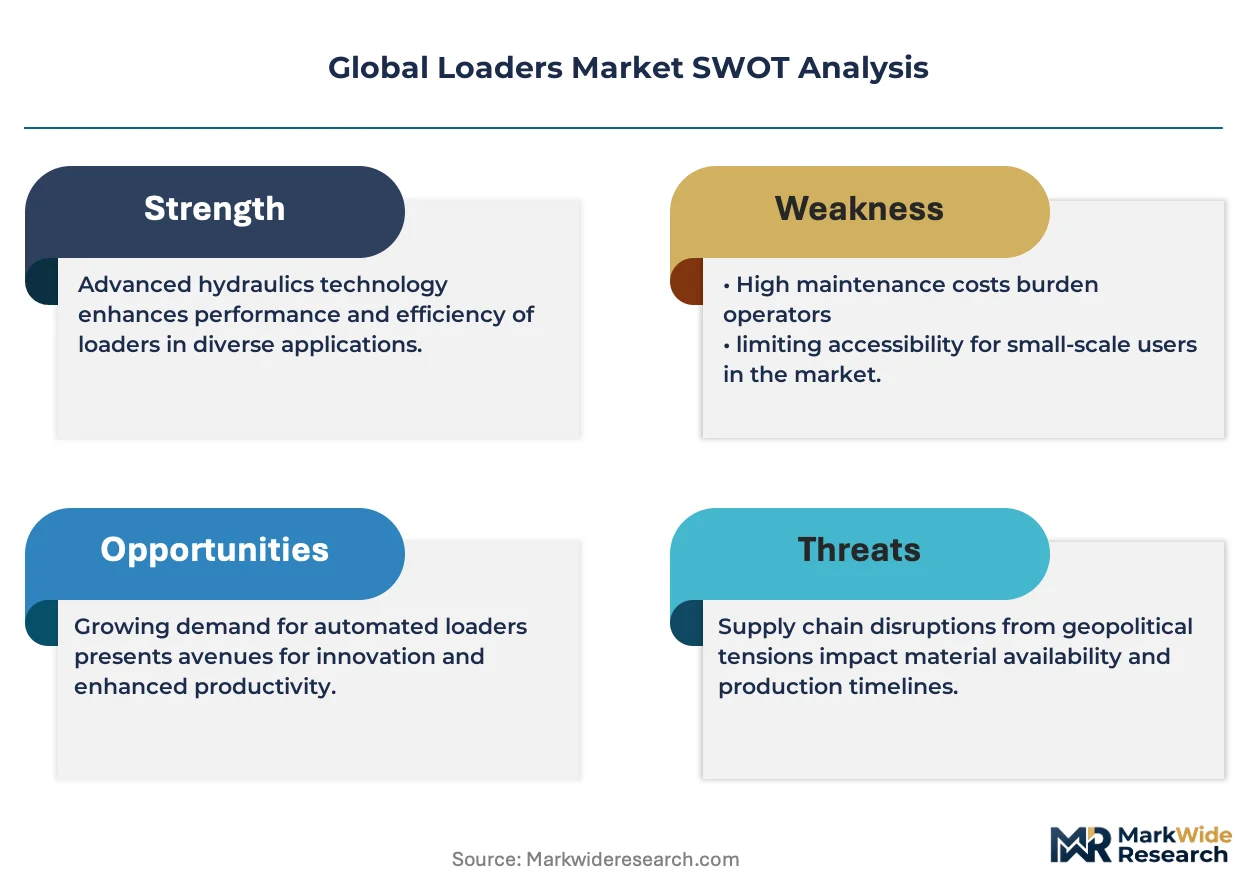
- Lithium-ion cell supply concentration:Battery pack production for electric loaders depends on cathode material processing concentrated in China and Indonesia. OEMs face input cost volatility and geopolitical exposure in their electrification roadmaps.
- Charging infrastructure absence:Remote mining sites in Chile's Atacama Desert and Australia's Northern Territory lack grid connectivity sufficient for electric fleet operation. Diesel-hybrid configurations remain the only viable compliance pathway in these geographies.
- Skilled technician scarcity:Electric powertrain diagnostics require competencies in high-voltage systems and battery management software that legacy diesel mechanic workforces lack. Training program development lags equipment introduction timelines.
Strategic Opportunities
- Urban zero-emission worksite mandates:Municipal ordinances in California and New York City are prohibiting diesel equipment from city-center construction zones. Electric wheel loaders with sub-75 dB noise profiles qualify for these restricted contracts.
- Battery swapping standardization:Convergence of modular battery pack architectures and automated swap stations is enabling continuous operation models for quarry applications previously reserved for diesel refueling cycles.
- Rental fleet electrification:Equipment rental channels in Germany and the Netherlands are adding electric loaders to meet corporate customer ESG procurement criteria. Rental penetration creates trial pathways for hesitant owner-operators.
Industry Challenges
- Certification timeline compression:GB standard updates from China's MIIT and evolving EU Stage V test cycles are forcing simultaneous compliance engineering across multiple regulatory frameworks. Validation resources are stretched across overlapping certification deadlines.
- Legacy fleet integration complexity:Mixed diesel-electric worksites require unified telematics platforms that can aggregate machine health data across incompatible OEM protocols. Fleet management software standardization remains unresolved.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Loaders Market |
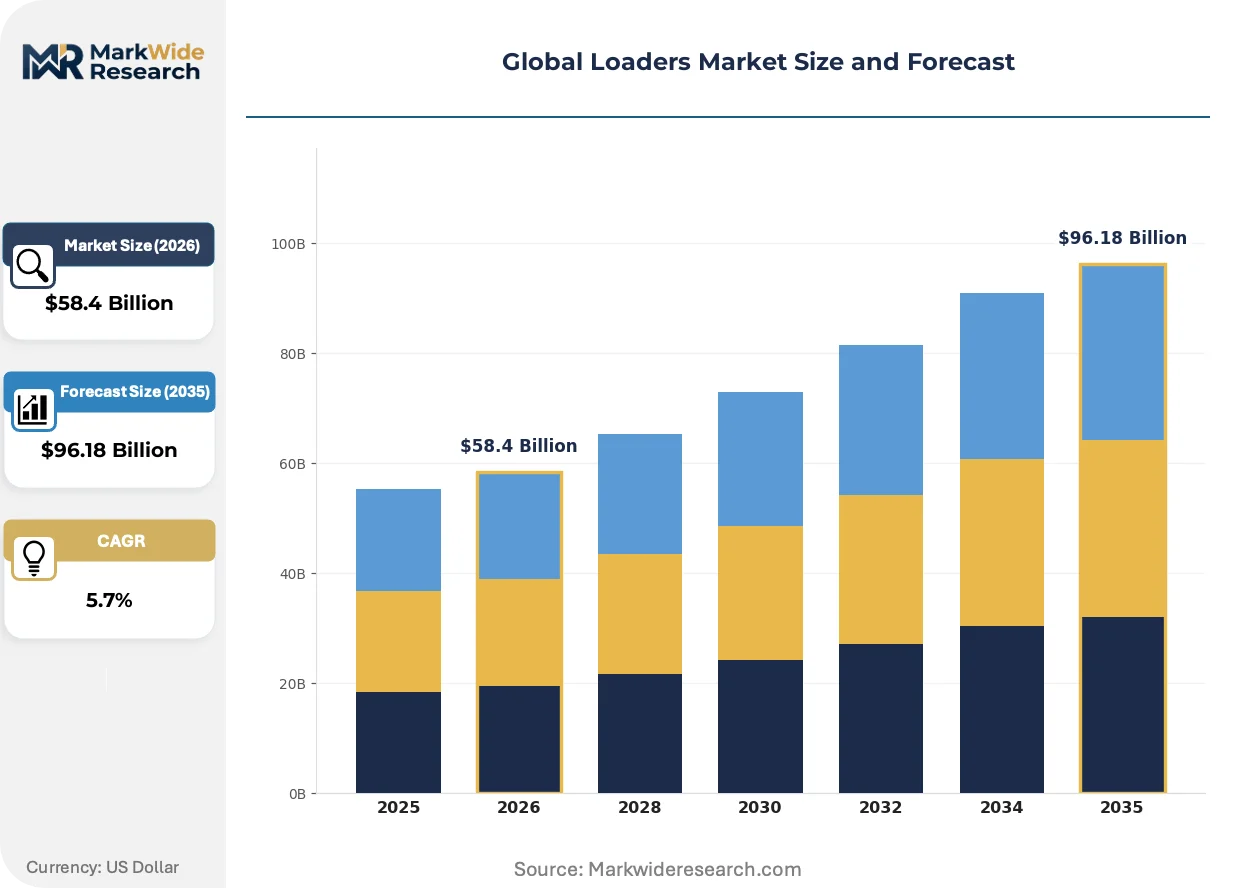
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $96.18 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Wheel Loader, Skid-Steer Loader, Backhoe Loader, Track Loader, Compact Loader Technology: Electric, Diesel, Hybrid, Hydraulic, Pneumatic Application: Construction, Mining, Agriculture, Waste Management, Forestry End User: Contractors, Quarry Operators, Farmers, Municipal Services, Logging Companies |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Volvo Construction Equipment, Liebherr Group, Hitachi Construction Machinery Co. Ltd., J.C. Bamford Excavators Limited, CNH Industrial N.V., Doosan Infracore Co. Ltd., Xuzhou Construction Machinery Group Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Loaders Market Shifts & Advancements
Electrification architecture choices are fragmenting competitive positioning, with manufacturers diverging between integrated battery development strategies and modular supplier partnerships while regulatory timelines compress decision windows.
Solid-state battery prototyping is decomposing the energy density limitations that have constrained electric loader duty cycles. Mining fleet operators in Chile are piloting prototype machines with silicon-anode cells that promise 40% range extension over conventional lithium-ion packs. The technology is decomposing the historical diesel advantage in remote-site autonomy, enabling electric machine specification for pit-to-crusher haul routes previously reserved for diesel powertrains.
EU Stage V and China's GB 20891-2014 Phase IV standards are tightening real-driving emission testing protocols for non-road mobile machinery. Engine after-treatment system complexity has increased manufacturing cost structures by requiring selective catalytic reduction and diesel particulate filter integration. European construction equipment distributors are responding by accelerating electric loader inventory commitments to reduce warranty exposure from emission system failures.
Equipment-as-a-service contracting is displacing traditional capital purchase models in municipal and utility sectors. German waste management operators are procuring loader capacity through hourly-rate agreements that bundle maintenance, energy, and telematics analytics. The shift is most visible in Scandinavia, where municipal procurement regulations favor operational expenditure treatment over balance-sheet asset ownership.
Global Loaders Market Segmentation
Loader procurement patterns diverge sharply across powertrain technologies and operator scale. Mining conglomerates in Chile and Australia specify autonomous-capable machines, while municipal fleets in California and Germany prioritize zero-emission configurations for urban worksite compliance.
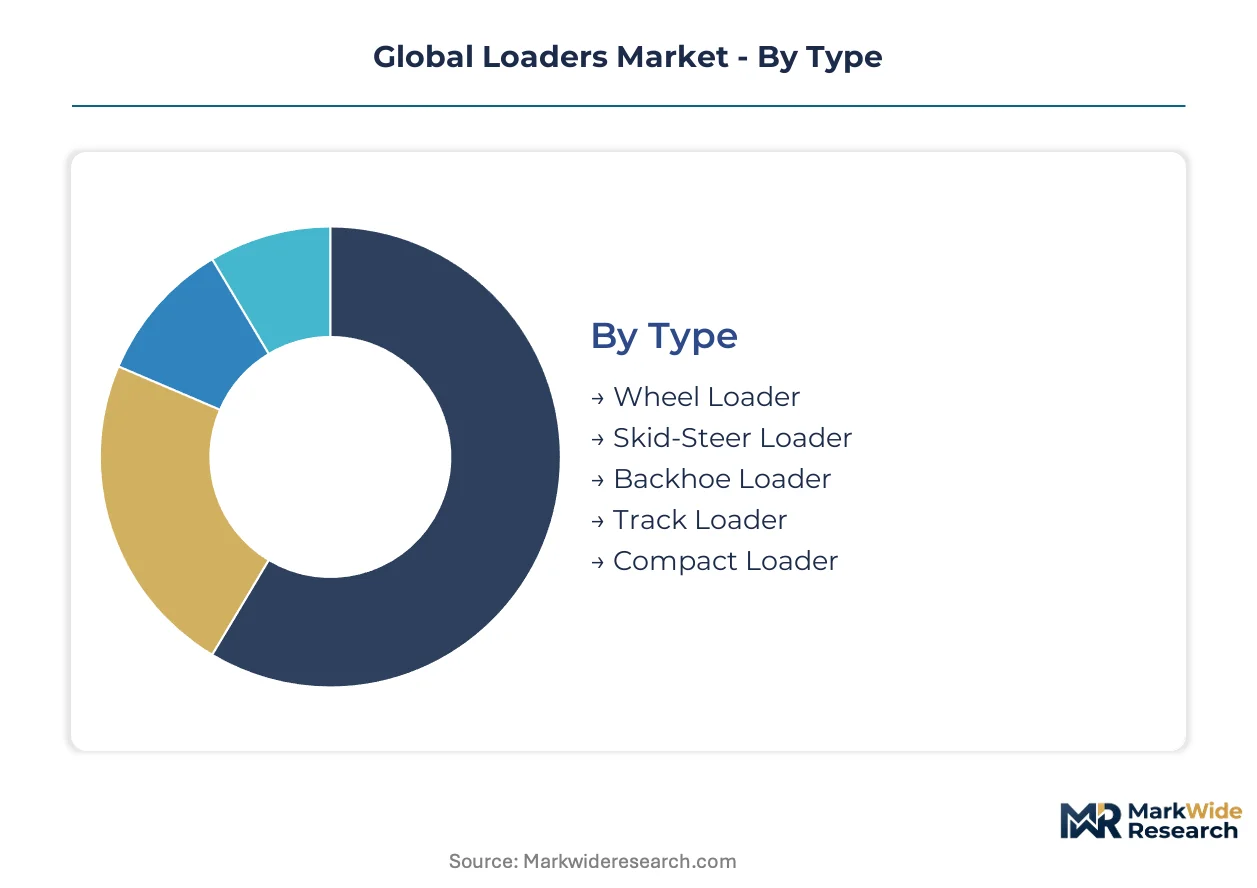
Type:
Domestic Chinese demand concentrates on cost-optimized wheel and compact variants, whereas export markets in Australia and Germany absorb premium-specification track and skid-steer configurations with advanced telematics integration.
- Wheel Loader:Front-mounted bucket designs from 0.5 to 30 cubic meters dominate surface earthmoving operations. Demand concentrates in China's western provinces where state-funded railway projects require sustained loading capacity for ballast and aggregate handling.
- Skid-Steer Loader:Compact zero-radius turning machines excel in confined construction zones. Municipal contractors in New York City and Los Angeles specify electric skid-steer units to meet zero-emission worksite mandates in dense urban cores.
- Backhoe Loader:Dual-function excavator-loader hybrids serve small-scale contractors with limited fleet diversity. Farmers in India's Punjab region utilize these machines for irrigation canal maintenance and field preparation.
- Track Loader:Continuous-track undercarriages distribute ground pressure for soft-terrain applications. Forestry operators in Canada's British Columbia deploy track loaders for log sorting on unstable slope conditions.
- Compact Loader:Sub-50-horsepower units target owner-operators and rental fleets. German equipment rental channels are expanding compact electric inventory to satisfy corporate ESG procurement criteria.
Wheel loaders hold the largest share; momentum sits with compact electric variants.
Technology:
Cost tier stratification separates premium electric platforms from standard diesel architectures, with hybrid configurations occupying an intermediate price-performance band for transitional mining applications.
- Electric:Battery-electric drivetrains with lithium-ion packs and thermal management systems enable zero-emission operation. Urban construction zones in California and New York City prohibit diesel equipment, mandating electric specification for city-center contracts.
- Diesel:Compression-ignition engines with after-treatment systems remain standard for remote mining deployments. Chile's Atacama Desert operations lack grid connectivity sufficient for electric fleet conversion.
- Hybrid:Diesel-electric series configurations optimize fuel consumption in variable-load quarry cycles. Australian Pilbara mining operators pilot hybrid loaders for pit-to-crusher haul routes pending charging infrastructure development.
- Hydraulic:Fluid-power actuation systems dominate legacy machine architectures. Xuzhou Construction Machinery Group leverages cost-optimized hydraulic designs to anchor domestic Chinese procurement.
- Pneumatic:Compressed-air powertrains serve specialized underground mining applications with explosion-risk constraints. Limited deployment concentrates in South African platinum extraction zones.
Diesel retains volume leadership; electric configurations are climbing the fastest as battery energy density improves.
Application:
Volume concentration varies by customer capital intensity, with mining and construction absorbing heavy-duty units while agriculture and waste management favor mid-size versatility.
- Construction:General earthmoving, material handling, and site preparation across commercial and residential projects. Chinese provincial authorities bundle loader acquisitions into multi-year infrastructure service agreements for western province highway development.
- Mining:Mineral extraction, overburden removal, and stockpile management in surface and underground operations. Autonomous haulage integration requirements in Australia's Pilbara region concentrate procurement among OEMs with proven machine-to-machine communication architectures.
- Agriculture:Feed handling, manure management, and field preparation across grain and livestock operations. Brazilian soybean producers utilize wheel loaders for grain elevator loading during harvest compression windows.
- Waste Management:Municipal solid waste transfer, recycling facility sorting, and landfill compaction. German waste operators are adopting equipment-as-a-service contracting with hourly-rate structures bundling maintenance and energy costs.
- Forestry:Log sorting, deck management, and biomass handling in timber harvesting operations. Swedish forestry cooperatives specify electric loaders for sensitive riparian buffer zones with noise restrictions.
Construction commands the largest application share; waste management is gaining share fastest through service-model innovation.
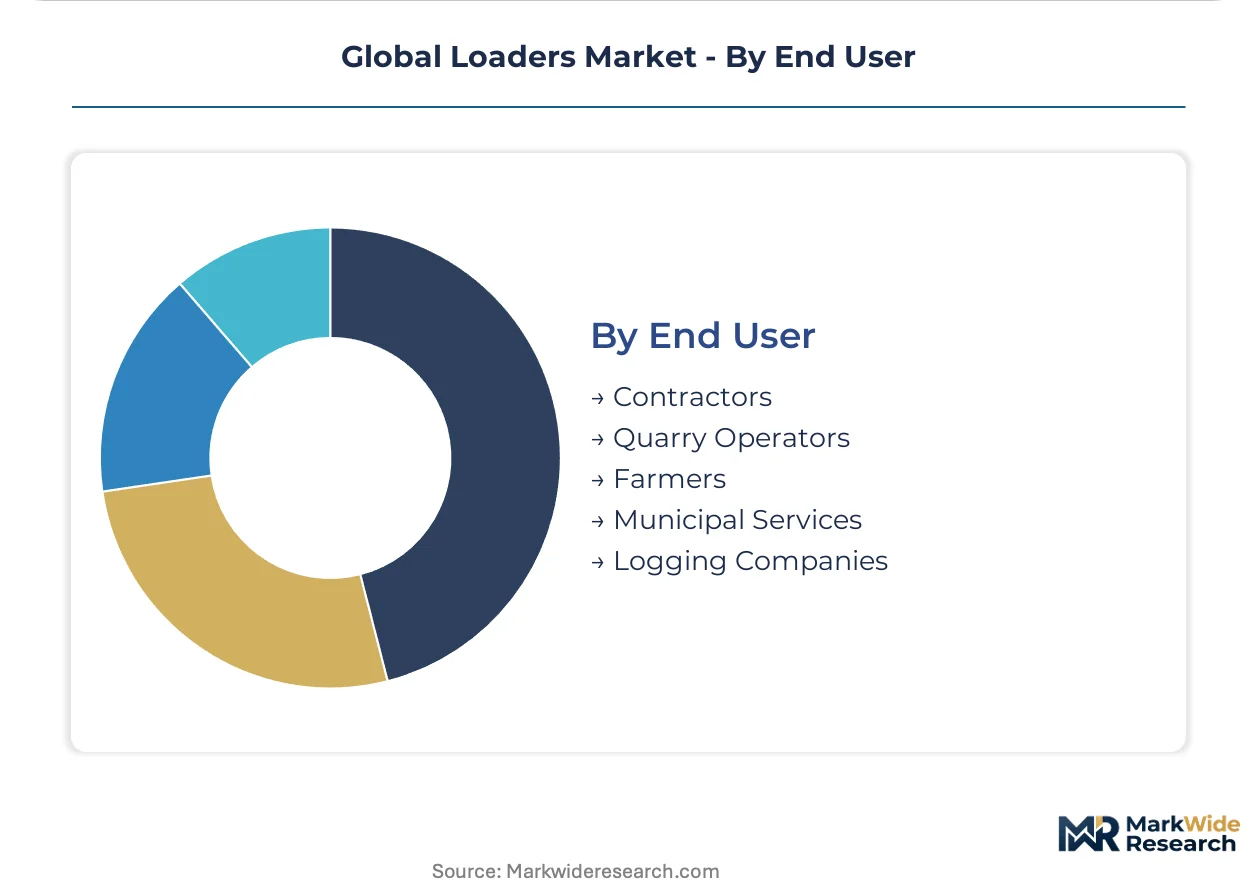
End User:
Customer type determines procurement channel preference, with large quarry operators favoring direct OEM relationships and smaller farmers relying on dealer financing programs.
- Contractors:General construction firms executing commercial, residential, and civil engineering projects. California contractors face EPA Tier 4 Final compliance deadlines accelerating fleet replacement cycles.
- Quarry Operators:Aggregate extraction and processing companies with continuous production requirements. Battery swapping standardization trials in German quarries enable continuous operation models matching diesel refueling cycles.
- Farmers:Owner-operators and agricultural cooperatives with seasonal equipment utilization patterns. Indian farmers access state-backed financing channels for domestic hydraulic loader procurement.
- Municipal Services:Government agencies responsible for public works, road maintenance, and waste collection. Scandinavian municipal procurement regulations favor operational expenditure treatment over balance-sheet asset ownership.
- Logging Companies:Timber harvesting enterprises with terrain-specific equipment requirements. British Columbia logging contractors specify track loaders for steep-slope extraction permits.
Contractors represent the largest end-user segment; municipal services are expanding most quickly through procurement regulation shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Chinese buyers prioritize acquisition cost and state-backed financing terms, while Australian and Chilean mining operators emphasize total cost of ownership and autonomous integration capabilities over upfront expenditure.
United States
Construction contractors in California and Texas face EPA Tier 4 Final compliance deadlines accelerating fleet replacement cycles. Municipal zero-emission mandates in New York City and Los Angeles prohibit diesel equipment from urban worksites, forcing electric loader specification for city-center contracts. Equipment rental channels in the Midwest are expanding electric inventory to meet corporate ESG procurement criteria.
China
State-funded infrastructure corridors in western provinces require sustained earthmoving capacity for railway and highway development. MIIT enforces GB 20891-2014 Phase IV emissions standards, creating compliance complexity for domestic manufacturers and exporters alike. Xuzhou anchors domestic procurement through cost-optimized hydraulic architectures and provincial equipment service agreements.
Australia
Mining operators in the Pilbara region specify loader-to-truck coordination protocols requiring embedded machine-to-machine communication hardware. Autonomous haulage integration capabilities concentrate procurement among OEMs with proven system architectures. Remote site locations lack grid connectivity sufficient for full electric fleet conversion, sustaining diesel-hybrid demand.
Germany
Waste management operators adopt equipment-as-a-service contracting with hourly-rate structures bundling maintenance and energy costs. EU Stage V regulations tighten real-driving emission testing protocols, accelerating electric loader inventory commitments among distributors. Quarries in Bavaria pilot battery swapping standardization enabling continuous operation models.
Chile
Copper extraction operations in the Atacama Desert delay electric fleet decisions pending charging infrastructure clarity. Diesel configurations retain dominance in remote deployments where grid connectivity remains absent. Mining conglomerates pilot silicon-anode solid-state battery prototypes promising extended range for pit-to-crusher haul routes.
Global Loaders Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the loaders market. The upper tier commands premium positioning through captive battery development and autonomous system integration, while mid-scale fabricators compete on cost-optimized hydraulic architectures and regional financing channels. Strategic archetypes include integrated powertrain developers, autonomous technology specialists, and state-backed domestic champions. Competitive moves concentrate on electrification roadmap acceleration and multi-year equipment service agreement bundling.
Among North American integrated manufacturers, Caterpillar Inc. exemplifies the captive battery development archetype with established mining sector relationships. Komatsu Ltd. occupies a position within the autonomous technology specialist tier, while Xuzhou Construction Machinery Group Co. Ltd. anchors the state-backed domestic champion category through cost-optimized positioning in Chinese provincial procurement.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Volvo Construction Equipment |
| Liebherr Group |
| Hitachi Construction Machinery Co. Ltd. |
| J.C. Bamford Excavators Limited |
| CNH Industrial N.V. |
| Doosan Infracore Co. Ltd. |
| Xuzhou Construction Machinery Group Co. Ltd. |
| Others |
Supply & Pricing Matrix
Scale economies in battery cell manufacturing concentrate pricing power among cathode material processors in China and Indonesia, compressing margins for OEMs while elevating price floors for electric loader variants above legacy diesel platforms. Mining procurement teams in Australia and Chile negotiate multi-year service agreements that bundle energy costs and maintenance into hourly-rate structures, shifting price discovery from unit transactions to operational expenditure models.
Pricing Analysis
After-sales revenue from parts, service contracts, and telematics subscriptions drives lifetime value capture across the loader installed base. Three-tier pricing structure across premium autonomous-capable, standard diesel-compliant, and economy hydraulic tiers separates OEMs with integrated battery development from cost-optimized fabricators. Cost compression in electric powertrain tiers is intensifying because lithium-ion cell supply volatility feeds through to pack pricing. Municipal contractors in Germany and California exhibit lowest price sensitivity due to zero-emission mandate compliance requirements, while Indian agricultural cooperatives anchor the economy tier through state-backed financing channels.
Supply Chain Analysis
Strait of Malacca transit underwrites cathode precursor chemical flows from Indonesian nickel processing plants to Chinese cell assembly facilities. Battery pack production draws from lithium carbonate extraction in Chile's Atacama, nickel laterite processing in Indonesia, and separator membrane manufacturing in South Korea. Single-source vulnerability concentrates in Chinese cathode material refining capacity. Distribution runs through captive dealer networks for mining sector direct sales and equipment rental channels for municipal trial adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Loader procurement is shifting toward platform-economics logic as autonomous haulage integration and battery swapping standardization create interoperability requirements that favor ecosystem orchestrators over component suppliers.
For Market Incumbents: Fortify autonomous system architectures through deeper machine-to-machine protocol development to defend against emerging electric-only entrants lacking mining sector relationships. Prioritize backward integration into battery thermal management competencies to reduce exposure to cathode material price volatility.
For New Entrants and Emerging Players: Anchor in municipal zero-emission worksite mandates across California and New York City where incumbent diesel service infrastructure creates transition friction. Target compact electric skid-steer configurations for rental fleet channels seeking ESG-compliant inventory.
For Investors and Strategic Acquirers: Autonomous software specialists with proven pit-to-crusher coordination protocols represent the most defensible acquisition profile as mining operators consolidate procurement around integrated system providers. Monitor charging infrastructure deployment timelines in Chile's Atacama and Australia's Pilbara as inflection indicators for electric fleet conversion velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swapping Standardization | Enables continuous quarry operations matching diesel refueling cycles in German Bavaria trials. |
| Autonomous Haulage Integration | Concentrates Pilbara procurement among OEMs with proven loader-to-truck coordination protocols. |
| Equipment-as-a-Service Contracting | Shifts German waste operators from capital expenditure to operational expenditure treatment. |
| Solid-State Battery Prototyping | Silicon-anode cells extend electric loader range for Chilean pit-to-crusher routes. |
| Captive Battery Development | Caterpillar's integrated cell engineering anchors North American mining contract retention. |
Research Methodology
Desk research of customs trade records, OEM technical filings, and mining fleet procurement databases preceded structured interviews with maintenance directors at Australian Pilbara operations, aftermarket service heads at European construction equipment distributors, and procurement teams at Chilean copper extraction conglomerates. Primary fieldwork with plant engineers and OEM technical sales specialists was validated against secondary sources including EPA certification filings, EU Stage V test cycle documentation, and MIIT GB standard updates. Bottom-up unit shipment estimates were triangulated against top-down value projections derived from equipment-as-a-service contract disclosures.
Variance decomposition across powertrain technology, application intensity, and regional regulatory clusters shaped the analytical framework throughout the projection horizon. Modeled segmentation spanned wheel, skid-steer, backhoe, track, and compact loader types; electric, diesel, hybrid, hydraulic, and pneumatic technologies; and construction, mining, agriculture, waste management, and forestry applications. CAGRs were derived from regression analysis of replacement cycle timing against compliance deadline schedules. Key forecast inputs included battery energy density improvement trajectories and charging infrastructure deployment pipelines.
Decision-makers should treat outputs as directional under assumptions of steady regulatory enforcement and lithium-ion supply expansion; material deviation in cathode material geopolitics or autonomous system certification timelines would warrant model refresh. Practitioners should keep alternative scenarios live as EU Stage V real-driving test protocols and China's GB standard updates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Spring Shackles Market
Material Handling Equipment
Shiplifts & Transfer Systems Market
Material Handling Equipment
Pharmaceutical Material Handling Equipment Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Asia Pacific Mobile Crane Market
Material Handling Equipment
Fluid Conveyance Systems Market
Material Handling Equipment
Vertical Lift Module (VLM) Market
Material Handling Equipment
Container Handling Equipment Market
Material Handling Equipment
Global Mechanical Seals Market
Material Handling Equipment
North America Industrial Duct for Dust Collection Market
Material Handling Equipment
Log Loaders Market
Material Handling Equipment
Modular Conveyor System Market
Material Handling Equipment
Reach Trucks Market
Material Handling Equipment
Vertical Platform Lift Market
Material Handling Equipment
Precision Ballscrews Market
Material Handling Equipment
Hydraulic Seals Market