
 Stair Lifts and Climbing Devices Market | 2026-2036
Stair Lifts and Climbing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Stair Lifts and Climbing Devices Market Intelligence
Buyer fragmentation across home healthcare agencies and independent living facilities is repositioning procurement patterns toward bundled service contracts. Bruno Independent Living Aids leverages its direct-to-dealer network to sustain installation capacity across North American markets. Handicare Group AB anchors its position through vertical integration into rail manufacturing, reducing lead times for custom curved configurations. Stannah Stairlifts differentiates through heritage brand strength and extended warranty programs that lock in long-term service revenue.
Stair lifts and climbing devices comprise motorized rail-mounted seating systems and platform-based vertical transport equipment engineered to navigate staircases with load capacities typically ranging from 250 to 400 pounds and travel speeds of 15 to 25 feet per minute. These systems serve the primary commercial purpose of enabling mobility-impaired individuals to traverse multi-level structures without structural elevator installation. Straight stair lifts occupy the largest installed base due to standardized rail geometries and rapid deployment timelines, while curved stair lifts command premium margin pools owing to custom rail fabrication requirements. DC motor technology is displacing AC alternatives in residential segments because battery backup functionality eliminates stranding risks during power outages.
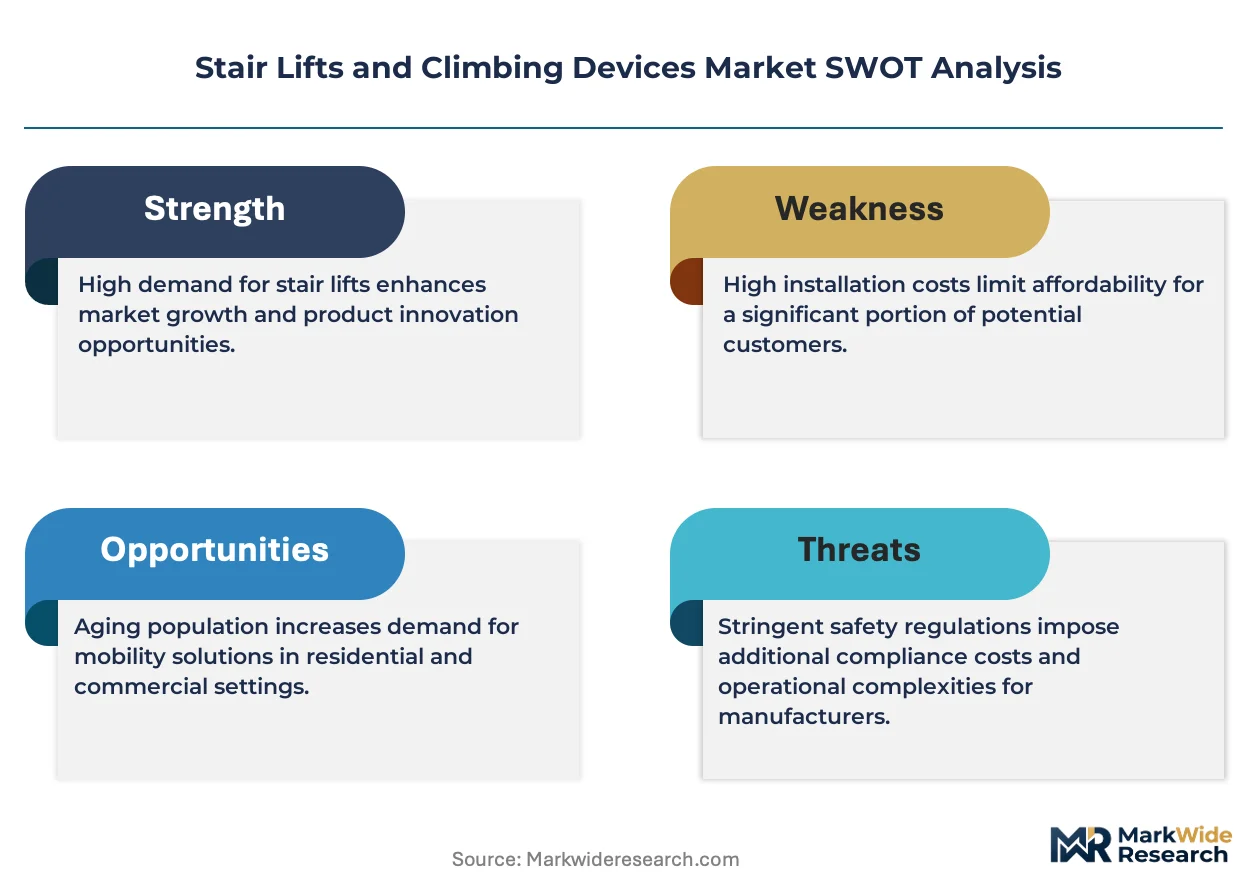
The FDA classifies powered stair lifts as Class II medical devices requiring 510(k) premarket notification, while the EU Medical Device Regulation mandates notified body oversight for active implantable mobility aids sold in member states. The Americans with Disabilities Act and EN 81-40 standards collectively shape product safety specifications and installation compliance obligations across transatlantic markets. Stakeholders must monitor evolving reimbursement codes from Medicare and national health services, as coverage determinations directly influence consumer out-of-pocket exposure and replacement cycle timing.
Market Dynamics
DC motor technology is overtaking AC alternatives in residential stair lift installations, eliminating stranding risks through battery backup functionality while compressing installation timelines and maintenance intervals across North American and European retrofit markets.
Growth Catalysts
- EU Medical Device Regulation (MDR):Tightened conformity requirements for powered mobility aids are accelerating replacement cycles among institutional buyers seeking certified equipment ahead of enforcement deadlines.
- Japan's aging demographic concentration:Residential retrofit installations in urban prefectures are expanding procurement volumes for curved rail configurations in multi-generational housing stock.
- Lithium-ion battery chemistry:Improved energy density and cycle life are enabling slimmer rail profiles and extended runtime between charging cycles in DC-powered residential units.
Market Restraints
- Custom rail fabrication costs:Curved stair lift configurations require site-specific rail manufacturing, concentrating margin pressure on installers serving non-standard staircase geometries.
- Copper and rare earth supply concentration:DC motor production depends on magnet materials sourced through concentrated Asian supply chains, exposing manufacturers to input cost volatility.
- Structural elevator substitution:Platform lifts and residential elevators are capturing new-build residential projects with sufficient footprint and vertical travel requirements.
Strategic Opportunities
- German home healthcare agency consolidation:Bundled service contracts covering installation, maintenance, and decommissioning are opening recurring revenue streams for equipment providers.
- Remote diagnostic integration:IoT-enabled condition monitoring is converging with predictive maintenance platforms to reduce emergency call-out frequency and extend service intervals.
- United Kingdom disability facility grants:Local authority funding mechanisms for accessibility adaptations are creating procurement windows for straight rail installations in social housing stock.
Industry Challenges
- Installation technician certification:Qualified rail fitters with electrical competency credentials are scarce across metropolitan markets, constraining deployment capacity during demand surges.
- Legacy staircase assessment complexity:Pre-installation surveys for curved configurations require specialized measurement protocols, extending sales-to-installation timelines and elevating cancellation risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stair Lifts and Climbing Devices Market |
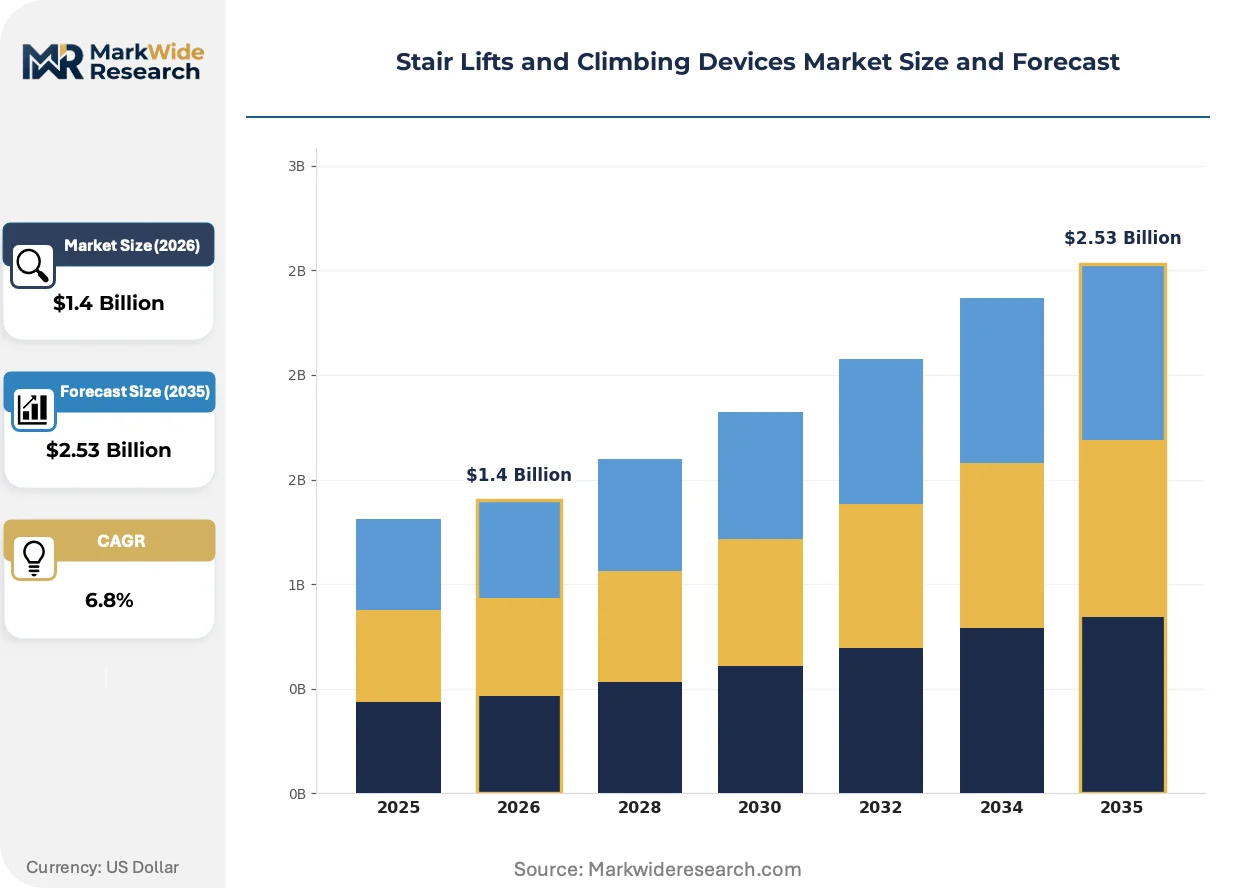
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Curved Stair Lifts, Straight Stair Lifts, Platform Lifts, Vertical Lifts Technology: AC Motor, DC Motor, Battery-Operated, Hydraulic End User: Residential, Commercial, Healthcare Facilities, Public Buildings Installation Type: Indoor, Outdoor, Modular, Custom |
| Companies Covered | Bruno Independent Living Aids, Stannah Stairlifts, Acorn Stairlifts Inc., Handicare Group AB, Savaria Corporation, Platinum Stairlifts, Sunrise Medical LLC, Garaventa Lift, Harmar Mobility LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stair Lifts and Climbing Devices Market Strategic Shifts & Innovations
Active load-sensing control systems and modular rail architectures are compressing product development cycles while elevating safety performance expectations among institutional specifiers and residential end-users alike.
Brushless DC motor drives with integrated battery management systems are overtaking brushed motor alternatives in premium residential segments. Home healthcare agencies specify these units for their reduced acoustic signature and elimination of brush replacement intervals. The technology is compressing total cost of ownership calculations and shifting specification criteria toward lifecycle value metrics.
EU MDR notified body oversight requirements for active implantable mobility aids are extending certification timelines for powered stair lift manufacturers seeking CE marking. Industrial consequence includes documentation burden elevation and quality management system audits. German and UK notified bodies are experiencing application backlogs, forcing manufacturers to front-load regulatory submissions ahead of product launch windows.
Service contract unbundling is fragmenting traditional dealer-installer relationships across North American markets. Independent living facilities are separating equipment procurement from maintenance agreements, creating direct manufacturer-to-institutional sales channels. This pattern is most visible in Medicare Advantage plan networks where capitated reimbursement structures favor predictable operational expenditure models over capital equipment purchases.
Stair Lifts and Climbing Devices Market Segmentation
Stair lift and climbing device procurement patterns diverge sharply across application contexts, with residential retrofit demand favoring standardized configurations while institutional buyers prioritize custom engineering for compliance and durability.
Product Type:
Straight rail configurations dominate unit volumes through rapid deployment timelines, while curved systems capture premium margin pools through site-specific fabrication requirements.
- Straight Stair Lifts:Standardized rail geometries enable same-day installation in residential retrofit markets across Germany and the United Kingdom. Demand concentrates in social housing stock where local authority grants fund accessibility adaptations.
- Curved Stair Lifts:Custom rail manufacturing accommodates spiral, fanned, and multi-flight staircase geometries with load capacities up to 350 pounds. Procurement volumes are climbing fastest in Japan's urban prefectures where multi-generational housing stock requires non-standard configurations.
- Platform Lifts:Wheelchair-compatible vertical transport systems serve commercial and public building applications with ADA and EN 81-40 compliance mandates.
- Vertical Lifts:Enclosed cab systems bridge larger vertical travel distances in healthcare facilities where elevator installation is structurally impractical.
Mature deployment sits with Straight Stair Lifts. Newer deployment is concentrated in Curved Stair Lifts.
Technology:
Power source selection directly determines installation feasibility, maintenance burden, and regulatory compliance pathways across residential and institutional segments.
- DC Motor:Brushless drives with integrated battery management eliminate stranding risks during outages while reducing acoustic signatures below 50 decibels. Home healthcare agencies in North America specify these units for lifecycle cost advantages.
- AC Motor:Mains-powered alternatives persist in commercial installations with dedicated electrical infrastructure and continuous duty cycles.
- Battery-Operated:Lithium-ion chemistry enables slimmer rail profiles and extended runtime between charging cycles in retrofit residential applications.
- Hydraulic:Fluid power systems serve heavy-duty platform and vertical lift configurations with load capacities exceeding 500 pounds.
Technology migration favors DC Motor systems for residential retrofit, while Battery-Operated variants are gaining share fastest in outdoor and off-grid installations.
End User:
Buyer type dictates specification criteria, procurement channel, and service contract structure across the value chain.
- Residential:Individual homeowners and family caregivers drive demand for compact, aesthetically integrated systems with financing options. Aging-in-place trends in Japan and Germany are expanding retrofit volumes.
- Healthcare Facilities:Hospitals and long-term care institutions require infection-control surfaces, bariatric capacity, and predictive maintenance integration under bundled service agreements.
- Commercial:Office buildings and retail environments prioritize rapid deployment and minimal aesthetic disruption during tenant improvements.
- Public Buildings:Government and educational institutions mandate ADA, EN 81-40, and EU MDR compliance with extended warranty terms and decommissioning obligations.
Residential segment holds the deepest installed base. Healthcare Facilities represent the steepest expansion trajectory through agency consolidation and capitated reimbursement structures.
Installation Type:
Environmental exposure and structural adaptability requirements segment deployment approaches across climate zones and building vintages.
- Indoor:Climate-controlled environments enable polymer and painted steel finishes with standard IP ratings for residential and commercial applications.
- Outdoor:Weather-sealed rail systems with marine-grade coatings serve exterior staircase access in coastal United Kingdom and Nordic markets where salt exposure accelerates corrosion.
- Modular:Pre-engineered component systems compress lead times for straight rail configurations in high-volume social housing programs.
- Custom:Site-specific engineering addresses heritage building constraints, structural load limitations, and aesthetic integration requirements in premium residential and institutional markets.
Indoor installation maintains volume leadership. Outdoor configurations are expanding most quickly as municipal accessibility mandates extend to public exterior staircases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential retrofit demand concentrates in Germany, Japan, and the United Kingdom where aging demographics and local authority funding mechanisms drive procurement volumes for accessibility equipment.
Germany
Home healthcare agency consolidation and multi-generational housing trends are expanding curved stair lift installations. The EU Medical Device Regulation mandates notified body oversight for powered mobility aids, accelerating certified equipment replacement cycles. Industrial concentration sits with Baden-Württemberg and North Rhine-Westphalia where rail fabricators serve institutional buyers.
Japan
Urban prefecture aging demographics and compact residential footprints are driving demand for custom curved configurations. METI guidelines on barrier-free housing standards shape product specifications for residential retrofits. Manufacturing and distribution clusters concentrate in Kanto and Kansai regions serving Tokyo and Osaka metropolitan markets.
United Kingdom
Local authority disability facility grants and social housing adaptation programs fund straight rail installations. EN 81-40 standards and Building Regulations compliance requirements govern public building accessibility mandates. Installation capacity concentrates in the Midlands and Southeast England serving municipal procurement windows.
United States
Medicare Advantage capitated reimbursement structures and aging-in-place trends are shifting procurement toward bundled service contracts. FDA Class II medical device classification requires 510(k) premarket notification for powered stair lifts. Dealer-installer networks concentrate in Florida, California, and Texas retirement corridors.
Canada
Provincial healthcare funding variations and residential accessibility tax credits are expanding retrofit volumes. Health Canada medical device regulations align with FDA pathways for cross-border equipment certification. Distribution clusters concentrate in Ontario and British Columbia serving urban elderly populations in Toronto and Vancouver.
Stair Lifts and Climbing Devices Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue adjacent mobility aid categories through technology licensing and geographic expansion. The vendor base segments into heritage manufacturers with captive installation networks, rail fabrication specialists with backward integration into custom metalwork, and diversified medical equipment conglomerates with institutional sales channels. Strategic archetypes include direct-to-dealer distributors, vertically integrated fabricators, and service-contract aggregators. Competitive moves concentrate on dealer network expansion and predictive maintenance platform development.
Within the heritage manufacturer tier, Bruno Independent Living Aids and Stannah Stairlifts exemplify established positioning through brand recognition and installation network scale. Handicare Group AB represents the fabrication-integrated archetype with in-house rail production capabilities. Among North American diversified players, Savaria Corporation occupies a position spanning residential and institutional segments.
| Leading Market Players |
|---|
| Bruno Independent Living Aids |
| Stannah Stairlifts |
| Acorn Stairlifts Inc. |
| Handicare Group AB |
| Savaria Corporation |
| Platinum Stairlifts |
| Sunrise Medical LLC |
| Garaventa Lift |
| Harmar Mobility LLC |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap fabricators in Baden-Württemberg and North Rhine-Westphalia anchor German rail production, compressing procurement costs for curved configurations while limiting pricing discipline among captive installation networks across European markets.
Pricing Analysis
Straight stair lifts move at volume-driven price points with thin margins, while curved systems capture premium pools through custom engineering. Three-tier pricing structure across premium brushless DC units, standard AC alternatives, and economy refurbished lines separates specification criteria. Cost compression in entry-level segments is intensifying because lithium-ion battery chemistry is commoditizing. Social housing procurement committees exhibit acute price sensitivity; private residential buyers prioritize lifecycle value over upfront expenditure.
Supply Chain Analysis
Domestic-content mandates in EU MDR enforcement are reshaping sourcing patterns for notified body-certified components. Magnet materials concentrate in Chinese rare earth processing, with South Korean and Japanese suppliers controlling refined neodymium output. Copper winding stock, aluminum rail extrusions, and lithium-ion cell packs constitute critical input dependencies. Single-source vulnerability runs through concentrated Asian magnet supply chains. Distribution runs through direct-to-dealer networks in North America and bundled service aggregators in German home healthcare markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR certification timelines and installation technician scarcity are forcing marginal fabricators toward exit, consolidating procurement power among heritage manufacturers with captive regulatory expertise.
For Market Incumbents: Lock in rail fabrication capacity through backward integration into custom metalwork, eliminating lead-time vulnerability for curved configurations. Capture predictive maintenance platform development to convert one-time equipment sales into recurring service revenue streams. Platform lift substitution from residential elevator entrants threatens premium residential positioning; defend through extended warranty bundling that elevates switching costs.
For New Entrants and Emerging Players: IoT-enabled remote diagnostic modules offer a technology-first wedge into fragmented aftermarket service contracts. Target outdoor weather-sealed configurations in Nordic and coastal United Kingdom municipalities where heritage manufacturers lack dedicated product lines. Pursue direct institutional sales to Medicare Advantage networks separating equipment procurement from maintenance agreements.
For Investors and Strategic Acquirers: Distressed-cycle entries favor fabrication-integrated specialists in German industrial clusters facing working capital pressure from MDR compliance investments. Five-to-ten-year viability hinges on recurring revenue share exceeding equipment sales. Monitor notified body application backlogs as inflection signal—clearing queues will release pent-up replacement demand and compress margins for unprepared inventory positions.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | IoT sensor integration with Medicare Advantage capitated structures converts capital sales to recurring operational expenditure models. |
| CE Marking Pathway Acceleration | Front-loaded regulatory submissions to German and UK notified bodies preempt MDR enforcement deadline bottlenecks. |
| Curved Rail Fabrication Capacity Expansion | In-house metalwork control compresses lead times for Japan's multi-generational housing retrofit specifications. |
| Hospital System Partnership | Bundled service agreements with long-term care institutions lock in infection-control surface specifications and bariatric capacity requirements. |
| Reimbursement Strategy Alignment | CMS coding advocacy and local authority grant navigation reduce consumer out-of-pocket exposure in UK social housing programs. |
Research Approach
Independent corroboration across installation technician interviews, home healthcare procurement manager surveys, and regulatory affairs director consultations underwrites the qualitative findings. Primary fieldwork captured perspectives from biomedical engineers specifying infection-control surfaces, GPO contracts managers negotiating bundled service terms, and aftermarket service heads managing predictive maintenance rollouts. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified body certification registries, CMS Medicare coverage determination filings, and hospital procurement database extracts. Bottom-up unit economics triangulated against top-down demographic demand projections.
Rate-of-change decomposition across product type, motor technology, end-user segment, and installation environment dimensions shaped the analytical framework. CAGRs were derived from fitted trend extrapolation moderated by regulatory inflection points and reimbursement policy shifts. Modeled inputs incorporated aging-in-place demographic trajectories in Japan and Germany, lithium-ion battery cost curves, and copper price volatility indices.
Several conditions sit outside the modeled scope, including macroeconomic recession impacts on discretionary retrofit spending and unanticipated platform lift technology breakthroughs. Forecasts reflect documented assumptions regarding MDR enforcement consistency and Medicare Advantage plan expansion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Industrial Hoists Market
Material Handling Equipment
Compactor Market
Material Handling Equipment
Crushing Screening Equipment Market
Material Handling Equipment
Global Bucket Loader Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Heavy Duty Ramp Market
Material Handling Equipment
Cherry Picker Crane Market
Material Handling Equipment
Selective Pallet Racking System Market
Material Handling Equipment
Slag Handling Machine Market
Material Handling Equipment
Warehouse Freight Elevators Market
Material Handling Equipment
Global Telescopic Boom Forklift Truck Market
Material Handling Equipment
Pipe Belt Conveyor Market
Material Handling Equipment
Roller Crusher Market
Material Handling Equipment
Scissor Lift Market
Material Handling Equipment
Roll Handling Machine Market