
 Freight Elevators Market | 2026-2036
Freight Elevators Market Size, Share, and Industry Trends Forecast 2026-2036
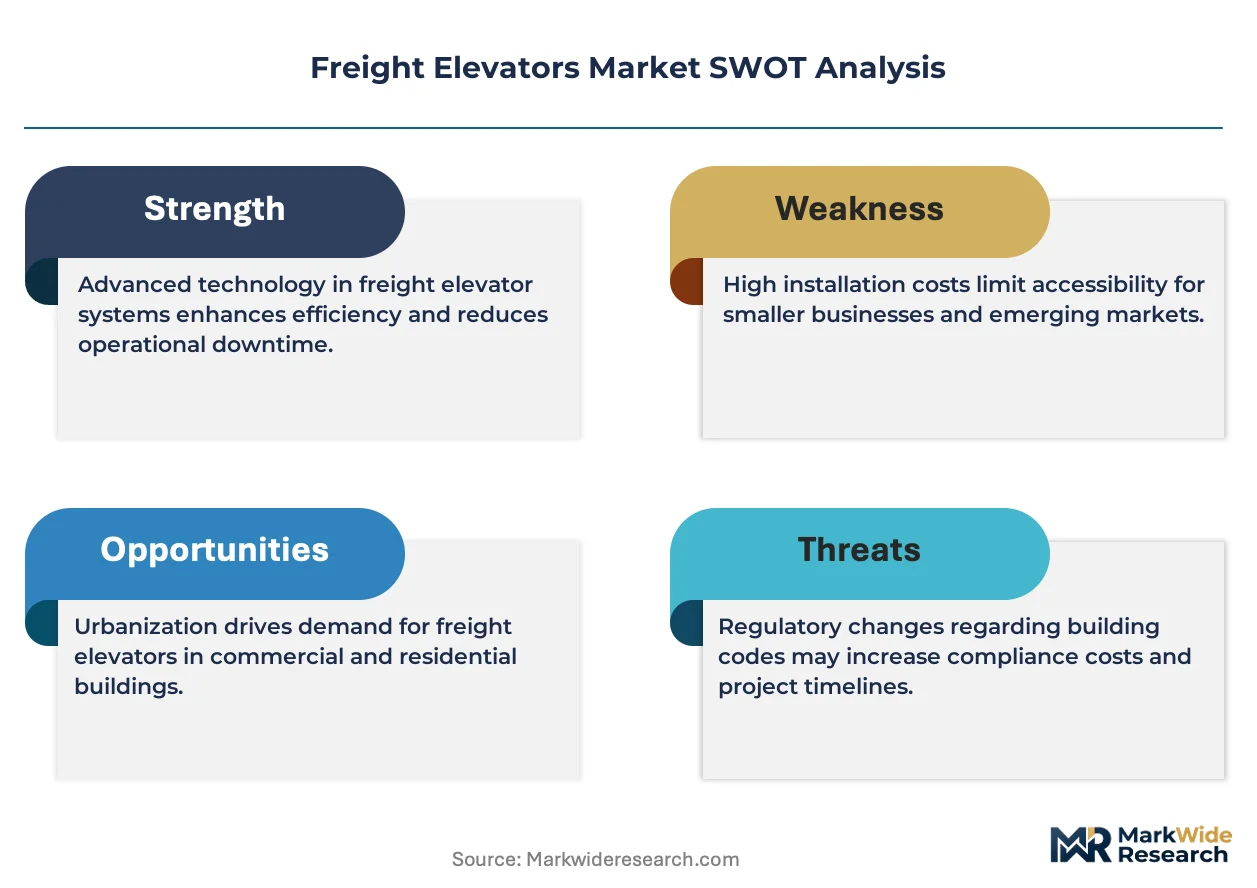
Freight Elevators Market Analysis
E-commerce fulfillment is rebalancing the end-use vertical mix toward warehousing and logistics facilities. TK Elevator leverages its European manufacturing base to serve automated distribution centers. Otis Elevator Company anchors its position through extensive service networks across North American industrial corridors. Schindler Group competes on modular traction systems designed for retrofit-heavy urban logistics buildings.
Freight elevators are vertical transportation systems engineered to move goods, materials, and equipment between building floors, typically rated for loads exceeding 2,300 kilograms with reinforced car platforms and heavy-duty door operators. Traction elevators dominate new installation demand in mid-rise and high-rise logistics facilities where energy efficiency and speed requirements exceed hydraulic system capabilities. Hydraulic elevators retain structural importance in low-rise warehousing and manufacturing plants where pit depth constraints and moderate travel heights limit traction adoption. Machine room less configurations are gaining share in modernization projects where existing building envelopes restrict mechanical penthouse expansion.
ASME A17.1 safety standards in the United States, the EU Machinery Directive with CE marking requirements in Europe, and China's GB 7588 national standard collectively govern freight elevator design certification, installation inspection protocols, and periodic maintenance mandates. These frameworks directly shape procurement timelines, compliance costs, and vendor qualification criteria for facility operators. Stakeholders must monitor evolving energy efficiency benchmarks and predictive maintenance mandates as regulatory bodies integrate decarbonization targets into vertical transport equipment standards.
Market Dynamics
Warehouse automation adoption is compressing freight elevator specification cycles as distribution centers demand higher throughput capacity and predictive maintenance integration from vertical transport systems.
Growth Catalysts
- ASME A17.1 modernization mandates:Stricter inspection protocols in the United States are forcing facility operators to replace aging hydraulic systems with traction alternatives.
- Last-mile logistics densification:Urban fulfillment centers in India and China are installing high-capacity units to support multi-level automated storage and retrieval systems.
- Machine room less traction technology:This configuration eliminates penthouse requirements, unlocking retrofit opportunities in legacy industrial buildings with constrained headroom.
Market Restraints
- Steel and copper input volatility:Car platform fabrication and motor winding costs fluctuate with commodity markets, squeezing OEM margins on fixed-price contracts.
- Pit depth constraints in legacy structures:Hydraulic systems retain structural lock-in where foundation excavation is economically or physically prohibitive.
- Certified installation labor scarcity:Journeyman elevator mechanic pipelines in Germany and Japan lag replacement demand, extending project timelines.
Strategic Opportunities
- Cold chain vertical expansion:Temperature-controlled logistics facilities in Brazil require specialized corrosion-resistant door operators and insulated car enclosures.
- EU Green Deal alignment:Regenerative drive systems qualify for accelerated depreciation incentives under national energy efficiency frameworks.
- Predictive maintenance convergence:Vibration sensor integration with building management systems creates recurring revenue streams for service providers.
Industry Challenges
- Legacy controller integration:Proprietary communication protocols from 1990s installations obstruct seamless IoT retrofit without complete control system replacement.
- CE marking timeline compression:EU Machinery Directive conformity assessment delays for custom high-capacity units extend delivery schedules by eight to fourteen weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freight Elevators Market |
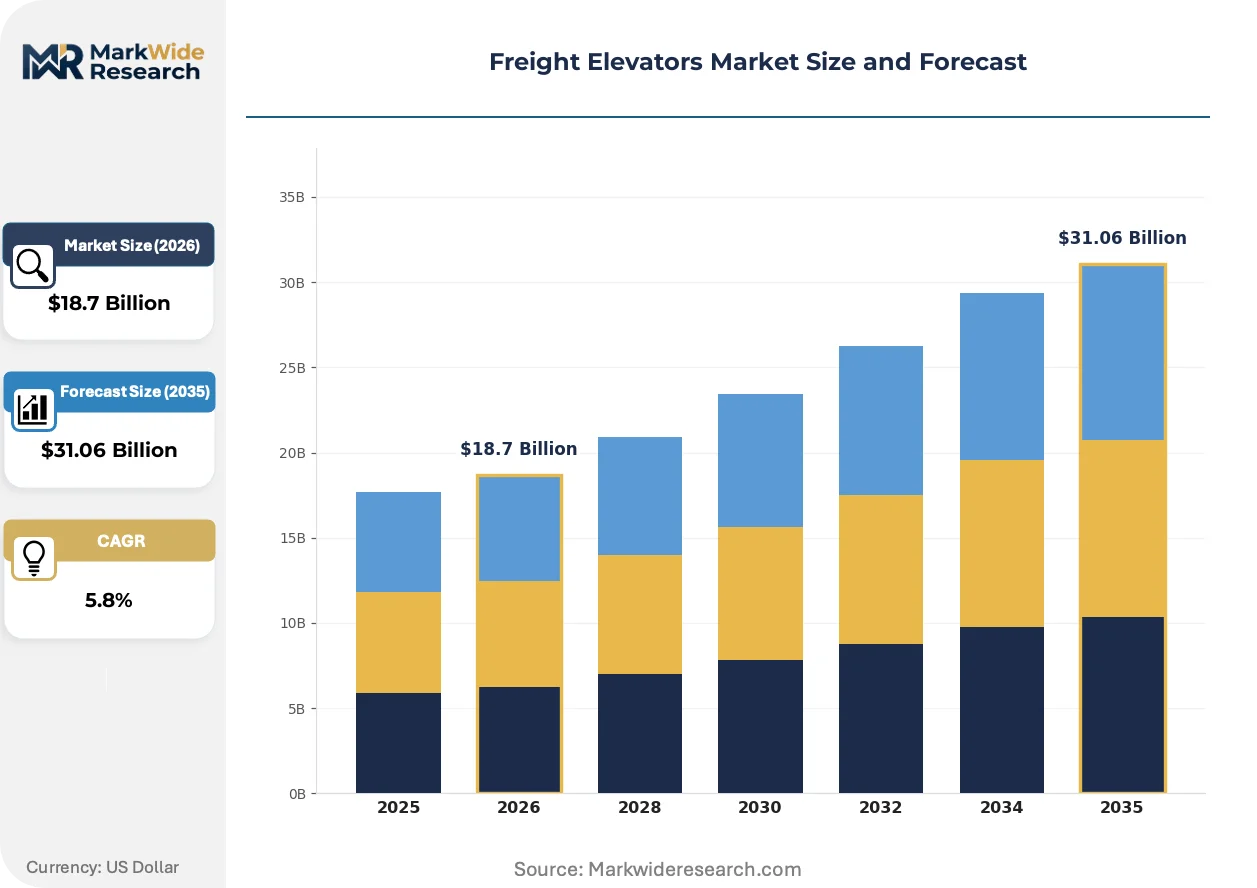
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Elevators, Traction Elevators, Machine Room Less, Vacuum Elevators End User: Logistics, Warehousing, Manufacturing, Retail Installation Type: New Installation, Modernization, Repair, Maintenance Service Type: Planned Maintenance, Emergency Repair, Replacement, Consulting |
| Companies Covered | Hitachi, Ltd., TK Elevator, Otis Elevator Company, Hyundai Elevator Co., Ltd., Fujitec Co., Ltd., KONE Corporation, Mitsubishi Electric Corporation, General Elevator Co., Ltd., Schindler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freight Elevators Market Emerging Trajectories
Digitalization of vertical transport is absorbing capital allocation as facility operators prioritize uptime guarantees over equipment ownership. Three developments are restructuring competitive positioning.
Regenerative drive technology is absorbing kinetic energy during descent and returning it to building electrical grids. Automated distribution centers in the Netherlands and South Korea are specifying this capability as standard. OEMs without regenerative portfolios are absorbing margin pressure from energy performance contracting requirements.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in machine room climate control, indirectly elevating demand for machine room less configurations. Manufacturers serving the European market are redesigning thermal management around ambient-cooled permanent magnet motors. This regulatory compression is absorbing engineering resources from traction system development teams.
Performance-based service agreements are replacing traditional time-and-material maintenance contracts. Third-party logistics operators in the United States are unbundling elevator service from general facility management, selecting specialized vertical transport contractors with guaranteed uptime clauses. This procurement evolution is absorbing risk onto service providers while compressing contract renewal cycles.
Freight Elevators Market Segmentation
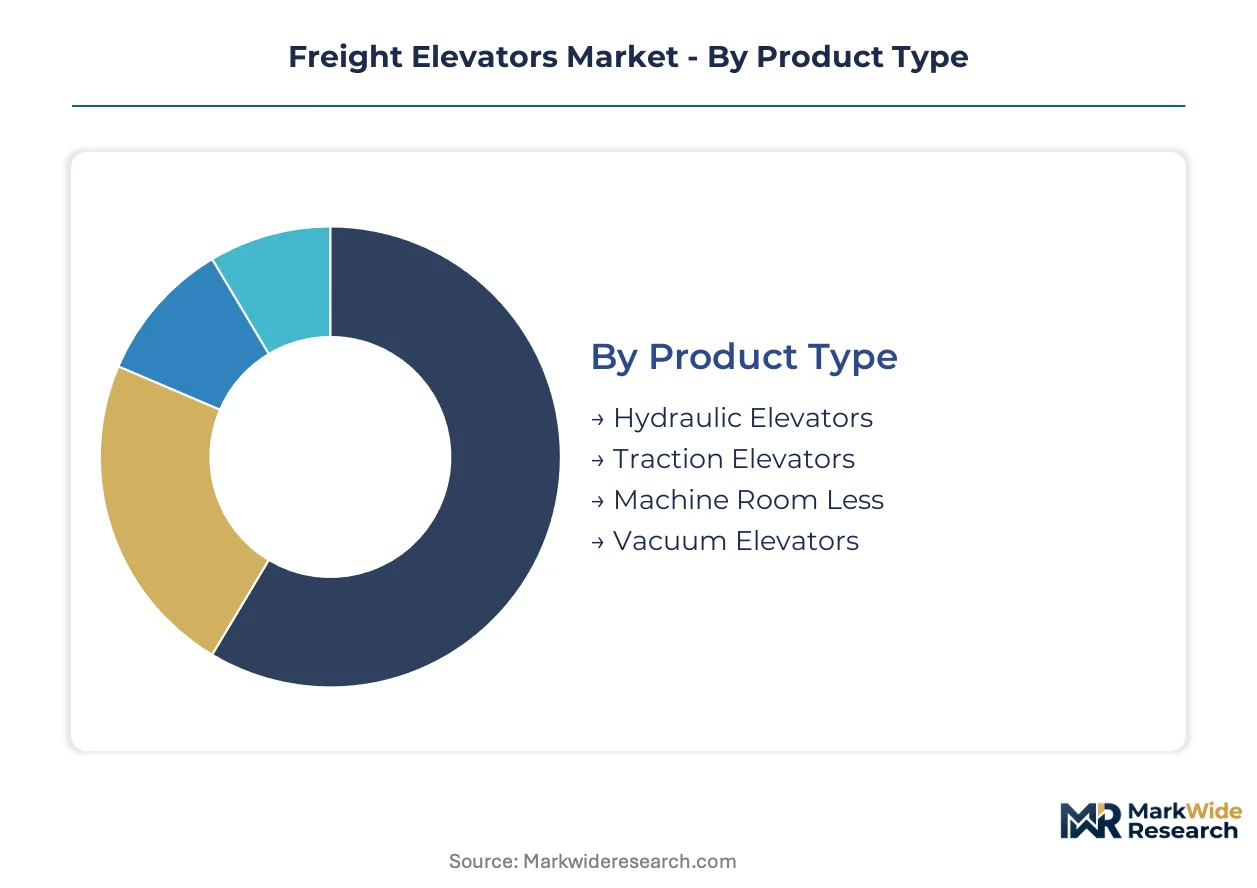
Freight elevator procurement patterns diverge sharply across product architectures and facility types. Segment-level specification requirements determine vendor qualification, installation complexity, and long-term service revenue potential for equipment suppliers.
Product Type:
Supply concentration in traction motor manufacturing favors established OEMs with in-house permanent magnet production capabilities.
- Traction Elevators:Geared and gearless systems utilizing steel ropes or belts over a drive sheave, rated for speeds exceeding 150 feet per minute in mid-rise logistics facilities. Demand concentrates in automated distribution centers across Germany, South Korea, and the United States where energy efficiency mandates from regulators like the EU Green Deal and EPA accelerate regenerative drive adoption.
- Hydraulic Elevators:Piston-driven systems lifting the car from below, structurally limited to six-floor travel heights but requiring no overhead machinery space. Warehousing operators in legacy industrial zones of India and Brazil retain this technology where pit excavation costs prohibit traction conversion.
- Machine Room Less:Compact traction systems with machinery integrated into the hoistway, eliminating penthouse requirements for retrofit projects.
- Vacuum Elevators:Pneumatic tube systems using air pressure differentials, restricted to light-load applications in boutique retail and small-scale manufacturing.
Today's leader: Traction Elevators. Tomorrow's challenger: Machine Room Less.
End User:
Cost tier differentiation separates specification requirements between capital-intensive automation projects and maintenance-budget-constrained facilities.
- Logistics:Third-party fulfillment operators demand predictive maintenance integration and guaranteed uptime clauses in procurement contracts. Cold chain facilities in Brazil and Saudi Arabia require corrosion-resistant door operators and insulated car enclosures for temperature-controlled vertical transport.
- Warehousing:Multi-level automated storage and retrieval systems drive demand for high-capacity units with reinforced platforms exceeding 4,500 kilograms.
- Manufacturing:Heavy industrial plants specify explosion-proof controllers and NEMA-rated enclosures for hazardous material handling.
- Retail:Big-box stores and shopping centers prioritize aesthetic integration and moderate load ratings for stock replenishment operations.
Volume concentrates in Logistics. Margin expansion sits with Warehousing.
Installation Type:
Application urgency shapes project timelines, with modernization cycles compressing as ASME A17.1 inspection protocols tighten across multiple jurisdictions.
- New Installation:Greenfield distribution centers in China and India specify integrated vertical transport during structural design, enabling machine room less configurations and optimized hoistway dimensions.
- Modernization:Controller replacement, door operator upgrades, and drive system retrofits dominate mature markets where legacy infrastructure lock-in prevents full replacement.
- Repair:Reactive service calls for component failures, typically under emergency response contracts with penalty clauses for downtime exceeding four hours.
- Maintenance:Periodic inspection and preventive servicing mandated by national safety regulators including OSHA in the United States and GB standards enforcement in China.
Revenue stability flows from Maintenance. Growth velocity belongs to Modernization.
Service Type:
Customer type stratification separates enterprise fleet operators seeking outcome-based contracts from single-facility owners prioritizing cost minimization.
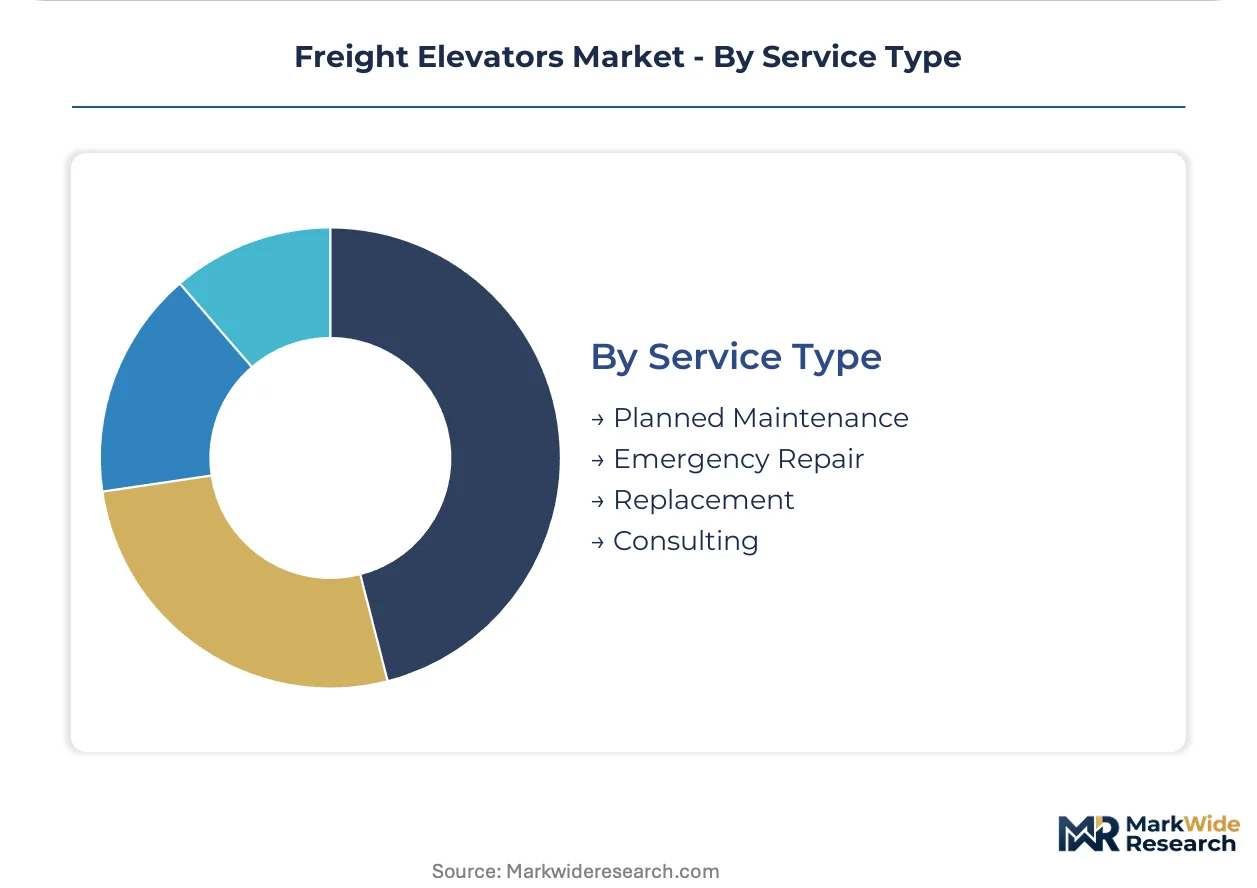
- Planned Maintenance:Scheduled inspection protocols covering lubrication, adjustment, and component replacement per manufacturer specifications and regulatory mandates.
- Emergency Repair:Unscheduled response to entrapments, controller failures, and safety circuit malfunctions, with premium pricing for after-hours dispatch.
- Replacement:Component-level procurement of controllers, motors, and door operators, increasingly bundled with extended warranty coverage.
- Consulting:Traffic analysis, energy audit, and modernization feasibility studies for facility operators evaluating capital allocation decisions.
Contract penetration peaks with Planned Maintenance. Value migration heads toward Consulting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as OEMs relocate production to jurisdictions with streamlined certification pathways. Cost-of-compliance gaps between mature and emerging markets are accelerating facility investment in Southeast Asia and Eastern Europe.
United States
Third-party logistics operators are modernizing aging hydraulic fleets to meet ASME A17.1 inspection mandates. The EPA's energy efficiency benchmarks are accelerating regenerative drive adoption in automated distribution centers. Industrial corridors across Ohio, Pennsylvania, and Illinois concentrate retrofit demand from legacy manufacturing plants.
Germany
Machine room less configurations are capturing share in brownfield logistics facilities across the Rhine-Ruhr industrial belt. The EU F-Gas Regulation is phasing out hydrofluorocarbon-dependent climate control systems, elevating demand for ambient-cooled permanent magnet motors. Bavaria's automotive supplier networks are specifying explosion-proof controllers for hazardous material handling.
China
GB 7588 national standard enforcement is compressing delivery timelines for domestic OEMs serving e-commerce fulfillment networks. Dual carbon goals from MEE are integrating energy efficiency benchmarks into vertical transport procurement specifications. Yangtze River Delta logistics clusters in Shanghai and Jiangsu province are installing high-capacity units for multi-level automated storage systems.
India
Warehousing operators in legacy industrial zones retain hydraulic systems where foundation excavation costs prohibit traction conversion. BIS certification requirements are extending project timelines for imported equipment. Gujarat and Maharashtra logistics corridors are densifying last-mile fulfillment infrastructure with vertical transport rated for loads exceeding 4,500 kilograms.
Brazil
Cold chain vertical expansion is driving demand for corrosion-resistant door operators and insulated car enclosures. ANVISA sanitary regulations for temperature-controlled pharmaceutical logistics are elevating specification requirements. São Paulo state distribution centers are integrating predictive maintenance systems to guarantee uptime in high-throughput operations.
Freight Elevators Market Vendor Landscape
Strategic partnerships dominate the current landscape as OEMs align with automation integrators to bundle vertical transport with warehouse management systems. The vendor base concentrates around full-service elevator manufacturers with captive traction motor production and specialized retrofit contractors serving legacy infrastructure. Three archetypes define competitive positioning: European engineering-led OEMs with regenerative drive portfolios, Asian scale manufacturers with cost-optimized hydraulic offerings, and regional service specialists with predictive maintenance platforms. Technology licensing agreements and geographic expansion through distributor networks represent the dominant competitive vectors.
Among Japanese industrial conglomerates with elevator divisions, Hitachi, Ltd., Mitsubishi Electric Corporation, and Fujitec Co., Ltd. occupy positions emphasizing permanent magnet motor development and building management system integration. These Tokyo-headquartered manufacturers exemplify the engineering-led archetype, leveraging domestic precision manufacturing capabilities to serve automated distribution centers across East Asian logistics corridors. Their market presence anchors the premium-tier specification segment where energy efficiency mandates from regulators like METI and the EU Green Deal drive procurement decisions.
| Leading Market Players |
|---|
| Hitachi, Ltd. |
| TK Elevator |
| Otis Elevator Company |
| Hyundai Elevator Co., Ltd. |
| Fujitec Co., Ltd. |
| KONE Corporation |
| Mitsubishi Electric Corporation |
| General Elevator Co., Ltd. |
| Schindler Group |
| Others |
Supply Flow & Price Mechanics
Steel futures volatility on the Shanghai Futures Exchange cascades through freight elevator manufacturing, compressing margins on fixed-price installation contracts while forcing tiered pricing stratification across premium regenerative systems, standard traction configurations, and economy hydraulic units.
Pricing Analysis
Distributor markup layers separate OEM factory pricing from end-user procurement, with authorized service networks capturing 15-25 point spreads on aftermarket components. Pricing stratifies across premium, standard, and economy tiers based on load capacity ratings and CE/UL certification levels. Cost compression in the hydraulic segment is intensifying because Brazilian and Indian warehousing operators prioritize first-cost minimization over lifecycle efficiency. Third-party logistics operators in automated distribution centers exhibit lowest price sensitivity, accepting premium positioning for guaranteed uptime clauses and predictive maintenance integration.
Supply Chain Analysis
CE marking and ASME A17.1 certification requirements gate qualified supplier pools, with permanent magnet motor production concentrating in Japan, Germany, and South Korea. Steel rope assemblies and controller electronics draw from Chinese and Taiwanese component ecosystems. Single-source vulnerability sits with specialized traction sheave castings from European foundries. Distribution runs through OEM-direct channels for new installations and fragmented authorized service networks for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freight elevators function as a regulatory compounder where ASME A17.1 modernization mandates in the United States create replacement demand cycles independent of new construction activity.
For Market Incumbents: Deploy predictive maintenance platforms as the primary retention lever. Capture stranded hydraulic fleet data through controller retrofit partnerships before traction conversion decisions finalize. Deepen in-house production of permanent magnet motors to defend margin position against commodity input volatility from steel and copper markets. For New Entrants and Emerging Players: Begin with cold chain vertical transport specialization in Brazil and Saudi Arabia where ANVISA and SFDA sanitary regulations elevate specification barriers incumbent OEMs serve reluctantly. Target mid-cap warehousing operators in India's Gujarat corridor with machine room less traction configurations priced below European imports. Lead with energy performance contracting that transfers efficiency risk from capital-constrained facility operators. For Investors and Strategic Acquirers: Asymmetric upside sits with regional service specialists possessing predictive maintenance platforms and captive installation labor pools. Long-term viability hinges on recurring revenue attachment rates rather than equipment shipment volumes. Watch for inflection when EU F-Gas Regulation enforcement accelerates machine room less configuration demand beyond current manufacturing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Drive Portfolio Expansion | Qualifies OEMs for EU Green Deal accelerated depreciation incentives in German distribution centers. |
| Predictive Maintenance Platform Acquisition | Captures recurring revenue streams from vibration sensor integration with building management systems. |
| Machine Room Less Manufacturing Scale-Up | Addresses retrofit demand from legacy industrial buildings with constrained headroom across Ohio and Pennsylvania. |
| Cold Chain Specialization Partnership | Opens ANVISA-regulated pharmaceutical logistics facilities in São Paulo state to corrosion-resistant product lines. |
| Certified Installation Labor Pipeline Investment | Resolves journeyman mechanic scarcity extending project timelines in Germany and Japan. |
Methodological Framework
Direct dialogue with facility maintenance directors, OEM procurement managers, elevator mechanic union representatives, and third-party logistics operators combined trade data from U.S. Census Bureau construction spending reports, EU Machinery Directive conformity assessment databases, and Chinese customs export classifications with SEC 10-K equipment revenue disclosures. Bottom-up installation unit estimates triangulated against top-down construction spending allocation models.
Segment-level value outputs across the projection horizon reflect traction versus hydraulic technology splits, machine room less penetration rates, and service revenue attachment by end-user vertical. CAGRs derived from regression against logistics construction indices and regulatory mandate implementation schedules. Forecast inputs incorporated ASME A17.1 inspection cycle data and EU F-Gas Regulation phase-down timelines.
Several conditions sit outside the modeled scope, including unannounced building code revisions, commodity price spikes exceeding historical volatility bands, and trade policy disruptions affecting steel rope import flows. A model refresh is warranted upon material change in EPA energy efficiency benchmark enforcement or MEE dual carbon goal acceleration in China.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
United States Conveyor Belt Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market
Material Handling Equipment
Precision Ballscrews Market
Material Handling Equipment
Industrial Lift Ladder Market
Material Handling Equipment
Pneumatic Conveying Systems Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Global Bop Handling Systems Market
Material Handling Equipment
Vertical Lifts Market
Material Handling Equipment
Loaded Container Handler Market
Material Handling Equipment
Crate Handling Systems Market
Material Handling Equipment
Heavy Duty Ramp Market
Material Handling Equipment
Rotary Breaker Market
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
Global Large Conveyor Chain Market
Material Handling Equipment
Low Clearance Loaders Market