
 Global Telescopic Boom Forklift Truck Market | 2026-2036
Global Telescopic Boom Forklift Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Global Telescopic Boom Forklift Truck Market Analysis
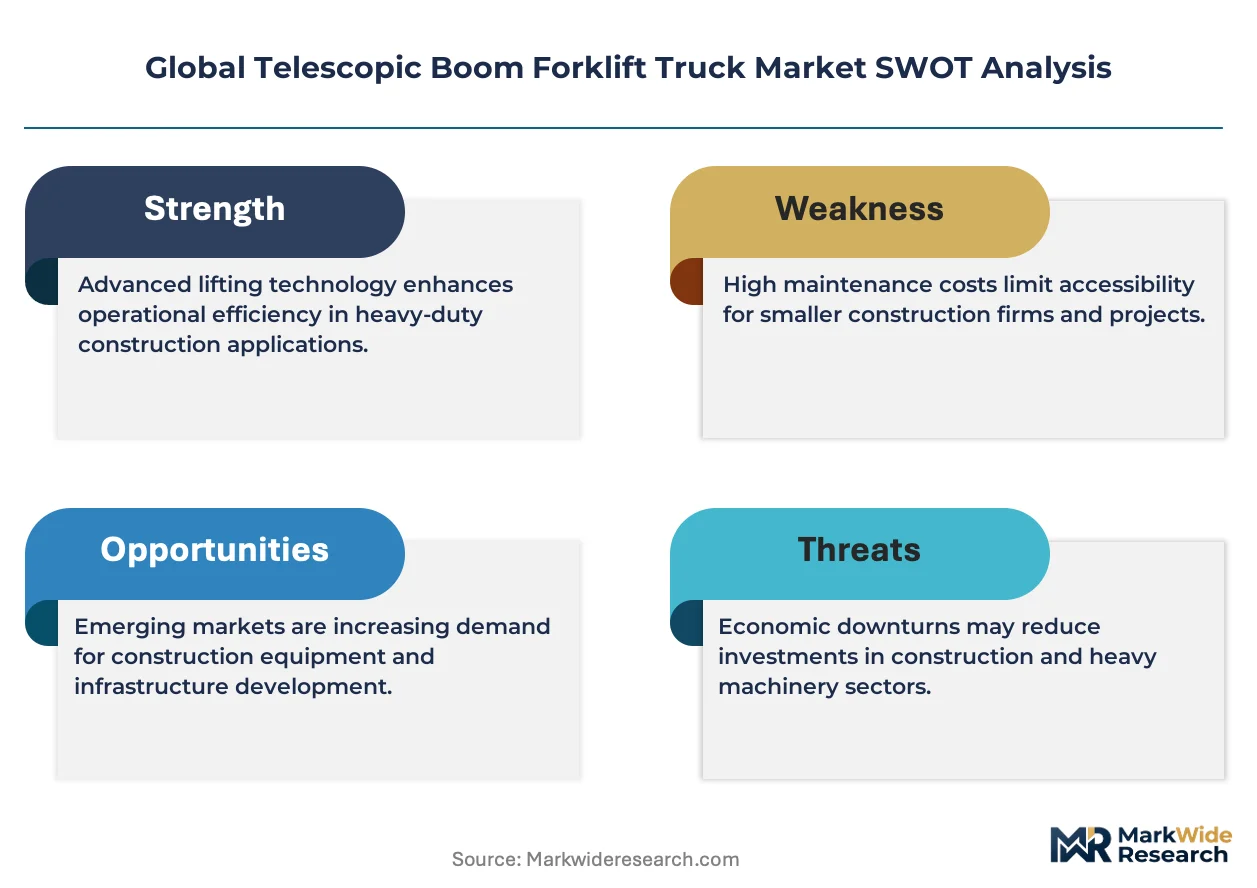
Equipment rental fleets and large general contractors is bifurcating demand away from small owner-operators across the telescopic boom forklift truck landscape. JLG Industries leverages vertical integration in boom manufacturing to control lead times for North American rental channels. Manitou Group anchors European supply through specialized agricultural configurations that sustain premium positioning. Caterpillar competes on brand strength and dealer density in heavy construction segments where uptime contracts dominate procurement.
Telescopic boom forklift trucks integrate extendable articulated booms with forklift carriage attachments, typically achieving lift heights exceeding standard rough-terrain forklifts through nested hydraulic cylinder stages; manufacturers machine boom sections from high-strength steel to manage torsional loads during extension. Diesel configurations still occupy the majority of installed base due to torque requirements in off-grid construction sites, though electric variants are capturing share in warehousing and indoor material handling where zero-emission mandates apply. The rental deployment channel generates the highest utilization rates as fleet owners amortize capital across multiple end users, while direct sales concentrate among agricultural buyers seeking customized hydraulic attachments.
EPA Tier 4 Final regulations in the United States and EU Stage V standards enforced by national type-approval authorities are compelling engine redesigns and after-treatment integration, elevating engineering costs for diesel-powered units. ISO 10896 rough-terrain forklift safety standards shape boom stability testing protocols that manufacturers must satisfy for CE marking and market access. Stakeholders must monitor battery energy density improvements and fast-charging infrastructure rollout to determine optimal timing for electric platform investments.
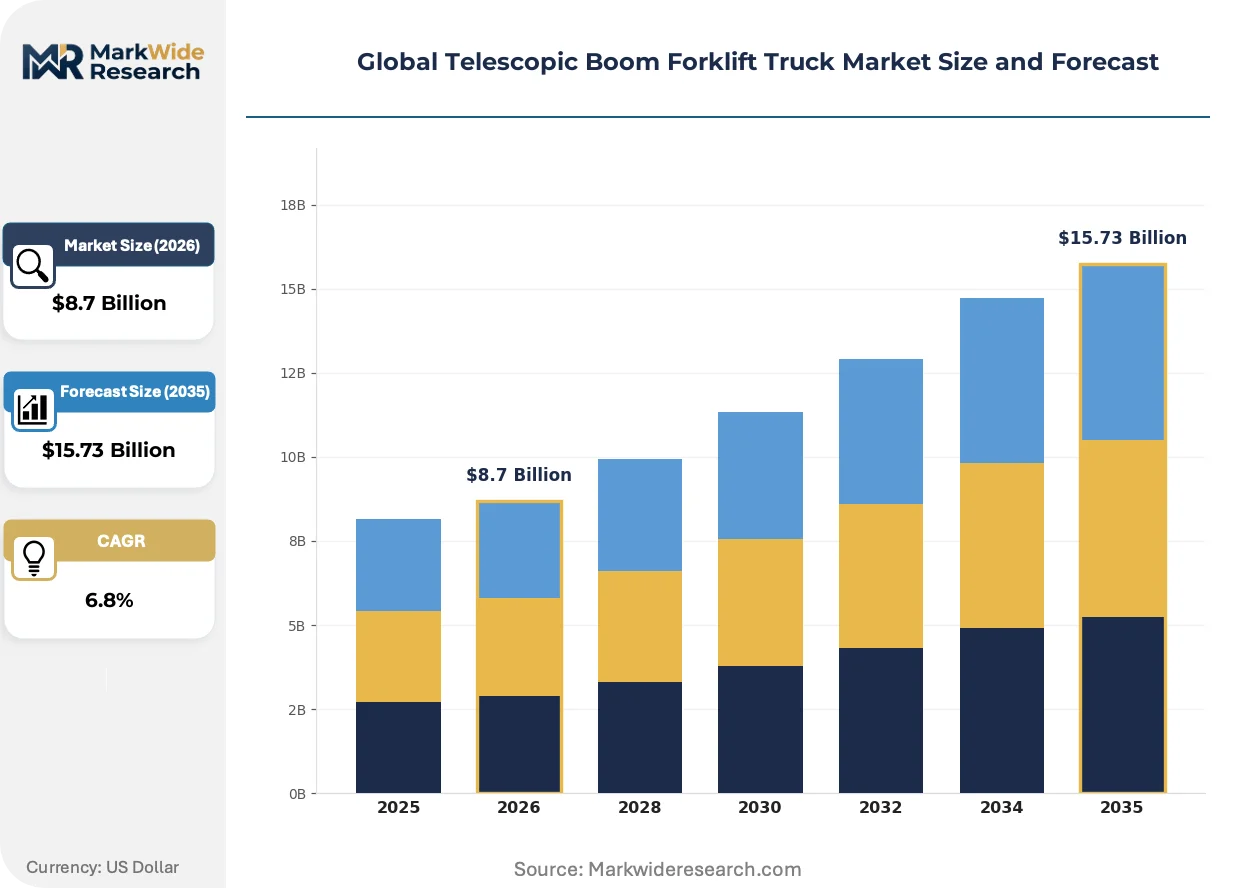
Market Dynamics
EPA Tier 4 Final and EU Stage V emission standards are forcing diesel-to-electric powertrain transitions while simultaneously inflating engineering costs and compressing margins for conventional engine architectures.
Growth Catalysts
- EPA Tier 4 Final compliance deadlines:Equipment rental fleets in the United States are accelerating replacement cycles to avoid penalties, pulling forward demand for certified units ahead of enforcement dates.
- Urban logistics densification:Zero-emission mandates in warehousing and indoor material handling are creating pull-through for electric telescopic boom variants with lithium-ion battery packs.
- Nested hydraulic cylinder advances:High-strength steel machining improvements are enabling greater lift heights without proportional weight penalties, expanding addressable applications in heavy construction.
Market Restraints
- After-treatment cost inflation:Diesel particulate filters and selective catalytic reduction systems required by EU Stage V are adding material cost burdens that manufacturers struggle to pass through in price-sensitive segments.
- Steel supply concentration:High-strength alloy plate production concentrates in a limited number of European and East Asian mills, exposing boom fabricators to input volatility and extended lead times.
- Electric range limitations:Battery energy density constraints restrict continuous operation duration for electric variants on off-grid construction sites lacking fast-charging infrastructure.
Strategic Opportunities
- German agricultural mechanization:Specialized hydraulic attachment demand among German farming cooperatives remains underserved by standardized rental fleet configurations, opening customization revenue pools.
- ISO 10896 certification arbitrage:Manufacturers achieving rough-terrain forklift safety standard compliance ahead of competitors can capture CE marking premiums in European markets with stringent type-approval requirements.
- Telematics-lease bundling:Fleet utilization data monetization through integrated IoT platforms is creating new recurring revenue streams alongside traditional equipment rental arrangements.
Industry Challenges
- Hydraulic systems engineering talent scarcity:Nested cylinder design and torsional load management expertise resides with a shrinking cohort of specialized engineers, constraining R&D velocity.
- CE marking timeline compression:ISO 10896 boom stability testing protocols require extended validation cycles that delay product launches and tie up capital in pre-certified inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Telescopic Boom Forklift Truck Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Diesel, LPG, Hydraulic Application: Construction, Agriculture, Warehousing, Landscaping End User: Contractors, Farmers, Retailers, Logistics Providers Deployment: On-site, Off-site, Rental, Sales |
| Companies Covered | Terex Corporation, Caterpillar, J C Bamford Excavators Ltd., JLG Industries, Manitou Group, Wacker Neuson SE, Liebherr-International AG, DIECI Srl, Merlo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Telescopic Boom Forklift Truck Market Emerging Trajectories
Powertrain electrification, safety standard harmonization, and rental fleet digitization are converging to reshape equipment economics and competitive positioning across material handling verticals.
Lithium-ion battery packs with integrated thermal management are decomposing the traditional diesel dominance in indoor and semi-urban applications. Warehousing operators in Germany and the Netherlands are specifying electric telescopic booms for zero-emission compliance, compressing the total cost of ownership gap versus diesel alternatives through reduced maintenance and energy arbitrage.
EU Stage V enforcement by national type-approval authorities is compelling engine platform consolidation across European manufacturing footprints. Diesel powertrain variants are disappearing from sub-50kW segments first, with agricultural buyers in France and Italy accepting price premiums for compliant units to maintain market access.
Equipment-as-a-service contracting is displacing outright purchase among mid-sized general contractors. United States rental channels are unbundling maintenance and telematics from base lease rates, with utilization-based pricing penetrating Texas and California construction markets where project duration uncertainty favors operational flexibility over capital commitment.
Global Telescopic Boom Forklift Truck Market Segmentation
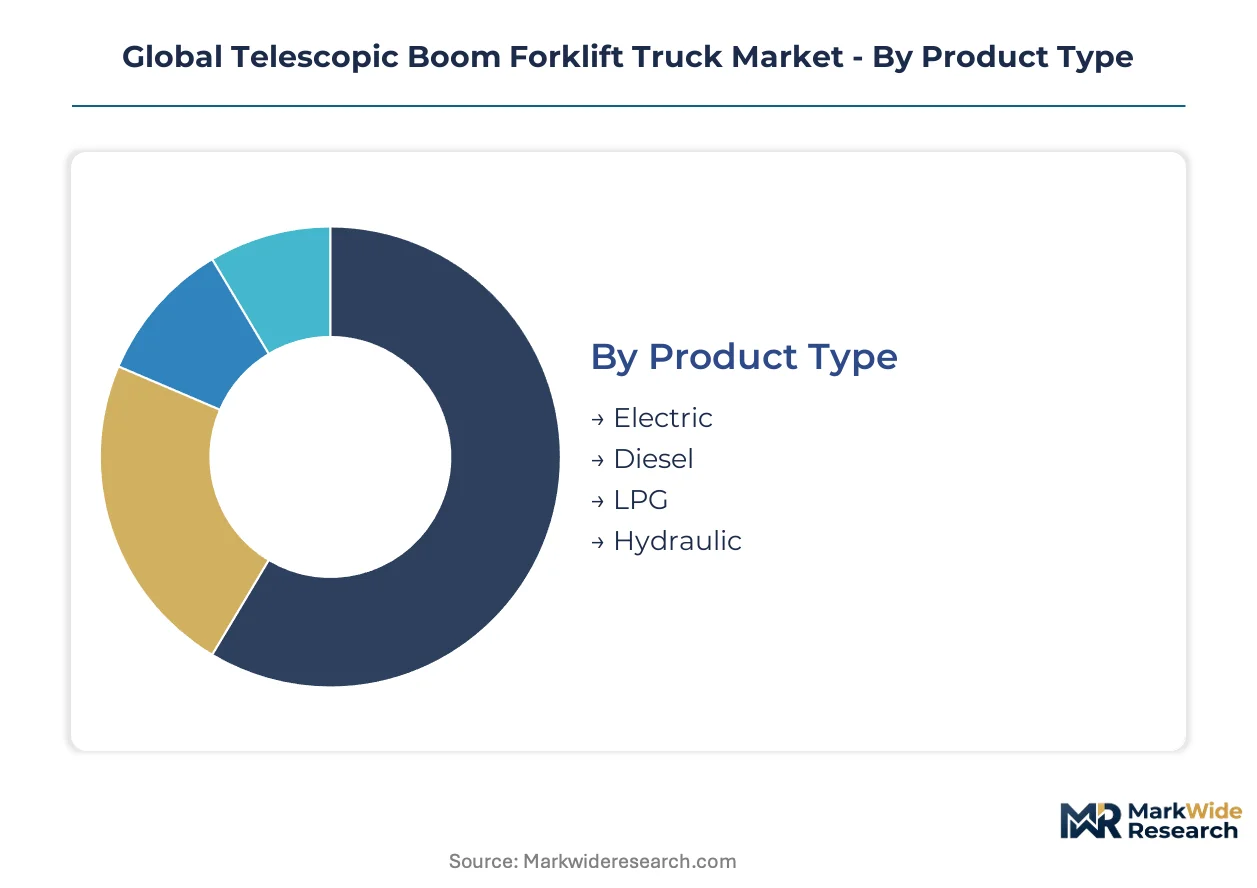
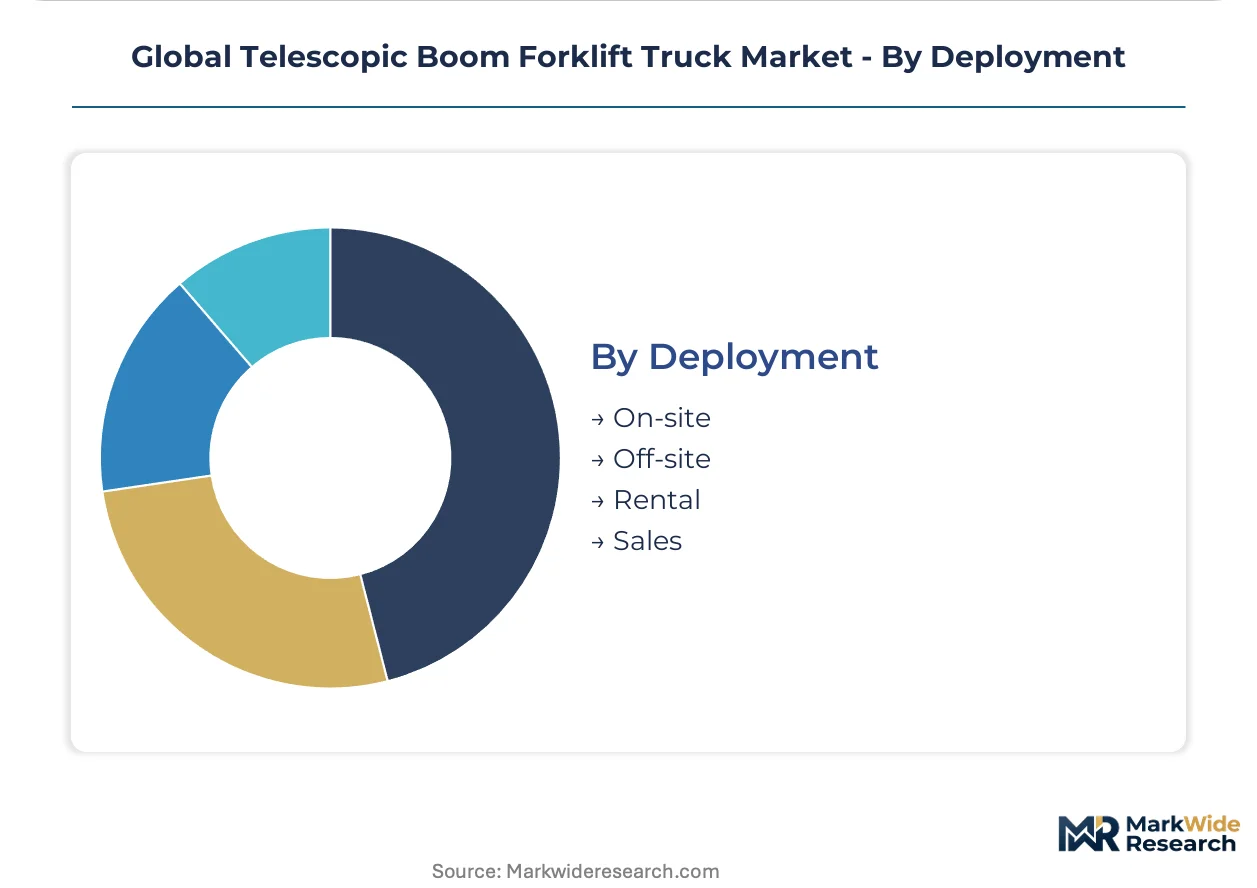
Telescopic boom forklift truck procurement channels diverge sharply across powertrain technologies and end-use applications. Rental fleets, direct agricultural sales, and contractor equipment-as-a-service contracts each favor distinct product configurations and pricing structures.
Product Type:
Channel-mix dynamics concentrate electric and diesel variants in rental fleets, while LPG and hydraulic configurations flow through specialized dealer networks serving niche applications.
- Electric:Lithium-ion battery packs with integrated thermal management systems deliver zero-emission operation for indoor warehousing and urban logistics. Demand clusters in Germany and the Netherlands where municipal zero-emission mandates apply, with fast-charging infrastructure investments accelerating fleet conversions.
- Diesel:EPA Tier 4 Final and EU Stage V compliant engines with after-treatment systems dominate off-grid construction sites requiring sustained torque output. Rental channels in Texas and California absorb the highest volumes as contractors prioritize uptime over capital expenditure.
- LPG:Propane powertrains bridge emission compliance and refueling infrastructure gaps in transitional markets.
- Hydraulic:Specialized fluid-power systems serve agricultural attachments requiring precise load modulation.
By volume, Diesel leads. By growth pace, Electric is expanding most quickly.
Application:
Cost-tier stratification separates premium heavy-lift construction specifications from standardized agricultural and warehousing configurations.
- Construction:Heavy-lift telescopic booms with nested hydraulic cylinders achieve lift heights exceeding 17 meters for infrastructure and commercial building projects. Demand concentrates in the United States where general contractors specify premium-capacity units for urban high-rise material handling.
- Agriculture:Specialized hydraulic attachments for bale handling and crop management command customization premiums in German and French farming cooperatives. Equipment-as-a-service contracts are displacing outright purchase among mid-sized operators seeking operational flexibility.
- Warehousing:Compact electric variants with maneuverable chassis serve indoor material handling in logistics hubs.
- Landscaping:Light-capacity units with turf-protecting tires address residential and commercial grounds maintenance.
Construction generates the highest revenue per unit. Warehousing is gaining share fastest through electrification mandates.
End User:
Customer-type concentration shapes procurement patterns, with rental intermediaries dominating contractor demand while farmers and retailers favor direct manufacturer relationships.
- Contractors:General and specialty construction firms specify rough-terrain capability and rapid deployment through rental channels. United States infrastructure project timelines are pulling forward fleet expansion among top-20 national contractors.
- Farmers:Agricultural cooperatives in Germany and France demand customized hydraulic attachments beyond standardized rental configurations. Direct sales relationships with regional dealers sustain premium positioning for specialized equipment.
- Retailers:Big-box and home improvement chains specify electric variants for distribution center operations.
- Logistics Providers:Third-party warehousing operators prioritize telematics-enabled fleet management for utilization optimization.
Contractors absorb the highest absolute volumes. Logistics providers are climbing the fastest through e-commerce fulfillment expansion.
Deployment:
Maturity-stage differentiation separates established rental and sales channels from emerging equipment-as-a-service and off-site deployment models.
- Rental:Fleet owners amortize capital across multiple end users, generating the highest utilization rates through telematics-enabled asset tracking. United States rental channels are unbundling maintenance and IoT services from base lease rates.
- Sales:Direct purchase concentrates among agricultural buyers seeking customized hydraulic configurations and long asset holding periods. German farming cooperatives sustain this channel through attachment specialization requirements.
- On-site:Dedicated equipment deployment for multi-year infrastructure projects.
- Off-site:Mobile fleet sharing across dispersed construction and agricultural operations.
Rental leads by fleet size. Off-site deployment shows the steepest expansion trajectory through asset-sharing platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment rental fleets and heavy construction contractors concentrate procurement in mature industrial economies with stringent emission enforcement. Demand clusters where infrastructure investment cycles intersect with regulatory compliance deadlines.
United States
General contractors operating in Texas and California are expanding rental fleet commitments ahead of EPA Tier 4 Final enforcement. The EPA compliance timeline is accelerating replacement cycles among top-20 national contractors. Houston's energy corridor construction activity is absorbing premium-capacity telescopic boom units for petrochemical facility upgrades.
Germany
Farming cooperatives in Bavaria and Baden-Württemberg are specifying customized hydraulic attachments beyond standardized rental configurations. EU Stage V type-approval requirements are elevating engineering costs for diesel-powered agricultural variants. Stuttgart's automotive supplier ecosystem is repurposing manufacturing equipment for boom fabrication to serve domestic OEM demand.
China
Urban logistics operators in the Yangtze River Delta are piloting electric telescopic boom deployments for warehouse densification projects. The Ministry of Ecology and Environment dual carbon goals are pressuring municipal fleets toward zero-emission procurement. Shanghai's port logistics cluster is integrating telescopic booms into container yard automation trials.
Japan
Construction firms in the Kanto region are adopting telematics-enabled rental contracts for Olympic legacy infrastructure maintenance. METI industrial efficiency standards are shaping equipment-as-a-service contract structures. Osaka's commercial building renovation market is specifying compact electric variants for constrained urban job sites.
France
Agricultural buyers in the Île-de-France and Auvergne-Rhône-Alpes regions are accepting price premiums for EU Stage V compliant units to maintain market access. The national type-approval authority enforcement timeline is compressing product launch windows for non-compliant manufacturers. Lyon's construction equipment distribution hub is consolidating regional dealer networks to optimize aftermarket service coverage.
Global Telescopic Boom Forklift Truck Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with captive construction equipment divisions. Market structure concentrates around vertically integrated manufacturers controlling boom fabrication and hydraulic system assembly. Three archetypes dominate: rental-channel specialists optimizing fleet utilization metrics, agricultural-configuration specialists commanding customization premiums, and heavy-lift premium-tier players competing on uptime contracting. Competitive moves center on backward integration into high-strength steel supply and telematics platform development for usage-based pricing.
Among European-based fabricators, Manitou Group and Merlo S.p.A. exemplify the agricultural-specialist archetype through regional dealer density and attachment customization capabilities. JLG Industries anchors the rental-channel specialist position in North American markets. Caterpillar occupies the diversified conglomerate tier where brand equity and service network scale determine procurement decisions in heavy construction segments.
| Leading Market Players |
|---|
| Terex Corporation |
| Caterpillar |
| J C Bamford Excavators Ltd. |
| JLG Industries |
| Manitou Group |
| Wacker Neuson SE |
| Liebherr-International AG |
| DIECI Srl |
| Merlo S.p.A. |
| Others |
Supply Flow & Price Mechanics
Lithium-ion battery pack substitution for diesel powertrains is redrawing procurement geography toward East Asian cell manufacturers while compressing margin structures for legacy engine suppliers locked into EPA Tier 4 Final after-treatment cost burdens.
Pricing Analysis
Cost-plus contracts with steel indexation dominate boom fabrication agreements between OEMs and European mill suppliers. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked heavy-lift units from rental fleet specifications and agricultural base configurations. Price differentiation hinges on ISO 10896 certification status and hydraulic customization depth. Pricing pressure stems from EU Stage V after-treatment cost pass-through struggles in sub-50kW segments. Agricultural cooperatives in France exhibit highest price sensitivity; infrastructure contractors in Texas absorb premium positioning through uptime contracting.
Supply Chain Analysis
Extended lead times for high-strength alloy plate have stretched to six months at German and South Korean mills serving boom fabricators. Supply concentrates in Sweden, Germany, and Japan for precision-machined hydraulic cylinder components. Raw material dependencies center on high-strength steel plate, lithium-ion cathode materials, and specialized hydraulic seals. Single-source vulnerability runs through nested cylinder engineering talent concentrated at a handful of European component suppliers. Distribution runs through rental fleet aggregators in North America and specialized agricultural dealers in continental Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where telematics-enabled utilization tracking and predictive maintenance contracts are expanding faster than hardware unit economics.
For Market Incumbents: Consolidate backward integration into high-strength steel supply to defend against mill concentration volatility in Europe and East Asia. Deepen captive hydraulic cylinder production capabilities to offset engineering talent scarcity constraining R&D velocity. Prioritize ISO 10896 pre-certification inventory positions to capture CE marking premiums ahead of competitors facing compressed launch timelines. For New Entrants and Emerging Players: Differentiate on electric platform architectures targeting German and Dutch warehousing operators under municipal zero-emission mandates. White-space sits with customized agricultural attachments for Bavarian farming cooperatives underserved by standardized rental configurations. Pursue equipment-as-a-service contracting models to bypass capital-intensive fleet ownership barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rental fleet operators seeking telematics platform consolidation. Long-term viability favors manufacturers controlling boom fabrication and battery thermal management integration. Monitor fast-charging infrastructure rollout velocity in Texas and California as inflection indicator for electric variant adoption timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Strength Steel | Captive supply from Swedish and German mills insulates boom fabricators from alloy plate volatility. |
| Telematics Platform Development | IoT-enabled utilization tracking unlocks recurring revenue from Texas and California rental channels. |
| ISO 10896 Pre-Certification Investment | Early compliance capture accelerates CE marking access in EU Stage V enforcement windows. |
| Electric Powertrain Platform Launch | Lithium-ion variants address German municipal zero-emission mandates in warehousing segments. |
| Hydraulic Attachment Customization | Specialized configurations for French agricultural cooperatives sustain premium pricing outside rental commoditization. |
Methodological Framework
A spread of perspectives from rental fleet operations directors, agricultural equipment procurement managers, hydraulic systems engineers, and construction contractor equipment heads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with aftermarket service heads and OEM platform engineers, validated against customs trade data for high-strength steel imports, EPA certification filings for Tier 4 Final engines, and EU type-approval authority registration databases. Bottom-up unit economics triangulated against top-down equipment fleet sizing from national construction industry associations.
Segmentation dimensions modeled span powertrain technology, lift capacity tier, deployment channel, and end-use application across the projection horizon. Value outputs reflect unit pricing stratification by certification grade and customization depth, with volume trajectories anchored to infrastructure investment cycles and agricultural mechanization trends. CAGRs derived from replacement cycle analysis, emission compliance deadline acceleration effects, and electric variant penetration curves in warehousing segments.
The analysis sits within stated boundaries; outcomes outside sustained steel price stability, battery energy density improvement trajectories, or EU Stage V enforcement continuity would require recalibration. Forecasts reflect documented assumptions regarding rental channel expansion rates and fast-charging infrastructure buildout timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Europe Port Equipment Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Material Handling Equipment Market
Material Handling Equipment
Machined Springs Market
Material Handling Equipment
Pick and Carry (PNC) Crane Market
Material Handling Equipment
Roll Slitting Machines Market
Material Handling Equipment
Global Pipe and Tube Bending Machine Market
Material Handling Equipment
Manual Lifting Mobile Light Tower Market
Material Handling Equipment
Vertical Baling Press Market
Material Handling Equipment
Slow Speed Shredding Machines Market
Material Handling Equipment
Global Hopper Loader Market
Material Handling Equipment
Shiplifts & Transfer Systems Market
Material Handling Equipment
Global Bop Handling Systems Market
Material Handling Equipment
Sorting Equipment Market
Material Handling Equipment
Hose Pump Market