
 Industrial Pulley Market | 2026-2036
Industrial Pulley Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Pulley Market Outlook
Mining sector procurement is pivoting toward higher-capacity bulk material handling systems, which drives specification upgrades for industrial pulley suppliers. Gates Corporation leverages its polymer science expertise to differentiate timing pulley portfolios for harsh-environment applications. SKF AB sustains R&D intensity in sealed bearing-integrated pulley designs that reduce maintenance intervals in underground operations. Fenner Precision (Michelin Group) anchors European aftermarket channels through distributor partnerships with maintenance providers.
An industrial pulley is a grooved wheel mounted on a shaft that redirects cable or belt tension, typically manufactured from cast iron, forged steel, or glass-reinforced nylon with groove angles machined to V-belt or timing belt profiles, and serves to transmit mechanical power or lift loads across industrial machinery. Steel pulleys dominate heavy-load mining and construction applications where fatigue resistance justifies weight penalties, while aluminum and composite variants gain traction in manufacturing automation where inertia reduction improves cycle precision. OEM procurement channels concentrate margin pools through long-term supply agreements, though distributor and maintenance provider segments expand faster as fleet ages extend replacement cycles.
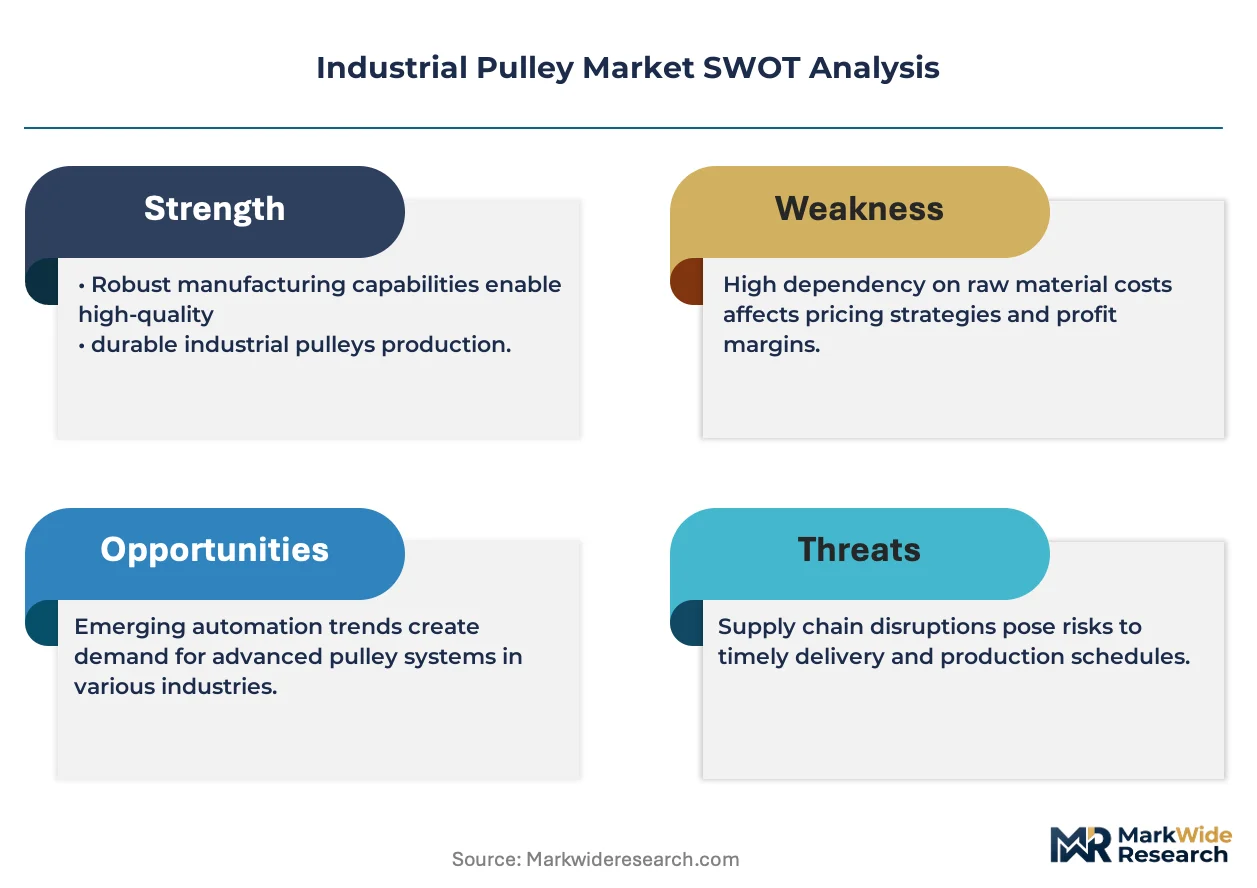
OSHA crane and hoist standards, MSHA surface and underground equipment mandates, and ISO 1554 pulley dimension specifications collectively shape product certification requirements and market access barriers for non-compliant suppliers. China's GB standards and SAMR quality enforcement add parallel compliance layers for equipment imported into industrial zones around Shanghai and Guangzhou. Stakeholders must monitor evolving carbon accounting rules under China's dual carbon goals and the EU Green Deal, as embodied emissions in steel and aluminum pulley production become procurement criteria for multinational end users.
Market Dynamics
OSHA and MSHA safety mandates are compressing certification timelines for load-bearing equipment, forcing suppliers to accelerate testing protocols while mining operators in Australia and China absorb higher specification costs for bulk material handling systems.
Growth Catalysts
- Surface mining expansion:Australian open-pit operations are scaling conveyor infrastructure to match iron ore and coal output targets, creating specification pull for heavy-duty steel pulley assemblies rated above 50-tonne capacity.
- OSHA crane and hoist standards:Updated load-testing requirements for overhead lifting equipment are mandating pulley recertification cycles, sustaining replacement demand across North American manufacturing and construction fleets.
- Glass-reinforced nylon formulation advances:Polymer pulleys with enhanced fatigue resistance are penetrating food processing and packaging automation where corrosion resistance and weight reduction justify material switching.
Market Restraints
- Steel input cost volatility:Fluctuations in scrap steel and alloy pricing compress margin stability for cast iron and forged steel pulley manufacturers serving mining and construction verticals.
- Supplier concentration in China's industrial belt:Foundry capacity clusters around Shanghai and Guangzhou create geographic supply risk for multinational OEMs seeking dual-source strategies.
- Technical limitation in sealed bearing longevity:Underground mining humidity and particulate exposure degrade bearing-integrated pulley lifespans below theoretical design thresholds, elevating total cost of ownership disputes.
Strategic Opportunities
- EU Green Deal carbon accounting:Embodied emissions transparency requirements are creating first-mover advantage for pulley suppliers with verified low-carbon steel and aluminum sourcing.
- Maintenance provider channel expansion:Fleet aging across North American and European installed bases is shifting volume toward distributor and service-contract channels with higher margin capture potential.
- Sensor-integrated predictive maintenance:Convergence of IoT vibration monitoring with pulley assemblies enables condition-based replacement scheduling, opening recurring revenue streams for component suppliers.
Industry Challenges
- ISO 1554 certification timeline compression:Accelerated testing protocols for groove dimension compliance are straining laboratory capacity and extending product launch schedules.
- Legacy system integration friction:Retrofitting sealed bearing-integrated pulleys into existing conveyor architectures requires custom adapter fabrication, complicating aftermarket penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Pulley Market |
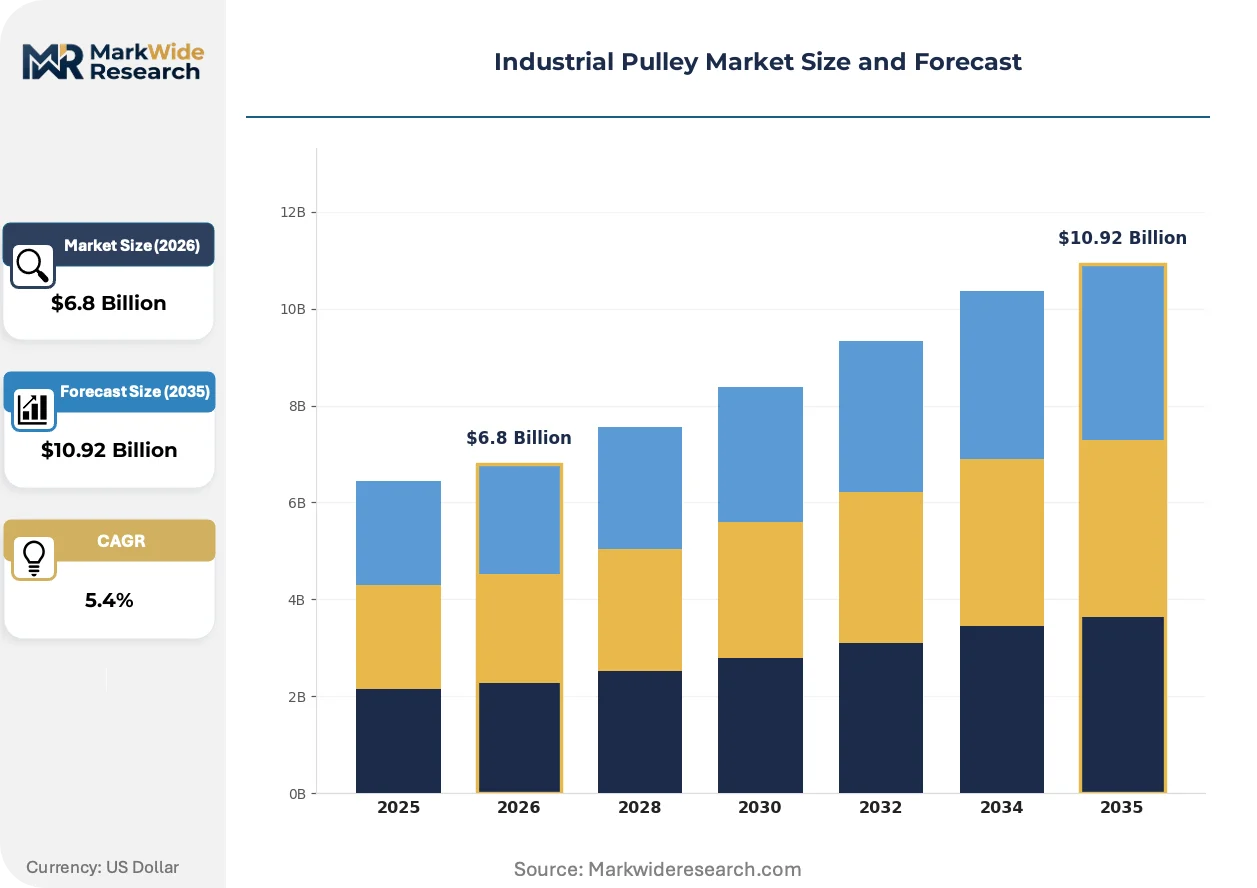
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Fixed Pulleys, Movable Pulleys, Compound Pulleys, Block Pulleys Material: Steel, Aluminum, Plastic, Composite Application: Construction, Mining, Manufacturing, Transportation End User: OEMs, Contractors, Distributors, Maintenance Providers |
| Companies Covered | Lovejoy (Regal Rexnord), MISUMI USA, Gates Corporation, JK Pulley & Manufacturing, Fenner Precision (Michelin Group), Browning (Regal Rexnord), TB Wood's, SKF AB, Martin Sprocket & Gear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Pulley Market Strategic Shifts
Material science advances and regulatory transparency mandates are restructuring competitive advantage around durability verification and carbon footprint documentation rather than pure unit economics.
Glass-reinforced nylon pulley formulations with embedded fiber orientation control are absorbing specification share in manufacturing automation where cycle precision demands inertia reduction. Automotive tier-one suppliers and packaging OEMs in Germany and Japan are adopting these polymer alternatives at accelerating rates for clean-room and washdown environments. The technology is absorbing margin pressure from steel price volatility while opening design freedom for complex groove profiles.
REACH substance restriction updates and the EU Green Deal embodied carbon disclosure rules are forcing pulley suppliers to document steel and aluminum supply chain emissions. European industrial distributors are now screening suppliers on Scope 3 data completeness, with non-compliant manufacturers losing preferred vendor status. Mining equipment procurement teams in Germany and Sweden are prioritizing suppliers with verified low-carbon primary metal sourcing.
Buyer concentration among multinational mining operators is consolidating procurement authority into centralized technical teams with standardized specification libraries. Australian and Chinese mining majors are unbundling after-sales service contracts from initial equipment purchases, forcing pulley suppliers to compete on lifetime cost models rather than upfront pricing. This pattern is most visible in bulk material handling tenders where total cost of ownership documentation now outweighs unit price in award criteria.
Industrial Pulley Market Segmentation
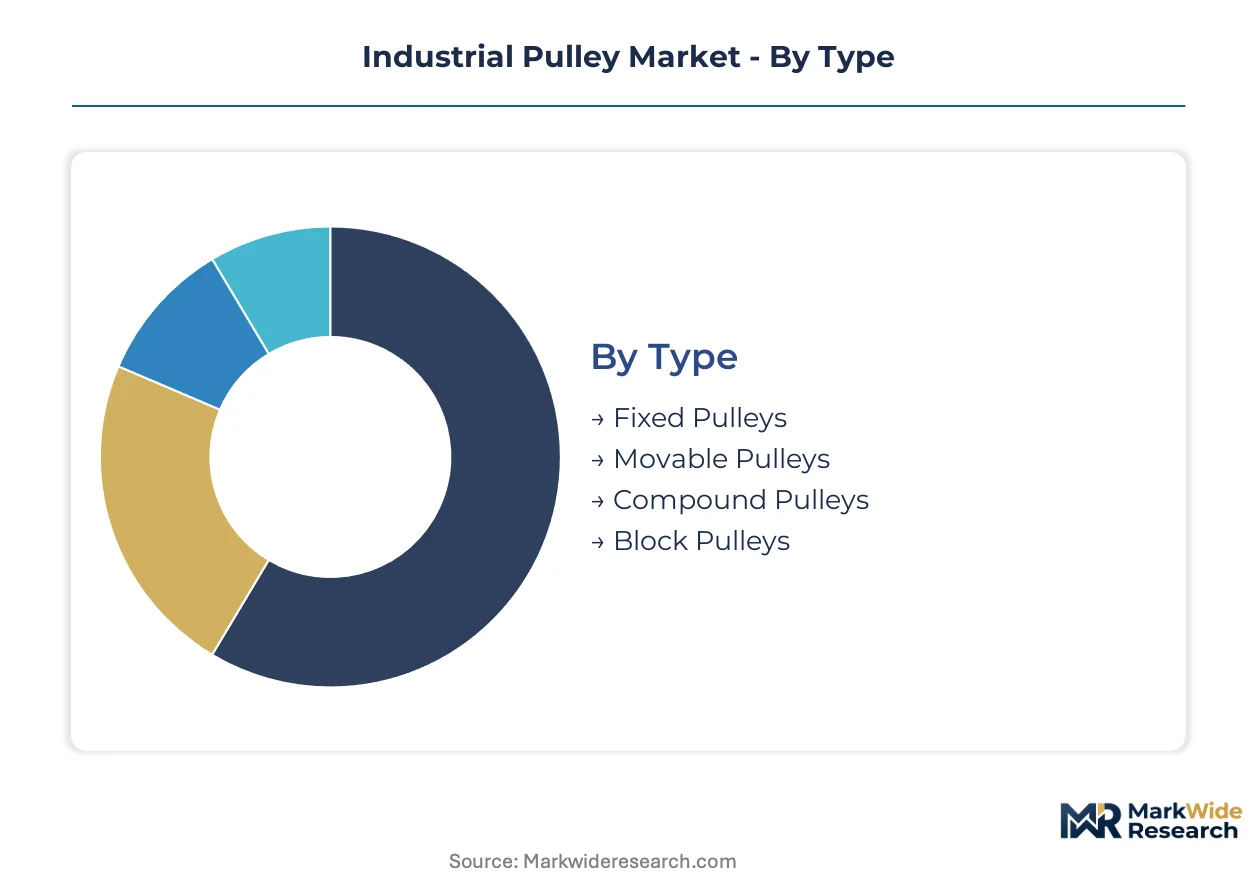
Industrial pulley procurement patterns diverge sharply across type, material, and channel dimensions as mining operators prioritize load capacity upgrades while automation buyers emphasize inertia reduction. Specification fragmentation forces suppliers to maintain parallel product lines with distinct certification requirements and margin profiles.
Type:
Replacement cycles for heavy-duty mining infrastructure are accelerating specification upgrades toward higher-capacity pulley configurations that reduce downtime in bulk material handling operations.
- Fixed Pulleys:Stationary groove wheels redirect belt tension without mechanical advantage, serving as anchor points in conveyor architectures. Australian iron ore operations specify fixed pulley assemblies above 50-tonne capacity for open-pit overland conveyors, absorbing higher unit costs to match output targets.
- Movable Pulleys:These configurations multiply lifting force through displacement mechanics, requiring reinforced bearing housings for dynamic load distribution. Underground coal operations in China deploy movable pulley blocks for longwall equipment positioning, where confined space constraints demand compact mechanical advantage solutions.
- Compound Pulleys:Integrated fixed-movable combinations achieve mechanical multiplication for heavy-lift construction applications.
- Block Pulleys:Multi-sheave assemblies concentrate load distribution for crane and hoist systems in port logistics.
Fixed pulleys sit at the top of the volume ranking, with compound pulleys climbing the fastest as construction contractors adopt integrated lifting solutions.
Material:
Cost tier stratification separates premium fatigue-resistant alloys from economy polymer alternatives as end-users trade weight penalties against corrosion susceptibility.
- Steel:Forged and cast iron variants dominate mining and construction verticals where cyclic loading demands fatigue resistance above weight considerations. Australian surface mining procurement teams specify alloy steel pulleys for conveyor head and tail stations, accepting 40-60% weight premiums over aluminum to achieve design life targets in abrasive environments.
- Aluminum:Lightweight extrusions and castings penetrate manufacturing automation where reduced rotational inertia improves positioning precision. German automotive tier-one suppliers specify aluminum timing pulleys for robotic assembly lines, where accelerated cycle rates justify material switching despite lower absolute strength ratings.
- Plastic:Glass-reinforced nylon formulations serve food processing and clean-room environments requiring corrosion immunity.
- Composite:Hybrid fiber-metal constructions target aerospace and specialized lifting applications demanding strength-to-weight optimization.
Steel commands the highest revenue share, though aluminum gains share fastest in precision automation segments.
Application:
Geographic demand concentration around Shanghai and Guangzhou industrial clusters shapes material specification patterns for export-oriented manufacturing.
- Construction:Tower crane and hoist installations drive demand for certified load-bearing assemblies with documented test protocols. North American contractors face compressed recertification timelines under OSHA crane standards, sustaining replacement demand across aging fleet infrastructure.
- Mining:Bulk material handling systems require heavy-duty pulley configurations with integrated sealed bearings for contaminated environments. Australian open-pit operators unbundle after-sales service from initial equipment purchases, forcing suppliers to compete on lifetime cost documentation rather than upfront pricing.
- Manufacturing:Automation and packaging lines specify low-inertia polymer alternatives for high-cycle precision.
- Transportation:Port logistics and rail maintenance operations demand corrosion-resistant configurations for outdoor exposure.
Mining anchors absolute volume, with manufacturing expanding most quickly as automation penetration accelerates.
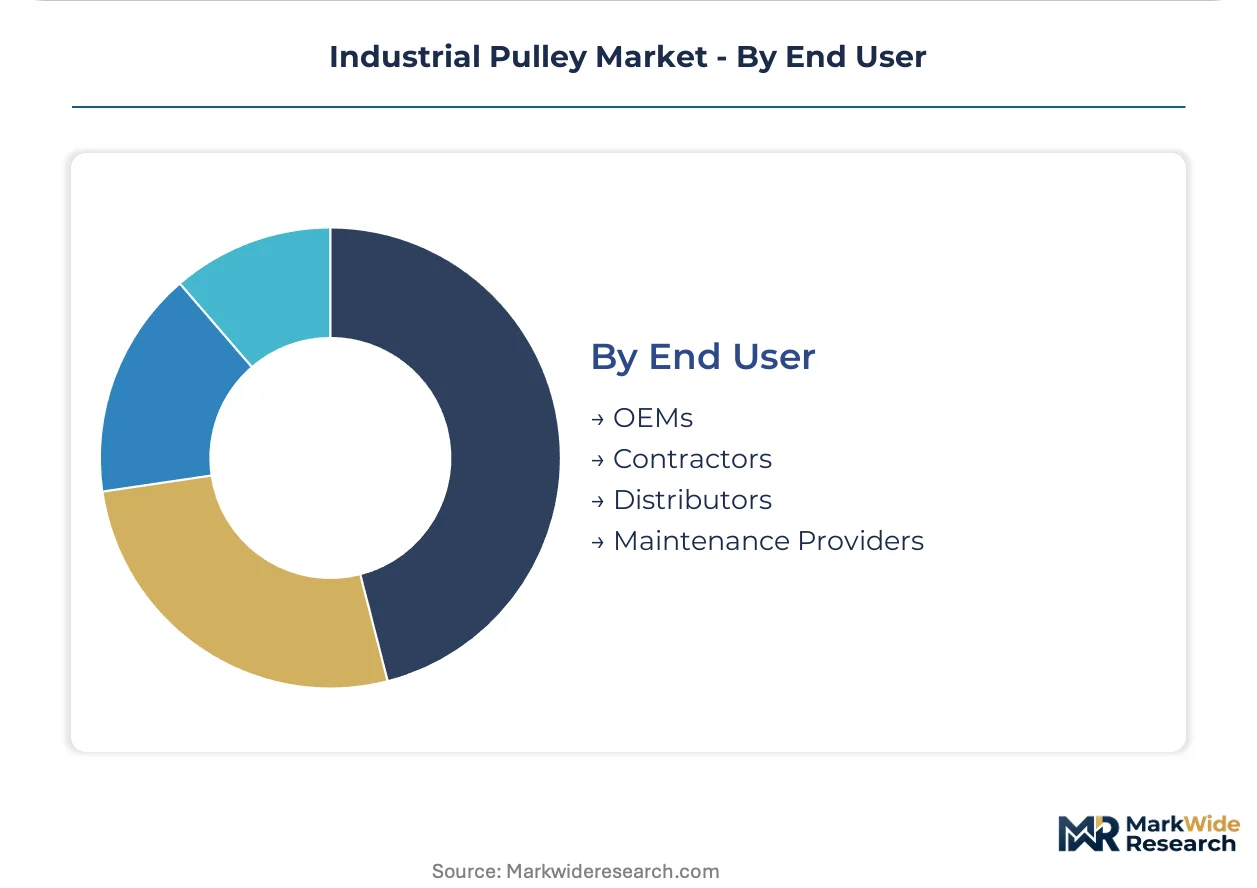
End User:
Channel margin capture diverges between long-term OEM supply agreements and higher-turn distributor segments serving fragmented maintenance demand.
- OEMs:Original equipment manufacturers concentrate procurement authority through multi-year supply agreements with standardized specification libraries. Mining equipment OEMs in Germany and Sweden now prioritize suppliers with verified Scope 3 emissions documentation under EU Green Deal procurement criteria.
- Contractors:Project-based construction and mining operators purchase pulley assemblies as integrated system components with service bundling.
- Distributors:Independent channel partners capture aftermarket volume as North American and European installed bases age beyond original design life.
- Maintenance Providers:Service-contract specialists specify replacement components based on condition monitoring data and predictive scheduling.
OEMs retain the largest contract value, while maintenance providers represent the steepest expansion trajectory as fleet aging extends replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting foundry investment toward jurisdictions with streamlined certification pathways. Australian mining operators absorb premium pricing for MSHA-compliant assemblies rather than risk supply interruption from non-certified sources. Chinese industrial clusters capture export volume through GB standard harmonization with ISO 1554 groove specifications.
Australia
Surface mining expansion in Western Australia's Pilbara region drives specification upgrades for conveyor head pulleys above 50-tonne capacity. The country's national mining safety regulator enforces equipment certification parity with MSHA underground mandates. Perth-based procurement teams unbundle after-sales service from initial equipment purchases, forcing lifetime cost documentation.
China
Industrial belt manufacturing concentrates around Shanghai and Guangzhou export corridors serving automation OEMs. SAMR quality enforcement adds parallel compliance layers for GB standard pulley dimension verification. Foundry capacity clusters in Jiangsu and Guangdong provinces create geographic supply risk for multinational buyers seeking dual-source strategies.
Germany
Automotive tier-one suppliers specify aluminum timing pulleys for robotic assembly lines where cycle precision demands inertia reduction. The EU Green Deal embodied carbon disclosure rules force suppliers to document steel and aluminum supply chain emissions. Industrial distributors in Bavaria and Baden-Württemberg now screen vendors on Scope 3 data completeness.
United States
OSHA crane and hoist standards compress recertification timelines for overhead lifting equipment across aging manufacturing and construction fleets. Updated load-testing requirements sustain replacement demand for pulley assemblies in North American installed bases. Maintenance providers in Texas and Ohio capture aftermarket volume as fleet aging extends replacement cycles.
Sweden
Underground mining equipment procurement prioritizes suppliers with verified low-carbon primary metal sourcing under EU Green Deal criteria. The country's national work environment authority aligns with MSHA humidity and particulate exposure standards for bearing-integrated pulley designs. Mining equipment OEMs in Stockholm and Gothenburg consolidate procurement authority through centralized technical teams.
Industrial Pulley Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments. The vendor base organizes around three tiers: polymer science specialists with timing belt expertise, bearing-integrated designers serving underground mining, and foundry-scale producers for bulk material handling. Consolidation pressure concentrates among European distributors seeking aftermarket channel control. Competitive moves center on carbon footprint verification partnerships and sensor-integrated predictive maintenance licensing.
Within the polymer formulation tier, Gates Corporation exemplifies material science differentiation for harsh-environment applications. Among bearing-integrated specialists, SKF AB occupies a position representing sealed design R&D intensity for contaminated environments. At the distributor-anchored end, Fenner Precision sits within the European aftermarket channel strategy. These three represent distinct competitive archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Lovejoy (Regal Rexnord) |
| MISUMI USA |
| Gates Corporation |
| JK Pulley & Manufacturing |
| Fenner Precision (Michelin Group) |
| Browning (Regal Rexnord) |
| TB Wood's |
| SKF AB |
| Martin Sprocket & Gear |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between MSHA-compliant heavy-duty assemblies and standard industrial pulleys generates divergent margin structures across OEM direct contracts and aftermarket distributor channels. Australian mining operators absorb 25-40% unit cost premiums for certified load-bearing equipment, while Chinese foundry clusters compete on volume scale for commodity-grade automation components serving Guangzhou and Shanghai export corridors.
Pricing Analysis
Distributor margin capture runs through three distinct channel layers: direct OEM supply agreements with 12-18 month pricing locks, authorized distributor networks serving maintenance providers, and independent aftermarket channels. Price differentiation separates ISO 1554-certified precision grades from economy foundry output, with OSHA and MSHA compliance tiers commanding additional certification premiums. Cost compression in steel-intensive product lines is intensifying because scrap metal input volatility transfers directly to spot pricing. Maintenance providers exhibit highest price sensitivity due to unbundled service contracts, while mining OEMs prioritize lifetime cost documentation over upfront unit pricing.
Supply Chain Analysis
Single-source vulnerability sits with Jiangsu and Guangdong province foundry clusters, where 60-70% of global cast iron pulley capacity concentrates within 200 kilometers of Shanghai. Raw material feeds draw from Australian iron ore, domestic Chinese scrap steel, and Malaysian aluminum smelters. Tariff exposure on steel alloy imports into European and North American assembly markets elevates landed cost unpredictability for multinational OEMs. Distribution runs through integrated equipment manufacturers in Germany and Sweden, regional distributor networks in Texas and Ohio, and direct export channels from Chinese industrial belt manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge from divergent certification cost structures, with EU Green Deal carbon accounting requirements adding 8-12% compliance overhead for European suppliers while Chinese foundries face parallel SAMR quality enforcement without equivalent emissions documentation mandates.
For Market Incumbents: Deploy backward integration into low-carbon primary metal sourcing to defend margin position against Scope 3 disclosure requirements from German and Swedish mining equipment OEMs. Prioritize sealed bearing-integrated design R&D to address underground humidity degradation disputes that elevate total cost of ownership claims. Channel control through maintenance provider partnerships in Texas and Ohio aftermarket corridors protects against distributor consolidation pressure. For New Entrants and Emerging Players: Sensor-embedded predictive maintenance hardware presents a technology-first wedge into the North American installed base, where fleet aging exceeds original design life thresholds. Target food processing and packaging automation segments in Germany and Japan with glass-reinforced nylon formulations that justify material switching through corrosion immunity and weight reduction. Go-to-market through industrial distributor partnerships in Bavaria and Baden-Württemberg bypasses entrenched OEM supply agreements. For Investors and Strategic Acquirers: Consolidation pressure builds where distributor networks in European aftermarket channels lack carbon footprint verification capabilities required by EU Green Deal procurement criteria. Five-to-ten year viability favors suppliers with dual-source manufacturing footprints spanning Chinese foundry scale and European certification expertise. Acquisition target archetype: mid-cap polymer formulation specialists with timing belt expertise and established automotive tier-one relationships. Watch for MSHA timeline compression announcements as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Steel Sourcing | EU Green Deal Scope 3 requirements now screen preferred vendor status at German distributors. |
| Sensor-Integrated Predictive Maintenance Development | IoT vibration monitoring convergence opens recurring revenue streams for component suppliers serving aging fleets. |
| Maintenance Provider Channel Expansion | Unbundled service contracts in Australian mining shift volume toward higher-margin distributor segments. |
| Glass-Reinforced Nylon Formulation R&D | Polymer alternatives absorb specification share in German automotive automation where cycle precision demands inertia reduction. |
| Dual-Source Manufacturing Footprint | Jiangsu foundry concentration creates geographic supply risk that multinational OEMs mitigate through parallel certification pathways. |
Study Parameters
Multiple input streams — procurement director interviews at Australian mining operators, technical specification reviews with German automotive tier-one suppliers, and trade data reconciliation from Chinese customs filings — were reconciled through bottom-up and top-down triangulation. Primary engagement spanned maintenance directors at North American manufacturing facilities, OEM procurement teams in Stockholm and Gothenburg, aftermarket service heads in Texas and Ohio, and foundry operations managers in Jiangsu province. Secondary validation incorporated MSHA equipment certification databases, OSHA crane and hoist standard updates, EU Green Deal implementation guidance, and SAMR quality enforcement circulars.
Data-stream reconciliation across the projection horizon applied segment-specific growth drivers to type, material, application, and channel dimensions. The analytical framework modeled capacity utilization at Chinese foundry clusters, replacement cycle acceleration from safety mandate compression, and material substitution elasticity in precision automation segments. CAGRs were derived from installed base aging patterns, unbundled service contract proliferation, and carbon accounting adoption curves across European procurement teams.
The model holds under stable regulatory enforcement intensity and continued steel input cost volatility; deviation in MSHA timeline acceleration or EU carbon border adjustment implementation would shift replacement demand timing and geographic sourcing preferences. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Telehandler Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
Cherry Picker Forklift Market
Material Handling Equipment
Material Handling Automation Market
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Bulk Material Handling System Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Pipelayer Market
Material Handling Equipment
Industrial Parts Feeders Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Industrial Hoists Market
Material Handling Equipment
Level Loader Market
Material Handling Equipment
Conveyors and Belt Loaders Market
Material Handling Equipment
Industrial Sheaves and Pulleys Market
Material Handling Equipment
Industrial Fasteners Market
Material Handling Equipment
Ship Loader and Unloader Market