
 GCC Conveyor Belt Market | 2026-2036
GCC Conveyor Belt Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Conveyor Belt Market Intelligence
A capital-intensity divergence between regional fabricators and European multinationals is collapsing as technology transfer agreements proliferate. Continental AG leverages its integrated manufacturing footprint to anchor premium heavy-duty supply contracts across Gulf cement and steel plants. Habasit Holding AG competes through modular PVC specialization, sustaining technical service density in Dubai's logistics corridors. Fenner Dunlop differentiates via aramid-reinforced compound expertise, occupying niche mining applications where heat and abrasion resistance command specification priority.
Conveyor belts are continuous elastomeric or synthetic fabric-reinforced loops engineered to transport bulk or unitized materials across defined paths, with operational parameters typically spanning tensile strengths from 315 N/mm to over 5,000 N/mm and temperature tolerances from -40°C to 400°C depending on compound formulation and carcass construction. Their primary industrial purpose centers on reducing manual handling costs while enabling controlled throughput velocity in mining extraction, port bulk terminals, and automated distribution centers. Heavy-duty rubber configurations dominate installed value across GCC mining and aggregate operations where carcass integrity under impact loading determines replacement cycles. Light-duty modular and PVC segments are capturing incremental share in food processing and intralogistics applications across Saudi Arabia's industrial cities, where washdown compliance and quick-change splicing reduce downtime penalties. Specialty high-speed belts concentrate margin pools in airport baggage handling and e-commerce sortation hubs concentrated in Dubai South and Jeddah Islamic Port free zones.
Gulf national standards bodies coordinate with SASO in Saudi Arabia and ESMA in the UAE to enforce fire-resistance ratings and static conductivity thresholds for underground mining belts, while OSHA-equivalent occupational frameworks across Bahrain and Oman mandate emergency stop integration and guarding protocols. These regulatory layers elevate compliance costs for non-certified imports while creating specification barriers that favor established suppliers with documented testing regimes. Stakeholders must monitor how Saudi Vision 2030 localization incentives and UAE domestic value-add requirements recalibrate sourcing patterns for replacement belting and integrated conveyor systems.
Market Dynamics
Aramid-reinforced compounds are displacing traditional steel-cord carcasses across Saudi mining clusters as operators prioritize heat tolerance over initial capex savings. ESMA fire-resistance mandates and SASO static conductivity thresholds now gate market access for non-certified imports.
Growth Catalysts
- Saudi Vision 2030 Localization Incentives:Domestic value-add requirements for mining equipment procurement are redirecting replacement belting contracts toward regional fabricators with in-country splicing facilities.
- UAE Logistics Free Zone Expansion:Dubai South and Jeddah Islamic Port e-commerce sortation hubs are generating specification demand for high-speed modular PVC configurations with sub-500mm pulley diameters.
- Aramid-Reinforced Compound Adoption:Heat-resistant carcass materials are extending replacement cycles in Eastern Province cement and steel operations where abrasion and thermal loading previously dictated 18-month changeouts.
Market Restraints
- Natural Rubber Input Volatility:Gulf fabricators remain exposed to Southeast Asian latex price swings that compress margin buffers on heavy-duty mining contracts with fixed-price terms.
- European Multinational Supply Concentration:Premium heavy-duty specification authority still resides with Continental AG and Fenner Dunlop, limiting pricing leverage for regional competitors in integrated plant contracts.
- Technical Limitation in High-Speed Applications:Regional PVC compounders lack validated formulations for airport baggage handling systems above 4 m/s, ceding this margin pool to Swiss and German specialists.
Strategic Opportunities
- Oman and Bahrain Industrial Diversification:Greenfield steel and aluminum smelter investments in Sohar and Alba are creating first-mover windows for belting suppliers with integrated conveyor system capabilities.
- Food Processing Washdown Compliance:Saudi Arabia's industrial cities are generating incremental demand for quick-change splicing and antimicrobial PVC surfaces in poultry and dairy processing lines.
- ESMA Fire-Resistance Mandate Acceleration:Tightening underground mining belt certification timelines are creating specification barriers that favor established suppliers with documented testing regimes and Dubai-based technical service density.
Industry Challenges
- Compound Formulation Talent Scarcity:Gulf polymer engineering programs produce insufficient specialists in elastomer heat-aging and dynamic fatigue modeling, forcing reliance on expatriate technical staff.
- SASO Certification Timeline Compression:Static conductivity and flame-resistance testing queues at Saudi accredited laboratories now extend 14-16 weeks, delaying project commissioning for non-prequalified suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Conveyor Belt Market |
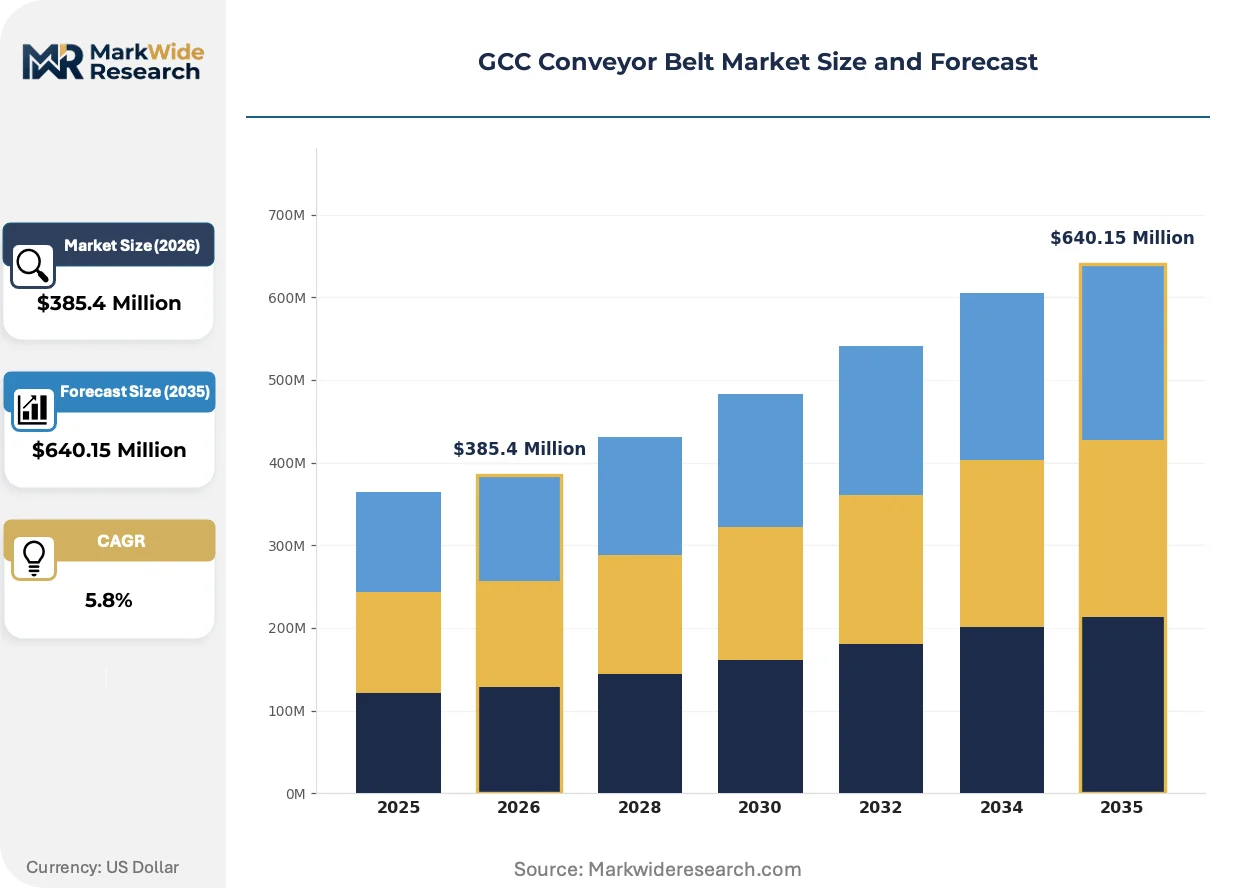
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber, PVC, Modular, Polyester End User: Mining, Agriculture, Manufacturing, Logistics Technology: Heavy-Duty, Light-Duty, High-Speed, Specialty Installation: On-Site, Off-Site, Integrated, Standalone |
| Companies Covered | Habasit Holding AG, Forbo Movement Systems, Continental AG, Phoenix Conveyor Belt Systems, Ammeraal Beltech, Bridgestone Corporation, Yokohama Rubber Co., Ltd., Sempertrans Conveyor Belt Solutions, Fenner Dunlop, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Conveyor Belt Market Strategic Shifts & Innovations
Modular thermoplastic belt designs are fragmenting the traditional rubber-dominated installed base as washdown compliance and quick-change maintenance protocols reshape buyer specifications across food processing and intralogistics verticals.
Sensor-embedded smart belting with RFID tracking and wear-state monitoring is fragmenting the aftermarket service model. Mining operators in Saudi Arabia's Eastern Province are piloting predictive replacement scheduling based on real-time carcass strain data. This capability is compressing the traditional calendar-based maintenance contracting that has dominated Gulf bulk material handling procurement.
ESMA's tightening fire-resistance ratings for underground mining equipment are forcing compound reformulation across all heavy-duty suppliers. The UAE regulator now requires documented flame propagation testing under EN 14973-equivalent protocols for all new installations. Saudi mining clusters are responding by pre-qualifying only those fabricators with accredited Dubai-based testing partnerships, effectively raising the compliance cost barrier for direct imports.
Buyer consolidation around integrated conveyor system procurement is displacing component-level belting contracts. Cement and steel operators in Saudi Arabia now specify complete bulk handling solutions rather than standalone belt replacement. This pattern concentrates volume with full-system vendors and compresses margins for pure-play belting specialists lacking mechanical integration capabilities.
GCC Conveyor Belt Market Segmentation
Conveyor belt segmentation in the GCC reveals how material specifications, duty cycles, and procurement models fragment margin capture across mining extraction, port logistics, and automated distribution. Understanding these fault lines exposes where regional fabricators can defend position against European multinationals and where technology gaps persist.
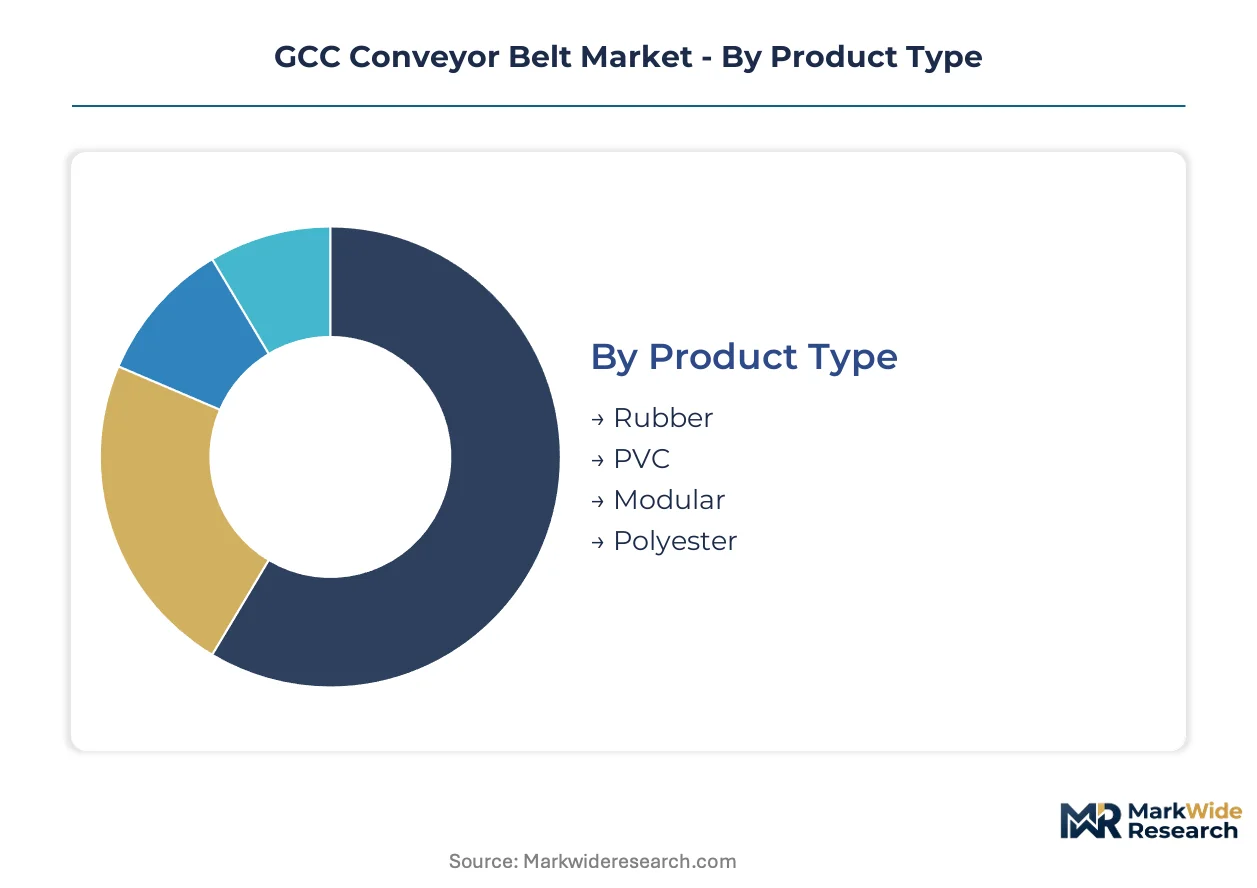
Product Type:
Margin pools concentrate in compound formulations that balance thermal tolerance against splicing labor costs, with reinforcement architecture determining replacement cycle economics.
- Rubber:Steel-cord and fabric-reinforced elastomeric carcasses dominate Eastern Province mining contracts where tensile ratings exceed 3,150 N/mm. Abrasion-resistant compounds command specification priority in Saudi cement clinker handling despite 40% higher unit costs versus standard grades.
- PVC:Thermoplastic formulations with embedded polyester traction layers are displacing rubber in Dubai logistics corridors where washdown compliance and sub-500mm pulley diameters reduce maintenance downtime. ESMA fire-resistance mandates are accelerating certified compound adoption.
- Modular:Interlocking thermoplastic segments enable quick-change maintenance protocols across Saudi poultry processing lines.
- Polyester:Woven synthetic carcasses serve light-duty intralogistics with calibrated elongation characteristics for precision indexing.
Rubber holds installed capacity. PVC is rotating up the share rankings.
End User:
Application intensity varies sharply across extraction, processing, and distribution verticals, with procurement centralization determining contract scale.
- Mining:Bulk material handling at Saudi phosphate and bauxite operations demands heavy-duty steel-cord configurations with SASO-certified static conductivity. Heat-resistant aramid compounds are extending replacement cycles beyond 24 months in Eastern Province clusters.
- Logistics:E-commerce sortation hubs at Dubai South and Jeddah Islamic Port free zones specify high-speed modular PVC with RFID tracking integration. Velocity requirements above 3 m/s are ceding margin to Swiss and German specialists.
- Manufacturing:Steel and aluminum smelters in Sohar and Alba require heat-tolerant carcass materials for slag handling.
- Agriculture:Grain terminals and date processing facilities utilize food-grade PVC with antimicrobial surface treatments.
Mining anchors contract value. Logistics is climbing the fastest.
Technology:
Duty classification separates specification authority between integrated system vendors and component suppliers, with predictive maintenance capabilities reshaping procurement criteria.
- Heavy-Duty:Multi-ply rubber carcasses with impact-resistant top covers serve Saudi mining and aggregate operations where lump size and drop height dictate structural design. Continental AG and Fenner Dunlop retain specification authority through integrated plant contracts.
- High-Speed:Precision-balanced tension members with low-elongation properties enable baggage handling velocities above 4 m/s at Dubai International Airport. Regional compounders lack validated formulations for this specification tier.
- Light-Duty:Reduced-ply constructions address unitized material handling with minimized drive power requirements.
- Specialty:Aramid-reinforced and sensor-embedded configurations target predictive replacement scheduling pilots in Eastern Province mining clusters.
Heavy-Duty retains procurement concentration. Specialty is gaining share fastest.
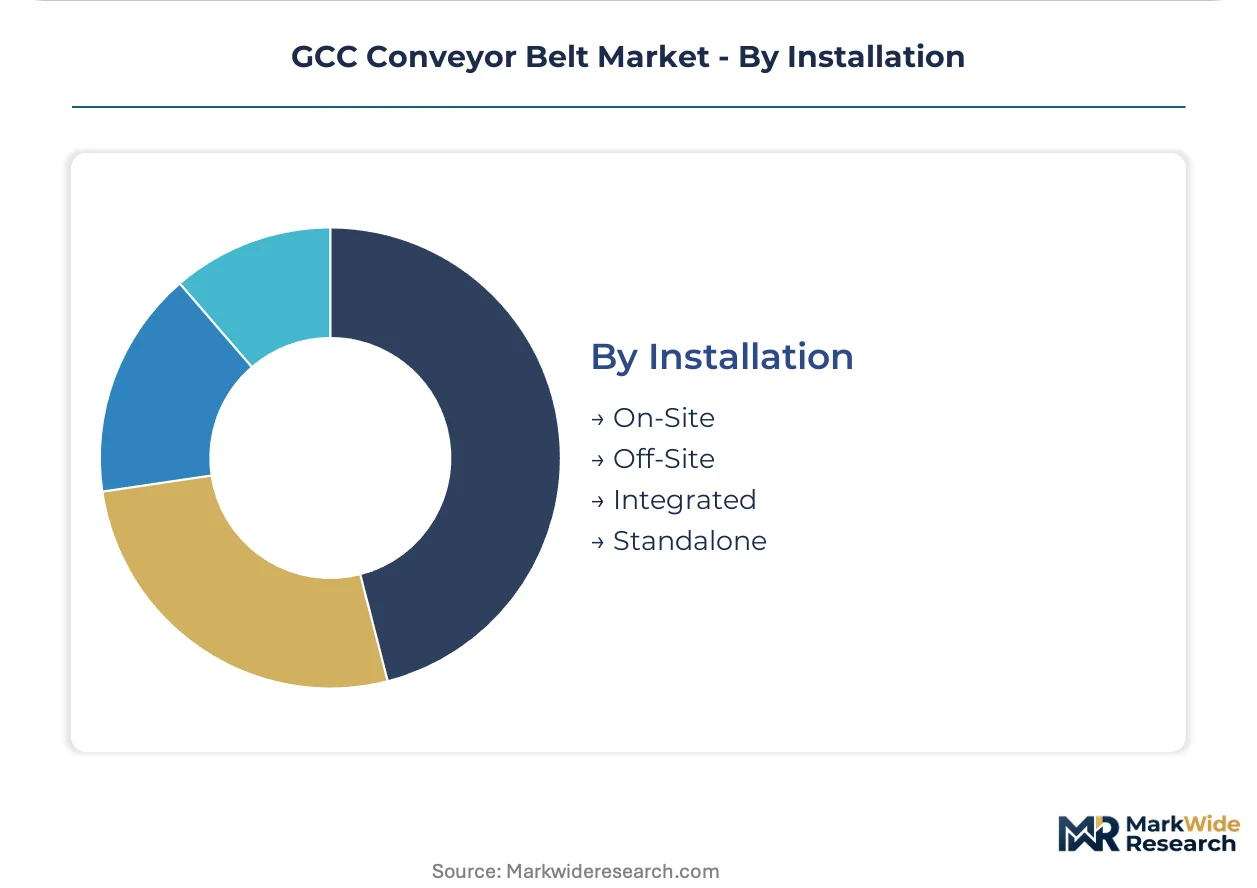
Installation:
Service model selection determines margin retention for regional fabricators versus European multinationals, with localization incentives redirecting contract flows.
- Integrated:Complete bulk handling system procurement now dominates Saudi cement and steel plant contracts, concentrating volume with full-system vendors. Habasit Holding AG competes through mechanical integration capabilities alongside belting supply.
- On-Site:Saudi Vision 2030 domestic value-add requirements are redirecting replacement belting toward regional fabricators with in-country splicing facilities and SASO pre-qualification.
- Off-Site:Pre-fabricated loop manufacturing with hot-vulcanized joints serves standardized port terminal configurations.
- Standalone:Component-level belting contracts persist in maintenance-only procurement with compressed margins.
Integrated commands project value. On-Site is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia consumes heavy-duty rubber configurations for phosphate extraction while the UAE rotates toward modular PVC for logistics automation, creating a product-mix divergence across the Gulf.
Saudi Arabia
Eastern Province mining clusters at Ma'aden phosphate and bauxite operations anchor heavy-duty steel-cord demand with tensile ratings exceeding 3,150 N/mm. SASO mandates static conductivity certification and flame-resistance testing for all underground mining belts, extending supplier qualification timelines to 14-16 weeks. Vision 2030 localization incentives redirect replacement contracts toward Jeddah and Riyadh-based fabricators with in-country splicing capabilities.
United Arab Emirates
Dubai South and Jebel Ali free zones generate high-speed modular PVC demand for e-commerce sortation hubs requiring sub-500mm pulley diameters. ESMA enforces EN 14973-equivalent fire-resistance protocols for all new mining and logistics installations. Abu Dhabi's Khalifa Industrial Zone concentrates steel and aluminum smelter investments where heat-tolerant aramid-reinforced compounds extend replacement cycles beyond 24 months.
Oman
Sohar Port and Freezone greenfield steel investments create first-mover windows for integrated conveyor system suppliers with bulk handling capabilities. The country's national standards body coordinates mining equipment safety mandates with GCC harmonization frameworks. Duqm Special Economic Zone attracts port terminal automation projects specifying pre-fabricated loop manufacturing with hot-vulcanized joints.
Qatar
Ras Laffan Industrial City petrochemical complexes sustain demand for chemical-resistant belting in fertilizer and plastics handling operations. Qatar General Organization for Standardization enforces equipment conformity assessment for all industrial machinery imports. Mesaieed Industrial Area concentrates cement clinker handling where abrasion-resistant compounds command 40% price premiums over standard grades.
Kuwait
Shuaiba Industrial Area refineries and petrochemical plants require heat-tolerant carcass materials for slag and catalyst handling applications. The Public Authority for Industry mandates compliance with Gulf Standardization Organization technical regulations for conveyor equipment. Al-Zour mega-refinery construction drives integrated system procurement rather than component-level belting contracts.
GCC Conveyor Belt Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with premium heavy-duty specification authority concentrating among European multinationals while regional fabricators capture replacement and maintenance volumes. The market structure rewards mechanical integration capabilities alongside compound formulation expertise. Three archetypes dominate: full-system vendors bundling belting with conveyor design, pure-play specialists with deep splicing service networks, and polymer compounders pivoting from rubber to modular thermoplastics. Competitive moves center on technology transfer partnerships with Gulf fabricators and Dubai-based technical service density investments.
Among European-based integrated manufacturers, Continental AG and Habasit Holding AG exemplify contrasting positioning archetypes. Continental anchors premium heavy-duty supply relationships through plant-level integration capabilities. Habasit competes via modular PVC specialization and mechanical integration expertise in logistics corridors. Fenner Dunlop occupies a niche mining position where aramid-reinforced compound expertise commands specification priority in heat-intensive applications.
| Leading Market Players |
|---|
| Habasit Holding AG |
| Forbo Movement Systems |
| Continental AG |
| Phoenix Conveyor Belt Systems |
| Ammeraal Beltech |
| Bridgestone Corporation |
| Yokohama Rubber Co., Ltd. |
| Sempertrans Conveyor Belt Solutions |
| Fenner Dunlop |
| Others |
Cost & Logistics Intelligence
SASO static conductivity certification and ESMA fire-resistance mandates gate both supplier qualification and price differentiation simultaneously, compressing margins for non-prequalified imports while elevating premium tiers for accredited Dubai-based technical service providers. Long-term offtake contracts with fixed-price terms dominate Saudi mining procurement, exposing Gulf fabricators to natural rubber input volatility from Southeast Asian latex markets. Spot purchasing persists in maintenance-only replacement cycles where buyers prioritize immediate availability over compound specification. Price differentiation rests on certification grade and in-country splicing capability, with Vision 2030 localization incentives redirecting volume toward regional fabricators. Cost compression in standard-grade rubber configurations is intensifying because European multinationals retain specification authority in integrated plant contracts. Maintenance procurement teams exhibit highest price sensitivity, while project engineering divisions prioritize heat-tolerant aramid compounds despite 40% unit cost premiums.
Pricing Analysis
Contract structures bifurcate between multi-year offtake agreements for greenfield mining installations and spot procurement for unplanned replacement cycles. Three-tier pricing structure across premium aramid-reinforced, standard steel-cord, and economy fabric-reinforced levels reflects compound formulation complexity and thermal tolerance ratings. Pricing pressure stems from fixed-price contract exposure to natural rubber commodity swings, compressing margin buffers for Gulf fabricators lacking backward integration into polymer compounding. Project engineering divisions at Saudi cement and steel plants show lowest price sensitivity, prioritizing replacement cycle extension over initial capex minimization.
Supply Chain Analysis
Inventory lead times for SASO-certified heavy-duty configurations now extend 14-16 weeks at Saudi accredited laboratories, forcing mining operators to pre-position replacement stock. Geographic supply concentration centers on Germany, Switzerland, and Japan for precision high-speed formulations above 4 m/s, while Thailand and Malaysia anchor natural rubber feedstock. Raw material dependencies encompass aramid fiber from DuPont and Teijin, synthetic rubber from South Korean petrochemical complexes, and PVC resin from Chinese specialty compounders. Single-source vulnerability in aramid-reinforced carcass materials threatens project timelines for Eastern Province mining clusters. Distribution runs through Dubai-based technical service hubs with Jeddah and Riyadh splicing facilities serving Saudi replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance service contracts and sensor-embedded smart belting deployments are expanding faster than hardware replacement cycles, creating recurring revenue layers that compound customer lifetime value. This service-attach dynamic reframes competitive positioning around data-driven replacement scheduling rather than commodity belt supply.
For Market Incumbents: Consolidate specification authority in integrated plant contracts by acquiring mechanical integration capabilities alongside compound formulation expertise. SASO certification timeline compression threatens market access for non-prequalified suppliers, creating defensive moats for established players with accredited Dubai-based testing partnerships. Capacity addition in Jeddah and Riyadh splicing facilities captures Vision 2030 localization incentives redirecting replacement volume.
For New Entrants and Emerging Players: ESMA fire-resistance fast-track partnerships with Dubai-based accredited laboratories enable qualification timeline compression against established competitors. Food processing washdown compliance in Saudi Arabia's industrial cities represents the most penetrable white-space, with poultry and dairy lines generating incremental demand for antimicrobial PVC surfaces and quick-change splicing protocols. Go-to-market positioning should emphasize modular thermoplastic specialization with sub-500mm pulley diameter configurations for logistics corridor penetration.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fabricators possessing in-country splicing networks but lacking integrated system capabilities, creating platform consolidation opportunities. Long-term viability over a 5-10 year window hinges on mechanical integration expertise as buyer procurement shifts from component-level belting to complete bulk handling solutions. The signal to watch is predictive maintenance contract penetration rates in Eastern Province mining clusters, indicating smart belting adoption velocity and service-attach revenue maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive aramid-reinforced formulation capability reduces exposure to Southeast Asian natural rubber volatility. |
| Dubai-Based Technical Service Density Expansion | ESMA certification proximity accelerates qualification timelines for UAE and Saudi mining procurement. |
| Smart Belting Sensor Partnership | RFID tracking and wear-state monitoring integration enables predictive replacement scheduling pilots. |
| Joint Venture with Regional Fabricator | Vision 2030 domestic value-add requirements redirect contracts toward Jeddah and Riyadh splicing facilities. |
| Modular Thermoplastic Product Line Launch | Quick-change splicing protocols address food processing washdown compliance in Saudi industrial cities. |
Research Approach
A spread of perspectives from plant maintenance directors, mining procurement leads, conveyor system OEMs, and aftermarket service heads converged on the working assumptions shaping demand projections. Primary interviews with bulk material handling operators across Saudi Arabia's Eastern Province and UAE logistics free zones combined with secondary validation from customs trade data, SASO certification registries, SEC filings of listed belting manufacturers, and GCC national standards body technical regulations. Bottom-up sizing of replacement cycles and top-down cross-check against cement, steel, and mining capacity expansion announcements established volume anchors.
Segmentation dimensions modeled encompass product type, end-user vertical, duty classification technology tier, and installation service model across the projection horizon. CAGRs were derived from regression analysis of historical replacement rates against capacity utilization and thermal loading intensity. Industry-specific forecast inputs incorporated aramid-reinforced compound adoption curves in Eastern Province clusters and modular PVC penetration rates in Dubai South e-commerce sortation hubs.
The analysis sits within stated boundaries; outcomes outside sustained mining investment execution or logistics automation deployment would require recalibration. Forecasts reflect assumptions around SASO certification timeline stability and natural rubber commodity price bands. Supply chain disruption from aramid fiber concentration or ESMA mandate acceleration represents specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Fasteners Market
Material Handling Equipment
Light Duty Telehandler Market
Material Handling Equipment
Global Lifting Columns Market
Material Handling Equipment
Gas Connectors and Gas Hoses Market
Material Handling Equipment
Cam and Groove Fittings Market
Material Handling Equipment
Stacker Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Global Elevator Market
Material Handling Equipment
Brazil Forklift Market
Material Handling Equipment
Air Hoist Market
Material Handling Equipment
Bridge Cable Sockets Market
Material Handling Equipment
Centrifugal Industrial Dryer Market
Material Handling Equipment
Global Metal Shredder Machine Market
Material Handling Equipment
Hose Pump Market
Material Handling Equipment
Pick and Carry (PNC) Crane Market
Material Handling Equipment
Debris Loaders Market