
 Water Hose Market | 2026-2036
Water Hose Market Size, Share, and Industry Trends Forecast 2026-2036
Water Hose Market Analytics
Multi-source procurement for reinforced elastomer compounds is shifting toward vertically integrated compounders with captive polymer capacity. Parker Hannifin Corporation leverages its materials science division to control nitrile and EPDM supply chains from monomer to finished hose. Gates Corporation anchors North American distribution through captive dealer networks serving agricultural OEMs. Continental AG competes on co-extrusion expertise, producing multi-layer constructions that sustain pressure ratings across temperature extremes.
A water hose is a flexible conduit, typically constructed from rubber, PVC, polyurethane, or vinyl reinforced with textile braids or wire helixes, designed to convey fluids under pressure or vacuum across distances where rigid piping is impractical. Garden hose products dominate residential volume but carry thin margins due to commoditization and retail channel concentration. Pressure hose applications in construction and mining equipment represent the fastest-growing segment, driven by hydraulic system pressure ratings that now routinely exceed 3000 PSI. Agricultural suction hoses for irrigation and manure handling occupy a stable mid-tier position where polyurethane formulations command premium pricing over PVC alternatives due to abrasion resistance and kink recovery.
EPA regulations under the Safe Drinking Water Act restrict lead content and phthalate migration in hoses designated for potable water contact, forcing reformulation of PVC compounds across domestic manufacturers. REACH compliance in Europe mandates substitution of certain plasticizers and flame retardants, elevating testing costs for exporters serving EU industrial customers. OSHA workplace safety standards govern pressure testing protocols and burst rating verification for hoses deployed in commercial and industrial settings. Stakeholders must monitor evolving chemical restrictions across multiple jurisdictions while assessing whether backward integration into polymer compounding justifies capital deployment against specialized compounder partnerships.
Market Dynamics
EPA and REACH compliance deadlines are forcing simultaneous reformulation across PVC, EPDM, and nitrile compounds, compressing product development cycles while elevating testing expenditures for manufacturers serving multiple jurisdictions.
Growth Catalysts
- Smart Irrigation Mandates:California's SGMA groundwater regulations and similar frameworks in Spain and Australia are accelerating replacement of leaky aluminum pipe with flexible suction hose in agricultural districts.
- REACH Substitution Deadlines:ECHA restrictions on phthalate plasticizers and short-chain chlorinated paraffins are pulling demand toward bio-based polyurethane formulations in EU industrial fluid handling.
- EPDM Capacity Expansion:Captive polymer production at integrated compounders is stabilizing raw material costs for reinforced hose manufacturers serving construction equipment OEMs.
Market Restraints
- Crude-Derived Input Volatility:Naphtha and propylene costs for synthetic rubber production swing with energy markets, squeezing margin predictability at mid-tier extruders.
- Chinese PVC Concentration:Sixty percent of global resin capacity sits in Shandong and Xinjiang provinces, exposing downstream hose fabricators to logistics disruptions and tariff exposure.
- Metal Hose Substitution:Corrugated stainless steel assemblies are capturing share in high-pressure hydraulic applications above 4000 PSI where rubber fatigue limits performance.
Strategic Opportunities
- India Agricultural Modernization:PM-KUSUM solar pump subsidies and micro-irrigation expansion in Gujarat and Maharashtra are creating pull for UV-stabilized PVC lay-flat hose.
- Per- and Polyfluoroalkyl Substance Bans:EPA PFAS restrictions and EU POPs Regulation are opening formulation space for silicone and TPV alternatives in potable water contact applications.
- Direct-to-Farm E-Commerce:Amazon Business and specialized ag-tech platforms are disintermediating traditional irrigation distributors in the US Corn Belt and Australian wheat belts.
Industry Challenges
- Compound Formulation Expertise Gap:Retiring polymer chemists at legacy manufacturers are creating knowledge vacuums in EPDM-peroxide curing systems and co-extrusion die design.
- Multi-Jurisdiction Certification Timelines:NSF/ANSI 61 potable water approval, WRAS certification for UK markets, and AS/NZS 4020 testing for Australia require eighteen-to-twenty-four-month validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Hose Market |
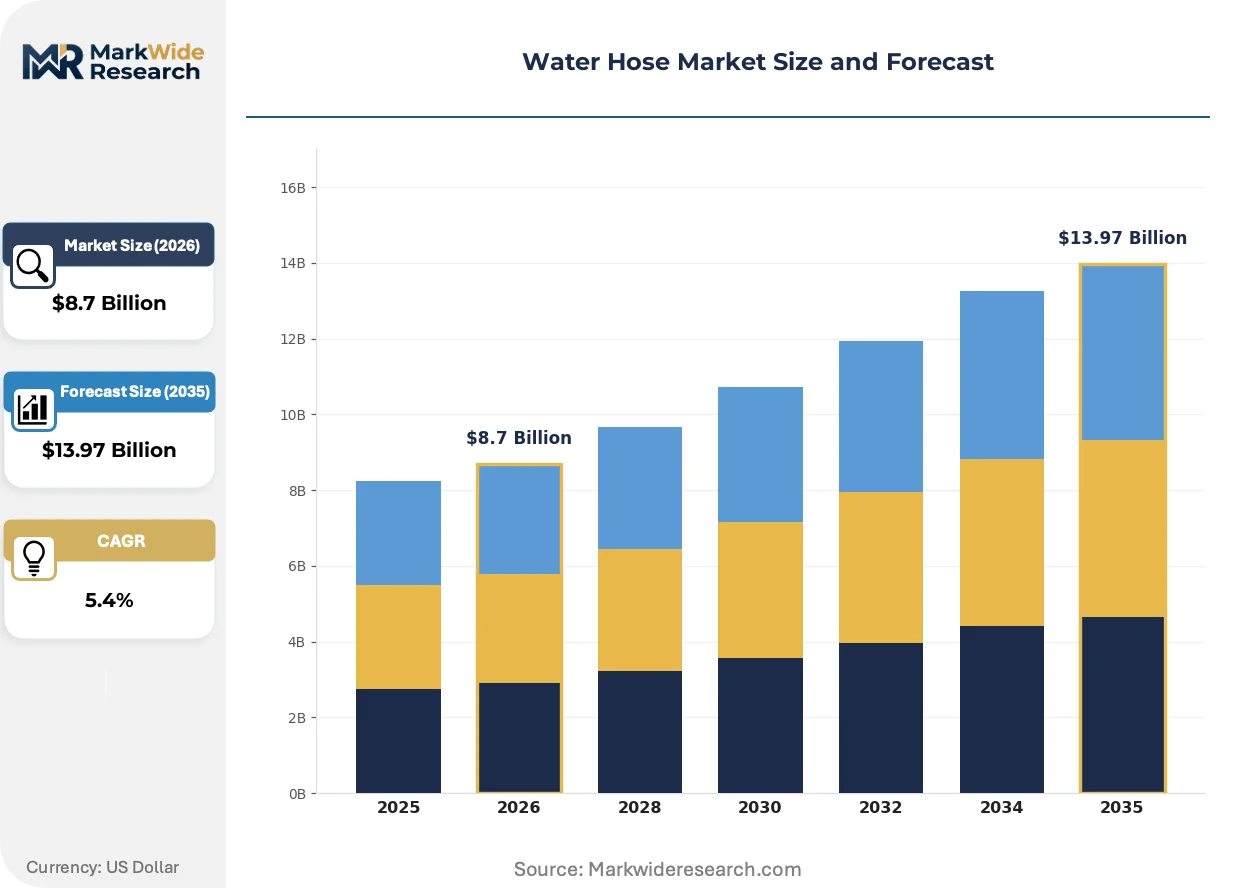
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Garden Hose, Pressure Hose, Suction Hose, Recoil Hose Material: Rubber, PVC, Polyurethane, Vinyl Usage: Residential, Commercial, Agricultural, Industrial Diameter: 1/4 Inch, 1/2 Inch, 3/4 Inch, 1 Inch |
| Companies Covered | Parker Hannifin Corporation, Eaton Corporation, Gates Corporation, Continental AG, Trelleborg AB, Kuriyama of America, Inc., Manuli Hydraulics, Saint-Gobain Performance Plastics, Yokohama Rubber Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Hose Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to reshape compound selection, manufacturing processes, and distribution architectures across industrial and consumer hose segments.
Thermoplastic vulcanizate formulations are replacing traditional EPDM rubber in medium-pressure agricultural and construction applications. Equipment OEMs in Germany and the US Midwest are specifying TPV for its weight reduction and color-coding flexibility. This material transition is decentralizing compound supply relationships away from petrochemical majors toward specialized polymer blenders with rapid formulation capabilities.
EPA's finalized lead-free certification requirements under the Safe Drinking Water Act are tightening allowable lead content in brass fittings and stabilizer packages. Domestic manufacturers must reformulate PVC compounds and source alternative heat stabilizers, driving testing costs upward. Garden hose and RV water hose segments in the United States are absorbing the bulk of compliance expenditure and inventory write-downs.
Large agricultural cooperatives and municipal water districts are consolidating purchasing through integrated supply contracts that bundle hose, fittings, and installation services. Traditional distribution through independent irrigation dealers is contracting in the US Great Plains and Australian Murray-Darling basin. This procurement consolidation is compressing supplier margins while favoring manufacturers with captive installation capabilities or regional service depots.
Water Hose Market Segmentation
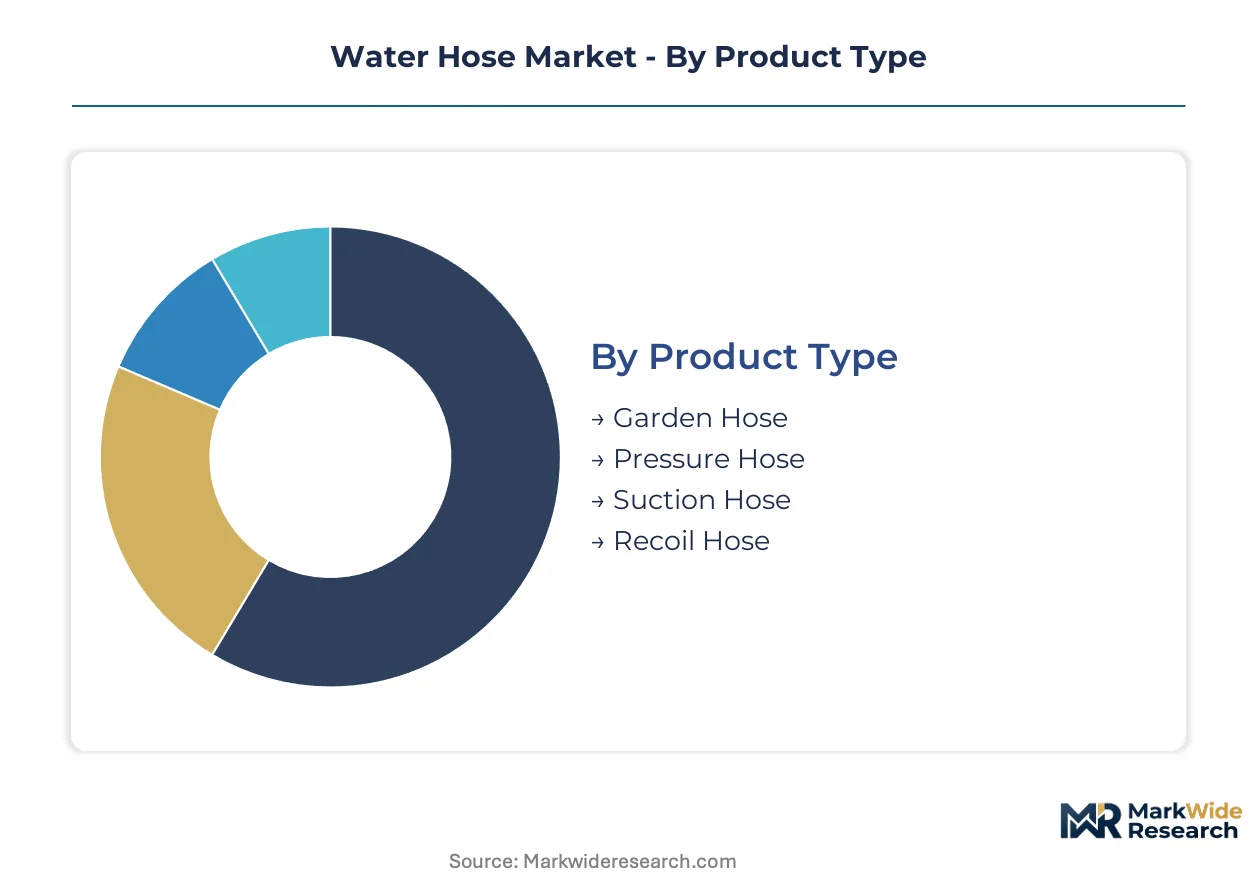
Water hose segmentation reflects divergent performance specifications across pressure ratings, chemical compatibility, and duty cycles. Material selection and diameter sizing determine application boundaries, while end-use differentiation drives pricing architecture and channel strategy.
Product Type:
Pressure rating and reinforcement architecture separate product categories across residential, commercial, and heavy-duty deployments.
- Pressure Hose:Multi-layer constructions with wire braiding or spiral reinforcement sustain hydraulic system demands exceeding 3000 PSI in construction and mining equipment. OEM specifications from German and US Midwest manufacturers are pulling demand toward thermoplastic vulcanizate formulations for weight reduction and color-coded fluid identification.
- Suction Hose:Rigid helix wire embedded between compound layers prevents collapse under vacuum conditions during agricultural manure handling and dewatering operations. Polyurethane formulations command premium positioning over PVC in Australia's Murray-Darling basin and India's Gujarat irrigation districts where abrasion resistance and kink recovery justify higher unit economics.
- Garden Hose:Light-duty PVC or vinyl constructions dominate residential volume through retail concentration, though EPA lead-free certification requirements under the Safe Drinking Water Act are forcing reformulation of legacy compounds.
- Recoil Hose:Spiral memory retains compact storage geometry for pneumatic tools and mobile pressure washing equipment in commercial maintenance applications.
Mature deployment sits with garden hose products. Newer deployment is concentrated in pressure hose applications.
Material:
Compound selection balances chemical resistance, temperature tolerance, and regulatory compliance across potable water and industrial fluid contact.
- Rubber:EPDM and nitrile formulations deliver superior ozone and petroleum resistance for agricultural and construction equipment OEMs. Captive polymer production at integrated compounders is stabilizing input costs for reinforced hose manufacturers.
- Polyurethane:Cast or extruded ether-based grades offer exceptional abrasion resistance and flex fatigue life, expanding most quickly in mining slurry handling and robotic cable protection where service intervals determine total cost of ownership.
- PVC:Plasticized formulations face REACH substitution deadlines for phthalate plasticizers and short-chain chlorinated paraffins, elevating testing expenditures for EU market access.
- Vinyl:Lower-specification compounds retain position in price-sensitive consumer segments despite thinner margins and retail channel consolidation.
EPDM rubber anchors industrial specification. Polyurethane is gaining share fastest in abrasion-critical deployments.
Usage:
End-use differentiation determines certification requirements, distribution architecture, and service attachment opportunities.
- Agricultural:Flexible suction and lay-flat hose for irrigation, manure handling, and chemical transfer. California SGMA groundwater regulations and India's PM-KUSUM solar pump subsidies are accelerating replacement of legacy aluminum pipe infrastructure.
- Industrial:Pressure hose for hydraulic systems, chemical transfer, and compressed air in manufacturing and process industries. OSHA workplace safety standards govern pressure testing protocols and burst rating verification.
- Residential:Garden hose and RV water hose segments absorb the bulk of EPA lead-free compliance expenditure and inventory write-downs.
- Commercial:Pressure washing, facility maintenance, and food service applications requiring NSF/ANSI 61 potable water approval.
Residential usage carries highest volume concentration. Agricultural usage is climbing the fastest on infrastructure replacement cycles.
Diameter:
Internal dimension determines flow capacity, pressure drop characteristics, and compatibility with standardized fitting systems.
- 3/4 Inch:Standard residential garden hose dimension balancing flow rate with handling convenience. Inventory concentration at North American retail chains.
- 1/2 Inch:Common specification for light-duty pressure washing and pneumatic tool supply in commercial maintenance.
- 1 Inch:Agricultural suction and discharge applications requiring higher volume transfer with moderate pressure tolerance.
- 1/4 Inch:Precision hydraulic lines and instrumentation tubing in industrial equipment where space constraints dominate.
3/4 inch diameter anchors consumer market standardization. 1 inch diameter is expanding most quickly on agricultural modernization investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, China, and Germany where industrial fluid handling investments remain elevated. Agricultural irrigation upgrades and construction equipment specifications drive procurement across these markets. Regulatory compliance timelines in each jurisdiction compress product development cycles for exporters.
United States
California's SGMA groundwater regulations and EPA lead-free certification requirements under the Safe Drinking Water Act accelerate replacement of legacy aluminum pipe infrastructure. The US Corn Belt sees direct-to-farm e-commerce platforms disintermediating traditional irrigation distributors. Parker Hannifin Corporation anchors North American supply chains through captive polymer capacity.
China
Sixty percent of global PVC resin capacity sits in Shandong and Xinjiang provinces, exposing downstream fabricators to logistics disruptions. Construction equipment OEMs in the Yangtze River Delta specify thermoplastic vulcanizate formulations for weight reduction. REACH compliance testing elevates costs for exporters serving EU industrial customers.
Germany
REACH substitution deadlines for phthalate plasticizers pull demand toward bio-based polyurethane formulations in EU industrial fluid handling. Continental AG competes on co-extrusion expertise from its manufacturing base. Equipment OEMs specify multi-layer constructions that sustain pressure ratings across temperature extremes.
India
PM-KUSUM solar pump subsidies and micro-irrigation expansion in Gujarat and Maharashtra create pull for UV-stabilized PVC lay-flat hose. BIS certification requirements govern potable water contact applications. Agricultural cooperatives consolidate purchasing through integrated supply contracts bundling hose, fittings, and installation services.
Australia
Murray-Darling basin irrigation districts specify polyurethane suction hose for abrasion resistance and kink recovery. AS/NZS 4020 testing requires eighteen-to-twenty-four-month validation cycles for potable water approval. Large agricultural cooperatives displace independent irrigation dealers through volume procurement consolidation.
Water Hose Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated compounders stabilize raw material costs through captive polymer production. The vendor base separates into three tiers: multinational diversified industrials with materials science divisions, specialized hose fabricators with regional service networks, and commodity extruders serving price-sensitive consumer segments. Two competitive moves define positioning: backward integration into polymer compounding and geographic expansion through captive dealer networks.
Among diversified industrial conglomerates, Parker Hannifin Corporation and Eaton Corporation exemplify the materials science-driven archetype with upstream control over nitrile and EPDM supply chains. Gates Corporation represents the distribution-anchored model through North American dealer networks serving agricultural OEMs. Continental AG occupies a position within the co-extrusion specialization tier, producing multi-layer constructions for pressure-critical applications.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Eaton Corporation |
| Gates Corporation |
| Continental AG |
| Trelleborg AB |
| Kuriyama of America, Inc. |
| Manuli Hydraulics |
| Saint-Gobain Performance Plastics |
| Yokohama Rubber Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Captive polymer production at integrated compounders anchors both supply security and pricing power across reinforced hose tiers. Parker Hannifin and Gates Corporation leverage in-house nitrile and EPDM capacity to buffer margin volatility while mid-tier extruders absorb cost swings from spot resin markets. This integration choice separates manufacturers who dictate terms from those who follow commodity cycles.
Pricing Analysis
Warranty and service bundling separates premium industrial contracts from unbundled consumer transactions. Three-tier pricing structure across premium, standard, and economy levels reflects pressure rating certification and NSF/ANSI 61 potable water approval status. Cost compression in garden hose retail channels is intensifying because EPA lead-free compliance forced legacy inventory write-downs. Agricultural cooperatives show lowest price sensitivity due to total cost-of-ownership calculations, while residential buyers concentrate volume at big-box price points.
Supply Chain Analysis
Synthetic rubber feedstock rests on naphtha and propylene streams tethered to energy market volatility in the United States, Germany, and China. PVC resin draws from concentrated capacity in Shandong and Xinjiang provinces, while EPDM polymer hinges on ethylene-propylene diene monomer supply from integrated petrochemical complexes. Single-source vulnerability sits with Chinese resin concentration exposing fabricators to logistics disruptions and tariff exposure. Distribution runs through captive dealer networks for agricultural OEMs and retail chains for residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is compressing margins for non-integrated players as captive polymer production becomes the cost-control imperative. Backward integration into EPDM compounding offers the decisive upstream lever for sustainable margin defense.
For Market Incumbents: Cement polymer supply security through captive production or long-term offtake agreements with specialized compounders. Metal hose substitution above 4000 PSI threatens rubber fatigue-limited applications, demanding co-extrusion expertise investment in multi-layer thermoplastic constructions. Channel control through regional service depots defends agricultural cooperative contracts against direct-to-farm e-commerce disintermediation. For New Entrants and Emerging Players: Direct-to-farm e-commerce platforms offer the most penetrable route for bypassing established irrigation dealer networks in the US Corn Belt and Australian wheat belts. UV-stabilized PVC lay-flat hose for India's PM-KUSUM solar pump expansion represents underserved white-space. Specialty polyurethane formulations for abrasion-critical mining slurry handling command premium positioning with lower certification barriers than potable water segments. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking materials science capabilities. The five-to-ten-year viability window favors targets with captive polymer production and regional service infrastructure over pure-play extruders. Acquisition target archetype: mid-tier compounders with rapid TPV formulation capabilities and existing REACH compliance testing infrastructure. Watch EPA PFAS restriction implementation timelines as inflection indicator for silicone and TPV alternative demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive EPDM production stabilizes input costs for construction equipment OEM supply contracts. |
| REACH Compliance Testing Infrastructure | EU market access requires eighteen-month validation cycles that specialized laboratories can monetize. |
| Direct-to-Farm E-Commerce Platform Launch | Amazon Business and ag-tech platforms disintermediate traditional irrigation distributors in grain belt states. |
| TPV Formulation Capability Expansion | Thermoplastic vulcanizate replaces EPDM rubber for weight reduction in German equipment specifications. |
| Regional Service Depot Network | Installation bundling secures agricultural cooperative contracts against price-only competitors. |
Research Methodology
Trade association databases, customs filings, and SEC 10-K disclosures formed the secondary backbone for market sizing validation. Primary interviews with plant engineers at agricultural equipment OEMs, procurement leads at municipal water districts, polymer chemists at compounder facilities, and aftermarket service heads at regional distributors combined with secondary triangulation. Bottom-up unit economics and top-down industrial production indices were reconciled across the analysis window.
Bottom-up modeling tracked pressure rating tiers, material compound classes, and end-use certification requirements throughout the forecast period. Top-down validation drew from agricultural machinery production data, construction equipment shipment reports, and irrigation infrastructure investment disclosures. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Key inputs included EPA regulatory timeline assumptions and ECHA substitution deadline enforcement patterns.
The model holds under steady regulatory enforcement timelines; deviation in PFAS restriction acceleration or REACH scope expansion would shift compound substitution trajectories. Forecasts reflect documented assumptions on raw material cost pass-through rates and agricultural modernization subsidy continuity. A small set of named triggers warrants ongoing watch: Chinese PVC logistics disruptions, EPDM capacity expansion completion, and direct-to-farm platform penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Forklift Rental Market
Material Handling Equipment
Steel Coil Handling Equipment Market
Material Handling Equipment
Industrial Parts Feeders Market
Material Handling Equipment
United States Automated Material Handling Market
Material Handling Equipment
Rough Terrain Lift Truck Market
Material Handling Equipment
Material Handling Monorails Market
Material Handling Equipment
Industrial Carts Market
Material Handling Equipment
Lump Breaker Machines Market
Material Handling Equipment
Latin America Conveyors Market
Material Handling Equipment
Tube Rotator Market
Material Handling Equipment
Global Hopper Loader Market
Material Handling Equipment
Froth Flotation Equipment Market
Material Handling Equipment
Belt Weigh Feeder Market
Material Handling Equipment
Torque Limiting Couplings Market
Material Handling Equipment
Electric Hoist Market