
 Global Conveyors Market | 2026-2036
Global Conveyors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Conveyors Market Analysis
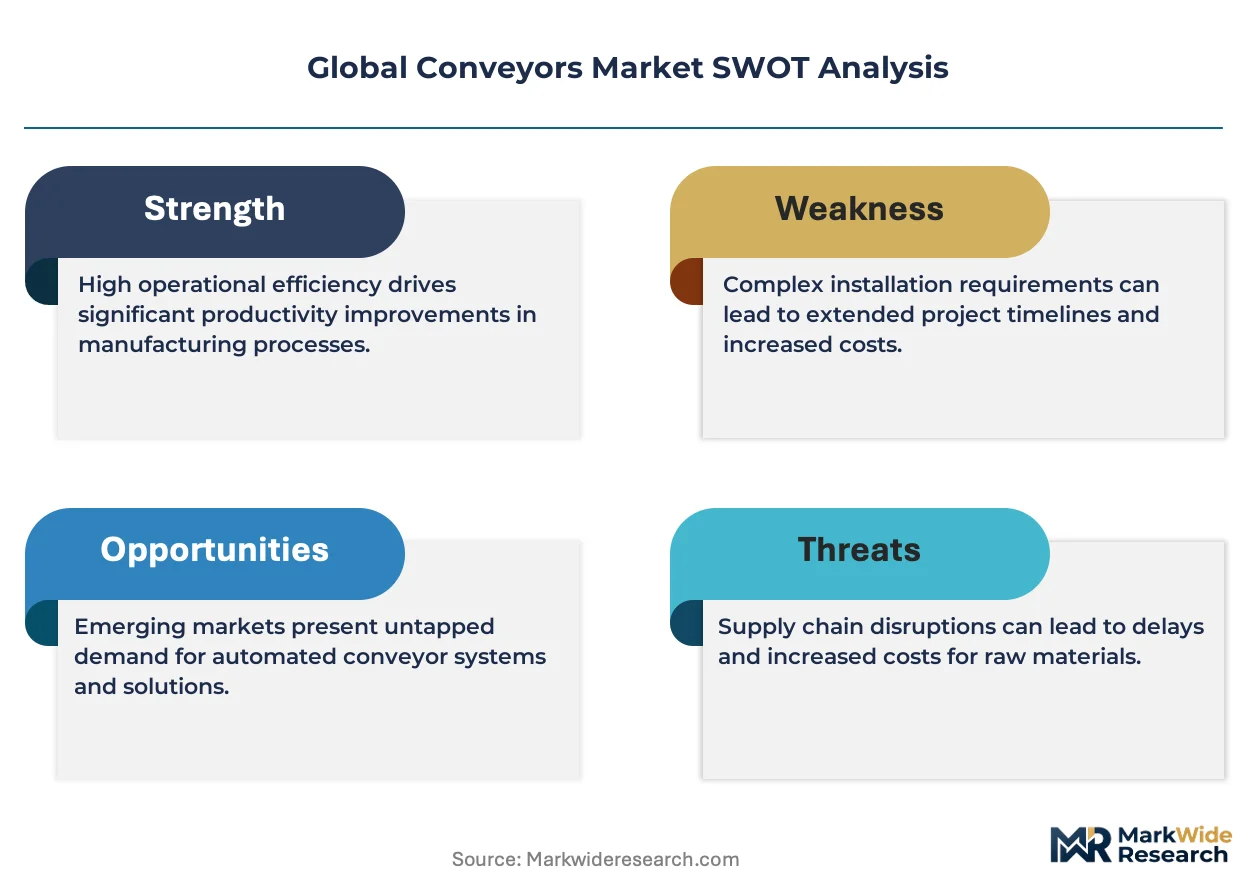
A widening capital-intensity gap between automated-system vendors and conventional equipment suppliers is rotating competitive advantage toward technology-heavy portfolios. Daifuku Co., Ltd. leverages its integrated material-handling software stack to anchor large-scale airport and factory automation contracts. Continental AG sustains dominance in heavy-duty belt systems through captive rubber-compounding operations and mining-sector relationships. Siemens AG competes by embedding IoT diagnostics directly into drive controllers, creating recurring service revenue streams.
Conveyors are continuous mechanical handling devices designed to move materials along a predetermined path, typically employing belts, rollers, chains, or slats driven by electric motors with load capacities ranging from kilograms to thousands of tons per hour. Their primary purpose is eliminating manual transport bottlenecks in high-throughput environments where speed, repeatability, and labor cost reduction determine operational economics. Belt conveyors occupy the largest installed base due to versatility across bulk and unit-load applications, though roller conveyors are capturing faster growth in last-mile distribution centers where gentle handling of variable package sizes matters. Automated technology segments command premium pricing over manual and hybrid alternatives because integration with warehouse management systems reduces picking errors and labor dependency.
The EU Machinery Directive and CE marking framework mandate exhaustive risk assessments and documented safety controls for conveyor installations sold across member states, effectively raising engineering costs for non-compliant Asian exporters. The US Occupational Safety and Health Administration enforces specific guarding standards around nip points and emergency stop placements, driving replacement demand as older systems fail retrofit audits. Japan's Ministry of Economy, Trade and Industry promotes JIS-certified energy-efficient motors through subsidy programs, indirectly favoring conveyor upgrades with variable-frequency drives. Stakeholders must monitor how impending EU battery-regulation supply-chain disclosure rules affect conveyor-dependent electric-vehicle gigafactory buildouts.
Market Dynamics
Automated sortation systems are compressing order fulfillment cycles in e-commerce warehouses, forcing conventional belt manufacturers to absorb control-software capabilities or surrender high-margin contracts to integrated automation vendors.
Growth Catalysts
- E-commerce fulfillment velocity:Same-day delivery mandates from retail platforms are accelerating deployment of high-speed sortation conveyors in distribution centers.
- EU Machinery Directive compliance:CE marking requirements for documented risk assessments are filtering out low-cost Asian exporters and consolidating contract awards to certified European suppliers.
- Automotive assembly modernization:German OEMs are replacing legacy chain conveyors with flexible pallet-based systems to accommodate electric-vehicle platform variations.
Market Restraints
- Steel and aluminum input volatility:Roller conveyor frames and belt support structures face margin compression from commodity price swings.
- Drive component supply concentration:Precision gearmotors and variable-frequency drives rely heavily on German and Japanese suppliers, creating single-source vulnerability.
- Manual handling substitution limits:Fragile or irregularly shaped goods in fresh produce and custom manufacturing resist full conveyor automation.
Strategic Opportunities
- India warehousing infrastructure:Cold chain expansion and organized retail growth are creating first-mover advantages for modular conveyor installations.
- Battery gigafactory buildouts:Electric-vehicle cell production lines require cleanroom-compatible conveyors with electrostatic discharge protection.
- Japan METI energy-efficiency subsidies:JIS-certified motor upgrades are subsidizing conveyor retrofits with regenerative drive systems.
Industry Challenges
- Mechatronics engineering scarcity:Integration of servo drives, PLCs, and vision systems demands cross-trained technicians that vocational programs are not producing at scale.
- Legacy system interoperability:Brownfield sites running decades-old relay-logic controls resist seamless integration with IoT-enabled conveyor segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Conveyors Market |
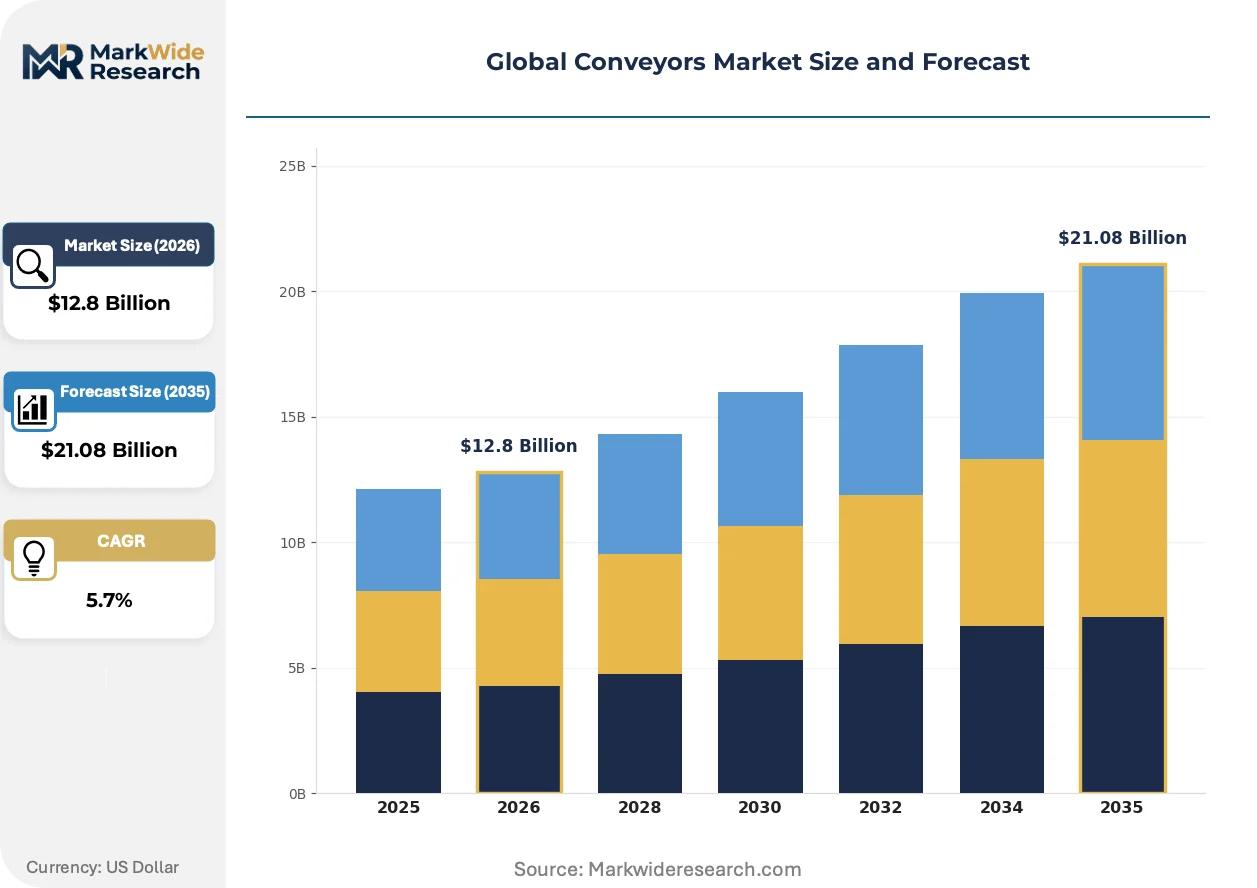
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belt Conveyors, Roller Conveyors, Chain Conveyors, Slat Conveyors Technology: Automated, Manual, Hybrid, Pneumatic End User: Manufacturing, Retail, Food & Beverage, Pharmaceuticals Application: Packaging, Assembly, Distribution, Warehousing |
| Companies Covered | Daifuku Co., Ltd., Continental AG, Fives Group, BEUMER Group, Siemens AG, Murata Machinery, Ltd., Interroll Group, Intralox, Dürr Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Conveyors Market Emerging Trajectories
Conveyor architectures are fragmenting between commodity bulk-handling equipment and intelligent material-handling platforms, with software-defined routing and predictive maintenance becoming the primary value differentiators.
Collaborative mobile robots equipped with conveyor tops are bifurcating warehouse automation strategies. Retail fulfillment centers in the United States are deploying these units for zone-to-zone transport. The technology is compressing the addressable market for fixed roller conveyors in facilities under 500,000 square feet.
REACH substance restrictions on perfluorinated compounds are compelling belt manufacturers to reformulate friction coatings. Suppliers serving the European market are accelerating validation of bio-based polyurethane alternatives. Food-contact conveyor segments face the steepest reformulation timelines.
Buyer consolidation among third-party logistics providers is compressing vendor qualification cycles. Large contract holders are unbundling installation and maintenance from equipment purchase, forcing manufacturers to compete on lifecycle service metrics. This pattern is most pronounced in German automotive supplier parks and Dutch port-centric distribution hubs.
Global Conveyors Market Segmentation
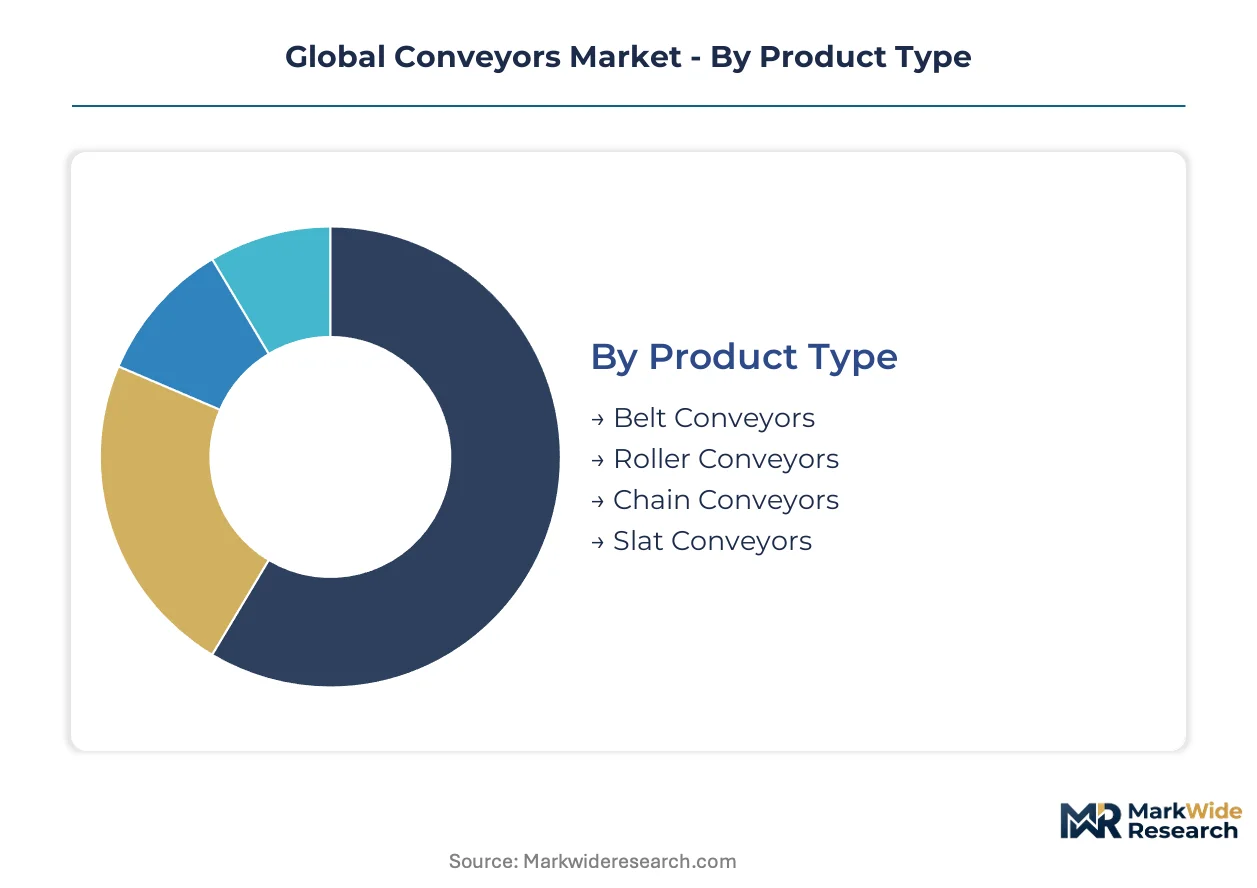
Segmentation in the conveyors market reveals how regulatory compliance, automation intensity, and end-use throughput requirements fragment purchasing behavior. Buyers select configurations based on CE marking obligations, cleanroom specifications, or e-commerce velocity mandates rather than generic mechanical performance.
Product Type:
CE marking requirements under the EU Machinery Directive impose divergent engineering costs across structural formats, favoring suppliers with documented risk assessment capabilities for cross-border sales.
- Belt Conveyors:Continuous fabric or rubber belts running over pulleys handle bulk materials and unit loads across variable inclines. German automotive OEMs specify modular belt systems for EV assembly lines where platform flexibility reduces retooling downtime.
- Roller Conveyors:Cylindrical rollers mounted on frames enable gravity-driven or powered transport of rigid containers. US e-commerce fulfillment centers deploy these for last-mile sortation where gentle handling of irregular package dimensions reduces damage claims.
- Chain Conveyors:Metal link chains withstand heavy loads and high temperatures in forging and foundry operations.
- Slat Conveyors:Rigid slats mounted on chains transport hot or sharp-edged materials where belt damage would halt production.
Belt conveyors handle the majority of throughput; roller conveyors are the fastest mover on share.
Technology:
Capital deployment intensity separates procurement tiers, with automated systems commanding premium pricing against manual alternatives due to warehouse management system integration requirements.
- Automated:Servo-driven conveyors with PLC control and vision-based sortation integrate directly with WMS platforms. Japanese METI energy-efficiency subsidies accelerate retrofit demand for regenerative drive configurations in domestic distribution centers.
- Manual:Gravity or hand-cranked rollers serve low-throughput operations where labor costs remain below automation breakeven thresholds. Indian cold chain warehouses deploy these for seasonal agricultural handling where capital constraints limit upfront investment.
- Hybrid:Segmented lines combine automated high-speed zones with manual loading stations for mixed-sku environments.
- Pneumatic:Vacuum or pressure-driven tube systems transport small parts or documents in cleanroom pharmaceutical operations.
Automated technology captures the steepest expansion trajectory as labor costs climb across developed economies; manual systems retain footholds in emerging market infrastructure buildouts.
End User:
Industry-specific contamination and safety standards dictate material selection and guarding architecture, fragmenting vendor qualification criteria.
- Manufacturing:Assembly line conveyors synchronize with robotic workcells and quality inspection stations. German supplier parks demand TÜV-certified emergency stop systems and documented mean-time-between-failure metrics for automotive tier-one contracts.
- Retail:High-velocity sortation systems process omnichannel returns and seasonal demand spikes. Dutch port-centric distribution hubs unbundle installation from equipment purchase, forcing lifecycle service competition.
- Food & Beverage:Stainless steel construction and washdown-rated motors satisfy FDA and EU hygiene mandates for direct product contact.
- Pharmaceuticals:Cleanroom-compatible designs with electrostatic discharge protection serve cell therapy and vaccine manufacturing.
Manufacturing absorbs the largest equipment volume; retail is climbing fastest on e-commerce fulfillment investment.
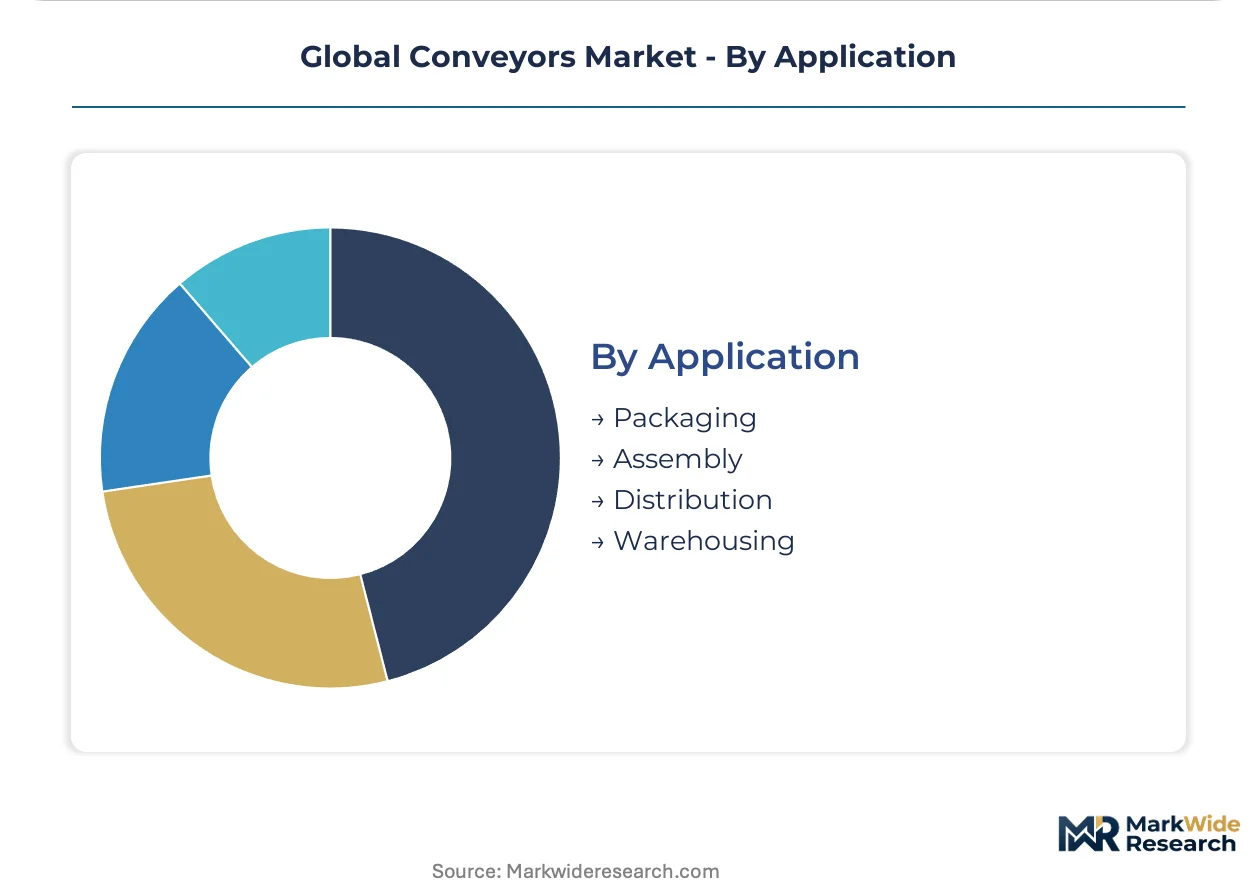
Application:
Operational tempo and error tolerance define specification priorities, with packaging lines demanding gentler handling than assembly or bulk distribution.
- Packaging:Accumulation conveyors buffer product flow between filling and sealing stations. REACH substance restrictions on perfluorinated compounds compel belt reformulation for European food-contact applications.
- Assembly:Pallet-based conveyor systems index workpieces through sequential operations. US OSHA guarding standards around nip points drive replacement demand where legacy systems fail retrofit audits.
- Distribution:High-speed sortation conveyors route parcels to shipping lanes by destination code.
- Warehousing:Mobile robots with conveyor tops are displacing fixed roller installations in facilities under 500,000 square feet.
Distribution commands the greatest installed base; warehousing is gaining share fastest on collaborative automation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in conveyor systems tilt toward net-importing manufacturing economies, with Germany, China, and the United States absorbing the largest equipment volumes while Japan and South Korea maintain selective export positions in precision drive components.
Germany
Automotive OEM retooling for electric-vehicle platforms drives demand for flexible pallet-based conveyor systems. The EU Machinery Directive and CE marking requirements filter non-compliant suppliers from cross-border procurement. Industrial clusters in Stuttgart and Munich concentrate tier-one supplier parks where documented mean-time-between-failure metrics determine contract awards.
United States
E-commerce fulfillment velocity compresses order cycles, accelerating high-speed sortation deployments in distribution centers. OSHA guarding standards around nip points and emergency stop placements drive replacement demand where legacy systems fail retrofit audits. The Chicago and Dallas-Fort Worth metro areas anchor third-party logistics consolidation, compressing vendor qualification cycles.
China
Battery gigafactory buildouts for electric-vehicle supply chains require cleanroom-compatible conveyors with electrostatic discharge protection. GB standards and MIIT industrial policy shape domestic procurement preferences. The Yangtze River Delta and Pearl River Delta clusters concentrate cell manufacturing investments, creating localized demand spikes for precision handling equipment.
Japan
METI energy-efficiency subsidies through JIS-certified motor programs accelerate conveyor retrofits with regenerative drive systems. Aging distribution center infrastructure in the Kanto and Kansai regions creates replacement windows for automated sortation. Nagoya-area automotive suppliers maintain demand for synchronized assembly line conveyors.
India
Cold chain expansion and organized retail growth create first-mover advantages for modular conveyor installations in warehousing. BIS certification requirements and PLI scheme incentives favor domestic assembly over fully-imported systems. The Maharashtra and Gujarat industrial corridors concentrate pharmaceutical and food processing investments with hygiene-rated equipment specifications.
Global Conveyors Market Vendor Landscape
Concentration sits with diversified industrial conglomerates and specialized material-handling vendors, with tiered competition separating integrated automation providers from component-focused fabricators. Japanese and German entities anchor premium positioning through captive control-software capabilities. Strategic moves cluster on backward integration into precision drive manufacturing and geographic expansion through distributor networks in Southeast Asian manufacturing zones.
Within the integrated-system tier, Daifuku Co., Ltd. and Murata Machinery, Ltd. represent Japanese conglomerates with material-handling software stacks, while Siemens AG exemplifies European industrial automation with embedded IoT diagnostics. Continental AG anchors heavy-duty belt supply through captive rubber-compounding operations. These three entities occupy positions spanning factory automation, airport logistics, and mining-sector relationships without overlapping segment dominance.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| Continental AG |
| Fives Group |
| BEUMER Group |
| Siemens AG |
| Murata Machinery, Ltd. |
| Interroll Group |
| Intralox |
| Dürr Group |
| Others |
Supply Flow & Price Mechanics
Fourteen-to-eighteen-week lead times for precision gearmotors and variable-frequency drives concentrate pricing power with German and Japanese component suppliers, compressing margins for system integrators while amplifying cost pass-through leverage to end-users in automotive and e-commerce fulfillment sectors.
Pricing Analysis
Configured-to-order pricing commands 35-50% premiums over standard catalog configurations in automated sortation systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and software integration depth. Cost compression in manual and hybrid segments intensifies because Asian exporters absorb CE marking compliance costs to maintain European market access. Third-party logistics providers exhibit highest price sensitivity due to unbundled procurement models, while pharmaceutical cleanroom buyers prioritize electrostatic discharge specifications over unit economics.
Supply Chain Analysis
Germany and Japan anchor precision drive manufacturing, while China dominates steel roller fabrication and aluminum extrusion for conveyor frames. Raw material dependencies center on high-grade steel alloys, rubber compounds for belt coatings, and rare-earth elements in servo motor magnets. Single-source vulnerability runs through German gearmotor suppliers serving automotive OEM retooling programs. Distribution runs through authorized distributor networks in Southeast Asian manufacturing zones, with direct-to-factory contracts consolidating in German supplier parks and Dutch port-centric hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Conveyors Market sits in early-cycle recovery as battery gigafactory capital expenditure resumes and automotive OEMs accelerate electric-vehicle platform retooling programs.
For Market Incumbents: Consolidate backward integration into precision drive manufacturing to neutralize single-source supply risk from German and Japanese component vendors. Deepen captive rubber-compounding capabilities to defend margin position against REACH substance restriction compliance costs. Prioritize TÜV-certified emergency stop system investments to filter non-compliant competitors from automotive tier-one contract awards in Stuttgart and Munich industrial clusters. For New Entrants and Emerging Players: Anchor in India's cold chain expansion and organized retail growth, where BIS certification requirements and PLI scheme incentives favor domestic assembly partnerships over fully-imported systems. Target modular gravity conveyor installations in Maharashtra and Gujarat pharmaceutical corridors where capital constraints limit upfront automation investment. Pursue distributor-led go-to-market models leveraging existing material-handling equipment channels rather than direct OEM sales cycles. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because buyer concentration among third-party logistics providers compresses vendor qualification cycles and rewards scaled service capabilities. Acquisition targets should emphasize software-defined routing platforms with predictive maintenance revenue streams rather than commodity bulk-handling fabricators. Monitor JIS-certified motor subsidy program expansions as inflection indicator for Japanese distribution center retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Drive Manufacturing | Reduces single-source dependency on German and Japanese gearmotor suppliers for automotive contracts. |
| Software-Defined Routing Platform Development | Captures recurring service revenue through predictive maintenance contracts with Dutch port-centric distribution hubs. |
| CE Marking and TÜV Certification Investment | Filters non-compliant Asian exporters from EU Machinery Directive procurement in German automotive supplier parks. |
| India Domestic Assembly Partnership | Aligns with BIS certification requirements and PLI scheme incentives in Maharashtra pharmaceutical corridors. |
| Regenerative Drive System Retrofit Programs | Captures METI energy-efficiency subsidies across aging Kanto and Kansai distribution center infrastructure. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads at automotive tier-one suppliers and third-party logistics providers. Secondary validation drew from customs and trade data, SEC 10-K filings, EU Machinery Directive compliance registries, and METI subsidy program disclosures. Bottom-up equipment shipment tallies by product type and technology tier were triangulated against top-down capital expenditure estimates from e-commerce fulfillment center buildouts and battery gigafactory announcements.
Across the analysis window, volume and value outputs were modeled through segmented forecasting across belt, roller, chain, and slat configurations; automated, manual, hybrid, and pneumatic technology tiers; and manufacturing, retail, food and beverage, and pharmaceutical end-use verticals. CAGRs were derived from regression analysis against industrial production indices and warehouse automation investment cycles. Forecast inputs incorporated EU battery regulation supply-chain disclosure timelines and OSHA guarding standard enforcement intensity.
Material uncertainties — steel and aluminum commodity price volatility, precision gearmotor supply disruptions, and REACH substance restriction enforcement scope — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding e-commerce fulfillment velocity sustainability and automotive EV platform standardization trajectories. Recalibration cycles align with material shifts in METI subsidy program renewals and EU Machinery Directive amendment schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Ship Loader and Unloader Market
Material Handling Equipment
Industrial Hoists Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Europe Conveyor Belt Market
Material Handling Equipment
Global Air Cannon System Market
Material Handling Equipment
Chute Liners Market
Material Handling Equipment
Truck Mounted Loader Cranes Market
Material Handling Equipment
Spring Shackles Market
Material Handling Equipment
Pallet Circulation System Market
Material Handling Equipment
Bulk Material Handling Products and Technologies Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Pedestal Boom System Market
Material Handling Equipment
Pipe Jacking Machines Market
Material Handling Equipment
Sweep Depalletizers Market
Material Handling Equipment
Jaw Crushers Market
Material Handling Equipment
Pipe Clamp Market