
 Linear Slide Units Market | 2026-2036
Linear Slide Units Market Size, Share, and Industry Trends Forecast 2026-2036
Linear Slide Units Market Outlook
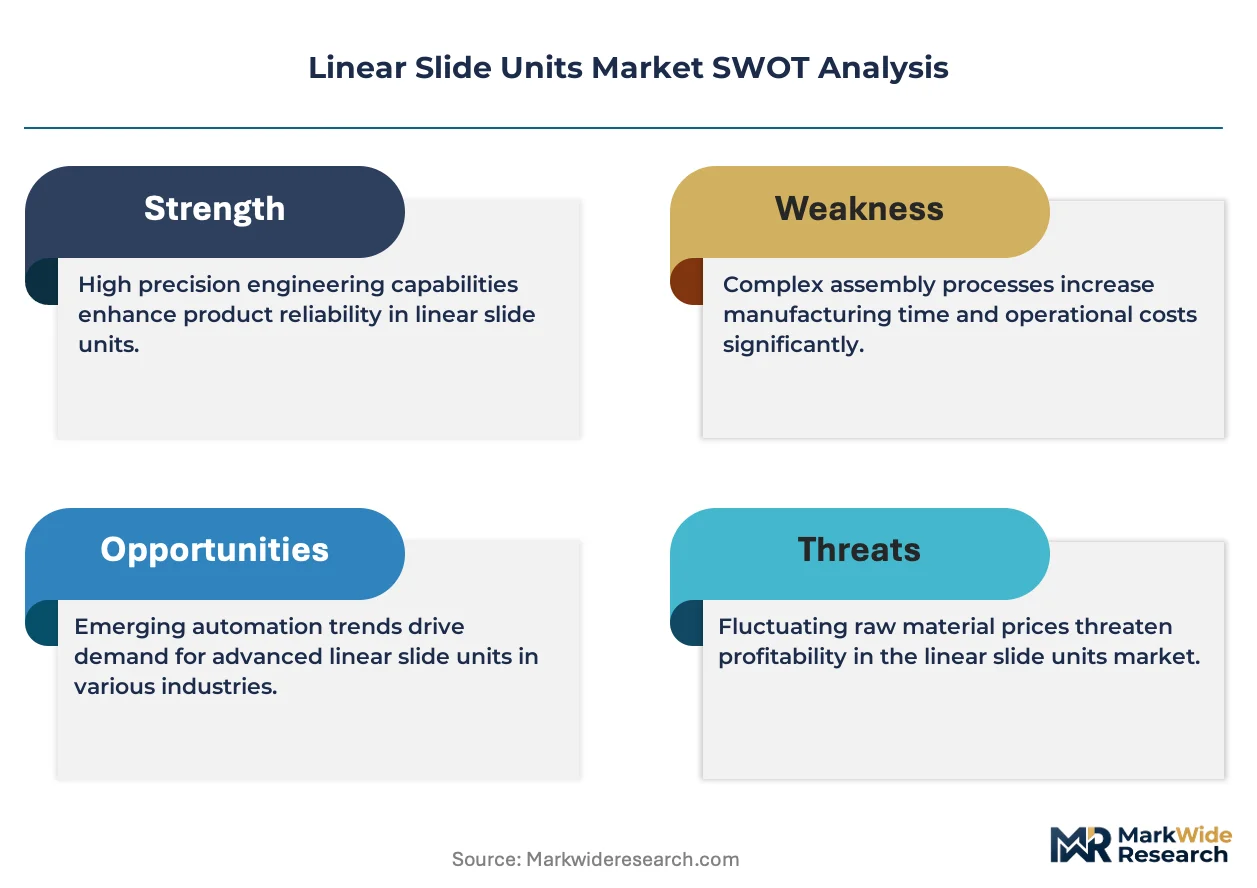
Electrification of factory motion systems is reshaping how OEMs specify positioning hardware across automated production lines. THK Co., Ltd. leverages its ball screw heritage to dominate high-precision CNC applications in East Asia. Bosch Rexroth AG anchors European demand through integrated drive-and-rail systems that simplify machine builder procurement. SKF Group competes on lubrication-free bearing technologies that extend maintenance intervals in food and packaging environments.
Linear slide units are electromechanical or pneumatic assemblies that translate rotary input into precise linear displacement along hardened steel or aluminum guide rails, typically achieving positional accuracy within micrometers. Their primary purpose is to deliver repeatable, load-bearing motion in automated machinery without the complexity of full Cartesian robots. Electric slide units now command the largest revenue pool as servo motor costs decline and energy efficiency mandates tighten. Ball screw drives retain the fastest expansion trajectory among drive technologies because they combine high thrust density with programmable positioning via servo controllers. Robotics applications are pulling disproportionate investment as collaborative robot arms require compact, modular linear axes for seventh-axis extensions and gantry configurations.
The EU Machinery Directive and CE marking requirements enforce functional safety standards on electromechanical positioning systems sold into European manufacturing. The EPA and OSHA in the United States impose energy efficiency and worker exposure limits that favor sealed electric slides over open pneumatic designs in certain factory deployments. Japan's METI industrial efficiency guidelines incentivize servo-based retrofits of legacy pneumatic actuation. Stakeholders must monitor how regional safety certifications fragment product platforms and whether servo motor supply constraints alter technology selection timelines.
Market Dynamics
Electrification of factory motion systems is compressing pneumatic actuator lifecycles as servo motor costs decline and energy efficiency mandates tighten across manufacturing jurisdictions. This technology shift is redrawing competitive boundaries between electromechanical and fluid power suppliers.
Growth Catalysts
- EU Machinery Directive safety mandates:Functional safety requirements for electromechanical positioning systems are accelerating replacement of legacy pneumatic slides in European automated production lines.
- Collaborative robotics integration:Seventh-axis linear extensions for cobot arms are pulling modular slide unit demand from automotive and electronics assembly sectors.
- Japan's METI industrial efficiency guidelines:Servo-based retrofits of legacy pneumatic actuation receive policy incentives, driving hardware refresh cycles in precision manufacturing.
Market Restraints
- Ball screw supply concentration:Precision ground screw production clusters in Germany and Japan, creating lead time vulnerability for high-accuracy positioning systems.
- Rare earth magnet cost volatility:Servo motor permanent magnets depend on neodymium supply chain fluctuations, pressuring electric slide unit pricing stability.
- Pneumatic infrastructure lock-in:Existing compressed air distribution in legacy factories creates switching friction against electric slide adoption in cost-sensitive retrofit scenarios.
Strategic Opportunities
- Food-grade lubrication-free bearings:SKF Group's sealed bearing technologies open packaging and pharmaceutical cleanroom applications previously closed to grease-dependent motion systems.
- India PLI scheme for manufacturing automation:Production-linked incentives for electronics and automotive component makers are creating first-time linear motion hardware demand in emerging industrial clusters.
- ISO 13849 functional safety certification:Pre-certified safety-rated slide platforms command premium positioning against uncertified competitors in European and North American machine builder procurement.
Industry Challenges
- Mechatronics engineering scarcity:Integration of servo drives, controllers, and mechanical guiding requires cross-functional expertise that outpaces vocational training pipeline output.
- CE marking timeline compression:EU Machinery Directive conformity assessment for multi-axis positioning systems extends product launch cycles by four to eight months.
- Legacy controller protocol fragmentation:Fieldbus and industrial Ethernet standard multiplicity forces redundant engineering effort for slide unit OEMs serving diverse installed bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linear Slide Units Market |
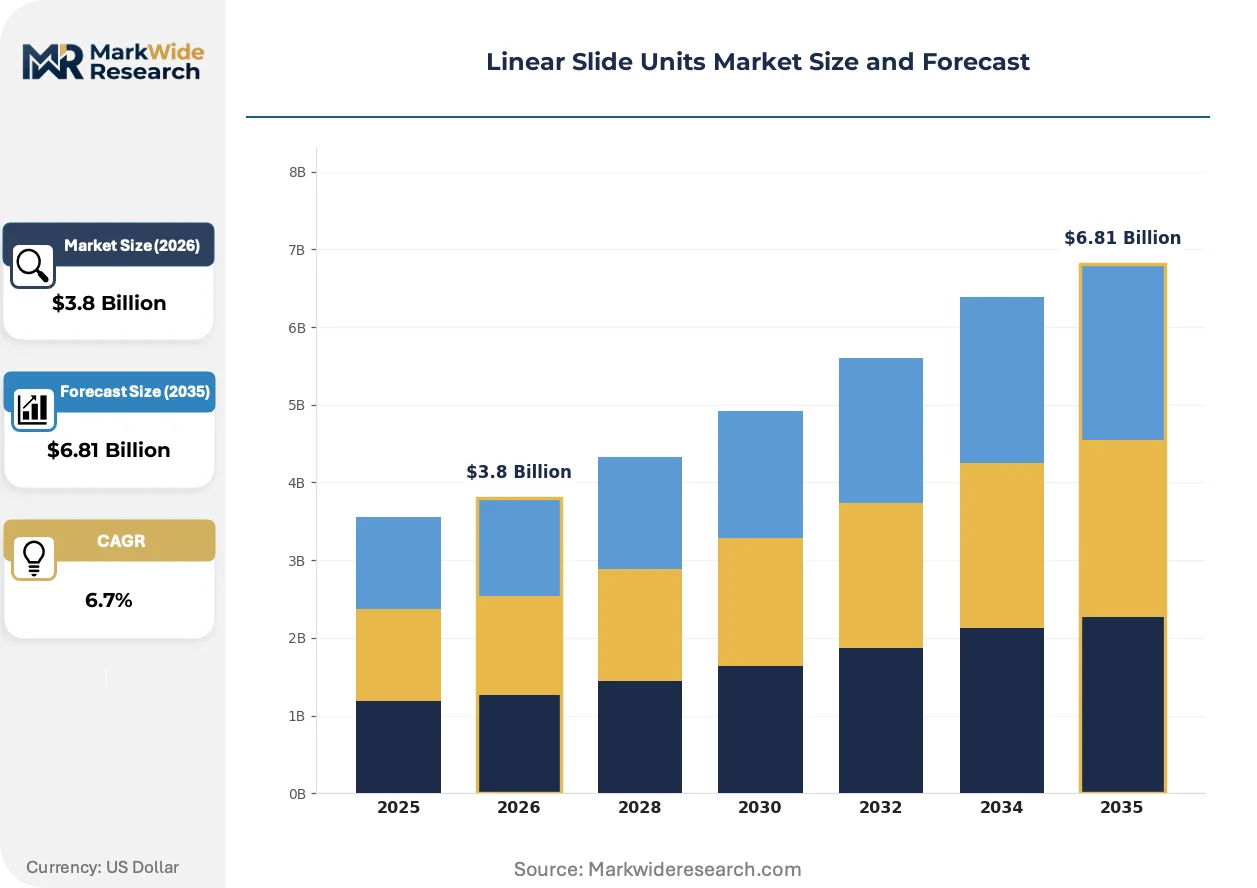
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Slide Units, Pneumatic Slide Units, Manual Slide Units, Hybrid Slide Units Technology: Linear Actuators, Servo Motors, Stepper Motors, Ball Screw Drives Application: Automated Assembly, Packaging Machinery, CNC Machines, Robotics End User: Manufacturing, Logistics, Aerospace, Electronics |
| Companies Covered | Parker Hannifin Corporation, HIWIN Technologies Corp., SKF Group, Thomson Industries Inc., NSK Ltd., THK Co., Ltd., Bishop-Wisecarver Corporation, Schneeberger Group, Bosch Rexroth AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linear Slide Units Market Strategic Shifts
Motion system architectures are shedding pneumatic infrastructure in favor of programmable electric positioning, while safety certification and predictive maintenance capabilities become table stakes in machine builder procurement.
Integrated linear motor slides are migrating from high-end semiconductor handling into mid-tier packaging and inspection equipment. Machine builders in Germany and Japan are specifying these direct-drive systems for throughput-critical indexing stations. This technology is migrating from niche cleanroom applications toward general factory automation, compressing the addressable market for ball screw alternatives in speed-sensitive segments.
REACH substance restrictions on lubricating oils and greases are forcing reformulation of bearing maintenance protocols for linear motion systems sold into European manufacturing. The regulation's industrial consequence is accelerated validation of solid lubricant and polymer bearing alternatives in food processing and medical device production. Packaging machinery OEMs in Italy and the Netherlands are responding fastest, redesigning slide specifications to eliminate hydrocarbon-based lubricants from washdown environments.
Machine-as-a-service contracting is restructuring how automotive tier-one suppliers acquire positioning hardware. Tier-one stampers and battery module assemblers are shifting from capital purchase to per-cycle pricing models, forcing slide unit vendors to embed connectivity and remaining-life diagnostics. This pattern is most visible in Michigan and Bavaria, where electric vehicle production lines demand uptime guarantees that transfer operational risk upstream to motion system suppliers.
Linear Slide Units Market Segmentation
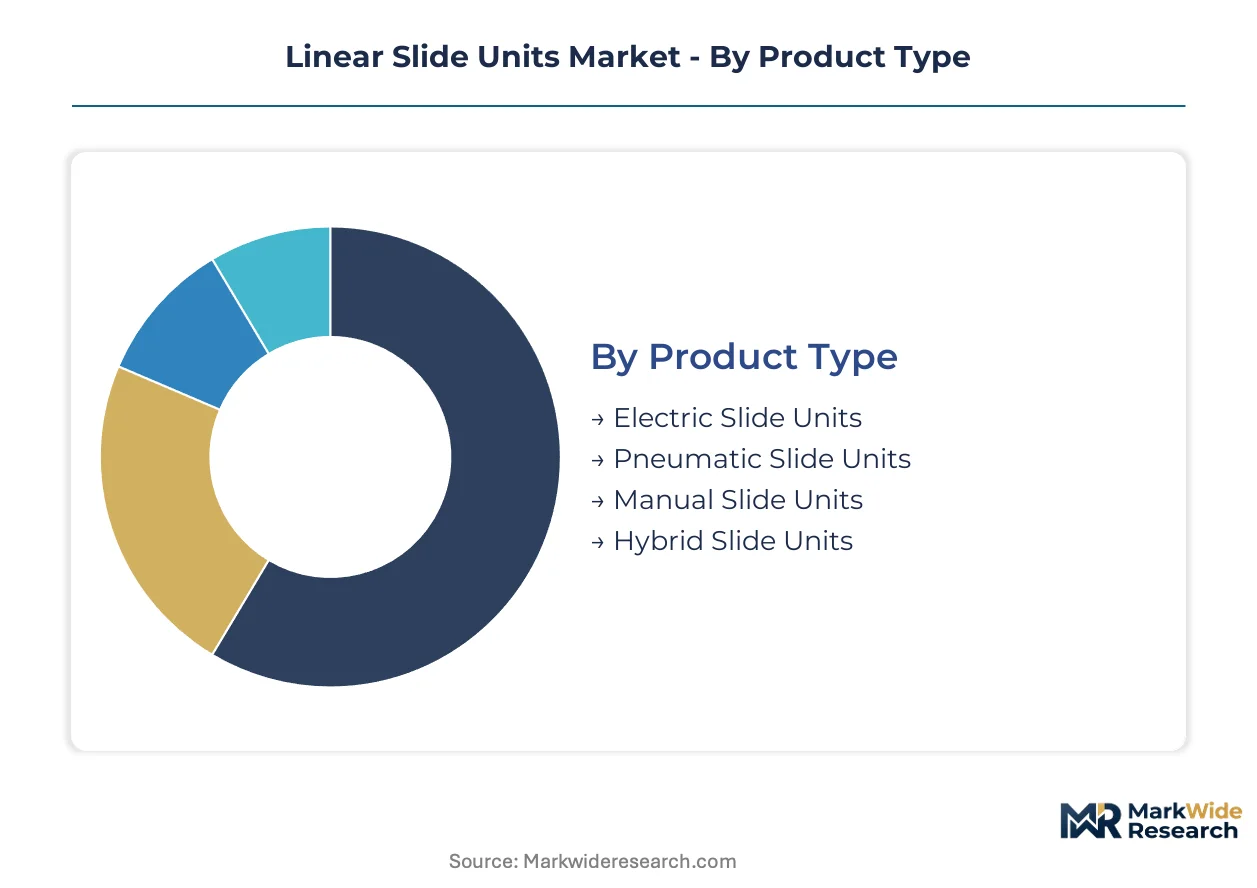
Linear slide unit procurement splits across electromechanical sophistication levels, with electric architectures displacing pneumatic legacy in precision applications while manual and hybrid variants retain footholds in cost-constrained or safety-critical niches. Technology selection hinges on thrust density requirements, positioning accuracy, and integration complexity with existing factory automation hierarchies.
Product Type:
Mature pneumatic infrastructure competes with emerging electric architectures as energy efficiency mandates and servo cost curves reshape factory floor specifications.
- Electric Slide Units:Servo-driven electromechanical assemblies deliver programmable positioning with micrometer repeatability, eliminating compressed air infrastructure. Demand concentrates in German automotive battery module assembly and Japanese electronics pick-and-place, where METI efficiency guidelines and EU Machinery Directive safety certifications accelerate pneumatic replacement.
- Pneumatic Slide Units:Compressed air cylinders with mechanical guiding remain prevalent in legacy food packaging and washdown environments where explosion-proofing takes precedence over precision. Existing air distribution in Michigan stamping plants and Bavarian tier-one facilities creates switching friction despite higher lifecycle energy costs.
- Manual Slide Units:Hand-cranked or lever-actuated positioning tables serve prototype workshops and low-volume repair operations.
- Hybrid Slide Units:Combined pneumatic-electric designs address safety-rated holding functions in collaborative robotics seventh-axis extensions.
Electric slide units retain volume leadership; hybrid configurations hold the steepest expansion curve as cobot integrators seek safety-redundant positioning.
Technology:
Cost tier stratification separates precision-ground ball screw systems from commodity linear actuator alternatives, with servo motor integration commanding premium positioning in high-throughput indexing stations.
- Linear Actuators:Belt-driven or rack-and-pinion mechanisms serve mid-accuracy material handling with lower capital outlay than screw-based alternatives. Logistics automation in Dutch distribution centers and Indian PLI-funded electronics assembly favors these for speed-over-precision conveyance tasks.
- Servo Motors:Closed-loop rotary actuators with encoder feedback enable dynamic positioning profiles and synchronized multi-axis coordination. German machine tool builders and Japanese semiconductor equipment OEMs specify these for sub-micron contouring in CNC and wafer handling applications.
- Stepper Motors:Open-loop incremental positioning suits cost-sensitive indexing where absolute accuracy is secondary to repeatability.
- Ball Screw Drives:Precision-ground recirculating ball nuts convert rotary servo input to linear motion with minimal backlash and high thrust density.
Ball screw drives retain specification dominance in CNC and semiconductor equipment; linear actuators are climbing fastest in logistics and packaging volume applications.
Application:
Customer type differentiation separates capital-intensive OEM machine builders from retrofit-focused systems integrators, with robotics applications pulling disproportionate R&D investment from slide unit vendors.
- Automated Assembly:Multi-axis positioning for component insertion, fastening, and inspection in automotive and electronics production. German tier-one suppliers and Japanese precision manufacturers drive specification toward ISO 13849-certified safety-rated platforms with embedded diagnostics.
- Packaging Machinery:High-speed indexing and cartoning operations demand washdown-compatible guiding and lubrication-free bearing technologies. Italian and Dutch OEMs are fastest in adopting REACH-compliant solid lubricant alternatives for food and pharmaceutical cleanrooms.
- CNC Machines:Tool positioning and workpiece handling axes require sub-micron repeatability and thermal stability.
- Robotics:Seventh-axis linear tracks and gantry configurations extend collaborative and industrial robot work envelopes.
Automated assembly commands the largest installed base; robotics applications are gaining share fastest as cobot deployment accelerates across automotive and electronics sectors.
End User:
Geography-driven specification variance fragments product platforms, with aerospace and electronics demanding certified precision while logistics prioritizes throughput and total cost of ownership.
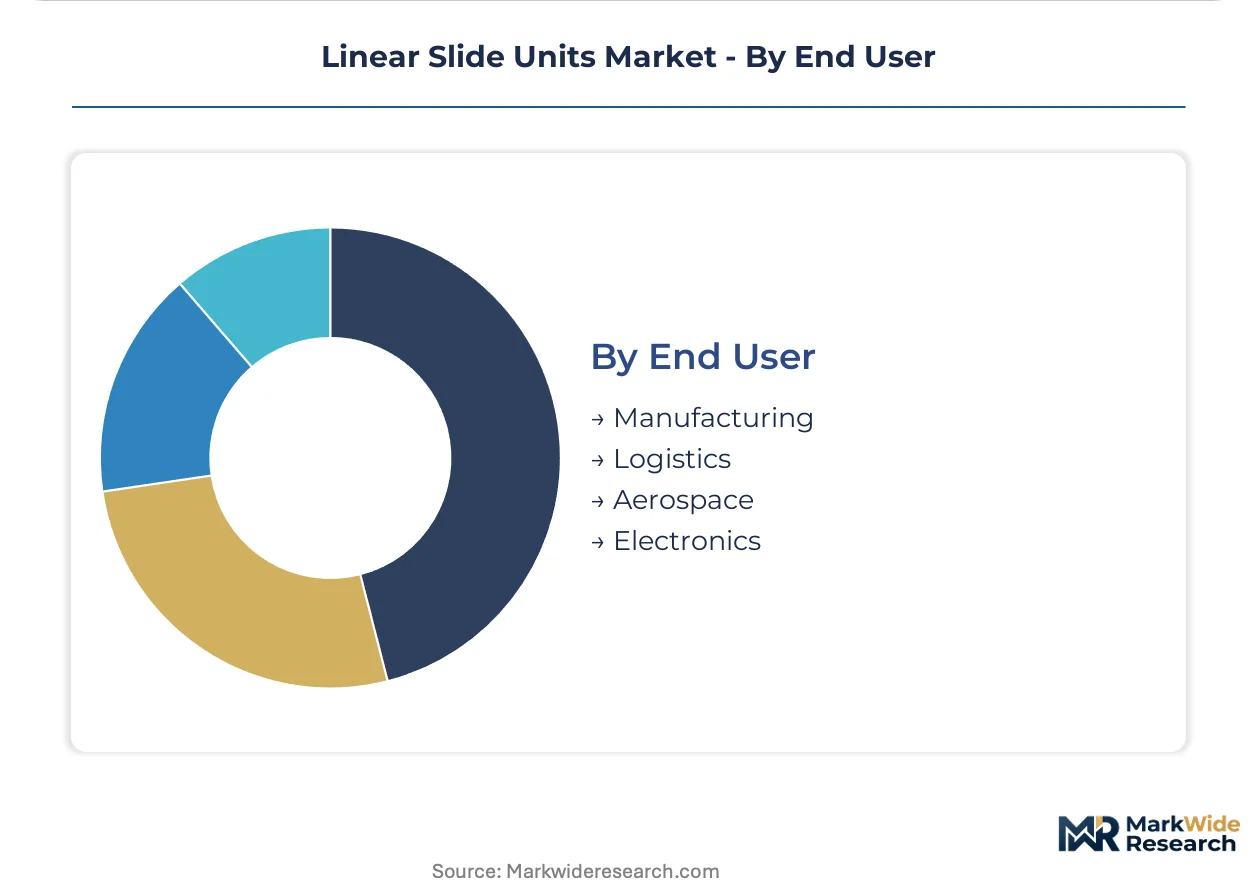
- Manufacturing:Discrete production across automotive, consumer goods, and industrial machinery represents the core demand pool. German, Japanese, and US facilities absorb the bulk of precision linear motion hardware as factory automation intensifies.
- Logistics:Automated storage, retrieval, and sortation systems favor belt-driven linear actuators over screw-based alternatives for speed and maintenance interval requirements. Indian emerging industrial clusters under PLI incentives are creating first-time demand for mid-tier positioning systems.
- Aerospace:Structural assembly and component handling require traceable materials and extended environmental qualification.
- Electronics:Semiconductor wafer handling and PCB assembly demand cleanroom-compatible guiding with vibration damping and particulate control.
Manufacturing retains volume leadership; electronics holds the steepest expansion trajectory as semiconductor capital expenditure cycles recover and packaging density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive battery module assemblers and Japanese precision electronics manufacturers absorb the bulk of high-accuracy linear motion hardware as factory automation intensifies. Robotics integrators in Michigan and Bavaria drive specification toward ISO 13849-certified platforms with embedded diagnostics. Indian PLI-funded electronics clusters are creating first-time demand for mid-tier positioning systems.
Germany
Automotive tier-one suppliers in Bavaria and Baden-Württemberg drive demand for safety-rated electromechanical positioning systems. The EU Machinery Directive enforces functional safety standards through CE marking requirements on multi-axis positioning equipment. Stuttgart-area machine builders specify integrated drive-and-rail systems that simplify procurement for battery module assembly lines.
Japan
Semiconductor equipment OEMs and electronics pick-and-place integrators require sub-micron repeatability in cleanroom-compatible guiding systems. METI industrial efficiency guidelines incentivize servo-based retrofits of legacy pneumatic actuation across precision manufacturing facilities. Nagoya-area automotive component makers are refreshing hardware to meet tightening energy efficiency mandates.
United States
Collaborative robot arm integrators in Michigan and California pull modular slide demand for seventh-axis linear extensions and gantry configurations. EPA energy efficiency and OSHA worker exposure regulations favor sealed electric slides over open pneumatic designs in automotive stamping plants. Greater Detroit tier-one stampers are shifting toward machine-as-a-service contracting with uptime guarantees.
India
Electronics and automotive component makers under the PLI scheme are creating first-time demand for belt-driven linear actuators in automated assembly. The country's national manufacturing incentive programs fund capital equipment procurement in emerging industrial clusters. Tamil Nadu and Karnataka contract manufacturers are specifying mid-accuracy positioning systems for speed-over-precision conveyance tasks.
Italy
Packaging machinery OEMs in Emilia-Romagna and Lombardy demand REACH-compliant solid lubricant alternatives for food and pharmaceutical cleanroom applications. ECHA substance restrictions on hydrocarbon-based lubricants force redesign of slide specifications in washdown environments. Bologna-area cartoning equipment specialists are fastest in adopting lubrication-free bearing technologies.
Linear Slide Units Market Competitive Environment
Channel-controlling players compete with product-specialist players for specification authority in machine builder procurement. The vendor base organizes around three archetypes: integrated motion system suppliers bundling drive-and-rail solutions, precision bearing specialists leveraging lubrication-free technologies, and regional fabricators serving cost-constrained retrofit markets. Dominant competitive moves include geographic expansion into PLI-funded Indian industrial clusters and technology licensing arrangements for functional safety certification.
Among Japanese precision specialists, THK Co., Ltd. and NSK Ltd. exemplify the heritage-driven archetype anchored in ball screw and linear motion component expertise. Bosch Rexroth AG occupies a position representing the integrated European motion system supplier with drive-and-rail bundling capabilities. SKF Group sits within the bearing-technology specialist tier, extending maintenance interval advantages into food-grade and cleanroom positioning applications.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| HIWIN Technologies Corp. |
| SKF Group |
| Thomson Industries Inc. |
| NSK Ltd. |
| THK Co., Ltd. |
| Bishop-Wisecarver Corporation |
| Schneeberger Group |
| Bosch Rexroth AG |
| Others |
Value Chain & Pricing Dynamics
Precision ground ball screw production clusters in Germany and Japan concentrate upstream supply power, anchoring margin pools with machine builders in Bavaria and Stuttgart who specify integrated drive-and-rail systems. This geographic concentration of critical screw manufacturing feeds directly into pricing leverage for electromechanical positioning hardware.
Pricing Analysis
Cost-plus contracts with steel and rare earth magnet indexation dominate procurement between Japanese ball screw specialists and German automotive tier-one suppliers. Three-tier pricing structure across ISO 13849-certified safety platforms, standard electric slides, and economy pneumatic alternatives reflects certification grade and volume scale differentiation. Pricing pressure stems from neodymium supply chain volatility pressuring servo motor costs, with logistics automation buyers in Dutch distribution centers exhibiting highest price sensitivity versus semiconductor equipment OEMs demanding sub-micron precision.
Supply Chain Analysis
Supplier-financing facilities extended by Bosch Rexroth AG and THK Co., Ltd. to machine builders in Michigan and Bavaria compress working capital cycles for battery module assembly lines. Component sourcing draws from German precision grinding houses, Japanese bearing specialists, and Chinese rare earth processors. Single-source vulnerability concentrates in neodymium magnet supply from Chinese refiners. Distribution runs through authorized distributor networks serving OEM procurement teams and systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Linear Slide Units Market functions as a defensive-moat arena where regulatory certification entrenchment creates switching costs that protect incumbent positioning against emerging competitors.
For Market Incumbents: Entrench ISO 13849 functional safety certification across product platforms to exploit CE marking timeline compression that delays competitor launches by four to eight months. Deepen backward integration into precision ground screw manufacturing in Germany and Japan to mitigate lead time vulnerability against emerging Asian competitors. Channel control through authorized distributor networks serving automotive tier-one procurement teams reinforces specification authority. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-funded electronics clusters where first-time automation demand creates specification openness absent in mature German and Japanese markets. Target mid-accuracy belt-driven linear actuators for speed-over-precision logistics applications in Tamil Nadu and Karnataka contract manufacturers. Partner with local systems integrators to bypass incumbent distributor lock-in. For Investors and Strategic Acquirers: Capital is best deployed toward lubrication-free bearing technology specialists with food-grade and cleanroom application credentials, as REACH compliance requirements expand addressable market in European packaging. Long-term viability hinges on electrification tailwinds displacing pneumatic infrastructure. Monitor servo motor supply constraint resolution as inflection indicator for electric slide unit pricing stability.| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Certification Investment | ISO 13849 pre-certification compresses EU Machinery Directive conformity timelines for Stuttgart machine builders. |
| Backward Integration into Precision Grinding | In-house ball screw production mitigates lead time exposure from German and Japanese supply concentration. |
| Geographic Expansion into Indian PLI Clusters | Tamil Nadu and Karnataka electronics assembly creates first-time demand for mid-tier positioning systems. |
| Lubrication-Free Bearing Technology Licensing | REACH-compliant solid lubricant alternatives open food and pharmaceutical cleanroom applications in Italy and the Netherlands. |
| Machine-as-a-Service Contracting Capability | Per-cycle pricing with embedded diagnostics transfers operational risk from Michigan tier-one stampers to motion suppliers. |
Study Parameters
The analysis maps electric slide units, pneumatic alternatives, ball screw drives, and linear actuator sub-sectors, each validated through maintenance directors at automotive tier-one facilities, OEM procurement teams specifying positioning hardware, and aftermarket service heads managing retrofit cycles. Primary interviews with robotics integrators deploying seventh-axis extensions combined with secondary validation from SEC filings of listed motion component suppliers, German mechanical engineering association trade statistics, and Japanese METI industrial equipment shipment data. Bottom-up unit demand modeling and top-down value triangulation cross-verify segment outputs.
Fixed assumptions held servo motor cost decline curves and EU Machinery Directive enforcement timelines constant across the projection horizon, while neodymium price volatility and India PLI scheme uptake were varied parametrically. Segmentation dimensions modeled include drive technology sophistication, end-use application intensity, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and automation capital expenditure elasticity estimates, with semiconductor capital equipment spending patterns and automotive battery module assembly line buildouts serving as industry-specific demand anchors.
Stress conditions across rare earth magnet supply disruption, REACH substance restriction expansion, and collaborative robotics deployment velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory implementation schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Slow Speed Shredding Machines Market
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Jaw Crushers Market
Material Handling Equipment
Hot-Rolling Mill and Cold-Rolling Mill Market
Material Handling Equipment
Debris Loaders Market
Material Handling Equipment
Trash Chute Market
Material Handling Equipment
Sweep Depalletizers Market
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
Port Equipment Market
Material Handling Equipment
Shaft Shredder Market
Material Handling Equipment
United States Hand Holes Market
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Log Loaders Market
Material Handling Equipment
Belt Weigh Feeder Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Resistance Welding Products Market