
 Global Metal Shredder Machine Market | 2026-2036
Global Metal Shredder Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal Shredder Machine Market Intelligence
A shift from multi-sourcing components to in-house production of critical parts is hardening competitive barriers for new entrants. This strategy gives established firms greater control over performance and supply chain resilience. Metso Corporation leverages its extensive engineering capabilities to produce proprietary shredder technologies. The ANDRITZ Group sustains its market position through a broad portfolio catering to diverse industrial waste streams, from automotive to e-waste.
A metal shredder machine is an industrial system designed to reduce the volume of metallic scrap through shearing, tearing, and compressing actions. These machines utilize powerful hydraulic or electric drive systems and specialized knife configurations to process materials for recycling. Among product types, double-shaft shredders dominate the scrap metal recycling application due to their high torque and resistance to jamming. The mobile shredder segment, however, represents the fastest-growing category, serving on-site needs in construction debris and automotive dismantling.
Equipment compliance is governed by multiple frameworks, including the EU's CE marking for machinery safety and China's GB standards for industrial equipment. In the United States, EPA regulations on scrap processing and emissions influence shredder design and operational requirements. The key decision for operators now centers on balancing initial capital investment in advanced sensor-sorting technology against the long-term revenue gains from higher-purity scrap output.
Market Dynamics
The central force shaping the metal shredder machine market is the global regulatory pivot towards a circular economy. Mandates from bodies like the European Union and national policies such as China's dual carbon goals are creating non-negotiable demand for scrap processing infrastructure.
Growth Catalysts
- Regulatory Mandates:The EU's Circular Economy Action Plan is enforcing higher material recovery targets, compelling member states to expand their metal recycling capacity and invest in more efficient shredding technology.
- Automotive Sector Transition:The shift towards electric vehicles and lightweight materials in automotive manufacturing generates more complex end-of-life vehicle scrap, requiring advanced shredders capable of separating diverse metal alloys and composites.
- Industrial Hub Concentration:Demand is intensifying in manufacturing centers, particularly in China's steel-producing regions, where shredders are critical for preparing scrap metal feedstock to meet industrial production and environmental standards.
Market Restraints
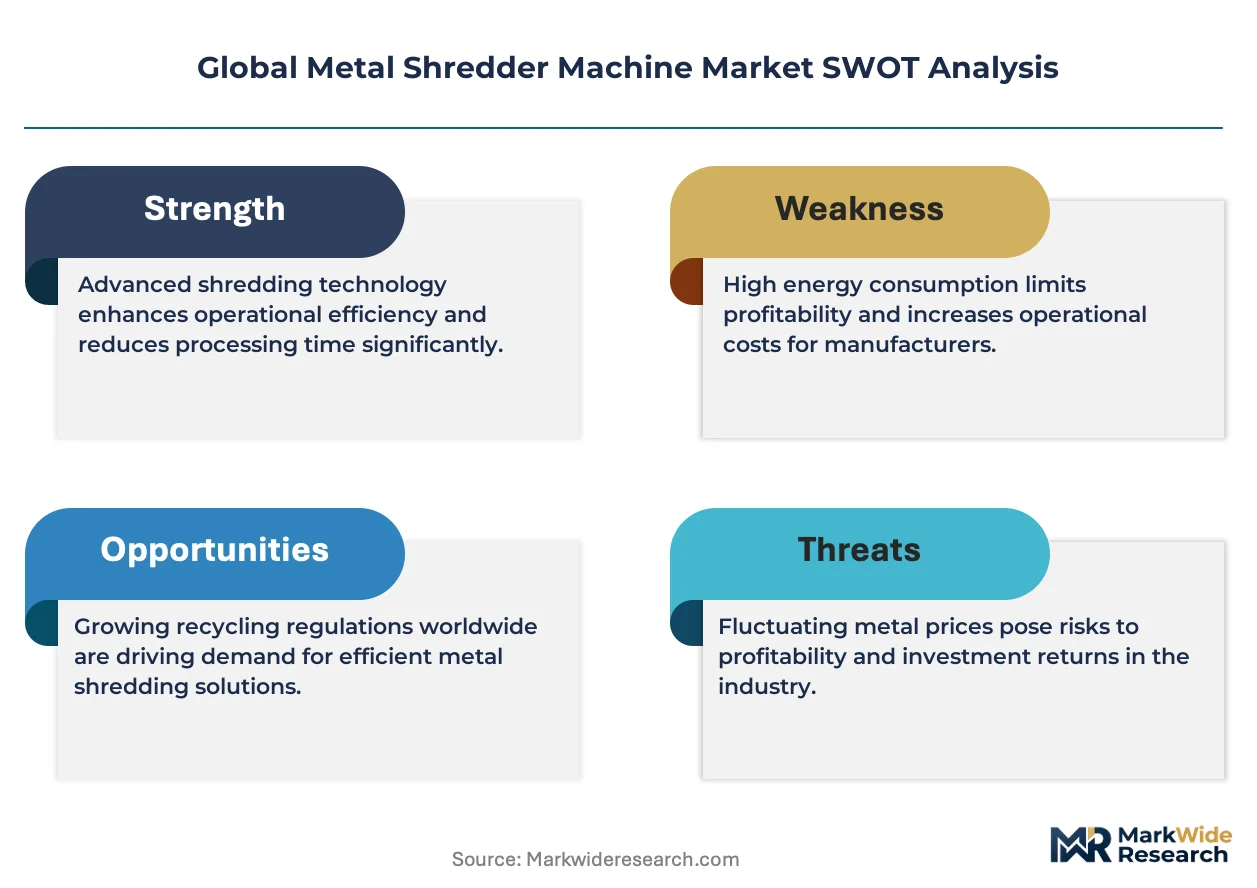
- High Capital Investment:The significant upfront cost of high-capacity shredders, particularly models integrated with advanced sensor-based sorting systems, presents a substantial financial barrier for small and medium-sized recycling enterprises.
- Component Wear and Maintenance:Critical components like hammers, knives, and grates are subject to rapid wear from processing abrasive materials, resulting in high operational costs and significant equipment downtime for replacement and maintenance.
- Regulatory Compliance Costs:Adhering to stringent environmental rules, such as EPA regulations in the United States covering air emissions and residue disposal, increases the operational complexity and cost of running a shredding facility.
Strategic Opportunities
- Mobile Shredder Deployment:The development of smaller, mobile shredder units creates opportunities to serve on-site processing needs at demolition projects, remote scrap collection points, and large-scale automotive dismantling yards, reducing transportation costs.
- E-Waste Stream Specialization:There is a growing opportunity for shredders specifically designed for electronic waste, capable of liberating and separating valuable precious metals from circuit boards and other complex electronic components.
- Predictive Maintenance Services:Offering IoT-enabled monitoring services that track equipment health and predict component failure allows manufacturers to sell uptime and performance as a service, creating recurring revenue streams.
Industry Challenges
- Skilled Labor Scarcity:A shortage of technicians trained to operate and maintain the complex hydraulic, electrical, and software systems of modern shredders can lead to operational inefficiencies and extended downtime.
- Technology Integration Complexity:Integrating new, high-performance shredders with existing downstream material handling and sorting equipment at established recycling facilities often poses significant technical and logistical challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal Shredder Machine Market |
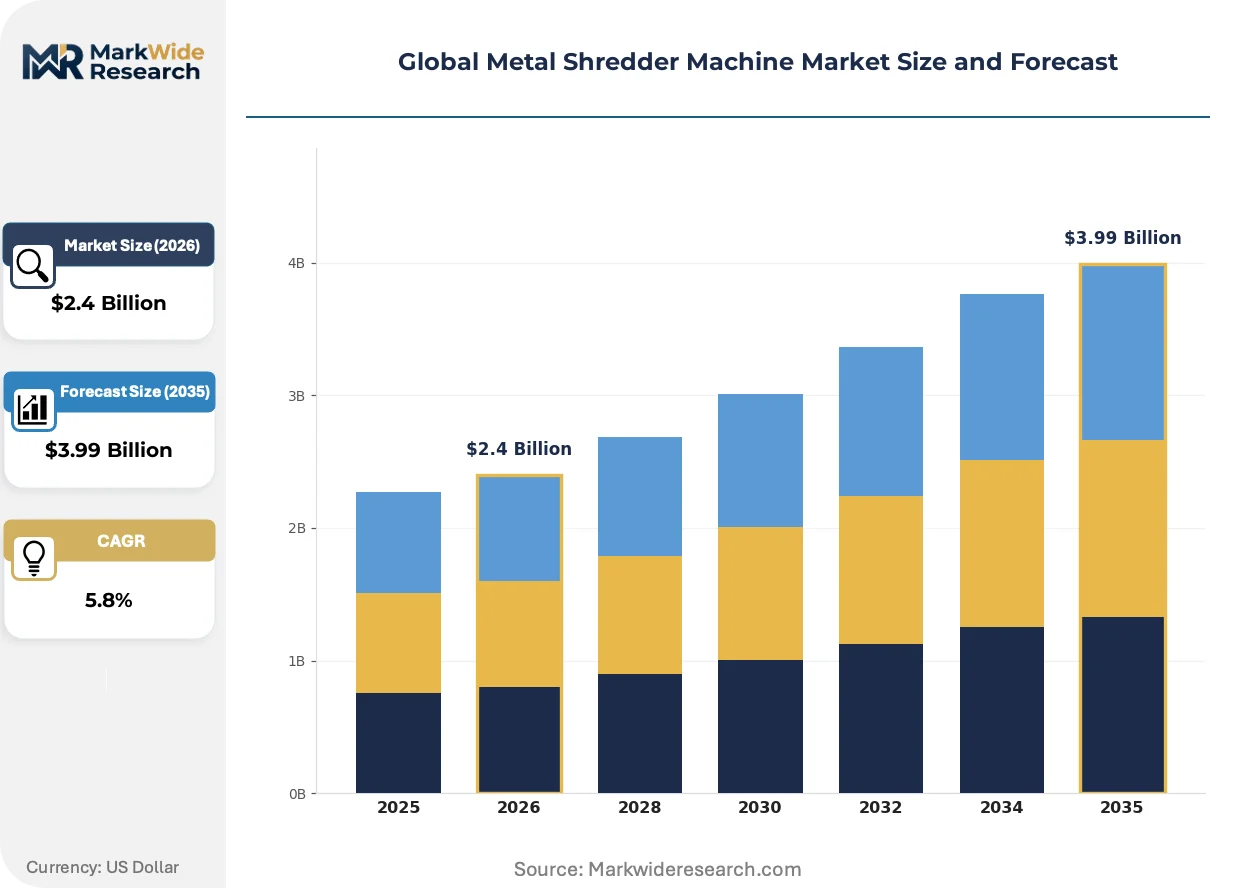
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Shaft, Double Shaft, Four Shaft, Mobile Shredders, Rotary Drum, Hammer Mills Technology: Hydraulic Drive, Mechanical Drive, Electric Drive, Pneumatic Drive, Magnetic Separation, Sensor Sorting Application: Scrap Metal Recycling, E-Waste Processing, Automotive Dismantling, Construction Debris, Industrial Waste Management, Military Waste End User: Metal Recycling Firms, Waste Management Companies, Manufacturing Plants, Metal Fabrication Shops, Defense Contractors |
| Companies Covered | WEIMA Maschinenbau GmbH, BCA Industries Inc., Metso Corporation, ANDRITZ Group, Hammermills International LLC, SSI Shredding Systems Inc., Vecoplan LLC, Granutech-Saturn Systems, UNTHA Shredding Technology GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal Shredder Machine Market Strategic Shifts & Innovations
The market is being reshaped by the integration of digital intelligence into heavy industrial machinery. This shift moves the value proposition from pure volume reduction towards maximizing the purity and value of the final recycled commodity through data-driven processing.
Advanced sensor-based sorting uses technologies like X-ray fluorescence and laser-induced breakdown spectroscopy to identify metal alloys in real time. Large-scale scrap processors and specialized recyclers are the primary adopters of these systems. This sorting capability is converging with the mechanical shredding action, enabling integrated machines to produce pre-sorted, high-purity material streams directly at the point of processing.
China's national dual carbon goals are driving a significant upgrade cycle within its domestic scrap processing industry. The policy mandates lower energy consumption and emissions, making older, less efficient shredder technologies obsolete. This shift most directly impacts the steel recycling sector, which now requires higher-purity scrap feedstock to minimize energy use and pollutants from electric arc furnaces.
A notable behavioral shift among scrap processors is the prioritization of total cost of ownership and operational uptime over initial equipment price. This change disrupts the traditional transactional sale, creating an advantage for manufacturers that provide comprehensive lifecycle support, including remote diagnostics and guaranteed parts availability. This trend is most prominent in Germany and the United States, where high labor costs make equipment reliability a critical financial lever.
Global Metal Shredder Machine Market Segmentation
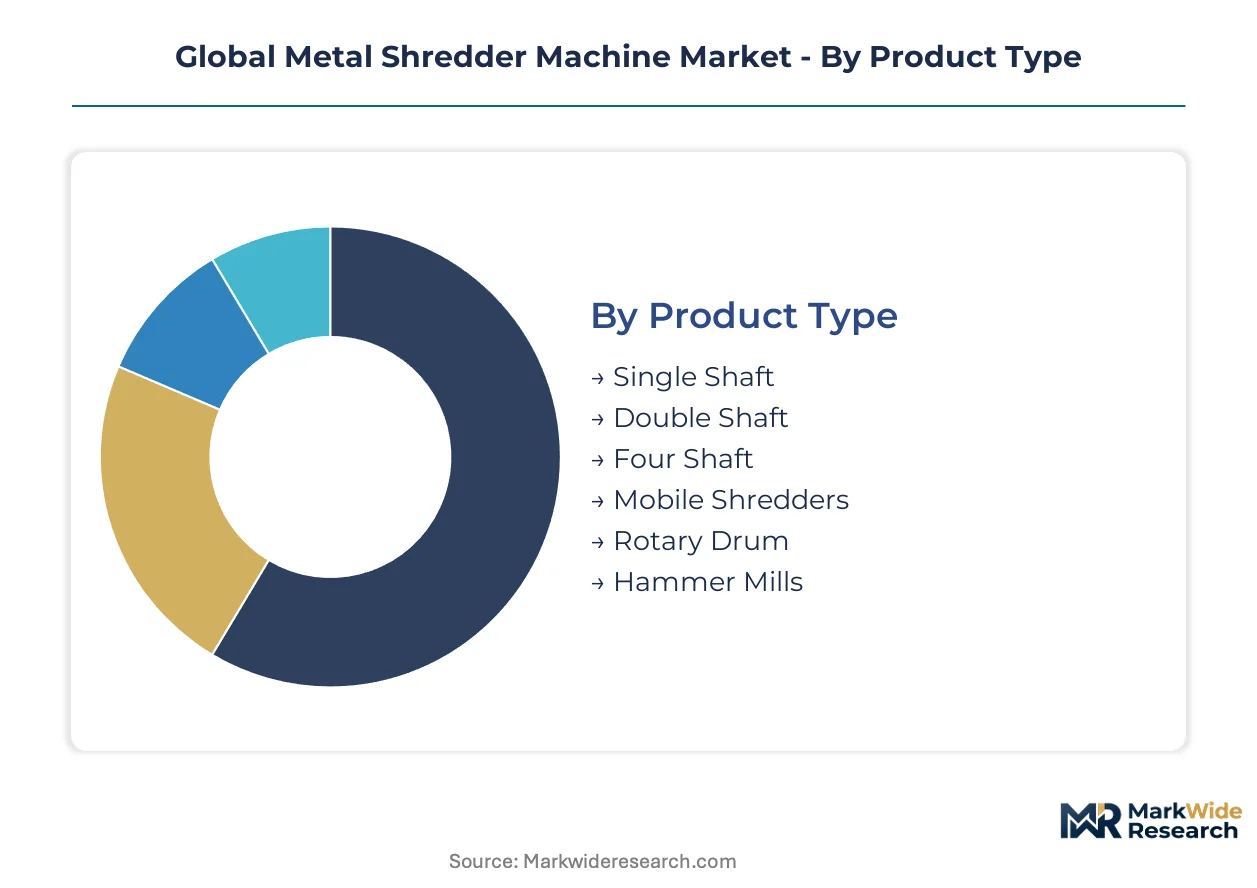
The global metal shredder machine market categorizes based on critical operational characteristics and application contexts. Understanding these segments helps identify specific demand drivers and technological preferences across diverse industrial users. This segmentation highlights areas of established market penetration and emerging growth opportunities.
Product Type:
Buyers in the product type segment differentiate their machinery selection based on material throughput requirements and the specific form of scrap processed.
- Double Shaft:High torque double-shaft shredders effectively process mixed scrap, resisting jamming from bulky materials. Demand concentrates in China's steel-producing regions, driven by the need for high-purity feedstock for electric arc furnaces.
- Mobile Shredders:These versatile units offer on-site processing capabilities, reducing transportation costs for demolition projects and remote scrap collection. The segment experiences rapid expansion, serving automotive dismantling and construction debris applications.
- Single Shaft:Single-shaft shredders handle various materials, often used for initial size reduction in less demanding applications.
- Four Shaft:Four-shaft shredders provide precise particle size control, ideal for producing uniform scrap output for specific industrial needs.
- Rotary Drum:Rotary drum shredders are suited for pre-shredding large volumes of light scrap and municipal solid waste.
- Hammer Mills:Hammer mills utilize impact forces to process brittle materials, commonly found in automotive and white goods recycling.
Volume sits with Double Shaft shredders; growth tilts toward Mobile Shredders.
Technology:
The technology segment reflects varying operational priorities, from raw power delivery to advanced material identification.
- Sensor Sorting:Sensor-based sorting integrates technologies like X-ray fluorescence, identifying specific metal alloys for higher purity output. Large-scale processors in Germany adopt these systems to maximize recycled commodity value.
- Electric Drive:Electric drive systems offer efficient and environmentally compliant operation, reducing energy consumption and emissions. Manufacturing centers in the United States increasingly favor these drives for their lower operational costs.
- Hydraulic Drive:Hydraulic drive systems deliver high torque for heavy-duty shredding applications, ensuring robust performance.
- Mechanical Drive:Mechanical drive systems provide a reliable and straightforward power transmission method for various shredder types.
- Pneumatic Drive:Pneumatic drive systems offer precise control in specific lighter-duty applications, though less common for heavy shredders.
- Magnetic Separation:Magnetic separation technology removes ferrous metals from mixed waste streams, enhancing material purity.
Efficiency and purity gains define this category's evolution, with sensor sorting capabilities gaining significant traction.
Application:
The application segment delineates the diverse material streams and processing objectives that metal shredders address.
- Scrap Metal Recycling:This application dominates demand, preparing ferrous and non-ferrous scrap for re-melting in steel mills and foundries. Global regulatory mandates for higher recycling rates sustain this segment.
- E-Waste Processing:Specialization in e-waste processing focuses on liberating valuable precious metals and separating complex electronic components. Opportunities are emerging in regions like the EU due to stringent WEEE directives.
- Automotive Dismantling:Automotive dismantling requires shredders capable of processing end-of-life vehicles, separating various metal and non-metal components.
- Construction Debris:Shredders in construction debris applications reduce bulky demolition waste, preparing materials for re-use or landfill reduction.
- Industrial Waste Management:This segment covers shredding diverse industrial by-products and manufacturing scrap for recycling or disposal.
- Military Waste:Processing military waste involves specialized shredders for secure destruction and material recovery from defense equipment.
While traditional scrap metal recycling remains foundational, specialized processing for e-waste is expanding quickly.
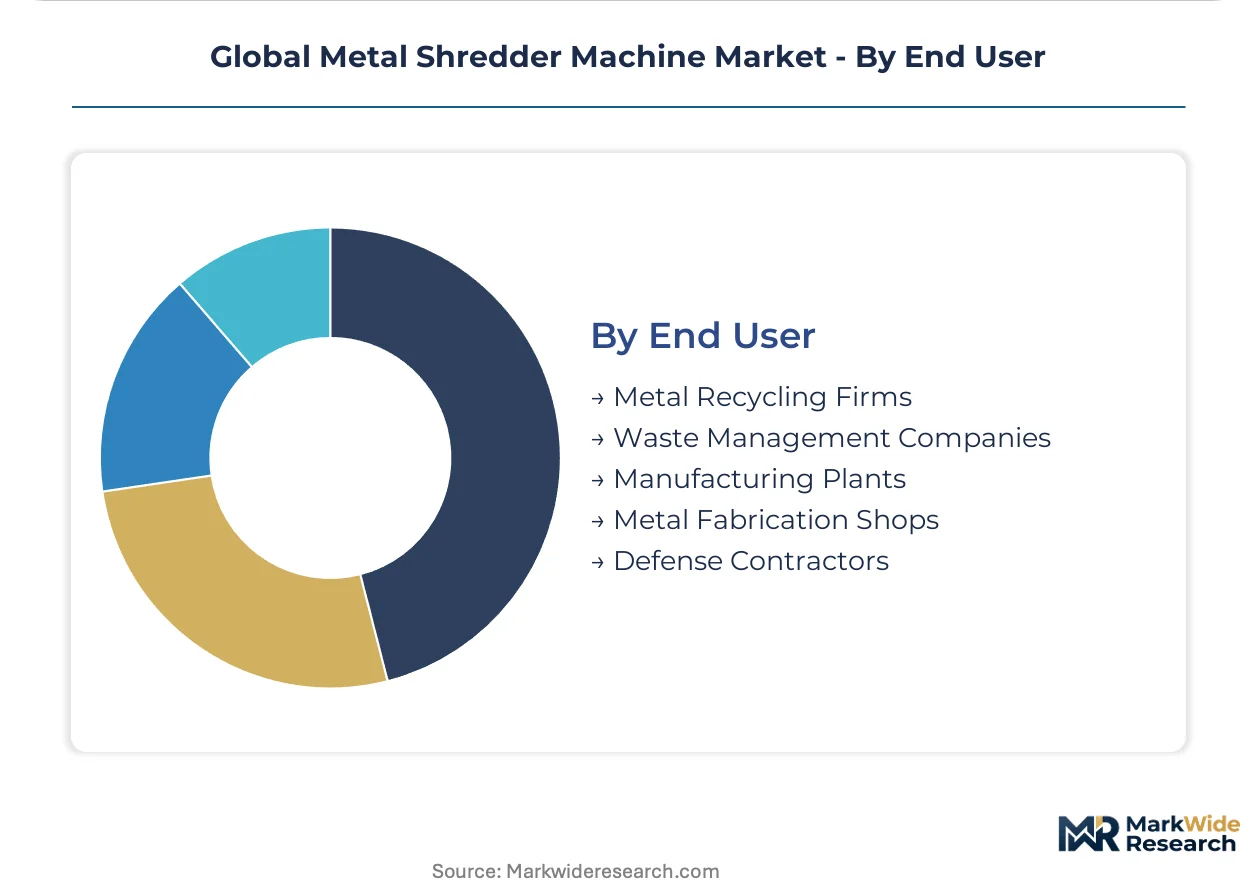
End User:
End users in this market are distinguished by their operational scale and primary business functions related to material recovery.
- Metal Recycling Firms:These firms represent the core customer base, operating shredders to process large volumes of scrap for commodity markets. High capital investment and operational costs are key considerations for these enterprises.
- Waste Management Companies:Waste management companies integrate shredders into broader waste streams, handling diverse materials from municipal to industrial sources. Their demand is influenced by environmental regulations and resource recovery goals.
- Manufacturing Plants:Manufacturing plants use shredders to process in-house scrap and production waste, optimizing material flow and recycling efforts.
- Metal Fabrication Shops:Smaller metal fabrication shops utilize compact shredders for managing their localized metal offcuts and turnings.
- Defense Contractors:Defense contractors employ shredders for secure disposal and demilitarization of sensitive materials and equipment.
The market serves a broad spectrum of industrial players, with core recycling businesses driving the largest demand and operational scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for metal shredder machines remains pronounced in industrial hubs across key global economies. These regions exhibit robust manufacturing bases, stringent recycling mandates, and a sustained need for high-purity scrap metal feedstock. Regulatory frameworks and economic incentives are accelerating investments in advanced shredding technologies.
China
Demand for metal shredders in China is driven by the vast steel-producing industry and a push for higher-purity scrap. China's dual carbon goals are compelling steel mills to upgrade their scrap processing infrastructure for electric arc furnaces. Major industrial clusters in the Yangtze River Delta and Hebei province are investing in advanced shredding and sorting systems.
Germany
Germany's market for metal shredders benefits from the EU's Circular Economy Action Plan, which enforces ambitious material recovery targets. This regulatory push encourages investment in efficient shredding technology to process diverse waste streams. Manufacturing centers in North Rhine-Westphalia and Bavaria are adopting sensor-sorting systems to maximize recycled commodity value.
United States
The United States market sees sustained demand from the automotive dismantling and construction debris sectors. EPA regulations on scrap processing and emissions influence shredder design and operational requirements. High labor costs in states like California and Texas make equipment reliability and automation critical financial levers for recycling operations.
Japan
Japan's metal shredder market is shaped by its advanced automotive manufacturing sector and stringent recycling standards for end-of-life vehicles. METI (Ministry of Economy, Trade and Industry) promotes resource efficiency and material recycling across industrial sectors. Industrial regions around Tokyo and Nagoya are upgrading facilities to handle complex metal alloys and composites.
India
India's growing manufacturing base and infrastructure development projects are fueling demand for metal shredding solutions. The country's push for a circular economy, supported by policies like the PLI scheme, encourages domestic recycling capabilities. Industrial clusters in Gujarat and Maharashtra are seeing increased adoption of shredders for processing ferrous and non-ferrous scrap.
Global Metal Shredder Machine Market Key Industry Players
In-house production of critical parts dominates the current landscape, hardening competitive barriers for new entrants in the metal shredder machine market. This strategy allows established firms to maintain greater control over product performance and supply chain resilience. The market exhibits a tiered structure, with large integrated manufacturers, specialized shredder producers, and technology-focused innovators representing key strategic archetypes. Key competitive moves include vertical integration to control component supply and continuous portfolio diversification to address diverse waste streams.
Within the large integrated manufacturers tier, Metso Corporation exemplifies extensive engineering capabilities and proprietary shredder technologies. The ANDRITZ Group occupies a position with its broad portfolio, catering to diverse industrial waste streams from automotive to e-waste. Germany-based WEIMA Maschinenbau GmbH represents a specialized shredder producer, focusing on robust solutions for various industrial applications and material types.
| Leading Market Players |
|---|
| WEIMA Maschinenbau GmbH |
| BCA Industries Inc. |
| Metso Corporation |
| ANDRITZ Group |
| Hammermills International LLC |
| SSI Shredding Systems Inc. |
| Vecoplan LLC |
| Granutech-Saturn Systems |
| UNTHA Shredding Technology GmbH |
| Others |
Cost & Logistics Intelligence
Skilled technicians trained to operate complex shredder systems, particularly in Germany and the United States, create labor-cost differentials that contribute to varied pricing tiers for advanced maintenance services and automated machinery. This influences total cost of ownership calculations for operators.
Pricing Analysis
Warranty and service bundling significantly influence the perceived value of metal shredder machines, moving buyers towards comprehensive lifecycle support. The dominant pricing model is hybrid, combining transactional equipment sales with subscription-based services for predictive maintenance and remote diagnostics. Price differentiation stems from advanced sensor-sorting capabilities and guaranteed parts availability, reflecting performance and reliability. Pricing softness reflects the high initial capital investment barrier for small and medium-sized recycling enterprises, who exhibit the highest price sensitivity, unlike large-scale processors who prioritize total cost of ownership.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke service networks are crucial for delivering metal shredders and ensuring timely parts availability in key markets. Manufacturing of critical shredder components concentrates in Germany, China, and the United States. The supply chain relies heavily on high-grade steel alloys for wear parts and specialized hydraulic systems. A structural risk exists in single-source vulnerability for advanced sensor technologies, while distribution runs through direct sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metal shredder machine market is undergoing a technology-transition phase, moving from basic volume reduction towards intelligent material separation. Advanced sensor-sorting technology is displacing legacy mechanical sorting methods, enhancing scrap purity and value.
For Market Incumbents: Acquire specialized software firms or sensor technology developers to integrate advanced sorting capabilities directly into shredder systems. Incumbents should deepen vertical integration into critical wear part manufacturing to control costs and supply chain resilience against component wear. Expanding global service networks and offering IoT-enabled predictive maintenance services can counter margin pressures from high operational costs. This strategy reinforces market leadership against new entrants focusing on niche applications like e-waste processing.
For New Entrants and Emerging Players: Small and medium-sized recycling enterprises, often constrained by high capital investment, represent a significant underserved buyer archetype. New entrants should target the mobile shredder segment, offering versatile units for on-site processing at demolition projects and remote scrap collection points. Specializing in e-waste processing provides another white-space opportunity, focusing on efficient liberation of precious metals. Go-to-market strategies should include flexible financing options like lease-to-own models, lowering entry barriers for these operators.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized shredder producers possessing strong intellectual property in sensor-sorting technology, given the global regulatory pivot towards a circular economy. The market exhibits long-term viability, driven by non-negotiable demand for scrap processing infrastructure over the coming decade. Acquisition targets should include niche technology providers in e-waste processing or regional players with robust service networks. A key signal to watch is the acceleration of M&A activity within the sensor-sorting and predictive maintenance solution providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-driven Sensor Sorting R&D | Enhances scrap purity, directly boosting recycled commodity value and meeting regulatory demands. |
| Expand Mobile Shredder Product Lines | Addresses on-site processing needs for construction debris and automotive dismantling, reducing logistics costs. |
| Develop E-Waste Specific Shredding Solutions | Unlocks new revenue streams by efficiently recovering valuable precious metals from complex electronics. |
| Offer IoT-Enabled Predictive Maintenance Services | Improves operational uptime for customers and creates recurring revenue streams for manufacturers. |
| Strengthen Component Vertical Integration | Ensures supply chain resilience and cost control for critical wear parts amidst market volatility. |
Research Approach
EU's Circular Economy Action Plan documents, China's dual carbon goals policy papers, and EPA regulations formed the secondary backbone for this market analysis. Primary interviews with plant engineers, procurement leads at steel mills, and shredder equipment manufacturers' R&D directors provided critical insights. This approach combined qualitative expert perspectives with quantitative data validation. Bottom-up market sizing and top-down revenue analysis were triangulated to ensure data accuracy and robustness.
A comprehensive bottom-up and top-down analytical framework was applied to project market growth across the analysis window. The market was segmented by product type, technology, application, end user, and key industrial hubs. Compound annual growth rates were derived from historical trends, projected demand, and regulatory impact assessments. Key industry-specific forecast inputs included global scrap metal generation rates and planned electric arc furnace capacity expansions.
Revisions become necessary when significant shifts in global trade policies or unforeseen technological breakthroughs in material separation materialize. Geopolitical instability affecting raw material supply and rapid changes in environmental regulations represent key risk factors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Racking Systems Market
Material Handling Equipment
Air Hoist Market
Material Handling Equipment
Global Dewatering Equipment Market
Material Handling Equipment
Vertical Reciprocating Conveyor Market
Material Handling Equipment
Material Handling Equipment Market
Material Handling Equipment
Industrial Pulley Market
Material Handling Equipment
Compactor Market
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
Sorting Machines Market
Material Handling Equipment
Rotating Fork Clamp Market
Material Handling Equipment
Warehouse Freight Elevators Market
Material Handling Equipment
Material Handling Monorails Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Ball Screw Support Unit Market
Material Handling Equipment
Pallet Truck Market