
 Industrial Jacks Market | 2026-2036
Industrial Jacks Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Jacks Market Foresight
The industrial distribution channel is fragmenting as regional hydraulic specialists and direct-to-fleet operators erode traditional distributor margins. Enerpac leverages its integrated manufacturing footprint to control specification-grade channels for heavy-capacity systems. Snap-on Incorporated anchors the automotive repair segment through captive dealer networks that bundle diagnostic and lifting equipment. Sunex Tools Inc. competes on portable jack portfolios aimed at mobile service technicians and independent shops.
Industrial jacks are mechanical, hydraulic, pneumatic, or electromechanical devices designed to raise, lower, or position loads ranging from one to twenty tons, typically incorporating screw mechanisms, ram cylinders, or motorized drive systems with hardened steel construction and safety overload valves. Their primary purpose centers on controlled elevation of heavy machinery, vehicles, and materials in environments where precision and operator safety are non-negotiable. Hydraulic jacks dominate the product type landscape due to superior power density and reliability in continuous-duty manufacturing environments, while electric jacks represent the fastest-expanding segment as facilities electrify material handling workflows to meet carbon reduction targets. Among end users, manufacturing facilities command the largest installed base, though shipping docks are emerging as a concentrated margin pool driven by e-commerce fulfillment center expansion and container throughput growth.
OSHA workplace safety regulations and ANSI load-rating standards govern jack design, testing protocols, and operator training requirements across United States industrial sites, directly shaping product liability exposure and procurement qualification criteria. The Department of Transportation's vehicle maintenance mandates for commercial fleets further tighten specification compliance for jacks deployed in roadside and depot service applications. Stakeholders must monitor evolving electrification standards and carbon disclosure rules that will increasingly filter equipment procurement decisions toward energy-efficient lifting technologies.
Market Dynamics
Electrification of material handling workflows is compressing replacement cycles across manufacturing facilities as operators retire hydraulic systems ahead of scheduled end-of-life. This technology displacement is reshaping supplier qualification criteria and procurement timelines.
Growth Catalysts
- OSHA lifting standards:Tightened certification requirements for load-bearing equipment are mandating equipment upgrades across United States industrial sites. Facilities must replace non-compliant jacks to maintain operational licenses.
- Reshoring of manufacturing operations:Domestic production expansion in the United States is accelerating capital expenditure on automated lifting infrastructure. New facility construction requires specification-grade jack installations.
- Carbon reduction targets:Electromechanical jack systems are displacing pneumatic alternatives in facilities pursuing energy efficiency mandates. Electrified workflows reduce compressed air dependency and associated emissions.
Market Restraints
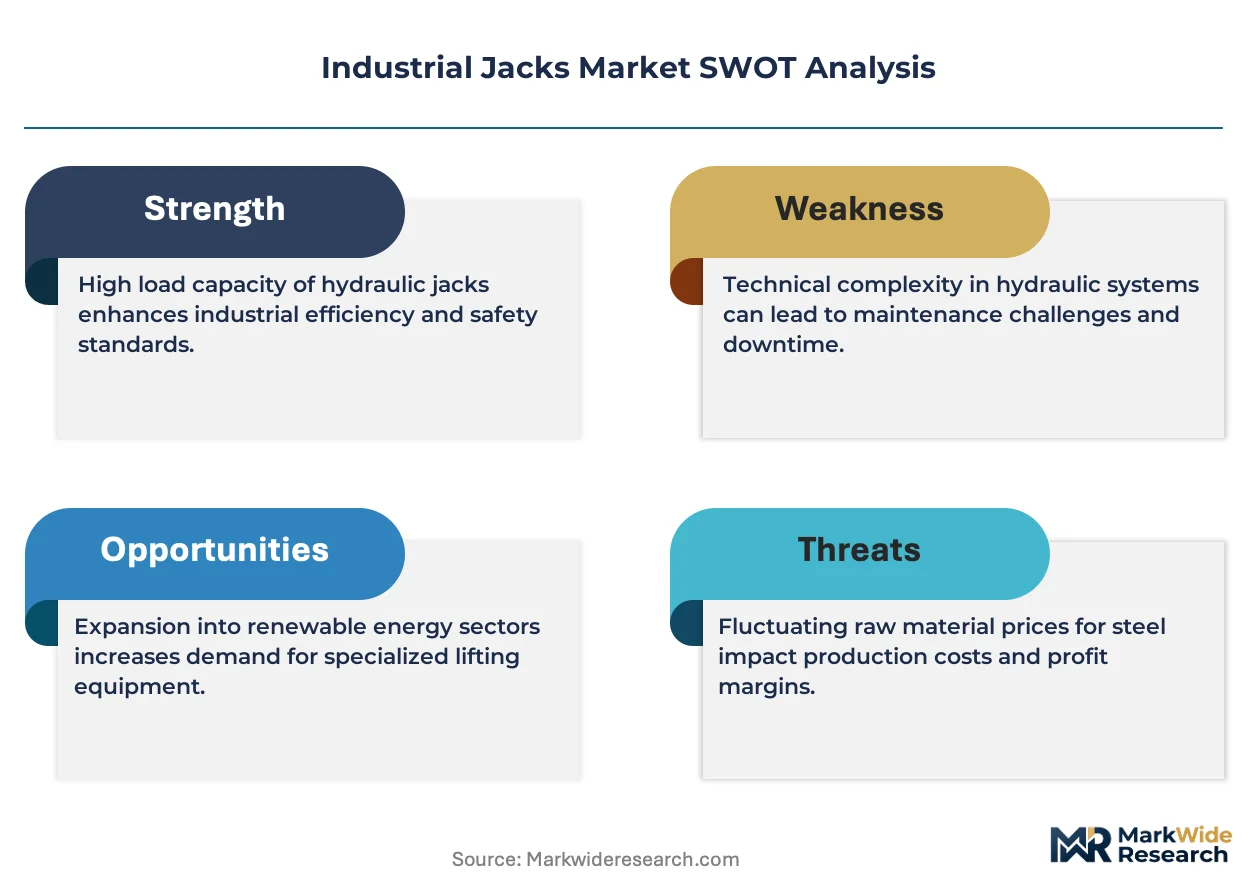
- Hardened steel input volatility:Alloy steel price fluctuations compress margin stability for jack manufacturers. Specialty-grade material sourcing concentrates among limited domestic suppliers.
- Technical limitation in high-tonnage electric systems:Motor thermal management constraints cap electromechanical jack capacity below twenty-ton thresholds. Heavy-capacity applications remain hydraulic-dependent.
- Substitution threat from integrated lifting platforms:Scissor lift tables and permanent elevation systems are capturing stationary maintenance applications. Mobile jack demand concentrates in field service and roadside deployment.
Strategic Opportunities
- Underpenetrated e-commerce fulfillment infrastructure:Shipping dock jack deployment lags behind conveyor and sortation capital investment. Container throughput growth creates concentrated demand for rapid-cycle lifting equipment.
- Regulatory tailwind from IRA clean energy incentives:Electrified material handling equipment qualifies for federal tax credits. Facilities are accelerating electric jack adoption to capture subsidy value.
- Technology convergence of IoT sensors and predictive maintenance:Smart jack systems with embedded load monitoring enable condition-based service scheduling. Fleet operators are piloting connected lifting equipment for uptime optimization.
Industry Challenges
- Certification timeline compression:ANSI load-rating testing protocols require extended third-party validation cycles. Product launch schedules face delays from backlog at accredited laboratories.
- Integration complexity with legacy hydraulic infrastructure:Mixed-fleet facilities struggle to standardize maintenance protocols across pneumatic, hydraulic, and electromechanical systems. Technician training requirements multiply with technology diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Jacks Market |
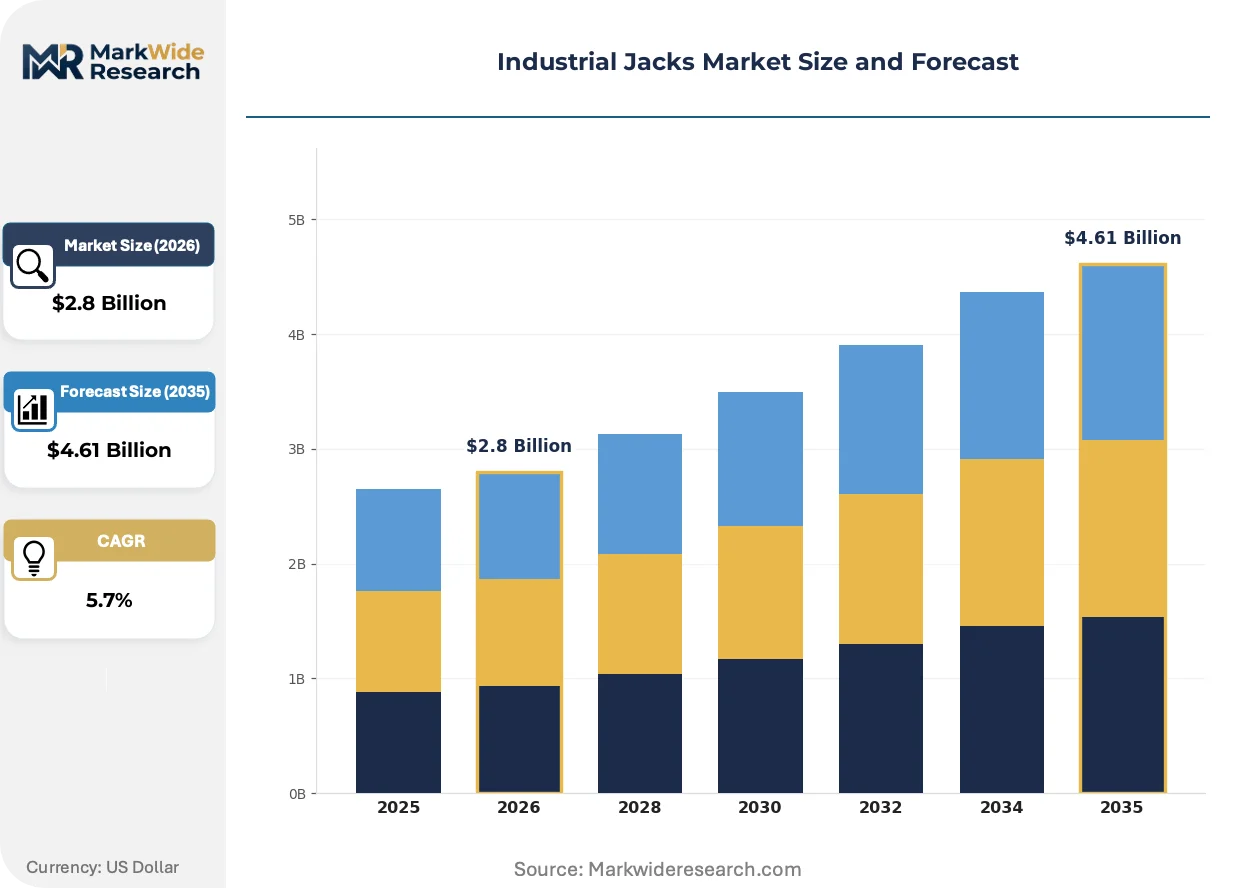
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Jacks, Pneumatic Jacks, Mechanical Jacks, Electric Jacks End User: Manufacturing Facilities, Shipping Docks, Automotive Repair Shops, Construction Sites Capacity: 1 Ton, 5 Ton, 10 Ton, 20 Ton Application: Heavy Lifting, Vehicle Maintenance, Equipment Positioning, Material Handling |
| Companies Covered | Enerpac, Snap-on Incorporated, Sunex Tools Inc., Shinn Fu Company of America, Norco Industries, Hi-Force, Holmatro, Metro Hydraulic Jack Co., Torin Jacks Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Jacks Market Shifts & Advancements
Digitalization of equipment monitoring is redefining service relationships between jack manufacturers and fleet operators. Predictive capabilities are shifting revenue models from transactional sales toward performance-based contracts.
Electromechanical screw jack systems with integrated position feedback are virtualizing the traditional maintenance schedule. Automotive assembly plants are deploying these units for precision chassis positioning. Real-time stroke monitoring eliminates calendar-based inspection intervals and compresses total cost of ownership calculations for procurement teams.
OSHA workplace safety regulations are mandating documented operator training for powered lifting equipment. Compliance documentation requirements are extending sales cycles but locking in incumbent supplier relationships. Heavy-capacity system vendors are bundling certification programs to accelerate specification approval.
Fleet operators are consolidating vendor relationships to reduce qualification overhead. Multi-site manufacturers are standardizing on single-source jack specifications across distributed facilities. This concentration pattern is most visible in United States commercial vehicle maintenance depots where DOT vehicle maintenance mandates enforce equipment traceability requirements.
Industrial Jacks Market Segmentation
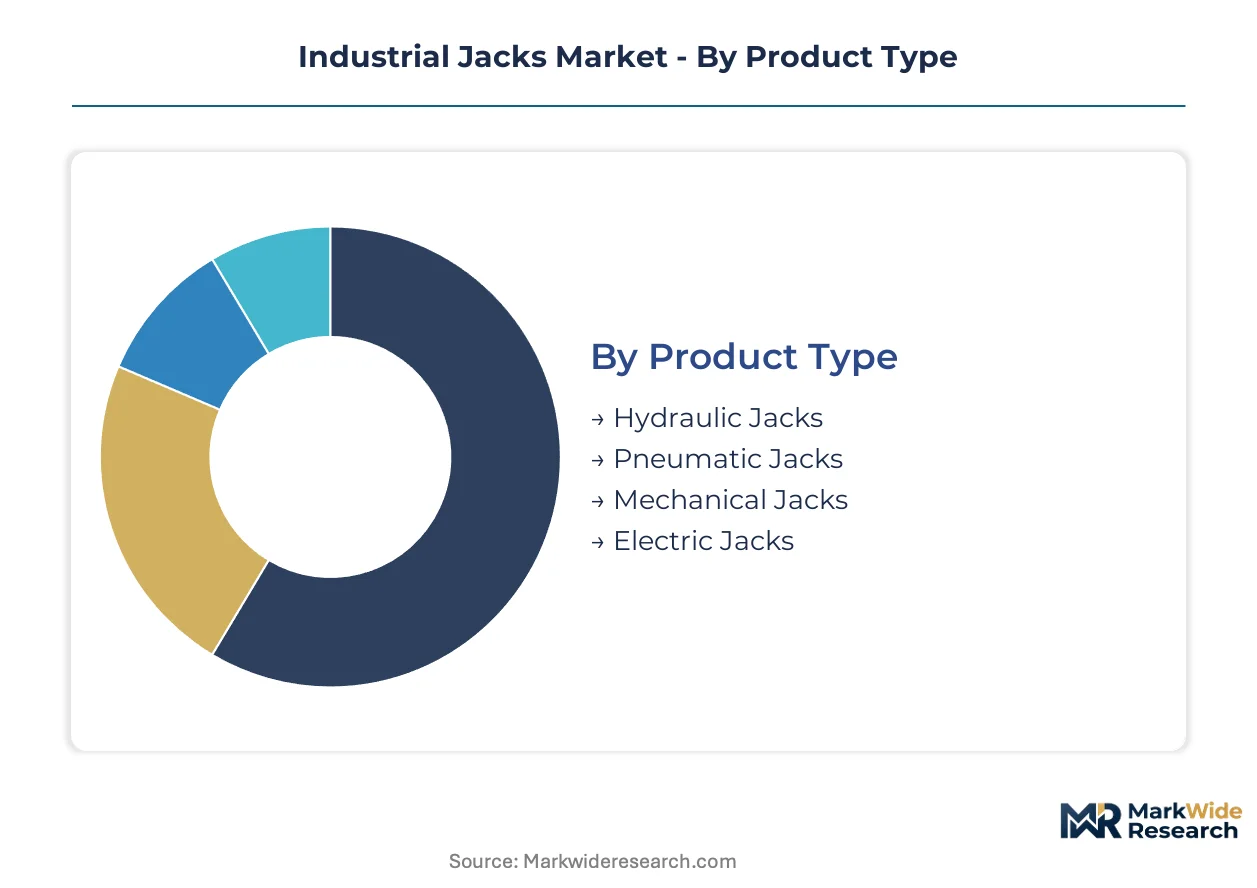
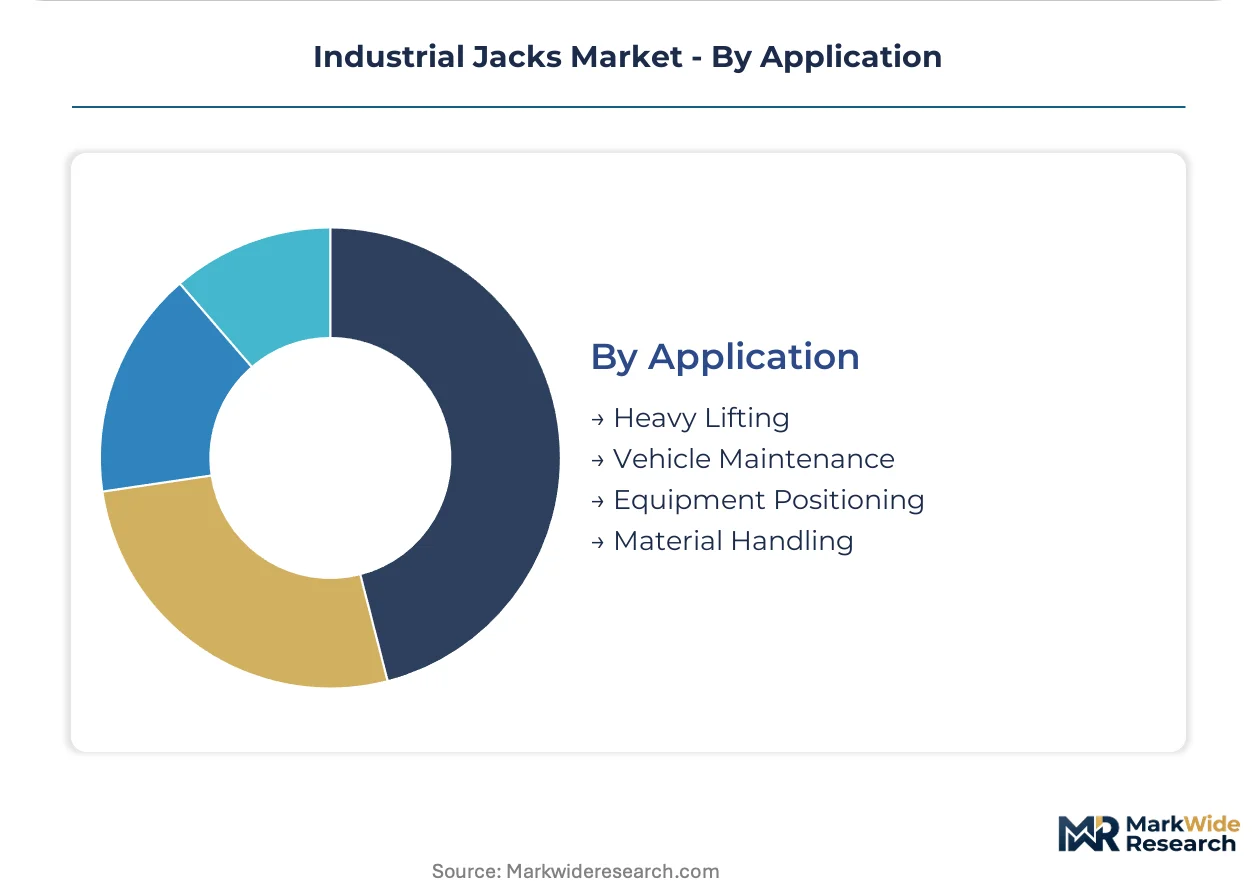
Industrial jack procurement varies sharply by operational context, with specification-grade systems commanding premium positioning in continuous-duty manufacturing while portable units compete on field-service mobility. Understanding segment boundaries clarifies where technology substitution disrupts incumbent suppliers versus where legacy hydraulic architectures retain defensive moats.
Product Type:
Power source selection traces directly to duty cycle intensity and facility electrification roadmap maturity.
- Hydraulic Jacks:Ram-cylinder architectures deliver superior power density for continuous-load manufacturing environments. Demand concentrates in heavy-capacity systems above ten tons where electromechanical thermal constraints persist, particularly across United States automotive stamping plants and metal fabrication facilities facing OSHA lifting standard compliance deadlines.
- Electric Jacks:Brushless motor and ball-screw mechanisms enable precise position feedback with zero hydraulic fluid maintenance. United States warehouse operators pursuing IRA clean energy incentives are accelerating displacement of pneumatic alternatives, though motor thermal management caps practical capacity below twenty-ton thresholds.
- Pneumatic Jacks:Compressed-air systems retain installed base in legacy facilities with captive compressor infrastructure.
- Mechanical Jacks:Screw-jack simplicity supports extreme environments where power source reliability is uncertain.
Established volume favors hydraulic architectures; emerging adoption favors electric systems.
End User:
Facility capital intensity and regulatory exposure shape specification requirements and vendor qualification barriers.
- Manufacturing Facilities:Automated production lines demand synchronized lifting arrays with programmable stroke control. United States reshoring projects are specifying electromechanical systems for energy efficiency documentation, while OSHA workplace safety regulations mandate documented operator certification for powered equipment.
- Shipping Docks:Container throughput velocity requires rapid-cycle equipment with minimal dwell time. E-commerce fulfillment center expansion across United States distribution corridors is outpacing conveyor capital investment, creating concentrated demand gaps for mobile jack deployment.
- Automotive Repair Shops:DOT vehicle maintenance mandates enforce equipment traceability for commercial fleet service.
- Construction Sites:Harsh-environment durability prioritizes mechanical simplicity over precision features.
Procurement scale favors manufacturing facilities; margin expansion favors shipping dock operators.
Capacity:
Load rating determines power source feasibility and directly governs regulatory testing protocol intensity.
- 20 Ton:Heavy machinery installation and industrial press maintenance require hardened alloy construction with safety overload valves. United States infrastructure renewal projects are accelerating replacement cycles for aging high-capacity systems, though ANSI load-rating certification backlogs extend procurement timelines.
- 10 Ton:Mid-range versatility spans manufacturing and commercial vehicle applications with balanced mobility.
- 5 Ton:Light industrial and workshop deployment favors portable configurations.
- 1 Ton:Bench-scale positioning and assembly line integration emphasize precision over power.
Specification-grade revenue concentrates at twenty-ton capacity; unit volume scales at five-ton ratings.
Application:
Functional use case dictates precision requirements, duty cycle expectations, and integration complexity with adjacent material handling systems.
- Heavy Lifting:Machinery relocation and press die changeover demand synchronized multi-point lifting with load equalization. United States metal forming facilities are deploying IoT-enabled jack arrays for predictive maintenance scheduling, converting capital equipment into performance-based service relationships.
- Vehicle Maintenance:Commercial fleet depots require rapid deployment with documented safety compliance.
- Equipment Positioning:Assembly line integration emphasizes repeatability and programmable stroke limits.
- Material Handling:General-purpose mobility competes with integrated scissor lift alternatives in stationary applications.
Technology convergence favors heavy lifting applications; substitution pressure weighs on material handling deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement teams command specification-grade premiums that German and Chinese fabricators cannot replicate at volume. This pricing-power asymmetry reflects divergent regulatory stringency and reshoring capital intensity across manufacturing corridors.
United States
OSHA workplace safety regulations and DOT vehicle maintenance mandates enforce equipment traceability across commercial fleet depots. The Infrastructure Investment and Jobs Act accelerates capital deployment toward automated lifting systems in metal forming facilities. Houston-Galveston petrochemical clusters and Detroit-Warren automotive corridors drive heavy-capacity jack replacement cycles.
Germany
Automotive stamping plants and industrial press manufacturers sustain demand for synchronized multi-point lifting arrays. CE marking requirements and EU Green Deal carbon disclosure rules filter procurement toward electromechanical alternatives. Stuttgart industrial zone and Ruhr Valley manufacturing belts concentrate specification-grade system deployment.
China
Dual carbon goals and MIIT industrial upgrading directives compress replacement cycles for pneumatic systems in coastal manufacturing zones. GB standards compliance and SAMR quality supervision tighten certification requirements for export-oriented fabricators. Yangtze River Delta and Pearl River Delta logistics hubs drive container throughput equipment demand.
Japan
Automotive assembly precision requirements and METI energy efficiency targets accelerate electromechanical jack adoption in chassis positioning applications. JIS standards and PMDA-equivalent industrial safety protocols govern load-rating verification. Nagoya industrial corridor and Osaka-Kobe manufacturing clusters anchor precision lifting system demand.
India
PLI scheme incentives for manufacturing expansion and BIS certification mandates reshape procurement qualification criteria for domestic facilities. DGFT import substitution policies concentrate demand on locally fabricated systems. Gujarat industrial corridor and Tamil Nadu automotive clusters drive mid-capacity equipment deployment.
Industrial Jacks Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream of final assembly relationships. The vendor base organizes around three structural tiers: specification-grade system houses with captive distribution, volume fabricators serving fleet operators through direct channels, and regional hydraulic specialists competing on service proximity. Strategic moves concentrate on backward integration into alloy steel sourcing and technology licensing for electromechanical architectures.
Within the specification-grade tier, Enerpac anchors heavy-capacity system positioning through integrated manufacturing footprints. Snap-on Incorporated and Sunex Tools Inc. occupy distinct mobility-focused segments, with the former leveraging captive dealer networks and the latter targeting portable configurations for independent service technicians. These three entities exemplify how channel control and application specialization determine margin capture.
| Leading Market Players |
|---|
| Enerpac |
| Snap-on Incorporated |
| Sunex Tools Inc. |
| Shinn Fu Company of America |
| Norco Industries |
| Hi-Force |
| Holmatro |
| Metro Hydraulic Jack Co. |
| Torin Jacks Inc. |
| Others |
Supply & Pricing Matrix
Yangtze River Delta alloy steel foundries anchor global jack component supply, with their capacity utilization rates directly transmitting into specification-grade pricing power for heavy-capacity system vendors. Hardened steel input volatility compresses margin stability when mill order backlogs extend, forcing fabricators to either absorb cost spikes or accelerate pass-through mechanisms to fleet operators.
Pricing Analysis
Configured-to-order pricing for twenty-ton synchronized lifting arrays commands spreads exceeding standard five-ton portable units by certification tier and alloy grade. Three-tier pricing structure across premium, standard, and economy levels reflects ANSI load-rating validation depth and OEM traceability documentation. Cost compression in mid-capacity electric systems intensifies because motor thermal management R&D expenses concentrate among limited qualified suppliers. Fleet operators at commercial vehicle depots exhibit highest price sensitivity, while automated manufacturing facilities prioritize specification compliance over unit economics.
Supply Chain Analysis
Alloy steel feedstock draws from United States, Germany, and China, with specialty-grade hardened material concentrating among domestic suppliers serving OSHA-regulated end markets. Ram cylinder seals, ball-screw mechanisms, and brushless motor assemblies rest on single-source vulnerability for electromechanical architectures. Tariff exposure on Chinese steel inputs threatens margin stability for volume fabricators. Distribution runs through captive dealer networks for automotive repair segments and direct specification channels for manufacturing facility procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance service contracts are expanding faster than hardware unit sales as fleet operators convert capital expenditure into performance-based relationships. IoT-enabled jack arrays with embedded load monitoring create recurring-revenue streams that outpace transactional equipment margins.
For Market Incumbents: Pre-empt substitution threats from integrated scissor lift platforms by bundling certification programs with specification-grade heavy-capacity systems. Backward integration into captive alloy steel sourcing defends margin position against hardened steel input volatility. Channel control through integrated manufacturing footprints locks in automotive stamping plant relationships.
For New Entrants and Emerging Players: Establish a beachhead in shipping dock rapid-cycle equipment where e-commerce fulfillment center expansion outpaces conveyor capital investment. Portable electric jack configurations for mobile service technicians represent the most penetrable white space. Direct-to-fleet operator channels bypass traditional distributor qualification overhead.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electromechanical system vendors with IoT sensor integration and predictive maintenance platforms. Long-term viability over a five-to-ten year window favors targets with captive specification-grade certification and aftermarket service density. Monitor ANSI load-rating laboratory backlog clearance as an inflection indicator for product launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Steel Sourcing | Captive supply of hardened material insulates margin stability against mill order volatility. |
| IoT Sensor Platform Development | Embedded load monitoring enables predictive maintenance contracts with fleet operators. |
| Certification Program Bundling | OSHA-compliant operator training accelerates specification approval timelines. |
| Direct-to-Fleet Channel Establishment | Bypassing traditional distributors captures margin from commercial vehicle depot procurement. |
| Electromechanical Capacity Expansion | IRA clean energy incentives accelerate electric jack adoption in warehouse electrification. |
Research Methodology
Cross-validation between primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads and secondary sources including customs trade data, SEC filings, and industrial equipment registration databases anchors the qualitative findings. OSHA enforcement records and ANSI certification laboratory disclosures provide regulatory calibration. Bottom-up triangulation across end-user segments converges with top-down value chain analysis.
Calibration against historical replacement cycle patterns and electrification roadmap maturity informs the analytical framework across the projection horizon. Segmentation dimensions span product type, end-user facility category, capacity tier, and application function. CAGRs derive from installed base turnover rates and capital expenditure intensity indices. Electrification subsidy capture rates and carbon disclosure compliance thresholds serve as industry-specific forecast inputs.
Stress conditions across alloy steel price bands, ANSI certification timeline compression, and substitution elasticity from integrated lifting platforms were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reshoring capital deployment velocity and IRA incentive permanence. Material shifts in OSHA enforcement stringency or motor thermal management breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Telescopic Boom Forklift Truck Market
Material Handling Equipment
Europe Conveyors Market
Material Handling Equipment
Heavy Hex Nuts Market
Material Handling Equipment
Robotic Palletizers and De-Palletizers Market
Material Handling Equipment
Stacker Market
Material Handling Equipment
Gravity Conveyor Market
Material Handling Equipment
Carry Deck Crane Market
Material Handling Equipment
Rough Terrain Lift Truck Market
Material Handling Equipment
Fork Lift Attachments Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
High-Performance Seals Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Crawler Crane Market
Material Handling Equipment
Europe Conveyor Belt Market
Material Handling Equipment
High Pressure Grease Hose Market
Material Handling Equipment
Global Industrial Lifting Equipment Market