
 Coal Handling Equipment Market | 2026-2036
Coal Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Coal Handling Equipment Market Analysis
Australian mining contractors is restructuring procurement patterns for heavy-duty conveyor systems. Caterpillar Inc. leverages its dealer network density across Queensland and New South Wales. Thyssenkrupp AG sustains engineering depth in high-capacity crusher technology. TAKRAF dominates bucket-wheel stacker-reclaimer installations for export terminal expansions.
Coal handling equipment encompasses the mechanical and automated systems engineered to receive, transport, crush, screen, and store coal at grades ranging from sub-bituminous to anthracite, with conveyor belts typically rated for capacities exceeding 10,000 tonnes per hour in large thermal power applications. The category serves power generation, mining, cement production, and steel manufacturing facilities by ensuring continuous fuel feed and minimizing fugitive dust emissions. Conveyors anchors the product mix due to their ubiquity across every handling stage from pit to port. Automation is displacing manual control rooms as mines pursue remote operations. Dust control technology occupies thinner margin pools despite tightening workplace exposure limits.
OSHA enforces permissible exposure limits for respirable coal dust in US operations, while India's BIS certifies conveyor belt fire-resistance standards under IS 1891. The EU's ATEX directives constrain equipment design for explosive atmospheres in European port terminals. Stakeholders must weigh refurbishment cycles against full automation retrofits as regulatory thresholds for particulate emissions tighten without uniform international alignment.
Market Dynamics
India's Bureau of Indian Standards is forcing a wholesale replacement cycle for conveyor safety equipment through mandatory fire-resistance certifications under IS 1891, compelling power utilities to accelerate capital deployment despite flat electricity demand growth.
Growth Catalysts
- IS 1891 Conveyor Certification:India's BIS mandates stricter fire-resistance standards for belt installations, triggering equipment replacement at thermal power stations across the National Capital Region and Maharashtra.
- Remote Operations Technology:Mining operators in Australia's Bowen Basin are automating control rooms to reduce on-site personnel exposure, driving demand for integrated sensor networks and autonomous stacker-reclaimer systems.
- Export Terminal Expansions:Port infrastructure projects in Queensland require high-capacity bucket-wheel equipment to handle metallurgical coal volumes destined for Asian steel mills.
Market Restraints
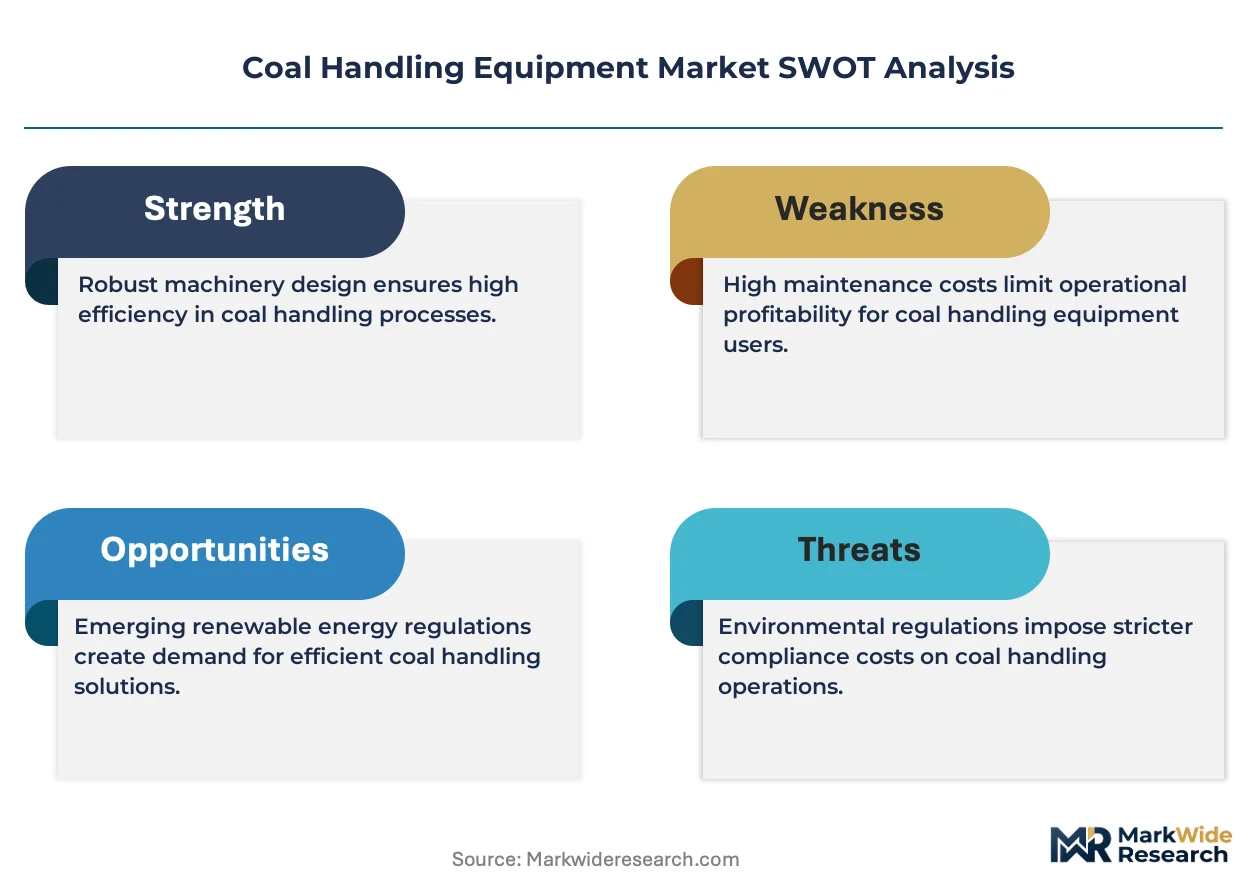
- Steel Input Volatility:Structural steel prices fluctuate with iron ore and scrap markets, compressing fabrication margins for conveyor frame manufacturers in Germany and Poland.
- Supply Concentration Risk:High-tensile belting production concentrates among three specialized compounders in East Asia, creating vulnerability to regional logistics disruptions.
- Technical Limitation:Existing dust suppression systems struggle to meet sub-1.5 mg/m³ respirable particulate thresholds in high-wind port environments without excessive water consumption.
Strategic Opportunities
- Underpenetrated Mining Belt:Indonesia's Kalimantan coal corridor lacks modern continuous handling infrastructure, presenting greenfield installation potential for integrated crushing-conveying systems.
- EU ATEX Compliance Services:European port terminals require explosion-proof equipment certification under ATEX directives, creating aftermarket retrofit and consulting revenue streams.
- Digital Twin Convergence:Physics-based simulation platforms are converging with real-time vibration monitoring to enable predictive maintenance contracts at Australian export facilities.
Industry Challenges
- Automation Skill Gap:Mining maintenance crews lack PLC programming and industrial network troubleshooting capabilities required for autonomous conveyor diagnostics.
- Legacy Integration Complexity:Brownfield power plants struggle to retrofit digital control architectures onto electromechanical interlock systems installed in the 1980s.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coal Handling Equipment Market |
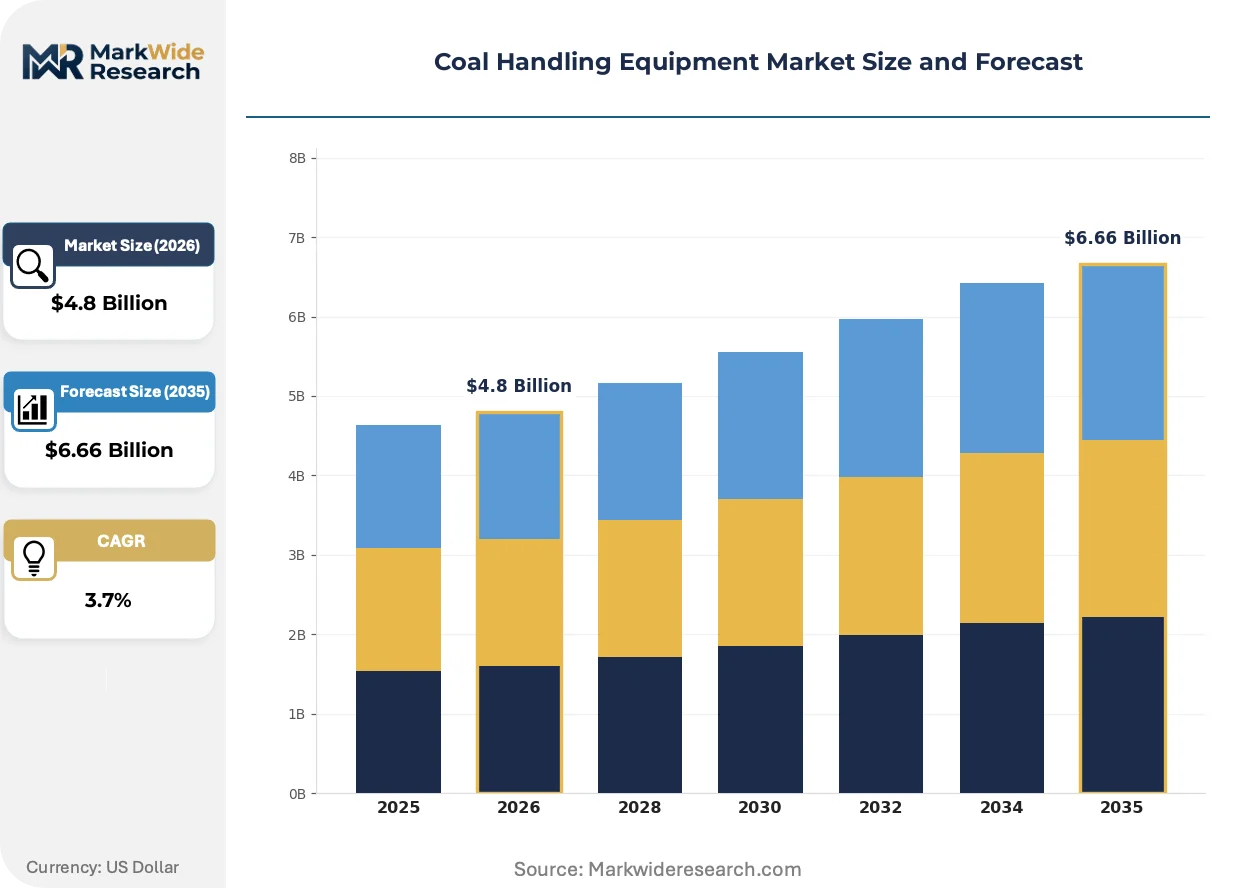
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyors, Crushers, Stackers, Screeners Application: Power Generation, Mining, Cement Production, Steel Manufacturing End User: Utilities, Industrial Plants, Mining Companies, Cement Firms Technology: Automation, Monitoring Systems, Dust Control, Material Processing |
| Companies Covered | FLSmidth & Co. A/S, Metso Corporation, Sandvik AB, Caterpillar Inc., Thyssenkrupp AG, TAKRAF, Elecon Engineering, FEECO International, Inc., Larsen & Toubro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coal Handling Equipment Market Emerging Trajectories
Automation architectures are displacing manual control paradigms across coal handling infrastructure, while regulatory pressure on particulate emissions accelerates filtration technology refresh cycles. Equipment vendors now compete on integrated system performance rather than component specifications.
Condition-based monitoring using distributed fiber-optic sensing is converging with edge computing platforms to enable real-time belt health assessment. Major mining contractors in Western Australia are deploying these systems at greenfield sites to eliminate scheduled shutdown intervals. This convergence is compressing maintenance contract structures toward availability-guarantee pricing rather than time-and-material billing.
OSHA's respirable dust enforcement in Appalachian mining operations is mandating continuous personal exposure monitoring tied to ventilation controls. Equipment suppliers must now certify integrated dust capture performance at the point of material transfer. Underground longwall operations in West Virginia and Kentucky are retrofitting enclosed conveyor loading stations to meet the stricter permissible exposure limits.
Buying committees at Indian state power utilities are consolidating vendor qualification lists to three approved suppliers per equipment category, displacing fragmented procurement across regional tendering offices. This concentration demands turnkey performance contracts with penalty clauses for downtime exceeding contracted thresholds. The shift is most visible at NTPC and state genco installations in Uttar Pradesh and Madhya Pradesh.
Coal Handling Equipment Market Segmentation
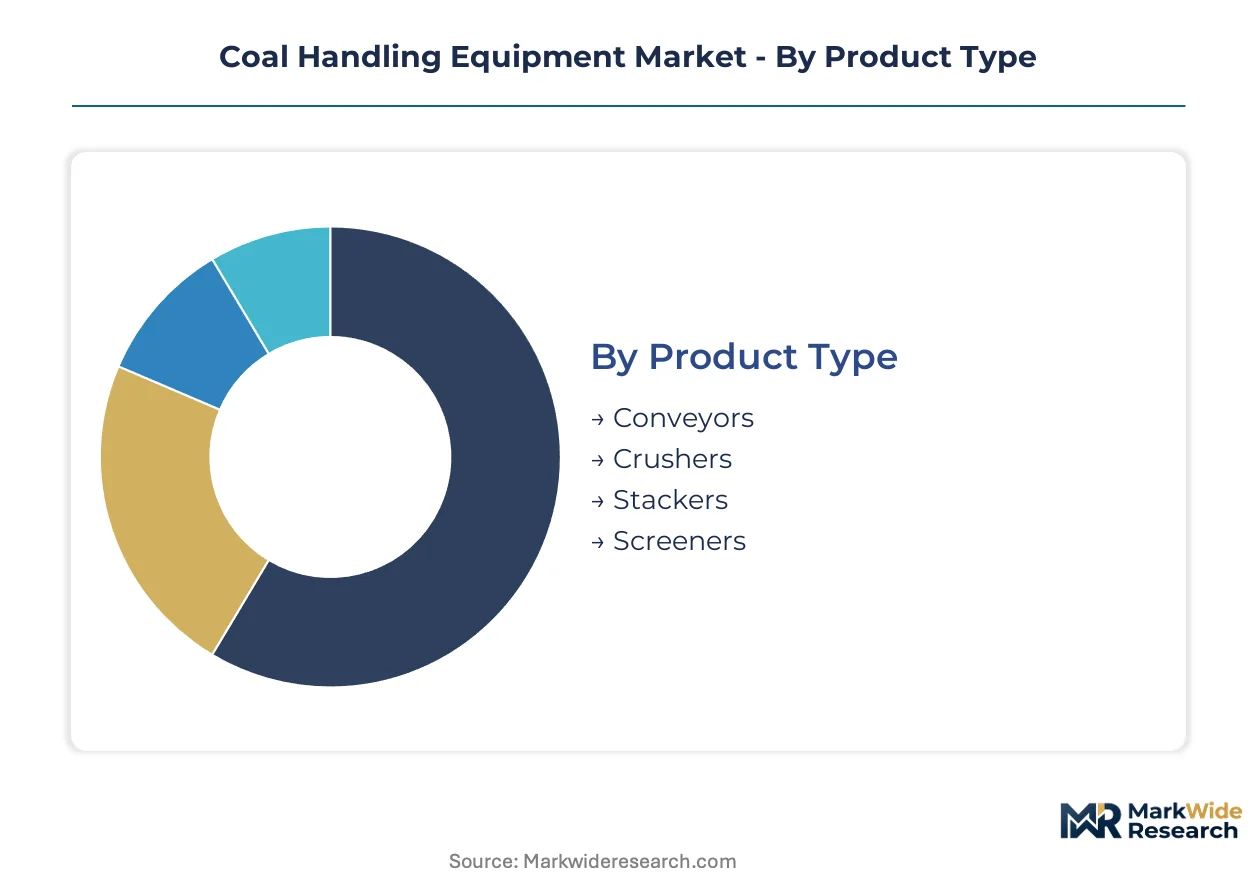
Coal handling equipment procurement varies sharply across operational contexts, from high-volume continuous mining to intermittent cement kiln feeding. Equipment specification, automation intensity, and dust control requirements diverge based on material throughput, regulatory exposure, and labor cost structures.
Product Type:
Buyers differentiate primarily by throughput capacity and integration complexity rather than component cost alone.
- Conveyors:Belt systems rated for 10,000+ tonnes per hour dominate large thermal power installations, with fire-resistant belting certified to India's IS 1891 now mandatory across National Capital Region utilities. Australian Bowen Basin miners are automating drive stations to enable remote operation from centralized control hubs.
- Crushers:High-capacity rotary and hammer configurations from Thyssenkrupp AG process run-of-mine coal to consistent sizing for pulverized fuel boilers. Demand concentrates at Indonesian Kalimantan greenfield projects lacking modern continuous handling infrastructure.
- Stackers:Bucket-wheel and cantilever designs manage stockpile geometry at export terminals, with TAKRAF installations handling metallurgical coal volumes for Asian steel mill destinations.
- Screeners:Vibrating and roller configurations separate fines from lump coal ahead of coking or combustion processes.
Conveyors lead volumes today; crushers are gaining share fastest in greenfield mining corridors.
Application:
Operational duty cycles and regulatory exposure create distinct procurement patterns across end-use sectors.
- Power Generation:Thermal utilities require 24/7 reliability with redundancy for base-load electricity supply. India's state gencos in Uttar Pradesh and Madhya Pradesh are consolidating vendor lists to three approved suppliers per category with penalty clauses for excessive downtime.
- Mining:Surface and underground extraction operations prioritize autonomous control to reduce on-site personnel exposure. Western Australian contractors deploy fiber-optic sensing with edge computing to eliminate scheduled shutdown intervals.
- Cement Production:Intermittent kiln feeding demands flexible material handling with lower capital intensity than power or mining installations.
- Steel Manufacturing:Metallurgical coal handling at coke ovens requires enclosed transfer points to meet OSHA respirable dust limits in Appalachian operations.
Power generation retains the largest installed base; mining applications are expanding most quickly through automation retrofits.
End User:
Capital deployment authority and maintenance capability shape vendor relationships more than purchase volume alone.
- Utilities:State-owned power generators in India operate under centralized procurement with turnkey performance contracts. NTPC qualification requirements now demand integrated system responsibility rather than component supply.
- Industrial Plants:Captive power and process heat users balance fuel flexibility against handling system standardization.
- Mining Companies:Australian contractors restructuring procurement patterns seek availability-guarantee pricing over traditional time-and-material maintenance structures.
- Cement Firms:Clinker production facilities prioritize dust suppression technology to meet tightening workplace exposure limits without excessive water consumption.
Utilities dominate current replacement cycles; mining companies are driving the steepest technology upgrade trajectory.
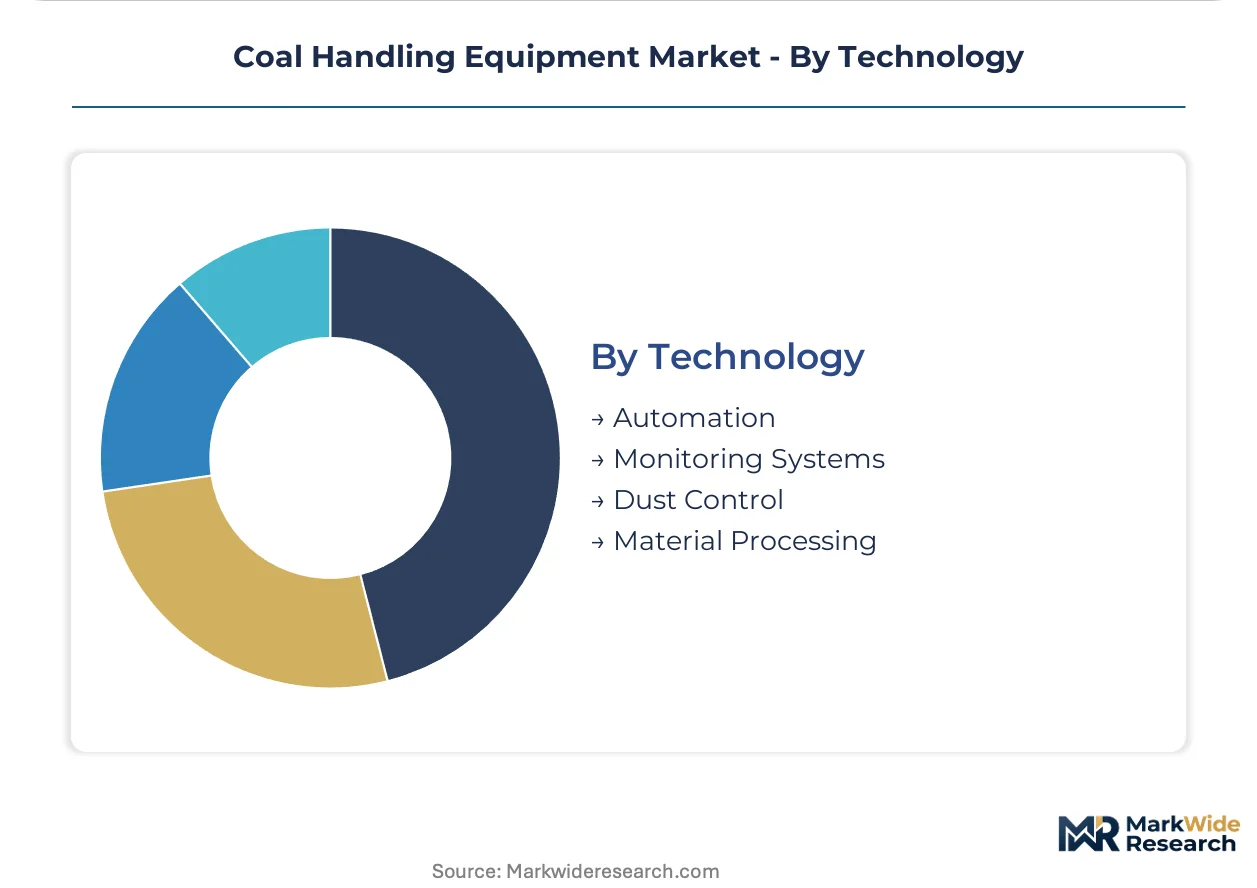
Technology:
Integration depth and data architecture differentiate competitive offerings beyond mechanical reliability.
- Automation:PLC-based control systems and autonomous stacker-reclaimer operation displace manual control rooms across Australian export facilities. Brownfield Indian power plants struggle to retrofit digital architectures onto 1980s electromechanical interlocks.
- Monitoring Systems:Distributed fiber-optic sensing converges with physics-based digital twins for predictive maintenance contracts.
- Dust Control:Enclosed transfer stations and point-source capture systems address OSHA enforcement in West Virginia and Kentucky longwall operations. High-wind port environments face technical limitations achieving sub-1.5 mg/m³ thresholds.
- Material Processing:Integrated crushing-conveying systems reduce truck haulage in underpenetrated Indonesian mining belts.
Automation commands premium positioning today; monitoring systems are climbing the fastest as maintenance contracts restructure around availability guarantees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing fabrication capacity toward jurisdictions with lower compliance burdens for dust control and fire-safety certification, while demand concentrates in mining corridors with export-oriented infrastructure requirements.
Australia
Bowen Basin mining contractors are automating control rooms to reduce on-site personnel exposure at metallurgical coal operations. The country's national mining safety regulator enforces continuous personal exposure monitoring for respirable dust. Queensland's export terminals require high-capacity bucket-wheel equipment for volumes destined to Asian steel mills.
India
State power utilities in Uttar Pradesh and Madhya Pradesh are consolidating vendor qualification lists to three approved suppliers per equipment category. BIS mandates stricter conveyor belt fire-resistance standards under IS 1891 across National Capital Region installations. NTPC and state genco facilities are accelerating capital deployment for equipment replacement despite flat electricity demand growth.
United States
Appalachian longwall operations in West Virginia and Kentucky are retrofitting enclosed conveyor loading stations to meet OSHA respirable dust enforcement. The Mine Safety and Health Administration ties ventilation controls to continuous personal exposure monitoring. Underground mining clusters face technical limitations achieving sub-1.5 mg/m³ particulate thresholds without excessive water consumption.
Indonesia
Kalimantan coal corridor operators lack modern continuous handling infrastructure for greenfield project development. The country's national mining ministry oversees environmental compliance for port terminal expansions. Integrated crushing-conveying systems are displacing truck haulage at surface mining operations across East Kalimantan.
Germany
Fabrication margins for conveyor frame manufacturers compress with structural steel price volatility tied to iron ore and scrap markets. The EU's ATEX directives constrain equipment design for explosive atmospheres at European port terminals. Engineering specialists in North Rhine-Westphalia maintain capability depth in high-capacity crusher technology.
Coal Handling Equipment Market Vendor Landscape
German engineering specialists anchor one tier; Australian mining contractors and Indian fabrication houses hold procurement influence through consolidated vendor lists. The vendor structure concentrates around turnkey performance contracts with penalty clauses for downtime exceeding contracted thresholds. Three strategic archetypes dominate: diversified industrial conglomerates with integrated system responsibility, specialized engineering firms with crusher and stacker-reclaimer depth, and regional fabricators serving brownfield retrofit cycles. Competitive moves center on availability-guarantee pricing restructuring and digital twin convergence for predictive maintenance contracts.
Within the diversified industrial tier, Thyssenkrupp AG and Caterpillar Inc. exemplify geographic anchoring strategies—Thyssenkrupp sustaining engineering depth in high-capacity processing equipment, Caterpillar leveraging dealer network density across Queensland and New South Wales. TAKRAF occupies a distinct position in bucket-wheel stacker-reclaimer installations for export terminal expansions. These three represent contrasting archetypes: German engineering conglomerate, US-based mining equipment multinational, and specialized bulk materials handling firm.
| Leading Market Players |
|---|
| FLSmidth & Co. A/S |
| Metso Corporation |
| Sandvik AB |
| Caterpillar Inc. |
| Thyssenkrupp AG |
| TAKRAF |
| Elecon Engineering |
| FEECO International, Inc. |
| Larsen & Toubro |
| Others |
Supply Flow & Price Mechanics
Captive integration into high-tensile belting production anchors supply security for conveyor system OEMs while insulating tier-one suppliers from compounder pricing volatility in East Asia. Australian mining contractors and Indian state utilities leverage this backward control to lock in long-term availability-guarantee contracts.
Pricing Analysis
Distributor margins on replacement belting and consumables compress the effective price realization for component manufacturers serving fragmented regional fabricators. Project-based pricing dominates greenfield installations, with differentiation across fire-resistance certification tiers under India's IS 1891 and Australia's equivalent standards. Cost compression in standard-grade conveyor frames is intensifying because structural steel input volatility from German and Polish mills erodes fabrication margins. Cement producers in developing markets exhibit the highest price sensitivity, while Australian Bowen Basin miners prioritize availability guarantees over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from NTPC and Queensland export terminal operators, bypassing distributor markups for integrated crushing-conveying systems. Manufacturing concentration in Germany, Poland, and East Asian belting compounders creates geographic clustering around engineering expertise and raw material access. The supply chain draws from specialized steel grades, fire-resistant rubber compounds, and precision drive components. Single-source vulnerability in high-tensile belting production presents structural risk, with distribution running through Caterpillar's Queensland dealer network and Thyssenkrupp's direct European engineering channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coal handling equipment market functions as a stable compounder, with regulatory-mandated replacement cycles in India and Australia providing predictable revenue visibility irrespective of commodity price cycles.
For Market Incumbents: Hedge against margin erosion in standard conveyor frames by deepening captive control over fire-resistant belting supply. Accelerate certification investment under India's BIS IS 1891 and EU ATEX directives to displace unqualified regional competitors from consolidated vendor lists at NTPC and state genco facilities.
For New Entrants and Emerging Players: Capture the underpenetrated Indonesian Kalimantan corridor where integrated crushing-conveying systems displace truck haulage at greenfield surface mines. Position through equipment-leasing structures with performance-based payment terms to overcome capital constraints at mid-tier mining contractors.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional fabricators in Germany and Poland lack scale to absorb steel input volatility while meeting tightening fire-safety certification requirements. Target engineering specialists with proven ATEX compliance track records and established relationships with Australian export terminal operators. Watch automation retrofit penetration rates at Indian brownfield power plants as the inflection indicator for maintenance contract restructuring toward availability-guarantee pricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Belting Production | Captive supply of fire-resistant compounds insulates margins from East Asian compounder concentration. |
| ATEX Certification Investment | Explosion-proof equipment approval unlocks European port terminal retrofit contracts under EU directives. |
| Digital Twin Platform Deployment | Physics-based simulation with fiber-optic sensing enables predictive maintenance contracts at Australian facilities. |
| Indonesian Greenfield Partnership | Integrated crushing-conveying systems displace truck haulage in Kalimantan's underpenetrated mining belt. |
| Indian Vendor List Consolidation | Qualification as one of three approved suppliers per category at NTPC secures replacement cycle revenue. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maintenance directors at Australian mining contractors, plant engineers at Indian state power utilities, OEM procurement teams in Germany, aftermarket service heads at conveyor system distributors, and EPC contractors specializing in port terminal expansions. Secondary validation drew from customs and trade data on steel and rubber imports, BIS certification registries, SEC filings of listed equipment manufacturers, and Australian mining safety regulator disclosure databases. Bottom-up equipment shipment tallies and top-down energy sector capital expenditure estimates were triangulated to anchor market sizing.
Historical reference periods spanning the pre-regulatory and post-mandate phases in India established baseline replacement cycle patterns that were projected across the forecast horizon. The analytical framework modeled segmentation across product type, application, end user, and technology integration depth, with CAGRs derived from regression against power generation capacity additions and mining export volume trajectories. Industry-specific inputs included BIS enforcement timelines for IS 1891 compliance and Queensland port terminal expansion schedules.
Steel price volatility, regulatory enforcement delays, and automation adoption rate variability are the dominant revision risks that could compress or extend projected equipment replacement timelines. Forecasts reflect documented assumptions regarding certification mandate adherence and mining labor cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Gantry Crane Market
Material Handling Equipment
Industrial Static Equipment Market
Material Handling Equipment
Telehandler Market
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
Industrial Counterweights Market
Material Handling Equipment
Hoist Sling Chains Assemblies Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Container Handler Market
Material Handling Equipment
Europe Port Equipment Market
Material Handling Equipment
Material Handling Automation Market
Material Handling Equipment
North America Screw Conveyor Market
Material Handling Equipment
Bale Clamp Intensive Market
Material Handling Equipment
Rotary Indexer Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Hydraulic Hose Market
Material Handling Equipment
High-Precision Gear Reducer Market