
 Reach Stacker Market | 2026-2036
Reach Stacker Market Size, Share, and Industry Trends Forecast 2026-2036
Reach Stacker Market Outlook
Maintenance contracts and telemetry-linked service subscriptions is rebalancing revenue streams away from pure equipment sales. Kalmar leverages its port automation software to anchor long-term service agreements with terminal operators. Konecranes competes through crane-to-stacker integration, while SANY extends its position with cost-optimized electric models for Asian port authorities. Liebherr sustains premium positioning through in-house drive system manufacturing.
A reach stacker is a mobile heavy-lift vehicle with a telescopic boom, typically rated for container handling between 10 and 50 tonnes, designed to transport, stack, and load intermodal containers in ports and inland terminals. The machine operates on rubber tires with 360-degree rotation capability, enabling flexible yard layouts without fixed rail infrastructure. Container stacker configurations dominate capital deployment due to terminal density requirements, while electric power sources represent the fastest-expanding segment as port operators face carbon disclosure mandates. Telematics integration concentrates margin pools in aftermarket software and predictive maintenance services rather than hardware alone.
EMA machinery directives and EU F-Gas Regulation shape engine certification and refrigerant requirements for European port equipment procurement. EPA Tier 4 Final standards in the United States enforce equivalent emission controls, while China's MIIT governs new energy vehicle subsidies that accelerate domestic electric reach stacker adoption. Stakeholders must monitor how port authority decarbonization timelines synchronize with OEM electrification roadmaps to avoid stranded diesel assets.
Market Dynamics
Port electrification mandates and EU F-Gas refrigerant phase-downs are forcing terminal operators to accelerate replacement cycles for diesel-powered yard equipment. The collision of emission compliance deadlines with vessel upsizing trends is compressing procurement timelines across major container hubs.
Growth Catalysts
- IMO Carbon Intensity Indicators:Shipping lines face mandatory efficiency ratings that cascade into terminal decarbonization requirements, driving demand for electric reach stackers in Hamburg and Rotterdam port clusters.
- Telematics-anchored service models:Predictive maintenance platforms generate recurring revenue streams that improve OEM margin stability and deepen operator lock-in.
- Vessel capacity expansion:Ultra-large container carriers now exceeding 24,000 TEU require higher-lift-capacity yard equipment to maintain berth productivity.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing dominates in China, exposing European and North American OEMs to raw material bottleneck risks and tariff exposure.
- High-voltage infrastructure retrofit costs:Legacy terminals require electrical grid upgrades and charging station installation that can exceed equipment capital expenditure.
- Skilled technician scarcity:Electric powertrain diagnostics demand competencies distinct from diesel engine repair, constraining service network expansion.
Strategic Opportunities
- India port privatization wave:Adani Ports and DP World India are modernizing container terminals in Mundra and Nhava Sheva, creating demand for cost-optimized electric models.
- Battery-swapping standardization:Interoperable swap protocols could eliminate charging downtime and enable smaller battery pack configurations.
- EU Green Deal port funding:Connecting Europe Facility grants cover up to half of sustainable equipment procurement costs for qualifying terminal operators.
Industry Challenges
- Certification timeline compression:EMA machinery directive updates and EPA Tier 4 Final recertification requirements create parallel approval tracks that delay product launches.
- Interoperability with legacy terminal operating systems:Electric stacker telematics must integrate with decades-old cargo management software without disrupting real-time yard dispatch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reach Stacker Market |
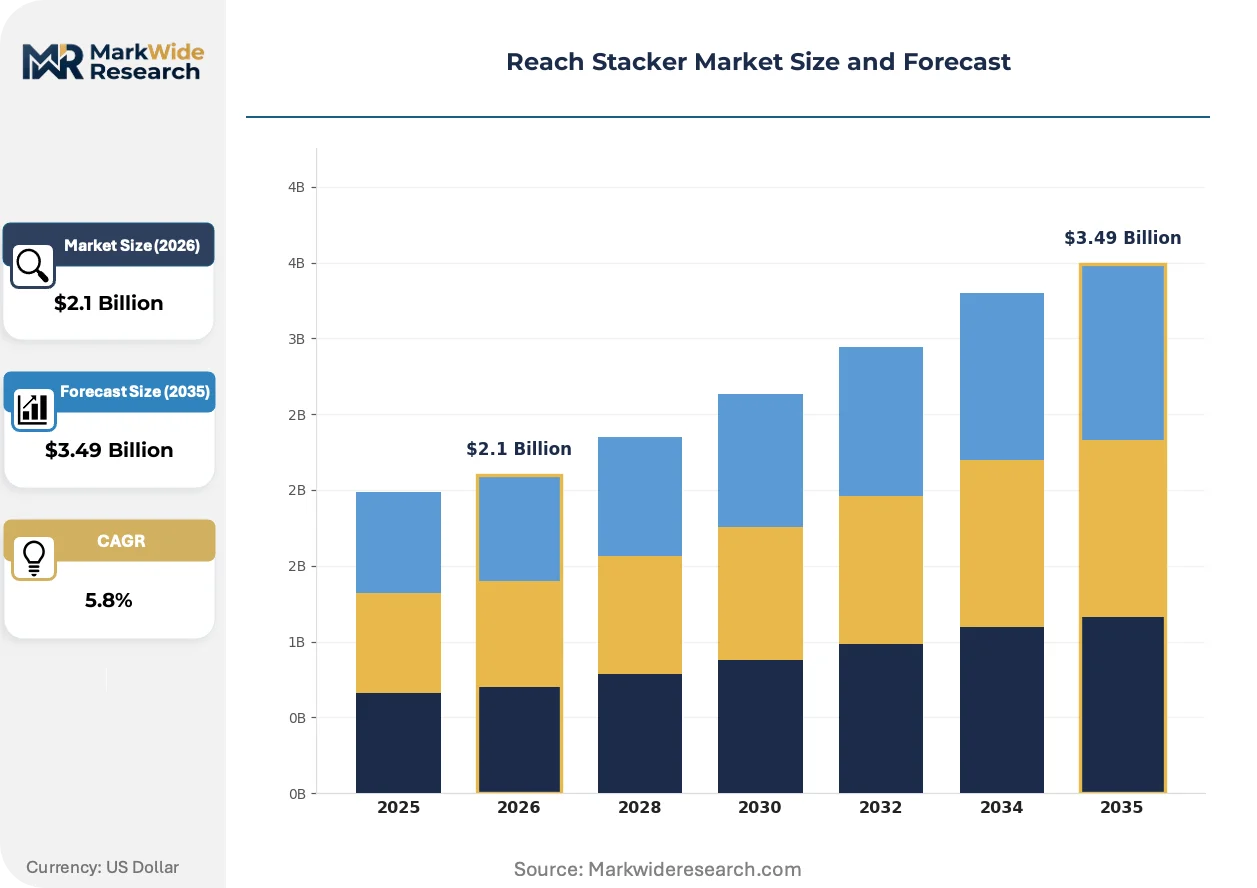
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telehandler, Container Stacker, Forklift, Heavy Lift End User: Shipping Ports, Warehousing, Logistics Providers, Construction Power Source: Diesel, Electric, Hybrid, LPG Technological Feature: Telematics, Stability Control, Automated Operation, Safety Systems |
| Companies Covered | Liebherr, CVS Ferrari, Kalmar, ZPMC, Toyota, Konecranes, SANY, Dalian Forklift, Hyster, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reach Stacker Market Strategic Shifts
Electrification architectures and autonomous navigation modules are converging to redefine yard equipment specifications. Terminal operators now evaluate total cost of ownership across energy, maintenance, and labor dimensions rather than acquisition price alone.
Solid-state battery chemistries are absorbing the high-duty-cycle demands of continuous container handling. Port authorities in Singapore and Los Angeles are piloting 350 kWh pack configurations that eliminate mid-shift charging. The technology is absorbing margin pressure from volatile diesel pricing and stabilizing operating cost forecasts for multi-shift operations.
The EU F-Gas Regulation mandates refrigerant phase-downs for mobile machinery air conditioning systems. Equipment manufacturers must redesign thermal management systems using CO2 or hydrocarbon alternatives. European procurement specifications now exclude conventional HFC-based systems, accelerating R&D expenditure across Kalmar, Konecranes, and Liebherr product lines.
Terminal operators are consolidating vendor relationships to secure outcome-based equipment availability guarantees. Long-term service agreements now bundle hardware, software, and maintenance into per-move pricing. This restructuring is most advanced in Germany and the Netherlands, where port authorities face binding carbon disclosure requirements under CSRD reporting standards.
Reach Stacker Market Segmentation
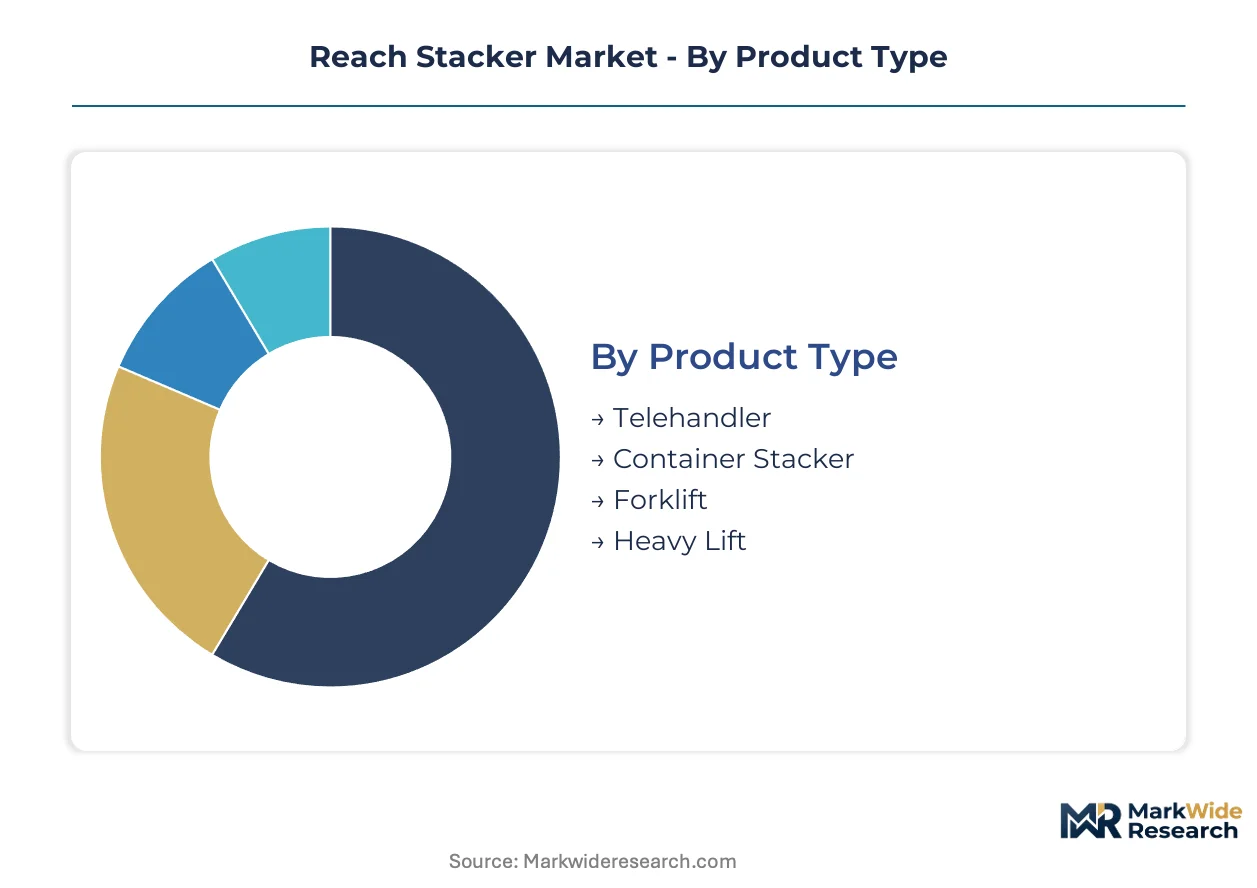
Reach stacker procurement decisions cluster around lifting configuration, operational environment, and compliance architecture. Terminal operators select segments based on berth productivity requirements, emission mandates from port authorities, and integration demands from legacy terminal operating systems.
Product Type:
EMA machinery directives and EPA Tier 4 Final certification requirements apply differentially across lifting configurations, with heavy-lift units facing the most stringent engine recertification timelines.
- Container Stacker:Telescopic boom configurations rated for 40-50 tonne lifts dominate capital deployment at high-density terminals. Hamburg and Rotterdam port clusters drive replacement cycles here as vessel upsizing forces yard equipment modernization.
- Heavy Lift:Specialized units handling 45+ tonne loads serve breakbulk and project cargo terminals. The segment absorbs premium pricing but faces compressed procurement timelines from EU Green Deal port funding deadlines.
- Telehandler:Versatile boom designs with rotating cabs address construction and intermodal yards requiring flexible reach.
- Forklift:Counterbalanced designs for lighter container handling and secondary yard operations.
Container Stacker sits at the top of the volume ranking, with Heavy Lift climbing the fastest.
End User:
Customer procurement authority concentrates with port authorities and global terminal operators who bundle fleet orders across multiple facilities.
- Shipping Ports:Container terminals in Bremerhaven, Singapore, and Los Angeles anchor demand for electrified configurations. Carbon disclosure mandates under CSRD reporting standards force synchronized replacement cycles across European hub ports.
- Logistics Providers:Third-party operators like DP World India and Adani Ports are modernizing inland terminals at Mundra and Nhava Sheva. The segment expands most quickly as port privatization waves unlock infrastructure investment.
- Warehousing:Distribution centers and intermodal facilities with lower duty cycles.
- Construction:Project cargo and temporary yard operations with seasonal demand patterns.
Shipping Ports command the largest installed base, while Logistics Providers gain share fastest.
Power Source:
Emission compliance deadlines and energy cost trajectories are rebalancing procurement specifications away from conventional diesel architectures.
- Electric:Lithium-ion configurations with 350 kWh packs eliminate mid-shift charging at Singapore and Los Angeles pilot terminals. MIIT subsidies in China and EU Green Deal grants accelerate adoption where grid infrastructure supports high-voltage installation.
- Hybrid:Diesel-electric architectures bridge legacy terminals facing retrofit cost constraints. The segment captures demand from operators with compressed procurement timelines who cannot await full electrification.
- Diesel:Conventional powertrains still dominate existing fleets but face stranded asset risk from F-Gas Regulation refrigerant phase-downs and IMO carbon intensity requirements.
- LPG:Transitional fuel for operators seeking emission reductions without electrical infrastructure investment.
Diesel retains the largest installed base, with Electric expanding most quickly.
Technological Feature:
Software-enabled capabilities now determine margin pools and vendor selection criteria more than mechanical specifications alone.
- Telematics:Predictive maintenance platforms generate recurring revenue through telemetry-linked service subscriptions. Kalmar and Konecranes anchor long-term agreements by bundling hardware with software-driven availability guarantees.
- Automated Operation:Autonomous navigation modules converge with electrification to redefine yard equipment specifications. Pilot programs at automated terminals test integration with decades-old cargo management software.
- Stability Control:Load-sensing systems for safe operation at maximum reach extensions.
- Safety Systems:Collision avoidance and operator assistance features meeting EMA machinery directive requirements.
Telematics commands the deepest vendor lock-in, with Automated Operation showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the highest equipment specification standards in Europe, while China leverages domestic battery supply chains to compress electric model pricing. Procurement patterns diverge sharply between mature port clusters facing carbon disclosure deadlines and emerging terminals prioritizing capital efficiency.
Germany
Hamburg and Bremerhaven port clusters drive replacement cycles for higher-lift-capacity units as vessel upsizing forces yard modernization. The EU F-Gas Regulation mandates refrigerant phase-downs for mobile machinery air conditioning, compressing certification timelines for equipment deployed at German terminals. North Rhine-Westphalia's inland port network is synchronizing fleet procurement with CSRD reporting standards.
China
Shanghai and Ningbo-Zhoushan container terminals anchor demand for cost-optimized electric configurations as MIIT subsidies accelerate domestic adoption. The country's dual carbon goals enforce emission benchmarks for port equipment procurement at state-owned terminal operators. Yangtze River Delta port authorities are consolidating vendor relationships to secure per-move pricing agreements.
United States
Los Angeles and Long Beach port complexes pilot 350 kWh battery configurations to eliminate mid-shift charging in multi-shift operations. EPA Tier 4 Final standards enforce emission controls equivalent to European machinery directives, raising engine recertification costs for yard equipment. Pacific Northwest intermodal terminals face grid infrastructure constraints that delay full electrification timelines.
India
Adani Ports and DP World India are modernizing container terminals at Mundra and Nhava Sheva, creating demand for electric models suited to tropical operating conditions. The country's PLI scheme for advanced chemistry cell manufacturing could localize battery pack assembly for port equipment. Gujarat's port privatization wave is unlocking infrastructure investment at previously underutilized terminal facilities.
Singapore
PSA Corporation's automated terminal operations are testing integration between electric reach stackers and decades-old cargo management software. The port authority's carbon neutrality targets compress procurement timelines for zero-emission yard equipment. Tuas Mega Port construction is absorbing premium-tier equipment with telematics-anchored service guarantees.
Reach Stacker Market Competitive Environment
Top-tier vendors anchor premium electrification and automation capabilities, while mid-tier fabricators compete on capital efficiency and regional service density. European specialists concentrate on crane-to-stacker integration and port automation software, whereas Asian manufacturers exploit backward integration into battery and drive system production. Strategic moves center on long-term service agreement restructuring and outcome-based equipment availability guarantees rather than pure hardware sales.
Among the named players, Kalmar and Konecranes occupy positions within the European premium tier, exemplifying vendors that bundle hardware with software-driven service models. SANY represents the scale-driven Asian archetype, leveraging cost-optimized electric configurations for emerging market port authorities. Liebherr sits within the in-house manufacturing specialist category, sustaining positioning through captive supply of drive systems and thermal management components.
| Leading Market Players |
|---|
| Liebherr |
| CVS Ferrari |
| Kalmar |
| ZPMC |
| Toyota |
| Konecranes |
| SANY |
| Dalian Forklift |
| Hyster |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between EMA-compliant European configurations and cost-optimized Asian models manifests in both pricing stratification and sourcing geography. Premium-tier vendors bundle telematics subscriptions and predictive maintenance guarantees, while commodity suppliers compete on equipment-only transactions with thinner aftermarket attachment.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for electric reach stacker configurations. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by EMA machinery directive certification, telematics bundling, and regional service density. Cost compression in the economy tier is intensifying because MIIT subsidies accelerate domestic OEM scale. Logistics providers at Adani Ports and DP World India exhibit highest price sensitivity, while automated terminals at PSA Corporation Singapore accept premium positioning for availability guarantees.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for advanced chemistry cells are reshaping battery pack sourcing decisions for port equipment OEMs. Cathode material processing concentrates in China, South Korea, and Japan, with European and North American fabricators drawing from Chinese lithium hydroxide and cobalt sulfate feedstocks. Single-source vulnerability in high-voltage inverter modules creates procurement risk for Kalmar and Konecranes electrification roadmaps. Distribution runs through authorized dealer networks anchored at Hamburg, Shanghai, and Los Angeles port clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Terminal operators are consolidating vendor relationships around outcome-based equipment availability guarantees rather than transactional procurement.
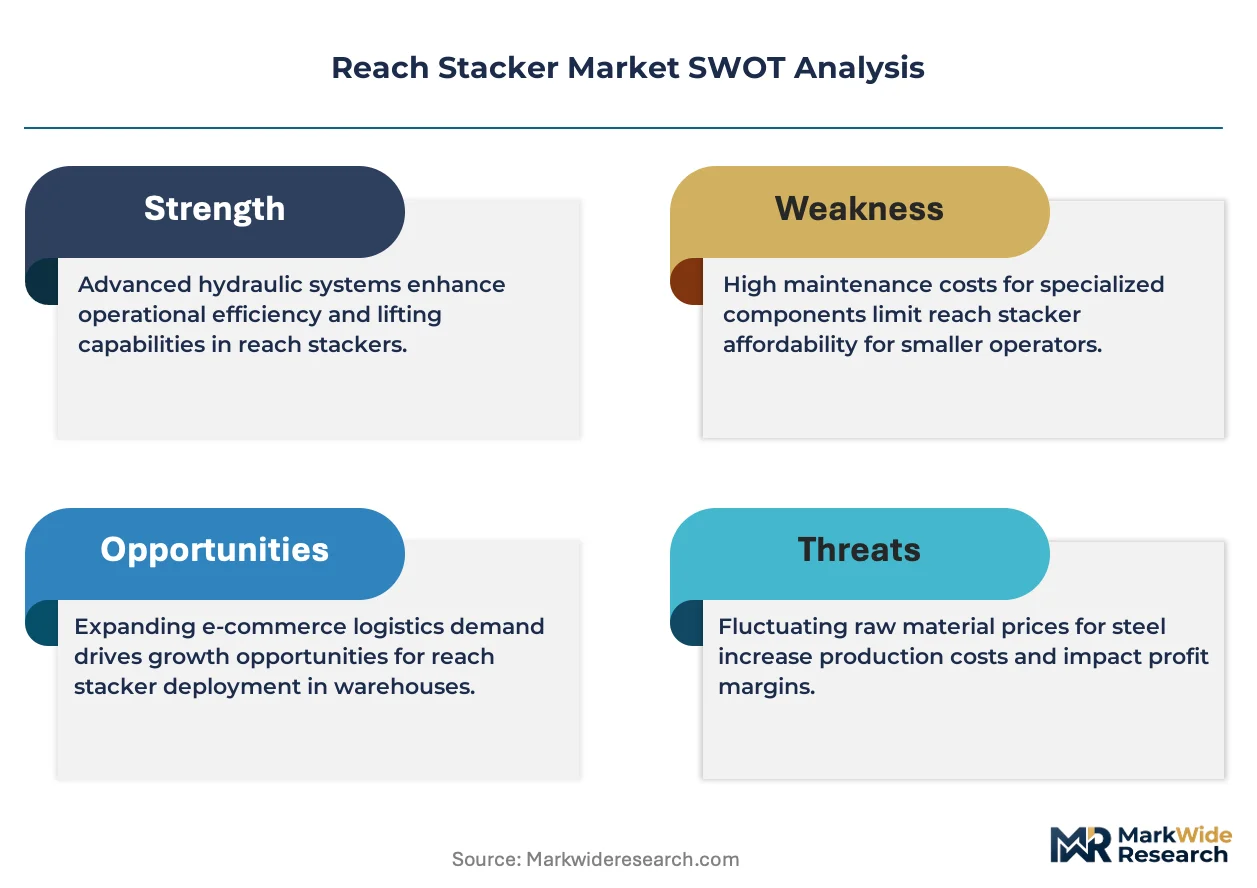
For Market Incumbents: To counter battery supply concentration in China, Kalmar and Liebherr should anchor long-term cathode material offtakes with Korean suppliers. Certification investment in CO2-based thermal management systems secures EU F-Gas Regulation compliance ahead of 2027 refrigerant phase-down deadlines. Backward integration into drive system manufacturing, as demonstrated by Liebherr's in-house production, defends margin position against Asian cost-optimized entrants. For New Entrants and Emerging Players: Direct-to-terminal digital sales channels bypass established dealer networks at privatized Indian ports. White-space opportunity concentrates in Mundra and Nhava Sheva, where Adani Ports modernization programs seek cost-optimized electric models suited to tropical duty cycles. Battery-swapping standardization advocacy creates differentiation against incumbents wedded to integrated charging infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with telematics-anchored service platforms rather than pure hardware fabricators. Long-term viability across the projection horizon favors vendors with software-driven recurring revenue streams and crane-to-stacker integration capabilities. Monitor EU Green Deal port funding disbursement velocity as inflection indicator for replacement cycle acceleration at Hamburg and Bremerhaven.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Kalmar's port automation software anchors per-move pricing agreements with Rotterdam terminal operators. |
| Battery Supply Agreement | Long-term cathode offtakes with Korean suppliers reduce MIIT subsidy dependency for European OEMs. |
| Green Certification Program | EMA machinery directive pre-certification accelerates procurement timelines at German port clusters. |
| Joint Venture | Localized assembly partnerships with Indian fabricators capture PLI scheme benefits for advanced chemistry cells. |
| Product Launch | 350 kWh solid-state configurations eliminate mid-shift charging at Los Angeles and Singapore pilot terminals. |
Study Parameters
Bottom-up terminal operator procurement modeling reconciled against top-down OEM production tracking forms the analytical core of this study. Primary interviews with port authority fleet managers, terminal engineering directors, aftermarket service heads, and OEM regional sales executives combined with secondary validation from customs trade data, EMA machinery directive filings, and SEC equipment manufacturer disclosures. Triangulation between demand-side procurement intentions and supply-side capacity announcements ensures statistical integrity.
Historical trendline analysis of replacement cycle timing and vessel upsizing correlations established baseline growth assumptions across the projection horizon. Segmentation modeling spans lifting configuration, power source architecture, end-user procurement authority, and technological feature adoption. CAGRs derive from equipment deployment velocity at named port clusters, MIIT subsidy trajectories, and EU Green Deal funding allocation patterns. Forecast inputs incorporate carbon disclosure mandate synchronization and high-voltage infrastructure retrofit cost curves.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for mid-shift charging elimination. Forecasts reflect assumptions regarding EMA directive update timelines and IMO carbon intensity enforcement stringency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Submersible Slurry Pumps Market
Material Handling Equipment
Canada Forklift Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
Asia-Pacific Forklift Truck Market
Material Handling Equipment
Pipe Clamp Market
Material Handling Equipment
Eye and Eye Turnbuckle Market
Material Handling Equipment
Industrial Racking Systems Market
Material Handling Equipment
Asia Pacific Mobile Crane Market
Material Handling Equipment
Electric Stacker Market
Material Handling Equipment
Log Stackers Market
Material Handling Equipment
Copper and Aluminum Welding Bar Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Froth Flotation Equipment Market
Material Handling Equipment
Clinching Machines Market
Material Handling Equipment
Vertical Lifts Market