
 Outdoor Power Equipment (OPE) Market | 2026-2036
Outdoor Power Equipment (OPE) Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Power Equipment (OPE) Market Analytics
Chinese lithium-ion cell production is expanding capacity for cordless OPE drivetrains. Husqvarna Group leverages its robotic mower R&D to sustain technology leadership in autonomous turf management. Robert Bosch anchors the European professional segment with precision brushless motor systems. Stanley Black & Decker competes through vertical integration into battery cell sourcing and charger ecosystems.
Outdoor power equipment comprises motorized implements designed for vegetation management, land clearing, and property maintenance, typically featuring two-stroke or four-stroke internal combustion engines, brushless DC electric motors, or battery-electric drivetrains with power ratings from 20V to 80V lithium-ion platforms. These machines serve residential consumers, commercial landscaping contractors, municipal maintenance departments, and agricultural operators requiring mechanized solutions for terrain that prohibits standard tractor access. Lawn mowers dominate value generation due to higher unit prices and replacement frequency among commercial users, while battery-powered leaf blowers and trimmers represent the fastest-expanding fuel type segment as runtime improvements displace gasoline alternatives in noise-restricted municipalities. Chainsaws retain specialized margin pools in forestry and emergency response applications where gasoline displacement proceeds more gradually.
EPA certifies small spark-ignition engines under Phase 3 standards that limit hydrocarbon and nitrogen oxide emissions, compelling manufacturers to redesign carburetion and exhaust systems or accelerate electrification roadmaps. The EU F-Gas Regulation and REACH chemical restrictions further constrain solvent-based coatings and refrigerants used in equipment manufacturing, while California Air Resources Board zero-emission mandates for small off-road engines create a regulatory laboratory affecting national product planning. Stakeholders must monitor battery supply chain localization requirements and evolving carbon border adjustments that will reshape sourcing decisions and factory placement across the forecast horizon.
Market Dynamics
Battery-electric drivetrains are compressing the gasoline engine supply base as commercial landscapers re-equip fleets to meet municipal noise ordinances and emissions mandates. This electrification pressure is restructuring supplier relationships, R&D allocation, and manufacturing footprints across the equipment value chain.
Growth Catalysts
- EPA Phase 3 emissions standards:Hydrocarbon and nitrogen oxide limits on small spark-ignition engines force manufacturers toward cleaner combustion designs or full electrification, expanding the addressable market for battery-powered alternatives.
- Commercial landscaping fleet renewal:Professional contractors in noise-restricted municipalities are replacing gasoline units with lithium-ion platforms to maintain operating hours and access contracts.
- Chinese lithium-ion cell capacity expansion:Domestic cell production growth is lowering drivetrain costs and shortening lead times for cordless OPE manufacturers sourcing from Asia-Pacific suppliers.
Market Restraints
- Cobalt and lithium price volatility:Battery metal cost swings compress margin predictability for manufacturers locked into fixed-price retail contracts with big-box distributors.
- Gasoline engine supplier concentration:Remaining two-stroke and four-stroke engine production concentrates among a handful of specialized foundries, creating single-source vulnerability for hybrid product lines.
- Runtime limitations in high-torque applications:Battery chemistry constraints prevent cordless platforms from matching gasoline power density in commercial-grade chainsaws and large-area mowers.
Strategic Opportunities
- India professional landscaping emergence:Urban green space expansion and golf course development create first-mover advantage for battery OPE brands establishing dealer networks before domestic manufacturing scales.
- Autonomous turf management convergence:Robotic mower navigation systems fused with cloud-based fleet management software open subscription revenue streams beyond equipment sales.
- EU Green Deal public procurement incentives:Carbon-neutral purchasing mandates for municipal maintenance departments tilt competitive bids toward zero-emission equipment suppliers.
Industry Challenges
- Battery pack thermal management engineering:Safely dissipating heat from 80V platforms in enclosed chassis designs requires scarce electrochemical and mechanical integration expertise.
- Cross-platform charger standardization delays:Proprietary voltage and connector protocols fragment the aftermarket accessory market, frustrating commercial users with mixed-fleet operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Power Equipment (OPE) Market |
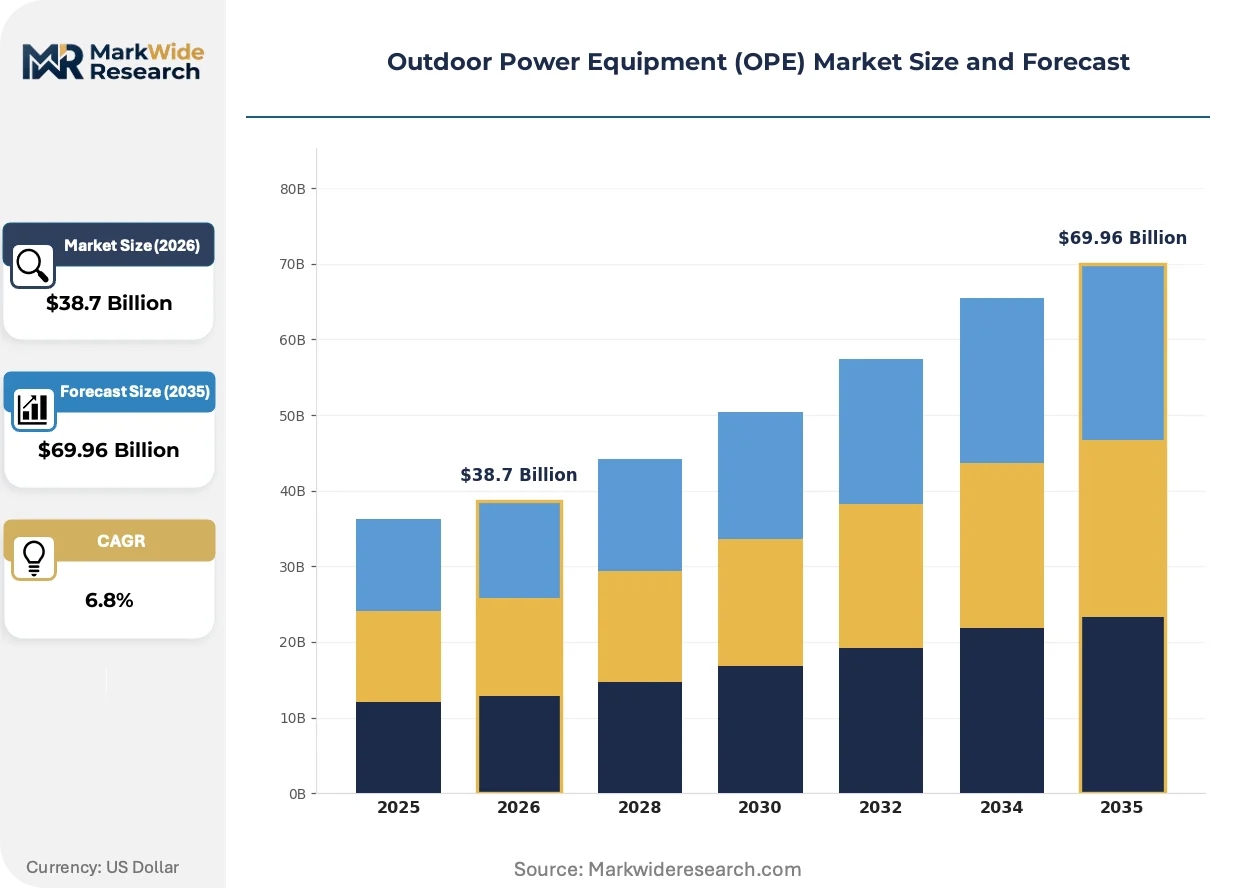
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lawn Mowers, Chainsaws, Trimmers, Leaf Blowers End User: Residential Users, Commercial Landscapers, Government Agencies, Agricultural Operators Fuel Type: Gasoline, Electric, Battery, Hybrid Distribution Channel: Online Retailers, Brick-and-Mortar Stores, Direct Sales, Wholesalers |
| Companies Covered | Stanley Black & Decker, Robert Bosch, Husqvarna Group, Techtronic Industries Company Limited, Briggs & Stratton Corporation, Deere & Company, The Toro Company, Yamabiko Corporation, Honda Motor Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Power Equipment (OPE) Market Evolving Landscape
Intelligent connectivity and powertrain electrification are redefining equipment value propositions, shifting competition from horsepower specifications to data-enabled uptime guarantees and total cost of ownership optimization.
Brushless DC motor systems paired with solid-state battery architectures are overtaking traditional brushed motor and cylindrical cell combinations in premium cordless platforms. Commercial landscaping contractors adopting these systems report extended duty cycles and reduced maintenance intervals. The technology is overtaking legacy drivetrain suppliers who lack in-house motor controller and battery management system capabilities.
California Air Resources Board zero-emission mandates for small off-road engines function as a regulatory laboratory influencing national product planning decisions. Equipment manufacturers must maintain parallel gasoline and electric SKUs or abandon the California market entirely. Professional-grade mowers and utility vehicles face the steepest compliance timelines, compressing development cycles for electrified replacements.
Landscaping contractors are consolidating vendor relationships around integrated battery ecosystems that lock charger compatibility across multiple tool categories. Big-box retail and direct-to-contractor digital channels are displacing independent dealer networks for standardized equipment purchases. This concentration is most visible in the United States, where national maintenance firms negotiate enterprise pricing tied to fleet telematics data sharing.
Outdoor Power Equipment (OPE) Market Segmentation
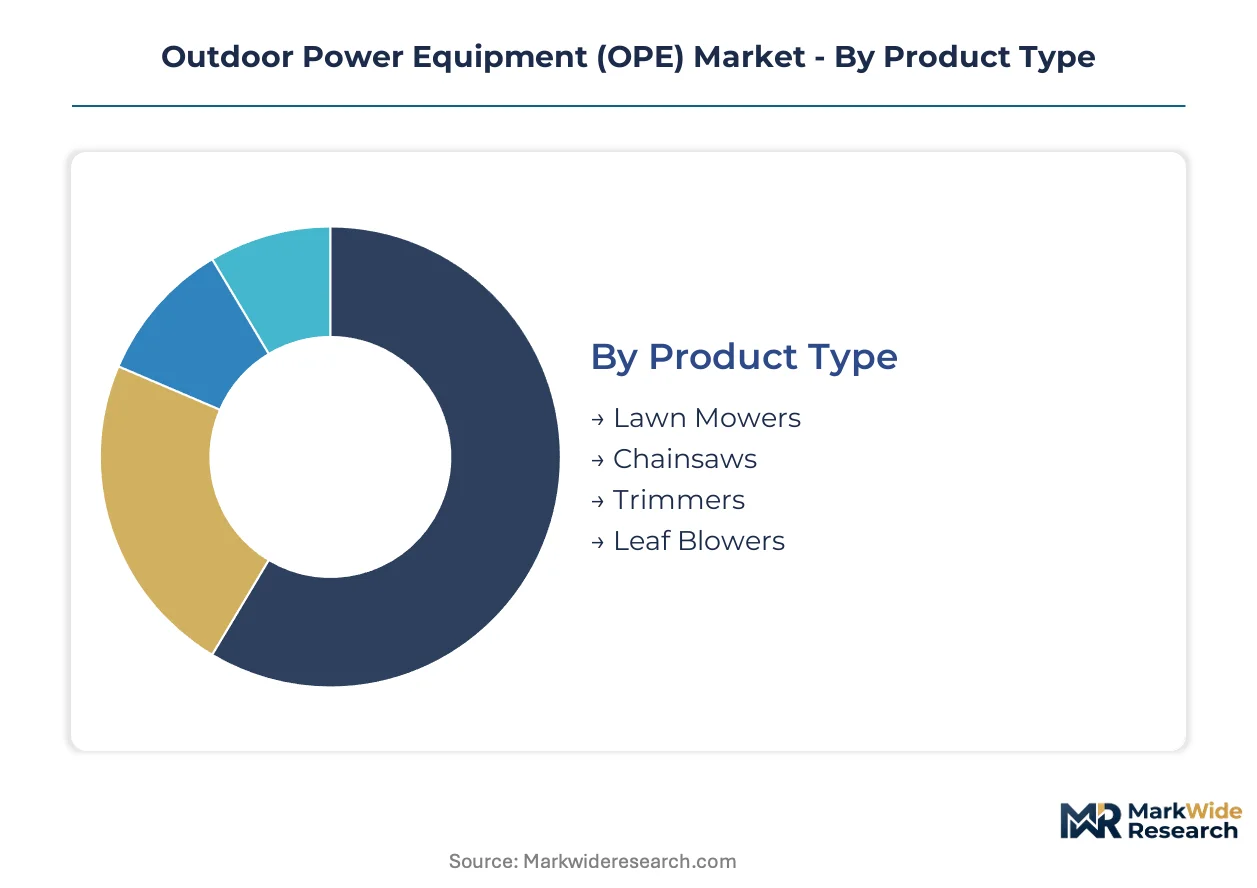
Outdoor power equipment manufacturers must navigate divergent performance requirements across residential, commercial, and municipal buyers. Segmentation reveals how battery chemistry limitations and torque demands create distinct product-positioning opportunities.
Product Type:
Volume concentration sits with lawn maintenance equipment, while premium margins concentrate in specialized forestry and precision trimming applications.
- Lawn Mowers:Self-propelled and riding configurations with cutting decks from 21 to 60 inches dominate commercial fleet procurement. Demand concentrates among United States landscaping contractors upgrading to lithium-ion platforms for noise-restricted municipal contracts.
- Chainsaws:Two-stroke gasoline engines persist in professional forestry and emergency response where battery power density cannot match sustained high-torque operation. California Air Resources Board zero-emission mandates are compressing development timelines for electrified alternatives.
- Trimmers:String and blade configurations serve residential edge maintenance and commercial precision work.
- Leaf Blowers:Handheld and backpack designs represent the fastest battery displacement as runtime improvements satisfy municipal noise ordinances.
Today's leader: Lawn Mowers. Tomorrow's challenger: Leaf Blowers.
End User:
Application intensity separates price-sensitive residential purchasers from commercial buyers prioritizing uptime guarantees and fleet telematics integration.
- Residential Users:Homeowners purchasing single units through big-box retail prioritize ergonomic design and storage footprint over professional-grade durability. United States suburban households drive seasonal replacement cycles.
- Commercial Landscapers:Fleet operators in Germany and China negotiate enterprise pricing tied to battery ecosystem compatibility and equipment connectivity platforms. These buyers demand interchangeable battery packs across mower, trimmer, and blower categories.
- Government Agencies:Municipal maintenance departments in California face zero-emission procurement mandates under state air quality regulations.
- Agricultural Operators:Orchard and vineyard managers require specialized configurations for terrain prohibiting standard tractor access.
Commercial landscapers command the steepest expansion trajectory. Residential users anchor absolute volume.
Fuel Type:
Regulatory pressure is restructuring the combustion-electric mix as EPA Phase 3 standards tighten hydrocarbon limits on small spark-ignition engines.
- Battery:Lithium-ion platforms from 20V to 80V are displacing gasoline in noise-restricted municipalities. Chinese cell production expansion is lowering drivetrain costs and shortening lead times for cordless equipment manufacturers.
- Gasoline:Two-stroke and four-stroke engines retain dominance in high-torque forestry and large-area mowing where energy density requirements exceed current battery chemistry capabilities.
- Electric:Corded designs persist in stationary applications with reliable grid access.
- Hybrid:Range-extender configurations bridge runtime gaps for commercial users transitioning from gasoline fleets.
Battery platforms are gaining share fastest. Gasoline retains torque-critical strongholds.
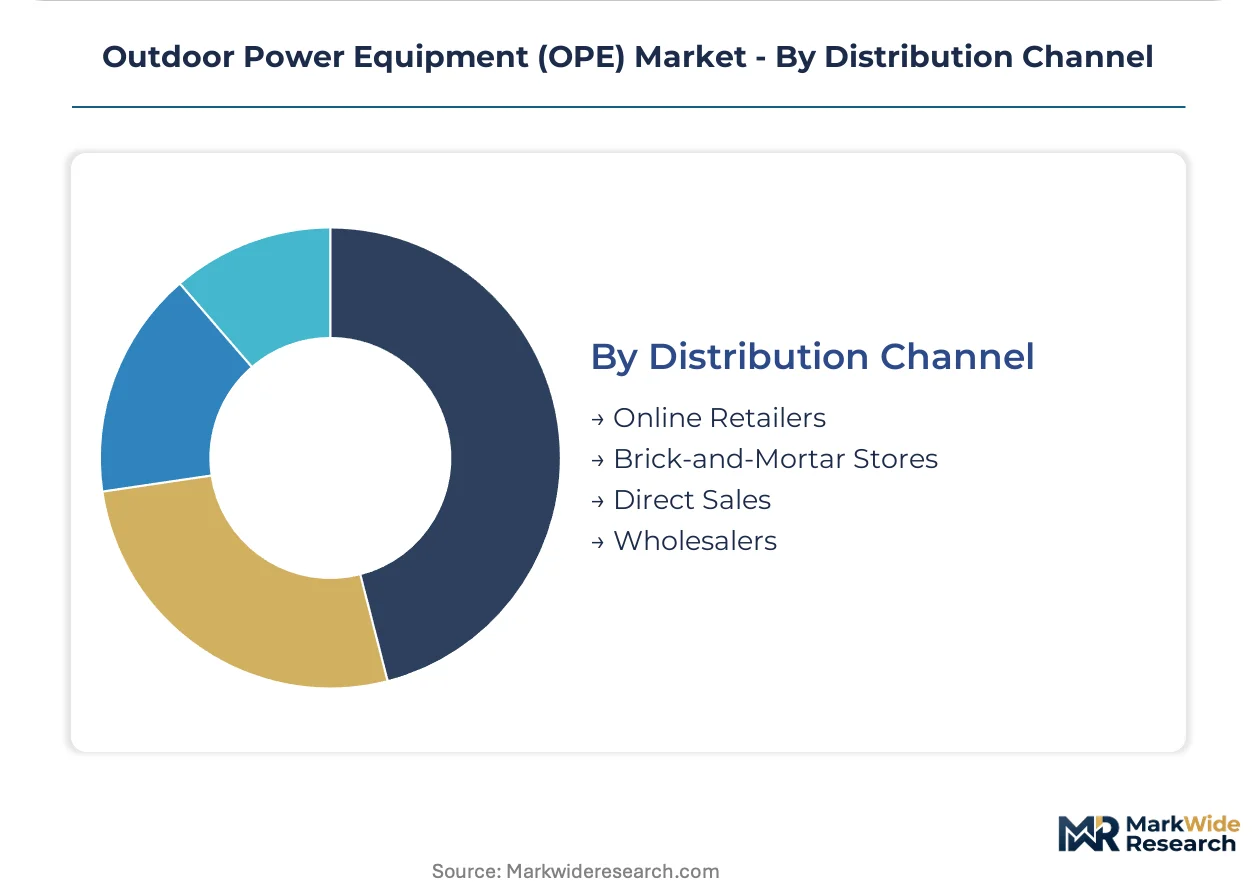
Distribution Channel:
Channel concentration reflects buyer sophistication, with integrated battery ecosystems favoring direct and digital procurement over fragmented retail.
- Online Retailers:Direct-to-contractor digital platforms and big-box e-commerce capture standardized equipment purchases. United States national maintenance firms leverage these channels for enterprise fleet procurement with telematics data sharing agreements.
- Brick-and-Mortar Stores:Independent dealer networks retain importance for service-dependent commercial buyers requiring localized parts and repair infrastructure.
- Direct Sales:Manufacturer-owned channels serve large fleet operators with customized financing and trade-in programs.
- Wholesalers:Regional distributors stock inventory for smaller landscaping contractors and municipal procurement departments.
Online retailers are climbing the fastest. Brick-and-mortar defends service-intensive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating assembly capacity to jurisdictions with lower compliance costs for small-engine emissions standards, creating divergent investment flows across major production bases.
United States
Commercial landscaping contractors in California face CARB zero-emission mandates for small off-road engines, accelerating fleet electrification timelines. The EPA Phase 3 standards tighten hydrocarbon limits nationwide, forcing carburetion redesigns or platform abandonment. Manufacturing concentrates in Wisconsin and South Carolina, where engine foundries and assembly plants serve domestic big-box retail channels.
China
Domestic lithium-ion cell production expansion is lowering drivetrain costs for cordless equipment exports. The Ministry of Ecology and Environment enforces dual carbon goals that constrain foundry energy intensity. Industrial clusters in Jiangsu and Zhejiang provinces host motor controller and battery management system suppliers integrating with cordless OPE assemblers.
Germany
Professional landscaping fleets prioritize precision brushless motor systems for noise-restricted municipal contracts. The EU F-Gas Regulation and REACH chemical restrictions constrain solvent-based coatings in manufacturing. Engineering expertise concentrates in Stuttgart and Munich, where automotive-tier suppliers adapt motor control technologies to commercial turf equipment.
Japan
Precision manufacturing capabilities support high-reliability two-stroke engines for professional forestry applications where battery displacement proceeds gradually. METI industrial policy promotes carbon-neutral technology exports. Industrial activity clusters in Aichi and Shizuoka prefectures, where small-engine specialists maintain tier-one supply relationships with global equipment brands.
India
Urban green space expansion and golf course development create first-mover opportunities for battery OPE brands establishing dealer networks. The Bureau of Indian Standards implements safety certification requirements for lithium-ion powered equipment. Manufacturing investment concentrates in Tamil Nadu and Gujarat, where electronics assembly infrastructure supports cordless tool production scaling.
Outdoor Power Equipment (OPE) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue autonomous navigation and fleet software subscriptions as differentiation vectors. The vendor base stratifies across engine manufacturers pivoting to electrification, power tool conglomerates leveraging battery ecosystem lock-in, and specialized robotics developers. Three archetypes dominate: diversified industrial conglomerates with captive cell supply, pure-play outdoor equipment specialists with forestry heritage, and Asian contract manufacturers scaling cordless platforms. Competitive moves center on backward integration into battery cell sourcing and strategic partnerships for solid-state chemistry access.
Within the diversified industrial tier, Stanley Black & Decker and Robert Bosch exemplify scale-driven positions anchored by vertical control over charger ecosystems and motor controller design. Husqvarna Group occupies a specialist archetype representing autonomous turf management convergence. These three entities illustrate how competitive positioning increasingly depends on software-enabled fleet management capabilities rather than mechanical specifications alone.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Robert Bosch |
| Husqvarna Group |
| Techtronic Industries Company Limited |
| Briggs & Stratton Corporation |
| Deere & Company |
| The Toro Company |
| Yamabiko Corporation |
| Honda Motor Company |
| Others |
Value Network & Pricing Analysis
Premium-mid-economy pricing differentiation across battery voltage tiers—20V residential platforms versus 80V commercial systems—creates parallel sourcing strategies where lithium-ion cell grade and thermal management complexity determine both factory gate pricing and supplier qualification depth. This bifurcation concentrates procurement leverage among fleet operators bundling charger ecosystems while fragmenting margin capture for manufacturers locked into fixed-price retail contracts.
Pricing Analysis
Distributor margin layers absorb 18-25 points before big-box retail markup, compressing manufacturer flexibility on cordless platform launches. Three-tier pricing structure across premium brushless systems, standard brushed motor units, and economy corded alternatives tracks battery chemistry grade and motor controller sophistication. Cost compression in residential 20V tiers intensifies as Chinese cell capacity expansion floods lower-voltage segments. Commercial landscapers negotiating enterprise fleet contracts exhibit lowest price sensitivity due to uptime guarantee requirements, while suburban homeowners purchasing single units through retail channels drive seasonal discounting cycles.
Supply Chain Analysis
Dual-sourcing requirements from United States-based fleet operators mandate qualified cell suppliers across China, South Korea, and domestic pilot lines to mitigate tariff exposure and logistics disruption. Lithium carbonate, cobalt sulfate, and electrolyte formulations constitute critical input dependencies tethered to spot market volatility. Single-source vulnerability concentrates in precision brushless motor laminations where Japanese and German specialty foundries maintain process control advantages. Distribution runs through direct-to-contractor digital platforms for standardized battery platforms, while independent dealer networks retain service-intensive commercial segments requiring localized repair infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge between California's CARB zero-emission mandates and China's dual carbon enforcement, where compliance cost differentials of 15-20 points on small-engine emissions create relocation incentives for final assembly capacity.
For Market Incumbents: Anticipate margin compression from solid-state battery entrants by securing captive lithium supply through offtake agreements with Jiangsu and Zhejiang cell producers. Reinforce dealer network control in Germany's noise-restricted municipal contracting corridors where precision brushless motor certification creates switching costs. Prioritize backward integration into battery management system firmware to defend against software-defined fleet management disruption from autonomous mowing specialists. For New Entrants and Emerging Players: CARB Phase 3 small off-road engine regulations in California open a window for pure-electric platform launches before incumbent hybrid SKU proliferation saturates distribution channels. Target India's professional landscaping emergence in Tamil Nadu and Gujarat golf course developments where dealer network gaps persist. Pursue direct-to-contractor digital sales with telematics-enabled uptime guarantees as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where battery ecosystem lock-in concentrates procurement leverage among three diversified industrial conglomerates controlling charger and motor controller IP. Frame long-term viability around solid-state chemistry access and autonomous navigation software capabilities rather than mechanical manufacturing scale. Monitor lithium hydroxide contract price convergence with carbonate as the inflection indicator for cell cost competitiveness. Deviation in cobalt substitution rates would shift the outlook materially.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Ecosystem Lock-In | Stanley Black & Decker's charger compatibility across mowers, trimmers, and blowers captures fleet renewal cycles. |
| Autonomous Navigation Convergence | Husqvarna Group's robotic mower R&D transfers to cloud-based fleet management subscription revenue streams. |
| Solid-State Chemistry Partnership | Robert Bosch's precision motor systems require next-generation cell architectures for 80V thermal management. |
| Geographic Manufacturing Relocation | Wisconsin and South Carolina engine foundries face EPA Phase 3 compliance costs favoring Zhejiang assembly expansion. |
| Dealer Network Consolidation | Big-box retail displacement of independent service channels threatens aftermarket parts profitability for Briggs & Stratton. |
Research Methodology
Bottom-up commercial landscaping fleet modeling reconciled against top-down lithium-ion cell production tracking forms the analytical core of this study. Primary interviews with fleet procurement managers at United States national maintenance firms, brushless motor engineering directors at Stuttgart-tier automotive suppliers, and Jiangsu battery management system developers combined with secondary validation from EPA certification filings, CARB small off-road engine registration databases, and Chinese Ministry of Ecology and Environment dual carbon compliance disclosures. Trade flow analysis across customs records and big-box retail point-of-sale data enabled triangulation between manufacturer shipment claims and end-use absorption rates.
Input-output matrices map cordless platform shipments against gasoline engine phase-out timelines across residential, commercial, and municipal buyer archetypes throughout the projection horizon. Segmentation dimensions include product type intensity, voltage tier, end-use application scale, and regional regulatory cluster stringency. CAGRs derive from equipment replacement cycle analysis weighted by fleet telematics adoption curves and battery chemistry cost experience curves. Forecast inputs incorporate municipal noise ordinance expansion rates and lithium-ion cell capacity utilization at key Asian production hubs.
Revisions become necessary when cobalt substitution breakthroughs, solid-state battery commercialization timelines, or California CARB mandate acceleration materialize outside modeled assumptions. Deviation in Chinese lithium hydroxide export licensing or EU F-Gas Regulation enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Mill Liner Market
Material Handling Equipment
Compaction Machines Market
Material Handling Equipment
Fork Lift Attachments Market
Material Handling Equipment
Industrial Hose Assemblies Market
Material Handling Equipment
Container Handler Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Global Conveyors Market
Material Handling Equipment
Port Equipment Market
Material Handling Equipment
Portable Forklift Ramps Market
Material Handling Equipment
Global Hydraulic Equipment Market
Material Handling Equipment
Industrial Pulley Market
Material Handling Equipment
Arrestor Cables Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Precision Ballscrews Market
Material Handling Equipment
Hydraulic Fittings Market
Material Handling Equipment
Floor Scrubber Machine Market