
 Hydraulic Binder Market | 2026-2036
Hydraulic Binder Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Binder Market Analytics
High-performance blended cement grades is collapsing the commodity premium as infrastructure specifications tighten across OECD procurement standards. Bosch Rexroth AG leverages its fluid power expertise to anchor industrial binder applications in automated batching systems. Parker Hannifin Corporation dominates hydraulic actuation interfaces for precision material handling in cement terminals. Danfoss sustains energy recovery systems that reduce clinker kiln fuel intensity by capturing waste heat.
Hydraulic binder denotes any finely ground inorganic material that sets and hardens through hydration reactions when mixed with water, with Portland cement comprising calcium silicates (C3S, C2S) and aluminate phases that achieve compressive strengths exceeding 40 MPa at 28 days under standard curing protocols. Cement leads product type volumes as the foundational matrix for concrete production, while eco-friendly technology segments capture margin expansion as calcined clay and supplementary cementitious materials displace conventional clinker content. Construction applications anchor absolute demand, though marine specifications for sulfate-resistant formulations command premium pricing in coastal infrastructure.
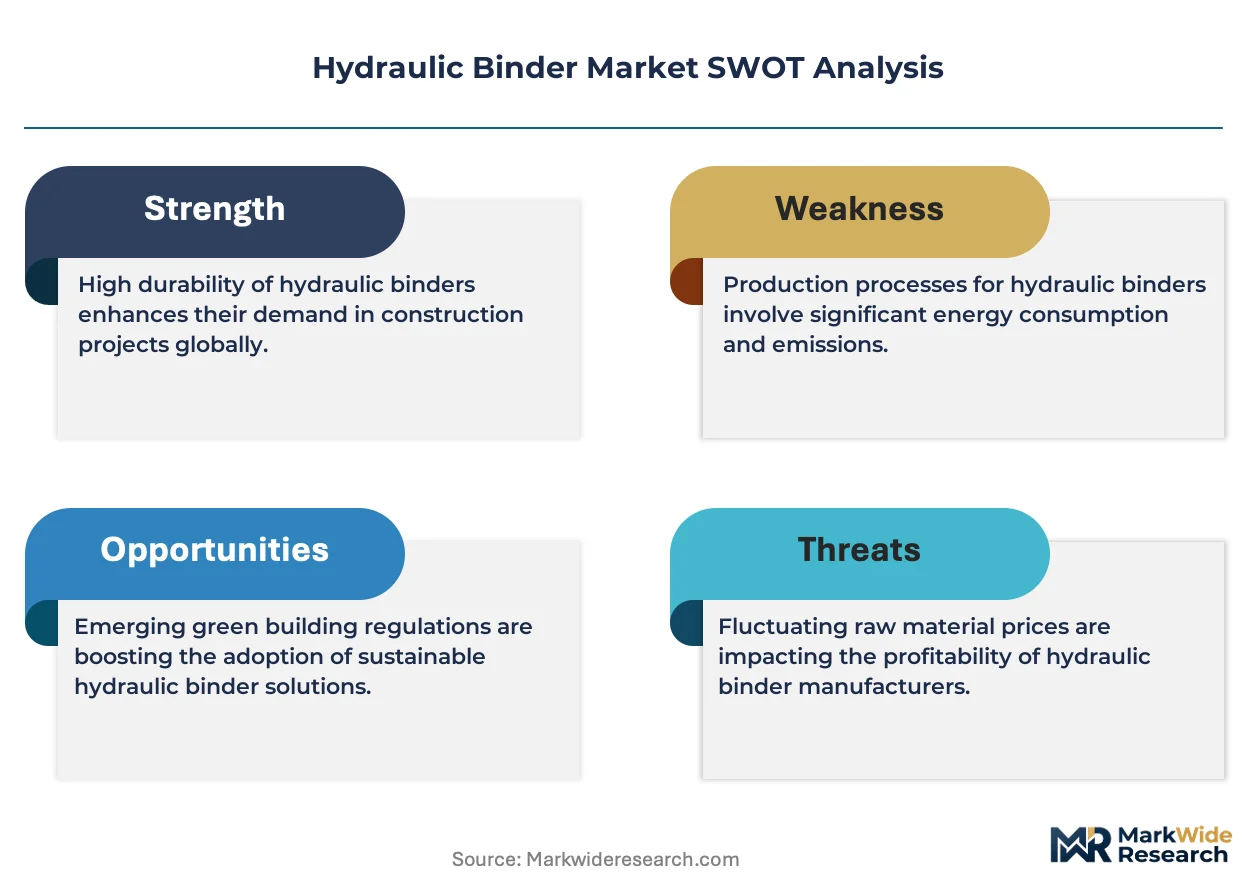
EPA National Emission Standards for Hazardous Air Pollutants constrain Portland cement kiln operations in the United States, while the EU ETS carbon pricing mechanism and REACH chemical registration requirements reshape formulation economics across European production bases. India's Bureau of Indian Standards mandates IS 269 certification for ordinary Portland cement, with the Bureau of Energy Efficiency's PAT scheme driving thermal efficiency benchmarks. Stakeholders must monitor evolving low-carbon procurement mandates as public infrastructure agencies embed embodied carbon thresholds into tender specifications.
Market Dynamics
Carbon border taxation and embodied carbon procurement mandates are restructuring specification requirements across public infrastructure tenders, forcing rapid formulation shifts toward low-clinker alternatives before compliance deadlines crystallize.
Growth Catalysts
- EU Carbon Border Adjustment Mechanism:Procurement officers in Germany and France now specify Portland-limestone cement grades to preempt tariff exposure on imported clinker-intensive products.
- Calcined clay activation:LC3 (limestone calcined clay cement) formulations achieve equivalent 28-day strength with 40% clinker reduction, unlocking specification upgrades in Vietnam's megaproject corridor.
- Infrastructure resilience programs:Southeast Asian development banks are embedding sulfate-resistant binder requirements into coastal flood-defense tenders from Ho Chi Minh City to the Mekong Delta.
Market Restraints
- Clinker feedstock concentration:High-quality limestone deposits suitable for low-carbon calcination concentrate in specific quarry regions, creating supply vulnerability for dispersed grinding plants.
- Alternative fuel infrastructure gaps:Waste-derived fuels essential for kiln decarbonization lack collection and preprocessing networks outside major industrial zones.
- Technical limitation in marine applications:High-volume supplementary cementitious material blends face delayed acceptance for submerged concrete specifications due to extended durability testing protocols.
Strategic Opportunities
- Underpenetrated calcined clay capacity:India and Brazil hold untapped kaolinite reserves suitable for LC3 production, awaiting capital deployment for kiln retrofitting and clay calcination infrastructure.
- Carbon capture integration:Post-combustion capture retrofits at existing European cement plants qualify for EU Innovation Fund financing, creating first-mover advantage in negative-emission binder certification.
- Digital twin optimization:Real-time kiln control systems using predictive analytics reduce fuel intensity and enable dynamic blending for project-specific performance envelopes.
Industry Challenges
- Specialized process engineering talent:Deep expertise in calcined clay reactivity modulation and alkali-silica reaction mitigation remains concentrated among a limited cohort of research institutions.
- Certification timeline compression:New binder formulations require multi-year performance validation under EN 197-1 and ASTM C1157 protocols, delaying market entry despite technical readiness.
- Legacy silo infrastructure:Existing cement terminals lack segregated storage for multiple blended grades, forcing capital-intensive retrofitting to handle specification diversity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Binder Market |
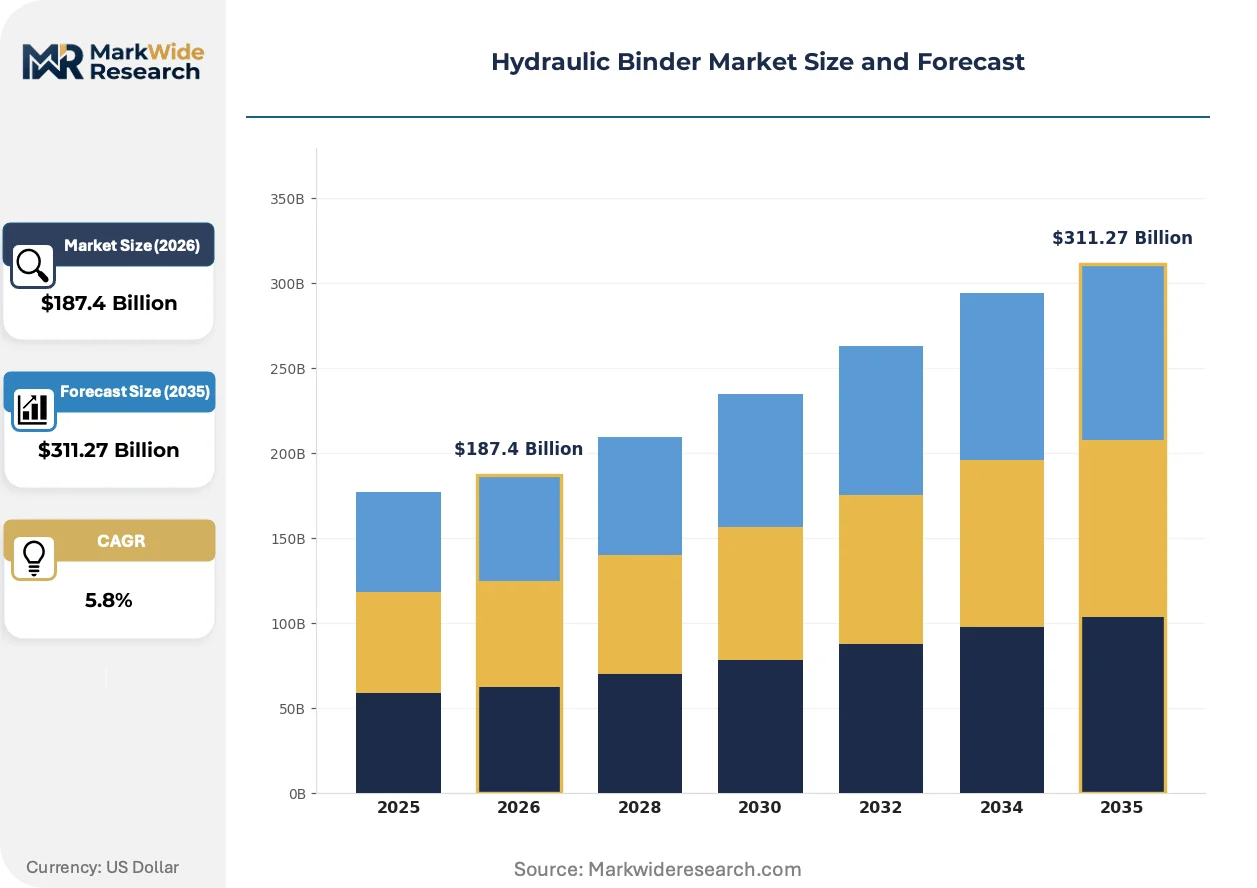
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement, Lime, Gypsum, Others Application: Construction, Infrastructure, Industrial, Marine End User: Residential, Commercial, Institutional, Government Technology: Traditional, Advanced, Eco-friendly, Sustainable |
| Companies Covered | Bosch Rexroth AG, Parker Hannifin Corporation, Danfoss, KYB Corporation, Eaton Corporation, Kawasaki Heavy Industries, HYDAC International, Linde Hydraulics, HAWE Hydraulik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Binder Market Evolving Landscape
Formulation chemistry, regulatory compliance architecture, and procurement specification frameworks are converging to accelerate displacement of conventional Portland cement across high-volume construction applications.
Calcined clay and limestone filler combinations are displacing traditional clinker content in standardized concrete applications. Ready-mix producers in France and Colombia have adopted LC3 blends for 30% of structural specifications since commercial-scale activation kilns achieved consistent metakaolin quality. This displacement is compressing the commodity premium for high-performance blended grades as supply scales beyond pilot volumes.
REACH chemical registration requirements and the EU ETS carbon pricing mechanism are reshaping formulation economics across European production bases. Kiln operators face escalating compliance costs for conventional clinker intensity, redirecting R&D budgets toward alternative hydraulic binders. Marine infrastructure specifications in the Netherlands and Denmark now mandate sulfate-resistant formulations with documented embodied carbon thresholds.
Public infrastructure agencies are embedding lifecycle carbon accounting into tender evaluation criteria. Contractors bidding on Vietnam's North-South Expressway segments must submit Environmental Product Declarations with third-verified Global Warming Potential figures. This behavioral shift privileges domestic grinding plants with integrated calcined clay supply chains over importers of conventional bulk cement.
Hydraulic Binder Market Segmentation
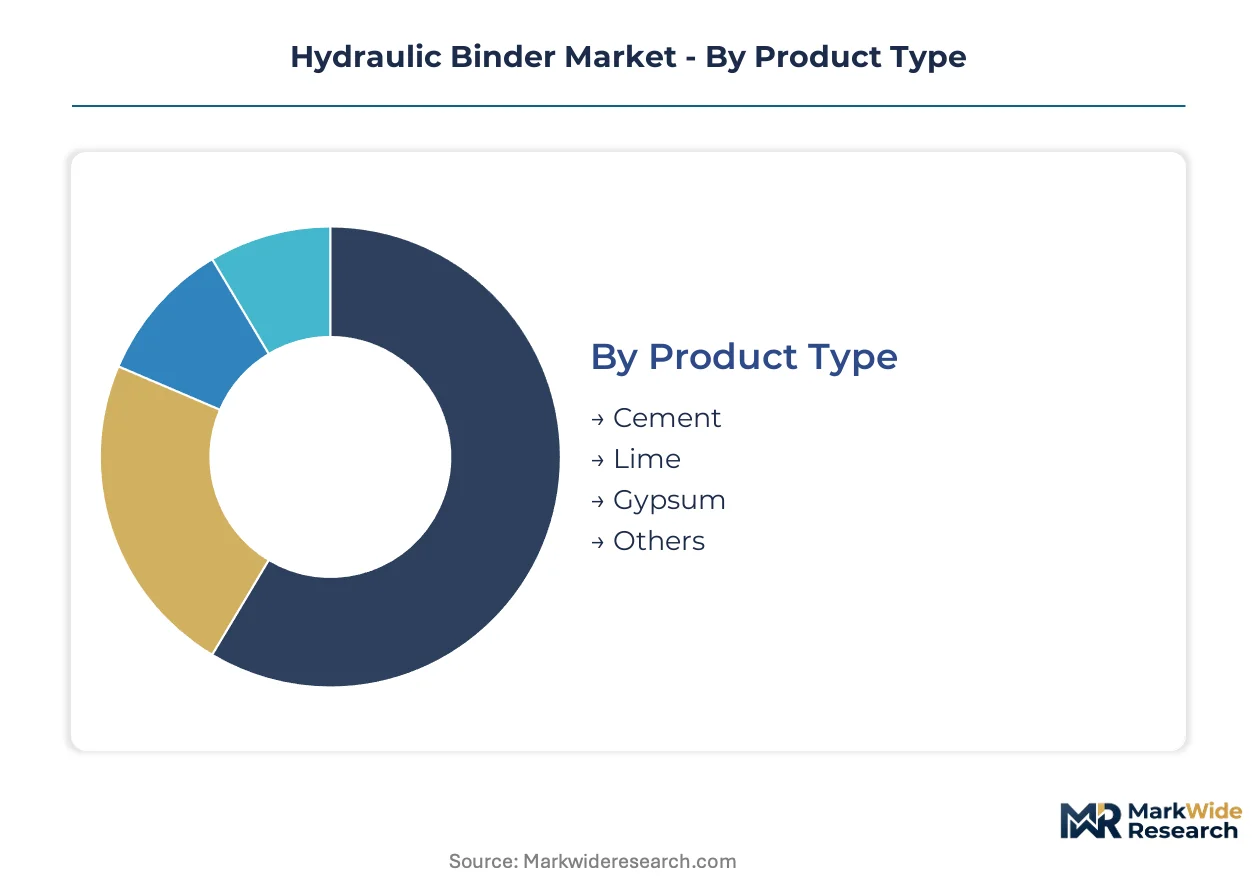
Segmentation in hydraulic binders determines procurement channel access, specification compliance pathways, and margin capture potential. Product chemistry and application severity dictate whether volumes flow through bulk terminal networks or project-specific batching operations.
Product Type:
Cement dominates bulk distribution through marine terminals and rail-served silo networks, while lime and specialty binders channel through chemical distributors and direct mill-to-project contracts.
- Cement:Portland and blended formulations containing calcium silicates (C3S, C2S) achieve compressive strengths exceeding 40 MPa at 28 days. Demand concentrates in Vietnam's megaproject corridor from Ho Chi Minh City through the Mekong Delta, where infrastructure resilience programs mandate sulfate-resistant grades for coastal flood defenses.
- Lime:Calcium oxide and hydroxide variants serve soil stabilization and historic masonry restoration with lower carbon intensity than clinker-based alternatives. German and French procurement officers now specify hydraulic lime for heritage conservation tenders to preempt EU Carbon Border Adjustment Mechanism exposure on imported cement.
- Gypsum:Calcium sulfate dihydrate functions as a set-retarder in Portland cement grinding and as the primary binder in plasterboard manufacturing.
- Others:Geopolymer and alkali-activated slag systems serve niche industrial applications requiring chemical resistance beyond conventional cement capacity.
Cement dominates installed base. Eco-friendly blended grades are where expansion concentrates.
Application:
Application severity determines specification tier, with marine and infrastructure projects commanding premium pricing through performance-based procurement while construction volumes compete on delivered cost.
- Construction:Residential and commercial concrete production consumes standardized Ordinary Portland Cement and Portland-limestone cement grades through ready-mix batching plants. LC3 formulations with 40% clinker reduction are gaining specification share in Colombia and France as calcined clay activation kilns achieve consistent metakaolin quality.
- Infrastructure:Highway, bridge, and tunnel specifications embed lifecycle carbon accounting into tender evaluation criteria. Vietnam's North-South Expressway segments require Environmental Product Declarations with third-party verified Global Warming Potential figures, privileging domestic grinding plants with integrated calcined clay supply chains.
- Industrial:Refractory linings, mining backfill, and waste stabilization demand specialized binder chemistries with controlled setting characteristics.
- Marine:Submerged concrete and coastal defense structures mandate sulfate-resistant formulations with documented embodied carbon thresholds under Netherlands and Denmark procurement protocols.
Construction anchors absolute volume. Marine specifications command the steepest expansion trajectory as coastal resilience investment accelerates.
End User:
Customer type shapes contract structure, with government and institutional buyers embedding compliance mandates that reshape supplier qualification requirements.
- Residential:Single-family and multi-family housing developers procure through ready-mix concrete suppliers with limited specification leverage.
- Commercial:Office, retail, and logistics construction projects increasingly require Environmental Product Declaration documentation for green building certification.
- Institutional:University and healthcare construction in the United States faces EPA National Emission Standards for Hazardous Air Pollutants constraints on kiln-sourced materials.
- Government:Public infrastructure agencies embed embodied carbon thresholds into tender specifications, with India's Bureau of Indian Standards mandating IS 269 certification for ordinary Portland cement in state-funded projects.
Government procurement dominates specification-setting authority. Commercial end users are climbing the fastest as private ESG commitments harden into contractual requirements.
Technology:
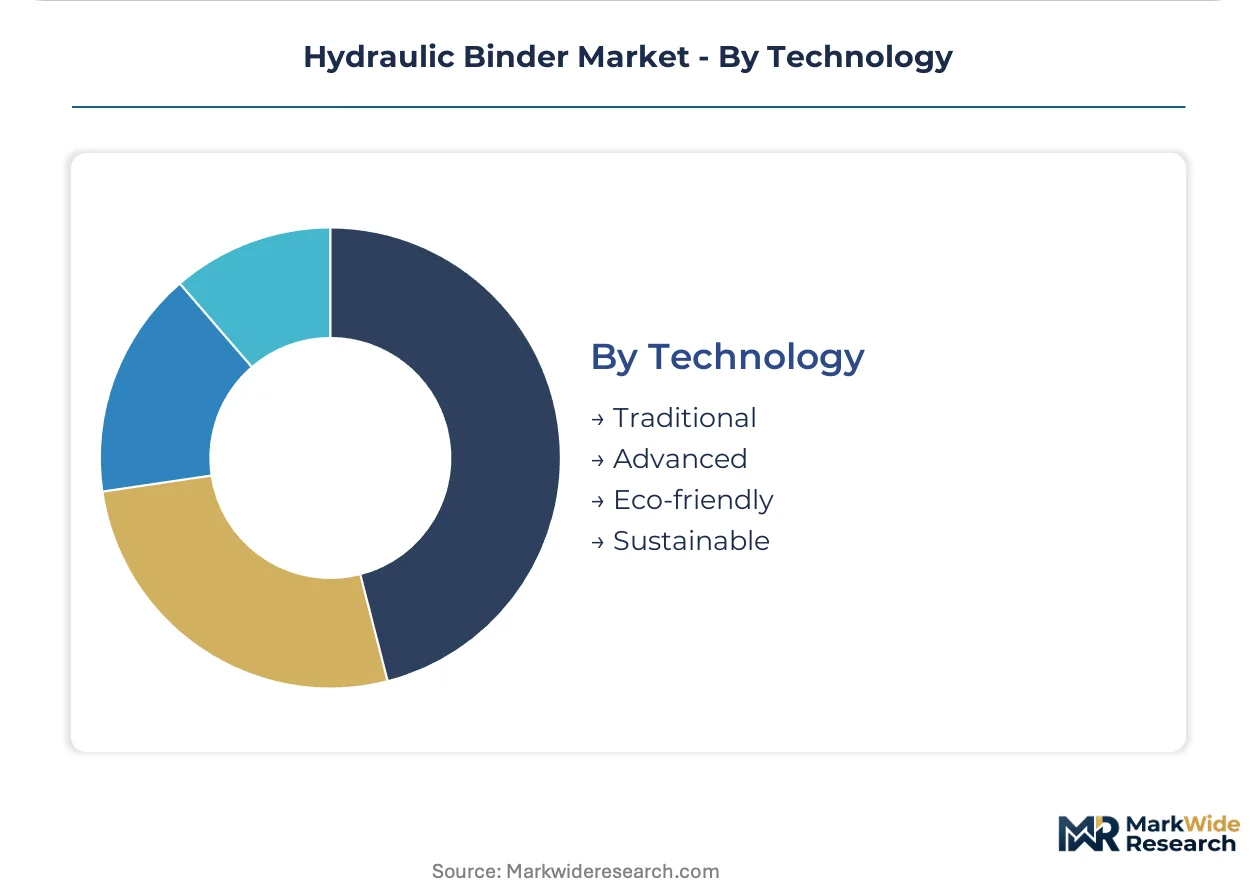
Technology tier determines capital intensity and regulatory exposure, with sustainable and eco-friendly segments capturing margin expansion as carbon pricing mechanisms mature.
- Traditional:Conventional Portland cement production with 90%+ clinker content faces escalating compliance costs under EU ETS carbon pricing and REACH chemical registration requirements.
- Advanced:Predictive kiln control systems and real-time blending optimization reduce fuel intensity and enable dynamic formulation for project-specific performance envelopes.
- Eco-friendly:Calcined clay and supplementary cementitious material blends displace conventional clinker content, with LC3 formulations achieving equivalent 28-day strength at reduced carbon intensity.
- Sustainable:Post-combustion carbon capture retrofits at European cement plants qualify for EU Innovation Fund financing, creating first-mover advantage in negative-emission binder certification.
Traditional technology retains volume concentration. Eco-friendly activation systems are gaining share fastest as procurement mandates tighten across OECD markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-quality limestone deposits for clinker production concentrate in Vietnam, Germany, India, Brazil, and the United States, creating geographic asymmetry between calcination capacity and grinding plant networks. Regulatory pressure from carbon pricing mechanisms and embodied carbon procurement mandates is accelerating regional formulation divergence.
Vietnam
Infrastructure resilience programs and megaproject corridors from Ho Chi Minh City through the Mekong Delta are driving sulfate-resistant binder demand. Development banks embed coastal flood-defense specifications into tender requirements. Domestic grinding plants with integrated calcined clay supply chains capture preference over bulk importers on the North-South Expressway.
Germany
EU Carbon Border Adjustment Mechanism exposure is redirecting procurement toward Portland-limestone cement grades with reduced clinker intensity. The EU ETS carbon pricing mechanism and REACH chemical registration requirements reshape kiln economics. Industrial clusters in North Rhine-Westphalia retrofit plants for post-combustion capture to qualify for EU Innovation Fund financing.
India
Untapped kaolinite reserves in Gujarat and Rajasthan await capital deployment for LC3 kiln retrofitting and clay calcination infrastructure. The Bureau of Indian Standards mandates IS 269 certification for ordinary Portland cement in state-funded projects. The Bureau of Energy Efficiency's PAT scheme drives thermal efficiency benchmarks across cement plants in Maharashtra and Karnataka.
Brazil
Calcined clay activation capacity remains underpenetrated despite abundant kaolinite deposits suitable for LC3 production. Environmental licensing constraints slow greenfield kiln development in Minas Gerais. Ready-mix producers in São Paulo state have adopted blended formulations for structural specifications as activation kilns achieve consistent metakaolin quality.
United States
EPA National Emission Standards for Hazardous Air Pollutants constrain Portland cement kiln operations, particularly in Texas and California production bases. Infrastructure procurement at state level increasingly references Environmental Product Declarations with verified Global Warming Potential figures. Gulf Coast terminals face specification pressure from Mexican low-carbon imports crossing the border.
Hydraulic Binder Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the hydraulic binder supply chain. The market structure consolidates around integrated cement majors with captive limestone reserves, while specialized grinding operators and technology licensors occupy distinct competitive tiers. Three archetypes dominate: integrated multinationals with calcined clay R&D pipelines, regional grinding specialists serving project-specific tenders, and industrial automation providers enabling precision batching systems. Competitive moves center on backward integration into clay calcination assets and strategic partnerships with ready-mix producers for specification lock-in.
Among industrial automation and fluid power specialists, Bosch Rexroth AG, Parker Hannifin Corporation, and Danfoss occupy positions anchoring precision material handling and energy recovery systems for cement terminals and kiln operations. These players exemplify the technology-enablement archetype rather than direct binder production, supplying automated batching interfaces and waste heat capture systems that reduce fuel intensity for clinker manufacturers. Their positioning reflects the decarbonization tooling layer rather than commodity supply.
| Leading Market Players |
|---|
| Bosch Rexroth AG |
| Parker Hannifin Corporation |
| Danfoss |
| KYB Corporation |
| Eaton Corporation |
| Kawasaki Heavy Industries |
| HYDAC International |
| Linde Hydraulics |
| HAWE Hydraulik |
| Others |
Value Network & Pricing Analysis
Kiln capacity utilization above 85 percent in Vietnam and Germany creates scale economies that compress marginal production costs and establish regional price floors for bulk cement. This concentration of calcination assets grants integrated producers pricing power over grinding-only operators, while the EU Carbon Border Adjustment Mechanism and EPA National Emission Standards for Hazardous Air Pollutants layer compliance premiums onto conventional clinker-intensive grades.
Pricing Analysis
The EU ETS carbon pricing mechanism dictates the pricing tier structure across European procurement, separating certified low-clinker formulations from conventional Portland cement through embodied carbon thresholds. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under EN 197-1 and ASTM C1157 protocols alongside volume scale for megaproject offtake. Cost compression in standard-grade bulk cement is intensifying because LC3 formulations with 40 percent clinker reduction are scaling beyond pilot volumes in France and Colombia. Government infrastructure agencies exhibit lowest price sensitivity due to mandated lifecycle carbon accounting, while residential developers through ready-mix channels face acute pressure on delivered cost.
Supply Chain Analysis
Marine terminal congestion at Ho Chi Minh City port underwrites distribution bottlenecks for imported clinker and blended cement entering Vietnam's megaproject corridor. High-quality limestone deposits concentrate in Vietnam, Germany, and India, while kaolinite reserves for calcined clay activation feed from Gujarat and Minas Gerais. Single-source vulnerability runs through specialized calcination kilns capable of consistent metakaolin production, with limited engineering talent for reactivity modulation. Distribution runs through bulk marine terminals and rail-served silo networks for cement, while lime and specialty binders channel through chemical distributors and direct mill-to-project contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent cement majors must defend against substitution by geopolymer and alkali-activated slag systems in niche industrial applications requiring chemical resistance beyond conventional capacity. The threat of calcined clay displacement across structural specifications demands rapid formulation portfolio restructuring.
For Market Incumbents: Fortify backward integration into captive clay calcination assets in India and Brazil before kaolinite reserve access tightens. Secure specification lock-in through strategic partnerships with ready-mix producers on Vietnam's North-South Expressway segments. Accelerate EN 197-1 certification timelines for LC3 blends to preempt grinding-only competitors from capturing megaproject tenders. For New Entrants and Emerging Players: IS 269 certification fast-track through India's Bureau of Indian Standards offers entry into state-funded infrastructure procurement with mandated compliance. Target Brazil's São Paulo ready-mix market where environmental licensing constraints slow incumbent kiln expansion. Pursue direct mill-to-project contracts for sulfate-resistant marine formulations in Vietnam's Mekong Delta coastal defense tenders. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors calcined clay activation specialists with proven kiln retrofitting capabilities and integrated metakaolin supply chains. Long-term viability hinges on carbon capture integration at European production bases qualifying for EU Innovation Fund financing. Monitor post-combustion capture retrofit announcements as the inflection indicator for negative-emission binder certification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Clay Calcination | Captive kaolinite processing in Gujarat secures LC3 supply for Indian megaproject tenders. |
| Carbon Capture Retrofit Deployment | Post-combustion systems at North Rhine-Westphalia plants qualify for EU Innovation Fund support. |
| Digital Twin Kiln Optimization | Real-time predictive analytics reduce fuel intensity for clinker production in German industrial clusters. |
| Long-term Supply Agreement | Ready-mix partnerships on Vietnam's North-South Expressway lock in specification compliance. |
| Green Certification Program | Third-party verified Environmental Product Declarations satisfy Netherlands marine procurement mandates. |
Research Methodology
A standing panel of kiln operations managers, ready-mix procurement directors, infrastructure project engineers, and regulatory compliance officers provided ongoing calibration across primary fieldwork. Secondary validation drew from EU ETS registry data, EPA air emissions filings, Bureau of Indian Standards certification records, and Vietnam Ministry of Construction tender documentation. Bottom-up volume estimates from grinding plant capacity and top-down demand projections from construction activity indices were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by product chemistry grade, application severity tier, end-user procurement authority, and technology decarbonization pathway. CAGRs were derived from regression analysis of historical capacity expansion and forward-looking regulatory compliance cost trajectories. Forecast inputs incorporated clinker substitution rates for LC3 formulations and carbon price elasticity assumptions under EU ETS mechanism evolution.
Underlying assumptions cover sustained infrastructure resilience program funding in Southeast Asia and calcined clay activation kiln commissioning timelines, with deviation risk concentrated in multi-year EN 197-1 certification delays and alternative fuel infrastructure gaps outside major industrial zones. Practitioners should keep alternative scenarios live as EU Carbon Border Adjustment Mechanism enforcement protocols and EPA National Emission Standards revision cycles evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Concrete Aggregate Market
Building & Construction Materials
Global Builder Hardware Market
Building & Construction Materials
Asia-Pacific Construction Adhesives Market
Building & Construction Materials
Poland Cement Market
Building & Construction Materials
Artificial Wood Beams Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
China Oriented Strand Board Market
Building & Construction Materials
Construction Aggregates Market
Building & Construction Materials
Global Floor and Wall Glazed Tiles Market
Building & Construction Materials
Door Hardware Market
Building & Construction Materials
Vinyl Windows Market
Building & Construction Materials
Elastomeric Expansion Joint Market
Building & Construction Materials
Composite Slate Roofing Market
Building & Construction Materials
Metal Grating Market
Building & Construction Materials
United States I-Joist Market
Building & Construction Materials
Construction Sealants Market