
 Transmission and Distribution Infrastructure Market | 2026-2036
Transmission and Distribution Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Transmission and Distribution Infrastructure Market Analytics
F-Gas Regulation is shifting the cost-of-entry calculus for gas-insulated switchgear manufacturers across Europe. Siemens Energy AG leverages its in-house gas-handling technology to sustain compliance leadership. Prysmian Group anchors its position through submarine and land cable integration. Hitachi Energy Ltd. differentiates via digital substation platforms that navigate evolving grid codes.
Transmission and distribution infrastructure encompasses the physical assets—conductors rated for 66 kV to 800 kV, oil-immersed and dry-type transformers, gas-insulated and air-insulated switchgear, and fiber-optic embedded cables—that transport electricity from generation sources to end-use points. Smart Grid technology leads investment flows as utilities deploy advanced metering infrastructure and distribution management systems. Underground cable installations represent the fastest-growing technology segment in dense urban corridors where right-of-way constraints eliminate overhead options. Transformers command the largest component share due to replacement cycles and renewable interconnection requirements.
EPA rules on SF6 emissions, EU F-Gas phasedowns, and India's CEA technical standards for grid connectivity collectively tighten product specifications and extend certification timelines. These frameworks force manufacturers to redesign insulation mediums and accelerate alternative gas development. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned R&D commitments.
Market Dynamics
Grid decarbonization mandates are forcing utilities to replace SF6-dependent switchgear while scaling interconnection capacity for offshore wind and solar farms. This dual pressure is compressing equipment procurement cycles and elevating total-cost-of-ownership calculations.
Growth Catalysts
- EU F-Gas phasedown:The regulation accelerates replacement demand for gas-insulated switchgear across German and French transmission networks, creating pull-through for alternative insulation technologies.
- India's Green Energy Corridors:Central Electricity Authority standards mandate high-capacity evacuation infrastructure, driving transformer and substation orders for renewable zones in Rajasthan and Gujarat.
- Smart meter deployment waves:Advanced metering infrastructure rollouts in Southeast Asian utilities generate recurring hardware demand and software integration services.
Market Restraints
- Copper and grain-oriented electrical steel volatility:Transformer core material costs swing with mining output and trade policy, squeezing manufacturer margins on fixed-price contracts.
- Specialized gas supply concentration:Fluoronitrile and C4-FN alternative gases for switchgear remain concentrated among limited chemical suppliers, creating bottleneck risk.
- SF6 banked inventory lock-in:Utilities with substantial installed bases of gas-insulated equipment face stranded asset risk as phasedown timelines accelerate.
Strategic Opportunities
- Vietnam and Philippines grid expansion:Underpenetrated rural electrification and urban load growth create greenfield substation and distribution automation demand.
- Digital twin convergence:Integration of asset performance management software with physical switchgear enables predictive maintenance revenue streams.
- US Inflation Reduction Act manufacturing credits:Domestic content incentives for electrical equipment reshore transformer and cable production capacity.
Industry Challenges
- High-voltage cable s technician scarcity:Specialized jointing and termination skills for 220 kV+ underground systems face generational workforce gaps.
- Type certification timeline compression:Evolving IEC and national grid code revisions force redesign cycles that outpace traditional validation periods.
- Legacy SCADA integration friction:New digital substation architectures must interoperate with decades-old control systems without operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transmission and Distribution Infrastructure Market |
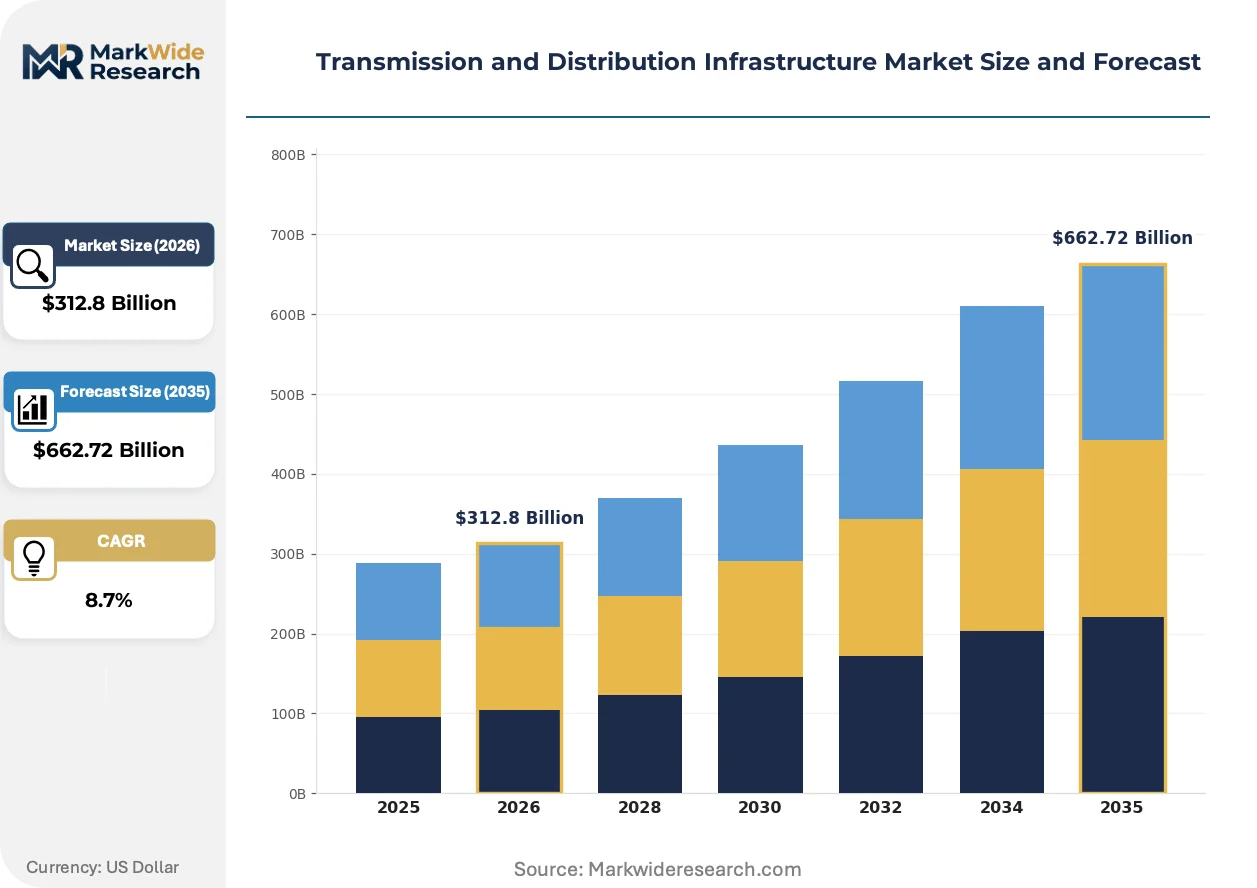
| Market Size in 2026 | $312.8 Billion |
| Market Size in 2035 | $662.72 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Transformers, Switchgear, Conductors, Cables Technology: Smart Grid, Underground, Overhead, Substation Automation End User: Utilities, Industrial, Commercial, Residential Installation Type: New, Upgrades, Maintenance, Replacement |
| Companies Covered | Siemens Energy AG, Prysmian Group, ABB Ltd., Hubbell Incorporated, Nexans S.A., Hitachi Energy Ltd., GE Vernova, NextEra Energy Transmission, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transmission and Distribution Infrastructure Market Evolving Landscape
Equipment architectures are fragmenting from centralized substation designs toward distributed, software-defined configurations. This shift elevates firmware and connectivity as competitive differentiators alongside physical ratings.
Gas-insulated switchgear is modularizing into compact, containerized units that slash installation footprints and enable factory-tested delivery. Offshore wind developers in the North Sea and Baltic are specifying these plug-and-play substations to accelerate project energization timelines. The technology is compressing civil works scope and reducing on-site commissioning risk for remote locations.
EPA's recent SF6 emissions reporting expansion tightens leak detection and repair obligations for US utilities operating gas-insulated equipment above 17.5 kV. The rule forces capital allocation toward monitoring infrastructure and accelerates pilot programs for fluoronitrile blends. Investor-owned utilities in California and Texas are consolidating replacement schedules to align with compliance deadlines.
Utility procurement patterns are fragmenting from bundled EPC contracts toward unbundled component sourcing with separate systems integration responsibility. This shift elevates specialized cable and switchgear vendors while compressing margins for full-scope contractors. European transmission system operators are pioneering this disaggregation to sharpen price transparency on major interconnector projects.
Transmission and Distribution Infrastructure Market Segmentation
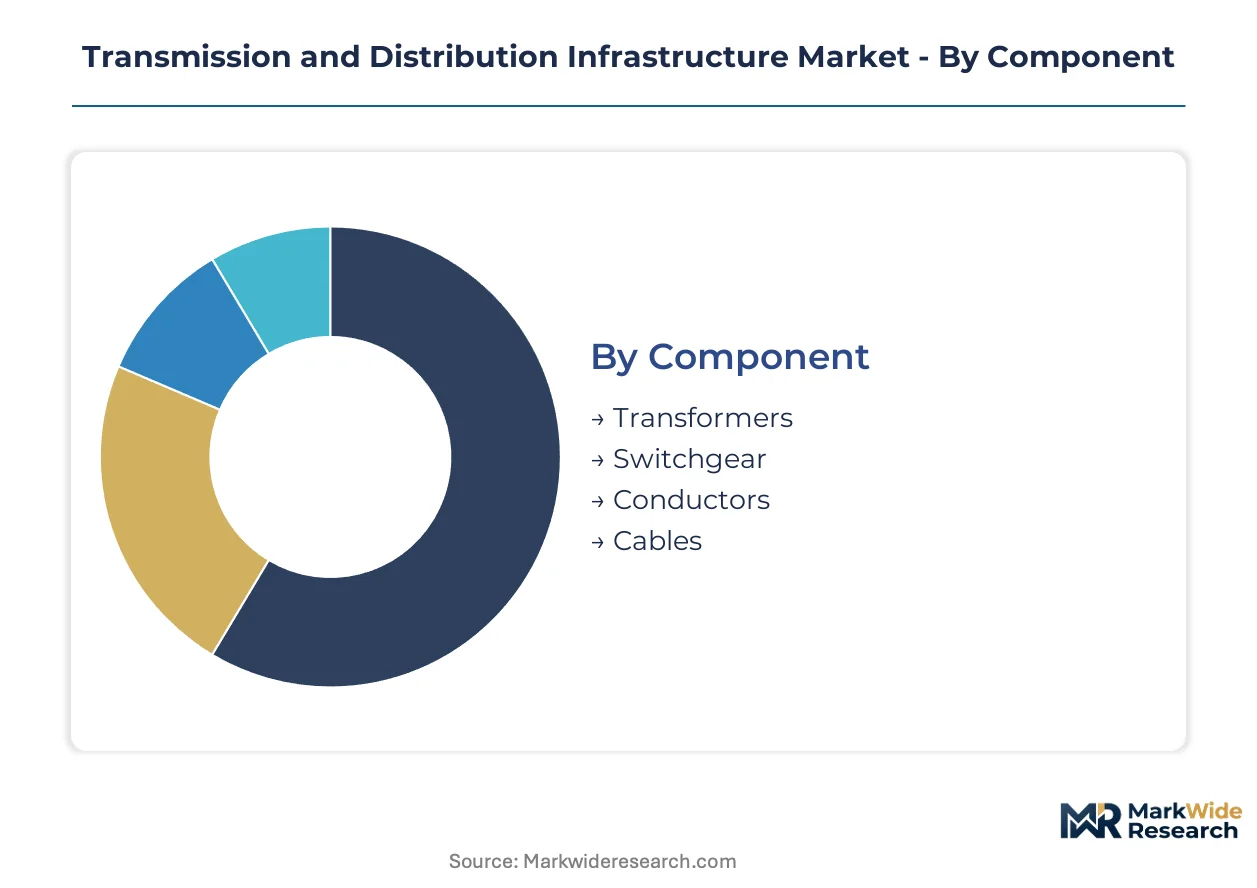
Segmentation in transmission and distribution infrastructure reveals divergent investment cycles across physical components, digital layers, and customer archetypes. Upgrade pressures from aging assets and renewable interconnection requirements create asynchronous growth trajectories that suppliers must navigate.
Component:
Replacement cycles for critical hardware dictate procurement timing across voltage classes and insulation technologies.
- Transformers:Oil-immersed and dry-type units rated from distribution to 800 kV bulk power levels. Demand clusters in India's Green Energy Corridor projects and German grid reinforcement schemes where renewable evacuation strains existing magnetics.
- Switchgear:Gas-insulated and air-insulated assemblies for circuit protection and isolation. EU F-Gas Regulation is accelerating fluoronitrile pilot programs in French and German transmission networks while utilities weigh stranded SF6 inventory.
- Conductors:Aluminum and composite core overhead lines spanning 66 kV to 765 kV. High-temperature low-sag variants gain traction in reconductoring projects where right-of-way constraints prevent new corridor development.
- Cables:Land and submarine extruded and laminated insulation systems. Submarine demand concentrates in North Sea offshore wind export links while urban undergrounding accelerates in Southeast Asian megacities.
Volume placements concentrate in Transformers; the faster expansion belongs to Cables.
Technology:
Capital allocation splits between physical route solutions and digital overlay architectures that optimize existing asset utilization.
- Smart Grid:Advanced metering infrastructure, distribution management systems, and demand response platforms. Southeast Asian utilities in Thailand and Vietnam are deploying AMI at scale to reduce technical losses and enable time-of-use pricing.
- Underground:Extruded cross-linked polyethylene and ethylene propylene rubber cable systems. Dense urban corridors in Manila and Jakarta are eliminating overhead options due to storm resilience mandates and aesthetic requirements.
- Overhead:Traditional lattice tower and compact line designs for rural and inter-regional transmission. Cost advantages persist in India's Rajasthan solar zones and Australian remote mining connections.
- Substation Automation:IEC 61850-compliant digital architectures with merging units and process buses. European transmission system operators are retrofitting legacy air-insulated substations to defer full replacement capital.
Smart Grid commands the dominant share of technology investment; Underground is climbing the fastest as urban density intensifies.
End User:
Procurement authority and technical specifications diverge sharply between regulated utilities and private load centers.
- Utilities:Vertically integrated and unbundled transmission and distribution operators with rate-base recovery mechanisms. State-owned entities in India and investor-owned utilities in Germany are consolidating transformer orders to capture scale economies.
- Industrial:Mining, metals, and petrochemical facilities with captive substations and high-reliability requirements. Indonesian smelter investments and Saudi petrochemical expansions are driving 220 kV+ dedicated infrastructure.
- Commercial:Data centers, hospitals, and campus environments with power quality sensitivities. Hyperscale facility developments in Singapore and Frankfurt are specifying gas-insulated switchgear for footprint minimization.
- Residential:Distribution-level connections and behind-the-meter integration. Rural electrification programs in the Philippines and Vietnam are expanding low-voltage network reach.
Utilities anchor procurement volume; Industrial is gaining share fastest on energy-intensive manufacturing reshoring.
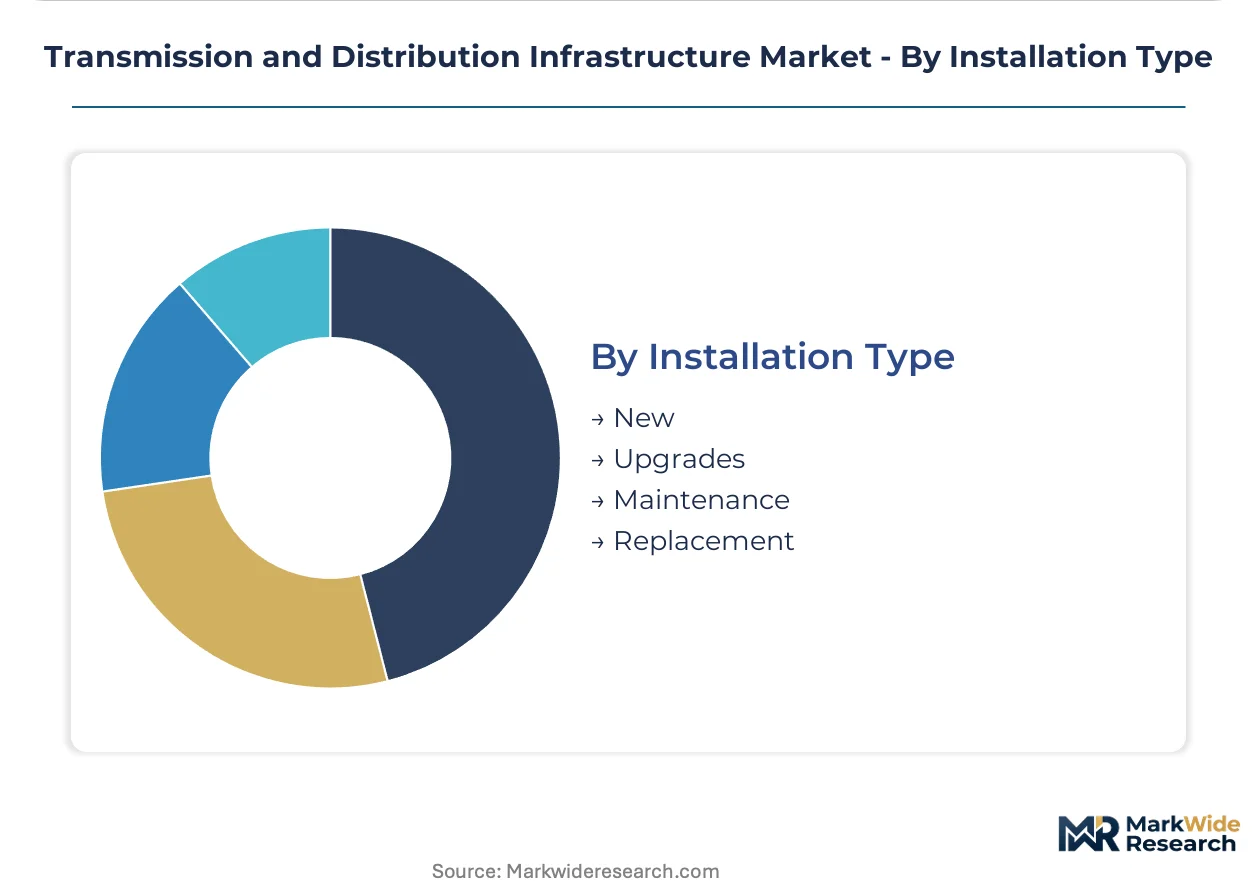
Installation Type:
Project categorization reflects the balance between net capacity addition and lifecycle management of installed base.
- New:Greenfield substations, transmission corridors, and distribution extensions for load growth or generation interconnection. India's renewable energy zones and Vietnam's north-south backbone are primary demand centers.
- Upgrades:Capacity augmentation and voltage class elevation of existing circuits. German 380 kV corridor reinforcement and US interconnection queue upgrades dominate this category.
- Maintenance:Preventive and corrective interventions to sustain reliability indices. Transformer oil processing and circuit breaker mechanism overhauls recur on 15-30 year cycles.
- Replacement:End-of-life asset substitution with modern equivalents. SF6 switchgear replacement under EU F-Gas timelines and pre-1980 transformer retirement are accelerating this segment.
New installations lead absolute spending; Replacement shows the steepest expansion trajectory as regulatory deadlines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra concentrate transformer manufacturing capacity serving India's renewable evacuation corridors. These zones attract joint ventures between European component suppliers and domestic fabricators seeking tariff advantages on imported electrical steel.
India
Green Energy Corridor projects in Rajasthan and Gujarat drive bulk procurement of 765 kV transformers and gas-insulated switchgear. CEA technical standards mandate grid connectivity specifications that extend certification timelines for imported equipment. Manufacturing clusters in Vadodara and Pune are expanding dry-type transformer lines to serve data center load growth in Mumbai and Bangalore.
Germany
Transmission system operators TenneT and 50Hertz accelerate 380 kV corridor reinforcement to integrate North Sea offshore wind. EU F-Gas Regulation forces replacement schedules for SF6-dependent switchgear across Bavarian and North Rhine-Westphalian substations. Siemens Energy anchors industrial activity in Berlin and Nuremberg while sourcing alternative insulation gases through limited chemical supplier channels.
United States
Interconnection queue backlogs in ERCOT and CAISO compress procurement cycles for high-voltage transformers and submarine export cables. EPA SF6 emissions reporting expansion tightens leak detection obligations for utilities operating gas-insulated equipment above 17.5 kV. Manufacturing investments in Texas and South Carolina respond to Inflation Reduction Act domestic content incentives for electrical equipment.
Vietnam
North-south 500 kV backbone expansion and rural electrification programs generate substation automation demand. State-owned EVN consolidates procurement for smart metering infrastructure to reduce technical losses in Hanoi and Ho Chi Minh City load centers. Japanese and Korean cable suppliers are establishing joint-venture extrusion facilities near Haiphong port.
United Kingdom
Offshore wind export links from Dogger Bank and Hornsea drive submarine cable demand through North Sea corridors. Ofgem's RIIO price control framework shapes transmission operator capital allocation toward digital substation retrofits. Manufacturing presence concentrates in Scottish transformer facilities and Northeast cable jointing centers serving North Sea developer clusters.
Transmission and Distribution Infrastructure Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across component and system integration tiers. The market structure shows concentration at the high-voltage transformer and submarine cable ends, with fragmentation in distribution-level switchgear and metering hardware. Three archetypes dominate: integrated energy technology conglomerates with full-scope EPC capability, cable-centric specialists with deep vertical integration into materials, and digital-focused players betting on software-defined substation architectures. Competitive moves center on alternative gas development partnerships and unbundled component sourcing strategies that bypass traditional EPC bundling.
Within the integrated technology tier, Siemens Energy AG and Hitachi Energy Ltd. occupy positions spanning high-voltage equipment through grid automation software. Prysmian Group anchors the cable-specialist segment with combined land and submarine system capabilities. These three exemplify divergent strategic postures: conglomerate breadth versus focused cable integration versus digital platform emphasis. Their relative positioning reflects bets on whether utilities prioritize single-source accountability or unbundled price transparency in procurement.
| Leading Market Players |
|---|
| Siemens Energy AG |
| Prysmian Group |
| ABB Ltd. |
| Hubbell Incorporated |
| Nexans S.A. |
| Hitachi Energy Ltd. |
| GE Vernova |
| NextEra Energy Transmission |
| Schneider Electric SE |
| Others |
Value Network & Pricing Analysis
High-voltage cable s technician scarcity in Germany and Japan widens labor-cost differentials between premium certified installations and economy-tier maintenance contracts. This workforce concentration shapes pricing-tier spreads as utilities absorb expedited jointing premiums or defer projects to standard schedules.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with utilities paying premiums for sub-12-month transformer delivery and securing discounts on spot inventory of standard distribution switchgear. Project-based contracting structures prevail across transmission infrastructure, with price differentiation hinging on IEC 61850 certification tier and bundled commissioning services. Pricing pressure stems from copper and grain-oriented electrical steel commodity swings that compress margins on fixed-price EPC agreements. Industrial end-users in mining and petrochemical sectors exhibit lowest price sensitivity due to captive reliability requirements, while rural electrification programs in Southeast Asia face severe budget constraints.
Supply Chain Analysis
CEA qualification gating and IEC type certification timelines constrain supplier eligibility for Indian transmission projects and European grid reinforcement schemes. Manufacturing concentrates in Germany, India, and China for high-voltage transformers, with submarine cable extrusion anchored in Italy, Japan, and South Korea. Raw material dependencies rest on electrical steel from Japanese and Korean mills, copper cathode from Chilean and Indonesian smelters, and fluoronitrile alternative gases from limited chemical suppliers. Single-source vulnerability for C4-FN insulation gases creates bottleneck exposure. Distribution runs through EPC contractors for bundled projects and direct procurement for unbundled component sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
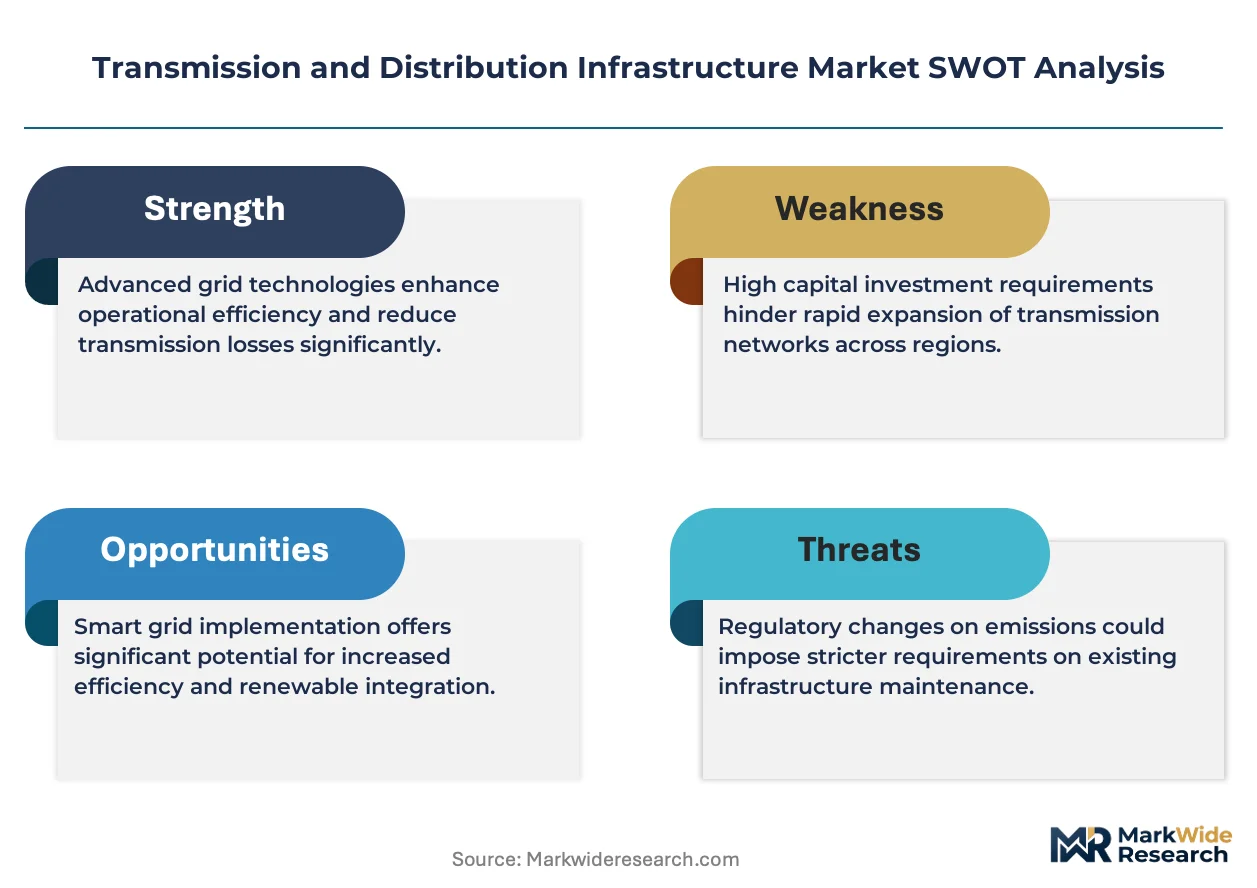
Specialized gas supply concentration for fluoronitrile alternatives props pricing power for certified switchgear manufacturers as utilities race EU F-Gas phasedown deadlines.
For Market Incumbents: Deepen backward integration into electrical steel and copper processing to insulate margins from commodity volatility. Secure captive fluoronitrile supply agreements with chemical partners to preempt competitor access. Anchor capacity expansion in Indian special economic zones to capture Green Energy Corridor transformer demand. For New Entrants and Emerging Players: Digital twin software for predictive maintenance offers a technology-first wedge into utility procurement patterns shifting toward unbundled component sourcing. Target Vietnam's north-south backbone automation and Philippines rural electrification as underpenetrated geographies with streamlined qualification pathways. Pursue joint-venture manufacturing with established cable extruders to bypass certification timeline barriers. For Investors and Strategic Acquirers: The window for entry favors pure-play digital substation software specialists ahead of hardware commoditization. Long-term viability centers on firms with IEC 61850-compliant platforms and recurring software revenue streams. Watch for accelerated utility disaggregation of EPC contracts as inflection signal for component vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Gas Partnership | Secures fluoronitrile supply channels for EU F-Gas compliance leadership. |
| Digital Substation Platform | Captures recurring software revenue as utilities retrofit legacy air-insulated substations. |
| Special Economic Zone Manufacturing | Positions transformer production within India's tariff-advantaged Gujarat clusters. |
| Submarine Cable Joint Venture | Establishes extrusion capacity near Haiphong to serve Vietnam offshore wind export links. |
| Advanced Metering Infrastructure Deployment | Reduces technical losses for EVN and Thai utilities through AMI integration. |
Research Methodology
Multi-period observation of transformer order backlogs, interconnection queue lengths, and alternative gas pilot program announcements anchored the trend analysis, supplemented by interviews with utility planning officers, EPC procurement directors, grid automation engineers, and high-voltage cable jointing contractors. Secondary validation drew from FERC interconnection filings, CEA technical standard notifications, EU F-Gas Regulation implementation reports, and IEC committee draft disclosures. Bottom-up equipment shipment tracking and top-down utility capex aggregation enabled triangulation across independent estimates.
Input-output matrices modeled capacity utilization rates, raw material cost pass-through coefficients, and regulatory compliance timeline impacts across the projection horizon. Segmentation dimensions spanned component category, voltage class, insulation technology, and end-user archetype. CAGRs derived from fitted growth curves against historical replacement cycle data and announced project pipelines. Forecast inputs incorporated copper price volatility scenarios and SF6 banked inventory depreciation schedules.
Several conditions sit outside the modeled scope, including sudden trade policy disruptions affecting electrical steel tariffs and unanticipated breakthroughs in solid-state insulation technologies. Forecasts reflect documented assumptions regarding regulatory phasedown adherence and supply chain qualification timelines. A model refresh is warranted upon material change in EU F-Gas enforcement intensity or EPA SF6 reporting expansion scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Belgium Data Center Construction Market
Infrastructure Construction
APAC Data Center Construction Market
Infrastructure Construction
South America Repair and Rehabilitation Market
Infrastructure Construction
Africa Pipeline Construction Market
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
Finland Transportation Infrastructure Construction Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Oman Transportation Infrastructure Construction Market
Infrastructure Construction
Transportation Infrastructure Construction Market
Infrastructure Construction
Brazil Data Center Construction Market
Infrastructure Construction
Norway Transportation Infrastructure Construction Market
Infrastructure Construction
Middle East Pipeline Construction Market
Infrastructure Construction
Asia-Pacific Transportation Infrastructure Construction Market
Infrastructure Construction
North America Pipeline Maintenance Market
Infrastructure Construction
Australia Transportation Infrastructure Construction Market