
 Air/Pneumatic Balancers Market | 2026-2036
Air/Pneumatic Balancers Market Size, Share, and Industry Trends Forecast 2026-2036
Air/Pneumatic Balancers Market Analytics
Modular balancer configurations with integrated vacuum gripping and sensor feedback are recalibrating buyer choice away from standalone units. Ingersoll Rand leverages its compressed air ecosystem to bundle balancers with downstream tooling, sustaining attach rates in automotive final assembly. Columbus McKinnon Corporation anchors its position through channel control in North American heavy machinery, while Dalmec specializes in custom-capacity units for European aerospace tooling.
Air/pneumatic balancers are force-multiplying lifting devices that use regulated compressed air to suspend and maneuver loads with near-zero operator effort, typically achieving positioning accuracy within millimeters through pneumatic servo valves or mechanical load-sensing bellows. Their primary industrial purpose is to eliminate musculoskeletal strain in repetitive lifting while maintaining cycle speed in paced production environments. The automatic type segment leads in revenue contribution due to integration with programmable logic controllers in industrial automation lines, while the medical equipment application category registers the fastest specification growth as hospitals adopt pneumatic assist for surgical instrument positioning and patient transfer systems. Heavy duty capacity units command the deepest margin pools given forged alloy construction and custom engineering requirements for aerospace and heavy machinery end users.
OSHA ergonomic standards and ISO 4414 pneumatic machinery safety frameworks shape product certification requirements and market access protocols for balancer manufacturers selling into regulated industrial environments. The EPA's compressed air energy efficiency guidelines indirectly influence demand by pushing facilities to audit pneumatic system losses, creating specification preference for low-consumption balancer designs. Stakeholders must monitor how CE marking evolution under the EU Machinery Directive affects testing burdens for automatic-type units with integrated control electronics.
Market Dynamics
Automotive assembly lines in Germany are recalibrating specification requirements toward integrated pneumatic balancer systems with vacuum gripping and sensor feedback, compressing demand for standalone units and rewarding compressed-air ecosystem bundling.
Growth Catalysts
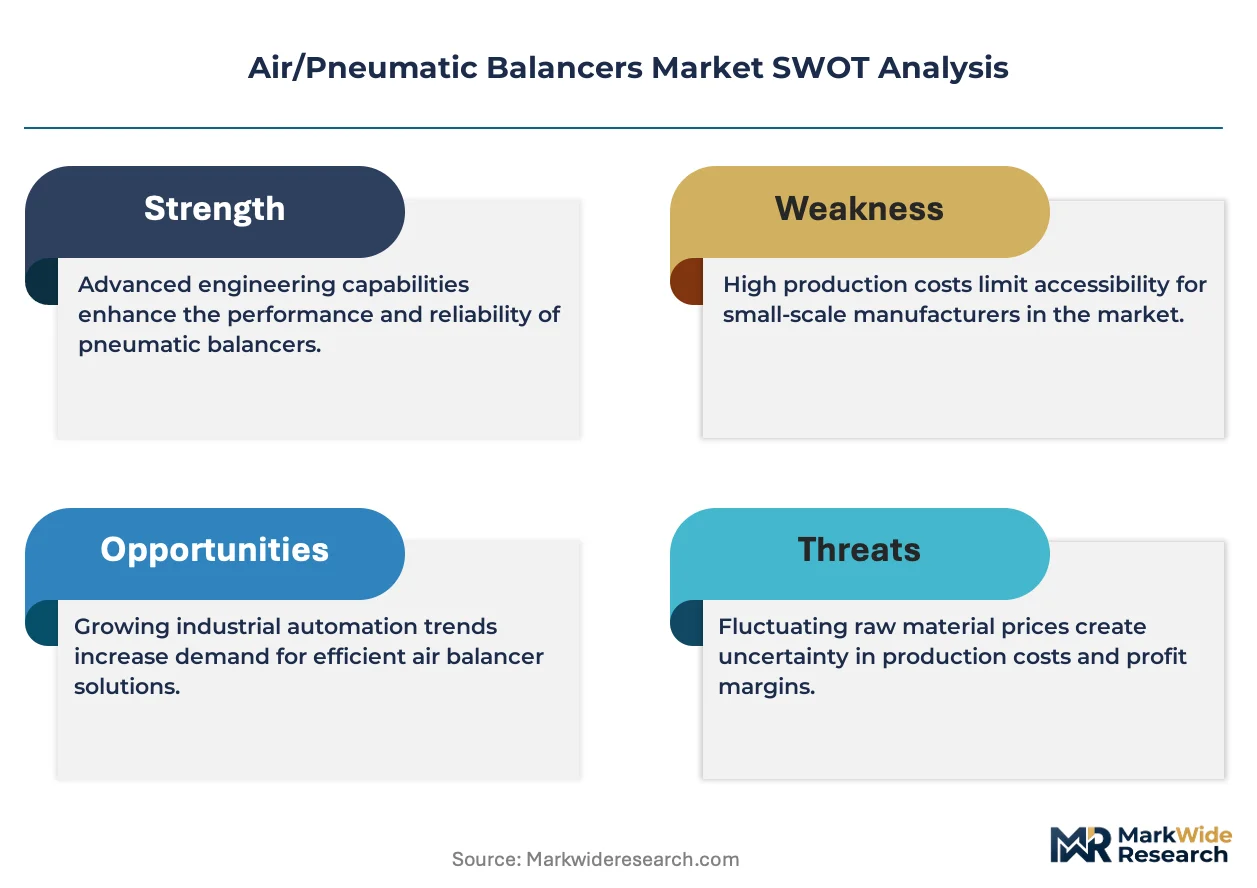
- OSHA Ergonomic Mandates:US workplace safety enforcement is tightening compliance thresholds for repetitive lifting equipment in manufacturing facilities, forcing facility upgrades toward pneumatic assist systems.
- European Aerospace Tooling:Custom-capacity balancer specifications for aircraft assembly jigs in France and Germany are driving engineering intensity and margin expansion for forged alloy construction.
- Compressed Air Energy Efficiency:EPA guidelines on pneumatic system audits are creating specification preference for low-consumption balancer designs among US industrial facilities optimizing energy footprints.
Market Restraints
- Forged Alloy Input Volatility:Heavy-duty capacity units depend on specialized alloy supply chains concentrated in German and Japanese metallurgical producers, exposing margin stability to raw material price swings.
- CE Marking Evolution:The EU Machinery Directive's expanding testing burdens for automatic-type units with integrated control electronics are lengthening certification timelines and raising compliance costs for European market entry.
- Electromechanical Substitution:Servo-electric lifting systems are capturing specification share in cleanroom and precision assembly environments where air quality contamination risks outweigh pneumatic benefits.
Strategic Opportunities
- Medical Equipment Applications:Surgical instrument positioning and patient transfer systems in US and German hospitals represent underpenetrated specification growth as healthcare facilities adopt pneumatic assist for operating theater ergonomics.
- Programmable Logic Controller Convergence:Integration of pneumatic servo valves with industrial automation controllers is opening specification pathways in Japanese and South Korean electronics assembly lines.
- Channel Control Expansion:North American heavy machinery distributors are consolidating specification influence, creating attach-rate opportunities for bundled balancer and downstream tooling offerings.
Industry Challenges
- Pneumatic Servo Valve Calibration Expertise:Millimeter-grade positioning accuracy requires specialized technician training that outpaces vocational program output in Midwest US manufacturing corridors.
- ISO 4414 Compliance Timeline Compression:Accelerated recertification cycles for pneumatic machinery safety frameworks are straining quality assurance bandwidth at mid-cap European producers.
- Legacy System Integration Friction:Retrofitting automatic-type balancers into existing PLC architectures in German automotive plants demands custom engineering that extends deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air/Pneumatic Balancers Market |
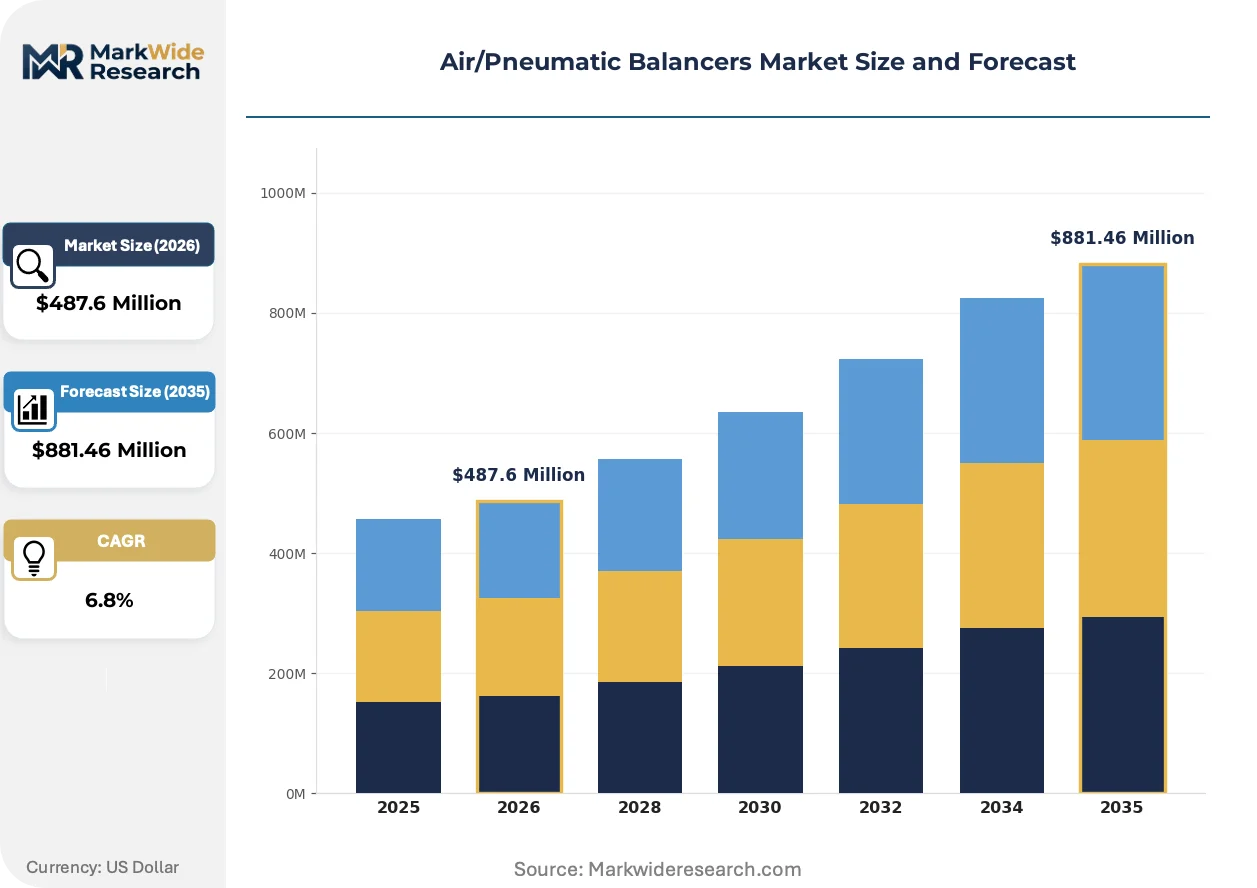
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Single Stage, Double Stage, Variable Stage, Automatic Application: Manufacturing, Assembly, Medical Equipment, Industrial Automation End User: Automotive, Aerospace, Electronics, Heavy Machinery Capacity: Lightweight, Medium Duty, Heavy Duty, Custom |
| Companies Covered | Positech Corporation, GTRADE LLC, Ingersoll Rand, Endo Kogyo Co., Ltd., ATLAS Copco AB, Columbus McKinnon Corporation, Dalmec, Carl Stahl GmbH, ASE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air/Pneumatic Balancers Market Evolving Landscape
Sensor-integrated pneumatic balancer configurations are compressing the specification window for standalone units while regulatory pressure on compressed air energy efficiency reshapes buyer evaluation criteria across industrial verticals.
Integrated vacuum gripping modules with real-time load-position feedback are overtaking conventional mechanical bellows designs in automotive final assembly specifications. Tier-one German OEMs are mandating these configurations for new line installations. The technology is overtaking standalone balancer procurement by embedding lifting and manipulation into single capital decisions.
The EU Machinery Directive's expanded scope for automatic-type units with electronic controls is compressing certification timelines for European market access. Manufacturers must now document functional safety validations for integrated PLCs and servo valves. Heavy-duty capacity producers serving French aerospace tooling are responding by pre-certifying modular control architectures to accelerate customer deployment.
Buyer evaluation criteria are hardening around total cost of ownership metrics that weight compressed air consumption against cycle speed and positioning accuracy. German automotive integrators are unbundling after-sales service contracts from initial capital purchases, forcing balancer suppliers to compete on transparent lifecycle costing. This pattern is most visible in Stuttgart and Wolfsburg assembly corridor procurement specifications.
Air/Pneumatic Balancers Market Segmentation
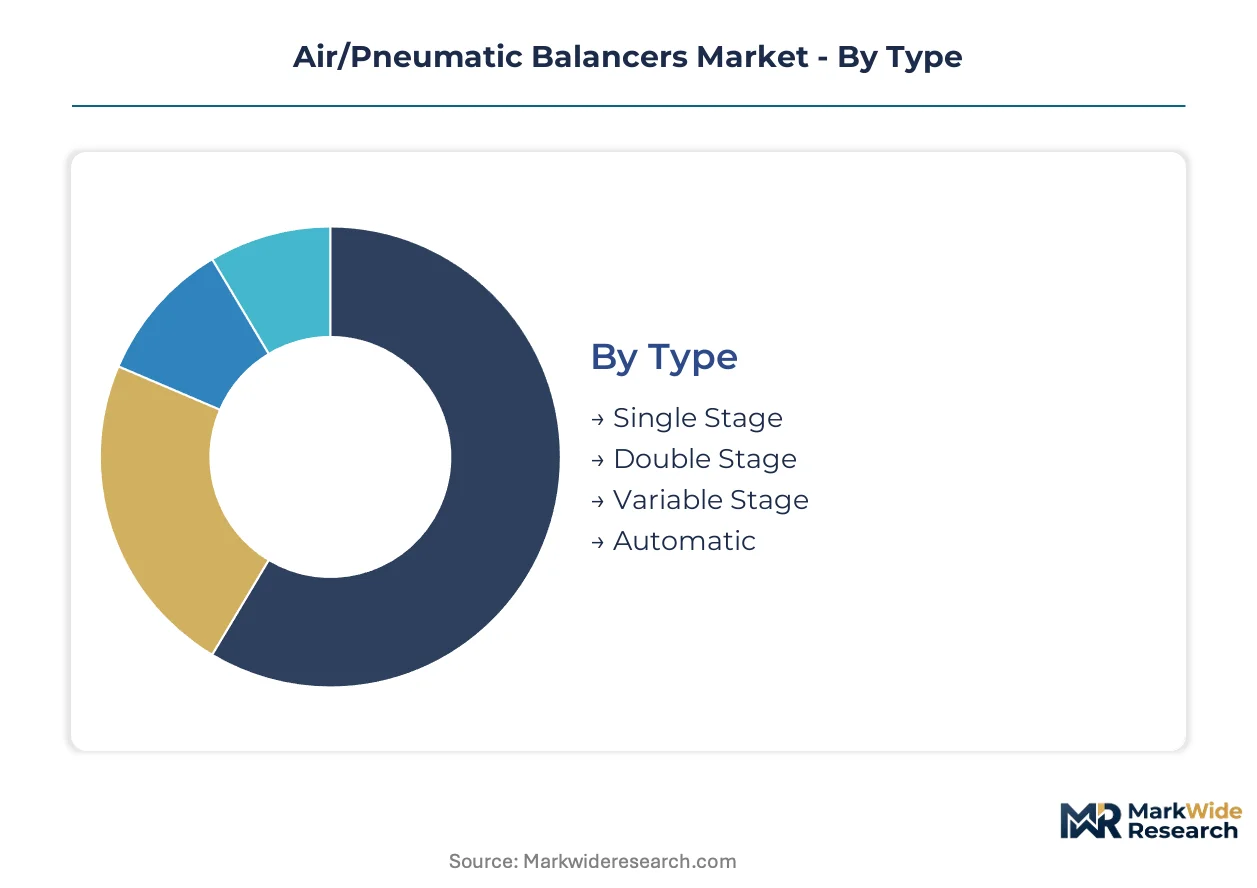
Buyer specification patterns for air/pneumatic balancers diverge sharply across automation integration depth, load capacity thresholds, and regulatory compliance requirements. Procurement committees in German automotive and French aerospace facilities weight segment selection against total cost of ownership metrics and compressed air efficiency audits.
Type:
Automation integration intensity drives type selection, with facilities prioritizing control precision against capital deployment constraints.
- Automatic:Pneumatic servo valves and integrated PLC architectures deliver millimeter-grade positioning accuracy for paced production lines. German automotive OEMs in Stuttgart and Wolfsburg mandate these configurations for new assembly installations, compressing demand for standalone alternatives.
- Variable Stage:Adjustable force multiplication ratios accommodate mixed-model production with fluctuating load weights. Japanese electronics assemblers specify these for smartphone component handling where batch sizes shift frequently.
- Double Stage:Dual-chamber bellows systems provide stepped lifting force for medium-weight components in general manufacturing.
- Single Stage:Fixed-ratio mechanical bellows serve legacy installations with consistent load profiles and limited automation requirements.
Automatic units lead on scale; Variable Stage units lead on momentum.
Application:
End-use environment dictates specification priorities, from cleanroom contamination protocols to surgical theater ergonomics.
- Industrial Automation:PLC-convergent balancer systems with sensor feedback dominate electronics and automotive final assembly. South Korean semiconductor fabs specify these for wafer handling where cycle speed and particulate control converge.
- Medical Equipment:Pneumatic assist for surgical instrument positioning and patient transfer systems is climbing fastest in US and German hospital procurement. OSHA ergonomic mandates and operating theater safety protocols accelerate specification.
- Manufacturing:General material handling across metal fabrication and packaging facilities favors standardized capacity ranges.
- Assembly:Repetitive component mating operations in consumer goods production utilize medium-duty configurations.
Industrial Automation anchors volume deployment; Medical Equipment shows steepest expansion trajectory.
End User:
Industry-specific load characteristics and precision requirements fragment demand across engineering-intensive verticals.
- Automotive:Final assembly lines in Germany specify integrated vacuum gripping modules with real-time feedback. Tier-one OEM procurement compresses standalone balancer demand through bundled compressed-air ecosystem decisions.
- Aerospace:French and German aircraft assembly jigs demand custom-capacity forged alloy construction. ANSM and KBA safety frameworks impose certification burdens that reward pre-validated modular architectures.
- Heavy Machinery:North American distributors consolidate specification influence for mining and construction equipment manufacturing.
- Electronics:Japanese and South Korean cleanroom environments face substitution pressure from servo-electric systems where air quality risks dominate.
Automotive commands the deepest specification volume; Aerospace generates the highest engineering intensity.
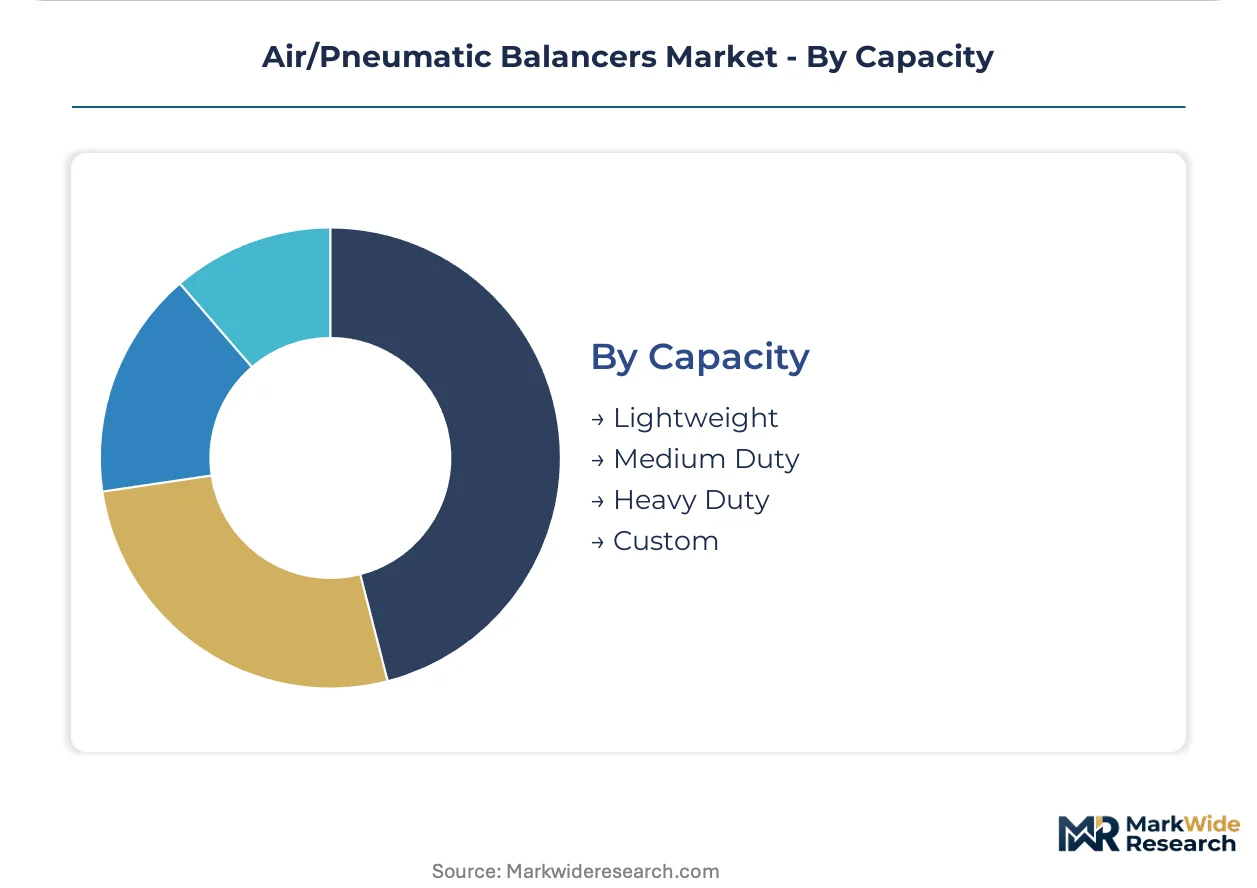
Capacity:
Load weight thresholds determine margin structure, with specialized metallurgy and custom engineering separating premium tiers from standardized offerings.
- Heavy Duty:Forged alloy construction for aerospace and mining equipment handling commands the deepest margin pools. Supply concentration in German and Japanese metallurgical producers exposes pricing to raw material volatility.
- Custom:Engineering-to-order for non-standard load geometries and integration constraints serves French aerospace tooling. EU Machinery Directive testing burdens lengthen certification timelines for these configurations.
- Medium Duty:Standardized ranges for general manufacturing balance capital cost against maintenance accessibility.
- Lightweight:Compact bellows systems for electronics and medical applications prioritize energy consumption minimization.
Heavy Duty leads on margin capture; Custom capacity shows fastest specification growth in regulated environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pneumatic balancer technology first achieved industrial scale in post-war German manufacturing corridors, where automotive assembly lines demanded precision load positioning. This engineering heritage continues to concentrate specification authority in Central European industrial clusters.
Germany
Automotive OEMs in Stuttgart and Wolfsburg mandate integrated vacuum gripping modules with real-time sensor feedback for new assembly installations. KBA safety frameworks impose certification burdens that compress demand for standalone units. The Baden-Württemberg automotive corridor generates the deepest specification volume for forged alloy heavy-duty configurations.
United States
OSHA ergonomic enforcement is tightening compliance thresholds for repetitive lifting equipment across Midwest manufacturing facilities. EPA compressed air energy efficiency guidelines push industrial plants toward low-consumption balancer audits. The Michigan-Ohio automotive belt exhibits the fastest retrofit specification growth as legacy lines upgrade pneumatic assist systems.
France
Aircraft assembly jigs in Toulouse and Nantes demand custom-capacity forged alloy construction with millimeter-grade positioning accuracy. ANSM safety protocols for medical equipment applications accelerate hospital procurement of pneumatic assist for surgical theaters. The Occitanie aerospace cluster anchors engineering-to-order demand for specialized load geometries.
Japan
Electronics assemblers specify variable stage balancers for smartphone component handling where batch sizes shift frequently. METI industrial automation incentives support PLC-convergent system adoption in Nagoya and Osaka manufacturing corridors. Cleanroom environments in Kyushu semiconductor fabs face substitution pressure from servo-electric alternatives.
South Korea
Semiconductor fabrication facilities in Seoul and Busan specify automatic-type balancers with sensor feedback for wafer handling where cycle speed and particulate control converge. National industrial competitiveness programs accelerate specification of pneumatic servo valve integration. The Gyeonggi electronics cluster represents the fastest-growing demand pocket for precision load positioning systems.
Air/Pneumatic Balancers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across engineering intensity and metallurgical specialization. The vendor base organizes into three tiers: forged alloy heavy-duty specialists, compressed-air ecosystem bundlers, and standardized capacity generalists. Two dominant competitive moves are reshaping positioning: backward integration into captive alloy supply chains and pre-certification of modular control architectures to compress EU Machinery Directive timelines.
Within the ecosystem-bundler tier, Ingersoll Rand exemplifies compressed-air platform leverage. Columbus McKinnon Corporation anchors North American channel control positions. Dalmec occupies a specialist position in custom-capacity European aerospace tooling. These three players represent distinct strategic archetypes without overlapping core positioning.
| Leading Market Players |
|---|
| Positech Corporation |
| GTRADE LLC |
| Ingersoll Rand |
| Endo Kogyo Co., Ltd. |
| ATLAS Copco AB |
| Columbus McKinnon Corporation |
| Dalmec |
| Carl Stahl GmbH |
| ASE Systems |
| Others |
Value Network & Pricing Analysis
Forged alloy input costs flow from German and Japanese metallurgical producers through heavy-duty capacity tiers into aerospace and mining equipment specifications, compressing margin stability for custom-engineered units while standard configurations absorb volatility through scale.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates forged alloy heavy-duty configurations from medium-duty standardized ranges and lightweight compact systems. Price differentiation hinges on ISO 4414 certification grade and after-sales service bundling, with German automotive integrators unbundling lifecycle contracts to force transparent total cost of ownership competition. Cost compression in heavy-duty tiers is intensifying because raw material volatility concentrates in specialized alloy supply chains. General manufacturing facilities exhibit highest price sensitivity, while French aerospace tooling procurement shows lowest sensitivity due to engineering-to-order requirements.
Supply Chain Analysis
Domestic-content mandates in EU defense-adjacent aerospace applications are reshaping sourcing patterns for forged alloy components and pneumatic servo valve assemblies. Supply concentrates in Germany, Japan, and China for metallurgical inputs, precision machining, and control electronics respectively. The chain draws from specialized alloy feedstock, servo valve subassemblies, and sensor modules as core inputs. Single-source vulnerability runs through German metallurgical producers for aerospace-grade forged alloys. Distribution runs through North American heavy machinery distributors and European industrial automation integrators as dominant downstream channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where OSHA ergonomic enforcement in the US Midwest creates specification pull at lower engineering intensity than EU Machinery Directive compliance in German automotive corridors.
For Market Incumbents: Acquire captive alloy supply capabilities to insulate margin pools from Japanese and German metallurgical price volatility. Pre-certify modular PLC architectures to compress EU Machinery Directive timelines for automatic-type units. Channel control investments in North American heavy machinery distribution defend attach-rate positions against compressed-air ecosystem bundlers. For New Entrants and Emerging Players: OSHA workplace safety mandates in US manufacturing facilities open a window for ergonomic assist system specification in underpenetrated Midwest automotive retrofit corridors. Medical equipment applications in German hospital procurement represent the most penetrable white-space target given accelerating surgical theater adoption. A go-to-market angle anchored on transparent lifecycle costing unbundled from capital purchase contracts aligns with Stuttgart and Wolfsburg procurement pattern shifts. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap European producers face ISO 4414 recertification bandwidth constraints and CE marking timeline compression. Long-term viability favors forged alloy heavy-duty specialists with backward integration into metallurgical supply or pre-validated modular control architectures. The signal to watch is German automotive OEM procurement specification shifts toward integrated vacuum gripping modules that compress standalone balancer demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forged Alloy Supply | Captive metallurgical sourcing insulates margin pools from German and Japanese raw material volatility. |
| Pre-Certification of Modular PLC Architectures | Accelerated EU Machinery Directive compliance compresses deployment timelines for French aerospace tooling. |
| Channel Control Expansion in North America | Distributor consolidation in heavy machinery creates attach-rate leverage for bundled downstream tooling. |
| Medical Equipment Application Development | OSHA ergonomic mandates and ANSM safety protocols accelerate hospital procurement for surgical theater systems. |
| Low-Consumption Balancer Design Engineering | EPA compressed air efficiency guidelines push specification preference toward energy-optimized pneumatic architectures. |
Research Methodology
Bottom-up automotive and aerospace end-use modeling reconciled against top-down pneumatic equipment supply-side tracking forms the analytical core of this study. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads were cross-validated against secondary sources including OSHA enforcement databases, ISO certification registries, EPA energy audit guidelines, and EU Machinery Directive implementation records. Trade flow analysis of forged alloy components and pneumatic servo valve imports provided additional triangulation anchors.
Input-output matrices mapped capacity deployment across automatic, variable stage, and heavy-duty segments against industrial automation, medical equipment, and aerospace application demand. Segmentation dimensions modeled include type tier, load capacity threshold, end-use vertical, and regional regulatory cluster. CAGRs were derived from slope analysis of specification intensity curves and installation base expansion rates. Forecast inputs incorporated OSHA enforcement trajectory projections and EU Machinery Directive scope evolution for electronic control integration.
Revisions become necessary when OSHA ergonomic mandate enforcement intensity shifts, EU Machinery Directive testing burden timelines compress further, or servo-electric substitution accelerates in cleanroom electronics environments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Modular Conveyor System Market
Material Handling Equipment
Automatic Conveyor Market
Material Handling Equipment
Truck Mounted Loader Cranes Market
Material Handling Equipment
Asia-Pacific Forklift Truck Market
Material Handling Equipment
Global Loading Dock Bumpers Market
Material Handling Equipment
Port Material Handling Equipment Vehicle Market
Material Handling Equipment
Level Loader Market
Material Handling Equipment
North America Conveyor Belt Market
Material Handling Equipment
Electric Wire Rope Hoist Market
Material Handling Equipment
Cable Conduit Systems Market
Material Handling Equipment
Electric Single Beam Crane Market
Material Handling Equipment
Automated Material Handling (AMH) Equipment Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
Heavy Duty Loading Ramps Market
Material Handling Equipment
Pharmaceutical Material Handling Equipment Market