
 Home Standby Gensets Market | 2026-2036
Home Standby Gensets Market Size, Share, and Industry Trends Forecast 2026-2036
Home Standby Gensets Market Analysis
Subscription-based leasing and power-as-a-service financing is reshaping competitive entry in the home standby gensets space, lowering capital barriers for middle-income households. Generac Holdings Inc leverages its captive dealer network to dominate residential installations across storm-belt states. Kohler Co anchors its position through backward integration into engine casting and alternator winding. Cummins Inc competes on dual-fuel engineering that bridges propane infrastructure gaps in rural markets.
Home standby gensets are permanently installed internal combustion engine-generator sets, typically rated between 10 kW and 20 kW, that automatically sense utility failure and transfer electrical load within 10 to 30 seconds to maintain critical household circuits. These systems employ air-cooled or liquid-cooled engines coupled with brushless alternators to deliver sustained voltage regulation for residential and small commercial applications during grid interruptions. Natural gas and propane configurations now lead fuel type adoption where utility gas lines exist, while diesel retains share in off-grid and rural installations where fuel storage independence matters. The 20 kW power rating band captures the fastest-growing structural segment as larger homes with electric HVAC and EV charging loads require expanded capacity margins.
The EPA governs stationary engine emissions under 40 CFR Part 60, compelling manufacturers to invest in catalytic aftertreatment and closed-loop fuel control for compliance. State-level building codes in Florida and Texas mandate automatic transfer switches and minimum setback distances that shape installation economics and product form factors. The National Electrical Code, enforced by local AHJs across U.S. jurisdictions, dictates grounding, fuel line sizing, and load calculation standards that determine genset specification. Stakeholders must monitor NHTSA-adjacent noise ordinances and evolving carbon intensity scoring that could reweight propane against natural gas in municipal permitting decisions.
Market Dynamics
The EPA Tier 4 Final emissions framework is forcing manufacturers to abandon carbureted gasoline architectures for closed-loop fuel injection and three-way catalytic aftertreatment, fundamentally restructuring engine sourcing and supplier relationships across the residential genset value chain.
Growth Catalysts
- Suburban construction codes:Florida and Texas building ordinances now classify automatic standby power as mandatory infrastructure in new residential developments above specified square footage thresholds.
- Natural gas reticulation:Expanding utility pipeline networks in coastal hurricane zones enable cleaner-burning genset configurations that satisfy municipal air quality permits where diesel faces restrictions.
- Grid instability normalization:California Public Utilities Commission-mandated public safety power shutoffs have recast backup generation from insurance purchase to essential household infrastructure.
Market Restraints
- Copper and silicon steel volatility:Alternator winding materials face price swings that compress manufacturing margins and complicate long-term dealer pricing contracts.
- Installation labor scarcity:Certified electrician shortages in storm-belt states extend project timelines and inflate soft costs for residential end-users.
- Permitting fragmentation:Municipality-specific setback distances and noise ordinances prevent standardized product platforms from scaling across jurisdictions.
Strategic Opportunities
- EV load integration:Bidirectional charging compatibility positions gensets as grid-tied energy arbitrage assets, not merely outage insurance.
- Subscription financing:Power-as-a-service models bypass capital expenditure barriers for middle-income households in Texas and Florida markets.
- Rural propane bridging:Dual-fuel engineering captures off-grid installations where natural gas infrastructure remains uneconomical to extend.
Industry Challenges
- Emissions certification timelines:EPA 40 CFR Part 60 validation cycles extend product launch windows and strain R&D resource allocation.
- Dealer network quality variance:Installation craftsmanship inconsistency across independent contractors damages brand equity and drives warranty claim escalation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Standby Gensets Market |
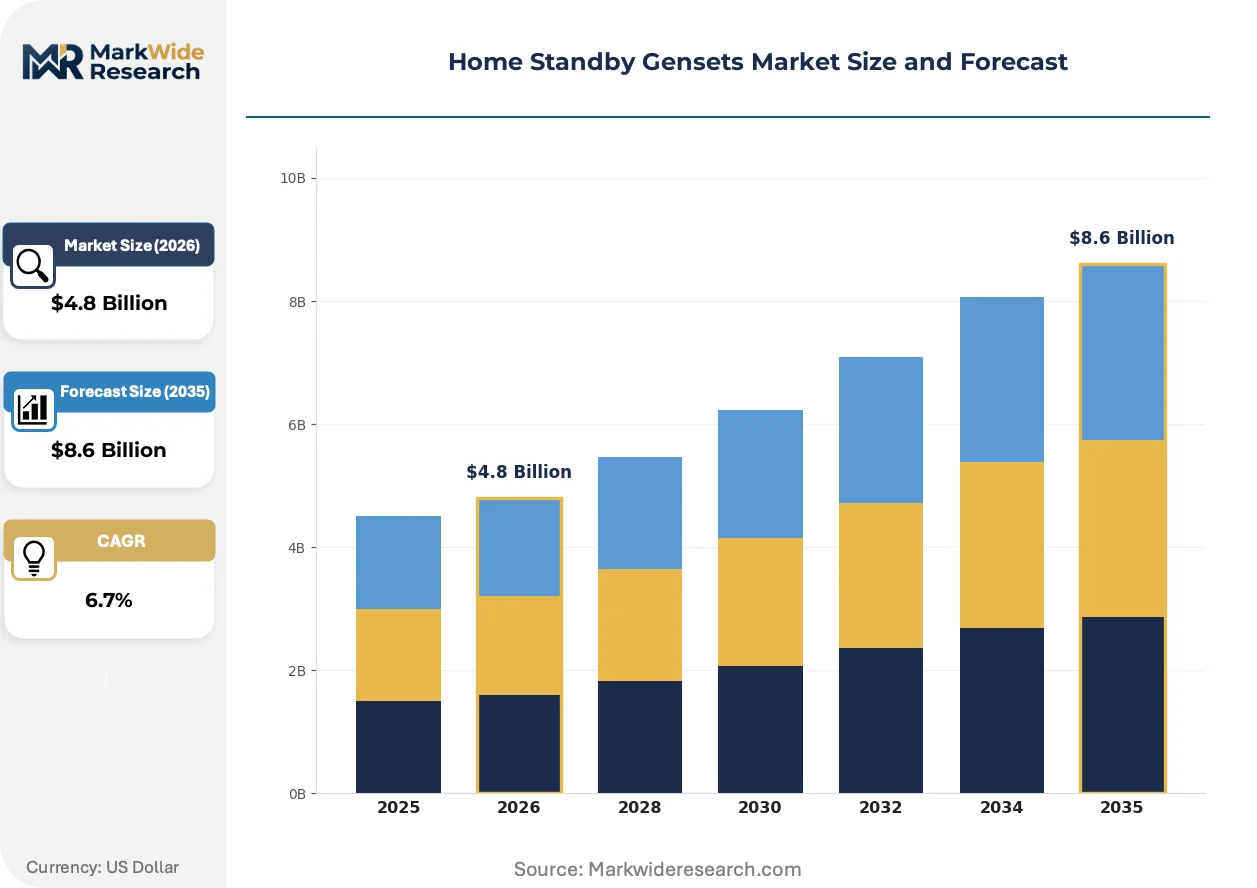
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Rating: 5 kW, 10 kW, 15 kW, 20 kW Fuel Type: Natural Gas, Propane, Diesel, Bi-Fuel Installation Type: On-Grid, Off-Grid, Portable, Fixed Control Mechanism: Manual, Automatic, Remote, Hybrid |
| Companies Covered | Generac Holdings Inc, Kohler Co, Briggs & Stratton Corporation, Cummins Inc, Honda Motor Co Ltd, Champion Power Equipment, Yamaha Motor Co Ltd, Atlas Copco AB, Kirloskar Oil Engines Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Standby Gensets Market Emerging Trajectories
Technology migration, regulatory stringency, and financing model disruption are converging to restructure how residential standby power is specified, procured, and monetized across North American markets.
Air-cooled engine architectures are migrating from cast-iron cylinder blocks to aluminum-silicon alloys with plasma-coated bores. Suburban homeowners with electric HVAC and EV charging loads specify these lighter platforms for pad-mounted installations where weight constraints matter. The shift compresses engine manufacturing lead times and enables modular genset form factors that reduce shipping costs.
California Air Resources Board (CARB) small off-road engine standards are accelerating catalytic aftertreatment adoption in gensets below 25 horsepower. Manufacturers now integrate closed-loop oxygen sensors and electronic fuel injection to satisfy oxides of nitrogen limits that phase in through 2028. The compliance burden falls heaviest on air-cooled product lines serving the California residential retrofit segment.
Homeowner purchasing behavior is fragmenting across generational cohorts. Baby boomer buyers favor single-purchase ownership with extended service contracts, while millennial households prefer subscription-based leasing with bundled maintenance. The divergence forces manufacturers to dual-track distribution: captive dealer networks for traditional buyers and direct-to-consumer digital platforms for subscription adopters, with Florida and Texas showing the most pronounced channel bifurcation.
Home Standby Gensets Market Segmentation
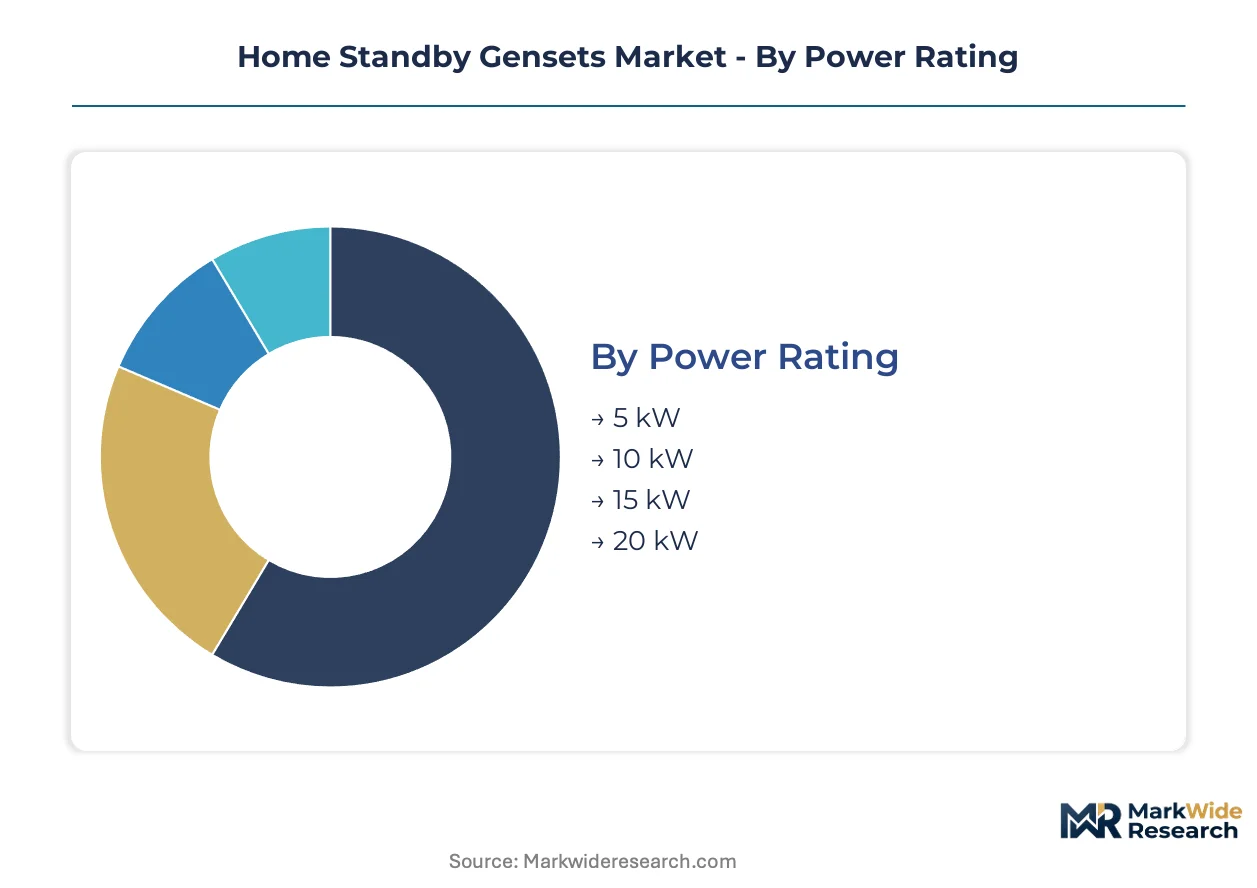
Segmentation in home standby gensets reveals how technical specifications align with distinct installation economics and regulatory environments. Power rating and fuel type decisions cascade through permitting requirements, dealer network capabilities, and homeowner financing preferences.
Power Rating:
Mature 10 kW and 15 kW platforms dominate current installations, while emerging 20 kW configurations capture expanding residential loads.
- 5 kW:Compact air-cooled units serve essential-circuit backup for smaller homes below 2,000 square feet. Demand concentrates in rural Texas counties where modest dwellings and propane tank constraints limit capacity requirements.
- 10 kW:Liquid-cooled or heavy-duty air-cooled architectures handle whole-house coverage for average-sized suburban homes. Florida building codes in hurricane-prone counties specify this threshold as minimum automatic standby capacity for new construction above specified square footage.
- 15 kW:Mid-capacity segment bridges electric HVAC loads and basic household circuits. California retrofit installations favor this rating where solar-plus-storage configurations supplement rather than replace grid dependence.
- 20 kW:Expanded alternator windings and enhanced engine displacement accommodate electric vehicle charging alongside residential HVAC. Texas and Florida suburban developments with integrated smart home infrastructure specify this capacity tier for new construction.
10 kW retains volume leadership; 20 kW holds the steepest expansion curve.
Fuel Type:
Natural gas infrastructure availability creates a geographic bifurcation between pipeline-connected suburbs and propane-dependent rural markets.
- Natural Gas:Direct utility connection eliminates fuel storage and refueling logistics. Demand clusters in Florida coastal subdivisions where municipal air quality permits restrict diesel and EPA Tier 4 Final compliance costs favor cleaner-burning methane configurations.
- Propane:Above-ground or buried tank installations provide fuel independence where utility reticulation stops. Rural Texas Hill Country and California Sierra Nevada foothill properties specify propane for off-grid resilience during extended outages.
- Diesel:Liquid-cooled compression-ignition engines deliver thermal efficiency and long runtimes. Agricultural and large estate applications in California Central Valley maintain diesel preference for extended irrigation and equipment power.
- Bi-Fuel:Dual-fuel carburation or injection systems switch between natural gas and propane based on availability. Texas markets with intermittent pipeline pressure during storm events specify bi-fuel for operational flexibility.
Natural gas captures the broadest addressable market; bi-fuel configurations gain share fastest in infrastructure-constrained zones.
Installation Type:
Fixed permanent installations anchor revenue, while portable configurations serve transitional and price-sensitive demand.
- On-Grid:Automatic transfer switch integration with utility service entrance panels. Florida and California jurisdictions mandate this configuration for code-compliant standby power in residential occupancies.
- Off-Grid:Standalone generator-fed distribution panels without utility interconnection. Remote Texas ranch properties and California mountain communities specify off-grid for primary power independence.
- Portable:Wheel-mounted or liftable units requiring manual connection and fueling. Temporary housing and construction-phase power in storm-recovery zones deploy portable units pending permanent installation.
- Fixed:Pad-mounted or slab-anchored permanent installations with weather enclosures. Suburban developments across all three core states standardize fixed installations for property value and insurance compliance.
Fixed installations dominate revenue; off-grid specifications climb fastest in utility-reliability-challenged regions.
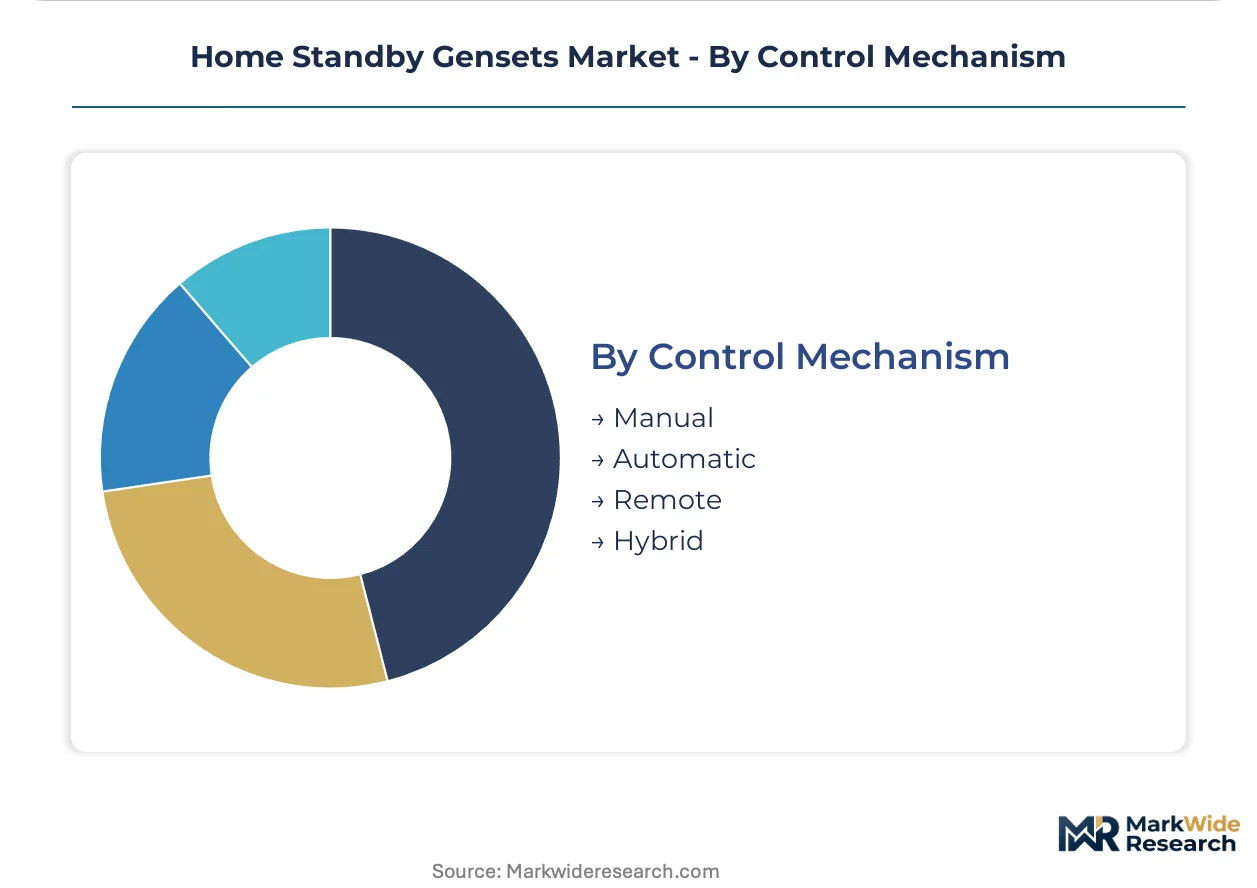
Control Mechanism:
Automatic control architectures command premium positioning, while manual systems persist in cost-constrained and specialized applications.
- Manual:Requires homeowner presence for startup, transfer switch operation, and shutdown. Secondary structures and agricultural outbuildings in rural markets specify manual control for capital cost minimization.
- Automatic:Utility failure detection triggers engine start and load transfer without human intervention. Florida building codes mandate automatic control for designated essential circuits in coastal high-velocity hurricane zones.
- Remote:Cellular or Wi-Fi enabled monitoring and control via smartphone applications. Tech-forward California homeowners and Texas second-property owners specify remote capability for operational visibility.
- Hybrid:Combines automatic failover with manual override and remote monitoring capabilities. Premium suburban installations across all markets specify hybrid control for maximum operational flexibility.
Automatic control retains installation volume leadership; hybrid configurations expand most quickly in high-value residential segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates sharply in Florida and Texas, where hurricane-driven code mandates and grid instability normalize premium standby power as essential infrastructure, while California's regulatory complexity compresses margins through extended compliance timelines.
United States
Florida and Texas dominate volume, with suburban construction codes in coastal counties mandating automatic standby power for new developments above specified square footage thresholds. The EPA's 40 CFR Part 60 framework governs stationary engine emissions, compelling manufacturers toward catalytic aftertreatment and closed-loop fuel injection. Miami-Dade and Houston metropolitan clusters anchor installation density, where certified electrician networks and captive dealer infrastructure concentrate to serve storm-belt demand.
Germany
Industrial and commercial backup applications drive genset specification, with manufacturing facilities prioritizing grid resilience amid energy transition volatility. The EU Green Deal and national Klimaschutzgesetz emissions targets pressure diesel architectures toward natural gas and hydrogen-ready configurations. Bavaria's industrial corridor, particularly around Munich and Nuremberg, concentrates demand from precision manufacturing and data center operators seeking uninterrupted power.
Japan
Seismic risk and typhoon exposure sustain residential and small commercial standby adoption, with building codes in Tokyo and Osaka mandating backup power for critical facilities. METI's GX League initiative and carbon neutrality targets push manufacturers toward cleaner-burning natural gas and fuel cell hybrid architectures. The Kanto region, centered on Tokyo-Yokohama, anchors premium-tier demand from high-value residential and medical facility applications.
Australia
Bushfire-driven grid isolation and rural electrification gaps sustain off-grid and backup genset demand, particularly in Queensland and Western Australia mining communities. State-level environmental protection agencies impose tiered emissions standards that favor liquid-cooled diesel in remote applications where runtime duration matters. Perth's resource sector and Brisbane's suburban expansion represent contrasting demand poles—industrial durability versus residential convenience.
India
Grid reliability deficits and commercial uptime requirements sustain diesel genset dominance, though urban air quality mandates in Delhi-NCR and Mumbai accelerate natural gas adoption where pipeline infrastructure exists. The Central Electricity Authority's emission norms for diesel generator sets compel particulate filter retrofits and cleaner fuel specifications. Maharashtra and Gujarat industrial clusters, particularly Pune and Ahmedabad manufacturing belts, concentrate mid-range power demand from automotive and pharmaceutical sectors.
Home Standby Gensets Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in alternator winding and engine casting. The market structure consolidates around three to five vertically integrated manufacturers with captive distribution networks, while mid-scale assemblers compete on regional customization and price-accessible configurations. Two strategic archetypes dominate: full-system providers with end-to-end installation and service ecosystems, and engine-alternator specialists supplying private-label platforms to regional brands. Competitive intensity centers on dealer network expansion and emissions certification speed rather than raw manufacturing scale.
Within the integrated-system tier, Generac Holdings Inc and Kohler Co exemplify platform dominance through captive supply chains and installation infrastructure. Cummins Inc occupies a distinct position bridging industrial engine heritage with residential application engineering. These three anchors represent divergent strategic postures—dealer network density, backward integration into casting and winding, and dual-fuel technical flexibility—rather than uniform competitive approaches.
| Leading Market Players |
|---|
| Generac Holdings Inc |
| Kohler Co |
| Briggs & Stratton Corporation |
| Cummins Inc |
| Honda Motor Co Ltd |
| Champion Power Equipment |
| Yamaha Motor Co Ltd |
| Atlas Copco AB |
| Kirloskar Oil Engines Limited |
| Others |
Supply Flow & Price Mechanics
Copper and silicon steel price volatility in alternator winding materials compresses manufacturing margins and forces tiered pricing stratification across premium certified, standard compliant, and economy non-certified product bands while reshaping supplier relationships toward long-term offtake contracts.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium UL-certified, standard EPA-compliant, and economy non-certified product levels. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because certified electrician shortages inflate installation soft costs. Price sensitivity concentrates among millennial subscription adopters, while baby boomer ownership buyers show minimal elasticity.
Supply Chain Analysis
Engine casting foundries in the United States, alternator winding specialists in Mexico, and catalytic converter suppliers in Canada hold concentrated contract-manufacturing capacity. The supply chain draws from copper rod, silicon steel laminations, and electronic fuel injection components. Single-source vulnerability sits with EPA-certified catalytic aftertreatment suppliers facing extended validation timelines. Distribution runs through captive dealer networks in Florida and Texas storm-belt markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The home standby gensets market represents an early-cycle expansion story as suburban construction codes in hurricane-prone coastal zones reclassify automatic standby power from insurance purchase to mandatory infrastructure.
For Market Incumbents: Build captive installation service moats through certified electrician apprenticeship programs and exclusive dealer territory allocations. Battery storage hybrids and solar-plus-storage substitutes threaten genset attach rates in California retrofit segments. Backward integration into engine casting secures margin control against commodity volatility. For New Entrants and Emerging Players: Build out white-space positions in rural Texas propane-dependent markets and California Sierra Nevada off-grid estates where natural gas infrastructure remains uneconomical. The most penetrable segment is middle-income Florida households bypassed by traditional dealer networks. A direct-to-consumer digital platform with subscription financing captures subscription-preferring millennial buyers. For Investors and Strategic Acquirers: The market sits at a code-mandated adoption phase that favors vertically integrated manufacturers with captive distribution. Long-term viability hinges on emissions certification speed and dual-fuel engineering capability. Acquisition targets should show EPA Tier 4 Final validation completion and established dealer density in storm-belt states. Quarterly review of California CARB rulemaking timelines and Florida building code amendment dockets is advised to detect inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Engineering Development | Captures rural propane markets and storm-event operational flexibility in Texas infrastructure gaps. |
| Catalytic Aftertreatment Certification | Unlocks California CARB compliance and Florida municipal air quality permit eligibility. |
| Subscription Financing Platform | Bypasses capital barriers for millennial households in Florida and Texas middle-income segments. |
| Certified Electrician Network Expansion | Reduces installation timeline inflation and warranty claim escalation from craftsmanship variance. |
| EV Load Integration Engineering | Positions gensets as grid-tied energy arbitrage assets beyond outage insurance functionality. |
Methodological Framework
Initial hypotheses were tested against primary input from genset manufacturing executives, certified installation contractors, municipal building code officials, and residential end-users and refined through secondary validation against EPA 40 CFR Part 60 filings, Florida and Texas state building code amendments, National Electrical Code updates, and customs trade data on copper and silicon steel imports. Bottom-up installation volume estimates and top-down manufacturer shipment data were triangulated to reconcile segmentation outputs.
Demand-supply balance modeling across the projection horizon incorporated power rating tiers, fuel type configurations, installation categories, and control mechanism specifications. CAGRs were derived from installation growth trajectories in Florida, Texas, and California metropolitan clusters weighted against permitting timeline constraints and certified labor availability. Industry-specific inputs included hurricane frequency indices, grid reliability metrics, and natural gas reticulation expansion schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by battery storage manufacturers or accelerated California solar-plus-storage mandates would shift outcomes. Forecasts reflect assumptions of continued EPA Tier 4 Final enforcement timelines and stable copper pricing environments. Quarterly review of Florida building code amendment dockets, California CPUC public safety power shutoff schedules, and EPA certification backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
South America and Africa Diesel Generator Market
Generators
Heat Recovery System Generator Market
Generators
Asia-Pacific Generator Sets Market
Generators
Africa Portable Generator Market
Generators
Reciprocating Power Generating Engine Market
Generators
Hand Crank Power Generator Market
Generators
China Generator Sets Market
Generators
Kuwait Diesel Gensets Market
Generators
Tri Fuel Generators Market
Generators
South America Portable Generator Market
Generators
Railway Generators Market
Generators
Marine Gensets Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
Gasoline Generator Market
Generators
Asia-Pacific Gas Generator Market
Generators
Gas Generator Market