
 Boiler, Turbine, and Generator (BTG) Market | 2026-2036
Boiler, Turbine, and Generator (BTG) Market Size, Share, and Industry Trends Forecast 2026-2036
Boiler, Turbine, and Generator (BTG) Market Intelligence
The dual trend of utility consolidation and the concurrent rise of specialized Independent Power Producers is realigning procurement channels for BTG systems. General Electric leverages its extensive service network and digital twin technology for power plant optimization. Siemens Energy competes with a strong portfolio in high-efficiency gas turbines and combined cycle solutions. In this environment, Mitsubishi Power specializes in advanced steam turbines and integrated power plant solutions for large-scale projects.
Boiler, Turbine, and Generator (BTG) systems constitute the core power island of thermal power plants, converting thermal energy from fuel combustion into electrical energy. These integrated systems feature boilers producing high-pressure steam, turbines that convert steam or gas flow into rotational motion, and generators producing electricity. Ultra-supercritical technology holds the highest efficiency ratings and commands premium pricing in the power generation application. Within the petrochemical sector, cogeneration systems are gaining share due to their ability to produce both electricity and process heat.
Emissions regulations from bodies like the US EPA and frameworks such as the EU Green Deal and China's dual carbon goals are mandating higher efficiency and lower pollutant outputs. These policies directly influence technology choices, favoring combined cycle and ultra-supercritical systems over older, less efficient subcritical designs. Decisions on fuel flexibility, particularly regarding hydrogen co-firing and carbon capture integration, will define long-term asset viability for manufacturers and operators.
Market Dynamics
The fundamental dynamic shaping the Boiler, Turbine, and Generator market is the global energy trilemma, which forces utilities and industrial producers to balance energy security, affordability, and environmental sustainability, directly influencing technology selection and investment cycles.
Growth Catalysts
- Policy Mandates:China's dual carbon goals are accelerating the replacement of older, subcritical coal plants with high-efficiency ultra-supercritical units to meet stringent emissions and performance standards.
- Infrastructure Expansion:India's significant power capacity addition plans, driven by industrialization and electrification goals, create sustained demand for new BTG power islands, particularly for large-scale thermal projects.
- Efficiency in Industrial Applications:The adoption of cogeneration systems within the petrochemical and manufacturing sectors is rising, as these systems provide both electricity and process heat, improving overall plant energy efficiency.
Market Restraints
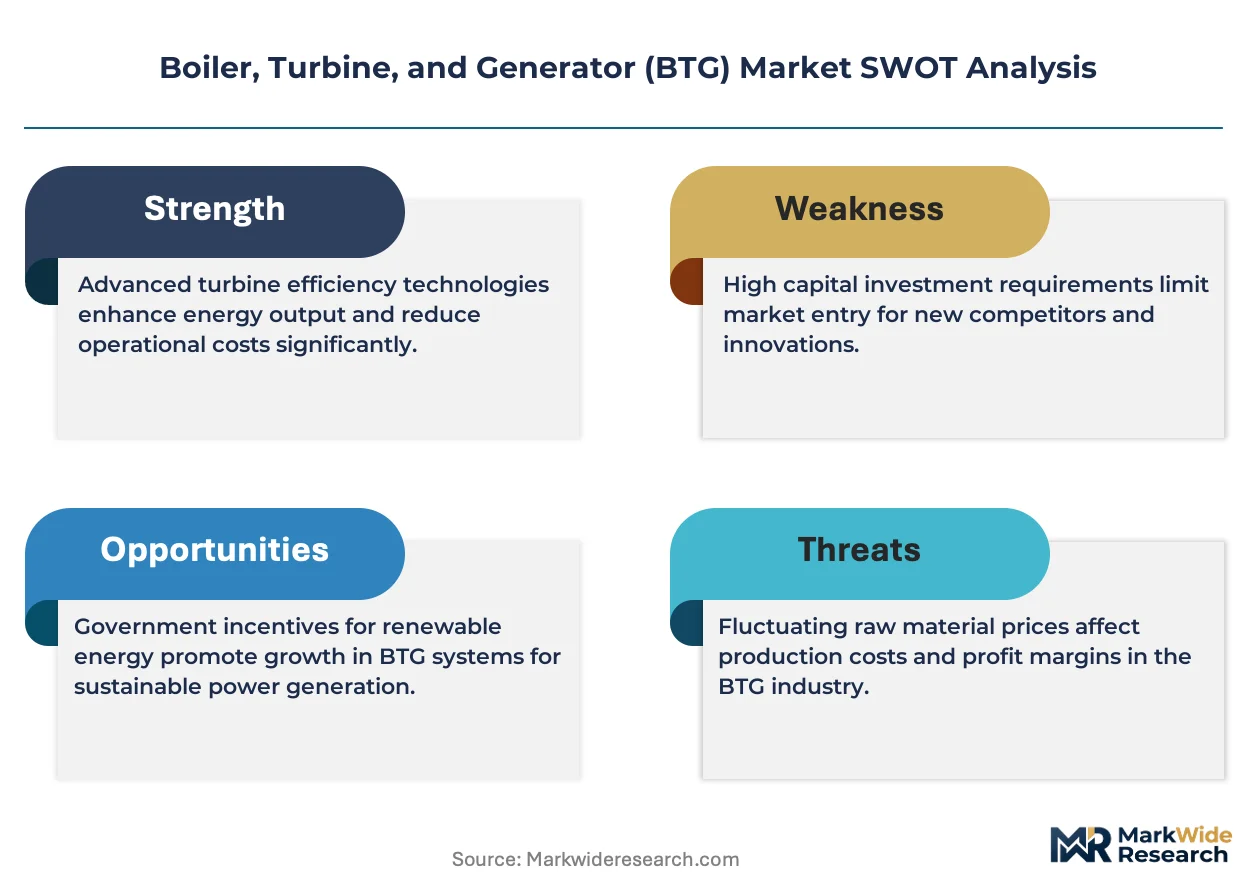
- High Capital Costs:The substantial upfront investment required for ultra-supercritical and integrated gasification combined cycle (IGCC) power plants presents a significant financial barrier for project developers, particularly in emerging economies.
- Grid Integration Complexity:The increasing share of intermittent renewable energy sources on the grid creates operational challenges for thermal power plants, which must provide flexible and reliable baseload power.
- Regulatory Hurdles:Strict environmental regulations, such as those from the US EPA, impose rigorous and lengthy permitting processes for new thermal power plants, increasing project costs and timelines.
Strategic Opportunities
- Fuel Flexibility Retrofits:Upgrading existing gas and steam turbines to enable hydrogen co-firing offers a pathway for asset owners to decarbonize and extend the operational life of their power plants.
- Decentralized Power Systems:The development of smaller, modular BTG units creates an opportunity to serve the growing need for reliable, on-site power in industrial parks, data centers, and remote communities.
- Carbon Capture Integration:The EU Green Deal and similar incentive programs are creating a market for BTG systems designed for seamless integration with post-combustion carbon capture technologies, a critical step for long-term viability.
Industry Challenges
- Legacy System Integration:Integrating advanced digital control systems, predictive maintenance platforms, and digital twins with aging power plant infrastructure is a complex and costly technical challenge for many operators.
- Specialized Talent Scarcity:A shortage of qualified engineers and technicians with expertise in high-pressure boiler operations and advanced turbine maintenance hampers the efficient operation of modern thermal power plants.
- Component Lead Times:Global supply chains for specialized, large-forged components, including turbine rotors and generator shafts, are constrained, leading to extended project delivery schedules and potential delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boiler, Turbine, and Generator (BTG) Market |
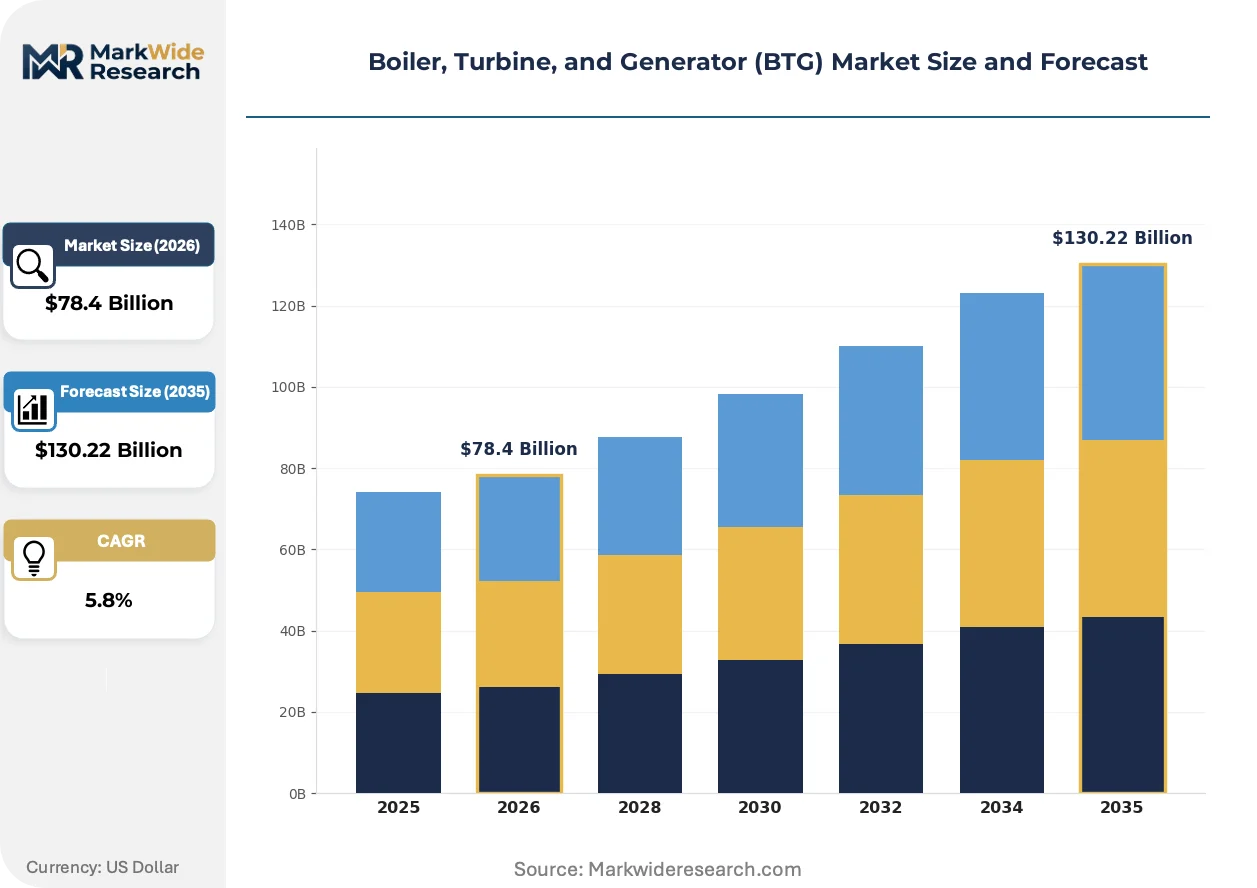
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-tube Boiler, Water-tube Boiler, Steam Turbine, Gas Turbine, Steam Generator Technology: Supercritical, Subcritical, Ultra-supercritical, Combined Cycle, Cogeneration Application: Power Generation, Petrochemical, Pulp & Paper, Desalination, Chemical Processing End User: Independent Power Producers, Manufacturing Plants, Utilities, Refineries, Mining Operations |
| Companies Covered | General Electric, Siemens Energy, Mitsubishi Power, Bharat Heavy Electricals Limited, Doosan Heavy Industries & Construction, Shanghai Electric, Harbin Electric, Ansaldo Energia, Babcock & Wilcox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boiler, Turbine, and Generator (BTG) Market Strategic Shifts & Innovations
The BTG market's evolution is defined by technological adaptations aimed at meeting stringent environmental regulations while ensuring grid stability. Innovations are focused on enhancing fuel flexibility, improving thermal efficiency, and integrating digital solutions for operational optimization across the power plant lifecycle.
Modular cogeneration systems, which produce both electricity and useful thermal energy from a single fuel source, are gaining traction. Industrial customers in sectors like chemicals and food processing are adopting these systems to improve on-site energy efficiency and reduce reliance on the grid. This adoption of smaller-scale, on-site solutions is decentralizing power generation away from exclusively large, centralized utility plants.
India's Central Electricity Authority (CEA) is enforcing stricter emission standards for thermal power plants, targeting pollutants like sulfur oxides (SOx) and nitrogen oxides (NOx). This regulatory action compels operators to invest heavily in pollution control equipment such as Flue Gas Desulphurization and Selective Catalytic Reduction systems. The nation's vast fleet of coal-fired power plants is most affected, facing significant retrofitting costs to achieve compliance.
Power plant operators are increasingly specifying performance-based long-term service agreements (LTSAs) at the time of equipment purchase. This model shifts the focus from one-time transactional sales to ongoing partnerships with OEMs, with contracts tied to metrics like plant availability and output efficiency. This trend is most visible in North America and Europe for new combined cycle gas turbine projects.
Boiler, Turbine, and Generator (BTG) Market Segmentation
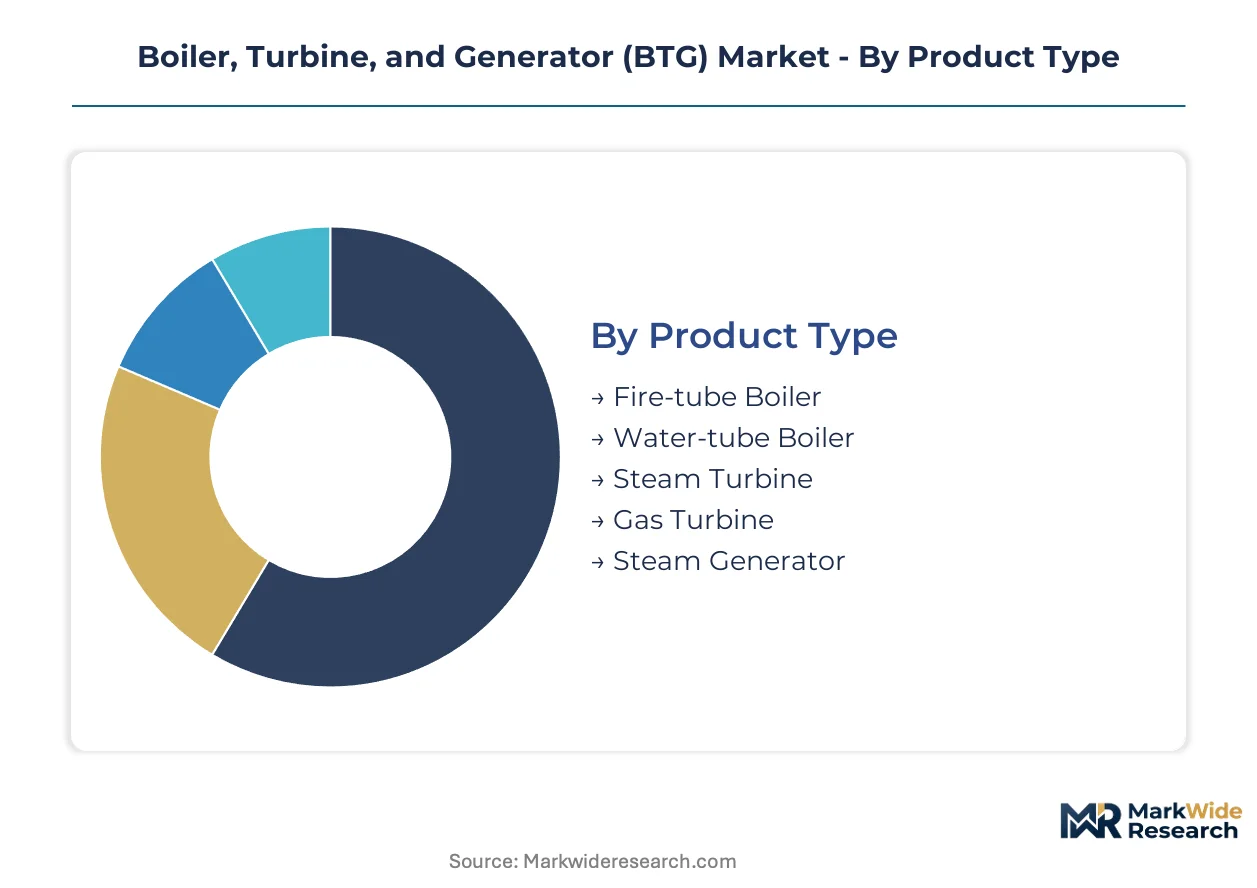
Segmentation clarifies how different power generation methods and industrial applications influence equipment design and procurement for Boiler, Turbine, and Generator systems. This analysis distinguishes between core thermal components and their integration into diverse plant configurations. It highlights distinct demand patterns across various energy transition pathways and industrial processes.
Product Type:
The upgrade and replacement cycles for existing power infrastructure heavily influence demand for specific BTG product types.
- Steam Turbine:These machines convert high-pressure steam into rotational energy for electricity generation. Modern steam turbines optimize blade design and materials for higher efficiency in ultra-supercritical plants. Demand concentrates in large-scale thermal power generation projects, particularly in India, for baseload capacity.
- Gas Turbine:Gas turbines use combustion gases to spin a turbine, generating power, often in combined cycle configurations. They offer rapid startup and operational flexibility, making them suitable for grid balancing. Demand is strong in regions like North America and Europe for new combined cycle gas turbine projects seeking efficiency.
- Water-tube Boiler:Water-tube boilers circulate water through tubes heated externally, producing high-pressure steam for power generation.
- Steam Generator:Steam generators produce steam, often associated with nuclear power plants or heat recovery steam generators in combined cycle plants.
- Fire-tube Boiler:Fire-tube boilers pass hot gases through tubes immersed in water, primarily used for industrial process heat and smaller-scale applications.
Steam Turbine sits at the top of the volume ranking, with Gas Turbine climbing the fastest.
Technology:
Technology choices reflect a balance between efficiency requirements, fuel flexibility, and environmental compliance across diverse power plant applications.
- Ultra-supercritical:This advanced thermal technology operates at extremely high pressures and temperatures, significantly improving efficiency and reducing emissions. Ultra-supercritical systems command premium pricing due to their superior performance. Demand is concentrated in China and India for new coal-fired power plants.
- Combined Cycle:Combined cycle plants integrate gas and steam turbines to recover waste heat from the gas turbine, boosting overall plant efficiency. These systems offer operational flexibility and lower carbon intensity compared to conventional thermal plants. North America and Europe are adopting these for new gas-fired capacity.
- Cogeneration:Cogeneration systems simultaneously produce electricity and useful heat from a single fuel source, enhancing energy efficiency in industrial settings.
- Supercritical:Supercritical technology operates above the critical point of water, offering better efficiency than subcritical designs but less than ultra-supercritical.
- Subcritical:Subcritical technology operates below the critical point of water, representing older, less efficient designs often targeted for replacement or modernization.
Ultra-supercritical technology leads in efficiency gains, while Combined Cycle solutions are gaining share fastest for new projects.
Application:
The specific application dictates the required scale, operational parameters, and integration complexity of BTG systems.
- Power Generation:This segment covers large-scale utility and industrial power plants converting thermal energy into electricity for grid supply. It demands robust, high-efficiency BTG systems capable of continuous operation. Demand is driven by new capacity additions in India and modernization efforts in China.
- Petrochemical:Petrochemical facilities utilize BTG systems, often in cogeneration configurations, to produce both electricity and process heat. These applications prioritize reliability and energy self-sufficiency. The Middle East and Asia-Pacific regions show strong demand due to industrial expansion.
- Pulp & Paper:Pulp and paper mills employ BTG systems, frequently with biomass fuel, for on-site power generation and process steam requirements.
- Desalination:Desalination plants use BTG systems to supply power and heat for water purification processes, often in water-scarce regions.
- Chemical Processing:Chemical processing plants integrate BTG units for reliable power and thermal energy, critical for various chemical reactions and operations.
Power Generation accounts for the largest volume of BTG deployments, with Petrochemical applications showing significant expansion.
End User:
End-user types exhibit distinct procurement channels and operational priorities for BTG system deployment.
- Utilities:Traditional utilities operate large, centralized power plants supplying electricity to national grids, prioritizing baseload reliability and long asset lifecycles. Their procurement often involves large-scale, integrated BTG solutions. Modernization initiatives in Europe and new capacity in India drive utility investments.
- Independent Power Producers:IPPs develop, own, and operate power generation facilities, selling electricity to utilities or directly to large consumers. They seek flexible, efficient BTG systems with competitive lifecycle costs. The rise of specialized IPPs is realigning procurement channels in North America.
- Manufacturing Plants:Manufacturing plants deploy BTG systems, particularly cogeneration units, for on-site power and process heat to enhance energy independence.
- Refineries:Refineries use BTG equipment for reliable electricity and steam essential for complex refining processes, often integrating with waste heat recovery.
- Mining Operations:Mining operations in remote locations often rely on captive BTG plants for stable power supply, reducing dependence on grid infrastructure.
Utilities remain the dominant end-user segment for BTG systems, while Independent Power Producers are rapidly expanding their share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While China drives extensive modernization of its thermal fleet, India focuses on new capacity additions for its industrialization goals. This dual dynamic shapes BTG market growth, reflecting diverse energy transition pathways and infrastructure needs. Both nations represent significant demand centers for high-efficiency power generation equipment.
China
Demand for high-efficiency power generation equipment in China is driven by the extensive replacement of older subcritical plants. China's dual carbon goals mandate the adoption of ultra-supercritical technology to meet stringent emissions and performance standards. Major industrial zones like the Yangtze River Delta are seeing significant power plant upgrades to enhance grid stability.
India
India's rapid industrialization and electrification goals create sustained demand for new BTG power islands. The Central Electricity Authority (CEA) enforces stricter emission standards for thermal power plants, compelling investment in pollution control. Large-scale thermal projects in states like Maharashtra are expanding to support economic growth.
United States
The United States experiences demand for flexible BTG systems, particularly in combined cycle configurations for grid balancing. The US EPA regulations influence technology choices, favoring systems with lower pollutant outputs. Energy hubs in Texas are investing in gas turbine projects to support grid modernization.
Germany
Germany's energy transition strategy requires highly efficient and flexible gas turbine solutions to complement renewable energy sources. The EU Green Deal framework encourages investments in technologies that reduce carbon intensity. Industrial clusters in North Rhine-Westphalia are adopting combined cycle solutions for enhanced efficiency.
Saudi Arabia
Saudi Arabia's petrochemical sector expansion drives demand for cogeneration systems, providing both electricity and process heat. The Kingdom's Vision 2030 initiatives promote energy efficiency and industrial diversification. Industrial cities like Jubail are heavily investing in BTG systems for reliable on-site power generation.
Boiler, Turbine, and Generator (BTG) Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the Boiler, Turbine, and Generator market. The market exhibits a tiered structure, with established global players dominating large-scale projects and regional specialists serving niche applications. Strategic archetypes include integrated solution providers, high-efficiency technology innovators, and regional manufacturing powerhouses. Portfolio diversification and strategic partnerships represent dominant competitive moves among these participants.
Global integrated solution providers, such as General Electric and Siemens Energy, anchor the premium segment with extensive service networks and advanced digital technologies. General Electric leverages its digital twin technology for power plant optimization across diverse assets. Siemens Energy competes with a strong portfolio in high-efficiency gas turbines and combined cycle solutions, particularly in European and North American markets. Mitsubishi Power occupies a strong position among specialists in advanced steam turbines and integrated power plant solutions for large-scale projects. These entities exemplify the industry's focus on high-efficiency, long-term operational performance, and robust technical support for complex power generation assets globally.
| Leading Market Players |
|---|
| General Electric |
| Siemens Energy |
| Mitsubishi Power |
| Bharat Heavy Electricals Limited |
| Doosan Heavy Industries & Construction |
| Shanghai Electric |
| Harbin Electric |
| Ansaldo Energia |
| Babcock & Wilcox |
| Others |
Cost & Logistics Intelligence
Vertical integration into specialized component manufacturing anchors the supply position for established BTG players, directly influencing their pricing power for large-scale projects. This strategy mitigates external supply chain risks and allows for differentiated offerings in high-efficiency technologies.
Pricing Analysis
Capacity additions in India are reshaping price floors for conventional thermal BTG systems, driven by competitive bidding for new power generation projects. Project-based pricing dominates the market, reflecting the bespoke nature of large power island deployments. Price differentiation stems from technology efficiency ratings, particularly for ultra-supercritical units, and the extent of bundled long-term service agreements. Pricing softness reflects the increasing competition from Chinese and South Korean manufacturers in certain segments. Utilities demonstrate lower price sensitivity for mission-critical baseload units, while IPPs seek more competitive lifecycle costs.
Supply Chain Analysis
Domestic-content mandates in India and China are reshaping sourcing strategies for BTG manufacturers, encouraging localized production and assembly. Geographic supply concentration for critical components like large-forged turbine rotors and generator shafts primarily resides in Germany, Japan, and China. Raw material dependencies include specialized alloys for high-temperature applications and rare earths for generator magnets. A structural risk involves component lead times, which are extended due to global supply chain constraints for these highly specialized items. Distribution runs through direct sales channels from OEMs to project developers and utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with China's dual carbon goals driving demand for high-efficiency, low-emission BTG systems globally.
For Market Incumbents:Deploy advanced digital twin technology to optimize existing asset performance, extending operational life and reducing maintenance costs for utilities. This strategy helps counter the threat from new entrants offering lower-cost, standard solutions. Invest in hydrogen co-firing R&D to future-proof gas turbine portfolios against stricter emissions regulations. Focus on securing long-term service agreements to ensure recurring revenue streams amidst fluctuating new build cycles.
For New Entrants and Emerging Players:Launch via modular cogeneration systems, targeting industrial parks and data centers in emerging economies like Southeast Asia. The petrochemical sector represents a penetrable application due to its high demand for both electricity and process heat. Offer flexible, smaller-scale BTG units with rapid deployment capabilities to address localized energy needs. Emphasize energy efficiency gains and reduced reliance on grid infrastructure as a key go-to-market angle.
For Investors and Strategic Acquirers:Consolidation pressure builds where specialized manufacturing capabilities for ultra-supercritical components are concentrated among a few players. The long-term viability favors entities with strong integration capabilities for carbon capture technologies and fuel flexibility. Target acquisition archetypes include specialized engineering firms with expertise in advanced materials or digital optimization platforms. A signal to watch is the acceleration of government incentives for hydrogen infrastructure development, indicating future growth areas.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Advanced Component Manufacturing | Secures critical supply for high-efficiency BTG systems, reducing reliance on external vendors for turbine rotors. |
| Development of Hydrogen-Ready Turbine Models | Extends asset viability and addresses future decarbonization mandates for gas turbine power plants. |
| Integration of Digital Twin and AI for Predictive Maintenance | Optimizes plant uptime and reduces operational expenditures for utilities across their BTG fleet. |
| Strategic Partnerships for Carbon Capture Integration | Positions BTG systems for long-term compliance with stringent emissions regulations under the EU Green Deal. |
| Modularization of Cogeneration Systems for Industrial Use | Expands market reach into decentralized power generation, serving petrochemical and manufacturing sectors. |
Research Approach
Direct dialogue with utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists provided qualitative grounding for the market analysis. This primary research was complemented by extensive secondary validation from public filings, industry association reports, and government energy statistics. A bottom-up approach was used to estimate market size, which was then triangulated with top-down validation.
The analytical framework employed a robust bottom-up modeling approach to project market volumes and values across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and key regional markets. Compound annual growth rates were derived through a regression analysis of historical data and forward-looking projections. Industry-specific forecast inputs included planned power capacity additions and regulatory emission standards.
Several conditions sit outside the modeled scope, including unforeseen geopolitical conflicts and drastic shifts in global commodity prices. Forecasts reflect assumptions documented regarding technological advancements and policy stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Electric Generators Market
Generators
Diesel Generator Market
Generators
Construction Prime Power Generators Market
Generators
North West Europe Diesel Generator Market
Generators
Heat Recovery System Generator Market
Generators
North America Gas Generator Market
Generators
Nuclear Turbine Generators Market
Generators
Southeast Asia Portable Generator Market
Generators
Europe Gas Generator Market
Generators
Global Portable Generator Market
Generators
Middle-East and Africa Portable Generator Market
Generators
Asia-Pacific Diesel Generator Market
Generators
Europe Gas Turbine Market
Generators
South America Gas Generator Market
Generators
Europe Portable Generator Market
Generators
Telecom Generator Market