
 Stationary Electric Vehicle Charging Gun Market | 2026-2036
Stationary Electric Vehicle Charging Gun Market Size, Share, and Industry Trends Forecast 2026-2036
Stationary Electric Vehicle Charging Gun Market Analytics
Fleet charging infrastructure is broadening as municipal transit authorities and logistics operators replace diesel depots with electric alternatives. ABB leverages its electrification portfolio to anchor large-scale fleet charging projects across European transit networks. Siemens competes through integrated grid-to-vehicle solutions that combine charging hardware with energy management software. Phoenix Contact specializes in high-reliability connector systems that sustain performance under continuous commercial cycling.
A stationary electric vehicle charging gun is a fixed-position conductive charging interface that transmits electrical energy from grid infrastructure to an electric vehicle, typically rated for currents between 16A and 500A depending on charging level, with housings engineered from flame-retardant thermoplastics or aluminum alloys to withstand thermal cycling and mechanical impact in outdoor installations. DC fast charger deployments command premium positioning due to higher material costs for liquid-cooled cable assemblies and power electronics integration, while Level 2 charger volumes dominate residential and workplace installations where lower capital expenditure drives accessibility. Connector type fragmentation creates parallel supply chains, with CCS Combo hardware leading in European and North American markets and GB/T interfaces capturing China's domestic requirements.
Europe's Alternative Fuels Infrastructure Regulation mandates standardized charging accessibility along major transport corridors, while China's MIIT enforces GB/T national standards that shape domestic product specifications. The US NHTSA and EPA coordinate on charger safety and grid integration protocols that influence manufacturer certification pathways. Stakeholders must monitor evolving interoperability mandates and cooling technology transitions as power ratings climb toward 350kW and beyond.
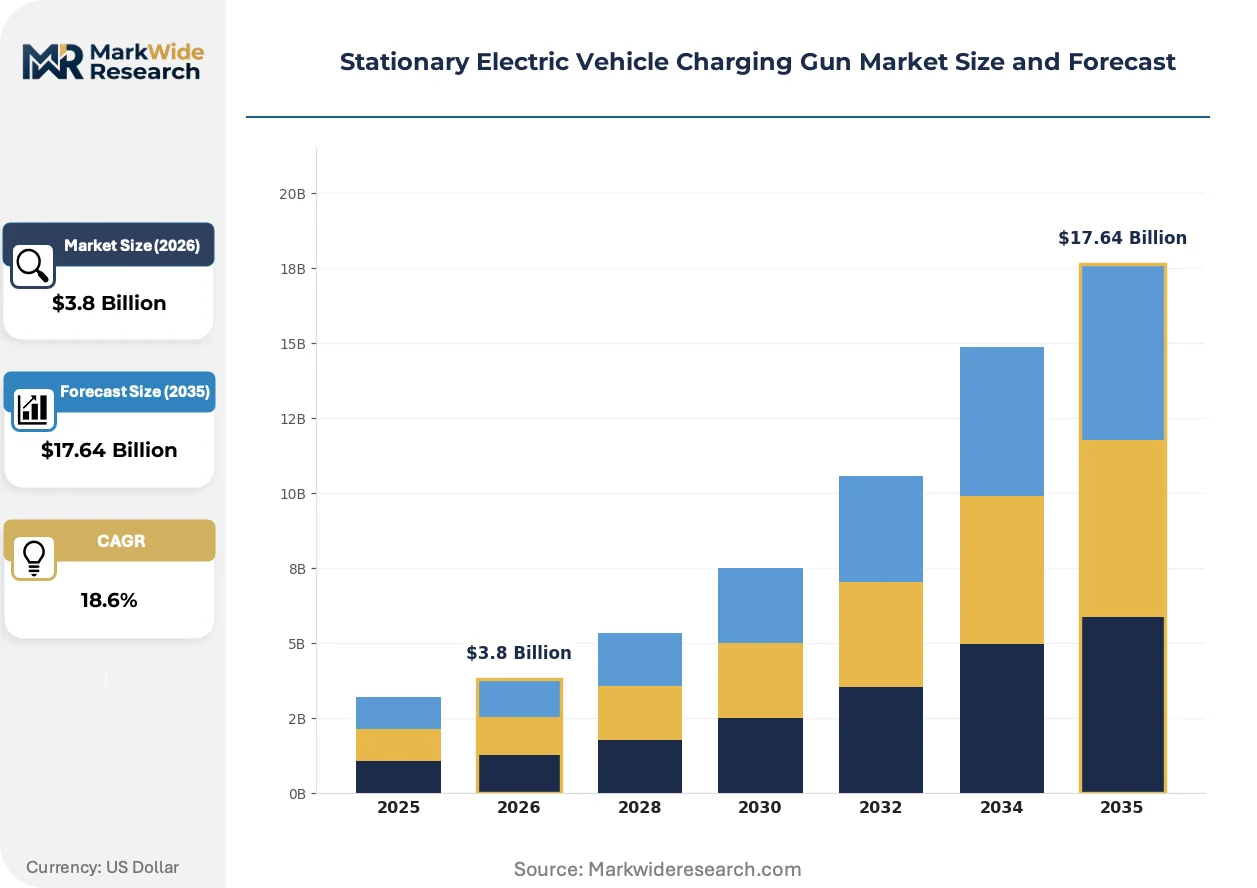
Market Dynamics
Power rating escalation toward 350kW and beyond is forcing wholesale redesigns of thermal management systems and cable assemblies across the stationary charging gun supply base. Liquid-cooled connector architectures now constitute the critical path for next-generation hardware deployment.
Growth Catalysts
- Europe's AFIR corridor mandates:Standardized high-power charging accessibility along trans-European transport networks is accelerating hardware procurement cycles for highway-adjacent charging hubs.
- Fleet depot electrification:Municipal transit authorities and logistics operators are replacing diesel infrastructure with centralized DC fast charging arrays for electric bus and commercial vehicle operations.
- GB/T national standard enforcement:China's MIIT mandates are concentrating domestic manufacturing capacity around domestically specified connector geometries and communication protocols.
Market Restraints
- Copper and aluminum price volatility:Raw material cost swings for conductor metals compress margin structures for cable assembly manufacturers.
- Connector standard fragmentation:Parallel CCS Combo, GB/T, and CHAdeMO supply chains force redundant tooling and inventory carrying costs across regional production facilities.
- Liquid cooling system complexity:Thermal management subsystem integration extends qualification timelines and raises warranty exposure for high-power charging hardware.
Strategic Opportunities
- India's nascent charging infrastructure:The country's Bureau of Indian Standards is finalizing AC and DC charging specifications, opening first-mover positioning for connector suppliers.
- Vehicle-to-grid integration:Bidirectional charging capability convergence with stationary energy storage systems creates new hardware specification requirements.
- Utility-managed charging programs:Demand-response rate structures from FERC-jurisdictional grid operators are creating procurement incentives for smart-charging-enabled hardware.
Industry Challenges
- High-voltage safety certification timelines:IEC 61851 and UL 2594 testing protocols for 1000V+ systems extend product launch schedules by six to twelve months.
- Thermal engineering talent scarcity:Specialized expertise in two-phase cooling and high-frequency power electronics remains concentrated among automotive Tier-1 suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stationary Electric Vehicle Charging Gun Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1 Charger, Level 2 Charger, DC Fast Charger, Wireless Charger Connector Type: Type 1, Type 2, CHAdeMO, CCS Combo, Tesla Application: Commercial Charging Stations, Residential Charging Setup, Fleet Charging, Public Transit Depots End User: Electric Vehicle Manufacturers, Fleet Operators, Municipal Transit Authorities, Private Consumers |
| Companies Covered | Schneider Electric, ABB, Bosch, Delta Electronics, Siemens, Phoenix Contact, AVIC Jonhon Optronic Technology, Zhejiang Yonggui Electric Equipment Co., Ltd., Wallbox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stationary Electric Vehicle Charging Gun Market Evolving Landscape
Hardware architecture is pivoting from passive air-cooled designs to active thermal management systems as power densities climb. This transition is reshaping supplier capabilities and procurement criteria across fleet, public, and residential installation segments.
Modular power electronics architectures are decentralizing charging system topologies. Power conversion modules now distribute thermal loads across multiple smaller units rather than centralizing in monolithic cabinets. Fleet operators with 24-hour duty cycles are adopting these configurations to isolate failure domains and reduce maintenance windows. The shift is compressing traditional integrated-system vendor margins while expanding opportunities for specialized component suppliers.
REACH substance restrictions and RoHS recast directives are eliminating certain halogenated flame retardants from thermoplastic housing formulations. European charging hardware manufacturers are reformulating material specifications to maintain UL 94 V-0 ratings without restricted additives. The regulatory pressure is most acute for outdoor-rated connector assemblies in Germany and the Netherlands, where environmental compliance auditing is tightening.
Charging-as-a-service contracts are displacing capital purchase models among commercial fleet operators. Third-party infrastructure providers now retain hardware ownership and charge per-kWh or per-mile fees, transferring technology obsolescence risk from vehicle operators to charging network developers. This restructuring concentrates buying power with national fleet management firms in California and Germany, reducing direct procurement volumes for individual depot operators.
Stationary Electric Vehicle Charging Gun Market Segmentation
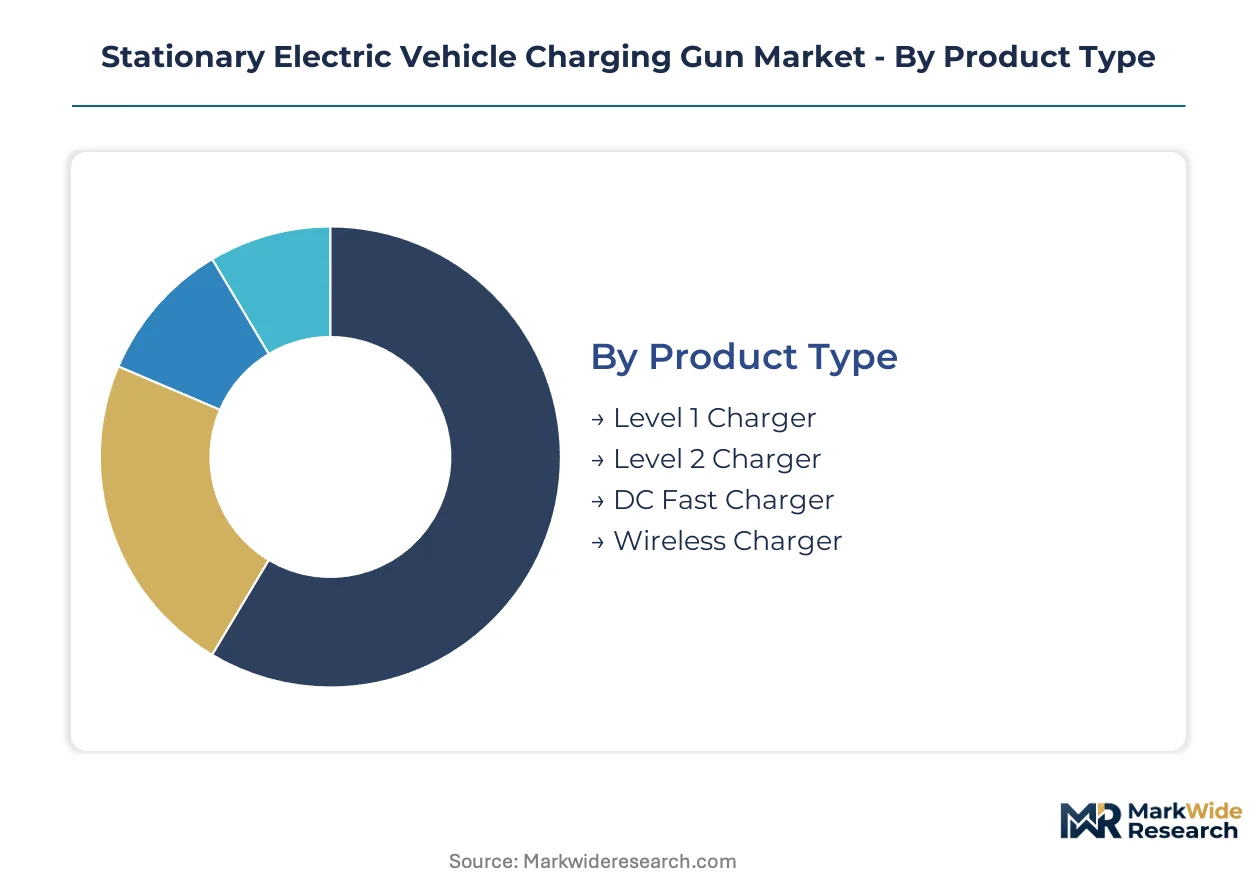
Segmentation reveals how hardware specifications diverge across deployment contexts. Charging guns designed for residential garages carry fundamentally different thermal and mechanical requirements than depot-grade equipment cycling through 500A currents daily.
Product Type:
Supply concentration clusters around DC fast charging architectures as fleet operators and highway corridor developers scale procurement of high-power hardware.
- Level 1 Charger:120V residential units delivering 1.4-1.9kW through standard NEMA connectors. Demand concentrates in North American single-family housing where overnight charging satisfies daily commuting patterns without panel upgrades. Copper conductor costs and slow charge speeds limit commercial viability.
- Level 2 Charger:240V systems rated 3.3-19.2kW dominate workplace and multi-unit dwelling installations. European workplace mandates in Germany and France are accelerating hardware procurement for employee parking facilities. Installation complexity varies by regional electrical codes.
- DC Fast Charger:Direct current systems bypass onboard converters to deliver 50-350kW. Liquid-cooled cable assemblies from Phoenix Contact and ABB sustain continuous commercial cycling at transit depots and logistics hubs.
- Wireless Charger:Inductive pad systems transfer power across air gaps without physical connectors. Pilot deployments concentrate at premium residential installations and automated fleet facilities where connector wear elimination justifies efficiency losses.
Today's leader: DC Fast Charger. Tomorrow's challenger: Wireless Charger.
Connector Type:
Regional regulatory mandates have fragmented connector supply chains into parallel certification tracks with incompatible tooling requirements.
- Type 1:Single-phase J1772 connectors standardize North American AC charging up to 19.2kW. Residential and workplace installations across California and Texas specify this interface for compatibility with legacy vehicle fleets.
- Type 2:Mennekes connectors handle three-phase AC power up to 43kW across European networks. Germany's KBA certification requirements and AFIR corridor mandates are concentrating manufacturing capacity in Bavarian industrial zones.
- CHAdeMO:Japanese-origin DC fast charging protocol supports bidirectional power flow for vehicle-to-grid applications. Deployment concentrates in Japanese domestic market and select European retrofits.
- CCS Combo:Combined Charging System integrates AC and DC pins into single connector geometry. European and North American markets are converging on CCS2 and CCS1 variants respectively for highway corridor standardization.
- Tesla:Proprietary connector architecture deployed across Supercharger networks. Tesla's North American Charging Standard licensing program is opening connector specifications to third-party manufacturers.
CCS Combo captures volume leadership. Tesla's NACS licensing is gaining fastest as infrastructure developers seek network interoperability.
Application:
Deployment environment dictates housing material specifications, cable flex ratings, and payment system integration requirements.
- Commercial Charging Stations:Highway-adjacent and retail location hardware requires weatherproof IP65+ enclosures and integrated payment terminals. European AFIR mandates are standardizing accessibility requirements across trans-European transport networks.
- Residential Charging Setup:Wall-mounted or pedestal units prioritize compact form factors and smartphone connectivity. German and Dutch building codes increasingly mandate pre-wiring for EV charging in new construction.
- Fleet Charging:Depot-scale installations coordinate multiple high-power dispensers through centralized energy management. California's Advanced Clean Fleets regulation is mandating zero-emission transitions for logistics and transit operators.
- Public Transit Depots:Electric bus charging infrastructure demands 150-450kW dispensers with automated connector positioning. China's eastern manufacturing corridor is scaling domestic production for municipal procurement programs.
Fleet Charging leads current investment cycles. Public Transit Depots are climbing fastest as diesel replacement deadlines approach in Germany and California.
End User:
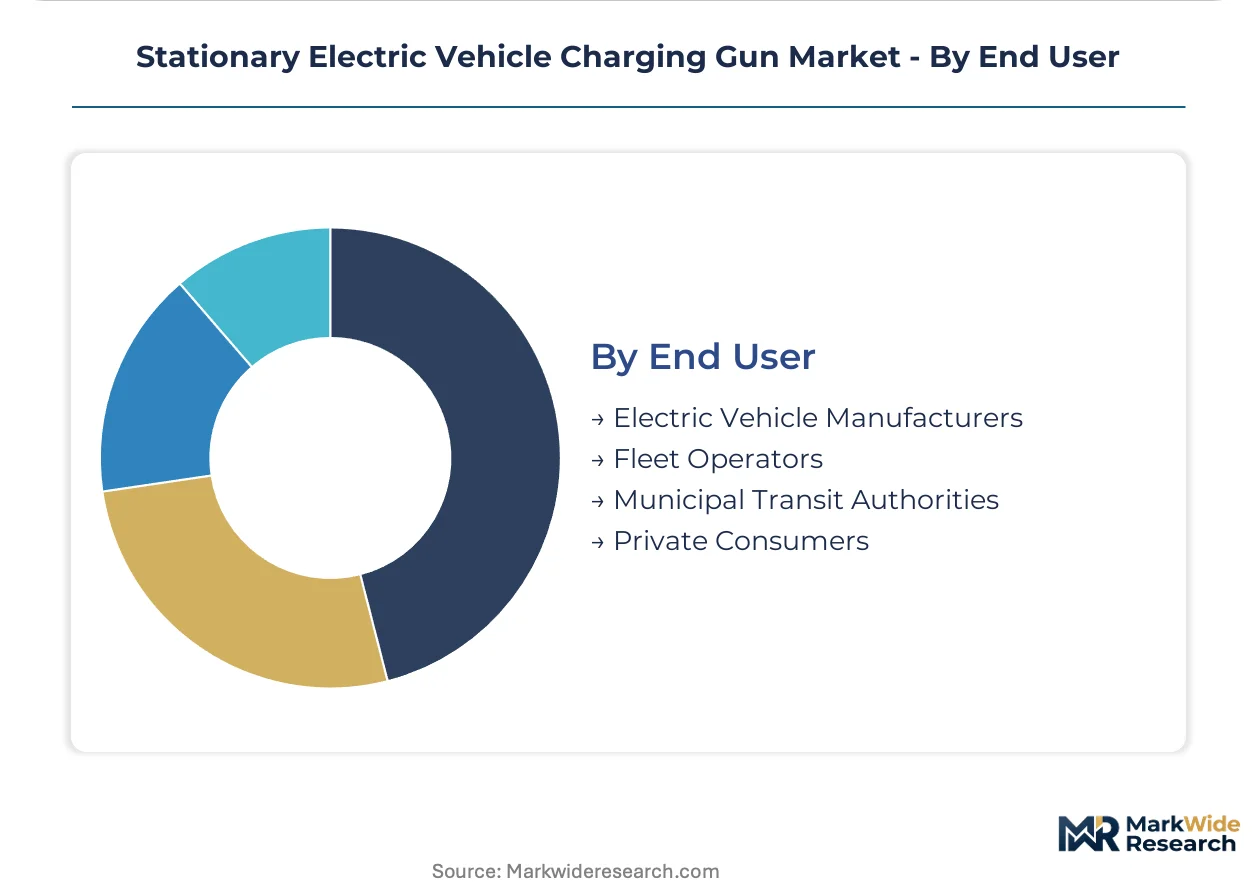
Procurement authority and technical specification control vary sharply across buyer categories with divergent maintenance capabilities.
- Electric Vehicle Manufacturers:OEMs bundle charging hardware with vehicle sales or operate captive charging networks. Tesla's integrated ecosystem and Volkswagen's Electrify America investments illustrate vertical control strategies.
- Fleet Operators:Logistics and delivery companies centralize procurement through national fleet management firms. Charging-as-a-service contracts transfer hardware ownership to infrastructure providers.
- Municipal Transit Authorities:Government procurement processes favor open technical specifications and multi-vendor qualification. European public procurement directives mandate competitive tendering for charging infrastructure.
- Private Consumers:Individual purchasers prioritize installation cost and smartphone app integration over technical specifications. Retail channel distribution through electrical wholesalers and home improvement retailers dominates.
Fleet Operators concentrate buying power today. Municipal Transit Authorities are expanding procurement fastest as diesel bus replacement programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor concentrates the majority of stationary charging gun production capacity, with Germany's automotive belt and California's zero-emission zones driving complementary demand clusters across three continents.
China
MIIT's GB/T connector mandates and municipal electric bus procurement programs are accelerating hardware deployment across Shanghai, Shenzhen, and Beijing transit depots. Zhejiang and Jiangsu provinces host dense concentrations of connector assembly specialists serving domestic OEMs and infrastructure developers. The Yangtze River Delta industrial cluster is scaling liquid-cooled cable production for 350kW+ highway corridor installations.
Germany
KBA certification requirements and AFIR corridor mandates are standardizing CCS Combo hardware specifications across Bavarian and Baden-Württemberg manufacturing zones. The country's national automotive regulator enforces rigorous thermal cycling protocols for depot-grade charging equipment. Munich and Stuttgart anchor integrated supply chains linking connector fabricators with Tier-1 power electronics suppliers.
United States
California's Advanced Clean Fleets regulation and EPA-coordinated grid integration protocols are mandating zero-emission transitions for logistics operators and transit authorities. NHTSA safety certification timelines shape product launch schedules for 1000V+ systems. The Los Angeles Basin and San Francisco Bay Area concentrate fleet charging procurement through national infrastructure providers.
India
The Bureau of Indian Standards is finalizing AC and DC charging specifications, opening first-mover positioning for connector suppliers ahead of mass fleet electrification. Central Electricity Authority grid codes are influencing smart-charging hardware requirements for utility-managed programs. Maharashtra and Gujarat industrial corridors are attracting component assembly investments from East Asian manufacturers.
Japan
METI-backed CHAdeMO bidirectional charging deployments concentrate in Kanto and Kansai metropolitan transit networks. The country's national standards body maintains distinct connector geometries that sustain parallel supply chains for vehicle-to-grid applications. Nagoya-area automotive suppliers are integrating charging gun production with existing high-voltage component expertise.
Stationary Electric Vehicle Charging Gun Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale liquid-cooled assembly lines to meet 350kW+ procurement cycles. The vendor base stratifies across three tiers: integrated electrification conglomerates with captive grid-to-vehicle portfolios, specialized connector fabricators focused on thermal reliability, and emerging Asian component suppliers capturing cost-sensitive volume segments. Strategic archetypes include full-system integrators, high-reliability specialists, and scale-driven commodity producers. Technology licensing and backward integration into conductor metallurgy represent the dominant competitive moves reshaping margin structures.
Within the integrated-system tier, ABB and Siemens exemplify full-portfolio positioning spanning power conversion, thermal management, and grid integration software. Phoenix Contact occupies a specialist position emphasizing connector reliability under continuous commercial cycling. Among Asia-based fabricators, Zhejiang Yonggui Electric Equipment Co., Ltd. and AVIC Jonhon Optronic Technology represent scale-oriented production archetypes serving domestic procurement programs. Schneider Electric, Bosch, Delta Electronics, and Wallbox complete the competitive set across European, North American, and Asian demand clusters.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Bosch |
| Delta Electronics |
| Siemens |
| Phoenix Contact |
| AVIC Jonhon Optronic Technology |
| Zhejiang Yonggui Electric Equipment Co., Ltd. |
| Wallbox |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between UL 2594-validated 1000V+ systems and uncertified lower-voltage hardware manifests in both pricing spreads and supplier concentration patterns. Premium liquid-cooled assemblies command substantial markups over air-cooled alternatives, while China's GB/T-certified fabricators and Germany's KBA-validated producers occupy parallel supply tiers with limited cross-certification.
Pricing Analysis
Input-cost pass-through from copper and aluminum conductor metals dominates pricing dynamics for cable assembly manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates liquid-cooled 350kW+ depot systems from workplace Level 2 hardware and residential Level 1 units. Cost compression in standard-tier Level 2 equipment is intensifying because Chinese producers are scaling GB/T-certified output for domestic procurement programs. Fleet operators demonstrate lowest price sensitivity due to charging-as-a-service contract structures, while private residential purchasers prioritize upfront capital minimization.
Supply Chain Analysis
Liquid-cooled connector architectures rest on specialized conductor metallurgy and thermal management subsystems sourced from Germany, China, and Japan. Critical inputs include high-purity copper rod, flame-retardant thermoplastic compounds, and ceramic-insulated power electronics substrates. Single-source vulnerability concentrates in liquid cooling pump assemblies qualified for continuous commercial cycling. Distribution runs through national fleet management firms in California and Germany, electrical wholesalers for residential channels, and direct OEM supply agreements for integrated vehicle-charging ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between China's low-cost GB/T manufacturing base and Europe's premium CCS certification requirements, with margin capture diverging sharply across these regulatory boundaries.
For Market Incumbents: Acquire thermal engineering talent pools concentrated in automotive Tier-1 suppliers to address capability scarcity in two-phase cooling design. Backward integration into conductor metallurgy reduces exposure to copper price volatility while securing supply for 350kW+ liquid-cooled cable production. Certification investment in India's emerging BIS standards opens first-mover positioning ahead of mass fleet electrification. For New Entrants and Emerging Players: Launch via charging-as-a-service distribution partnerships targeting municipal transit authorities in Germany and California where diesel replacement deadlines concentrate procurement. India's nascent Bureau of Indian Standards specification finalization presents the most penetrable geography, with Maharashtra and Gujarat industrial corridors attracting component assembly investments. White-space exists in bidirectional vehicle-to-grid hardware integrating with stationary energy storage systems. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized connector fabricators possessing KBA or UL 2594 certification credentials rather than undifferentiated commodity producers. Long-term viability across the analysis window hinges on thermal management subsystem integration capabilities as power ratings escalate. Acquisition target archetype: mid-scale liquid-cooled assembly specialists with qualified production lines and established depot operator relationships. Watch FERC-jurisdictional demand-response rate structures as inflection indicators for smart-charging-enabled hardware procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductor Metallurgy | Captive copper supply reduces raw material volatility exposure for cable assembly manufacturers serving 350kW+ installations. |
| Technology Licensing for NACS Connector Production | Tesla's North American Charging Standard opening creates interoperability revenue streams for third-party hardware fabricators. |
| Joint Venture for Indian Market Entry | BIS specification alignment with Maharashtra industrial corridor partners accelerates qualification ahead of mass fleet procurement. |
| Capacity Expansion in Liquid-Cooled Assembly Lines | 350kW+ highway corridor mandates across Germany's AFIR networks concentrate demand for thermally validated depot-grade equipment. |
| Green Manufacturing Transition for REACH Compliance | Halogenated flame-retardant elimination from thermoplastic housings maintains UL 94 V-0 ratings under tightening Dutch and German environmental auditing. |
Research Methodology
Coverage spans China, Germany, the United States, India, and Japan, with primary inputs from each market's distinct regulatory and procurement environments. Primary interviews with charging infrastructure procurement managers at municipal transit authorities, fleet operations directors at logistics operators, Tier 1 supplier platform engineers, and power electronics R&D leads combined with secondary validation from MIIT GB/T standard filings, KBA certification databases, EPA grid integration protocols, and FERC demand-response program disclosures. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment flows.
Rate-of-change decomposition across the analysis window separates volume expansion from value migration toward higher-power hardware segments. Segmentation dimensions modeled include charging level, connector type, application environment, and end-user procurement authority, with power rating escalation curves and thermal management technology transitions as industry-specific forecast inputs. CAGRs derived from infrastructure investment pipeline analysis and fleet electrification mandate compliance schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper price volatility extremes or accelerated connector standard convergence. Forecasts reflect documented assumptions regarding regulatory enforcement timelines, fleet operator capital commitment patterns, and cooling technology qualification trajectories. A small set of triggers—including AFIR corridor mandate acceleration, India's BIS specification finalization, and CHAdeMO bidirectional deployment scaling—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
EV Solar Charging Wallbox Market
Electric Vehicle Charging
Heavy-Duty Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Wireless Electric Vehicle Charger Market
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charger and Charging Station Market
Electric Vehicle Charging
United States Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Charging Plugs Market
Electric Vehicle Charging
Electric Bus Charging Infrastructure Market
Electric Vehicle Charging
EV Charging Point Market
Electric Vehicle Charging
Denmark Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
North America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
DC Chargers Market
Electric Vehicle Charging
Airport Charging Stations Market
Electric Vehicle Charging
US Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
EV Charging Facilities Market