
 Kuwait Diesel Gensets Market | 2026-2036
Kuwait Diesel Gensets Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Diesel Gensets Market Outlook
A shift from single-source procurement to multi-source supplier panels is recalibrating how Kuwaiti end-users contract genset fleets. FG Wilson leverages its regional assembly footprint to shorten lead times for Kuwaiti contractors. Caterpillar Inc. anchors the high-power segment through its dealer network serving oilfield operators. Jubaili Bros. competes aggressively on aftermarket service coverage across the emirate's industrial zones.
Kuwait diesel gensets are internal combustion engine-generator packages rated from 15 kVA to above 500 kVA, converting diesel fuel into electrical power through synchronous alternators coupled to compression-ignition engines; they serve as primary or standby power for facilities lacking grid reliability. The 300-500 kVA and above 500 kVA power rating brackets dominate revenue as Kuwait's oil infrastructure and megaprojects require sustained heavy-load capability. Oil and Gas as an end user commands premium pricing due to continuous-duty requirements and explosion-proof specifications, while Construction absorbs volume through project-based rentals.
Kuwait's Public Authority for Industry (PAI) enforces conformity assessment for imported gensets, while the Environment Public Authority (EPA) regulates exhaust emissions under national air quality standards. These frameworks compel manufacturers to certify engines for Kuwait's thermal and particulate limits before customs clearance. Stakeholders must track how the emirate's renewable energy targets and grid stabilization investments reshape the business case for diesel backup versus hybrid alternatives.
Market Dynamics
Kuwait's Ministry of Electricity and Water is tightening emissions standards for imported gensets, forcing suppliers to re-engineer fuel systems and exhaust after-treatment before customs clearance. This regulatory compression is restructuring supplier资格 and accelerating the phase-out of mechanically governed engines.
Growth Catalysts
- EPA Thermal Limits:Kuwait's Environment Public Authority mandates particulate filters and selective catalytic reduction for units above 500 kVA, creating replacement demand for older fleets in Al-Ahmadi industrial zones.
- Peak Summer Grid Strain:Northern oilfield operators expand standby capacity to prevent production losses when ambient temperatures exceed 50°C and air-conditioning loads spike.
- Electronic Fuel Injection:Common-rail diesel systems improve fuel efficiency by 12-18% versus mechanical pumps, justifying premium pricing for continuous-duty oil and gas applications.
Market Restraints
- Steel and Copper Volatility:Alternator windings and engine block castings face input cost swings tied to London Metal Exchange pricing, compressing margins for fixed-price construction contracts.
- Single-Port Import Concentration:Shuwaikh Port handles over 80% of genset arrivals, creating customs bottleneck risk during peak construction seasons.
- Solar-Plus-Storage Substitution:Kuwait's renewable energy targets and declining lithium-ion costs threaten diesel standby economics for commercial buildings under 300 kVA.
Strategic Opportunities
- Hybrid Retrofit Kits:Battery-diesel integration allows existing fleets to reduce runtime hours and fuel consumption while maintaining spinning reserve capability.
- Kuwait City Commercial Corridor:Megaproject pipeline including Silk City and Bubiyan Island development requires temporary power infrastructure before grid extension.
- PAI Fast-Track Certification:Kuwait's Public Authority for Industry offers expedited conformity assessment for manufacturers pre-certified to EU Stage V or US EPA Tier 4 Final standards.
Industry Challenges
- Certification Timeline Compression:EPA and PAI dual approval processes extend product launch cycles by 8-14 months, delaying revenue recognition for new engine platforms.
- Aftermarket Technician Scarcity:Electronic engine management and emissions diagnostics require training investments that local service networks struggle to fund at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Diesel Gensets Market |
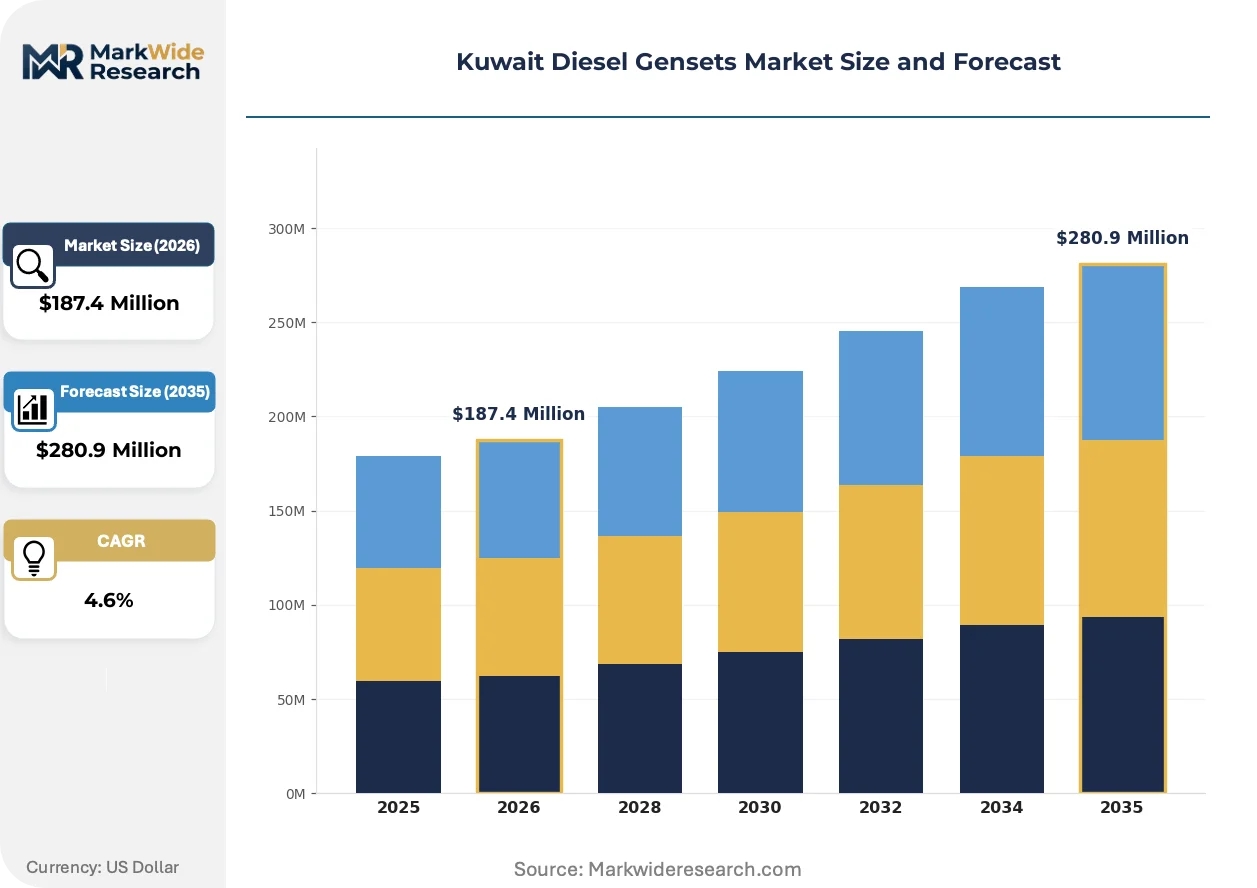
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Rating: 15-100 kVA, 100-300 kVA, 300-500 kVA, Above 500 kVA End User: Construction, Oil & Gas, Manufacturing, Telecommunications Deployment Model: Portable, Stationary, Residential, Commercial Fuel Type: Diesel, Bio-Diesel, Dual-Fuel, Others |
| Companies Covered | Kohler Co., FG Wilson, Caterpillar Inc., Jubaili Bros., Yanmar Holdings Co. Ltd., Cummins Inc., Generac Power Systems, Inc., Kirloskar Oil Engines Limited, Atlas Copco AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Diesel Gensets Market Strategic Shifts
Technology substitution and procurement model evolution are compressing traditional equipment lifecycles. Suppliers must now bundle digital monitoring and predictive maintenance to differentiate beyond hardware specifications.
Electronic engine management systems with real-time combustion optimization are overtaking mechanical governor controls in the above-300 kVA segment. Oilfield operators now specify CAN-bus diagnostics and remote telemetry as standard procurement requirements. This capability shift is compressing the installed base of pre-2019 gensets and accelerating fleet refresh cycles in Kuwait's northern production zones.
Kuwait's Environment Public Authority is aligning national air quality standards with Gulf Cooperation Council technical regulations, mandating closed crankcase ventilation and diesel particulate filters for all new imports. Engine manufacturers must submit type-approval documentation to PAI before customs release. The above-500 kVA segment faces the steepest compliance burden, with several suppliers withdrawing mechanically governed models rather than recertifying.
Equipment-as-service contracts with guaranteed uptime SLAs are displacing outright purchase for construction and event power applications. Rental fleet operators now bundle fuel management, preventive maintenance, and 24-hour response guarantees into monthly tariffs. This shift is most visible in Kuwait City's commercial construction corridor, where contractors prioritize balance-sheet flexibility over asset ownership for temporary power needs.
Kuwait Diesel Gensets Market Segmentation
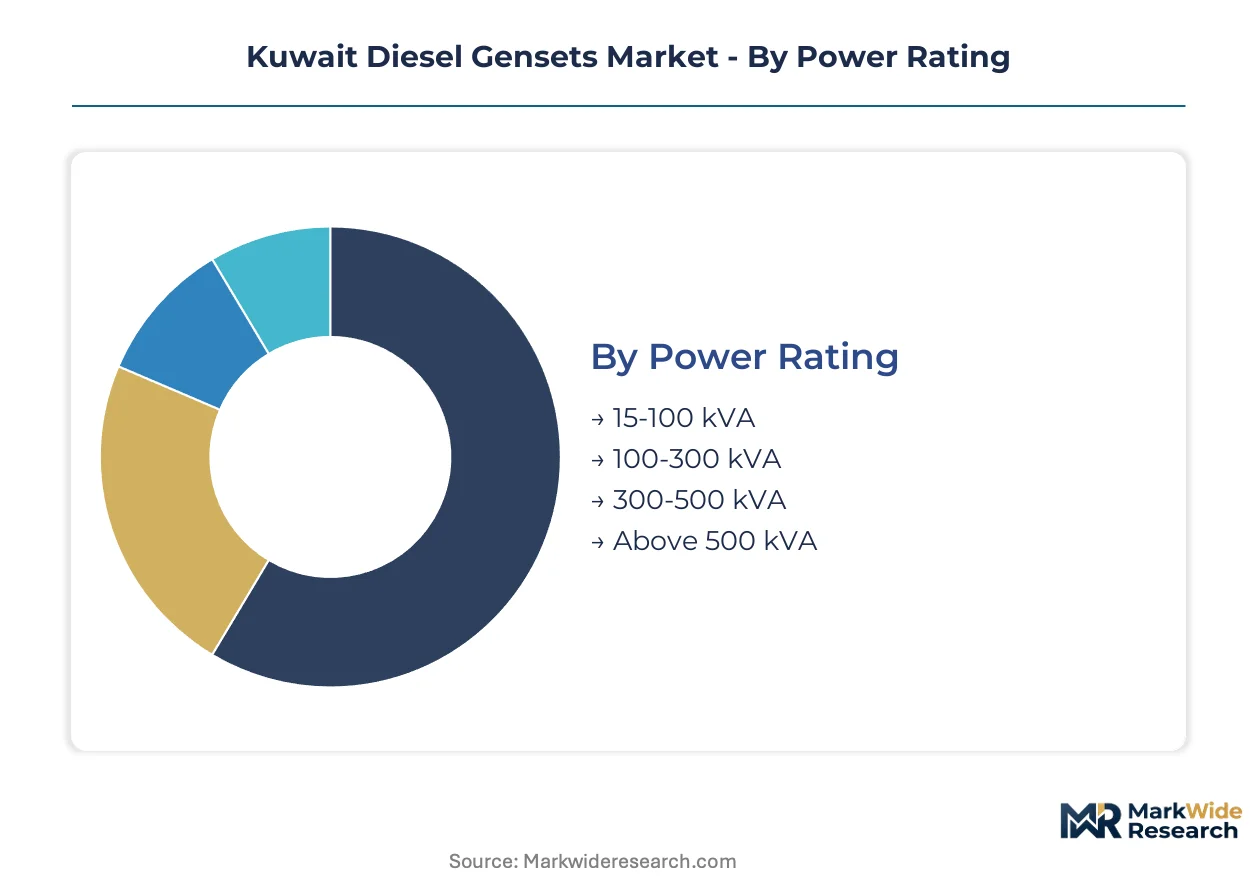
Power rating brackets determine engine architecture and emissions compliance pathways for Kuwaiti imports. End-user concentration in oil infrastructure and construction corridors shapes regional demand clustering. Deployment models reflect the tension between permanent industrial installations and project-based temporary power needs.
Power Rating:
Engine displacement and alternator frame size define thermal output thresholds that trigger distinct regulatory treatment under EPA and PAI standards.
- Above 500 kVA:These heavy-frame units employ V-block diesel architectures with closed crankcase ventilation and selective catalytic reduction systems to satisfy EPA particulate mandates. Northern oilfield operators in Kuwait's Burgan and Ratqa fields specify this bracket for continuous-duty production uptime during grid instability.
- 300-500 kVA:Inline-six and V8 configurations dominate this mid-heavy segment, balancing fuel efficiency with load-following capability. Al-Ahmadi refinery complexes and Kuwait City commercial megaprojects anchor procurement volumes here, driven by simultaneous process power and HVAC redundancy requirements.
- 100-300 kVA:Compact inline engines serve distributed manufacturing facilities and mid-rise construction sites across Jahra and Farwaniya governorates.
- 15-100 kVA:Single-cylinder and small multi-cylinder packages address residential backup and small commercial applications in Kuwait City's dense urban fabric.
Above 500 kVA leads on scale; 300-500 kVA leads on momentum.
End User:
Operational duty cycles and explosion-proof specifications create divergent procurement economics across industrial verticals.
- Oil & Gas:Continuous-duty ratings and Zone 2 hazardous area certifications command premium pricing structures. Kuwait Oil Company and its international joint venture partners mandate API standards compliance for all rotating equipment deployed in the partitioned neutral zone and northern production assets.
- Construction:Rental fleet operators dominate procurement through project-based equipment-as-service contracts. The Silk City and Bubiyan Island development corridors generate concentrated demand spikes synchronized to civil works phasing.
- Manufacturing:Food processing and plastics producers in Shuwaikh Industrial Area seek synchronized paralleling capability for seamless grid transfer.
- Telecommunications:Mobile network operators prioritize acoustic enclosures and remote telemetry integration for unmanned cell tower sites across Kuwait's desert highway corridors.
Oil & Gas commands margin premiums; Construction drives absolute volume throughput.
Deployment Model:
Asset mobility requirements determine enclosure engineering and foundation specifications for Kuwait's extreme ambient conditions.
- Stationary:Permanent concrete-pad installations with weatherproof enclosures serve critical infrastructure and industrial process loads. Kuwait's Ministry of Electricity and Water specifies this model for desalination plant backup systems.
- Portable:Skid-mounted and trailer-configured units enable rapid repositioning across construction phases. Rental fleet operators in the commercial construction corridor maintain extensive portable inventories for just-in-time site mobilization.
- Commercial:Rooftop and basement installations with acoustic attenuation serve retail and office complexes in Salmiya and Hawally districts.
- Residential:Compact standby units with automatic transfer switches protect villas and low-rise housing in Kuwait City's established neighborhoods.
Stationary dominates installed base value; Portable captures replacement velocity.
Fuel Type:
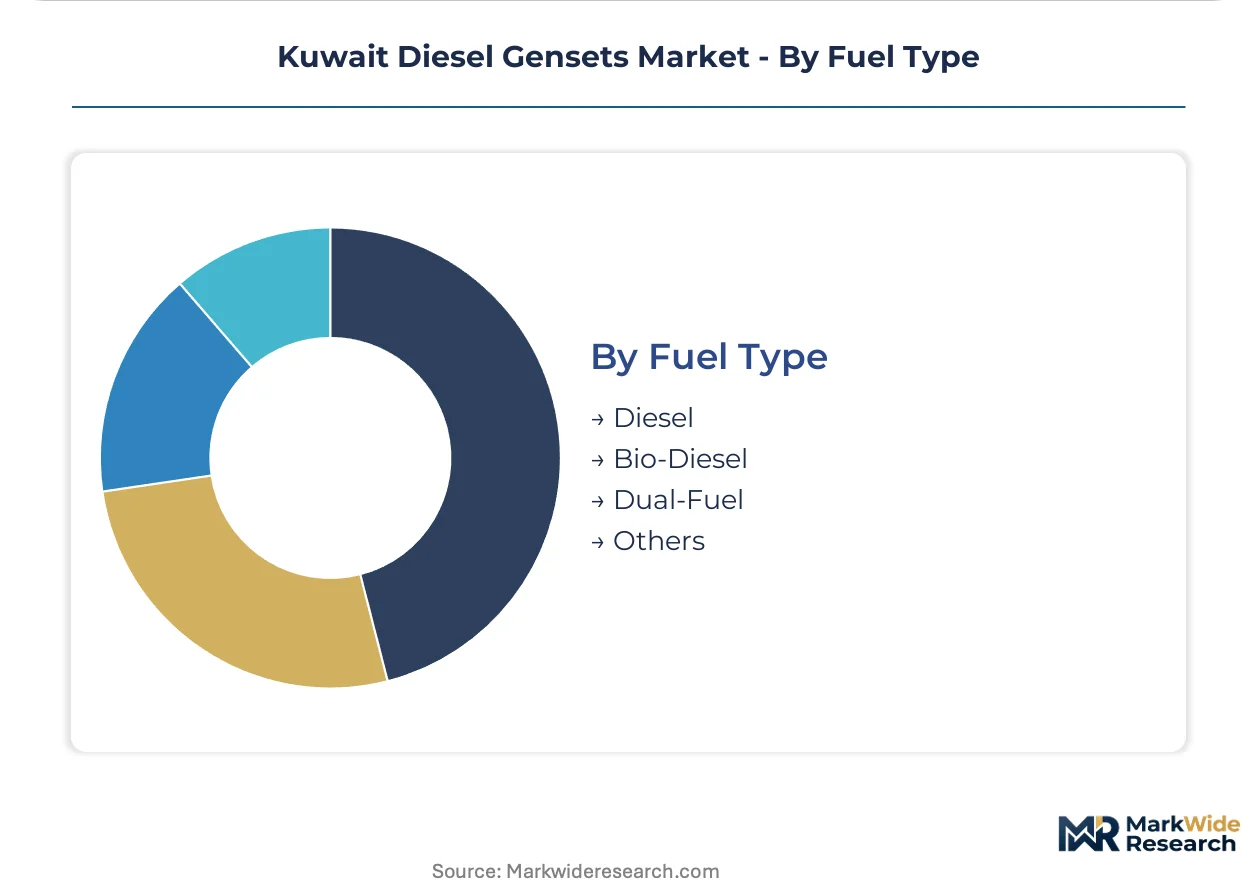
Combustion chemistry and storage infrastructure compatibility shape operational economics and emissions profiles.
- Diesel:Conventional petroleum distillate remains the baseline specification across all power ratings, with EN 590 grade fuel available through Kuwait National Petroleum Company distribution networks.
- Dual-Fuel:Natural gas-diesel blending capability reduces liquid fuel consumption for continuous-duty applications with pipeline access. Oilfield operators evaluate this option for production facilities proximal to associated gas gathering systems.
- Bio-Diesel:B5 and B20 blends face limited adoption due to thermal stability concerns in Kuwait's 50°C summer ambient conditions.
- Others:Synthetic and hydrogen-enriched pilot programs remain experimental with no commercial scale deployment.
Diesel anchors current procurement; Dual-Fuel shows steepest expansion trajectory among alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Al-Ahmadi industrial zone anchors Kuwait's diesel genset procurement, with oilfield operators and refinery complexes driving concentrated demand for heavy-frame units above 500 kVA.
Kuwait City Commercial Corridor
Silk City and Bubiyan Island megaprojects generate synchronized demand spikes for temporary power infrastructure. Kuwait's Public Authority for Industry enforces expedited conformity assessment for pre-certified equipment. Construction contractors in Salmiya and Hawally districts prioritize portable rental fleets over asset ownership.
Northern Oilfields
Burgan and Ratqa field operators expand standby capacity to prevent production losses during peak summer grid strain. The Environment Public Authority mandates particulate filters and selective catalytic reduction for units above 500 kVA. Continuous-duty specifications here command premium pricing structures unavailable in other segments.
Al-Ahmadi Industrial Zone
Refinery complexes and petrochemical facilities require synchronized paralleling capability for seamless grid transfer. EPA thermal limits create replacement demand for older mechanically governed fleets. Shuwaikh Industrial Area food processors and plastics producers concentrate procurement in the 300-500 kVA bracket.
Jahra and Farwaniya Governorates
Distributed manufacturing facilities and mid-rise construction sites absorb volume in the 100-300 kVA compact segment. Ministry of Electricity and Water grid stabilization investments reshape backup power economics here. Residential and small commercial standby applications in dense urban fabric favor 15-100 kVA single-cylinder packages.
Kuwait Diesel Gensets Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue hybrid retrofit and equipment-as-service models to bypass capital-intensive manufacturing barriers. The supplier base consolidates around three strategic archetypes: integrated engine-alternator manufacturers with regional assembly footprints, specialized rental fleet operators bundling fuel management and uptime guarantees, and aftermarket service networks competing on technician density across industrial zones. Dominant competitive moves include backward integration into alternator winding operations and strategic partnerships with port logistics providers to circumvent Shuwaikh customs bottlenecks.
Among the named participants, FG Wilson leverages its regional assembly footprint to shorten lead times for Kuwaiti contractors, while Caterpillar Inc. anchors the high-power segment through its dealer network serving oilfield operators. Jubaili Bros. occupies a position competing aggressively on aftermarket service coverage across the emirate's industrial zones.
| Leading Market Players |
|---|
| Kohler Co. |
| FG Wilson |
| Caterpillar Inc. |
| Jubaili Bros. |
| Yanmar Holdings Co. Ltd. |
| Cummins Inc. |
| Generac Power Systems, Inc. |
| Kirloskar Oil Engines Limited |
| Atlas Copco AB |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed refinery operators and family-owned rental fleet specialists anchor Kuwait's diesel genset procurement, concentrating buying power among price-disciplined end-users who negotiate multi-year service contracts. This ownership pattern compresses supplier margins while rewarding regional assembly footprints that bypass customs bottlenecks at Shuwaikh Port.
Pricing Analysis
Input-cost pass-through from London Metal Exchange steel and copper pricing governs contract structures for fixed-price construction tenders, with alternator winding and engine block castings absorbing volatility. Three-tier pricing structure across premium, standard, and economy levels separates EPA-certified electronic fuel injection systems from mechanically governed legacy units. Price differentiation hinges on after-sales service bundling and PAI fast-track certification status. Cost compression in the below-300 kVA segment intensifies because solar-plus-storage alternatives erode standby power economics. Construction contractors show highest price sensitivity, while oilfield operators accept premiums for continuous-duty ratings and Zone 2 hazardous area certifications.
Supply Chain Analysis
Alternator winding supply rests on German, Chinese, and Indian specialty electrical steel producers, with engine block castings sourced from foundries in Turkey, Italy, and South Korea. Raw material dependencies include copper magnet wire, silicon steel laminations, and high-grade nodular iron for crankshaft production. Single-source vulnerability concentrates at Shuwaikh Port, where over 80% of genset arrivals face customs clearance delays during peak construction seasons. Distribution runs through Caterpillar and FG Wilson dealer networks serving oilfield operators, alongside Jubaili Bros. service corridors spanning Al-Ahmadi industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait's diesel genset market represents a late-cycle quality story as EPA emissions mandates and PAI conformity assessment force fleet replacement toward electronic fuel injection and after-treatment systems. Oil and gas operators now specify CAN-bus diagnostics and remote telemetry as standard procurement requirements, elevating premium-tier equipment economics.
For Market Incumbents: To counter solar-plus-storage substitution in the below-300 kVA commercial segment, FG Wilson and Caterpillar should deepen backward integration into alternator winding operations to hedge London Metal Exchange volatility. Certification investment in EU Stage V pre-approval pathways secures PAI fast-track clearance and compresses product launch cycles by 8-14 months. For New Entrants and Emerging Players: The 100-300 kVA price-point gap between premium electronic fuel injection systems and economy mechanical pumps offers white-space entry for hybrid retrofit kit specialists targeting Jahra and Farwaniya manufacturing facilities. Equipment-as-service contracts with guaranteed uptime SLAs penetrate Kuwait City's commercial construction corridor most rapidly, where contractors prioritize balance-sheet flexibility over asset ownership. For Investors and Strategic Acquirers: Valuations sit cheapest among aftermarket service networks with technician density across Al-Ahmadi and northern oilfield zones, given scarcity of electronic engine management diagnostics capability. Long-term viability over a 5-10 year window hinges on hybrid integration IP and rental fleet scale. The signal to watch is Environment Public Authority alignment with GCC technical regulations accelerating mechanically governed engine phase-out.| Strategic Initiative | Industry Significance |
|---|---|
| PAI Fast-Track Certification Investment | Pre-approval to EU Stage V standards compresses customs clearance timelines for Kuwaiti imports. |
| Hybrid Retrofit Kit Development | Battery-diesel integration reduces runtime hours while maintaining spinning reserve for oilfield operators. |
| Aftermarket Technician Training Scale-Up | Electronic engine management diagnostics scarcity constrains service network expansion across industrial zones. |
| Backward Integration into Alternator Winding | Captive supply of copper magnet wire hedges London Metal Exchange price volatility for fixed-price contracts. |
| Equipment-as-Service Contract Expansion | Monthly tariffs bundling fuel management and 24-hour response displace outright purchase in construction corridors. |
Study Parameters
Bottom-up oilfield operator and construction contractor modeling reconciled against top-down import tracking through Kuwait's Public Authority for Industry forms the analytical core of this study. Primary interviews with maintenance directors at Kuwait Oil Company, plant engineers at Al-Ahmadi refinery complexes, rental fleet operators in Salmiya, and aftermarket service heads at Jubaili Bros. combined with secondary validation from EPA regulatory filings, PAI conformity assessment databases, customs import records, and London Metal Exchange pricing data. Triangulation between demand-side procurement patterns and supply-side manufacturing capacity ensures statistical integrity.
Historical trendline analysis of power rating bracket shipments across the projection horizon informs segment-level growth trajectory modeling. Segmentation dimensions include power rating tier, end-user vertical, deployment model mobility requirements, and fuel type combustion chemistry. CAGRs derive from regression analysis against oilfield expansion capex, commercial construction permit flows, and grid stabilization investment schedules. Forecast inputs incorporate EPA emissions mandate compliance timelines and PAI certification throughput rates.
Caveats apply where Kuwait's renewable energy targets or lithium-ion cost declines could materially shift the outlook for diesel standby economics in commercial applications below 300 kVA. Forecasts reflect assumptions around northern oilfield production uptime requirements and summer grid strain severity. A small set of triggers—including EPA-GCC regulatory alignment acceleration and hybrid technology cost parity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Europe Portable Generator Market
Generators
Boiler Turbine and Generator BTG Sales Market
Generators
Southeast Asia Portable Generator Market
Generators
Home Standby Gensets Market
Generators
Middle-East and Africa Generator Sets Market
Generators
Digital Inverter Generator Market
Generators
Global Diesel Gensets Market
Generators
Tanzania Diesel Generator Market
Generators
South America Gas Generator Market
Generators
Diesel Generator Market
Generators
Railway Generators Market
Generators
Onboard Marine Gensets Market
Generators
United States Diesel Generator Market
Generators
Silent Generator Market
Generators
India Diesel Generator Market
Generators
Gas Generator Sets Market