
 Heat Recovery System Generator Market | 2026-2036
Heat Recovery System Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Recovery System Generator Market Foresight
Modular heat exchange architectures is fragmenting traditional centralized HRSG procurement models across heavy industry. Siemens Energy AG leverages its turbine-integration expertise to anchor large-scale combined-cycle projects in European power corridors. Mitsubishi Power competes on ultra-supercritical steam parameters for Asian utility customers. Thermax Limited specializes in standardized, skid-mounted units that reduce installation timelines for Indian cement and steel producers.
A heat recovery system generator captures exhaust thermal energy from gas turbines, industrial furnaces, or process streams and converts it into steam or electric power through thermodynamic cycles. These systems typically operate at pressures ranging from sub-atmospheric to supercritical conditions above 220 bar, with feedwater temperatures engineered to prevent acid dewpoint corrosion in sulfur-bearing flue gases. Steam-based HRSG configurations retain the largest installed base across power utilities, though Organic Rankine Cycle units are expanding fastest in geothermal and biomass applications where source temperatures fall below 300°C. Cement plants and oil refineries represent concentrated margin pools where energy management mandates drive retrofit demand.
The US EPA enforces Maximum Achievable Control Technology standards that compel refinery operators to recover waste heat rather than vent thermal emissions to atmosphere. China's MEE implements dual carbon targets that phase down coal-fired auxiliary boilers, directly expanding HRSG deployment in manufacturing zones. The EU Green Deal and associated ETS carbon pricing mechanisms force industrial emitters to justify unrecovered heat streams against compliance costs. Stakeholders must track how carbon border adjustment mechanisms reshape the cost calculus for imported versus domestically manufactured heat recovery equipment.
Market Dynamics
China's dual carbon mandates are compressing installation timelines for waste heat recovery units across cement and steel corridors, forcing engineering procurement to abandon traditional build-to-order cycles in favor of standardized skid-mounted configurations.
Growth Catalysts
- MEE dual carbon enforcement:China's Ministry of Ecology and Environment phases down coal-fired auxiliary boilers in manufacturing zones, compelling cement producers to install Organic Rankine Cycle systems for low-grade heat capture.
- Refinery MACT compliance:The US EPA mandates Maximum Achievable Control Technology standards that prohibit thermal venting, requiring petroleum refiners to deploy HRSG units for exhaust energy conversion.
- Modular heat exchange architectures:Standardized skid-mounted designs reduce field installation labor and commissioning duration, accelerating procurement decisions among Indian steel producers facing compressed capital approval windows.
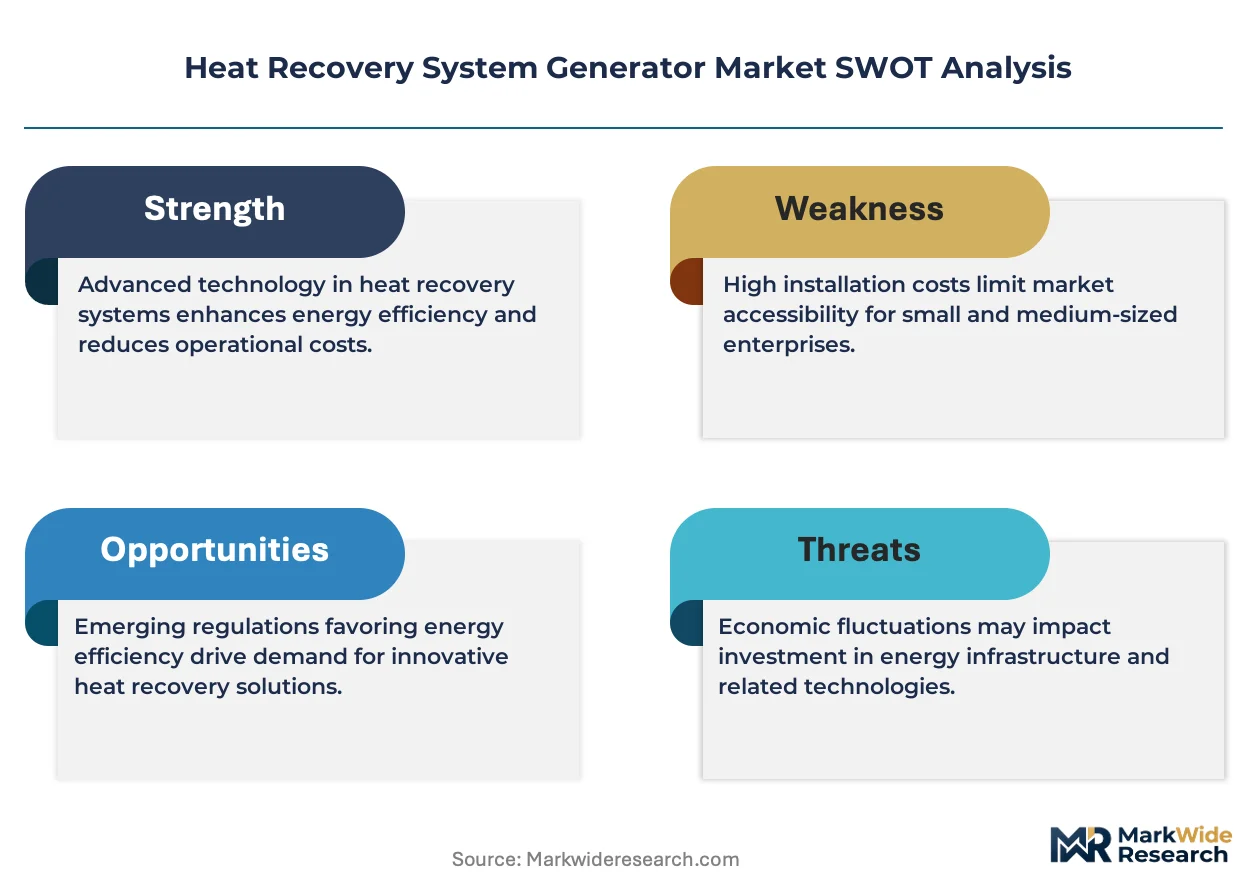
Market Restraints
- Superalloy supply concentration:High-nickel heat exchanger tubing faces sourcing constraints from concentrated specialty steel producers, inflating lead times for supercritical pressure HRSG configurations.
- Acid dewpoint corrosion limits:Sulfur-bearing flue gases in oil refining and coal-adjacent processes impose material selection constraints that elevate capital costs for sub-150°C exhaust streams.
- Legacy steam turbine substitution:Existing combined-cycle operators defer HRSG retrofits when gas turbine repowering offers faster payback, cannibalizing waste heat recovery capital allocations.
Strategic Opportunities
- EU ETS carbon price escalation:The European Union Emissions Trading System forces industrial emitters to justify unrecovered heat against compliance costs, expanding retrofit demand in German chemical corridors.
- Geothermal binary cycle expansion:Organic Rankine Cycle technology converges with geothermal brine applications below 300°C, opening project finance structures previously reserved for higher-temperature steam resources.
- Biomass cogeneration clusters:Agricultural waste-to-energy facilities in Southeast Asia adopt low-grade heat recovery where grid interconnection tariffs favor distributed generation over utility-scale alternatives.
Industry Challenges
- ASME Section VIII certification timelines:Pressure vessel qualification for supercritical HRSG designs extends engineering cycles, compressing vendor margins on fixed-price contracts.
- Legacy DCS integration complexity:Brownfield installations require protocol bridging between modern heat recovery controls and existing distributed control systems, inflating commissioning risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Recovery System Generator Market |
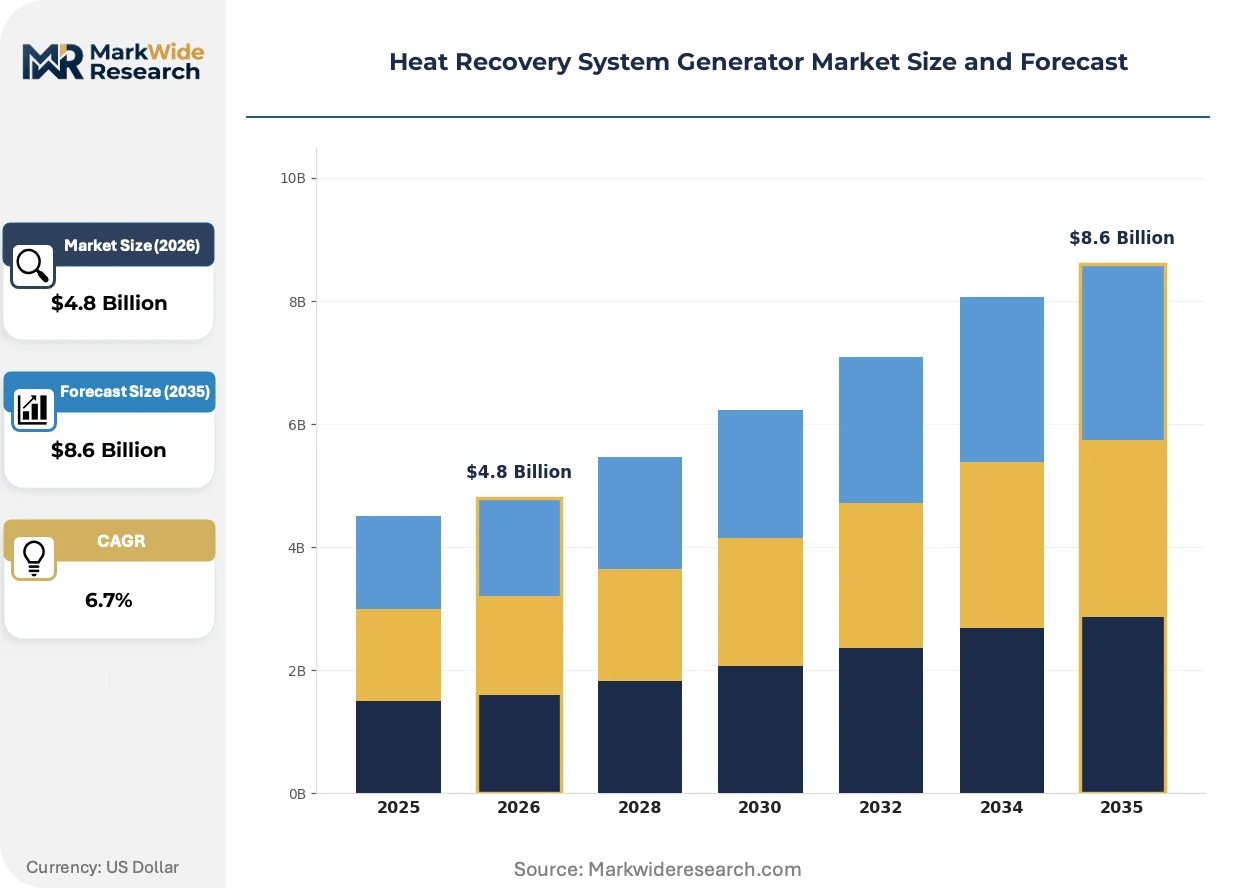
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Steam, Organic Rankine Cycle, Thermoelectric, Heat Pump Application: Industrial Processes, Power Generation, HVAC, Energy Management End User: Cement Plants, Oil Refineries, Manufacturing, Power Utilities Deployment: On-Site, Distributed, Centralized, Modular |
| Companies Covered | General Electric (GE Vernova), Siemens Energy AG, Mitsubishi Power, Thermax Limited, Nooter/Eriksen, Babcock & Wilcox, Doosan Enerbility, CMI Energy, John Cockerill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Recovery System Generator Market Shifts & Advancements
Equipment vendors are reconfiguring product architectures around thermal source variability rather than design-point optimization, anticipating feedstock flexibility requirements that span biomass, geothermal, and industrial waste streams.
Organic Rankine Cycle technology is hybridizing with conventional steam-bottoming configurations to capture heat across wider temperature gradients. Cement producers in Shandong Province pilot these dual-cycle arrangements to maximize energy recovery from kiln exhaust. The approach compresses payback periods by eliminating the economic dead zone where pure steam systems fail to justify capital deployment.
The EU Green Deal's F-Gas Regulation accelerates refrigerant substitution in ORC working fluids, restricting high-global-warming-potential hydrocarbons from new installations. Equipment suppliers reformulate thermal oil chemistries to maintain cycle efficiency under tighter environmental constraints. Geothermal developers in Italy and Turkey face accelerated obsolescence risk for existing hydrocarbon-based units.
Refinery operators unbundle after-sales service contracts from initial equipment procurement, awarding multi-year performance guarantees to specialized maintenance providers rather than OEM service divisions. This procurement fragmentation compresses vendor margins on original sales while expanding recurring revenue pools for independent service companies. The pattern is most pronounced among US Gulf Coast processors facing compressed turnaround windows.
Heat Recovery System Generator Market Segmentation
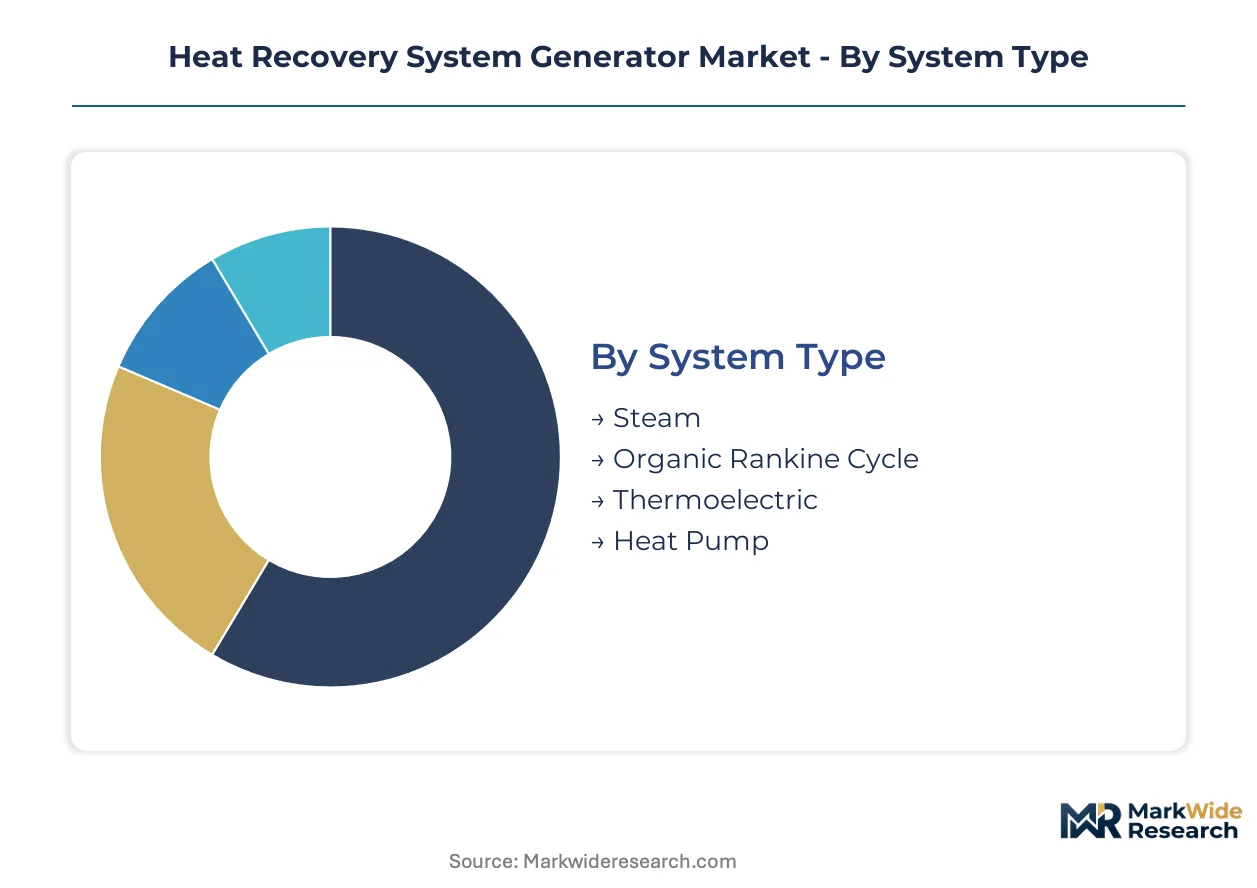
Heat recovery system generators serve divergent thermal profiles across industrial and power applications, forcing vendors to architect platforms around temperature bands, pressure regimes, and integration complexity rather than universal specifications.
System Type:
Mature steam-based configurations dominate utility-scale installations while emerging thermoelectric and heat pump architectures capture niche temperature ranges where conventional cycles fail.
- Steam:Conventional water-steam cycles operate across sub-atmospheric to supercritical pressures above 220 bar, handling exhaust temperatures from 300°C to 600°C. Cement producers in China deploy these for high-grade kiln exhaust recovery under MEE dual carbon enforcement, though acid dewpoint corrosion constraints limit economizer performance in sulfur-bearing streams.
- Organic Rankine Cycle:Hydrocarbon or silicone-based working fluids enable power generation from heat sources below 300°C where steam efficiency collapses. Geothermal developers in Italy and Turkey favor these units for brine applications, though EU F-Gas Regulation refrigerant restrictions now force working fluid reformulation.
- Thermoelectric:Solid-state semiconductor modules convert thermal gradients directly to electricity without moving parts, suited for remote or maintenance-constrained environments.
- Heat Pump:Mechanical vapor compression upgrades low-grade waste heat to useful temperature levels for process integration or district heating networks.
Steam handles the majority of throughput; Organic Rankine Cycle is the fastest mover on share.
Application:
Cost tier differentiation separates capital-intensive power generation deployments from operational-expense-focused industrial process integration.
- Industrial Processes:Exhaust recovery from furnaces, kilns, and reactors where thermal integration directly reduces fuel input costs. Oil refineries under US EPA MACT standards deploy these systems to eliminate thermal venting, with payback periods compressed by carbon pricing exposure.
- Power Generation:Combined-cycle gas turbine bottoming cycles that lift plant efficiency from simple-cycle levels. Asian utility operators specify ultra-supercritical steam parameters to maximize output from premium natural gas feedstock.
- HVAC:Building-scale heat recovery ventilation and thermal energy storage for commercial and institutional facilities.
- Energy Management:Grid-interactive systems that modulate heat recovery based on real-time electricity pricing and demand response signals.
Industrial Processes anchors current deployment value; Energy Management is expanding most quickly as digital controls mature.
End User:
Customer type segmentation reveals concentrated procurement authority among energy-intensive process industries versus fragmented utility purchasing.
- Cement Plants:Rotary kiln exhaust recovery dominates waste heat capture economics in this sector, with Chinese producers under dual carbon mandates driving standardization toward skid-mounted configurations.
- Oil Refineries:FCCU and coker exhaust streams contain recoverable thermal energy, though hydrogen sulfide content imposes severe acid dewpoint corrosion limits on material selection.
- Manufacturing:Steel, glass, and chemical producers with dispersed heat sources favor modular architectures that match recovery capacity to individual process lines.
- Power Utilities:Centralized procurement of large-scale combined-cycle HRSG units with long service contracts and performance guarantees.
Cement Plants command the largest project pipeline; Manufacturing is climbing the fastest as distributed energy mandates proliferate.
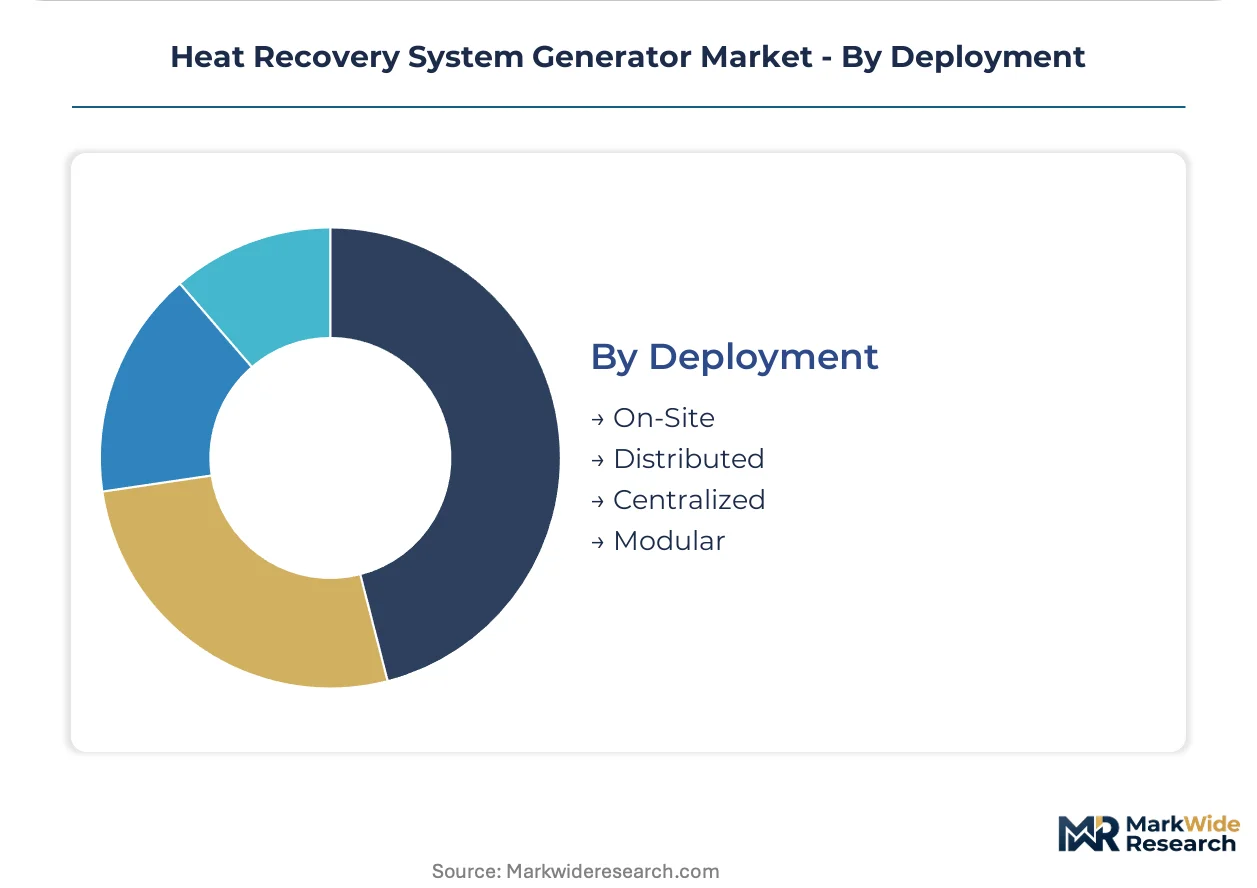
Deployment:
Supply concentration in modular fabrication is displacing field-erected construction for projects below 100 MW thermal capacity.
- On-Site:Custom-engineered systems built and commissioned at the point of use, retaining preference for supercritical pressure configurations where transport limits apply.
- Distributed:Multiple smaller units serving thermal loads across extended industrial campuses or district heating networks.
- Centralized:Single large-capacity systems integrated with utility-scale power generation or major process complexes.
- Modular:Factory-fabricated skid-mounted units that reduce field labor and commissioning duration, accelerating procurement decisions among Indian steel producers facing compressed capital approval windows.
On-Site retains the largest installed base; Modular is gaining share fastest as engineering procurement cycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering exports anchor European HRSG procurement while Chinese fabrication supplies retrofit waves across Asian cement corridors. Trade flows concentrate specialized heat exchanger components from South Korean foundries into US Gulf Coast refinery expansions.
United States
US Gulf Coast refineries under EPA MACT enforcement drive demand for acid-resistant HRSG configurations. The Environmental Protection Agency prohibits thermal venting from FCCU and coker exhaust streams. Houston-area processors award multi-year performance contracts to specialized maintenance providers rather than OEM divisions.
China
Shandong Province cement producers pilot hybrid steam-ORC arrangements to maximize kiln exhaust recovery. The Ministry of Ecology and Environment phases down coal-fired auxiliary boilers under dual carbon mandates. Modular skid-mounted configurations displace field-erected construction across manufacturing zones.
Germany
Ruhr industrial clusters face EU ETS carbon pricing that forces chemical producers to justify unrecovered heat streams. The EU Green Deal and F-Gas Regulation restrict high-GWP refrigerants in ORC working fluids. Bavarian engineering groups supply ultra-supercritical steam parameters to Asian utility customers.
India
Maharashtra and Gujarat steel producers compress capital approval windows for waste heat recovery installations. The Bureau of Indian Standards certifies pressure vessels for sub-critical HRSG deployments. Thermax Limited anchors standardized skid-mounted supply from Pune fabrication facilities.
Italy
Tuscany and Sicily geothermal developers favor ORC units for brine applications below 300°C. The EU F-Gas Regulation accelerates obsolescence risk for existing hydrocarbon-based working fluid installations. Binary cycle project finance structures now compete with traditional steam resource economics.
Heat Recovery System Generator Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement hierarchies that separate utility-scale combined-cycle projects from industrial retrofit deployments. The vendor base organizes around three strategic archetypes: turbine-integrated system architects, modular fabrication specialists, and aftermarket service unbundlers. Consolidation pressure concentrates among superalloy heat exchanger suppliers facing nickel sourcing constraints. Competitive moves center on vertical integration into specialty steel tubing and geographic expansion through licensing arrangements in ASEAN manufacturing corridors.
Within the turbine-integrated tier, General Electric (GE Vernova) and Siemens Energy AG exemplify system architects that anchor large-scale power generation procurement. Mitsubishi Power occupies a position among Asian-headquartered ultra-supercritical specialists serving utility customers. Thermax Limited represents the modular fabrication archetype with standardized skid-mounted configurations. Nooter/Eriksen and Babcock & Wilcox sit within the aftermarket and retrofit specialist tier. Doosan Enerbility, CMI Energy, and John Cockerill each exemplify regional fabrication anchors with distinct geographic positioning.
| Leading Market Players |
|---|
| General Electric (GE Vernova) |
| Siemens Energy AG |
| Mitsubishi Power |
| Thermax Limited |
| Nooter/Eriksen |
| Babcock & Wilcox |
| Doosan Enerbility |
| CMI Energy |
| John Cockerill |
| Others |
Supply & Pricing Matrix
High-nickel superalloy supply concentration from concentrated specialty steel producers determines both pricing tier spreads and supply chain shape across supercritical pressure HRSG configurations. Procurement officers face extended lead times that compress vendor margins on fixed-price contracts while inflating capital costs for sub-150°C exhaust stream applications.
Pricing Analysis
Steam-generation versus Organic Rankine Cycle technology-generation pricing gaps separate mature utility-scale configurations from emerging low-grade heat recovery systems. Three-tier pricing structure across premium supercritical steam, standard sub-critical modular, and economy-grade ORC units reflects ASME Section VIII certification investment and nickel alloy content. Cost compression in standard skid-mounted tiers intensifies because Indian and Chinese fabricators compete on installation timeline reduction. Cement producers in Shandong Province exhibit highest price sensitivity due to compressed capital approval windows under MEE dual carbon enforcement, while European utility operators under EU ETS carbon pricing show lowest sensitivity as compliance costs dominate total cost of ownership.
Supply Chain Analysis
Extended payment terms from 90 to 180 days now anchor supplier-financing negotiations between OEMs and specialty steel tubing mills. High-nickel alloy production concentrates in Germany, Japan, and South Korea, drawing from Indonesian nickel ore and Chilean copper cathode feedstocks. Single-source vulnerability for superalloy heat exchanger tubing creates procurement chokepoints when refinery MACT compliance deadlines compress simultaneously across US Gulf Coast installations. Distribution runs through EPC contractors with established relationships to cement and steel producers rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EPA MACT standards and EU ETS carbon pricing creates durable defensive moats for incumbent vendors with certified pressure vessel portfolios and established refinery service relationships.
For Market Incumbents: Harden position by securing captive supply agreements with South Korean and German specialty steel producers before nickel sourcing constraints deepen. Expand backward integration into nickel alloy tubing production to defend margins against emerging modular fabrication specialists from India and ASEAN manufacturing corridors. For New Entrants and Emerging Players: Mid-scale biomass cogeneration clusters in Southeast Asia represent the most penetrable entry point where grid interconnection tariffs favor distributed generation over utility-scale alternatives. Geothermal binary cycle projects below 300°C in Italy and Turkey offer second white-space target where EU F-Gas Regulation accelerates obsolescence risk for existing hydrocarbon-based ORC units. License ORC working fluid formulations from European engineering groups to bypass refrigerant chemistry R&D barriers. For Investors and Strategic Acquirers: EU F-Gas Regulation refrigerant substitution deadlines reshape the acquisition landscape toward ORC technology holders with reformulated silicone-based working fluid portfolios. Long-term viability centers on project finance structures for low-temperature geothermal and industrial waste heat applications rather than commodity steam HRSG fabrication. Monitor carbon border adjustment mechanism implementation as inflection indicator for imported versus domestically manufactured equipment cost calculus.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Alloy Tubing | Captive supply of superalloy heat exchanger components defends margins against sourcing concentration. |
| ORC Working Fluid Reformulation | Silicone-based refrigerant chemistry maintains cycle efficiency under EU F-Gas Regulation constraints. |
| Modular Skid-Mounted Standardization | Factory fabrication reduces field labor and accelerates procurement decisions among Indian steel producers. |
| Geothermal Binary Cycle Expansion | Project finance structures for sub-300°C brine applications open non-traditional heat recovery markets. |
| Aftermarket Service Unbundling | Multi-year performance guarantees to independent providers expand recurring revenue pools beyond OEM divisions. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, maintenance directors, EPC procurement officers, and aftermarket service heads across cement, steel, and refinery installations; and secondary validation through EPA MACT enforcement records, EU ETS carbon pricing databases, ASME Section VIII certification registries, and customs trade data for nickel alloy tubing imports. Bottom-up project pipeline aggregation across Chinese cement corridors, US Gulf Coast refineries, and Indian steel producers was triangulated against top-down vendor revenue segmentation.
Forecast inputs considered system type segmentation across steam, Organic Rankine Cycle, thermoelectric, and heat pump configurations; application splits between industrial process integration, power generation bottoming cycles, and energy management systems; and end-user concentration among cement plants, oil refineries, manufacturing facilities, and power utilities across the projection horizon. CAGRs were derived from installed base growth rates and retrofit penetration assumptions, with specific weighting for MEE dual carbon enforcement timelines and EU Green Deal implementation pace.
Stress conditions across nickel price volatility, ASME certification backlog duration, and carbon border adjustment mechanism coverage were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and superalloy supply availability. Macroeconomic contraction, accelerated refrigerant phase-out schedules, or breakthrough thermoelectric efficiency gains would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Halogenerator Market
Generators
Multi Fuel Generators Market
Generators
Nuclear Turbine Generators Market
Generators
Middle East Portable Generator Market
Generators
East Africa Diesel Generator Market
Generators
Europe Diesel Generator Market
Generators
Generator Sets Market
Generators
Global Portable Generator Market
Generators
South America Gas Generator Market
Generators
Diesel Generator Market
Generators
Power Generator Rental Market
Generators
North America Gas Generator Market
Generators
Wind Power Generators Market
Generators
Generator (Up to 20 Kva) Market
Generators
Portable Inverter Generators Market
Generators
Electric Generators Market