
 Marine Gensets Market | 2026-2036
Marine Gensets Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Gensets Market Analysis
Market Context
The capital-intensity divergence between integrated engine builders and component assemblers is redrawing competitive boundaries in marine power generation. Wärtsilä leverages its in-house dual-fuel technology to anchor premium contracts for offshore support vessels. Caterpillar sustains manufacturing scale across multiple power nodes, from harbor tugs to deep-sea container ships. Weichai Power competes aggressively on cost-engineered diesel platforms for Asian commercial fishing fleets.
Technical Definition and Segment Structure
Marine gensets are self-contained engine-generator assemblies engineered for salt-air corrosion resistance, continuous-rated output under vessel motion, and compliance with International Maritime Organization emission tiers. These units convert mechanical shaft power into shipboard electrical supply for propulsion auxiliaries, hotel loads, and mission-critical navigation systems. Diesel generators still occupy the dominant revenue position across commercial shipping applications, though hybrid generators are gaining structural share in leisure yachting where silent anchorage rules tighten. The above 500 kW power rating category concentrates margin pools, as offshore platforms and deep-sea vessels demand redundant megawatt-class installations with classification society certification.
Regulatory Framework and Outlook
The International Maritime Organization enforces Tier III nitrogen oxide limits in emission control areas, while the EU Green Deal and F-Gas Regulation constrain refrigerant choices in genset cooling circuits. EPA marine engine standards in the United States and China's MEE domestic emission rules add overlapping compliance layers for multinational fleet operators. Stakeholders must monitor which fuel pathway—methanol, ammonia, or advanced biofuel—gains regulatory preference in major flag states before committing to next-generation platform designs.
Market Dynamics
The IMO Tier III nitrogen oxide limits are fragmenting engine architectures, forcing manufacturers to split R&D budgets across scrubber-retrofitted diesel, dual-fuel methanol, and ammonia-ready platforms while offshore operators delay procurement decisions.
Growth Catalysts
- Offshore electrification gaps:Aging North Sea platforms in Norway sustain fossil backup demand as grid connections lag behind decommissioning schedules.
- EU Green Deal compliance:F-Gas Regulation constraints on refrigerants drive cooling circuit redesigns that favor higher-efficiency genset configurations.
- Dual-fuel engine maturation:Methanol bunkering infrastructure in Rotterdam and Singapore enables fuel-flexible genset deployments for container feeder vessels.
Market Restraints
- Stainless steel price volatility:Exhaust manifold and heat exchanger fabrication costs swing with nickel futures, compressing margins on fixed-price platform contracts.
- Classification society bottlenecks:Lloyd's Register and DNV type-approval queues for novel ammonia engines stretch 18-24 months, freezing newbuild genset selections.
- Electrification substitution:Battery-hybrid shore power systems at the Port of Los Angeles and Hamburg displace harbor genset runtime for container vessels.
Strategic Opportunities
- Vietnam shipbuilding expansion:Hyundai-Vinashin and other yards in Haiphong lack indigenous genset suppliers, creating white space for component localization.
- China MEE domestic emission rules:Stricter enforcement in Yangtze River emission control areas forces fishing fleet retrofits that favor modular genset swaps over full engine replacement.
- Digital twin convergence:Integration of genset telemetry with vessel energy management systems enables predictive maintenance contracts that capture aftermarket revenue.
Industry Challenges
- Combustion chemist scarcity:Ammonia flame stability expertise concentrates in marine engine OEMs, leaving independent genset assemblers dependent on licensed combustion maps.
- Multi-fuel certification complexity:Demonstrating compliance across diesel, methanol, and ammonia modes requires three parallel test cell campaigns, tripling validation capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Gensets Market |
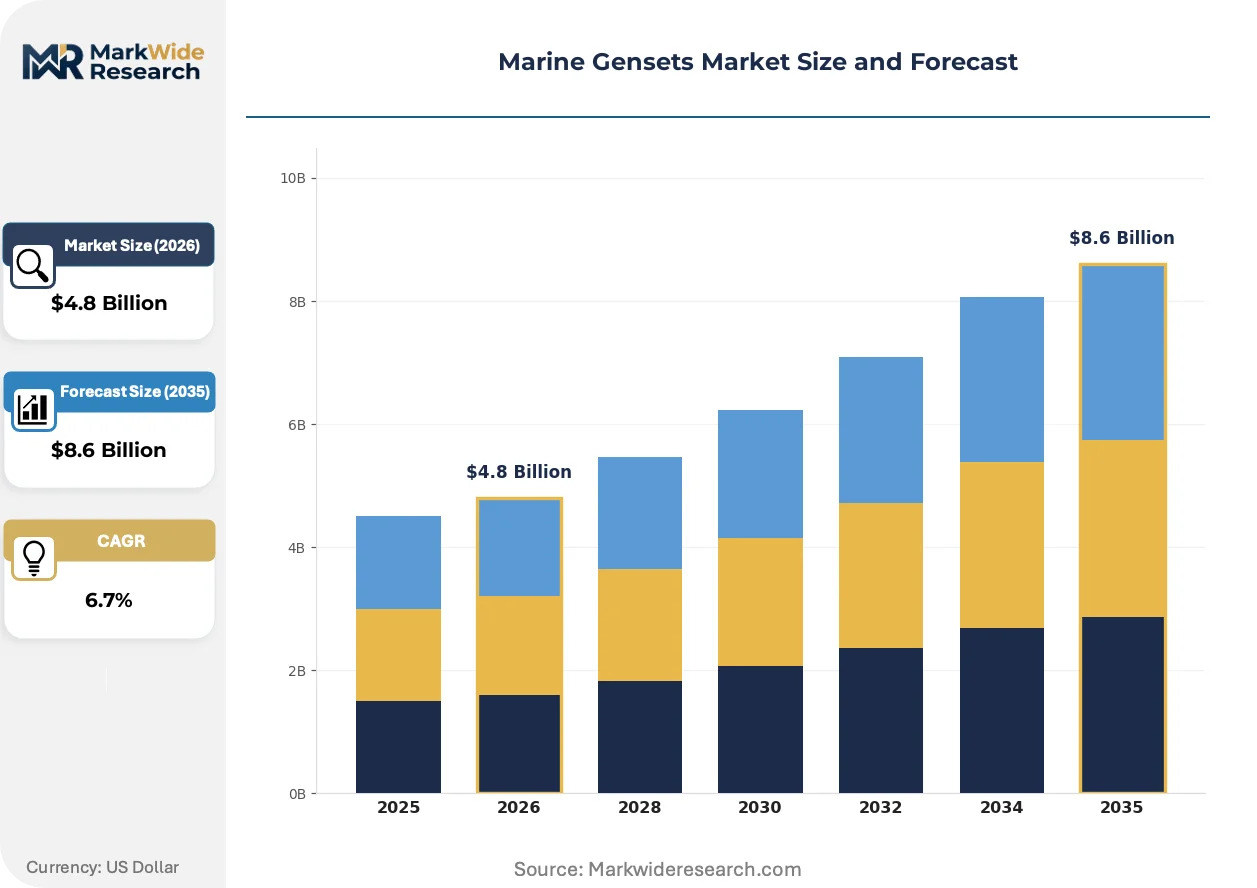
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generators, Gas Generators, Hybrid Generators, Portable Generators Application: Commercial Shipping, Leisure Yachting, Offshore Platforms, Fishing Vessels Power Rating: Up to 50 kW, 51 kW to 100 kW, 101 kW to 500 kW, Above 500 kW End User: Shipbuilders, Fleet Operators, Marine Researchers, Emergency Services |
| Companies Covered | Wärtsilä, Rolls-Royce Power Systems, Caterpillar, Weichai Power, Kohler Power, MAN Energy Solutions, Volvo Penta, Yanmar, Cummins Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Gensets Market Emerging Trajectories
Modular power architectures are displacing monolithic genset designs as vessel operators seek configurable redundancy for variable hotel loads and mission profiles.
Hybrid diesel-battery gensets are decomposing the traditional split between prime power and emergency generator categories. Offshore support vessel operators in the North Sea now specify combined packages where battery banks handle load spikes and diesels run at optimal continuous ratings. This convergence compresses the addressable market for standalone auxiliary gensets below 200 kW.
EPA marine engine standards and China's MEE rules are diverging on test cycle specifications, forcing multinational fleet operators to maintain dual certification dossiers for the same genset platform. The compliance burden falls heaviest on container lines with US-Asia routes, which now specify engines meeting both jurisdictions' worst-case limits to avoid port state control detention.
Charterers are unbundling genset maintenance from vessel management contracts, creating direct procurement relationships with engine OEMs that bypass traditional ship manager intermediaries. Greek and Singapore-based owners with large fleets now negotiate enterprise service agreements covering genset overhauls across multiple vessel classes, consolidating aftermarket spend with single-source providers.
Marine Gensets Market Segmentation
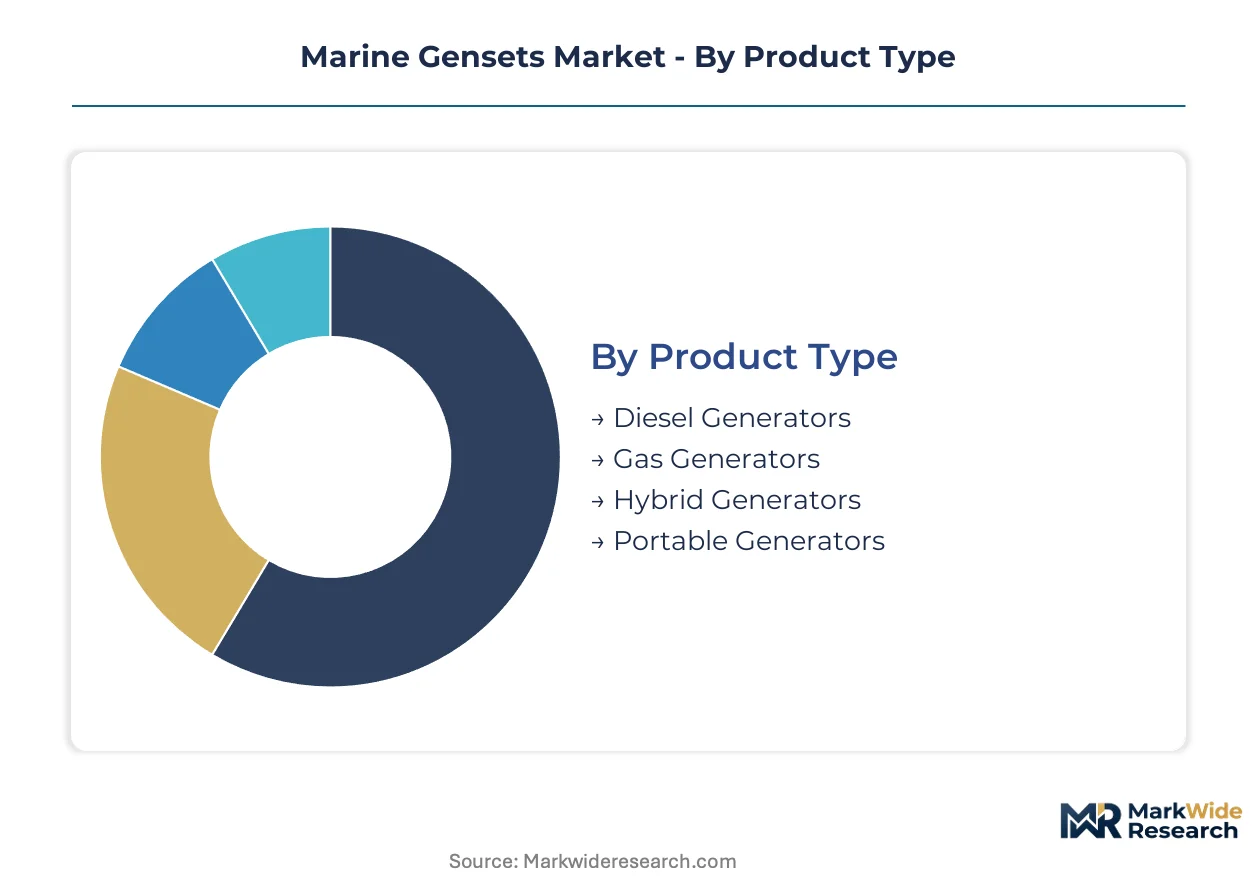
Segmentation in marine gensets reveals how regulatory pressure and operational duty cycles fragment procurement patterns across vessel classes. Understanding these divides helps suppliers align certification investments with actual revenue concentration rather than assumed fleet homogeneity.
Product Type:
IMO Tier III nitrogen oxide limits and the EU F-Gas Regulation on refrigerants create divergent compliance burdens across fuel and cooling architectures, forcing buyers to weight capital cost against multi-fuel flexibility.
- Diesel Generators:Compression-ignition engines with selective catalytic reduction or exhaust gas recirculation dominate commercial shipping due to established bunkering infrastructure. Fleet operators in Rotterdam and Singapore prioritize scrubber-retrofitted units for ECAs while awaiting methanol clarity.
- Hybrid Generators:Diesel-battery integrated systems with power electronics for load-leveling now anchor offshore support vessel specifications in Norway's North Sea cluster. Battery banks handle transient loads; diesels run at optimal continuous ratings, cutting fuel consumption and maintenance intervals.
- Gas Generators:Spark-ignited natural gas or dual-fuel engines serving LNG carriers and coastal ferries where IMO Tier III compliance is intrinsic to the fuel choice.
- Portable Generators:Compact skid-mounted units below 100 kW for emergency services and harbor maintenance craft requiring rapid deployment.
Established volume favors diesel architectures; emerging adoption favors hybrid configurations with integrated energy storage.
Application:
Cost tier differentiation separates capital-intensive offshore installations from price-sensitive coastal operations, with certification grade and redundancy requirements driving margin dispersion.
- Offshore Platforms:Redundant megawatt-class installations with DNV or Lloyd's Register type-approval for drilling support and accommodation power on aging North Sea infrastructure. Electrification gaps in Norway sustain fossil backup demand despite grid connection timelines.
- Commercial Shipping:Deep-sea container vessels and bulk carriers specifying gensets for hotel loads and navigation systems, with EPA and China MEE dual certification now standard for US-Asia routes.
- Leisure Yachting:Silent anchorage regulations in Mediterranean and Caribbean ports drive demand for low-noise, low-emission units with inverter synchronization.
- Fishing Vessels:Modular genset swaps preferred over full engine replacement in China's Yangtze River emission control areas, favoring cost-engineered platforms with MEE compliance.
Offshore platforms concentrate premium margin pools; fishing fleets represent the steepest expansion trajectory for retrofit-focused suppliers.
Power Rating:
Volume concentration in mid-range ratings contrasts with margin capture at the extremes, where classification society bottlenecks and material cost volatility reshape competitive economics.
- Above 500 kW:Megawatt-class synchronous generators with redundant cooling circuits and vibration isolation for deep-sea vessels and offshore platforms. Nickel price volatility in stainless steel exhaust manifolds compresses margins on fixed-price contracts.
- 101 kW to 500 kW:Workhorse ratings for harbor tugs, coastal ferries, and platform supply vessels where standardization enables manufacturing scale.
- 51 kW to 100 kW:Compact units for fishing vessels and inland waterway craft with space-constrained engine rooms.
- Up to 50 kW:Emergency and auxiliary power for yachts and small commercial craft, with battery-hybrid substitution eroding standalone diesel demand.
Above-500 kW ratings anchor aftermarket service contracts; sub-100 kW segments face electrification displacement.
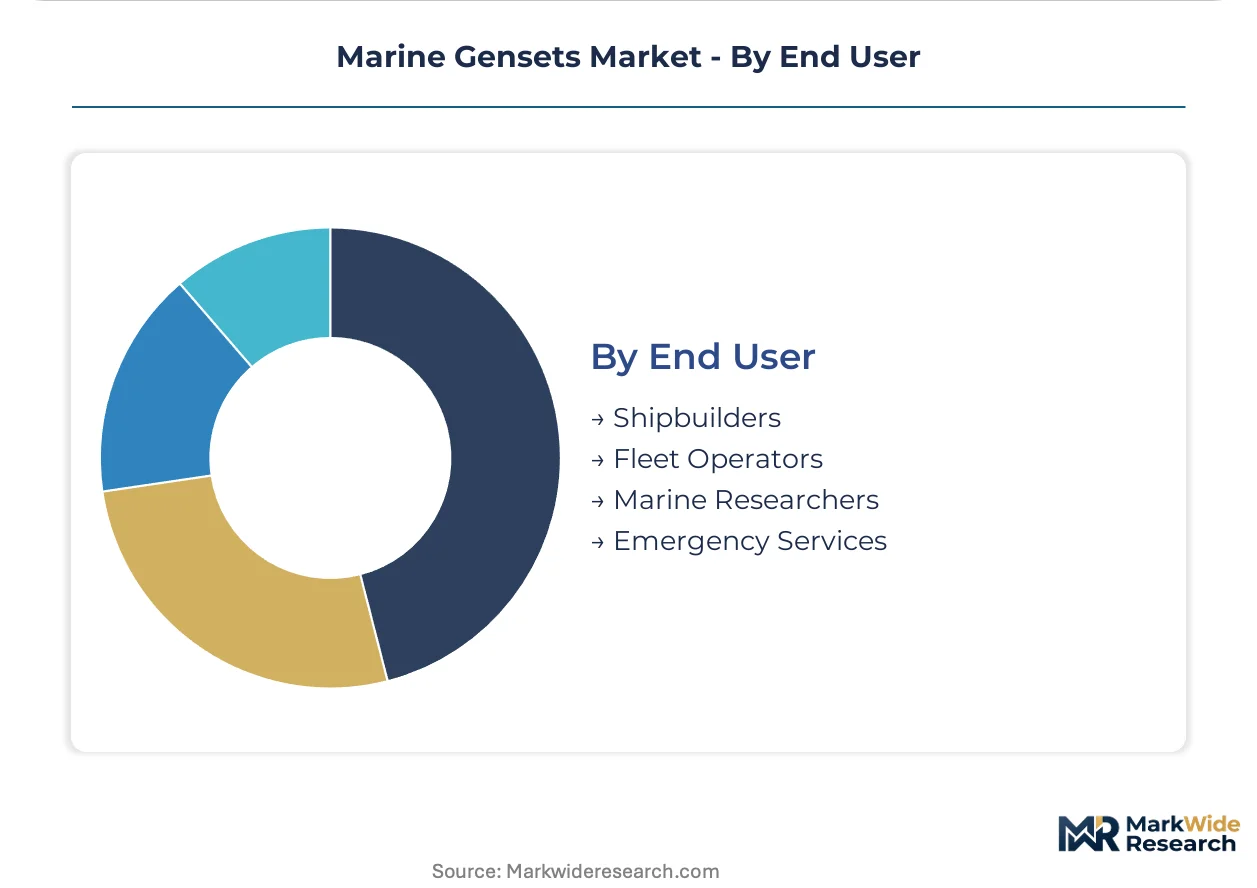
End User:
Customer type determines procurement channel structure, with direct OEM relationships displacing traditional ship manager intermediaries for large fleet operators.
- Fleet Operators:Greek and Singapore-based owners negotiating enterprise service agreements for genset overhauls across multiple vessel classes, consolidating aftermarket spend with single-source providers.
- Shipbuilders:Hyundai-Vinashin and other yards in Vietnam's Haiphong cluster lacking indigenous genset suppliers, creating localization opportunities for component assemblers.
- Marine Researchers:Ice-class research vessels requiring specialized cold-start and shock-rated installations for polar operations.
- Emergency Services:Coast guard and search-and-rescue fleets prioritizing reliability certification and rapid spare parts availability over fuel efficiency optimization.
Fleet operators drive consolidation in aftermarket capture; shipbuilders in emerging construction centers offer white-space expansion for supply localization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Vietnam and Indonesia exhibit acute price sensitivity on genset procurement, while Norwegian offshore operators absorb premium pricing for DNV-certified redundancy systems without volume elasticity.
Norway
North Sea platform electrification gaps sustain megawatt-class diesel backup demand as grid connection timelines slip past decommissioning schedules. The EU Green Deal and national carbon intensity targets force dual-fuel retrofits on aging accommodation modules. Bergen and Stavanger anchor the supplier ecosystem, where Wärtsilä and local engineering firms co-locate service centers for rapid offshore mobilization.
China
Yangtze River emission control areas drive modular genset swaps across fishing fleets seeking MEE compliance without full engine replacement. Stricter enforcement of domestic emission rules accelerates retrofit timelines for coastal vessels. Shanghai and Ningbo concentrate manufacturing capacity, with Weichai Power and domestic assemblers competing on cost-engineered platforms for Asian commercial operators.
United States
EPA marine engine standards and California Air Resources Board rules create overlapping compliance layers for container lines on US-Asia routes. Battery-hybrid shore power installations at the Port of Los Angeles displace harbor genset runtime for vessels at berth. The Gulf Coast petrochemical corridor sustains demand for explosion-rated gensets on tankers and offshore supply vessels.
Germany
EU F-Gas Regulation constraints on refrigerants force cooling circuit redesigns that favor higher-efficiency genset configurations for inland waterway craft. The KBA enforces type-approval standards that extend validation timelines for novel fuel architectures. Hamburg and the Rhine-Ruhr industrial belt concentrate engine testing infrastructure, with MAN Energy Solutions anchoring R&D investment in ammonia-ready platforms.
Singapore
Methanol bunkering infrastructure expansion enables fuel-flexible genset deployments for container feeder vessels transiting the Strait of Malacca. The Maritime and Port Authority mandates emission monitoring systems that integrate with genset telemetry for real-time compliance reporting. Jurong ship repair clusters and Tuas port development sustain aftermarket service demand for dual-fuel retrofits.
Marine Gensets Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with in-house combustion technology separating premium contract winners from component assemblers. The top tier captures offshore platform and deep-sea vessel mandates through captive dual-fuel development, while mid-tier players compete on manufacturing scale for harbor craft and fishing fleets. Strategic archetypes include full-stack engine builders, licensed assemblers, and aftermarket service consolidators. M&A activity concentrates on digital twin capabilities and predictive maintenance platforms; geographic expansion targets Vietnam's shipbuilding white space.
Among integrated European engine builders, Wärtsilä and MAN Energy Solutions exemplify the premium-tier archetype through in-house dual-fuel technology and classification society co-development. Caterpillar occupies a position at the scale-driven end, sustaining manufacturing breadth across multiple power nodes and vessel classes. Weichai Power represents the cost-engineered specialist tier, competing aggressively on diesel platform pricing for Asian commercial fishing and coastal operations.
| Leading Market Players |
|---|
| Wärtsilä |
| Rolls-Royce Power Systems |
| Caterpillar |
| Weichai Power |
| Kohler Power |
| MAN Energy Solutions |
| Volvo Penta |
| Yanmar |
| Cummins Inc. |
| Others |
Supply Flow & Price Mechanics
Manufacturing scale at Wärtsilä's Finnish and Chinese facilities anchors price floors for dual-fuel gensets, while smaller assemblers in Vietnam and Indonesia compete on stripped-down diesel platforms with thinner aftermarket margins. This scale divergence concentrates premium pricing power among integrated engine builders and compresses mid-tier profitability.
Pricing Analysis
Aftermarket service contracts and spare parts provisioning drive lifetime value for genset OEMs, often exceeding initial equipment margins across the ownership cycle. Three-tier pricing structure across premium, standard, and economy levels separates DNV-certified offshore installations from harbor craft and fishing fleet configurations. Pricing pressure stems from nickel volatility in stainless steel exhaust manifolds, which squeezes fixed-price platform contracts. Fleet operators in Greece and Singapore exhibit lowest price sensitivity for enterprise service agreements, while Vietnamese shipbuilders demand aggressive cost engineering on initial procurement.
Supply Chain Analysis
Inventory lead times for selective catalytic reduction catalysts and classification society type-approvals stretch 18-24 months, freezing newbuild genset selections for novel ammonia architectures. Manufacturing concentrates in Finland, Germany, and China, with Bergen and Shanghai anchoring dual-fuel and cost-engineered production respectively. The supply chain draws from nickel futures markets for exhaust manifolds, copper for windings, and rare earth elements for power electronics. Single-source vulnerability concentrates in European combustion chamber machining. Distribution runs through shipyard direct procurement and fleet operator enterprise agreements, bypassing traditional ship manager intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual-fuel engine maturation and IMO Tier III regulatory fragmentation create a high-growth disruption window, with ammonia-ready platforms and hybrid-battery architectures forcing procurement decisions before fuel pathway clarity emerges.
For Market Incumbents: Fortify aftermarket capture through predictive maintenance platforms integrating genset telemetry with vessel energy management systems. Defend against charterer disintermediation by negotiating direct enterprise service agreements with Greek and Singapore-based fleet operators. Prioritize backward integration into combustion chamber machining to reduce single-source exposure. For New Entrants and Emerging Players: Digital twin convergence for predictive maintenance represents a service-layer gap where incumbents under-serve independent genset assemblers. Target Vietnam's shipbuilding expansion at Hyundai-Vinashin and Haiphong yards lacking indigenous suppliers. Penetrate through component localization partnerships rather than full-engine competition. Pursue modular genset swap configurations for China's Yangtze River fishing fleet retrofits as the most penetrable application tier. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-agnostic component suppliers with certification flexibility across diesel, methanol, and ammonia architectures. Long-term viability over the coming decade rests on fuel pathway optionality rather than single-fuel commitment. Acquisition targets should demonstrate Lloyd's Register or DNV co-development relationships. Watch methanol bunkering infrastructure buildout in Rotterdam and Singapore as the inflection signal for dual-fuel genset deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Platform Development | Captures premium contracts as IMO Tier III forces fuel flexibility across offshore support vessels. |
| Predictive Maintenance Integration | Locks in aftermarket revenue through genset telemetry convergence with vessel energy management systems. |
| Component Localization in Vietnam | Addresses supply gap at Hyundai-Vinashin and Haiphong yards lacking indigenous genset manufacturing. |
| Ammonia-Ready Certification Investment | Positions for regulatory preference shifts before Lloyd's Register and DNV type-approval queues clear. |
| Enterprise Service Agreement Consolidation | Bypasses ship manager intermediaries through direct relationships with Greek and Singapore fleet operators. |
Methodological Framework
The analysis maps diesel generator, hybrid generator, gas generator, and portable generator sub-sectors, each validated through interviews with offshore platform engineering managers, shipyard procurement directors, fleet technical superintendents, and classification society surveyors. Secondary validation draws from Lloyd's Register type-approval databases, DNV certification records, EPA marine engine filings, and China MEE emission compliance registries. Bottom-up vessel fleet segmentation triangulates against top-down OEM revenue attribution across power rating tiers.
Consistency checks against Lloyd's Register newbuild order data and DNV fleet statistics validate volume and value outputs across the projection horizon. The analytical framework models fuel type, power rating tier, application segment, and end-user category dimensions. CAGRs derive from segmented growth rate reconciliation with aggregate market expansion. Forecast inputs include offshore platform electrification gap timelines, methanol bunkering infrastructure development, and nickel price trajectory assumptions for stainless steel components.
Underlying assumptions cover IMO regulatory enforcement consistency, classification society approval timelines, and fuel pathway preference stability, with deviation risk concentrated in ammonia combustion technology maturation and nickel futures volatility. Revision becomes warranted when methanol or ammonia regulatory preference crosses adoption thresholds in major flag states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Kuwait Diesel Gensets Market
Generators
Construction Portable Generators Market
Generators
Power Generator Rental Market
Generators
Diesel Generator Market
Generators
Heat Recovery Steam Generator Sales Market
Generators
Tri Fuel Generators Market
Generators
China Gas Generator Market
Generators
Generator Rental Market
Generators
Global Portable Generator Market
Generators
North America Gasoline Gensets Market
Generators
Saudi Arabia Diesel Generator Market
Generators
North America Portable Generators Market
Generators
Asia Pacific Electric Generators Market
Generators
Residential Gas Generator Market
Generators
Mobile Generators Market
Generators
Middle East and Africa Gas Generator Market