
 Asia-Pacific Generator Sets Market | 2026-2036
Asia-Pacific Generator Sets Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Generator Sets Market Outlook
Multi-source procurement for engine blocks and alternators is shifting toward captive production among top-tier suppliers. Cummins Inc leverages its Indian manufacturing footprint to anchor regional supply for commercial standby units. Caterpillar Inc competes through its dealership density across Indonesian mining concessions. Mitsubishi Heavy Industries Ltd specializes in large-frame gas-fired systems for Japanese utility customers.
Generator sets are self-contained engine-alternator assemblies that convert mechanical energy into electrical power, typically rated from 5 kW to 50 kW for residential units and scaling to multiple megawatts for industrial applications; they serve as primary, standby, or emergency power sources where grid reliability is insufficient or absent. Diesel configurations retain the largest installed base across the Asia-Pacific due to fuel availability and torque density, though natural gas variants are gaining share in urban commercial settings where emissions restrictions apply. Portable installations dominate construction and event rental channels, while standby systems command premium positioning in hospital and data center applications.
India's BIS certifies engine emissions compliance under evolving CPCB norms, while Australia's state-level environmental authorities enforce noise and exhaust standards for mining-site deployments. Japan's METI directs efficiency benchmarks through its Top Runner program, affecting import eligibility for foreign manufacturers. Stakeholders must weigh fuel-type portfolio rebalancing against the capital intensity of certifying products under divergent national regimes.
Market Dynamics
Data center operators across Southeast Asia are expanding backup power fleets at unprecedented scale, creating a demand pull that is restructuring procurement priorities and supplier relationships across the region.
Growth Catalysts
- India's BIS emission norms:Tightening certification requirements for diesel engines are filtering out marginal suppliers and concentrating orders among certified manufacturers.
- Southeast Asian data center buildouts:Hyperscale cloud providers are mandating N+1 redundancy standards that require multiple megawatt-class standby installations per facility.
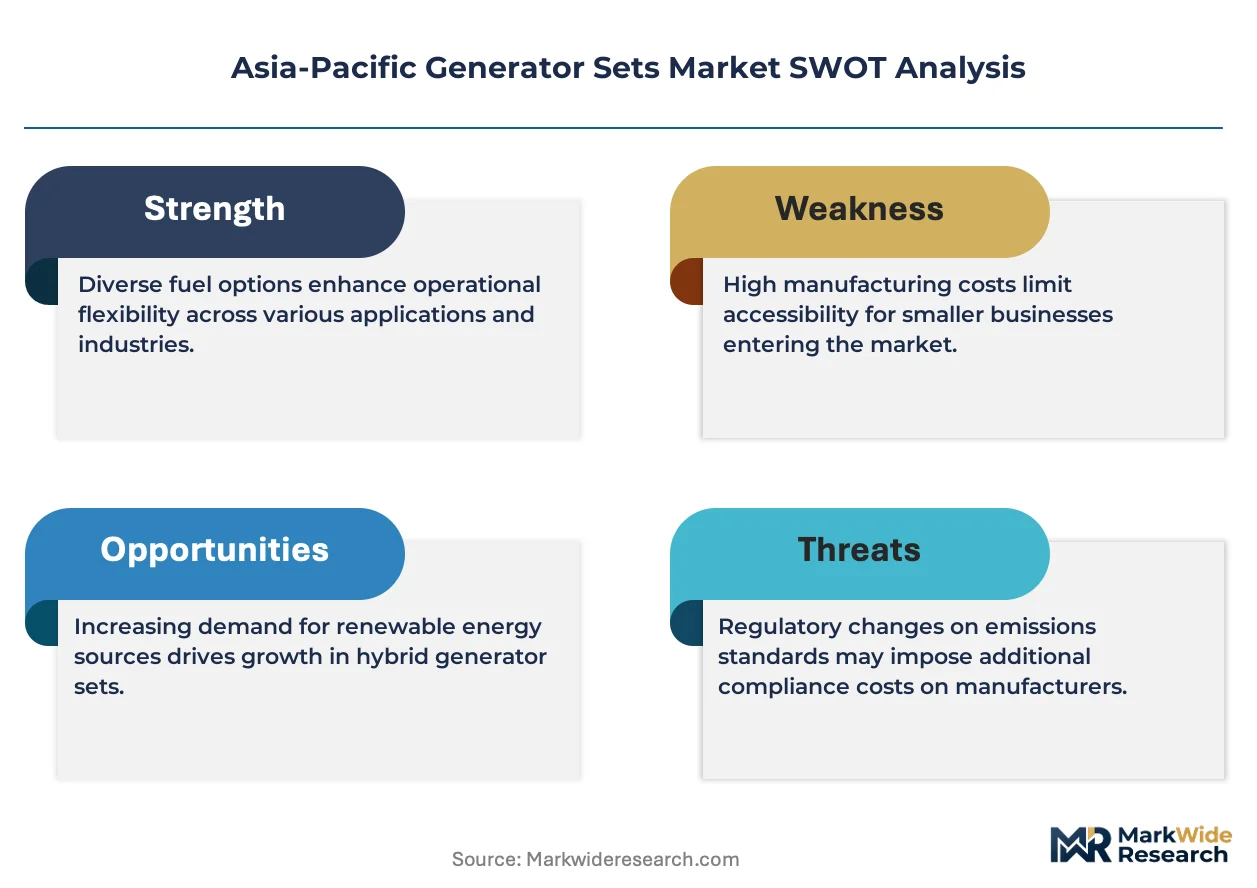
- Hybrid microgrids:Solar-diesel and solar-gas hybrid configurations are gaining traction in Australian mining corridors where fuel logistics costs dominate operating economics.
Market Restraints
- Engine block supply concentration:Foundry capacity for large-frame castings concentrates in China and India, creating vulnerability for Japanese and Australian assemblers during trade disruptions.
- Copper and silicon steel volatility:Alternator core materials face price swings that compress margin visibility on fixed-price construction contracts.
- Natural gas infrastructure gaps:Pipeline coverage limitations outside urban India and coastal China restrict gas-fired unit deployment despite emissions advantages.
Strategic Opportunities
- Indonesia's outer island mining:Remote gold and nickel operations lack grid connectivity and represent captive demand for containerized modular power plants.
- Japan's hydrogen roadmap:METI funding for hydrogen combustion turbines creates early-mover positioning for genset manufacturers developing dual-fuel capabilities.
- Rental fleet digitization:IoT-enabled remote monitoring platforms are opening subscription revenue streams alongside traditional equipment sales in Australian construction markets.
Industry Challenges
- Emissions calibration expertise:India's evolving CPCB norms require specialized test-cell capabilities that smaller regional distributors lack.
- Multi-country certification timelines:Parallel BIS, JIS, and Australian state-level approvals extend product launch cycles by 8-14 months.
- Legacy control system integration:Mining and utility customers demand compatibility with existing SCADA architectures that use proprietary protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Generator Sets Market |
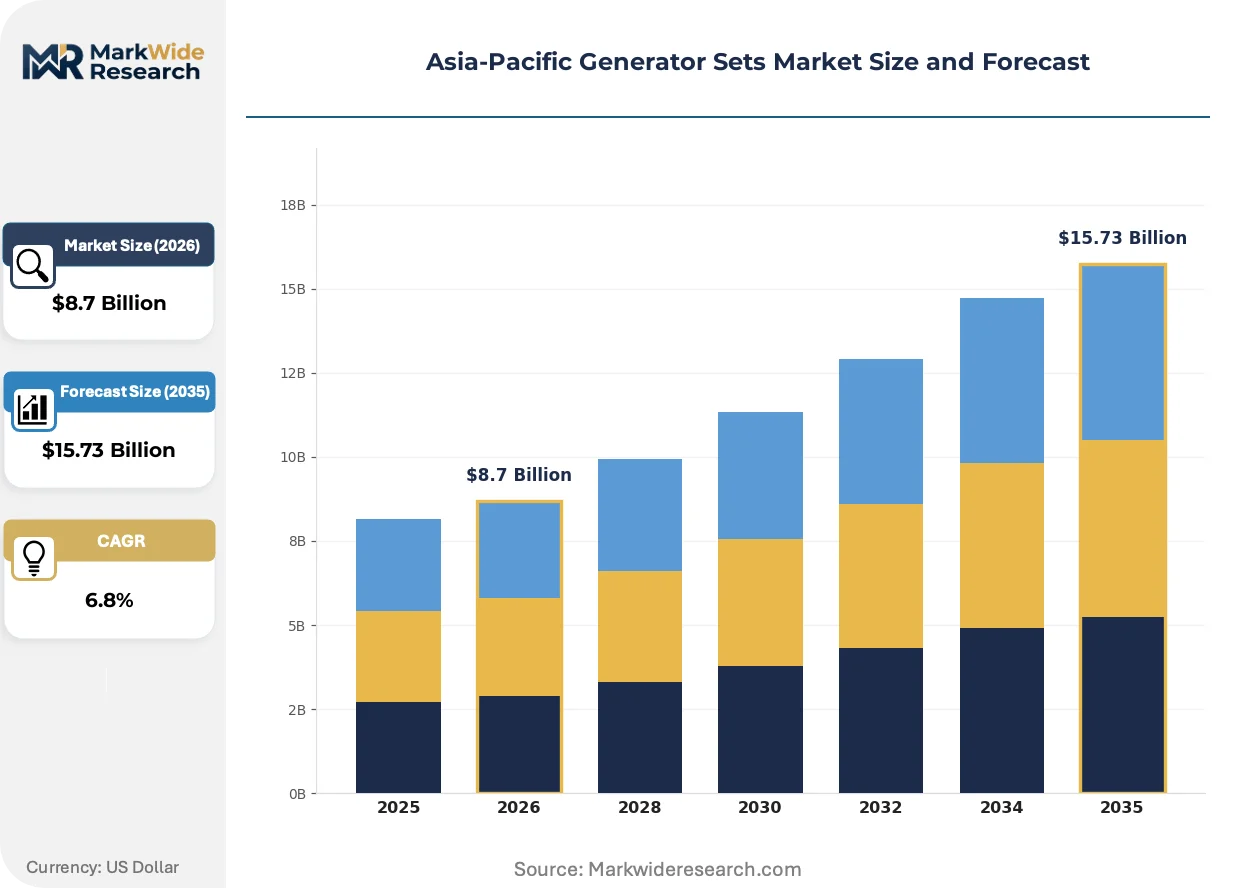
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Rating: 5 kW, 10 kW, 20 kW, 50 kW Fuel Type: Diesel, Natural Gas, Biogas, Propane End User: Residential, Industrial, Commercial, Agricultural Installation Type: Portable, Standby, Primary, Mobile |
| Companies Covered | Cummins Inc, Caterpillar Inc, Mitsubishi Heavy Industries Ltd, Aggreko plc, Generac Power Systems, Kohler Co, Doosan Corporation, Weichai Power Co., Ltd., FG Wilson, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Generator Sets Market Strategic Shifts
Diesel-gas hybrid architectures and digital fleet management platforms are converging to redefine how power reliability is procured, shifting competitive advantage from hardware specifications toward lifecycle service integration.
Integrated power control systems are consolidating generator, battery, and renewable inputs into unified dispatch platforms. Data center operators in Singapore and Sydney are specifying these systems as standard procurement requirements. This consolidation is compressing the addressable market for standalone synchronous controllers and favoring suppliers with software development capabilities.
Japan's METI Top Runner program is tightening efficiency benchmarks for imported power generation equipment. Foreign manufacturers must now demonstrate fuel consumption performance exceeding domestic incumbent levels to maintain market access. Large-frame gas turbine suppliers serving Japanese utility customers are responding by localizing final assembly to secure regulatory preference.
Equipment-as-a-service contracts are displacing outright purchase models in Australian mining and Indonesian plantation sectors. Rental providers are bundling maintenance, fuel logistics, and remote monitoring into per-kWh pricing structures. This shift is most visible in Western Australia's iron ore belts where operators prioritize balance sheet flexibility over asset ownership.
Asia-Pacific Generator Sets Market Segmentation
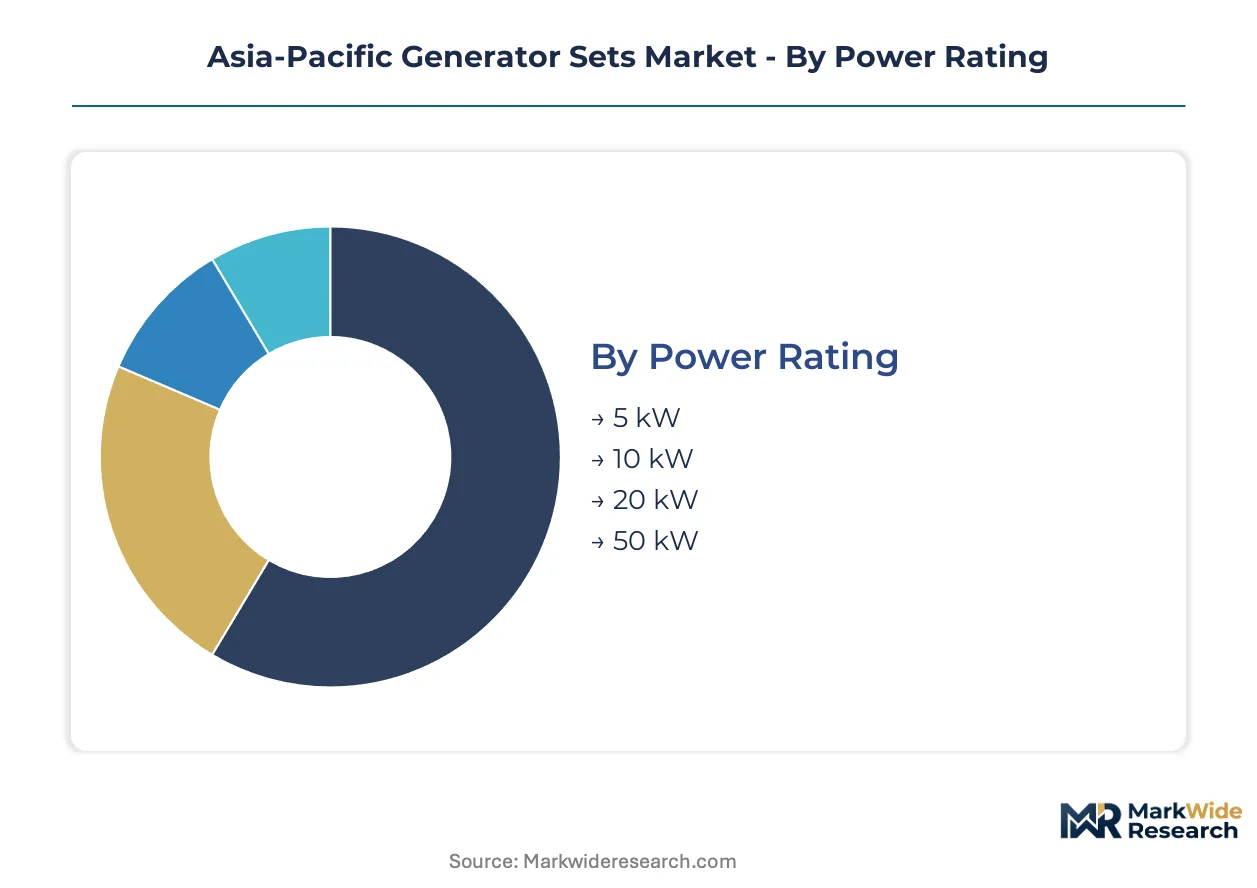
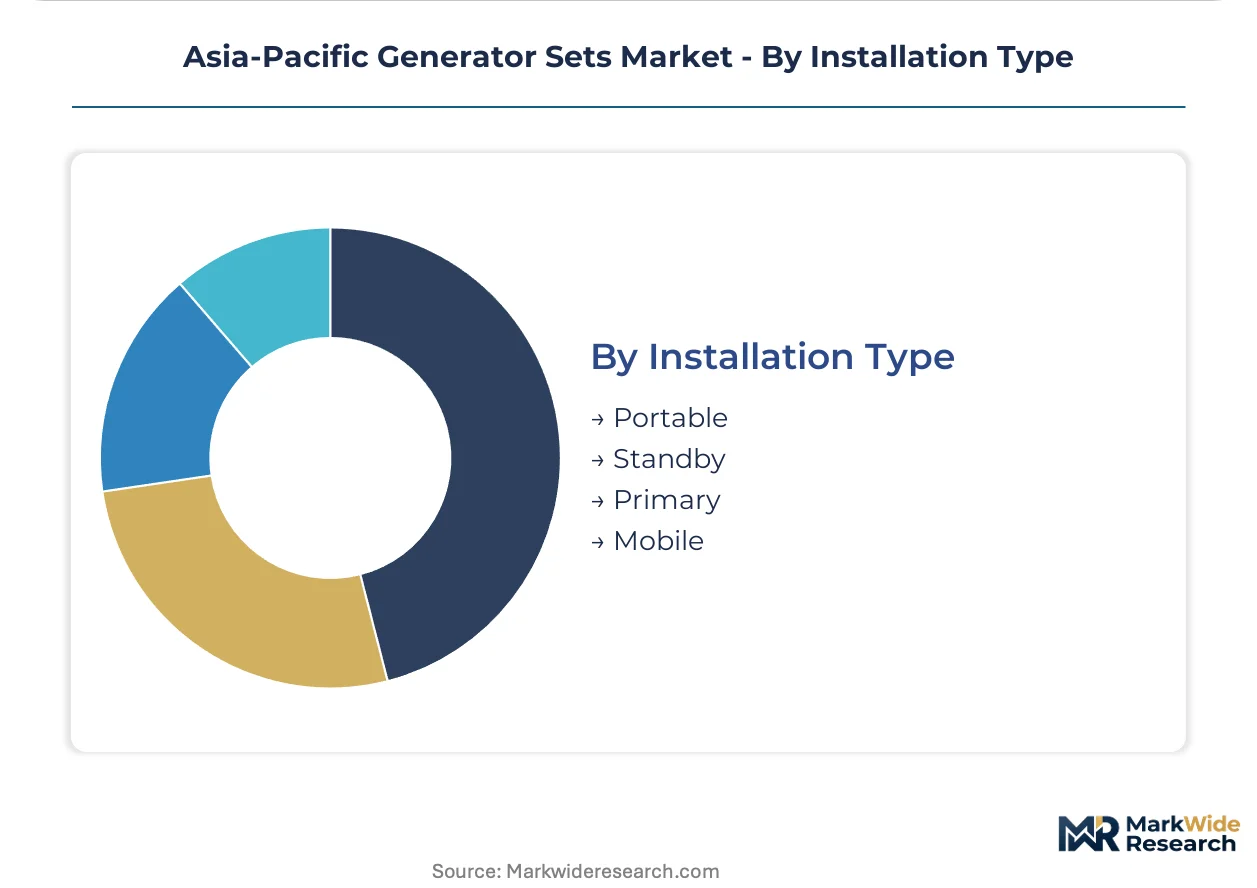
Generator set procurement in the Asia-Pacific follows distinct technical and economic logics. Buyers segment by power rating for load matching, fuel type for regulatory compliance, end-use for duty cycle requirements, and installation type for mobility needs.
Power Rating:
Capital intensity and operating hours drive buyer selection across kW tiers.
- 50 kW:Three-phase output configurations serve small commercial facilities and rural healthcare clinics across India's manufacturing corridors. Hospital administrators in Maharashtra and Tamil Nadu specify this tier for surgical suite backup where grid reliability fluctuates seasonally.
- 20 kW:Single-phase residential units dominate Australian remote homestead markets and Indonesian island resorts. Queensland property developers bundle these into off-grid housing packages where connection fees exceed generator lifecycle costs.
- 10 kW:Compact footprints suit mobile food vendors and construction site offices throughout Southeast Asian urban cores.
- 5 kW:Entry-level residential standby dominates Philippine suburban markets where scheduled brownouts persist.
50 kW leads on scale; 5 kW leads on volume penetration.
Fuel Type:
Emissions regulations and infrastructure availability partition procurement across combustion chemistries.
- Diesel:Compression-ignition architectures deliver torque density for mining haulage and data center load acceptance across Australia's Pilbara and Singapore's Tuas corridor. BIS certification requirements under evolving CPCB norms are consolidating supplier bases around manufacturers with in-house test cell capabilities.
- Natural Gas:Spark-ignited lean-burn systems command premium positioning in Japanese commercial districts and Seoul's Gangnam business district where urban emissions limits apply. METI efficiency benchmarks under the Top Runner program favor imported units demonstrating fuel consumption below domestic incumbent levels.
- Biogas:Agricultural digesters in Vietnam's Mekong Delta and Thailand's palm oil belts supply captive fuel for plantation processing operations.
- Propane:LPG portability suits Indonesian outer island fishing communities lacking diesel logistics infrastructure.
Diesel anchors current installed base; natural gas gains share fastest in urban commercial applications.
End User:
Duty cycle severity and redundancy requirements differentiate procurement specifications.
- Industrial:Continuous-duty ratings for Australian iron ore crushing circuits and Vietnamese steel rolling mills specify hardened crankcases and extended oil change intervals. Mining operators in Western Australia negotiate power purchase agreements with rental fleet providers to preserve balance sheet flexibility.
- Commercial:N+1 redundancy mandates from hyperscale cloud providers in Singapore and Sydney data centers require synchronized paralleling controls and sub-10-second load transfer capabilities.
- Residential:Automatic transfer switches dominate Australian bushfire-prone regions and Japanese earthquake zones where unattended operation is essential.
- Agricultural:Seasonal irrigation pumping across India's Punjab and Haryana drives demand for cost-optimized units with minimal electronic complexity.
Industrial commands highest unit margins; commercial shows steepest expansion trajectory.
Installation Type:
Mobility requirements and permanence expectations shape enclosure and fuel system engineering.
- Standby:Weatherproof enclosures with integrated fuel tanks serve hospital and financial institution applications across Tokyo, Hong Kong, and Mumbai where regulatory mandates require emergency power availability.
- Primary:Extended-run fuel systems with bulk storage characterize Indonesian nickel mining camps and Papua New Guinea highlands communities beyond grid extension timelines.
- Portable:Skid-mounted units with forklift pockets dominate Australian construction rental fleets and Southeast Asian event infrastructure.
- Mobile:Trailer-mounted configurations serve disaster response agencies in the Philippines and flood-prone regions of Bangladesh requiring rapid deployment capabilities.
Standby generates premium pricing; portable delivers highest fleet turnover velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's Pilbara mining corridor anchors regional demand for continuous-duty generator sets, with iron ore operators negotiating power purchase agreements to preserve capital flexibility. India's manufacturing corridors and Japan's utility modernization programs reshape procurement specifications across distinct regulatory environments.
India
Maharashtra and Tamil Nadu hospital administrators specify 50 kW surgical suite backup units where grid reliability fluctuates seasonally. The Bureau of Indian Standards certifies engine emissions compliance under evolving Central Pollution Control Board norms, filtering marginal suppliers from certified manufacturer pools. Gujarat's industrial estates concentrate diesel generator procurement for pharmaceutical and chemical processing operations requiring uninterrupted power.
Japan
Tokyo data centers and Osaka commercial districts mandate natural gas spark-ignited systems where urban emissions limits apply. The Ministry of Economy, Trade and Industry directs efficiency benchmarks through its Top Runner program, requiring foreign manufacturers to demonstrate fuel consumption below domestic incumbent levels. Kanto region utilities prioritize large-frame gas turbine installations for grid stabilization services.
Australia
Western Australia's iron ore crushing circuits specify hardened crankcases with extended oil change intervals for continuous-duty ratings. State-level environmental authorities enforce noise and exhaust standards for Pilbara mining-site deployments. Queensland property developers bundle 20 kW single-phase units into off-grid housing packages where grid connection fees exceed generator lifecycle costs.
Indonesia
Remote gold and nickel operations across outer islands lack grid connectivity and represent captive demand for containerized modular power plants. Provincial regulators coordinate with national energy planners on rural electrification timelines. Kalimantan mining concessions and Sumatra plantation belts drive procurement of extended-run fuel systems with bulk storage capabilities.
Singapore
Tuas corridor data centers require synchronized paralleling controls and sub-10-second load transfer capabilities under N+1 redundancy mandates. National infrastructure agencies enforce strict emissions standards for backup power installations in dense urban environments. Hyperscale cloud providers specify integrated power control systems consolidating generator, battery, and renewable inputs as standard procurement requirements.
Asia-Pacific Generator Sets Market Competitive Environment
Global majors compete with regional champions across certification capabilities and service network density. The supplier base concentrates around manufacturers with in-house emissions test cell facilities and multi-country approval portfolios. Three archetypes dominate: integrated engine-alternator assemblers with captive foundry capacity, rental fleet operators bundling maintenance into per-kWh contracts, and component specialists supplying alternator cores to third-party integrators. Competitive moves center on localizing final assembly to secure regulatory preference and digitizing rental fleets with IoT-enabled remote monitoring platforms.
Among Asia-Pacific-based fabricators, Weichai Power Co., Ltd. and Doosan Corporation occupy positions within the integrated assembler tier, while Aggreko plc exemplifies the rental fleet operator archetype. These entities represent distinct strategic postures: the former anchor regional supply chains through manufacturing footprint depth, the latter shift competitive advantage toward lifecycle service integration through equipment-as-a-service contract structures. Each sits within a broader ecosystem where certification timelines and emissions calibration expertise filter market participation.
| Leading Market Players |
|---|
| Cummins Inc |
| Caterpillar Inc |
| Mitsubishi Heavy Industries Ltd |
| Aggreko plc |
| Generac Power Systems |
| Kohler Co |
| Doosan Corporation |
| Weichai Power Co., Ltd. |
| FG Wilson |
| Others |
Value Chain & Pricing Dynamics
Hyperscale data center operators in Singapore and Sydney concentrate procurement volumes for megawatt-class standby systems, anchoring contract-based long-term offtake structures that compress spot-market exposure for certified manufacturers. This buyer concentration amplifies pricing power asymmetry toward suppliers with BIS and METI approval portfolios, while marginal players face margin erosion on non-certified diesel units.
Pricing Analysis
Input-cost pass-through from copper and silicon steel volatility shapes alternator pricing, with foundry energy surcharges feeding directly into engine block quotations. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the 5-20 kW residential segment intensifies because of import competition from Chinese fabricators. Small commercial buyers in Philippine suburban markets exhibit highest price sensitivity; data center operators in the Tuas corridor show least sensitivity due to N+1 redundancy mandates.
Supply Chain Analysis
Single-source vulnerability sits with large-frame casting capacity concentrated in China and India, exposing Japanese and Australian assemblers to trade disruption risk. Engine block production draws from foundries in Shandong and Maharashtra, while alternator core laminations hinge on silicon steel mills in South Korea and Japan. Tariff exposure on Chinese-origin castings represents the dominant structural risk. Distribution runs through authorized dealership networks for mining and utility customers, with rental fleet operators bypassing traditional channels in Australian construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific generator sets market functions as a stable compounder, with data center power reliability mandates providing non-cyclical demand underpinning. Infrastructure digitization and emissions compliance create durable barriers that sustain incumbent returns.
For Market Incumbents: Lock in captive foundry capacity through backward integration into Indian and Chinese casting facilities, insulating against trade disruption risk. Deepen emissions calibration expertise to maintain BIS certification advantage as CPCB norms tighten, filtering regional distributors lacking test-cell capabilities. For New Entrants and Emerging Players: Rental fleet operators represent the most accessible channel partner type for equipment-as-a-service positioning, bypassing capital-intensive manufacturing entry barriers. Target Indonesian outer island mining camps and Philippine disaster response agencies with containerized modular power plants, leveraging local fuel logistics partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Integrated engine-alternator assemblers with captive emissions test cell facilities are the most active acquirer in this space, consolidating regional certification capabilities. The 5-10 year viability window favors manufacturers with dual-fuel development pipelines aligned to Japan's hydrogen roadmap. Watch METI funding disbursement velocity for hydrogen combustion turbines as the inflection indicator for technology transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Emissions Test Cell Investment | BIS certification under evolving CPCB norms filters marginal competitors from Indian manufacturing corridors. |
| Dual-Fuel Capability Development | METI hydrogen roadmap funding creates early-mover positioning for Japanese utility customer segments. |
| Rental Fleet Digitization | IoT-enabled remote monitoring platforms unlock subscription revenue streams in Australian iron ore belts. |
| Foundry Capacity Backward Integration | Captive engine block production insulates against supply disruption in China and India concentration zones. |
| Integrated Power Control Systems | Software consolidation of generator, battery, and renewable inputs meets Singapore data center procurement standards. |
Study Parameters
Direct dialogue with data center infrastructure directors, mining procurement officers, rental fleet operations managers, and power systems engineers grounded qualitative insights, cross-validated against customs trade databases, BIS certification registries, METI efficiency benchmarking disclosures, and hyperscaler capex filings. Bottom-up and top-down triangulation reconciled unit shipment estimates with aggregate regional demand indicators.
Bottom-up modeling aggregated segment-level volume and value outputs across power rating tiers, fuel type categories, end-use verticals, and installation configurations over the projection horizon. CAGRs were derived from fitted growth curves applied to base-year estimates, with industry-specific inputs including data center N+1 redundancy buildout schedules, Australian mining power purchase agreement volumes, and Indian BIS certification timeline data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hydrogen infrastructure deployment rates and trade policy shifts affecting Chinese foundry access. Forecasts reflect documented assumptions regarding emissions regulatory trajectory and data center construction pipelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Military Generator Market
Generators
South America and Africa Diesel Generator Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
North America Gasoline Gensets Market
Generators
Asia-Pacific Gas Generator Market
Generators
Generator Sales Market
Generators
Containerized Solar Generators Market
Generators
China Generator Sets Market
Generators
North West Europe Diesel Generator Market
Generators
US Generator Sales Market
Generators
Onboard Marine Gensets Market
Generators
Tri Fuel Generators Market
Generators
Asia Pacific Electric Generators Market
Generators
Marine Gensets Market
Generators
Digital Inverter Generator Market
Generators
Telecom Generator Market