
 Gas Generator Market | 2026-2036
Gas Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Generator Market Analysis
Chinese engine block foundries and Korean component suppliers is consolidating around a tighter supplier base for gas generator castings and ignition systems. Caterpillar Inc. leverages its integrated dealer network to control aftermarket service revenue across North American industrial sites. Cummins Inc. sustains engineering intensity in reciprocating engine platforms for standby power applications. Mitsubishi Heavy Industries, Ltd. anchors turbine generator supply for utility-scale combined cycle installations in Southeast Asia.
A gas generator converts chemical energy from gaseous fuels into electrical power through internal combustion or turbine-driven alternator systems, typically operating at 50 Hz or 60 Hz with output ratings from 5 kW residential units to 500 MW industrial blocks. The primary purpose is to provide reliable on-site electricity for backup, prime, or peaking duty where grid stability is insufficient or absent. Industrial generators occupy the largest revenue pool due to continuous-duty requirements at manufacturing plants and data centers. Natural gas configurations are displacing diesel in urban standby applications where local air quality regulations restrict particulate emissions. Reciprocating engine technology leads unit shipments while turbine engines capture the highest average selling prices in utility deployments.
The EPA enforces Tier 4 final emission limits on stationary gas engines above certain horsepower thresholds, compelling manufacturers to invest in selective catalytic reduction and oxidation catalyst systems. The EU F-Gas Regulation restricts fluorinated greenhouse gases used in generator cooling circuits, altering product design for equipment sold into Europe. ISO 8528 defines power rating classifications and performance testing protocols that govern international procurement specifications. Stakeholders must monitor evolving carbon intensity benchmarks for backup power as corporate sustainability targets begin to override first-cost purchasing criteria in commercial and industrial segments.
Market Dynamics
Hyperscaler data center construction in the United States is concentrating gas generator demand into megawatt-scale standby fleets, compressing procurement timelines and tightening supplier qualification standards for continuous-duty reciprocating engines.
Growth Catalysts
- EPA Tier 4 Final compliance:Stationary engine emission limits are forcing manufacturing plant upgrades across Texas and Virginia, creating replacement demand for certified natural gas units.
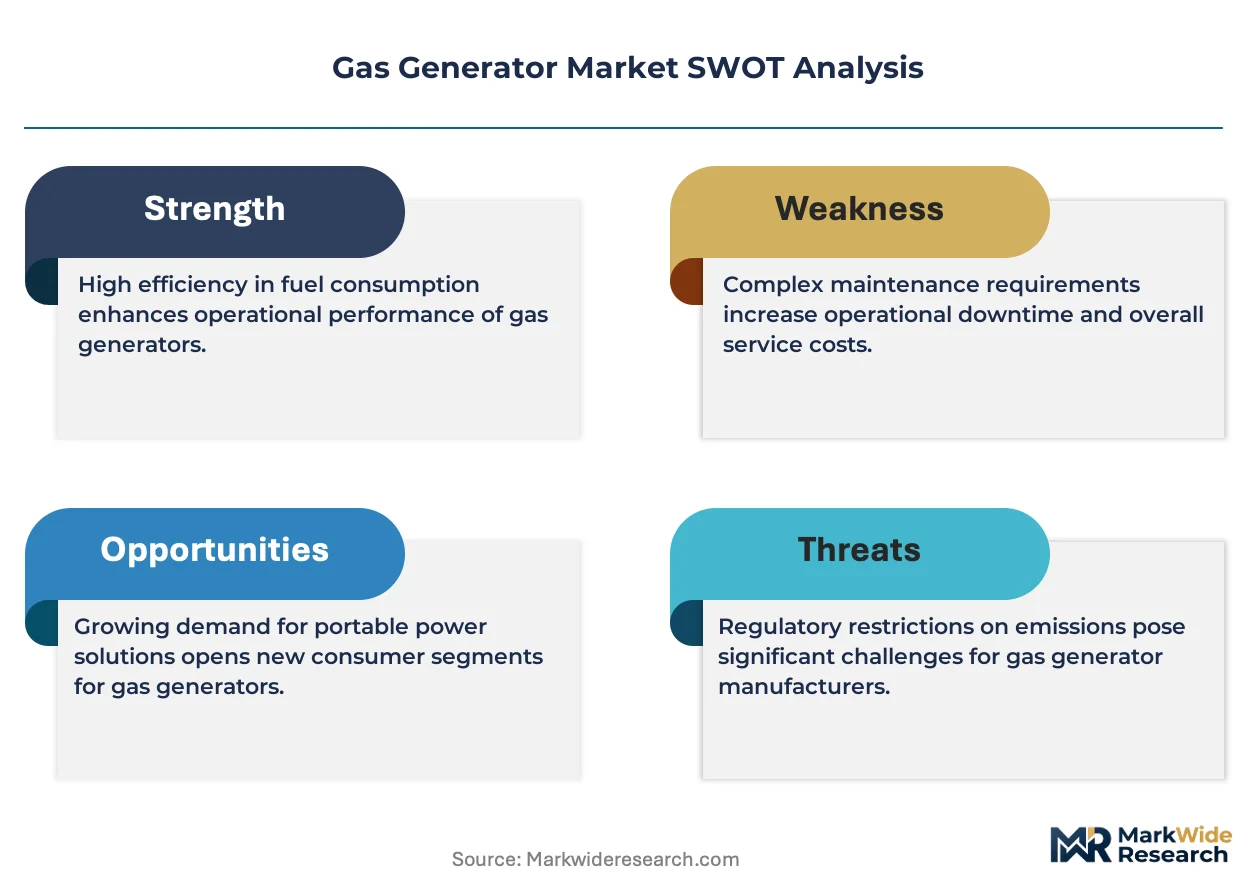
- AI compute load expansion:Data center operators in Arizona are sizing backup power for 100+ megawatt facilities, requiring turbine and reciprocating engine blocks in parallel configurations.
- Natural gas infrastructure density:Pipeline networks in the Permian Basin and Appalachian shale regions are enabling fuel-switching from diesel to gas for urban standby applications.
Market Restraints
- Casting supply concentration:Chinese foundries control the majority of large engine block production, exposing North American OEMs to shipping cost volatility and tariff exposure.
- Platinum group metal cost inflation:Selective catalytic reduction systems require palladium and rhodium catalyst substrates, with prices fluctuating on South African mining output.
- Grid interconnection queues:Utility-scale gas turbine projects face multi-year delays in ERCOT and PJM territories, deferring revenue recognition for equipment suppliers.
Strategic Opportunities
- Hydrogen-ready engine platforms:Blending capability up to 25% H2 by volume is attracting European utility tenders under the EU Green Deal hydrogen bank financing mechanisms.
- Microgrid controller integration:Synchronization software for gas generators with battery energy storage systems is opening campus-scale deployments at university and hospital districts.
- Aftermarket service unbundling:Remote monitoring subscriptions and predictive maintenance contracts are creating recurring revenue streams independent of new unit sales.
Industry Challenges
- Combustion engineer scarcity:The retirement wave of turbine specialists from 1980s-era combined cycle buildouts is outpacing university pipeline output for thermal power plant design.
- ISO 8528 power rating disputes:Continuous versus prime rating classifications create warranty claim conflicts between manufacturers and data center operators operating at 85%+ load factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Generator Market |
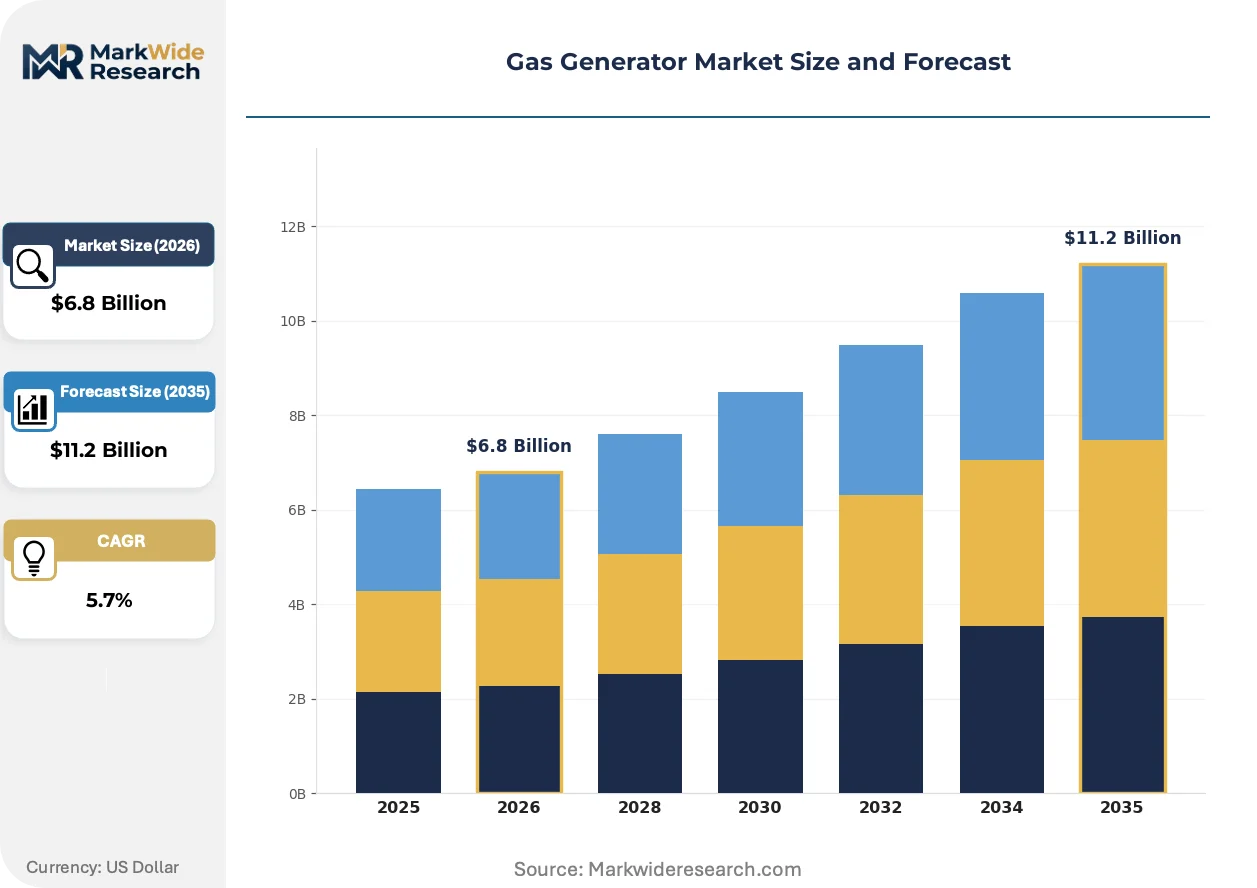
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Industrial Generators, Standby Generators, Inverter Generators Fuel Type: Natural Gas, Propane, Biogas, Diesel End User: Residential, Commercial, Industrial, Agricultural Technology: Reciprocating Engine, Turbine Engine, Fuel Cell, Hybrid Systems |
| Companies Covered | Caterpillar Inc., Cummins Inc., Generac Power Systems, Inc., Kohler Co. Inc., MTU Onsite Energy, Cooper Corporation, Mitsubishi Heavy Industries, Ltd., General Electric Company, Briggs & Stratton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Generator Market Emerging Trajectories
Gas generator architecture is fragmenting into scalable, containerized configurations that match hyperscaler procurement patterns for phased data center buildouts, while emission control systems absorb increasing engineering bandwidth.
Containerized reciprocating engine packages are modularizing from 2.5 megawatt building blocks into 50+ megawatt arrays. Data center developers in Northern Virginia are specifying these configurations for 18-month deployment cycles rather than 36-month traditional installations. This approach is modularizing the competitive landscape away from custom-engineered turbine halls toward standardized, repeatable power islands.
EPA enforcement of stationary source air permits is tightening opacity and NOx monitoring requirements for gas engines above 500 horsepower. Engine manufacturers are integrating continuous emissions monitoring systems into standard control packages rather than aftermarket add-ons. The industrial standby segment is absorbing these compliance costs through extended service contracts that bundle regulatory reporting.
Power purchase agreement structures are displacing direct equipment ownership at manufacturing facilities. Energy-as-a-service providers are installing and operating gas generators under 10-15 year contracts, transferring operational risk from plant engineers to third-party asset managers. This model is concentrating in Texas and Ohio where industrial electricity rates exhibit the highest volatility.
Gas Generator Market Segmentation
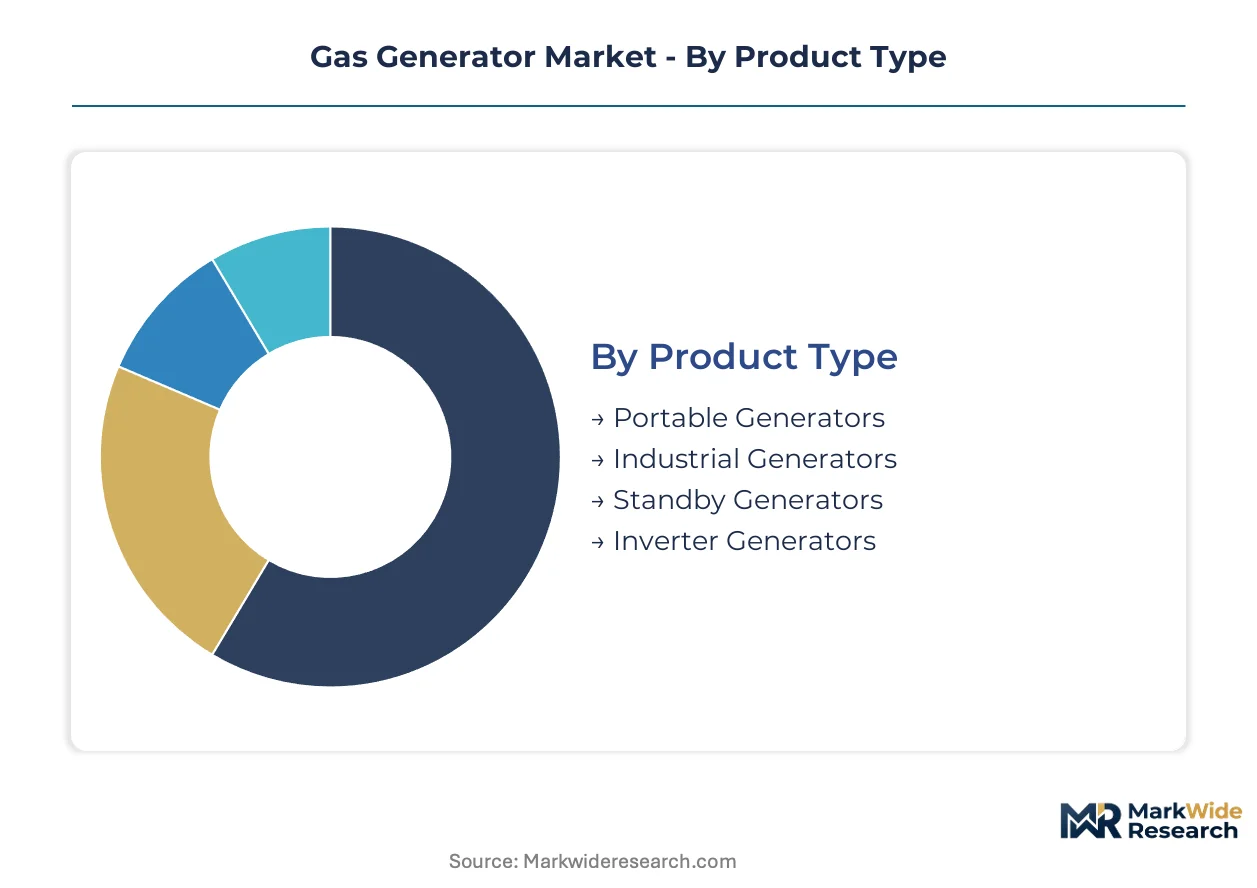
Gas generator procurement patterns diverge sharply between volume-driven residential replacement cycles and premium industrial installations where EPA Tier 4 Final compliance dictates specification. Understanding these segment boundaries reveals where margin pools concentrate versus where unit shipments dominate revenue.
Product Type:
Industrial generators command premium pricing through continuous-duty engineering, while portable units drive volume through hurricane-season replacement demand.
- Industrial Generators:Engineered for 24/7 operation with integrated heat recovery and SCR emission controls. Demand concentrates in Texas and Virginia data center corridors where 100+ megawatt facilities require parallel reciprocating engine arrays. Caterpillar and Cummins dominate specification through embedded dealer service contracts.
- Standby Generators:Automatic transfer switch integration enables sub-10-second grid failure response for hospitals and financial clearing operations. Arizona hyperscalers are sizing these units for 18-month deployment cycles rather than traditional 36-month installations.
- Portable Generators:Mobile power for construction sites and emergency response fleets.
- Inverter Generators:Variable-speed engines for sensitive electronics and recreational vehicle power.
Today's leader: Industrial Generators. Tomorrow's challenger: Standby Generators.
Fuel Type:
Natural gas infrastructure density determines regional fuel switching economics, with pipeline proximity enabling diesel displacement in urban standby applications.
- Natural Gas:Pipeline-connected installations dominate EPA Tier 4 Final compliance pathways through lean-burn combustion and oxidation catalyst systems. The Permian Basin and Appalachian shale regions are enabling fuel-switching from diesel for manufacturing plant upgrades.
- Biogas:Landfill and anaerobic digester methane capture creates carbon-negative power credentials for corporate sustainability targets. Agricultural operations in California's Central Valley are deploying these systems under state LCFS credit mechanisms.
- Propane:Rural standby applications beyond natural gas pipeline networks.
- Diesel:Restricted to remote mining and military applications where fuel logistics override emission regulations.
Natural Gas retains installed base dominance. Biogas climbs fastest on carbon accounting incentives.
End User:
Industrial procurement absorbs engineering-intensive configurations, while commercial segments prioritize first-cost minimization and rapid deployment.
- Industrial:Continuous-duty requirements at semiconductor fabs and chemical processing plants demand ISO 8528 prime rating certification. Energy-as-a-service providers in Texas and Ohio are assuming operational risk through 10-15 year power purchase agreements.
- Commercial:Retail and office installations prioritize compact footprint and noise attenuation over thermal efficiency. Northern Virginia data center developers are specifying containerized configurations for phased buildout scalability.
- Residential:Post-hurricane replacement cycles in Florida and Gulf Coast states.
- Agricultural:Irrigation pump power and on-farm processing operations.
Industrial segment anchors revenue. Commercial applications expand most quickly on modular deployment trends.
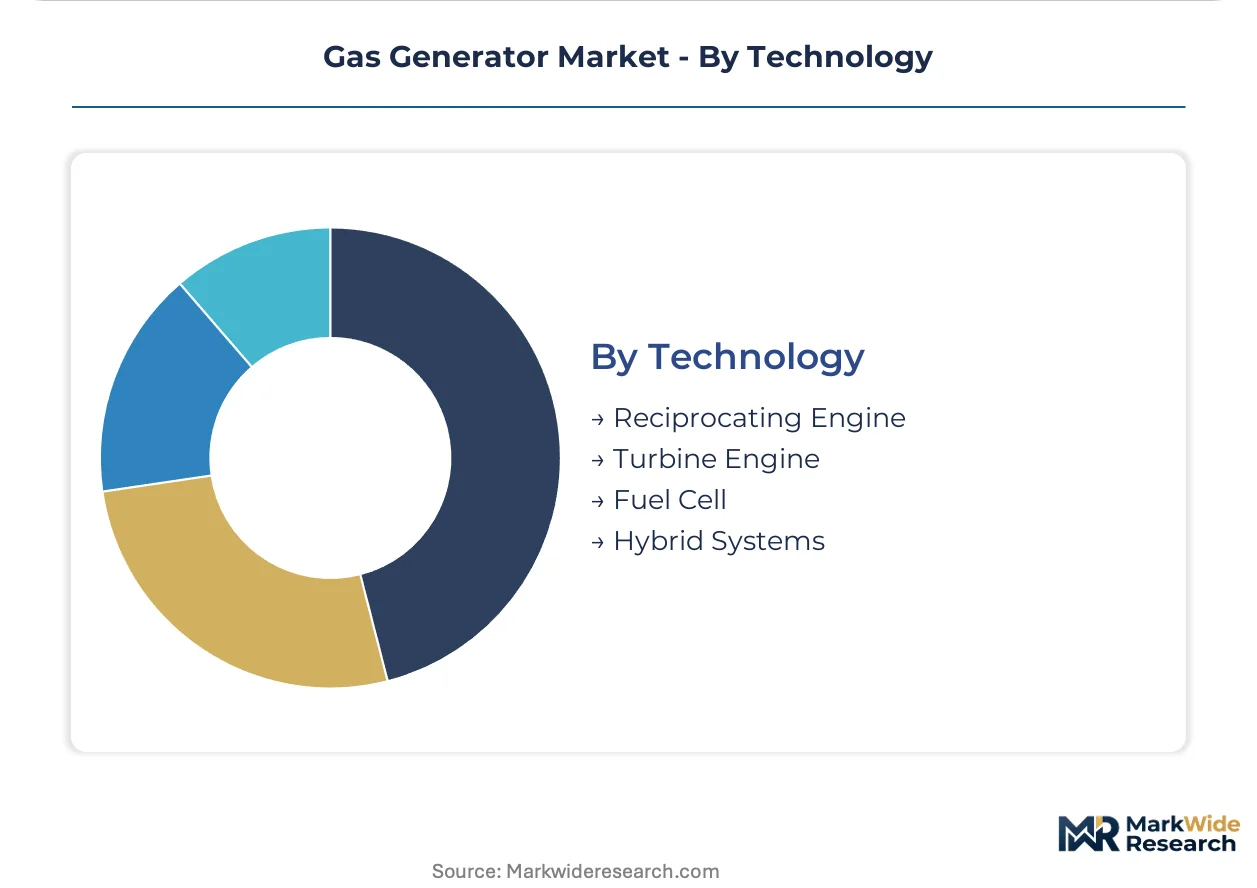
Technology:
Reciprocating engines capture unit volume through manufacturing scale, while turbine systems retain utility-scale combined cycle premium positioning.
- Reciprocating Engine:Modular cylinder architecture enables 2.5 megawatt building blocks to scale into 50+ megawatt arrays. Mitsubishi Heavy Industries anchors turbine generator supply for utility-scale installations in Southeast Asia.
- Turbine Engine:Brayton cycle efficiency above 40% LHV drives utility peaking and combined heat-and-power applications. Grid interconnection queues in ERCOT and PJM territories are deferring revenue recognition for equipment suppliers.
- Fuel Cell:Solid oxide systems for premium microgrid applications requiring silent operation.
- Hybrid Systems:Battery-gas synchronization for campus-scale resilience at university and hospital districts.
Reciprocating Engine dominates shipments. Hybrid Systems gain share fastest on storage integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial gas generator fleet emphasizes efficiency retrofits, while China's manufacturing scale drives cost compression across Asia-Pacific export markets.
United States
Hyperscaler data center construction in Texas and Virginia concentrates demand for megawatt-scale standby reciprocating engine arrays. The EPA enforces Tier 4 Final emission limits on stationary engines above 500 horsepower, compelling selective catalytic reduction integration. Northern Virginia's Ashburn-Dulles corridor hosts 100+ megawatt facilities requiring 18-month deployment cycles for containerized generator packages.
Germany
Industrial combined heat-and-power installations anchor turbine generator demand amid energy security restructuring. The EU F-Gas Regulation restricts fluorinated greenhouse gases in cooling circuits, altering product design for European-bound equipment. Bavaria's chemical processing corridor sustains continuous-duty prime rating procurement for manufacturing plant resilience.
China
Domestic engine block foundries supply casting capacity for global OEM assembly operations. The Ministry of Ecology and Environment enforces dual carbon goals tightening industrial emission benchmarks. Shandong Province's manufacturing clusters integrate gas generators into captive power systems for grid-independent operations.
Japan
Utility-scale combined cycle projects sustain premium turbine generator procurement despite grid interconnection constraints. METI's hydrogen roadmap incentivizes 25% H2 blending capability in new engine tenders. The Chubu-Nagoya industrial zone deploys microgrid-synchronized gas generators for semiconductor fab resilience.
India
Manufacturing plant expansion drives standby power investment amid unreliable grid supply in industrial corridors. The Central Electricity Authority mandates emission norms for captive power plants above specified capacity thresholds. Gujarat's petrochemical clusters and Maharashtra's automotive belt concentrate natural gas generator deployment for prime duty applications.
Gas Generator Market Vendor Landscape
North American producers anchor one tier; Asian fabricators hold cost-optimized supply positions. The vendor base stratifies across three tiers: integrated engine-alternator manufacturers, component specialists, and regional assembly operations. Two strategic archetypes dominate: full-lifecycle service providers capturing aftermarket revenue, and modular platform specialists enabling rapid deployment. Competitive moves concentrate on hydrogen-ready engine certification and microgrid controller integration partnerships.
Within the integrated manufacturer tier, Caterpillar Inc. and Cummins Inc. exemplify North American engineering intensity in reciprocating platforms, while Mitsubishi Heavy Industries, Ltd. anchors turbine generator positioning for utility-scale Southeast Asian installations. These entities represent contrasting geographic specializations and technology emphases rather than direct segment overlap.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| Generac Power Systems, Inc. |
| Kohler Co. Inc. |
| MTU Onsite Energy |
| Cooper Corporation |
| Mitsubishi Heavy Industries, Ltd. |
| General Electric Company |
| Briggs & Stratton |
| Others |
Supply Flow & Price Mechanics
EPA Tier 4 Final certification tiers bifurcate the gas generator market into premium-compliant and non-compliant equipment strata, with certified natural gas units commanding substantial dealer margins while uncertified diesel alternatives compete on first-cost metrics. This divergence concentrates pricing power among integrated manufacturers with captive selective catalytic reduction supply chains, while commodity engine assemblers face margin compression from platinum group metal cost volatility and Chinese casting import tariffs.
Pricing Analysis
Distributor margins absorb 18-25 points on industrial reciprocating engine sales, with Caterpillar's embedded dealer network extracting premium service bundling that independent distributors cannot match. Three-tier pricing structure across prime-rated continuous duty, standby emergency, and portable rental applications separates ISO 8528 certification grades, with data center operators in Northern Virginia exhibiting lowest price sensitivity due to 18-month deployment deadlines. Pricing pressure stems from palladium and rhodium catalyst substrate inflation, forcing OEMs to push cost recovery through extended maintenance contracts rather than equipment markups.
Supply Chain Analysis
Regional distribution centers in Houston, Chicago, and Atlanta maintain 30-60 day inventory buffers for containerized generator packages, feeding hub-and-spoke patterns into data center construction corridors. Engine block casting concentrates in Chinese foundries and Korean component suppliers, with ignition system assembly anchored in German and Japanese precision manufacturing. Raw material dependencies span nodular iron for cylinder heads, copper windings for alternators, and ceramic substrates for oxidation catalysts. Single-source vulnerability in South African platinum group metal mining exposes catalyst suppliers to supply disruption. Distribution runs through OEM-captive dealer networks for industrial accounts and electrical wholesalers for commercial standby installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gas generator market has entered a late-cycle quality phase where EPA Tier 4 Final compliance and hydrogen-ready certification now override first-cost purchasing criteria among data center and industrial buyers. Premium specification demand is concentrating procurement power with full-lifecycle service providers capable of bundling regulatory reporting and predictive maintenance.
For Market Incumbents:Hedge platinum group metal exposure through long-term catalyst supply agreements with South African refiners while securing backward integration into Chinese foundry partnerships via minority equity stakes or offtake guarantees. Defend dealer network density against energy-as-a-service entrants by unbundling remote monitoring subscriptions from equipment sales, creating recurring revenue streams that match third-party asset manager offerings.
For New Entrants and Emerging Players:Launch via microgrid controller integration partnerships, targeting university and hospital districts in Texas and Ohio where campus-scale resilience requirements outstrip incumbent service capacity. White-space exists in biogas landfill methane capture systems for California Central Valley agricultural operations, where state LCFS credit mechanisms offset equipment premiums. Penetrate through energy-as-a-service contracting models that transfer operational risk from plant engineers, bypassing entrenched OEM dealer relationships.
For Investors and Strategic Acquirers:Consolidation pressure builds where hydrogen-ready engine certification gaps strand mid-tier assemblers without R&D scale to meet EU Green Deal hydrogen bank tender requirements. Long-term viability favors integrated manufacturers with captive aftermarket service revenue and utility-scale turbine generator positioning in Southeast Asian combined cycle buildouts. Acquisition targets include regional gas generator distributors with embedded data center relationships and combustion engineering specialists capable of 25% H2 blending platform development. Watch EPA enforcement intensity on stationary source air permits as the inflection signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Engine Certification | EU Green Deal hydrogen bank financing mechanisms now require 25% H2 blending capability in utility tenders. |
| Microgrid Controller Integration | Synchronization software for battery-gas hybrid systems opens campus-scale deployments at university districts. |
| Aftermarket Service Unbundling | Remote monitoring subscriptions create recurring revenue independent of new unit sales cycles. |
| Selective Catalytic Reduction Integration | EPA Tier 4 Final compliance forces bundled emission control systems rather than aftermarket add-ons. |
| Containerized Package Standardization | Modular 2.5 megawatt building blocks enable 18-month deployment cycles for hyperscaler data centers. |
Methodological Framework
Multiple input streams — primary interviews with data center construction directors, EPA compliance officers, and industrial plant engineers; secondary validation through EIA power generation databases, FERC interconnection queue filings, and OEM dealer network disclosures — were reconciled through bottom-up unit shipment modeling and top-down revenue triangulation. Stakeholder conversations spanned utility-scale project developers in ERCOT and PJM territories, captive power procurement leads at Texas semiconductor fabs, and aftermarket service heads at reciprocating engine distributors.
Data-stream reconciliation across product type, fuel configuration, end-use sector, and technology architecture enabled segmentation-specific growth trajectory modeling throughout the forecast period. CAGRs were derived from installed base replacement cycles, hyperscaler facility construction pipelines, and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporated EPA Tier 4 Final enforcement timelines, natural gas pipeline expansion maps in the Permian Basin and Appalachian shale regions, and platinum group metal price volatility indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tariff escalation on Chinese engine block castings or accelerated grid interconnection queue clearance in ERCOT territories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Digital Inverter Generator Market
Generators
South America Portable Generator Market
Generators
Europe Gas Turbine Market
Generators
Africa Diesel Generator Market
Generators
Asia-Pacific Gas Generator Market
Generators
Portable Inverter Generators Market
Generators
Portugal Gas Generator Market
Generators
Diesel Generator Market
Generators
Construction Prime Power Generators Market
Generators
Middle-East and Africa Generator Sets Market
Generators
Europe Diesel Generator Market
Generators
Hand Crank Power Generator Market
Generators
Construction Portable Generators Market
Generators
Asia Pacific Electric Generators Market
Generators
US Generator Sales Market
Generators
Saudi Arabia Diesel Generator Market