
 South America Portable Generator Market | 2026-2036
South America Portable Generator Market Size, Share, and Industry Trends Forecast 2026-2036
South America Portable Generator Market Analytics
The capital-intensity divergence between integrated engine manufacturers and assembly-focused competitors is redrawing competitive boundaries across the region. Caterpillar Inc. leverages captive engine production to sustain margin structures in heavy-duty diesel segments. Kohler Power Systems anchors its position through channel depth in Brazilian home improvement retail. Generac Holdings Inc. competes by specializing in residential standby configurations adapted to voltage fluctuation patterns common in Argentine and Brazilian grids.
A portable generator is a self-contained combustion or photovoltaic power unit with output ratings typically spanning 1 kW to 15 kW, designed for temporary deployment without fixed installation infrastructure; these units employ reciprocating engines, inverter electronics, or solar charge controllers to deliver alternating current for locations lacking grid connectivity or requiring redundancy. Diesel generators occupy the dominant revenue position in construction and industrial rental fleets due to fuel availability and runtime economics across remote Brazilian mining and agricultural zones. Solar generators represent the fastest-expanding product category, though from a narrow base, as lithium-ion battery cost curves improve payback periods for rural telecommunications and outdoor event applications where fuel logistics burden operational budgets.
ANEEL, Brazil's national electric energy regulator, shapes demand through distributed generation frameworks that incentivize backup power investments where grid reliability remains inconsistent. Argentina's Secretariat of Energy and PROCREL efficiency standards influence product certification requirements for import clearance at Buenos Aires port terminals. Stakeholders must monitor how PROINFA renewable integration targets and evolving Mercosur technical barriers to trade reshape equipment specification standards and cross-border supplier qualification protocols.
Market Dynamics
ANEEL's distributed generation framework is restructuring procurement patterns across Brazil's commercial and industrial segments, converting backup power from emergency contingency to integrated operational infrastructure.
Growth Catalysts
- ANEEL Net-Metering Regulations:Brazil's regulatory body permits grid-connected backup systems with energy credit mechanisms, accelerating commercial adoption of portable units as hybrid power assets.
- Construction Fleet Expansion:Contractors across São Paulo and Rio de Janeiro states are expanding equipment holdings to counter grid instability during peak demand periods.
- Lithium-Ion Cost Curves:Battery pack economics are compressing payback periods for solar generator configurations in rural telecommunications applications.
Market Restraints
- Import Tariff Volatility:Mercosur technical barriers create friction at Buenos Aires port terminals, inflating landed costs for Argentine distributors sourcing Brazilian-assembled units.
- Fuel Logistics Burden:Diesel supply chain gaps across remote Amazonian and Patagonian zones constrain runtime economics for conventional generator deployments.
- PROCREL Certification Timelines:Argentina's efficiency standards impose extended product clearance protocols that delay market entry for new equipment configurations.
Strategic Opportunities
- Argentine Agricultural Belt:Underpenetrated grain silo and irrigation pump segments present white space for solar-battery hybrid units with minimal fuel dependency.
- Outdoor Event Infrastructure:Festival and exhibition organizers in São Paulo are adopting silent-running inverter generators to comply with municipal noise ordinances.
- Telecommunications Tower Electrification:Rural 4G/5G backbone expansion is creating demand for photovoltaic generators with satellite monitoring integration.
Industry Challenges
- Service Network Density:Sparse authorized technician coverage across Brazil's northern states extends mean-time-to-repair for inverter electronics failures.
- Dual Certification Burden:Manufacturers must simultaneously satisfy ANEEL grid-interconnection protocols and PROCREL efficiency mandates to serve cross-border demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Portable Generator Market |
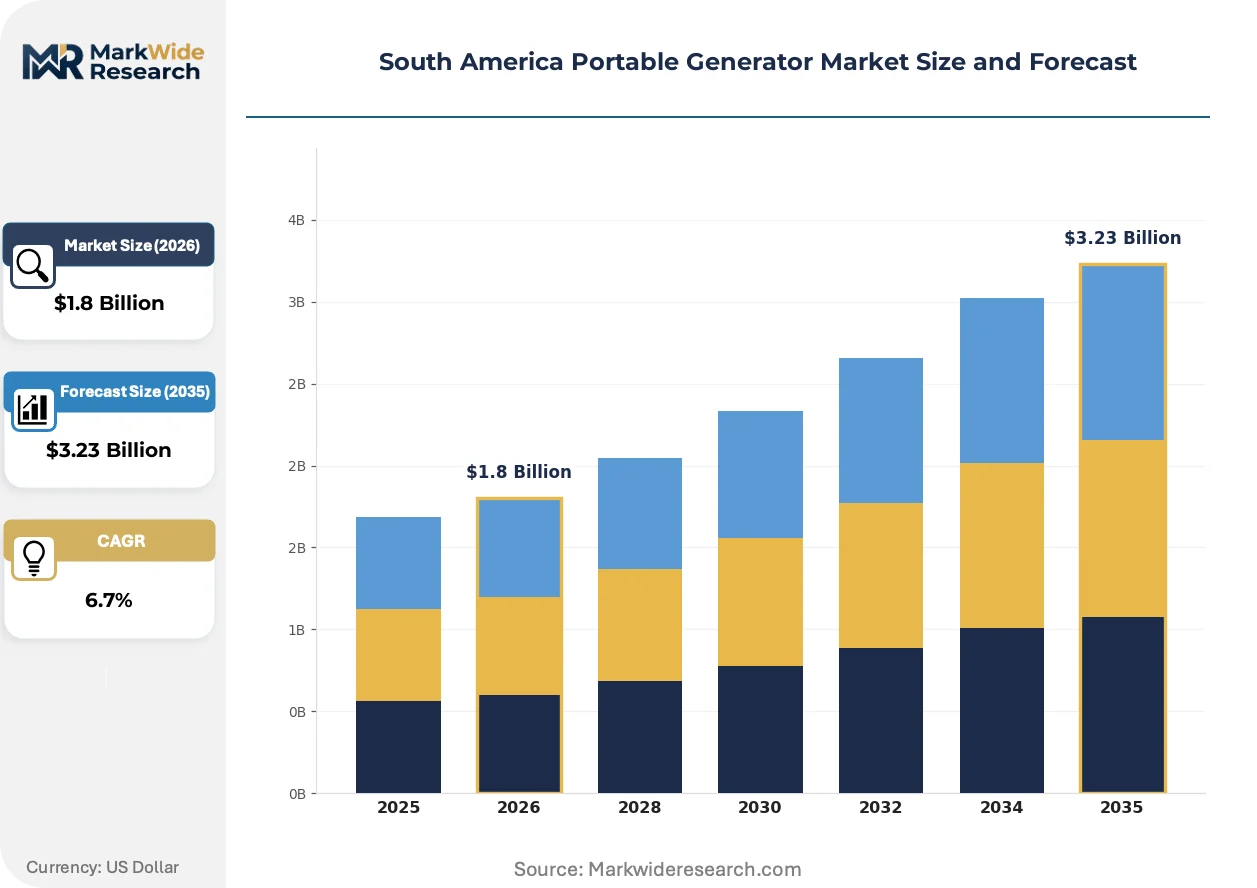
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline Generators, Diesel Generators, Solar Generators, Dual Fuel Generators Application: Residential, Construction, Outdoor Events, Emergency Backup End User: Homeowners, Contractors, Event Organizers, Industrial Users Distribution Channel: Online Retailers, Specialty Stores, Home Improvement Chains, Direct Sales |
| Companies Covered | Generac Holdings Inc., Caterpillar Inc., Kohler Power Systems, Briggs & Stratton Corporation, Atlas Copco AB, Cummins Inc., Ingersoll Rand, HIMOINSA, Kohler-SDMO, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Portable Generator Market Evolving Landscape
Power electronics miniaturization and regulatory pressure on emissions are converging to reshape equipment specifications and channel economics across the region.
Inverter generator technology is decomposing the traditional tradeoff between portability and waveform quality. Brazilian rental fleet operators are phasing out conventional alternator units in favor of digital sine-wave models that protect sensitive construction instrumentation. This shift is compressing residual values for legacy equipment and accelerating replacement cycles in São Paulo's equipment auction markets.
ANEEL's distributed generation frameworks are mandating bidirectional power interfaces for grid-connected backup systems. Industrial facilities in Minas Gerais are retrofitting portable units with smart metering hardware to qualify for net-metering credits. This regulatory pull is forcing manufacturers to integrate communication modules that were previously confined to stationary standby systems.
Equipment leasing is displacing outright purchase among mid-sized Argentine construction firms facing peso volatility and credit access constraints. Rental channels in Buenos Aires and Córdoba are expanding inventory pools with telematics-equipped units that enable usage-based billing. This model is penetrating fastest in commercial segments where project duration uncertainty makes capital commitment risky.
South America Portable Generator Market Segmentation
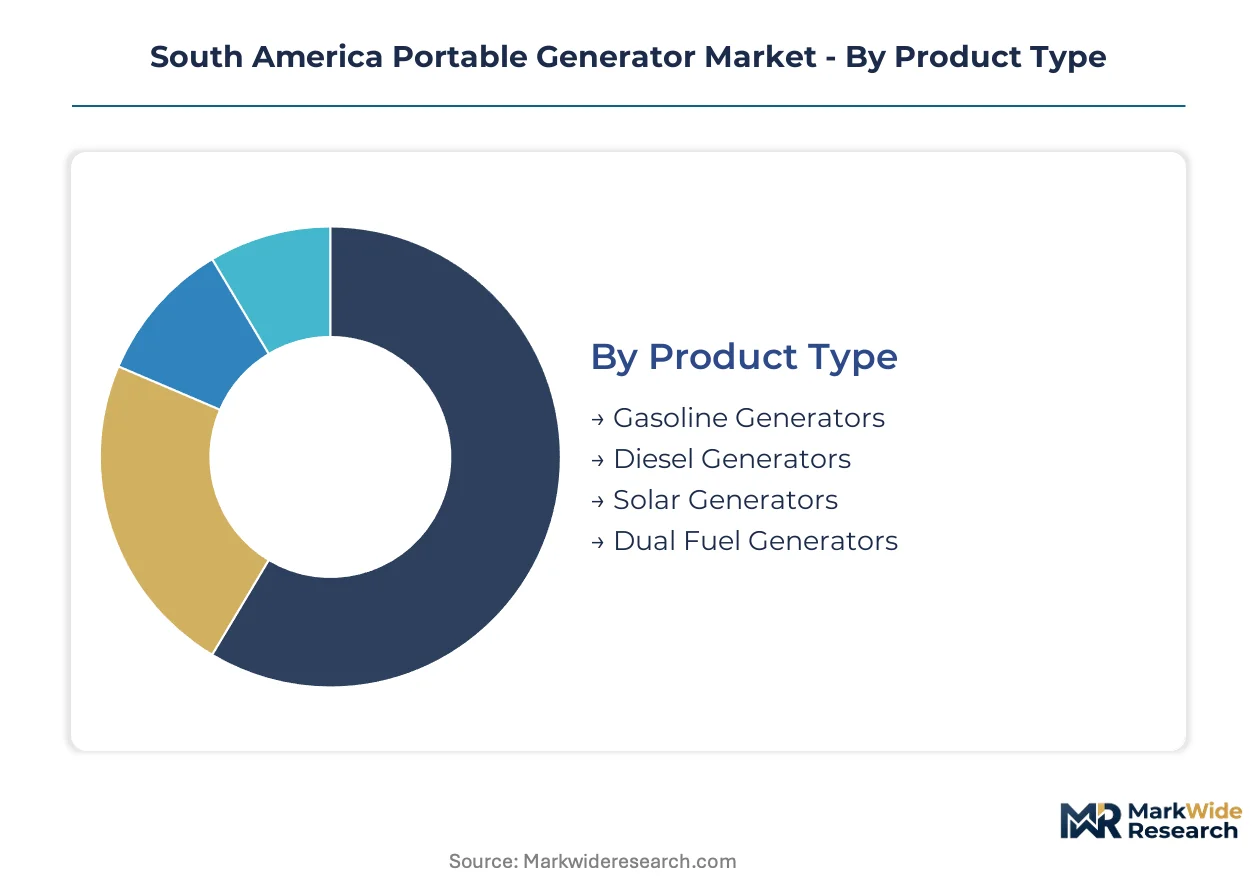
Segmentation in South America's portable generator market reveals how fuel type, application intensity, and channel structure create distinct competitive arenas. Each dimension carries different margin profiles and regulatory exposure across Brazil and Argentina.
Product Type:
Diesel and gasoline units face divergent substitution pressures from solar-battery hybrids as ANEEL net-metering frameworks alter lifecycle economics for commercial buyers.
- Diesel Generators:Compression-ignition engines rated 5 kW to 15 kW dominate construction rental fleets across São Paulo and Minas Gerais due to fuel availability and runtime durability. Mining contractors in Brazil's southeastern industrial corridor specify these units for continuous-duty applications where grid backup is non-negotiable.
- Solar Generators:Photovoltaic-battery systems with lithium-ion storage are compressing payback periods for rural telecommunications towers and outdoor event staging. Argentine grain silo operators in Córdoba province are piloting hybrid configurations to eliminate diesel logistics burdens.
- Gasoline Generators:Spark-ignition units under 5 kW serve homeowners and small contractors seeking low first-cost solutions for intermittent outage protection.
- Dual Fuel Generators:Engine platforms capable of gasoline or LPG operation offer fuel flexibility for event organizers facing municipal emissions restrictions in Buenos Aires.
Diesel retains volume leadership; solar holds the steepest expansion curve.
Application:
Application segmentation tracks how duty cycles and waveform requirements split procurement between price-sensitive residential buyers and specification-driven commercial operators.
- Construction:Brazilian contractors across Rio de Janeiro state are expanding equipment holdings to counter grid instability during peak demand periods, driving specification toward inverter-equipped units that protect sensitive instrumentation.
- Emergency Backup:Industrial facilities in Minas Gerais retrofit portable units with smart metering hardware to qualify for ANEEL net-metering credits, converting backup power from contingency to revenue-generating infrastructure.
- Residential:Homeowners in Argentina's urban centers prioritize low-noise inverter models for weekend outage protection where municipal noise ordinances apply.
- Outdoor Events:Festival organizers in São Paulo specify silent-running equipment to comply with decibel restrictions while powering lighting and sound systems.
Construction commands the largest equipment fleet; emergency backup is gaining share fastest as regulatory frameworks monetize standby capacity.
End User:
End user categories map to financing capacity and technical sophistication, from peso-constrained Argentine contractors to credit-accessing Brazilian industrial accounts.
- Contractors:Mid-sized Argentine construction firms facing currency volatility are shifting from purchase to leasing models, expanding rental channel penetration in Buenos Aires and Córdoba.
- Industrial Users:Manufacturing plants across Brazil's southeastern corridor specify bidirectional power interfaces to capture ANEEL energy credits, demanding communication modules previously confined to stationary systems.
- Homeowners:Residential buyers in São Paulo's suburban markets prioritize portability and storage convenience for intermittent grid failure scenarios.
- Event Organizers:Commercial staging companies value rapid deployment and noise compliance over fuel efficiency for short-duration applications.
Contractors represent the deepest equipment base; industrial users are driving specification upgrades fastest.
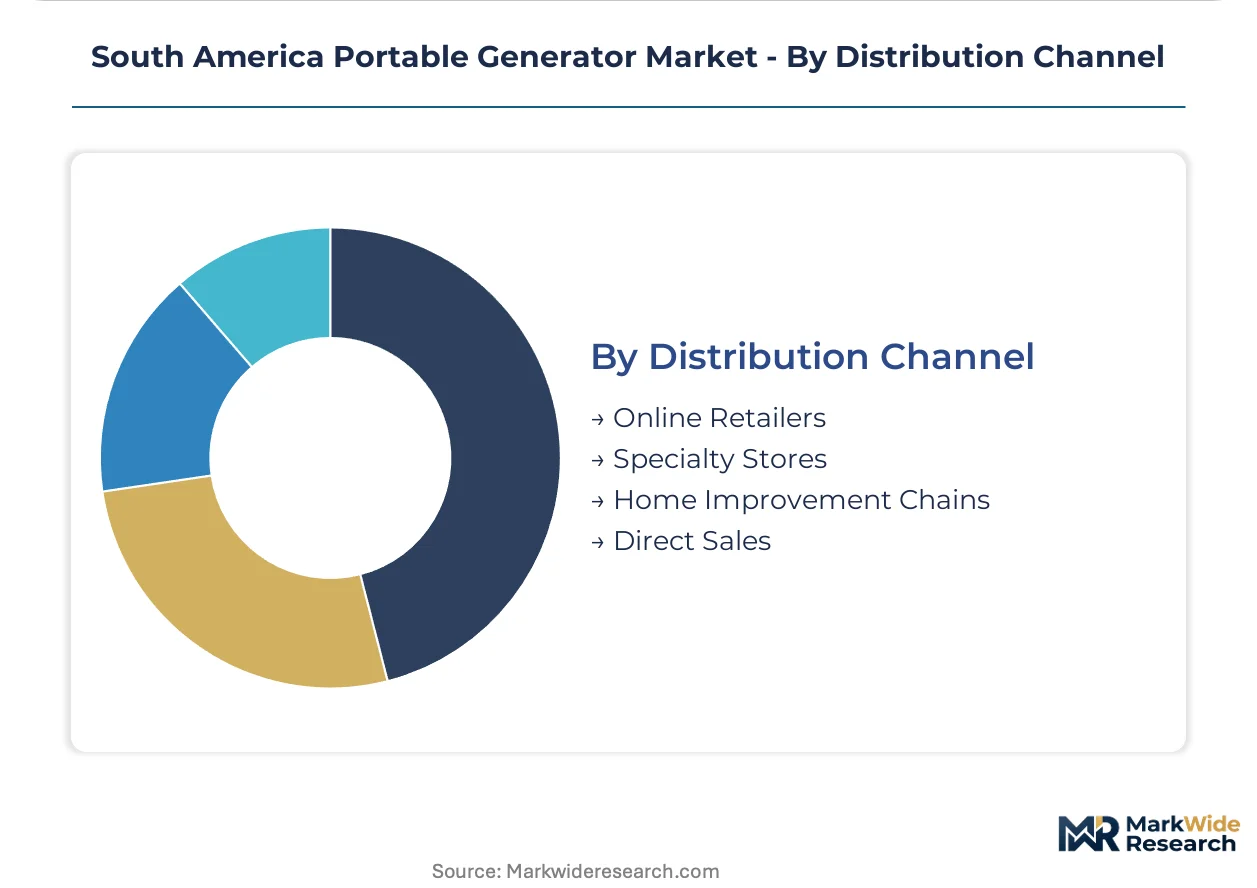
Distribution Channel:
Channel structure reflects the tension between technical pre-sale requirements and the geographic reach needed to serve dispersed mining and agricultural demand.
- Specialty Stores:Authorized dealer networks in Brazil's northern states provide technician coverage for inverter electronics failures, though sparse density extends mean-time-to-repair.
- Home Improvement Chains:Brazilian retail channels anchor Kohler's residential standby positioning through shelf presence and consumer financing programs.
- Direct Sales:Manufacturers serving Argentine industrial accounts navigate PROCREL certification timelines by controlling import clearance protocols directly.
- Online Retailers:E-commerce platforms are penetrating homeowner segments with specification transparency and comparative pricing tools.
Specialty stores retain the service-intensive commercial base; home improvement chains are expanding fastest into residential standby configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands pricing power across the South America portable generator market, while Argentine distributors absorb landed cost premiums from import friction at Buenos Aires terminals. This asymmetry shapes procurement patterns and competitive positioning across the region.
Brazil
Construction contractors in São Paulo and Rio de Janeiro states are expanding equipment fleets to counter grid instability during peak demand periods. ANEEL's distributed generation regulations now permit net-metered backup systems, accelerating commercial adoption of portable units as hybrid power assets. Industrial facilities across Minas Gerais are retrofitting portable generators with smart metering hardware to capture energy credits.
Argentina
Mid-sized construction firms in Buenos Aires and Córdoba are shifting from purchase to leasing models due to peso volatility and credit access constraints. The Secretariat of Energy's PROCREL efficiency standards impose extended product clearance protocols that delay market entry for new equipment configurations. Grain silo operators in Córdoba province are piloting solar-battery hybrid configurations to eliminate diesel logistics burdens.
Chile
Mining contractors in the Atacama Desert specify portable diesel units for continuous-duty applications where grid connectivity remains unreliable. The country's national energy commission has strengthened backup power requirements for critical mineral extraction operations. Equipment lessors in Santiago are expanding inventory pools with telematics-equipped units that enable usage-based billing for project-duration uncertainty.
Colombia
Oil and gas field operators in the Llanos Basin deploy portable generators for remote wellhead electrification where pipeline infrastructure remains underdeveloped. The national mining and energy planning unit has streamlined import protocols for backup power equipment serving extractive industries. Rental channels in Bogotá are penetrating commercial segments with specification-driven procurement for construction and events.
Peru
Telecommunications tower electrification in the Andean highlands creates demand for photovoltaic generators with minimal fuel logistics. The Ministry of Energy and Mines has promoted rural electrification frameworks that incentivize renewable backup systems. Mining camps in the Apurímac region are adopting hybrid power configurations to reduce diesel transport costs across difficult terrain.
South America Portable Generator Market Competitive Landscape
Concentration sits with integrated engine manufacturers who leverage captive production to sustain margin structures against assembly-focused competitors. The market exhibits a tiered structure where heavy-duty diesel specialists, residential standby providers, and solar-battery hybrid innovators occupy distinct competitive arenas. Three archetypes dominate: vertically integrated engine producers, channel-anchored retail brands, and emerging clean-technology specialists. Competitive moves center on backward integration into powertrain components and geographic expansion through rental network partnerships.
Within the integrated manufacturer tier, Caterpillar Inc. and Cummins Inc. represent the capital-intensive archetype with in-house engine production capabilities. Kohler Power Systems and Kohler-SDMO occupy positions anchored in Brazilian home improvement retail and European engineering heritage respectively. Among specialists in residential standby configurations, Generac Holdings Inc. exemplifies the adaptive technology approach for voltage fluctuation patterns common in Argentine and Brazilian grids.
| Leading Market Players |
|---|
| Generac Holdings Inc. |
| Caterpillar Inc. |
| Kohler Power Systems |
| Briggs & Stratton Corporation |
| Atlas Copco AB |
| Cummins Inc. |
| Ingersoll Rand |
| HIMOINSA |
| Kohler-SDMO |
| Others |
Value Network & Pricing Analysis
Forty-five to sixty-day engine import lead times from Asian manufacturing hubs concentrate procurement risk among Brazilian assemblers while granting integrated manufacturers pricing power through captive component supply. This inventory compression forces assembly-focused competitors to absorb margin volatility or cede share to vertically integrated rivals with deeper balance sheets.
Pricing Analysis
Configured-to-order diesel units for mining contractors command fifteen to twenty-five percent premiums over standard rental fleet specifications due to continuous-duty engineering and ANEEL grid-interconnection module integration. Three-tier pricing structure across premium inverter, standard alternator, and economy gasoline levels stratifies by waveform quality and runtime durability. Pricing pressure stems from lithium-ion battery cost compression eroding payback differentials for solar-battery hybrids in telecommunications applications. Argentine contractors exhibit highest price sensitivity due to peso volatility and credit access constraints, while Brazilian industrial users prioritize specification compliance over first cost.
Supply Chain Analysis
Buenos Aires port terminal congestion acts as a persistent chokepoint inflating landed costs for Argentine distributors sourcing Brazilian-assembled units. Engine block casting and electronic control module production concentrates in China, Japan, and South Korea, while alternator winding and final assembly clusters in Brazil and Mexico. Raw material dependencies span copper magnet wire, rare-earth permanent magnets, and hardened crankshaft steel grades. Single-source vulnerability in inverter semiconductor supply creates exposure to allocation constraints during demand spikes. Distribution runs through authorized dealer networks for commercial accounts and home improvement retail chains for residential standby configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Authorized technician density for inverter electronics repair represents the critical capability gap constraining service responsiveness across Brazil's northern states and Argentina's agricultural interior. Manufacturers who solve this scarcity capture disproportionate share in specification-driven commercial segments.
For Market Incumbents: Secure exclusive distribution partnerships with Brazilian home improvement chains to block competitor shelf access in residential standby segments. Expand captive engine production capacity to defend margin structures against assembly-focused rivals sourcing from volatile Asian supply chains. Invest in ANEEL certification pre-approval for grid-interconnection modules to accelerate commercial sales cycles. For New Entrants and Emerging Players: After-sales service coverage gaps in Brazil's Pará and Amazonas states present immediate white-space opportunity for solar-battery hybrid specialists with remote diagnostic capabilities. Target Argentine grain silo operators in Córdoba province with fuel-free power configurations that eliminate diesel logistics burdens. Deploy direct-to-contractor leasing models with telematics-enabled usage billing to bypass established dealer networks. For Investors and Strategic Acquirers: Long-term, this sits as a grid-resilience infrastructure play because ANEEL distributed generation frameworks and Argentine energy efficiency mandates structurally embed backup power as operational rather than contingency expenditure. Acquisition targets should display vertical integration into powertrain components or proprietary inverter control software. Monitor PROCREL certification timeline compression as signal of regulatory environment favoring compliant market entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Engine Manufacturing | Captive production insulates margin structures from Asian component volatility and exchange rate swings. |
| ANEEL Grid-Interconnection Certification | Pre-approved bidirectional power modules accelerate commercial sales cycles in Minas Gais industrial corridor. |
| Telematics-Enabled Leasing Platform | Usage-based billing models penetrate Argentine contractor segments facing peso volatility and credit constraints. |
| Solar-Battery Hybrid Product Line Expansion | Lithium-ion cost curves compress payback periods for rural telecommunications and agricultural pump applications. |
| Specialty Store Service Network Densification | Technician coverage in Brazil's northern states reduces mean-time-to-repair for inverter electronics failures. |
Research Methodology
Desk research of customs trade databases, ANEEL regulatory filings, and PROCREL efficiency standard protocols preceded structured interviews with Brazilian rental fleet operators, Argentine grain cooperative procurement managers, and telecommunications tower electrification contractors. Primary fieldwork with São Paulo construction contractors and Minas Gerais industrial facility engineers validated secondary demand indicators. Bottom-up equipment shipment analysis triangulated against top-down power generation capacity projections across the analysis window.
Variance decomposition across fuel type, application intensity, end-user financing capacity, and distribution channel structure anchored the analytical framework throughout the projection horizon. CAGRs derived from segment-level demand elasticity modeling incorporating lithium-ion battery cost trajectory assumptions and diesel fuel logistics burden indices. Modeled outputs incorporate ANEEL net-metering adoption curves and PROCREL certification timeline distributions as industry-specific forecast inputs.
Forecasts assume regulatory continuity in ANEEL distributed generation frameworks and PROCREL efficiency mandates; material policy shifts would require re-modeling of commercial adoption trajectories and import clearance protocols. Practitioners should keep alternative scenarios live as Mercosur technical barrier negotiations and Brazilian renewable integration targets evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Digital Inverter Generator Market
Generators
South America Diesel Generator Market
Generators
North America Gasoline Gensets Market
Generators
Wind Power Generators Market
Generators
South America and Africa Diesel Generator Market
Generators
Wind Turbine Alternator Market
Generators
Generator Sets Market
Generators
Generator (Up to 20 Kva) Market
Generators
Saudi Arabia Diesel Generator Market
Generators
Natural Gas Generator Market
Generators
South Africa Diesel Generator Market
Generators
Asia Pacific Electric Generators Market
Generators
Middle-East and Africa Portable Generator Market
Generators
China Diesel Generator Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
Military Generator Market