
 Africa Portable Generator Market | 2026-2036
Africa Portable Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Portable Generator Market Outlook
Nigeria's Petroleum Industry Act is consolidating the cost-of-entry calculus for foreign equipment suppliers entering West African markets. Cummins Inc. leverages its distribution density across Lagos and Abuja to sustain aftermarket parts availability. Kirloskar Oil Engines Ltd. anchors its position through localized assembly partnerships that reduce import duty exposure. HIMOINSA competes on dual-fuel architecture suited to variable diesel-availability environments.
Africa portable generators are self-contained combustion or renewable-energy units rated between 1 kW and above 10 kW, designed to convert mechanical energy into electrical power for off-grid or backup applications through alternator induction or inverter-controlled output. Their primary purpose spans construction site electrification, residential backup during utility failures, and critical load support for emergency medical and telecommunications infrastructure. Diesel generators dominate current fleet composition due to fuel accessibility and torque characteristics, while inverter generators capture premium residential and events segments where noise suppression and waveform quality command price premiums. Solar fuel type represents the fastest-growing structural category as photovoltaic-battery hybrid systems displace pure combustion units in telecom tower and rural commercial applications.
Nigeria's Department of Petroleum Resources, South Africa's National Energy Regulator, and Kenya's Energy and Petroleum Regulatory Authority each enforce emissions and safety standards that shape product certification requirements and import documentation burdens. Compliance with these overlapping national frameworks elevates working capital needs for distributors and favors manufacturers with established conformity-assessment pathways. Stakeholders must monitor regulatory divergence between ECOWAS harmonization efforts and national-level petroleum subsidy reforms that alter diesel-to-solar crossover economics.
Market Dynamics
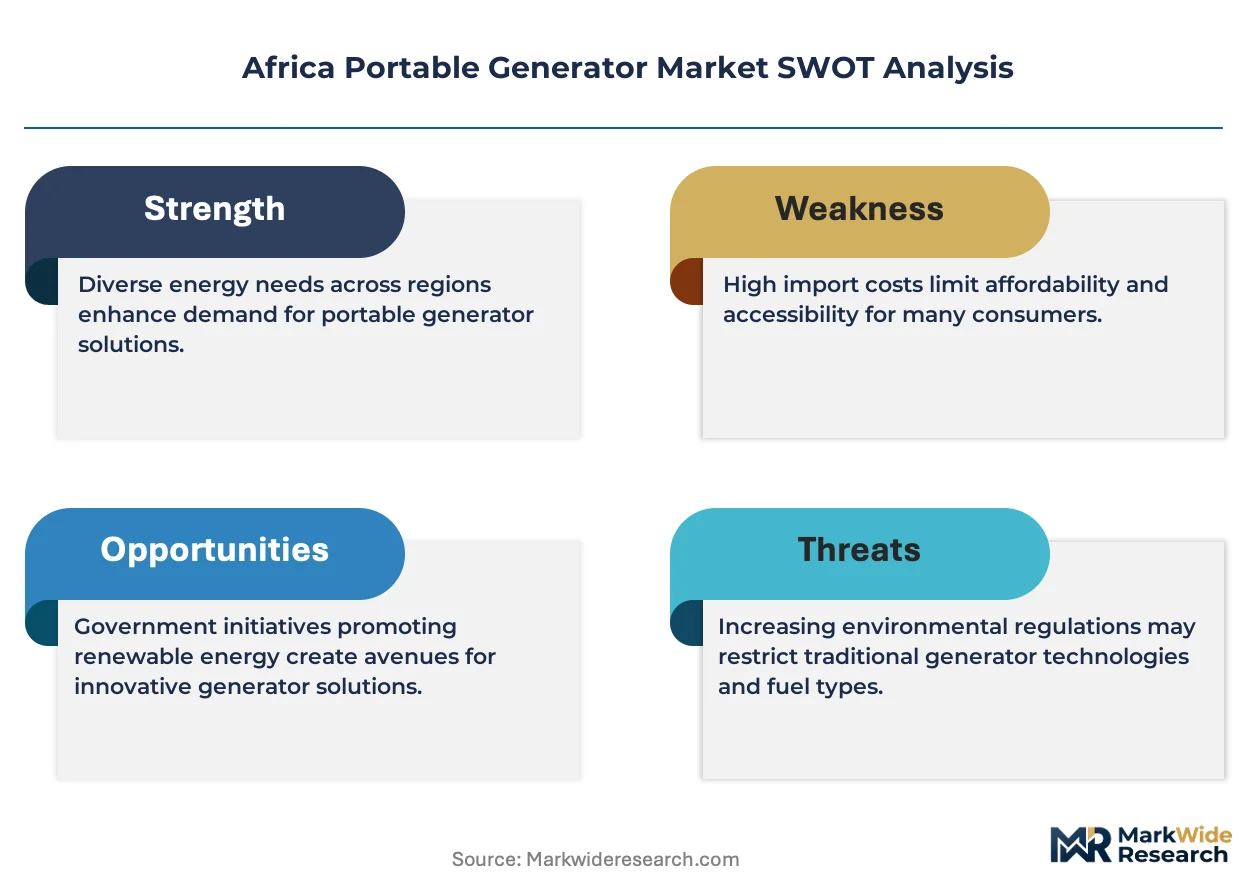
Grid instability across Sub-Saharan Africa is compressing replacement cycles for diesel units while Nigeria's Petroleum Industry Act recalibrates fuel economics toward hybrid architectures. This structural tension between legacy combustion dependence and solar-battery convergence defines current competitive positioning.
Growth Catalysts
- Telecom Tower Electrification:MTN and Airtel expansion programs across Ghana and Kenya mandate reliable off-grid power for rural base stations, pulling inverter-generator and solar-hybrid procurement volumes.
- Nigeria Petroleum Industry Act:Deregulated downstream pricing reduces diesel subsidy distortions, improving total-cost-of-ownership transparency for commercial buyers evaluating fuel-switching timelines.
- Mining Output Recovery:Copper and cobalt extraction resumption in the Democratic Republic of Congo drives 24/7 power demand at remote pit operations where grid extension remains uneconomical.
Market Restraints
- Diesel Price Volatility:Import-dependent fuel supply chains in landlocked Zambia and Zimbabwe expose operators to currency-driven cost spikes that disrupt annual maintenance budgeting.
- Chinese Component Concentration:Alternator and engine block sourcing clusters in Guangdong and Zhejiang provinces create single-origin vulnerability for African assemblers facing shipping delays.
- Emissions Compliance Friction:Divergent national standards between South Africa's National Energy Regulator and Kenya's Energy and Petroleum Regulatory Authority multiply certification costs for pan-regional suppliers.
Strategic Opportunities
- Ethiopia Manufacturing Corridors:Industrial park electrification gaps outside Addis Ababa present first-mover positioning for solar-diesel hybrid providers targeting textile and agro-processing tenants.
- Pay-as-you-go Generator Leasing:Mobile money-enabled asset financing models pioneered in Kenya and Tanzania unlock informal construction and event-rental segments previously excluded from formal credit.
- ECOWAS Harmonization Trajectory:Regional standards convergence on emissions testing and safety certification would collapse documentation burdens currently fragmenting West African distribution networks.
Industry Challenges
- Skilled Technician Scarcity:Inverter-generator and hybrid system repair capabilities concentrate in Lagos, Nairobi, and Johannesburg, leaving secondary cities dependent on extended manufacturer response times.
- Working Capital Intensity:Inventory financing for import-heavy diesel generator stock ties up distributor liquidity, particularly where Nigerian naira and Kenyan shilling depreciation accelerates foreign-exchange exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Portable Generator Market |
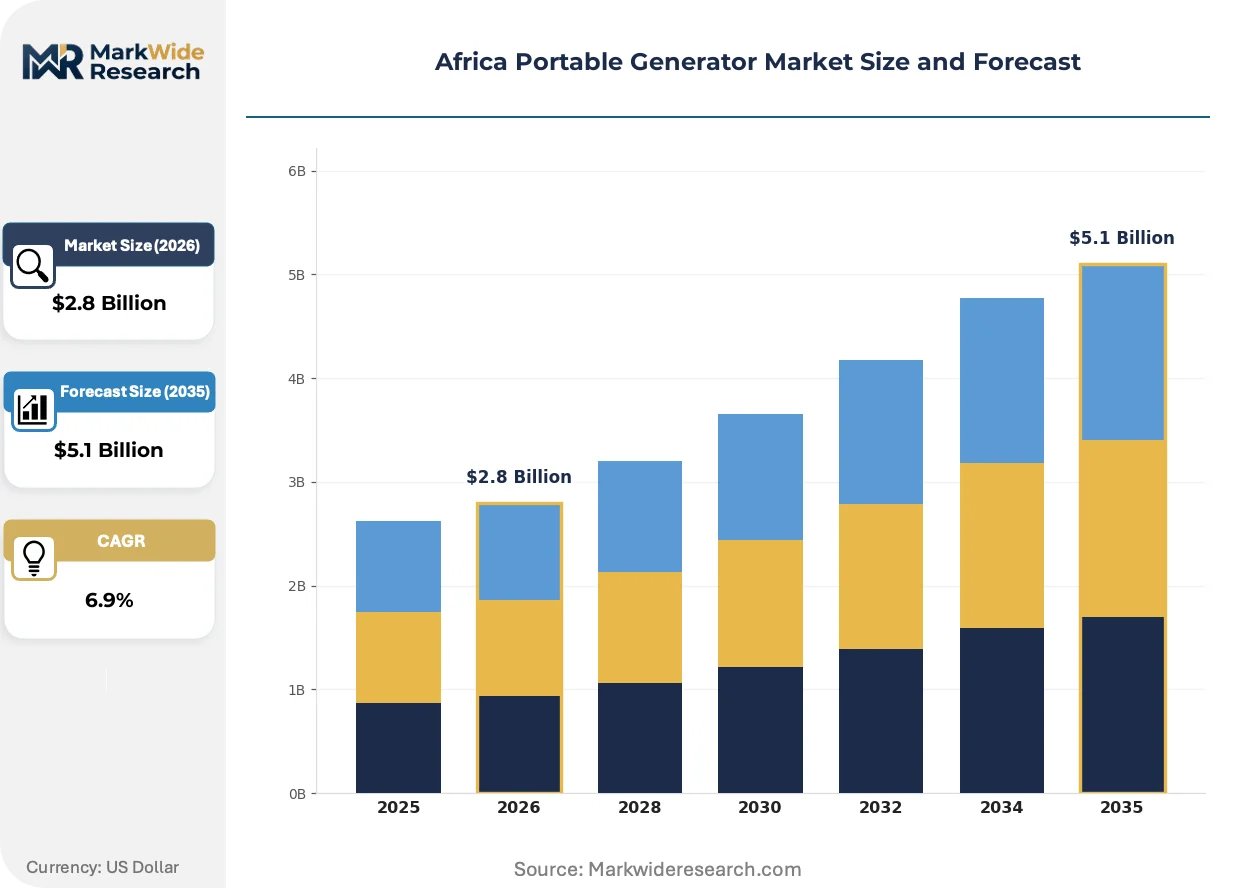
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.1 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inverter Generators, Conventional Generators, Diesel Generators, Biomass Generators End User: Residential, Construction, Events, Emergency Services Fuel Type: Diesel, Gasoline, Propane, Solar Power Rating: 1-3 kW, 3-5 kW, 5-10 kW, Above 10 kW |
| Companies Covered | Mitsubishi Heavy Industries, Atlas Copco AB, Cummins Inc., Caterpillar, Kohler Co., Denyo Co., Ltd., Kirloskar Oil Engines Ltd., Wärtsilä Corporation, HIMOINSA, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Portable Generator Market Strategic Shifts
Solar-battery hybrid architectures are compressing pure diesel generator relevance across telecom and commercial verticals. Three developments are accelerating this transition.
Photovoltaic-battery inverter systems are overtaking conventional diesel units in telecom tower applications. Tower operators across Kenya and Tanzania now specify lithium-ion storage paired with 5-10 kW solar arrays to reduce fuel logistics costs. This technology shift is enabling 72-hour autonomous runtime at remote sites while compressing generator replacement demand in East Africa's tower electrification networks.
Nigeria's Department of Petroleum Resources has tightened emissions testing protocols for imported generating sets above 10 kW. The regulation forces distributors to pre-certify units through Lagos-based conformity assessment bodies before customs clearance. Commercial construction buyers in Lagos and Abuja are responding by accelerating solar-hybrid evaluations to sidestep diesel compliance timelines.
Construction contractors are consolidating procurement through equipment rental platforms rather than direct manufacturer relationships. Jumia and specialized B2B marketplaces in Nigeria and South Africa now aggregate generator availability with bundled maintenance. This channel shift is most visible in West Africa's commercial building corridors where project-based buyers prioritize uptime guarantees over asset ownership.
Africa Portable Generator Market Segmentation
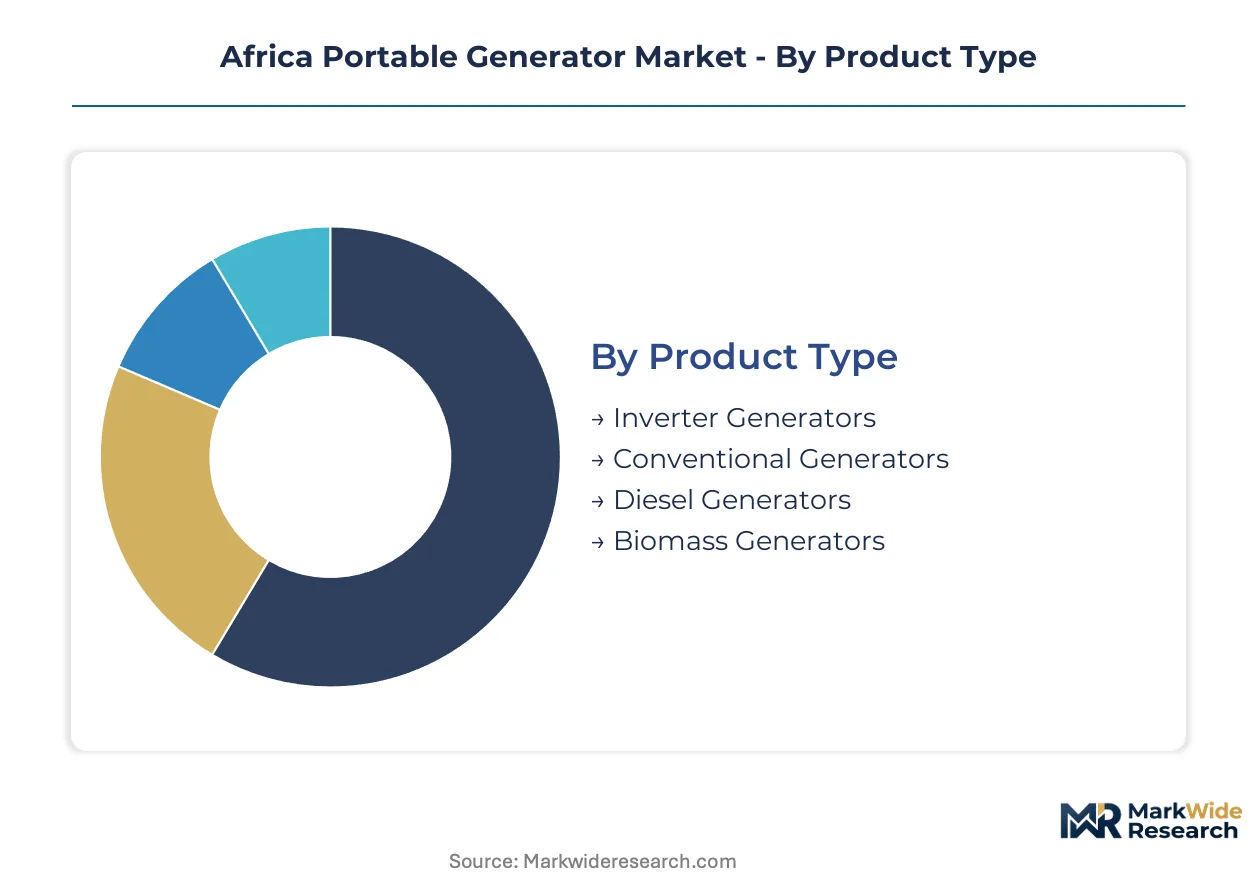
Segmentation reveals how capital requirements and fuel economics fragment procurement patterns across African markets. Diesel units demand heavy working capital but dominate mining and construction, while solar-battery hybrids attract leaner financing models in telecom and residential backup.
Product Type:
Capital intensity varies sharply across product architectures, with conventional diesel platforms requiring the highest distributor inventory investment and inverter systems demanding technical certification spend.
- Conventional Generators:These units employ brushed alternators with fixed-speed engines producing unconditioned AC output. Mining contractors across South Africa and the Democratic Republic of Congo specify conventional diesel units above 10 kW for pit operations where waveform purity matters less than torque response and parts availability.
- Inverter Generators:Microprocessor-controlled inverter modules convert raw alternator output to stable sine-wave electricity through DC-link architecture. Lagos event-rental operators and Nairobi telecom contractors pay premiums for inverter units when powering sensitive electronics, with noise suppression below 65 dB enabling urban deployment where conventional units face noise ordinances.
- Diesel Generators:Compression-ignition engines paired with synchronous alternators dominate fleet composition through fuel accessibility and load-following capability.
- Biomass Generators:Gasification systems converting agricultural residue to producer gas for spark-ignition engines remain experimental, with pilot installations concentrated in Ethiopian agricultural processing cooperatives.
Most installed capacity flows through Conventional Generators. Expansion is steepest in Inverter Generators.
End User:
Customer procurement sophistication spans informal cash purchases to structured equipment financing, with construction and telecom buyers commanding volume discounts unavailable to fragmented residential demand.
- Construction:Site electrification for commercial building corridors across Lagos, Abuja, and Nairobi drives diesel generator procurement through rental platforms and direct manufacturer relationships. Nigerian contractors face compressed project timelines when grid connections delay, accelerating spot-market generator rentals.
- Residential:Backup power for middle-income households in grid-unstable neighborhoods concentrates demand in 3-5 kW gasoline and inverter segments. Kenyan and Nigerian buyers prioritize portability and noise suppression over fuel efficiency for intermittent outage coverage.
- Events:Temporary power for outdoor gatherings and religious functions pulls single-phase inverter units below 5 kW, with rental duration typically spanning 24-72 hours.
- Emergency Services:Hospital and clinic backup specifications mandate automatic transfer switches and 72-hour fuel autonomy, concentrating procurement through specialized medical equipment distributors.
Construction absorbs the largest share of diesel unit volume. Residential solar-hybrid adoption is climbing fastest.
Fuel Type:
Fuel supply infrastructure and subsidy regimes determine total-cost-of-ownership calculations, with diesel accessibility in urban centers contrasting propane distribution gaps in rural markets.
- Diesel:Compression-ignition fuel with higher energy density per liter than gasoline dominates remote mining and construction applications. Nigeria's Petroleum Industry Act deregulation has compressed subsidy distortions, improving price transparency for commercial buyers evaluating hybrid transition timelines.
- Solar:Photovoltaic-battery hybrid systems displace pure combustion units in telecom tower and rural commercial verticals. Tower operators across Kenya and Tanzania now specify lithium-ion storage paired with 5-10 kW arrays to eliminate diesel logistics costs at remote sites.
- Gasoline:Spark-ignition fuel for portable units below 5 kW serves residential and small commercial backup where runtime demands remain modest.
- Propane:Liquefied petroleum gas offers cleaner combustion but limited retail availability outside South African urban centers constrains adoption.
Diesel retains the largest installed base. Solar is gaining share fastest in new installations.
Power Rating:
Unit economics and application scale segment procurement, with sub-5 kW units moving through retail channels and above-10 kW systems requiring engineered sales and installation services.
- Above 10 kW:Three-phase output units serve commercial building backup and industrial process loads. Nigeria's Department of Petroleum Resources mandates emissions pre-certification for imported sets in this tier, elevating documentation burdens and delivery timelines.
- 5-10 kW:Single and three-phase hybrid solar-diesel systems dominate telecom tower specifications across East Africa, with lithium-ion battery integration enabling 72-hour autonomous runtime.
- 1-3 kW:Portable gasoline and inverter units for residential backup and small events concentrate in Lagos, Nairobi, and Johannesburg retail channels.
- 3-5 kW:Mid-range residential and light commercial backup applications where gasoline accessibility outweighs diesel torque requirements.
Above 10 kW commands the highest revenue per unit. 5-10 kW solar-hybrid configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled diesel generator technicians concentrate in Lagos, Nairobi, and Johannesburg, anchoring aftermarket service networks while leaving secondary cities dependent on extended manufacturer response timelines. This talent geography shapes procurement confidence across the continent's fragmented power infrastructure.
Nigeria
Commercial construction corridors across Lagos and Abuja drive diesel generator procurement through rental platforms and direct manufacturer relationships. The country's Department of Petroleum Resources enforces emissions pre-certification for imported sets above 10 kW, elevating documentation burdens and delivery timelines. Distributors in Lagos leverage established conformity-assessment pathways to accelerate customs clearance for compliant units.
South Africa
Mining operations across the platinum and gold belts sustain 24/7 power demand at remote pit operations where grid extension remains uneconomical. The National Energy Regulator enforces emissions and safety standards that shape product certification requirements and import documentation burdens. Johannesburg anchors the continent's deepest aftermarket parts network, sustaining generator fleet availability for cross-border mining contractors.
Kenya
Telecom tower electrification networks across rural base stations pull inverter-generator and solar-hybrid procurement volumes from MTN and Airtel expansion programs. The Energy and Petroleum Regulatory Authority mandates emissions and safety standards that multiply certification costs for pan-regional suppliers. Nairobi concentrates inverter-generator and hybrid system repair capabilities, leaving Mombasa and secondary cities with extended response timelines.
Democratic Republic of Congo
Copper and cobalt extraction resumption drives 24/7 power demand at remote pit operations in the Katanga mining belt. The country's national mining regulator coordinates with energy authorities on off-grid power specifications for extractive operations. Lubumbashi serves as the logistics gateway for generator imports serving cross-border mining contractors operating in the copperbelt.
Ethiopia
Industrial park electrification gaps outside Addis Ababa present first-mover positioning for solar-diesel hybrid providers targeting textile and agro-processing tenants. The national energy authority prioritizes renewable integration in new industrial zone masterplans. Hawassa and Dire Dawa industrial corridors concentrate demand for reliable backup power where grid connection timelines remain uncertain.
Africa Portable Generator Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Africa portable generator market, creating a tiered competitive structure. The vendor base spans global engine manufacturers with African distribution networks, regional assemblers with localized production partnerships, and specialized hybrid system integrators. Three strategic archetypes dominate: integrated power solutions providers, cost-optimized diesel specialists, and renewable-hybrid technology leaders. Competitive intensity centers on distribution density in Lagos and Nairobi, plus aftermarket parts availability for mining contractors.
Among diversified industrial conglomerates, Mitsubishi Heavy Industries and Caterpillar exemplify scale-driven positioning through established African dealer networks and mining sector relationships. Cummins Inc. anchors the integrated power solutions tier with distribution density across Lagos and Abuja sustaining aftermarket parts availability. HIMOINSA occupies a specialist position within the hybrid technology segment, competing on dual-fuel architecture suited to variable diesel-availability environments.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| Atlas Copco AB |
| Cummins Inc. |
| Caterpillar |
| Kohler Co. |
| Denyo Co., Ltd. |
| Kirloskar Oil Engines Ltd. |
| Wärtsilä Corporation |
| HIMOINSA |
| Others |
Value Chain & Pricing Dynamics
Platts Dubai crude benchmarks cascade through diesel generator landed costs in Lagos and Mombasa, compressing margin structures for distributors holding inventory against currency depreciation. Nigerian naira volatility and Kenyan shilling weakness amplify working capital intensity, forcing pricing stratification across premium-certified, standard-import, and economy-refurbished tiers.
Pricing Analysis
Bundled maintenance contracts versus unbundled equipment-only transactions split procurement economics across African markets. Three-tier pricing structure across premium inverter, standard conventional diesel, and economy gasoline units reflects certification grade and after-sales coverage depth. Cost compression in the standard diesel tier is intensifying because Nigerian Petroleum Industry Act compliance adds pre-certification documentation burdens. Informal construction contractors in secondary cities exhibit highest price sensitivity; mining operators in South Africa and DRC demonstrate lowest sensitivity due to uptime guarantee requirements.
Supply Chain Analysis
Skilled alternator-winding technicians and engine-block machinists concentrate in Guangdong and Zhejiang provinces, anchoring Chinese component clusters that feed African assembly operations. Engine blocks, copper windings, and electronic control modules draw from East Asian manufacturing hubs. Single-origin vulnerability from Guangdong port congestion creates inventory disruption risk for Lagos and Mombasa distributors. Distribution runs through manufacturer-direct dealer networks in capital cities, with secondary markets served by independent spare-parts traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity into competitive advantage, with Nigeria's Petroleum Industry Act emissions pre-certification requirements accelerating consolidation among compliant distributors.
For Market Incumbents: Acquire established conformity-assessment relationships in Lagos and Abuja to defend against solar-hybrid entrants exploiting diesel compliance delays. Deepen backward integration into alternator and engine-block sourcing through direct partnerships with Zhejiang manufacturers, reducing exposure to Chinese trading-house markups. Anchor aftermarket service density in secondary cities where technician scarcity currently extends manufacturer response timelines. For New Entrants and Emerging Players: Equipment rental platforms in Nigeria and Kenya represent the most penetrable channel for solar-hybrid systems, bypassing capital-intensive distributor inventory requirements. Target Ethiopia's Hawassa and Dire Dawa industrial corridors where grid connection uncertainty creates first-mover positioning for hybrid providers. Lead with mobile money-enabled pay-as-you-go financing models proven in Kenyan and Tanzanian construction segments. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid system integrators possessing lithium-ion battery supply agreements and East African telecom tower relationships. Five-to-ten-year viability hinges on solar-diesel crossover economics improving faster than pure diesel cost curves. Watch ECOWAS emissions harmonization progress as inflection indicator for West African documentation burden collapse.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Architecture Development | HIMOINSA's variable diesel-availability systems capture procurement preference in Nigerian and DRC mining corridors. |
| Localized Assembly Partnership | Kirloskar Oil Engines Ltd. reduces Nigerian import duty exposure through domestic production agreements. |
| Solar-Battery Hybrid Integration | MTN and Airtel tower specifications in Kenya and Tanzania displace pure diesel with 72-hour autonomous runtime systems. |
| Conformity Assessment Pre-Certification | Cummins Inc. leverages Lagos-based certification pathways to accelerate customs clearance above 10 kW units. |
| Mobile Money Equipment Financing | Kenyan and Tanzanian rental platforms unlock informal construction segments previously excluded from formal credit. |
Study Parameters
Multiple input streams — diesel generator distributor interviews, telecom tower operator procurement assessments, and mining contractor equipment surveys — were reconciled against Nigerian Department of Petroleum Resources regulatory filings, Kenyan Energy and Petroleum Regulatory Authority certification databases, and South African National Energy Regulator emissions standards. Secondary validation drew from customs import records, EPC contractor project databases, and tower electrification procurement disclosures. Bottom-up unit shipment estimates and top-down market value reconstructions were triangulated to anchor volume and value outputs.
Historical shipment trajectories were cross-referenced against panel input from generator manufacturer regional heads and aftermarket service network managers. Segmentation modeling spanned product architecture, fuel type, power rating tier, end-use vertical, and geographic regulatory cluster. CAGRs were derived from fitted trend analysis adjusted for Nigeria's Petroleum Industry Act implementation pace and solar-hybrid technology cost curves. Forecast inputs included diesel price volatility scenarios and ECOWAS harmonization probability assessments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion battery supply constraints and Nigerian naira depreciation trajectories. Assumptions underlying projections reflect current regulatory enforcement intensity and technology substitution elasticities. Material deviation in ECOWAS harmonization timelines or Chinese component shipping reliability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
North America Gas Generator Market
Generators
Generator Belt Market
Generators
Industrial Generator Market
Generators
China Diesel Generator Market
Generators
Multi Fuel Generators Market
Generators
Europe Diesel Generator Market
Generators
Power Generator for Military Market
Generators
Nuclear Turbine Generators Market
Generators
Railway Generators Market
Generators
Europe Gas Generator Market
Generators
Onboard Marine Gensets Market
Generators
Digital Inverter Generator Market
Generators
India Generator Sets Market
Generators
Wind Turbine Alternator Market
Generators
Residential Gas Generator Market
Generators
Generator [Up to 100 Kva] Market