
 Reciprocating Power Generating Engine Market | 2026-2036
Reciprocating Power Generating Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Reciprocating Power Generating Engine Market Analysis
Aftermarket service revenue is fragmenting across original equipment manufacturers and independent service providers. Wärtsilä Oyj Abp leverages its global service network to capture long-term maintenance contracts. Cummins Inc. anchors its position through backward integration into fuel system components. Caterpillar Inc. competes by dominating the mining and heavy industrial channel.
A reciprocating power generating engine converts linear piston motion into rotational mechanical energy through crankshaft linkage, typically operating at speeds from 500 to 1,500 rpm with bore diameters exceeding 200 mm in utility-class units. Its primary purpose is stationary electricity generation for baseload, peaking, and emergency backup applications across industrial and commercial installations. Diesel engines retain the largest installed base in remote mining and marine propulsion segments where fuel availability dictates technology choice. Dual-fuel engines represent the fastest-expanding category as operators seek compliance flexibility under tightening emissions protocols. Natural gas engines command premium margins in utility-scale power generation where pipeline infrastructure exists.
EPA stationary engine standards, EU F-Gas Regulation, and China's MEE emission guidelines collectively mandate nitrogen oxide and particulate reductions that accelerate engine replacement cycles. These frameworks push end users toward certified low-emission configurations or dual-fuel retrofits rather than conventional diesel installations. Stakeholders must monitor carbon border adjustment mechanisms and hydrogen blending trials to anticipate fuel pathway obsolescence.
Market Dynamics
The reciprocating power generating engine market is compressing around dual-fuel retrofit economics as EPA Tier 4 and EU F-Gas regulations force premature replacement of legacy diesel installations. Engine OEMs now compete on compliance velocity rather than raw thermal efficiency.
Growth Catalysts
- Data Center Buildouts:Hyperscale operators in the United States and Germany are installing 2-5 MW diesel and natural gas units for grid-islanded backup. Colocation providers specify dual-fuel engines to hedge carbon border exposure.
- EPA Tier 4 Final:The standard mandates 90% NOx reduction from Tier 2 baselines, compelling fleet turnover in stationary emergency power. End users face operating-hour restrictions on non-compliant engines.
- Remote Mining Electrification:African and Australian mine developers deploy containerized reciprocating gensets where grid extension is uneconomic. Fuel logistics dictate medium-speed engine selection over gas turbines.
Market Restraints
- Steel and Rare Earth Volatility:Crankshaft forgings and permanent magnet alternators expose manufacturers to nickel and neodymium price swings. Chinese supply concentration amplifies margin compression.
- Technical Ceiling on Thermal Efficiency:Diesel cycles plateau near 48% brake thermal efficiency. Further gains require bottoming cycles or fuel cells that displace core engine value.
- EU F-Gas Phase-Down:The regulation restricts HFC refrigerants in engine hall HVAC, raising installation costs for large genset enclosures. Project developers absorb compliance premiums.
Strategic Opportunities
- Hydrogen Blending Trials:Dutch and German utilities test 25% H2 injection in natural gas engines. Retrofit kits open service revenue streams without full engine replacement.
- Microgrid-as-a-Service:African mining contractors now lease containerized power rather than own assets. OEMs capture recurring revenue through availability contracts.
- India's CEA Grid Codes:New frequency response mandates create demand for fast-start reciprocating engines in peaking service. Domestic manufacturers gain preference in public tenders.
Industry Challenges
- Combustion Calibration Talent:Dual-fuel engine tuning requires rare expertise in diesel and spark-ignition control. OEM service networks struggle to staff field engineers.
- Certification Timeline Compression:EPA and EU type-approval cycles now exceed 18 months for novel fuel configurations. Product launches lag technology readiness by two years.
- Legacy SCADA Integration:New digital engine controls must interface with 1990s-era plant DCS architectures. Custom protocol gateways erode project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reciprocating Power Generating Engine Market |
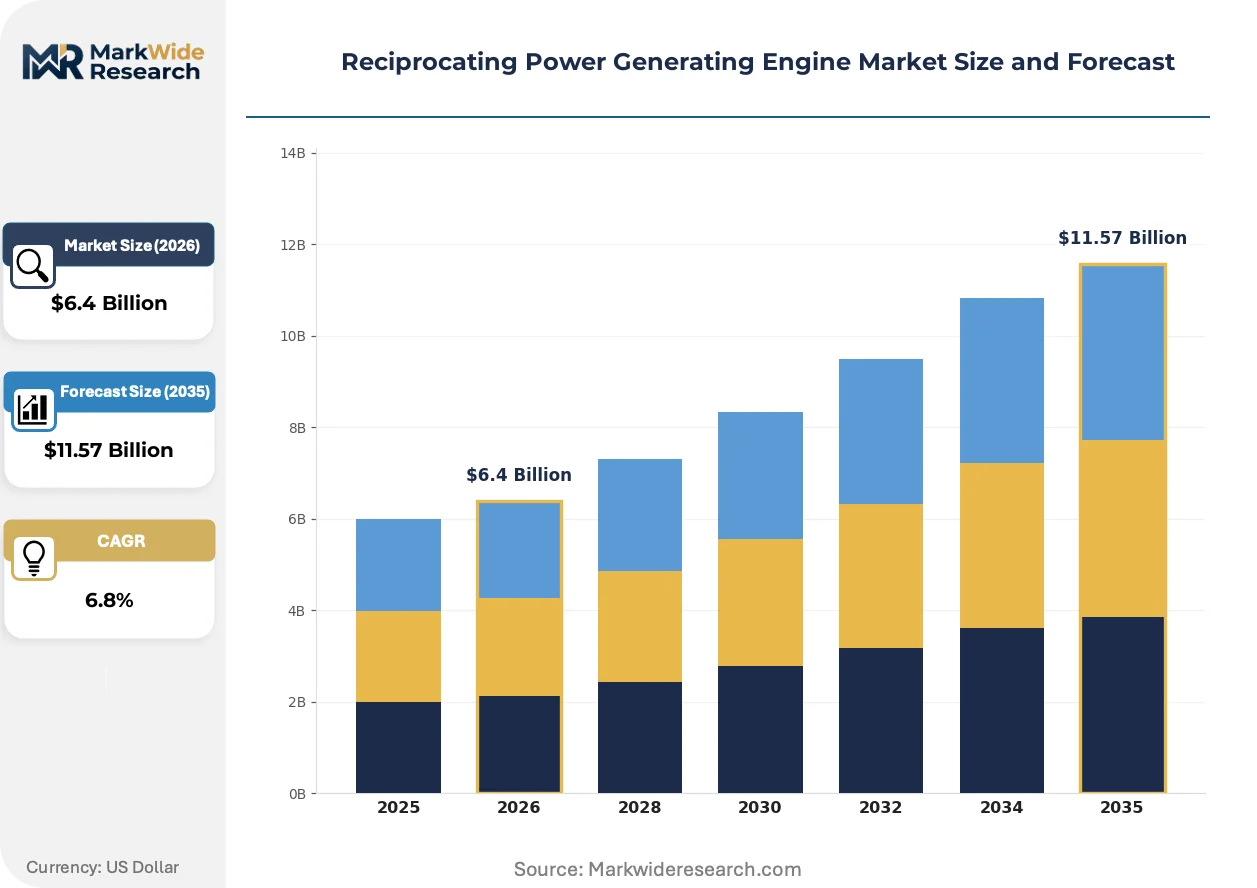
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Engine Type: Gas Engine, Diesel Engine, Dual-Fuel Engine, Natural Gas Engine Application: Power Generation, Marine Propulsion, Industrial Power, Backup Power End User: Utilities, Mining, Oil & Gas, Manufacturing Fuel Type: Biofuel, Methanol, LNG, HFO |
| Companies Covered | Rolls-Royce, Kirloskar Oil Engines Limited, Caterpillar Inc., Wärtsilä Oyj Abp, Kawasaki Heavy Industries Ltd., Cummins Inc., Kohler Co., INNIO Jenbacher GmbH & Co., MAN Energy Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reciprocating Power Generating Engine Market Emerging Trajectories
Digital twins and predictive combustion analytics are displacing scheduled maintenance paradigms. OEMs now monetize engine health data rather than hardware alone.
Digital twin platforms are virtualizing engine performance optimization across distributed fleets. Remote mining operators in Australia deploy physics-based models to predict piston ring wear and optimize lube oil intervals. The technology is virtualizing traditional time-based maintenance contracts into condition-driven service models.
EU F-Gas Regulation is tightening refrigerant leakage thresholds for engine hall climate systems. Manufacturers now specify CO2-based chillers or ammonia alternatives in large genset packages. German utility-scale installations face the strictest compliance timelines, driving specification changes ahead of 2027 review cycles.
Power purchase agreement structures are fragmenting ownership models for reciprocating engine assets. African mine developers now procure electricity under 10-year availability contracts rather than capital purchases. Equipment financiers assume operational risk, forcing OEMs to guarantee output and emissions performance in harsh environments.
Reciprocating Power Generating Engine Market Segmentation
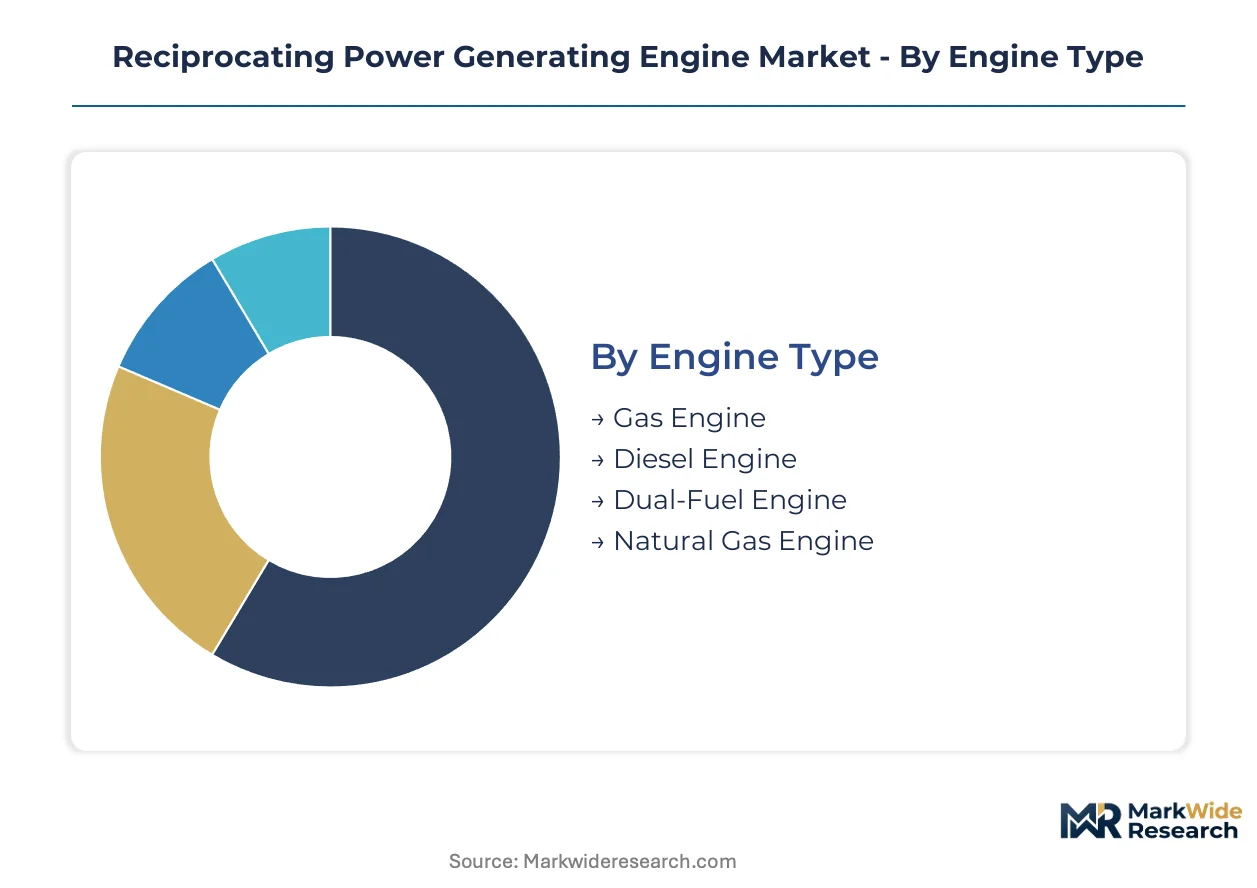
Segmentation in the reciprocating power generating engine market reveals divergent technology economics across fuel pathways and duty cycles. Procurement criteria now prioritize emissions compliance velocity alongside traditional metrics of thermal efficiency and capital cost.
Engine Type:
Cost tier differentiation separates mature diesel platforms from emerging dual-fuel architectures requiring premium engineering investment.
- Gas Engine:Spark-ignited designs operate on pipeline natural gas with lower NOx signatures than compression-ignition alternatives. Demand clusters in United States utility-scale peaking plants where FERC market rules reward fast-start flexibility. EPA permitting advantages accelerate procurement timelines versus diesel counterparts.
- Diesel Engine:Compression-ignition technology dominates installed base in remote mining and marine applications where fuel logistics constrain alternatives. African and Australian mine developers specify medium-speed diesel gensets for grid-isolated operations. Tier 4 Final compliance costs erode competitiveness against dual-fuel retrofits in developed markets.
- Dual-Fuel Engine:Configurable combustion systems switch between diesel pilot ignition and gaseous primary fuel. German utilities and Dutch grid operators test hydrogen blending compatibility for carbon border adjustment hedging.
- Natural Gas Engine:Purpose-built spark-ignited designs optimize for methane-specific combustion chamber geometries. Pipeline infrastructure availability dictates geographic deployment feasibility.
Diesel engines command the established base. The steepest expansion runs through dual-fuel configurations.
Application:
Volume concentration varies sharply across duty cycle profiles from continuous baseload to intermittent emergency service.
- Power Generation:Continuous-duty installations in utility and industrial cogeneration applications specify medium-speed engines above 1 MW unit capacity. Indian CEA grid code revisions mandate frequency response capabilities favoring reciprocating engines over gas turbines. Domestic manufacturers capture preference in public tender processes.
- Marine Propulsion:Medium-speed engines in the 500-1,200 rpm range dominate cargo vessel and offshore support vessel propulsion. IMO sulfur regulations and EU MRV monitoring requirements accelerate interest in LNG and methanol fuel variants.
- Industrial Power:Cogeneration applications in chemical and paper plants exploit waste heat recovery for process steam. Energy intensity of host facility determines payback calculus for capital investment.
- Backup Power:Emergency standby installations prioritize start reliability and load acceptance speed over thermal efficiency. Hyperscale data center operators in Germany and the United States specify 2-5 MW units for grid-islanded resilience.
Power generation anchors volume commitments. Backup power applications are climbing the fastest as digital infrastructure investment accelerates.
End User:
Customer type determines procurement sophistication, contract structure, and service attachment rates.
- Utilities:Grid-scale operators procure under regulated cost-recovery frameworks with extended asset depreciation schedules. Dutch and German utilities pilot hydrogen blending trials in existing natural gas engine fleets.
- Mining:Remote operations in Africa and Australia deploy containerized reciprocating gensets where grid extension proves uneconomic. Power purchase agreement structures shift ownership risk to equipment financiers under availability contracting.
- Oil & Gas:Upstream and midstream facilities require explosion-rated enclosures and sour gas fuel handling capabilities. Wellhead gas availability often dictates on-site generation economics.
- Manufacturing:Cogeneration adopters prioritize thermal load matching over electrical efficiency. Process heat demand profiles determine engine sizing and operating hour optimization.
Utilities represent the most mature demand segment. Mining applications are gaining share fastest through African electrification projects and contract structure innovation.
Fuel Type:
Maturity stage and supply infrastructure availability segment fuel alternatives across commercial readiness horizons.
- Biofuel:Hydrotreated vegetable oils and fatty acid methyl esters offer drop-in compatibility with existing diesel engine hardware. EU renewable energy directives create compliance value in member state installations.
- Methanol:Low-flashpoint liquid fuel requires modified injection systems and fuel handling safety protocols. Marine sector interest accelerates with IMO carbon intensity indicator regulations.
- LNG:Cryogenic storage and vaporization systems add capital cost but deliver sulfur and particulate compliance advantages. Bunkering infrastructure constraints limit geographic deployment.
- HFO:Residual fuel oil retains cost advantage in marine and remote power applications where emissions regulations permit continued operation. IMO 2020 sulfur cap compliance requires scrubber installation or fuel switching.
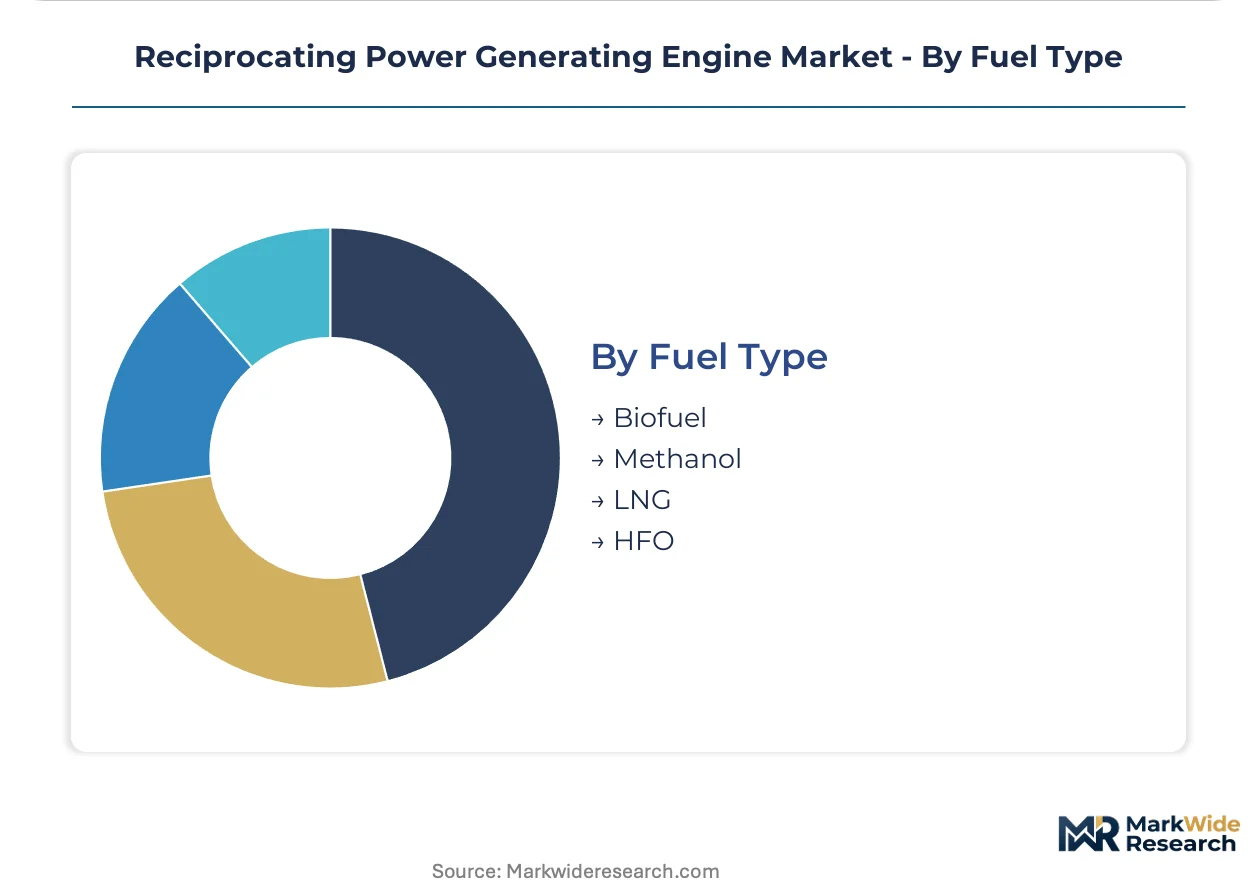
HFO retains the largest installed base. Methanol is expanding most quickly as marine decarbonization pathways crystallize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States exhibit low price elasticity as emissions compliance deadlines compress procurement timelines. Chinese mining operators and Indian industrial users retain higher sensitivity to capital cost, favoring established diesel platforms over premium dual-fuel configurations.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth Metroplex are installing 2-5 MW gensets for grid-islanded backup. EPA Tier 4 Final mandates drive fleet turnover in stationary emergency power applications. Texas ERCOT market volatility accelerates peaking plant investments near Houston and Midland-Odessa.
Germany
Dutch and German utilities pilot hydrogen blending trials in existing natural gas engine fleets to hedge carbon border adjustment exposure. EU F-Gas Regulation tightens refrigerant leakage thresholds for engine hall climate systems. Industrial cogeneration clusters in North Rhine-Westphalia specify CO2-based chillers ahead of 2027 compliance deadlines.
China
Remote mining electrification in Inner Mongolia and Xinjiang deploys containerized reciprocating gensets where grid extension proves uneconomic. MEE emission guidelines mandate nitrogen oxide reductions that accelerate engine replacement cycles. Domestic manufacturers capture preference in public tender processes under central procurement directives.
India
CEA grid code revisions mandate frequency response capabilities favoring fast-start reciprocating engines in peaking service. Manufacturing and chemical plants in Gujarat and Maharashtra exploit waste heat recovery for process steam. Domestic engine assemblers gain share through localized content requirements in utility tenders.
Australia
African and Australian mine developers specify medium-speed diesel gensets for grid-isolated operations in Western Australia and Queensland. Fuel logistics dictate reciprocating engine selection over gas turbines in Pilbara iron ore districts. Power purchase agreement structures shift ownership risk to equipment financiers under availability contracting models.
Reciprocating Power Generating Engine Market Vendor Landscape
Capability concentration sits with specialized combustion engineering houses; scale advantage sits with diversified industrial conglomerates. The market structures around three tiers: integrated power system providers, pure-play engine specialists, and regional assembly licensors. Dominant competitive moves include backward integration into fuel injection components and geographic expansion through local manufacturing joint ventures.
Among diversified industrial groups, Caterpillar Inc., Wärtsilä Oyj Abp, and Cummins Inc. occupy positions spanning multiple fuel pathways and application segments. These entities exemplify the integrated tier through captive control over critical subsystems and global service network density. Kirloskar Oil Engines Limited and INNIO Jenbacher GmbH & Co. represent specialized archetypes concentrated on specific thermal duty ranges or regional market penetration. MAN Energy Solutions and Rolls-Royce anchor the large-bore utility-scale segment through project engineering capabilities and long-term service contracting expertise.
| Leading Market Players |
|---|
| Rolls-Royce |
| Kirloskar Oil Engines Limited |
| Caterpillar Inc. |
| Wärtsilä Oyj Abp |
| Kawasaki Heavy Industries Ltd. |
| Cummins Inc. |
| Kohler Co. |
| INNIO Jenbacher GmbH & Co. |
| MAN Energy Solutions |
| Others |
Supply Flow & Price Mechanics
Shanghai's concentration of crankshaft forging capacity and permanent magnet alternator assembly feeds directly into OEM pricing power over European and North American project developers. Chinese supply dominance in nickel and neodymium processing allows domestic engine manufacturers to undercut import pricing by double-digit margins in African mining tenders.
Pricing Analysis
Long-term availability contracts now dominate utility-scale procurement, displacing spot-market transactions for units above 2 MW capacity. Three-tier pricing structure across premium, standard, and economy levels separates EPA Tier 4 certified configurations from legacy diesel platforms and basic genset skids. Pricing pressure stems from steel and rare earth volatility eroding manufacturer margins on fixed-price EPC contracts. Mining contractors in Africa exhibit highest price sensitivity, while German utilities accept premium positioning for hydrogen-ready dual-fuel architectures.
Supply Chain Analysis
Contract manufacturing for crankshaft forgings concentrates among specialized foundries in China, India, and Germany, with Chinese facilities capturing over half of global medium-speed engine component output. Engine assembly draws from nickel alloy bar stock, neodymium permanent magnets, and high-pressure fuel injection hardware. Single-source vulnerability runs through Chinese rare earth processing for alternator magnets. Distribution runs through OEM captive service networks and independent EPC contractors for remote project deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
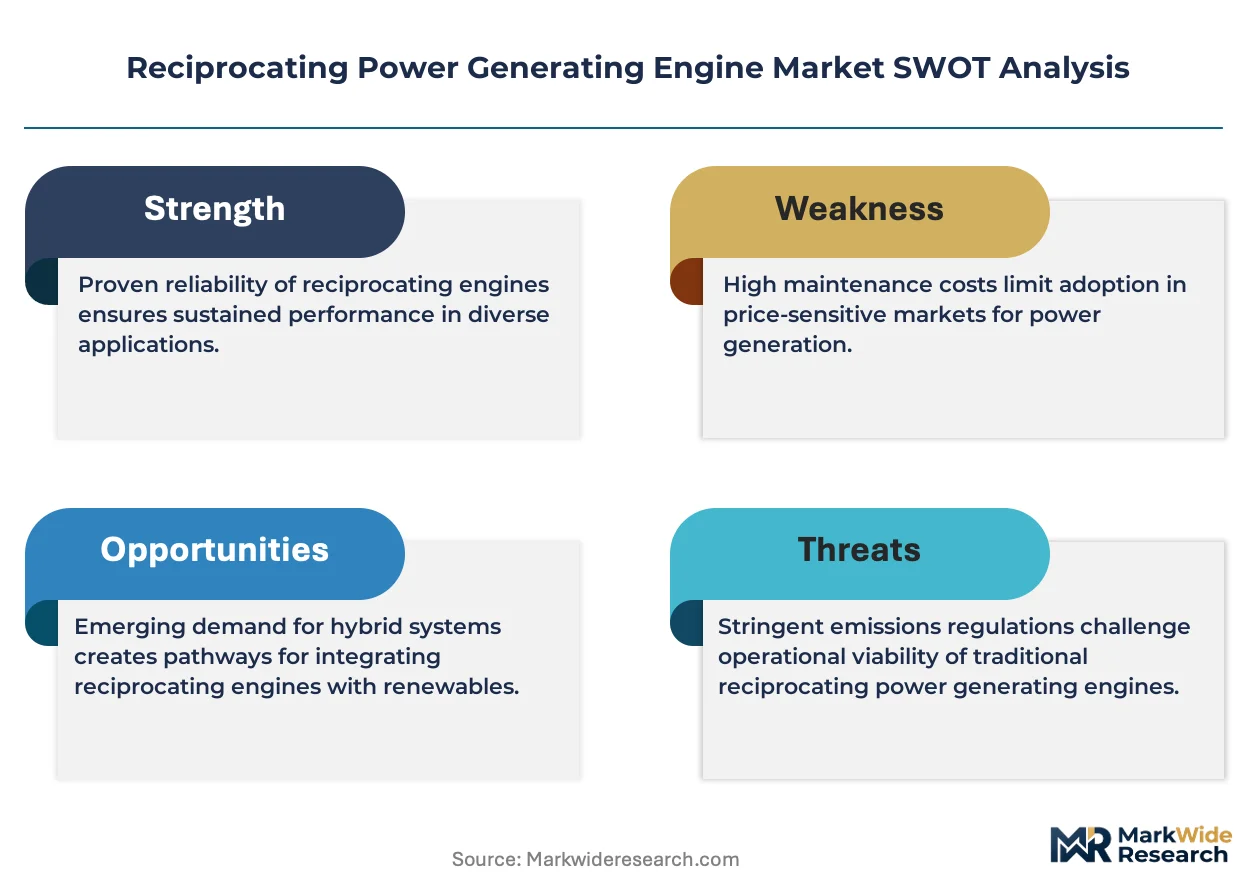
Dual-fuel combustion calibration expertise has become the constraining asset in this market, with field engineering talent scarcity limiting OEM service network expansion faster than manufacturing capacity growth.
For Market Incumbents: Entrench position through backward integration into fuel injection system components and exclusive long-term service contracting with hyperscale data center operators. Battery storage and fuel cell substitution threats demand accelerated hydrogen blending certification investment. Channel control over mining sector EPC relationships provides defensive moat against Chinese cost competition. For New Entrants and Emerging Players: Mid-market commercial and industrial cogeneration in Southeast Asia represents the most penetrable entry point, with fragmented local assembly creating white-space below 1 MW unit capacity. Containerized power-as-a-service contracting models bypass capital-intensive manufacturing scale requirements. Partner with established fuel logistics providers to de-risk fuel supply chain execution. For Investors and Strategic Acquirers: Long-term, this sits as a service-revenue compounding play because aftermarket contracting generates recurring cash flows decoupled from new equipment cyclicality. Acquisition targets should combine combustion engineering talent density with established utility relationships. Watch hydrogen blending trial results from Dutch and German utilities as inflection indicator for dual-fuel technology obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fuel Injection Components | Cummins and Caterpillar capture margin pools previously surrendered to Bosch and Delphi through in-house production of high-pressure common rail systems. |
| Hydrogen Blending Retrofit Program | Wärtsilä and MAN Energy Solutions extend service revenue streams from existing natural gas engine fleets without requiring full engine replacement capital expenditure. |
| Microgrid-as-a-Service Joint Venture | African mining contractors shift from asset ownership to availability contracting, transferring operational risk to OEM balance sheets under long-term offtake structures. |
| Digital Twin Platform Launch | Remote monitoring and predictive maintenance displace time-based service intervals, converting hardware sales into recurring software and analytics revenue. |
| Local Manufacturing Licensing Agreement | Indian domestic assemblers gain preference in CEA-mandated public tenders through localized content compliance and reduced import duty exposure. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA certification databases, EIA power plant inventories, and EU industrial emissions registries across the analysis window. Primary interviews engaged engine OEM product managers, utility procurement officers, mining EPC contractors, and aftermarket service directors. Secondary validation drew from FERC interconnection queues, IEA power system data, and customs trade records for reciprocating engine component flows. Bottom-up unit shipment modeling triangulates against top-down addressable market sizing.
Forecast inputs include EPA and EU regulatory compliance timelines, data center power demand projections, and mining electrification capital commitment pipelines. Segmentation modeling spans engine type, fuel pathway, application duty cycle, and regional regulatory framework clusters. CAGRs derive from unit volume trajectories applied to average selling price assumptions across premium and standard tier configurations. Hydrogen infrastructure deployment assumptions and carbon border adjustment mechanism implementation pace inform scenario-weighted outcomes.
Stress conditions across rare earth price volatility, EPA certification timeline extensions, and African mining investment cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding dual-fuel technology adoption curves and data center buildout momentum. Quarterly review of hydrogen blending trial results, EPA enforcement patterns on Tier 4 Final operating hour restrictions, and Chinese export license trends for permanent magnet materials is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Commercial Generator Market
Generators
Europe Generator Sets Market
Generators
Electric Generators Market
Generators
Asia-Pacific Portable Generator Market
Generators
South America Gas Generator Market
Generators
Portable Inverter Generators Market
Generators
Dual-Fuel Generator Market
Generators
Europe Turbo Generator Market
Generators
Telecom Generator Market
Generators
Residential Generators Market
Generators
Generator [Up to 100 Kva] Market
Generators
Gasoline Gensets Market
Generators
China Gas Generator Market
Generators
North America Gasoline Gensets Market
Generators
Generator Sales Market
Generators
Portugal Gas Generator Market