
 Egypt Natural Gas Market | 2026-2036
Egypt Natural Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Natural Gas Market Foresight
Market Context
Pipeline network architecture across the Nile Delta and Western Desert is reshaping how producers reach Egyptian industrial buyers. Egyptian Natural Gas Holding Company leverages its control over transmission infrastructure to coordinate field-to-factory flows. BP plc anchors deepwater production through its West Nile Delta concessions, while Eni SpA dominates the supergiant Zohr development with proprietary subsea technology. Shell Egypt competes in offshore exploration blocks, extending its presence beyond legacy onshore assets.
Technical and Segment Structure
Natural gas consists primarily of methane, typically comprising 70-90% of composition by volume, with variable ethane, propane, and butane fractions extracted through seismic surveying, directional drilling, and hydraulic fracturing before processing at treatment plants for pipeline specification or cryogenic liquefaction. Conventional gas from mature Nile Delta fields sustains baseline supply, while liquefied natural gas through Egyptian LNG's Idku terminal captures premium export margins to European buyers. Power generation applications absorb the largest volume share, though petrochemical industry offtake is deepening as ethane feedstock demand rises at Alexandria and Damietta complexes.
Regulatory Environment
Egypt's Petroleum Ministry and Egyptian Natural Gas Holding Company regulate upstream licensing, production-sharing agreements, and domestic price ceilings that shape producer economics and investment timelines. The General Authority for Investment and Free Zones governs Suez Canal Economic Zone gas allocations, while environmental compliance standards from the Egyptian Environmental Affairs Agency constrain flaring and mandate emissions monitoring at processing facilities. Stakeholders must track how Cairo balances export revenue optimization against industrial electrification targets and fertilizer subsidy obligations.
Market Dynamics
Egypt's natural gas sector operates under the Petroleum Ministry's dual mandate: maximizing export revenue through Idku LNG while securing subsidized feedstock for domestic fertilizer and power plants. This tension between hard-currency generation and local industrial obligations structures every investment decision.
Growth Catalysts
- West Nile Delta field ramp-up:BP plc's phased development of Taurus and Libra fields is expanding pipeline-delivered supply to Alexandria's petrochemical corridor, displacing imported naphtha as ethane feedstock.
- Petroleum Ministry domestic price reforms:Gradual lifting of industrial gas price ceilings is restoring producer economics at mature Nile Delta fields, encouraging workover investments and infill drilling programs.
- Suez Canal Economic Zone licensing:The General Authority for Investment and Free Zones is fast-tracking gas allocation permits for methanol and ammonia projects, anchoring offtake commitments from new industrial tenants.
Market Restraints
- Upstream capital intensity:Deepwater development costs at Zohr-grade pressures exceed $4 per barrel oil equivalent, constraining EGAS's ability to self-finance satellite exploration without production-sharing partners.
- Domestic price ceiling compression:The Petroleum Ministry's administered pricing regime caps industrial tariffs below netback export equivalents, eroding returns on incremental supply investments.
- Liquefaction capacity bottleneck:Egyptian LNG's Idku terminal operates at nameplate throughput, limiting spot cargo availability without debottlenecking investments that compete with domestic pipeline priorities.
Strategic Opportunities
- Red Sea exploration frontier:Unlicensed blocks offshore Hurghada and Safaga remain underpenetrated, offering carbonate reservoir analogs to Zohr's Cretaceous play fairway.
- Hydrogen hub development:The Suez Canal Economic Zone's existing gas infrastructure positions Egypt to pivot toward blue ammonia exports, leveraging Idku terminal logistics for European offtake.
- Digital field management convergence:Integration of subsea sensors with cloud-based production optimization platforms is enabling remote well intervention, reducing offshore personnel costs at mature Western Desert assets.
Industry Challenges
- Reservoir engineering specialization gap:Egypt's technical universities produce insufficient geoscientists trained in carbonate diagenesis, forcing operators to import expertise for Red Sea and ultra-deepwater appraisal.
- Pipeline integrity capex burden:Decades-old Nile Delta transmission infrastructure requires continuous corrosion monitoring and smart pigging investments to maintain pressure specifications for industrial buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Natural Gas Market |
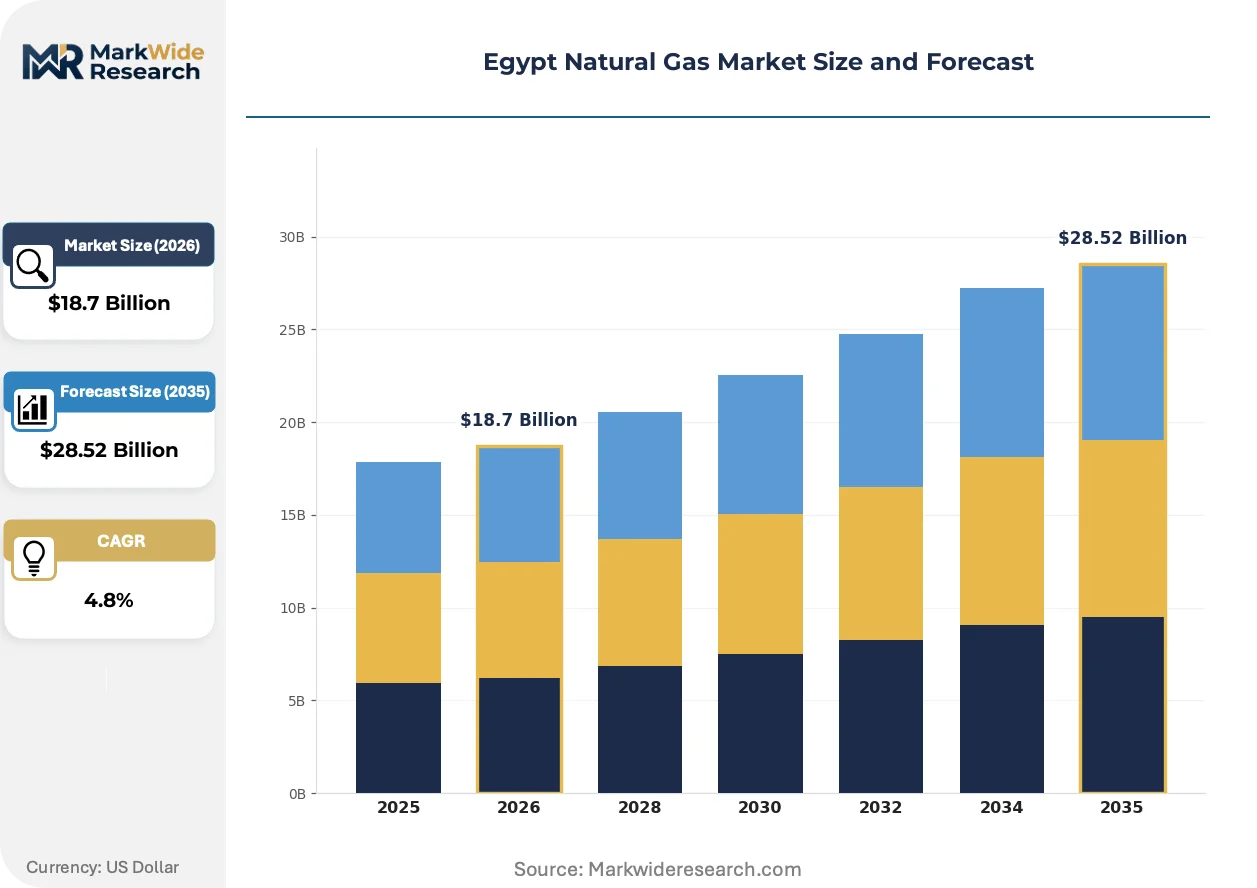
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Conventional Gas, Unconventional Gas, Liquefied Natural Gas, Compressed Natural Gas, Synthetic Natural Gas Application: Power Generation, Residential Heating, Fertilizer Production, Transportation Fuel, Petrochemical Industry End User: Utilities, Manufacturing Firms, Transport Operators, Agricultural Businesses, Chemical Plants Distribution Channel: Pipeline Network, LNG Terminals, Gas Bottling Plants, Local Distributors, Export Terminals |
| Companies Covered | Egyptian LNG, BP plc, Egyptian Natural Gas Holding Company, Chevron Corporation, Eni SpA, Egyptian General Petroleum Corporation, Shell Egypt, Apache Corporation, Egyptian Natural Gas Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Natural Gas Market Shifts & Advancements
Subsea processing technology and digital twin deployment are compressing development timelines across Egypt's offshore concessions. These advances are reshaping how Eni SpA and partners manage Zohr-scale reservoirs while the Petroleum Ministry tightens flaring enforcement.
Subsea multiphase pumping is collapsing the surface facility footprint required for deepwater gas development. Eni SpA is deploying this technology at Zohr satellite wells, eliminating separate processing platforms. The compression enables tieback economics at marginal discoveries that would otherwise remain stranded, accelerating field development cadence across the Egyptian Mediterranean.
Egyptian Environmental Affairs Agency flaring regulations are mandating continuous emissions monitoring at all processing facilities. The Petroleum Ministry is enforcing zero-routine-flaring deadlines at West Nile Delta complexes, requiring vapor recovery unit retrofits. Offshore operators are responding with closed-loop flare gas recovery systems, prioritizing compression over venting for safety and maintenance events.
Industrial buyers are consolidating procurement through long-term take-or-pay contracts rather than spot market exposure. Fertilizer complexes at Damietta and Alexandria are locking in decade-long supply agreements with EGAS, trading price flexibility for volume security. This preference for contractual certainty is most pronounced among export-oriented nitrogen producers facing volatile international urea pricing.
Egypt Natural Gas Market Segmentation
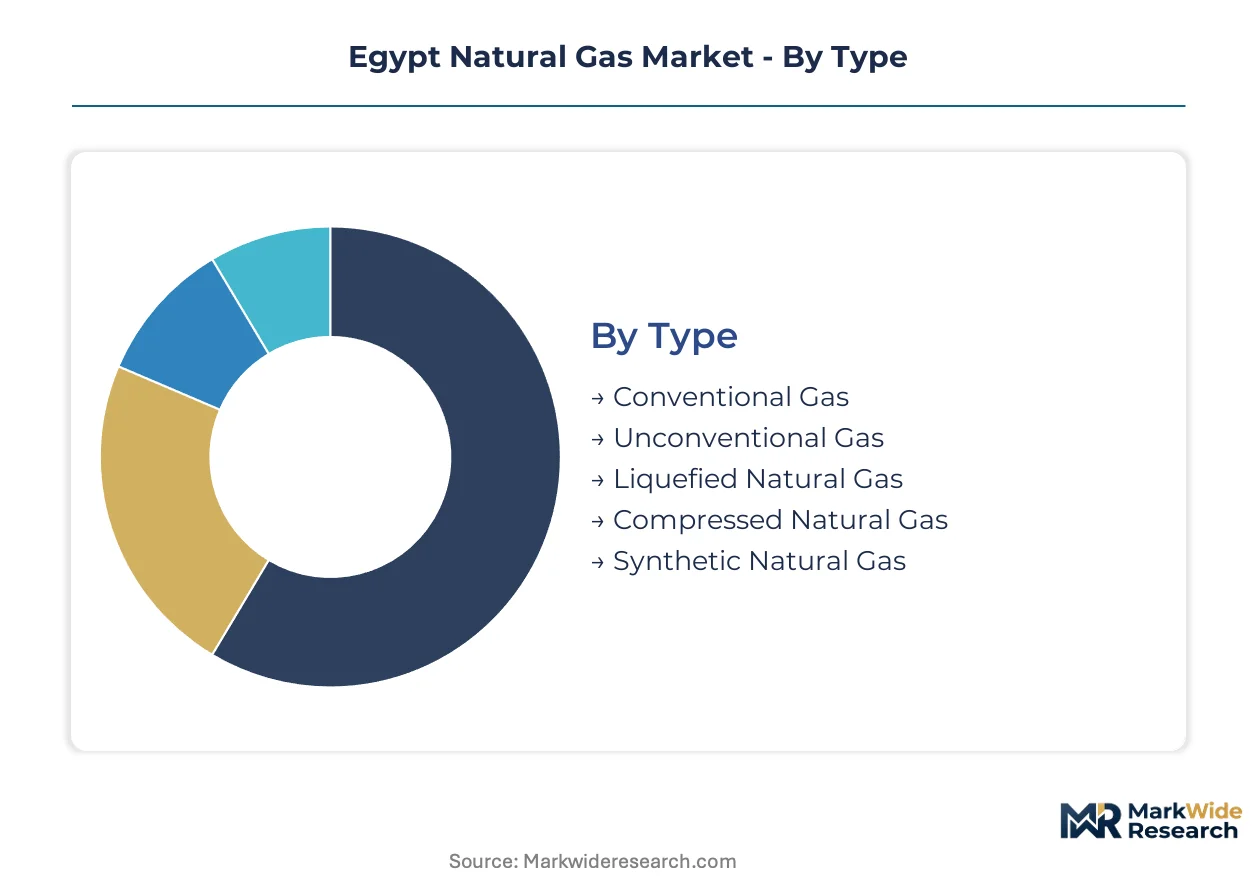
Segmentation in Egypt's natural gas market reveals how infrastructure constraints and regulatory mandates fragment commercial opportunities. Each dimension exposes distinct margin profiles and capital requirements that shape investment allocation across upstream, midstream, and downstream verticals.
Type:
After-sales service intensity varies dramatically across gas types, with liquefaction assets demanding continuous cryogenic maintenance while conventional pipeline supply requires minimal post-delivery intervention.
- Conventional Gas:Methane-rich production from mature Nile Delta and Western Desert fields supplies baseline industrial demand through existing pipeline architecture. Egyptian Natural Gas Holding Company prioritizes this segment for domestic fertilizer and power plant obligations, though reservoir depletion is accelerating workover frequency at aging concessions.
- Liquefied Natural Gas:Cryogenic processing at Egyptian LNG's Idku terminal converts pipeline gas into export-grade cargo for European spot markets. Suez Canal Economic Zone petrochemical projects compete with liquefaction offtake, creating allocation tensions under Petroleum Ministry export revenue targets.
- Unconventional Gas:Tight sandstone and shale prospects in the Western Desert remain underexplored due to water scarcity and fracturing cost structures.
- Compressed Natural Gas:Vehicle fuel applications concentrate in Cairo and Alexandria taxi fleets with limited retail infrastructure beyond fleet depots.
- Synthetic Natural Gas:Coal gasification and biomass methanation projects remain pre-commercial, constrained by feedstock logistics and carbon accounting frameworks.
Conventional gas holds the largest share; momentum sits with liquefied natural gas as European import demand reshapes Egyptian export economics.
Application:
Cost tier differentiation separates subsidized power generation from premium petrochemical feedstock pricing, with fertilizer production occupying a politically sensitive middle band.
- Power Generation:Combined-cycle gas turbines at West Damietta and Burullus plants absorb the largest volume share under long-term fuel supply agreements. Egyptian Electricity Holding Company procurement prioritizes price stability over spot market flexibility, locking in pipeline deliveries from West Nile Delta fields.
- Fertilizer Production:Ammonia and urea complexes at Abu Qir and Talkha depend on administered gas tariffs below export netback equivalents. Misr Fertilizers Production Company and Egyptian Chemical Industries anchor offtake, though subsidy reform debates threaten margin predictability.
- Petrochemical Industry:Ethane feedstock demand at Alexandria's ethylene crackers is deepening as naphtha import costs rise, with SIDPEC expanding polyethylene capacity.
- Residential Heating:Cairo and Delta governorate distribution networks serve urban households through local gas companies under regulated retail tariffs.
- Transportation Fuel:Compressed natural gas vehicle conversion programs target public transport fleets, with limited private passenger vehicle penetration.
Power generation commands the greatest volume; petrochemical industry applications are expanding most quickly as ethane cracking economics improve against liquid alternatives.
End User:
Customer type determines contract structure, with utilities securing decade-long take-or-pay terms while manufacturing firms negotiate shorter flexible arrangements.
- Utilities:Egyptian Electricity Holding Company subsidiaries operate under sovereign-backed offtake guarantees that minimize counterparty risk for upstream producers. Cairo Electricity Production Company and East Delta Electricity Production Company dominate procurement, with demand concentrated at coastal generation hubs near gas transmission infrastructure.
- Chemical Plants:Ethylene and methanol producers in the Suez Canal Economic Zone require high-pressure pipeline specifications and interruptible supply clauses for process safety.
- Manufacturing Firms:Cement and steel producers in Upper Egypt face transmission distance penalties that elevate delivered costs above coastal industrial zones.
- Agricultural Businesses:Greenhouse heating and irrigation pump fuel demand remains fragmented across small-scale distributors with limited metering infrastructure.
- Transport Operators:Fleet conversion economics depend on vehicle utilization intensity, with Cairo taxi cooperatives achieving payback periods below private owner-operators.
Utilities hold the largest share; chemical plants are gaining share fastest as Suez Canal Economic Zone licensing accelerates methanol and ammonia project commitments.
Distribution Channel:
Supply concentration dictates pricing power, with pipeline network control vesting Egyptian Natural Gas Holding Company with transmission gatekeeper authority while LNG terminals compete in tradable international markets.
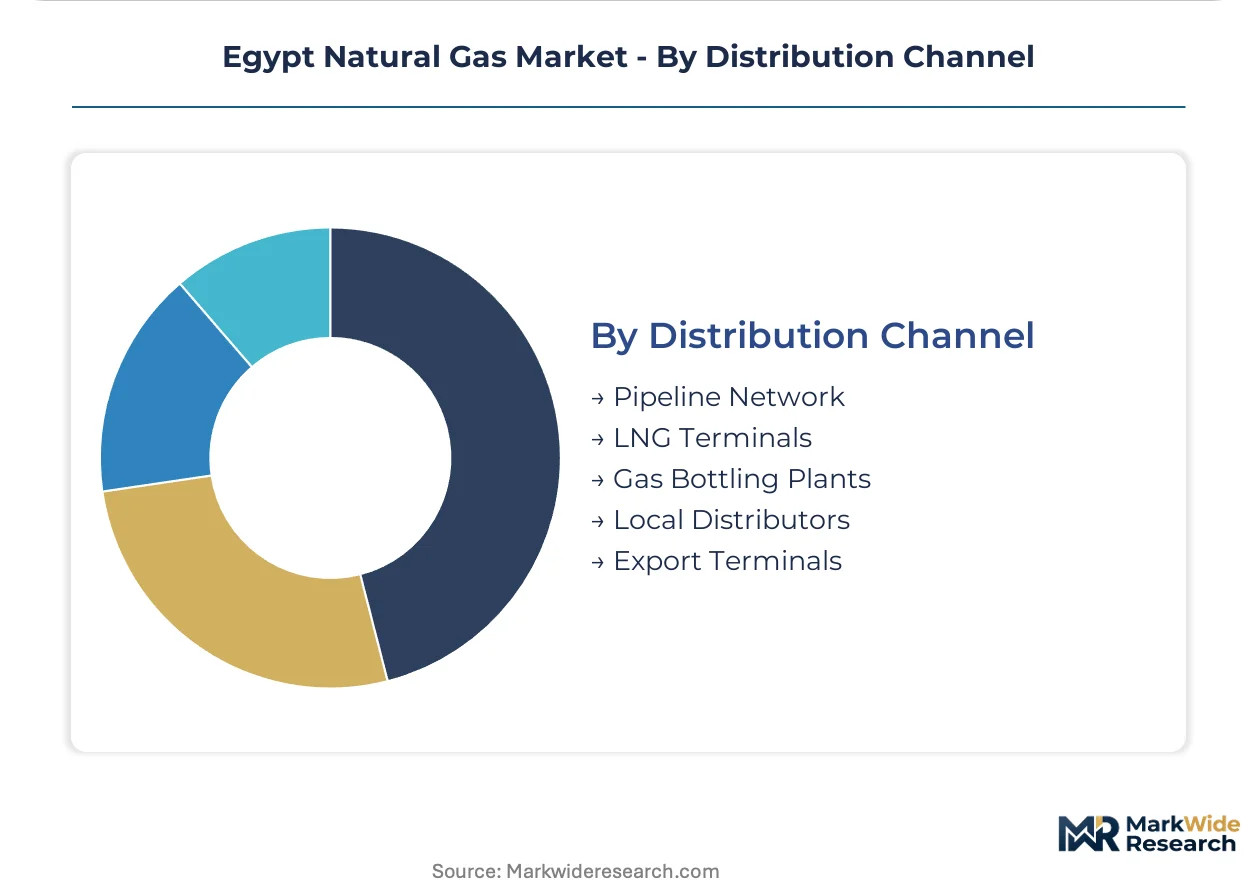
- Pipeline Network:National Gas Grid spanning the Nile Delta and Western Desert delivers processed gas to industrial zones under pressure specifications monitored by EGAS control centers. Compressor station investments at El Hammam and Abu Madi maintain flow capacity for Alexandria and Cairo demand corridors.
- LNG Terminals:Idku liquefaction trains and Ain Sokhna regasification capacity enable bidirectional trade, with export cargoes capturing premium European pricing during supply disruptions.
- Export Terminals:Mediterranean loading facilities serve Italian and Spanish buyers through long-term contracts and spot market sales.
- Gas Bottling Plants:LPG blending and cylinder filling operations supply residential and commercial customers beyond pipeline reach in Upper Egypt and Sinai.
- Local Distributors:Governate-level gas companies manage last-mile retail connections, with Cairo Gas Company and Tanta Gas Company holding franchise territories.
Pipeline network holds the largest share; LNG terminals are climbing the fastest as European energy security priorities expand Egyptian export opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European buyers command premium pricing leverage through Idku LNG spot cargoes, while Egyptian industrial zones absorb subsidized pipeline supply at administered tariffs below export netback equivalents.
Greater Cairo Metropolitan Area
Power generation utilities anchor demand through Egyptian Electricity Holding Company procurement at Burullus and West Damietta combined-cycle plants. Petroleum Ministry price ceilings cap industrial tariffs below liquefaction export economics. Cairo Gas Company manages last-mile distribution across Giza and Qalyubia governorates, expanding residential connections under regulated retail frameworks.
Alexandria Petrochemical Corridor
Ethylene crackers at SIDPEC and ethane-fed polyethylene complexes drive feedstock demand displacement of imported naphtha. EGAS pipeline specifications prioritize high-pressure delivery for chemical process safety. West Nile Delta field infrastructure terminates at Abu Qir processing facilities, consolidating offshore supply for Alexandria industrial zones.
Suez Canal Economic Zone
Methanol and ammonia project licensing accelerates under General Authority for Investment and Free Zones gas allocation permits. Idku liquefaction trains compete with domestic petrochemical offtake for finite feedstock volumes. Ain Sokhna regasification capacity enables bidirectional trade flexibility during European supply disruption windows.
Nile Delta Production Belt
Mature conventional fields at Abu Madi and El Hammam require accelerating workover frequency as reservoir depletion intensifies. Egyptian Natural Gas Holding Company compressor station investments maintain flow capacity for northern demand corridors. Tanta Gas Company serves fragmented agricultural and small industrial loads across Gharbia and Kafr El Sheikh governorates.
Western Desert Frontier
Apache Corporation onshore concessions sustain baseline supply through infill drilling programs at Khalda and Qarun complexes. Petroleum Ministry domestic price reform signals are restoring producer economics for marginal field rehabilitation. Upper Egypt cement and steel producers face transmission distance penalties elevating delivered costs above coastal industrial zones.
Egypt Natural Gas Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with proprietary subsea technology and field-specific extraction methods. The market structures around state-owned transmission gatekeepers coordinating production-sharing partners across deepwater and onshore concessions. Two archetypes dominate: integrated international operators with proprietary offshore technology and national holding companies controlling pipeline allocation authority. Competitive moves concentrate on production-sharing agreement renegotiation and liquefaction capacity debottlenecking investments competing for capital allocation.
Within the integrated international tier, BP plc and Eni SpA exemplify deepwater development archetypes leveraging proprietary subsea processing capabilities. Egyptian Natural Gas Holding Company occupies the national champion position coordinating field-to-factory flows through transmission infrastructure control. Shell Egypt represents the portfolio diversification approach spanning legacy onshore assets and offshore exploration blocks. These three anchors illustrate how foreign operator technology access combines with state-owned midstream gatekeeping to structure investment returns.
| Leading Market Players |
|---|
| Egyptian LNG |
| BP plc |
| Egyptian Natural Gas Holding Company |
| Chevron Corporation |
| Eni SpA |
| Egyptian General Petroleum Corporation |
| Shell Egypt |
| Apache Corporation |
| Egyptian Natural Gas Co. |
| Others |
Supply & Pricing Matrix
Zohr-scale offshore concentration in the Egyptian Mediterranean positions EGAS as the dominant price setter, capturing margin pools at liquefaction export premiums while compressing industrial pipeline tariffs below netback equivalents. This upstream gatekeeper structure forces producers to accept administered domestic pricing or divert volumes toward Idku spot cargoes.
Pricing Analysis
Configured-to-order supply agreements for Suez Canal Economic Zone petrochemical projects command substantial premiums over standard pipeline deliveries to Cairo power utilities. The dominant structure is contract-based long-term offtake with take-or-pay clauses, differentiated by volume scale and interruptibility provisions. Cost compression in subsidized industrial tiers is intensifying because Petroleum Ministry price ceilings lag feedstock import inflation. Fertilizer producers exhibit highest price sensitivity due to thin nitrogen export margins, while LNG traders show lowest sensitivity during European supply disruption windows.
Supply Chain Analysis
Extended payment terms from Egyptian Electricity Holding Company strain upstream operator cash flows, with EGAS intermediating working capital through supply-chain finance facilities. Geographic concentration centers on Egypt itself for pipeline gas, with Italy and Spain as primary LNG offtake markets. Critical inputs draw from Italian subsea equipment suppliers and German compressor manufacturers. Single-source vulnerability sits with proprietary subsea processing technology licensed from Eni SpA for Zohr satellite developments. Distribution runs through EGAS-controlled national grid infrastructure with coastal compressor stations maintaining pressure specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's natural gas market functions as a service-attach opportunity where digital field management and predictive maintenance contracts expand faster than raw molecule sales. Subsea sensor integration and cloud-based optimization platforms generate recurring revenue streams that outpace commodity price volatility.
For Market Incumbents: Entrench control through backward integration into pipeline integrity services and captive compression station operations. Deepen vertical integration by acquiring specialized corrosion monitoring firms serving Nile Delta transmission infrastructure. EGAS allocation authority poses substitution risk for independent producers lacking dedicated downstream offtake. For New Entrants and Emerging Players: Pursue white-space positioning in Red Sea carbonate exploration blocks offshore Hurghada, where technical specialization gaps deter established Mediterranean operators. Target digital twin deployment for mature Western Desert assets as the most penetrable segment, leveraging remote monitoring capabilities to reduce offshore personnel costs. Position through production-sharing agreement partnerships rather than standalone concession bids. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed offshore services contractors holding proprietary subsea intervention capabilities. Long-term viability across the projection horizon hinges on Egypt's ability to balance export revenue optimization against industrial electrification targets. Watch Petroleum Ministry domestic price reform signals as the critical inflection indicator for producer economics restoration.| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Processing Technology Licensing | Eni SpA's proprietary multiphase pumping eliminates separate platform requirements at Zohr satellite wells. |
| Pipeline Integrity Service Expansion | Smart pigging and corrosion monitoring investments secure decade-long maintenance contracts from EGAS. |
| Digital Twin Platform Deployment | Cloud-based production optimization reduces offshore personnel costs at Apache Corporation's Western Desert assets. |
| Liquefaction Capacity Debottlenecking | Idku terminal throughput expansion captures premium European spot pricing during supply disruption windows. |
| Hydrogen Hub Development | Blue ammonia export positioning leverages existing Suez Canal Economic Zone infrastructure for European offtake. |
Research Methodology
Cross-validation between Egyptian Petroleum Ministry production data and IEA natural gas trade statistics anchors the qualitative findings. Primary interviews with upstream field development executives, EGAS transmission planners, Suez Canal Economic Zone investment officers, and petrochemical procurement leads combined with secondary validation from EIA country analyses, BP Statistical Review of World Energy, and SEC filings from listed operators. Bottom-up field-level production estimates and top-down national balance triangulation ensure consistency.
Calibration against historical price differentials between domestic industrial tariffs and Idku export netbacks shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include gas type, application sector, end-user category, and distribution channel, with regional grid infrastructure and regulatory framework clusters as additional industry-specific dimensions. CAGRs derived from production-sharing agreement timelines and concession renewal schedules, incorporating reservoir depletion curves and workover frequency assumptions.
Sensitivities concentrate around Petroleum Ministry price reform implementation pace and European LNG demand volatility. Forecasts reflect documented assumptions regarding Zohr field plateau sustainability and West Nile Delta ramp-up cadence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Mud Balance Market
Oil & Gas
Well Test Market
Oil & Gas
Europe Hydraulic Fracturing Market
Oil & Gas
Europe Oilfield Services Market
Oil & Gas
Libya Oil and Gas Midstream Market
Oil & Gas
United States Oil and Gas Midstream Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
South America Intelligent Pigging Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
Injection Well Market
Oil & Gas
Zonal Isolation Market
Oil & Gas
Algeria Oil and Gas Market
Oil & Gas
Kazakhstan Oil and Gas Downstream Market
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market
Oil & Gas
Africa Natural Gas Market